
 Fermented Tea Market | 2026-2036
Fermented Tea Market Size, Share, and Industry Trends Forecast 2026-2036
Fermented Tea Market Intelligence
Subscription-based delivery models for specialty batches and new flavor profiles is hardening the direct-to-consumer channel. GT's Kombucha sustains its market leadership through extensive brand recognition and a diverse product portfolio. Health-Ade differentiates with its focus on small-batch production and distinct glass bottle packaging. KeVita leverages broad retail distribution networks to reach a wider consumer base.
Fermented tea is a beverage produced by fermenting sweetened tea with a symbiotic culture of bacteria and yeast (SCOBY). This process creates a range of organic acids, enzymes, and probiotic microorganisms, defining its characteristic tangy flavor and functional properties. While Kombucha represents the dominant product type, interest in other fermented beverages like Jun and water Kefir is expanding the category. Glass bottles remain the primary packaging format, associated with premium quality, though aluminum cans are gaining share due to convenience and recyclability.
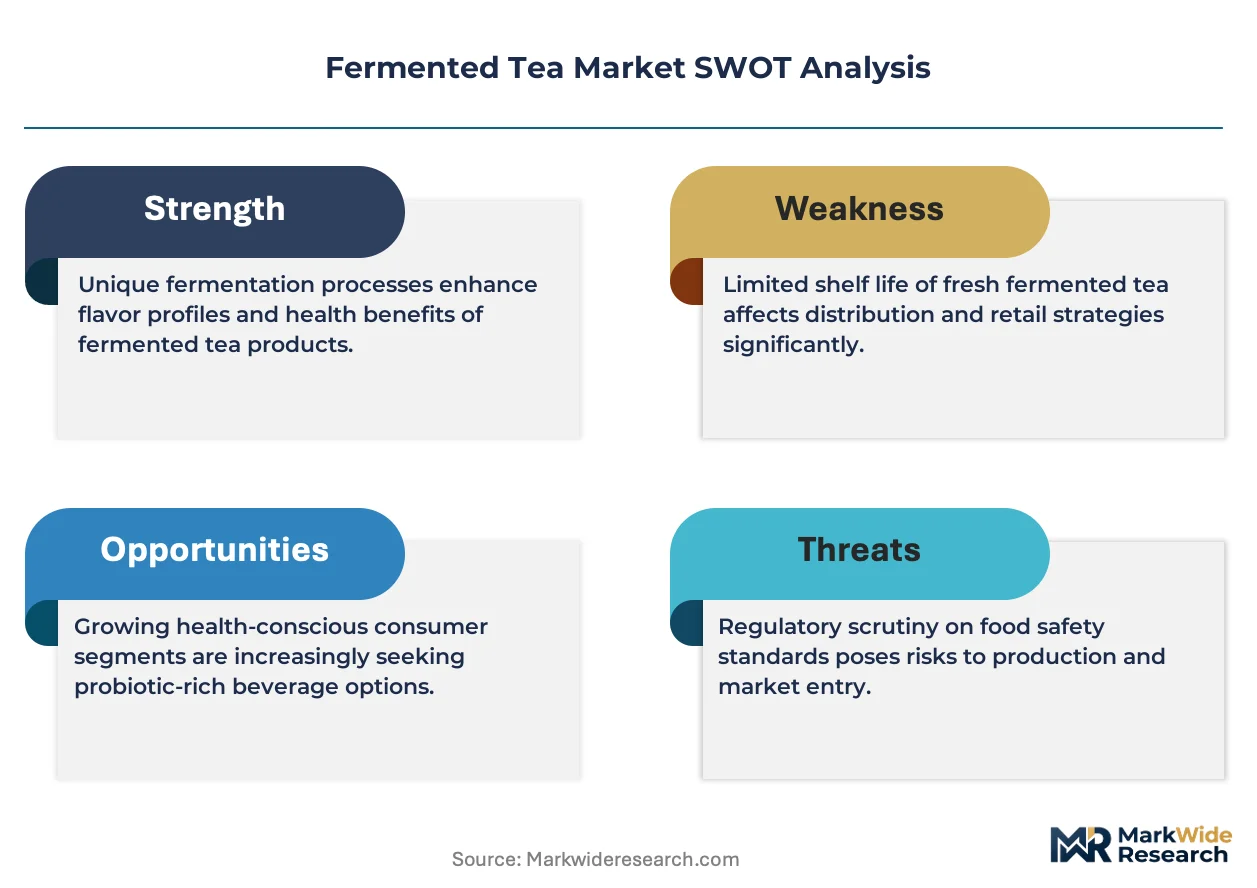
Market access requires adherence to strict food safety and labeling regulations, such as those enforced by the US Food and Drug Administration (FDA) and Health Canada. In Europe, the European Food Safety Authority (EFSA) scrutinizes health and probiotic claims, while alcohol content regulations present a compliance hurdle in multiple jurisdictions. Producers must navigate the strategic choice between artisanal positioning and achieving the production consistency required for large-scale retail partnerships.
Market Dynamics
The fermented tea market's structure is defined by the need to balance artisanal product positioning with the production consistency demanded by large-scale retail channels. This dynamic is intensified by health-conscious consumer demand colliding with strict food safety regulations.
Growth Catalysts
- Validated Functional Benefits:Scrutiny from the European Food Safety Authority (EFSA) on health claims drives use of validated ingredients, building consumer trust.
- Urban Wellness Demand:Health enthusiasts in United States urban centers create a concentrated customer base for specialty fermented tea products.
- Fermentation Innovation:Advances in managing SCOBY cultures enable development of novel flavor profiles, expanding the category beyond traditional Kombucha.
Market Restraints
- Alcohol Content Regulation:Strict alcohol by volume limits in multiple jurisdictions necessitate costly monitoring and control processes, creating a significant compliance burden.
- Glass Packaging Dominance:The market's reliance on glass bottles increases shipping weight and breakage risk, elevating logistical costs for producers.
- Live Culture Consistency:Achieving consistent flavor and probiotic profiles in live-culture products at industrial scale remains a major technical challenge for producers.
Strategic Opportunities
- Direct-to-Consumer Subscriptions:Subscription models for specialty batches build customer loyalty and provide a direct channel for launching new flavor profiles.
- Aluminum Can Packaging:The adoption of aluminum cans enhances portability and recyclability, opening new retail channels where glass is impractical.
- Functional Ingredient Blends:Incorporating ingredients like adaptogens or nootropics allows brands to target specific wellness concerns and differentiate products.
Industry Challenges
- Regulatory Compliance Burden:Producers face the ongoing operational challenge of adhering to evolving food safety and labeling rules from agencies like the US FDA and Health Canada.
- Cold Chain Logistics:Maintaining an unbroken refrigerated supply chain is critical for product stability and safety, adding significant cost and complexity to distribution networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fermented Tea Market |
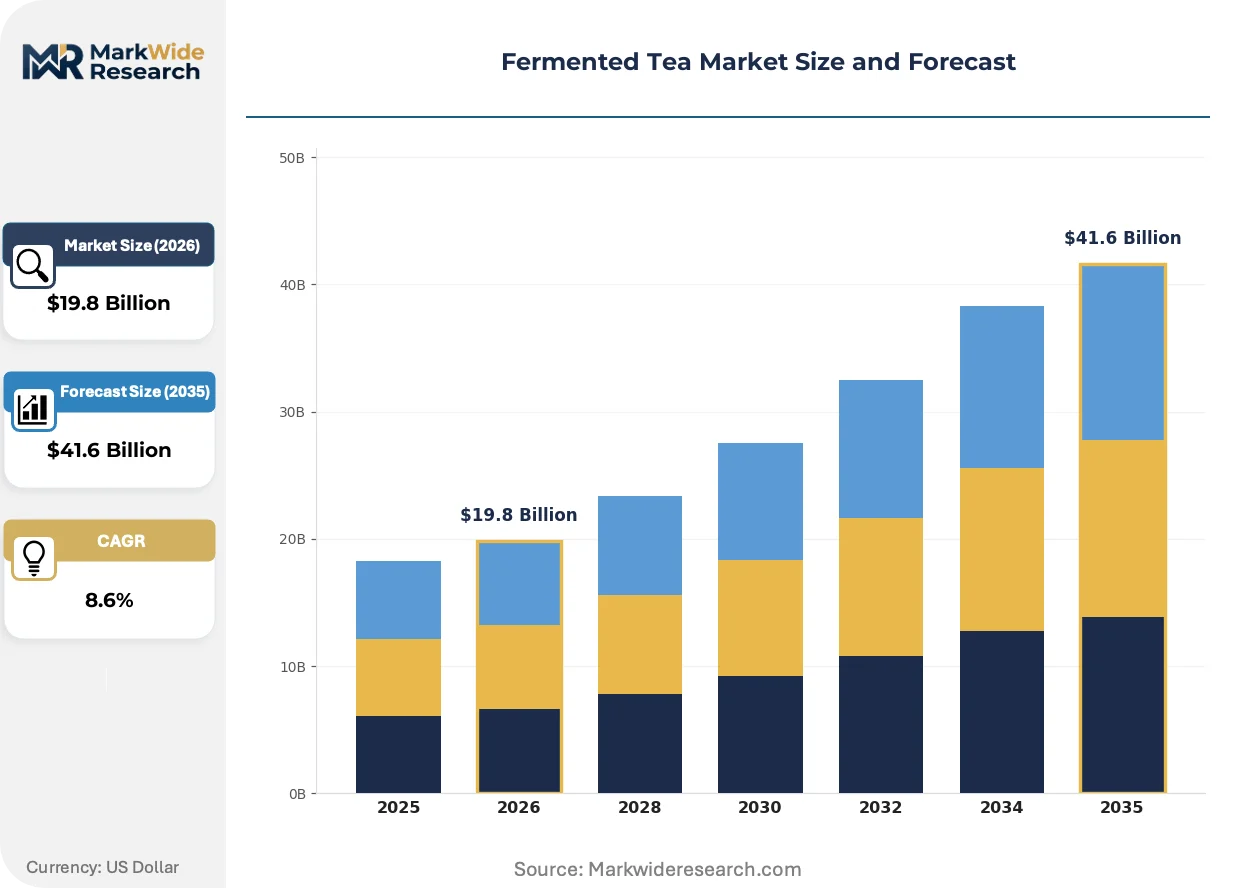
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $41.6 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kefir, Kombucha, Jun, Tepache End User: Health Enthusiasts, Restaurants, Retailers, Beverage Manufacturers Packaging Type: Bottles, Cans, Pouches, Kegs Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Cafes |
| Companies Covered | Brew Dr. Kombucha, Reed's, GT's Kombucha, Love Kombucha, The Humm Kombucha, Health-Ade, Celestial Seasonings, Townshend's Tea, KeVita, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fermented Tea Market Strategic Shifts & Innovations
Advanced fermentation science is intersecting with sophisticated digital marketing, pushing the market beyond traditional kombucha. This evolution creates products with targeted functional benefits, supported by direct consumer education and community-building initiatives.
Precision fermentation allows producers to control specific microbial strains within the SCOBY. Commercial-scale brands are rapidly adopting this technology to ensure product consistency and support specific functional claims. This scientific rigor is absorbing the unpredictability inherent in wild fermentation, enabling the creation of standardized products for mass retail.
Heightened regulatory focus on truth-in-labeling is compelling brands to validate their probiotic claims. Agencies like the US FDA and European Food Safety Authority are scrutinizing on-package statements about live cultures. Consequently, producers marketing functional benefits are investing in third-party lab testing and more controlled production processes to ensure compliance and maintain credibility.
Direct-to-consumer subscription models are gaining traction, shifting purchasing behavior away from incidental retail buys. This disintermediates traditional grocery channels, giving brands direct access to customer feedback and sales data for rapid product development. This trend is most prominent among newer brands in the United States targeting specific consumer niches with exclusive flavor drops.
Fermented Tea Market Segmentation
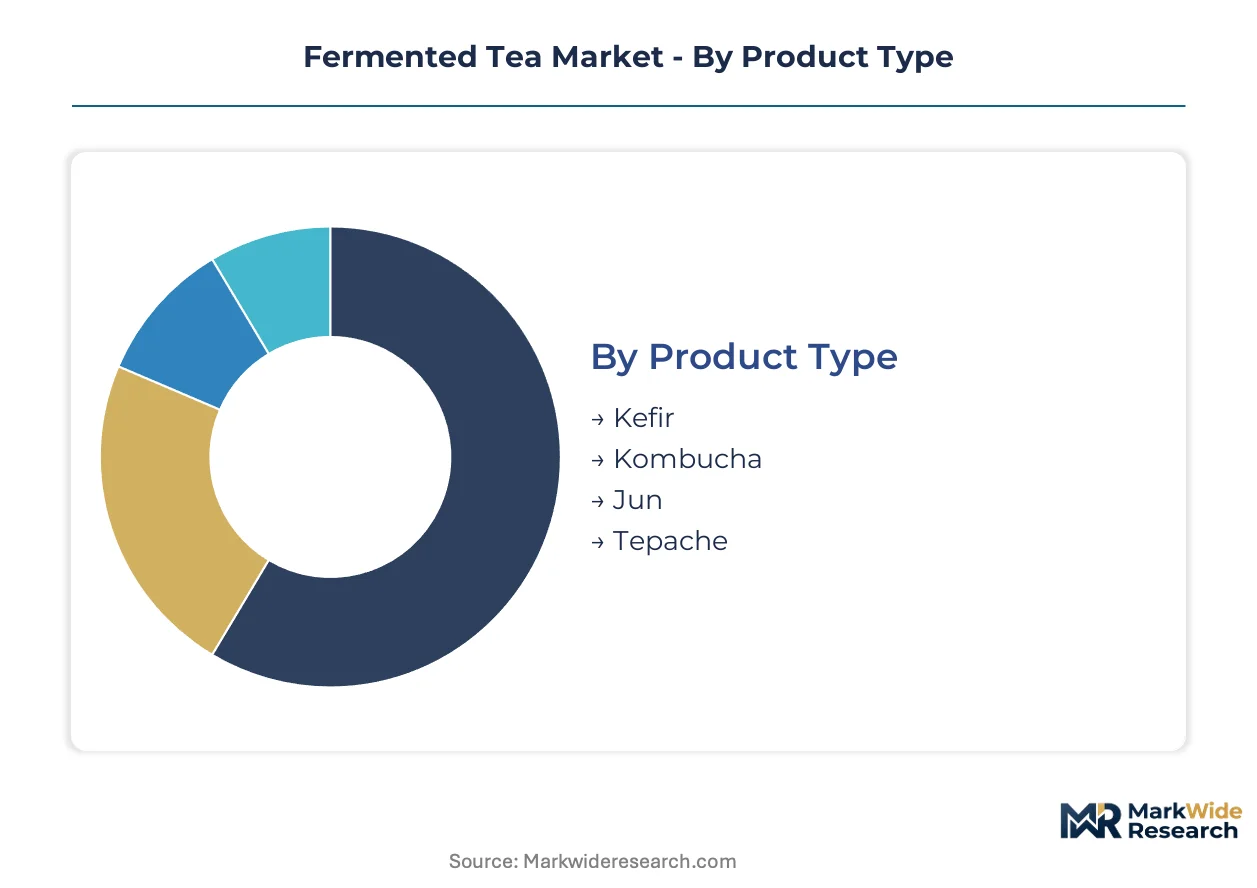
Market segmentation for fermented tea products provides a granular view of consumer preferences and operational considerations. Analyzing these distinct categories allows producers to tailor product development, marketing strategies, and distribution networks effectively. Understanding these segments is crucial for navigating competitive landscapes and identifying growth opportunities.
Product Type:
Buyers of fermented tea products often differentiate their choices based on the unique microbial cultures and flavor profiles each product type offers.
- Kefir:This fermented milk or water beverage contains a complex mix of bacteria and yeasts, offering a tangy, slightly effervescent profile. Demand for water kefir is expanding among consumers seeking dairy-free probiotic options across European markets.
- Kombucha:A fermented tea made with a SCOBY, characterized by its tart and slightly sweet taste and effervescence. This dominant product type sees significant consumption in urban centers of the United States, driven by perceived health benefits.
- Jun:A green tea and honey-based fermented beverage, known for its milder, less acidic flavor compared to traditional kombucha.
- Tepache:A traditional Mexican fermented beverage typically made from pineapple rind, brown sugar, and cinnamon.
Kombucha leads volumes today; Jun is gaining share fastest.
End User:
The diverse needs and consumption patterns of various customer types shape demand for fermented tea products.
- Health Enthusiasts:Individuals actively seeking beverages with functional benefits such as probiotics, digestive support, and natural energy. This segment drives innovation in product formulation and ingredient blends, particularly within the United States.
- Retailers:Grocery stores, convenience stores, and health food outlets stocking fermented tea products for direct consumer purchase. These channels require consistent product quality and adherence to labeling regulations from agencies like the US FDA.
- Restaurants:Food service establishments offering fermented tea as a beverage option, often featuring unique or artisanal selections.
- Beverage Manufacturers:Companies that incorporate fermented tea as an ingredient in other drinks or produce white-label products.
Health Enthusiasts represent a significant consumption base, while Retailers provide critical market access.
Packaging Type:
Packaging choices for fermented tea products are influenced by logistical efficiency, perceived premium quality, and environmental considerations.
- Bottles:Primarily glass bottles, associated with premium quality, product visibility, and maintaining carbonation. Glass bottles are the primary packaging format in European markets despite higher shipping costs.
- Cans:Aluminum cans offer convenience, portability, and recyclability, appealing to on-the-go consumers and venues where glass is restricted. Their adoption is expanding in North American markets due to logistical advantages.
- Pouches:Flexible packaging solutions, often used for single-serve portions or specialized product lines, offering lightweight transport.
- Kegs:Larger format containers used for bulk distribution to restaurants, bars, or refill stations, reducing individual packaging waste.
Glass bottles maintain their premium association, but aluminum cans are rapidly expanding due to convenience and recyclability.
Distribution Channel:
The accessibility and reach of various distribution channels significantly impact consumer purchasing behavior for fermented tea.
- Online Retail:E-commerce platforms and brand-specific websites offering direct-to-consumer sales, often featuring subscription models and exclusive flavor drops. This channel facilitates rapid product development and customer feedback in the United States.
- Supermarkets:Large retail chains providing broad availability and shelf space for established fermented tea brands. These channels demand production consistency and compliance with local food safety standards, such as those from Health Canada.
- Specialty Stores:Health food stores, organic markets, and gourmet shops that curate niche and artisanal fermented tea selections.
- Cafes:Coffee shops and casual eateries that offer fermented tea as an alternative beverage option, often focusing on local or craft brands.
Supermarkets ensure widespread availability, while online retail channels foster direct brand engagement and niche product sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While consumption in the United States concentrates in urban centers, European markets like Germany emphasize strict health claim validation. This difference shapes product development and marketing efforts across distinct regulatory environments.
United States
Health enthusiasts in urban centers drive significant demand for specialty fermented tea products. The US Food and Drug Administration (FDA) enforces stringent food safety and labeling regulations. Major metropolitan areas like Los Angeles and New York City exhibit high consumption of functional beverages.
Germany
Consumer demand for dairy-free probiotic options, particularly water kefir, is expanding within German markets. The European Food Safety Authority (EFSA) rigorously scrutinizes health and probiotic claims for all products. Berlin's vibrant wellness scene fosters innovation among artisanal fermented tea producers.
United Kingdom
Health-conscious consumers in the UK seek fermented teas for their perceived functional benefits and digestive support. The Food Standards Agency (FSA) oversees food labeling and safety standards for beverages. London's specialty food retailers increasingly stock a diverse range of fermented tea selections.
Canada
Health enthusiasts drive product innovation and new flavor profiles across Canadian provinces. Health Canada regulates health and probiotic claims, necessitating careful formulation and labeling. Urban centers such as Toronto and Vancouver represent concentrated customer bases for specialty fermented teas.
Australia
Growing consumer interest in gut health and natural beverages fuels demand for fermented tea products in Australia. Food Standards Australia New Zealand (FSANZ) governs product standards and ingredient declarations. Major cities like Sydney and Melbourne feature a rising number of cafes and health food stores offering fermented tea options.
Fermented Tea Market Key Industry Players
Top-tier vendors anchor market leadership through extensive brand recognition, while smaller artisanal producers differentiate with specialty batches. The market exhibits a tiered structure, with established brands focusing on broad retail distribution and newer entrants leveraging direct-to-consumer models. Companies engage in significant product portfolio diversification and strategic partnerships to expand reach.
Within the market leadership tier, GT's Kombucha exemplifies a brand built on extensive recognition and a diverse product portfolio. Health-Ade occupies a distinct position by focusing on small-batch production and premium glass bottle packaging. KeVita represents a strategy centered on leveraging broad retail distribution networks to achieve wider consumer access.
| Leading Market Players |
|---|
| Brew Dr. Kombucha |
| Reed's |
| GT's Kombucha |
| Love Kombucha |
| The Humm Kombucha |
| Health-Ade |
| Celestial Seasonings |
| Townshend's Tea |
| KeVita |
| Others |
Cost & Logistics Intelligence
Skilled fermentation specialists in urban centers drive labor-cost differentials, which directly influence pricing-tier spreads across the fermented tea market. This specialization contributes to the premium positioning of artisanal and small-batch products.
Pricing Analysis
Capacity additions in United States urban centers are reshaping price floors for high-volume fermented tea products. The market employs a hybrid transactional and subscription pricing model, catering to both retail purchases and direct-to-consumer loyalty. Price differentiation stems from packaging format, particularly glass bottles versus aluminum cans, and established brand recognition. Cost compression intensifies in the mass-market segment due to increased competition and retailer demands. Health enthusiasts demonstrate lower price sensitivity for products with validated functional benefits, while large retailers prioritize consistent pricing for shelf space.
Supply Chain Analysis
Reverse logistics for glass bottles, a primary packaging format, adds complexity and cost to the fermented tea supply chain. Geographic supply concentration includes major production hubs in the United States, alongside specialized water kefir producers in Germany and diverse offerings in the United Kingdom. Raw material dependencies center on sweetened tea, specialized SCOBY cultures, and packaging components. Cold chain logistics represents a significant structural risk, requiring unbroken refrigeration from production to point of sale. Distribution runs through a dual model, leveraging broad supermarket networks alongside targeted online retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fermented tea market is now a late-cycle quality story, driven by a pronounced demand-shift toward validated functional benefits and premium specifications.
For Market Incumbents:Lock in existing market share by investing in precision fermentation technologies to ensure consistent flavor and probiotic profiles at scale. Diversify product portfolios with functional ingredient blends to counter emerging artisanal producers. Expand direct-to-consumer subscription models to build deeper customer loyalty. Prioritize certification investment to meet stringent regulatory scrutiny on health claims from agencies like the US FDA and EFSA, maintaining credibility.
For New Entrants and Emerging Players:European Food Safety Authority (EFSA) health claim validation in European markets opens a window for scientifically backed new product introductions. Target underserved niches with specialty flavor profiles and innovative packaging, such as aluminum cans for convenience. Focus on urban wellness demand in the United States, leveraging direct-to-consumer subscription models for rapid market penetration. Incorporate adaptogens or nootropics to create differentiated products addressing specific consumer health concerns.
For Investors and Strategic Acquirers:Valuations sit cheapest among artisanal producers with strong regional ties and unique product offerings. The long-term viability hinges on the sustained consumer shift towards natural, functional beverages with verifiable health benefits. Identify acquisition targets that possess robust intellectual property in fermentation science or established direct-to-consumer channels. Practitioners should monitor successful navigation of alcohol content regulations by smaller brands as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Investment | Ensures product consistency and validates functional claims for mass retail channels. |
| Aluminum Can Packaging Shift | Expands market reach into new retail channels and improves logistical efficiency. |
| Functional Ingredient Integration | Differentiates products by targeting specific wellness concerns for health enthusiasts. |
| Direct-to-Consumer Channel Expansion | Builds customer loyalty and provides rapid feedback for new product development. |
| Regulatory Compliance Specialization | Mitigates risks associated with alcohol content and health claim scrutiny from US FDA. |
Research Approach
Multiple input streams — primary interviews, market reports, and regulatory filings — were reconciled to construct a comprehensive market view. This involved combining insights from brand managers, retail category buyers, food safety consultants, and fermentation scientists with extensive secondary validation. Bottom-up and top-down triangulation ensured data accuracy for the fermented tea market.
The forecast framework cross-references historical market performance with expert panel input across the analysis window. This process modeled segmentation dimensions including product type, end user, packaging type, distribution channel, and regional regulatory environment. Compound annual growth rates were derived from these inputs, with consumer health trend adoption rates and new flavor profile introductions serving as key forecast drivers.
Revisions become necessary when significant regulatory shifts or new scientific validations materialize within the industry. Forecasts reflect assumptions regarding current market dynamics and technological progress. Unforeseen changes in food safety standards or shifts in consumer preferences for functional beverages represent key risk factors. Practitioners should monitor evolving regulatory landscapes and scientific research for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
White Tea Extract Market
Tea
Europe Tea Market
Tea
Tea Essence Market
Tea
Probiotic Tea Market
Tea
Organic Tea Market
Tea
Tea Infuser Market
Tea
Pyramid Tea Bags Market
Tea
Out of Home Tea Market
Tea
Tea Pitchers Market
Tea
Smart Tea Maker Market
Tea
Green Tea Market
Tea
South America Tea Market
Tea
Instant Tea Premix Consumption Market
Tea
Nitro Tea Market
Tea
Tea Subscription Market
Tea
Europe Green Tea Market