
 Trehalose Market | 2026-2036
Trehalose Market Size, Share, and Industry Trends Forecast 2026-2036
Trehalose Market Outlook
China's Shandong Province is narrowing the cost gap between enzymatic and fermentation-derived trehalose through centralized bioreactor investments. Hayashibara Co. Ltd (Nagase Viita) anchors high-purity pharmaceutical grade output from its Okayama facilities, while Cargill Inc. leverages its global sweetener distribution network to extend food-grade penetration across North American bakery chains. Meihua Holdings Group competes on amino acid and sugar alcohol co-location economics in Hebei.
Trehalose is a non-reducing disaccharide composed of two glucose units linked by an alpha-1,1-glycosidic bond, manufactured industrially via enzymatic conversion of maltose using trehalose synthase or through fermentation with Corynebacterium glutamicum. Its superior protein-stabilizing and moisture-retention properties drive demand across pharmaceutical formulations, freeze-dried foods, and cosmetic emulsions. Food Grade trehalose dominates volume flows into Japanese and Korean confectionery supply chains, while Pharmaceutical Grade commands concentrated margin pools from mRNA vaccine excipient contracts. Biotechnology applications represent the fastest-expanding demand channel as cell-culture media formulators replace sucrose with trehalose for osmotic stability.
Japan's PMDA enforces strict excipient monograph compliance for trehalose used in parenteral drug products, while China's NMPA and SAMR coordinate GB standard updates for food additive purity tiers. The EU REACH framework governs industrial grade imports into European cosmetic manufacturing, creating divergent certification burdens across export destinations. Stakeholders must monitor regulatory alignment between pharmacopeial standards in Asia-Pacific and emerging biosimilar production clusters.
Market Dynamics
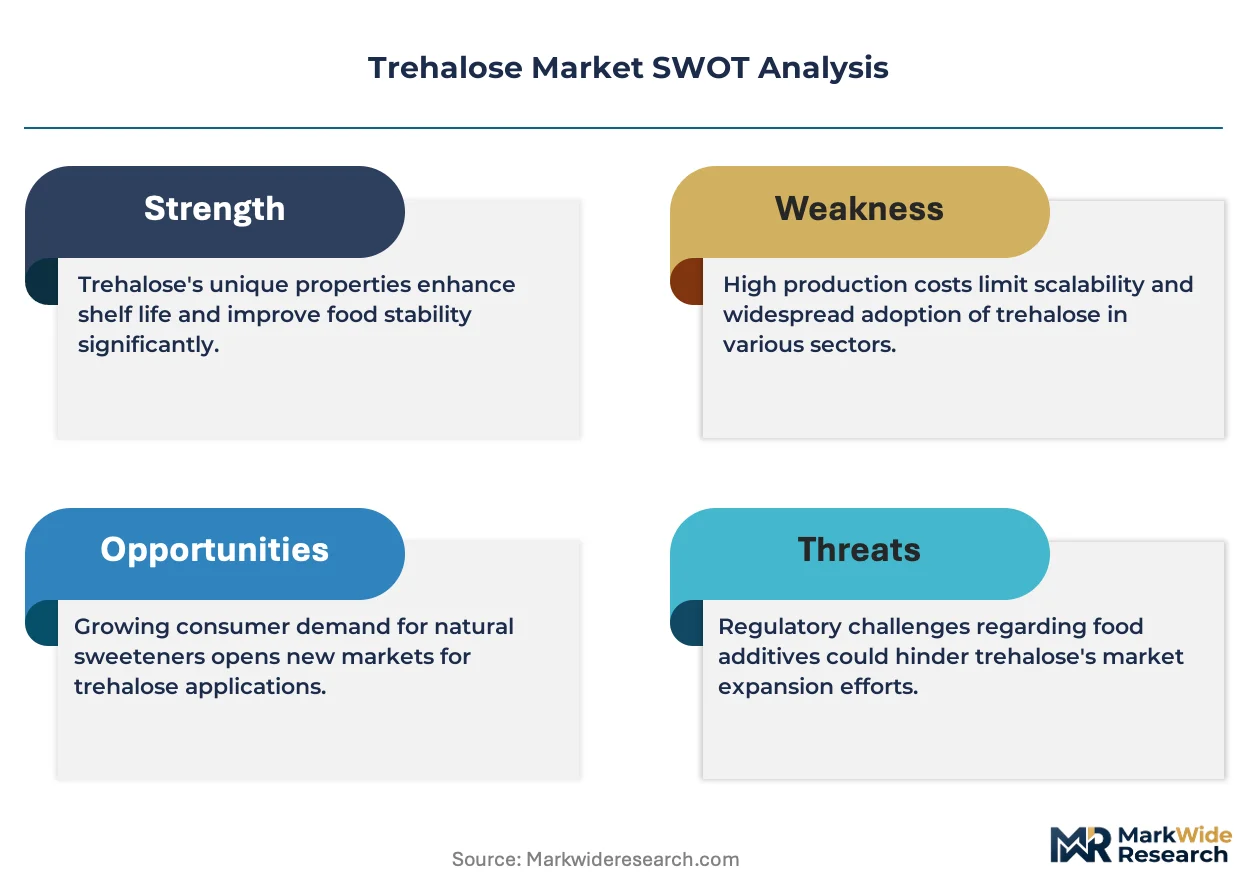
Enzymatic trehalose synthesis is hybridizing with precision fermentation platforms, collapsing the cost premium that previously separated pharmaceutical-grade from food-grade supply tiers and redrawing competitive boundaries across East Asian manufacturing clusters.
Growth Catalysts
- Biologics Excipient Mandates:Japan's PMDA enforces trehalose inclusion in protein stabilization protocols for parenteral formulations, pulling high-purity demand from contract manufacturing organizations.
- Cell-Culture Media Reformulation:Biotechnology laboratories are displacing sucrose with trehalose for osmotic stability in mammalian cell lines, creating a dedicated demand channel with premium pricing power.
- Shandong Fermentation Corridor:Centralized bioreactor investments in China's Shandong Province are compressing unit economics for fermentation-derived trehalose, narrowing the cost gap with enzymatic routes.
Market Restraints
- Maltose Feedstock Volatility:Starch processing margins fluctuate with corn and wheat commodity cycles, transmitting input cost instability to trehalose contract pricing.
- Okayama Supply Concentration:High-purity pharmaceutical-grade output concentrates in a single Japanese prefecture, creating geographic vulnerability for mRNA vaccine excipient procurement.
- Sucrose Substitution Threat:Food manufacturers retain sucrose as a lower-cost humectant in non-critical confectionery applications, capping trehalose penetration in volume segments.
Strategic Opportunities
- Lyophilized Ready-Meal Expansion:South Korean and Japanese food processors are adopting trehalose for moisture retention in premium freeze-dried product lines, opening a packaged-food channel beyond confectionery.
- Cosmetic Emulsion Convergence:Trehalose is penetrating K-beauty and J-beauty formulations as a cryoprotectant and texture stabilizer, riding the clean-label ingredient replacement wave.
- China NMPA Excipient Harmonization:Tightening GB standards for pharmaceutical-grade imports are creating certification moats for early-compliant foreign suppliers against late entrants.
Industry Challenges
- Trehalose Synthase Enzyme Sourcing:Limited commercial suppliers of thermostable synthase variants constrain enzymatic production scaling for mid-tier manufacturers.
- Pharmacopeial Cross-Alignment:Divergent monograph specifications between Japan's PMDA, China's NMPA, and US FDA force multi-track validation campaigns for global excipient suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trehalose Market |
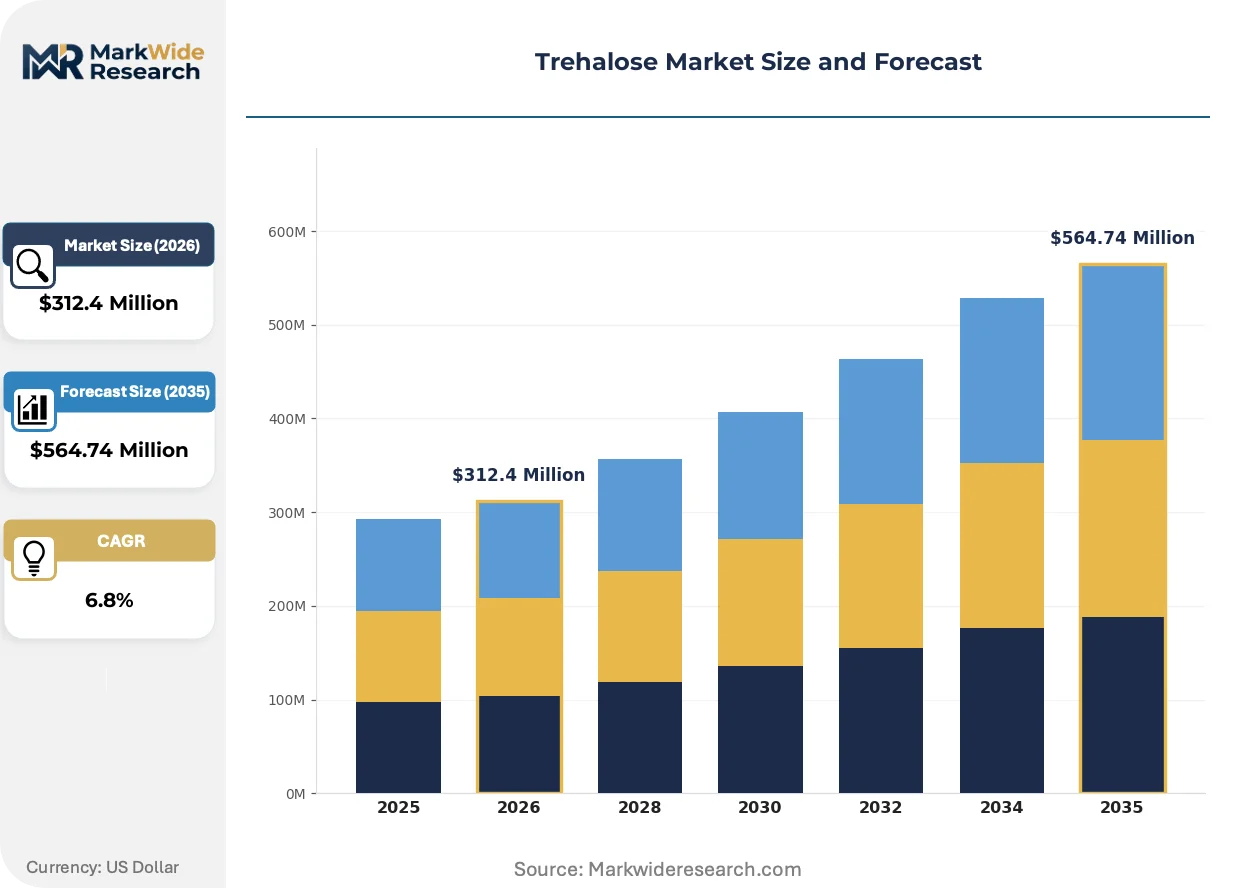
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Pharmaceutical Grade, Cosmeceutical Grade, Industrial Grade Application: Food Preservation, Medical Applications, Cosmetics, Biotechnology End User: Food Manufacturers, Pharmaceutical Companies, Cosmetic Brands, Research Institutions Distribution Channel: Online Retail, Direct Sales, Distributors, Specialty Stores |
| Companies Covered | Sinozyme Biotechnology, Shandong Fuyang Biotechnology, Hayashibara Co. Ltd (Nagase Viita), Nagase Group, Baolingbao Biology, Meihua Holdings Group, Cargill Inc., Ingredion Incorporated, Shandong Lianmeng Chemical Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trehalose Market Strategic Shifts
Continuous processing technology and regulatory harmonization pressures are compressing batch-to-batch variability while opening new application vectors in cell therapy and precision nutrition.
Enzymatic trehalose production is hybridizing with immobilized enzyme reactor systems that enable continuous-flow manufacturing. Biopharmaceutical contract manufacturers in Japan and South Korea are piloting these platforms to reduce solvent use and downstream purification costs. This technology convergence is collapsing the traditional separation between food-grade and pharmaceutical-grade production infrastructure.
China's NMPA coordination with SAMR on GB standard updates is tightening heavy metal and endotoxin thresholds for imported trehalose. Foreign suppliers face extended registration timelines and mandatory local testing protocols. The pharmaceutical excipient segment bears the heaviest compliance burden, with some European suppliers redirecting volume toward cosmetic-grade contracts rather than pursue dual-track certification.
Long-term supply agreements are displacing spot-market purchasing for pharmaceutical-grade trehalose. mRNA vaccine manufacturers in Japan and South Korea are locking in multi-year excipient contracts with fixed-price escalation clauses. This procurement pattern shift concentrates volume with established Okayama and Shandong suppliers while raising barriers for new market entrants lacking validation track records.
Trehalose Market Segmentation
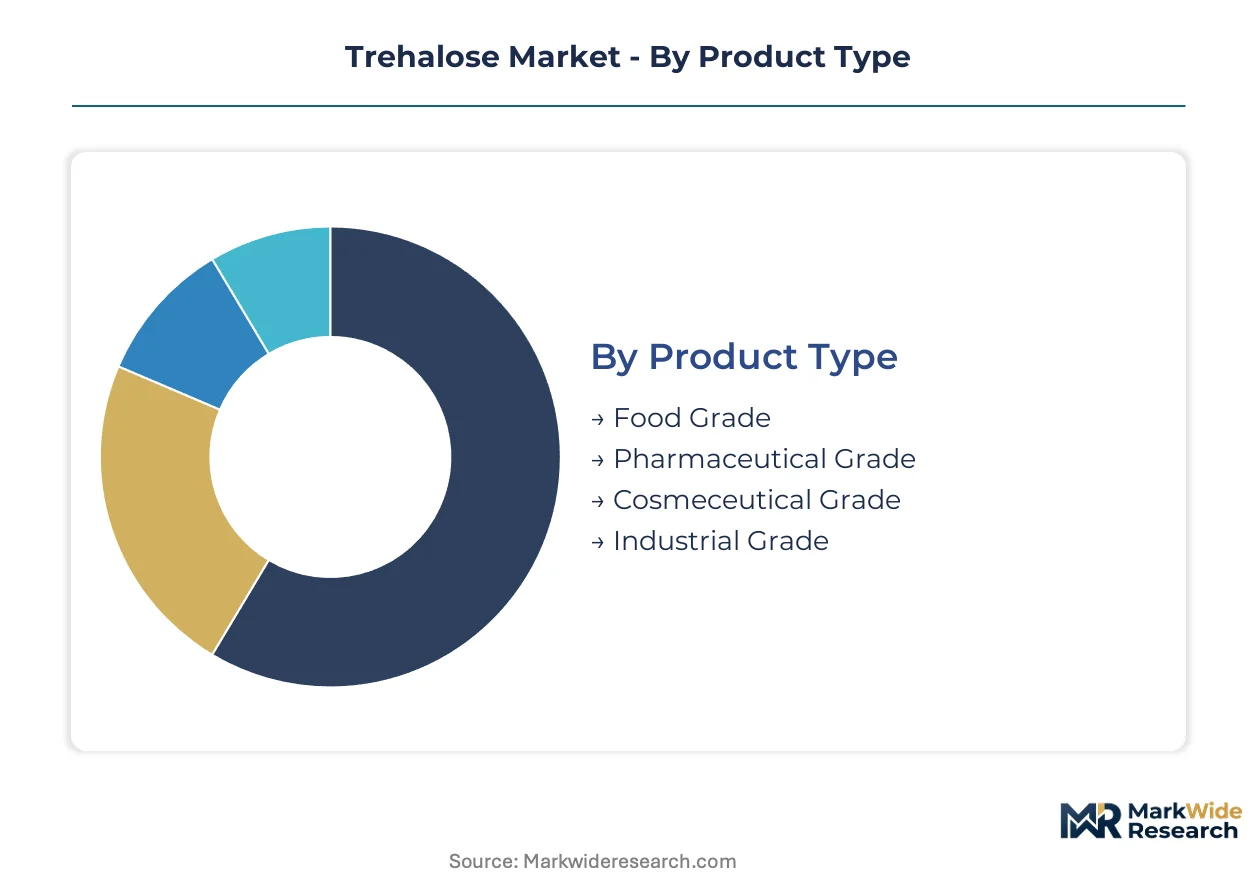
Trehalose procurement cycles vary dramatically across purity tiers and end-use specifications. Pharmaceutical-grade contracts lock in multi-year supply agreements with validation-heavy onboarding, while food-grade volumes rotate through quarterly purchasing schedules. Understanding these velocity differentials shapes inventory positioning and margin capture strategies.
Product Type:
Food Grade trehalose turns inventory fastest with standardized specifications and commodity-like contracting. Pharmaceutical Grade operates on 18-36 month procurement cycles driven by pharmacopeial validation requirements. Cosmeceutical and Industrial grades occupy intermediate velocity positions with formulation-specific testing protocols.
- Food Grade:Standardized purity specifications (minimum 98% trehalose dihydrate) with moisture retention and non-reducing sugar properties optimized for confectionery and bakery applications. Japanese and Korean food manufacturers concentrate procurement through Shandong fermentation suppliers for cost-competitive humectant replacement in premium snack lines.
- Pharmaceutical Grade:Ultra-high purity (≥99.5%) with endotoxin limits below 10 EU/g and heavy metal thresholds meeting USP-NF and JP monograph standards. mRNA vaccine excipient contracts in Japan and South Korea pull concentrated demand from Okayama manufacturing facilities with PMDA-validated track records.
- Cosmeceutical Grade:Intermediate purity tier with enhanced stability testing for K-beauty and J-beauty cryoprotectant formulations.
- Industrial Grade:Technical-grade specifications serving bioprocessing and enzyme stabilization applications with relaxed purity tolerances.
Food Grade dominates installed base. Pharmaceutical Grade is where expansion concentrates.
Application:
Cost tier stratification separates premium-positioned applications from commodity substitution plays. Medical and biotechnology channels command 3-5x price multiples over food preservation volumes, with cosmetics occupying a mid-tier value position.
- Food Preservation:Moisture retention and cryoprotection in freeze-dried ready-meals, confectionery, and bakery products with trehalose displacing sucrose in premium positioning strategies. South Korean food processors are expanding adoption for shelf-stable convenience products targeting export markets.
- Medical Applications:Protein stabilization in parenteral biologics, lyophilized vaccines, and monoclonal antibody formulations where excipient quality directly impacts therapeutic shelf life. PMDA-mandated inclusion protocols in Japan create structural demand pull from contract manufacturing organizations.
- Cosmetics:Emulsion stabilization and cell cryoprotection in clean-label skincare formulations riding ingredient transparency trends.
- Biotechnology:Mammalian cell-culture media reformulation replacing sucrose for osmotic stability in stem cell and gene therapy production workflows.
Food Preservation commands volume leadership. Biotechnology is climbing the fastest.
End User:
Customer type determines specification intensity and relationship durability. Pharmaceutical companies and research institutions demand technical service depth, while food manufacturers and cosmetic brands prioritize supply security and cost predictability.
- Food Manufacturers:Large-scale confectionery and bakery producers in Japan, South Korea, and China sourcing through annual tenders with volume-based pricing structures and just-in-time delivery requirements.
- Pharmaceutical Companies:Biologics manufacturers and vaccine producers in Japan and South Korea locking in multi-year excipient contracts with fixed-price escalation clauses and mandatory audit rights.
- Cosmetic Brands:K-beauty and J-beauty formulators seeking clean-label humectant alternatives with supplier sustainability credentials and regional regulatory compliance documentation.
- Research Institutions:Academic and commercial biotechnology laboratories purchasing smaller volumes with high specification variability for experimental cell-culture media development.
Food Manufacturers anchor volume throughput. Pharmaceutical Companies are where margin expansion concentrates.
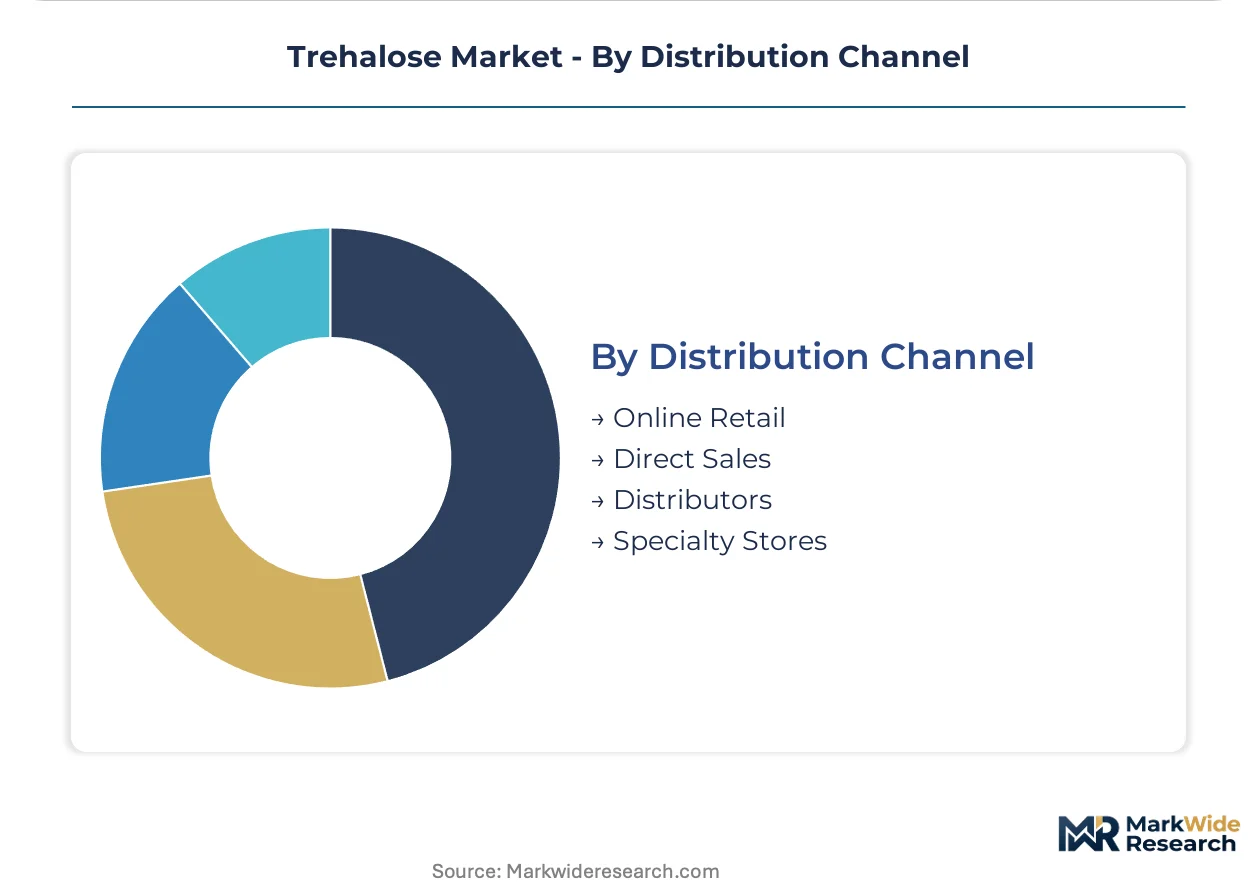
Distribution Channel:
Supply concentration varies sharply across channel structures. Direct sales relationships with pharmaceutical and large food manufacturers dominate value capture, while distributor networks extend geographic reach into fragmented cosmetic and research segments.
- Direct Sales:Dedicated account management for pharmaceutical-grade contracts with technical service support, regulatory documentation packages, and co-development partnerships for formulation optimization.
- Distributors:Regional chemical and ingredient distributors serving mid-tier food manufacturers and cosmetic formulators with consolidated logistics and local inventory positioning.
- Online Retail:E-commerce platforms targeting small-scale research institutions and specialty food producers with standard-packaged products and rapid fulfillment.
- Specialty Stores:Niche channels for cosmeceutical-grade trehalose in ingredient-focused retail environments serving artisanal cosmetic producers.
Direct Sales dominates value concentration. Distributors are gaining share fastest in geographic extension plays.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PMDA enforcement of excipient monographs in Japan anchors pharmaceutical-grade demand, while China's NMPA tightens import standards and South Korea's MFDS accelerates biologics manufacturing. These regulatory postures concentrate procurement power across three East Asian jurisdictions with divergent certification burdens.
Japan
Protein stabilization protocols for parenteral biologics pull high-purity trehalose through contract manufacturing organizations. PMDA mandates trehalose inclusion in lyophilized vaccine formulations, creating structural demand from mRNA producers. Okayama Prefecture hosts concentrated pharmaceutical-grade manufacturing with validated track records for export certification.
China
Shandong Province's biotechnology corridor narrows cost gaps between enzymatic and fermentation-derived supply through centralized bioreactor investments. NMPA coordination with SAMR on GB standard updates tightens heavy metal and endotoxin thresholds for imported excipients. Foreign suppliers face extended registration timelines and mandatory local testing protocols.
South Korea
Cell-culture media reformulation drives biotechnology demand as laboratories displace sucrose with trehalose for osmotic stability in mammalian cell lines. MFDS alignment with PMDA pharmacopeial standards streamlines cross-border excipient validation for biologics manufacturers. Seoul Capital Area anchors multi-year procurement contracts with fixed-price escalation clauses.
United States
Freeze-dried food applications expand through North American bakery chains seeking moisture-retention alternatives to sucrose. FDA oversight of pharmaceutical-grade imports maintains pharmacopeial cross-alignment with USP-NF standards. Cargill's global sweetener distribution network extends food-grade penetration across regional convenience product lines.
Germany
Cosmetic emulsion applications penetrate K-beauty and J-beauty supply chains through clean-label ingredient replacement trends. ECHA REACH framework governs industrial-grade imports for European cosmetic manufacturing, creating divergent certification burdens from pharmaceutical channels. Bavaria-based distributors consolidate logistics for mid-tier formulators.
Trehalose Market Competitive Environment
Integrated fermentation specialists and global ingredient distributors split the market into divergent margin tiers. Production infrastructure concentrates in East Asian biotechnology corridors where enzymatic and fermentation routes hybridize. Three archetypes dominate: Japanese pharmaceutical-grade validators, Chinese cost-optimized fermenters, and multinational sweetener distributors. Capacity expansion and pharmacopeial certification campaigns constitute the primary competitive moves as manufacturers defend position against regulatory tightening.
Within the pharmaceutical-grade validation tier, Hayashibara Co. Ltd (Nagase Viita) exemplifies the Japanese archetype with Okayama-based manufacturing anchored to PMDA compliance. Shandong Fuyang Biotechnology and Meihua Holdings Group occupy positions within China's fermentation-optimized segment, leveraging Shandong Province's bioreactor corridor economics. Cargill Inc. represents the multinational distribution archetype, extending food-grade penetration through captive sweetener supply networks rather than standalone trehalose specialization.
| Leading Market Players |
|---|
| Sinozyme Biotechnology |
| Shandong Fuyang Biotechnology |
| Hayashibara Co. Ltd (Nagase Viita) |
| Nagase Group |
| Baolingbao Biology |
| Meihua Holdings Group |
| Cargill Inc. |
| Ingredion Incorporated |
| Shandong Lianmeng Chemical Group |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Okayama's pharmaceutical-grade fermenters is tightening supply discipline and amplifying pricing power for PMDA-validated producers serving Japanese biologics manufacturers. This utilization squeeze propagates through contract structures, rewarding incumbents with validated track records while forcing cost absorption onto newer Shandong entrants competing for food-grade share.
Pricing Analysis
A 40-60% price spread separates pharmaceutical-grade trehalose in Japan from food-grade volumes in Shandong, with certification tier and endotoxin testing burden as the primary differentiation drivers. Contract-based long-term offtake dominates pharmaceutical procurement, locking in 18-36 month supply security with fixed-price escalation clauses. Cost compression in food-grade tiers is intensifying because Shandong fermentation clusters are expanding bioreactor capacity. Food manufacturers exhibit highest price sensitivity, while mRNA vaccine producers prioritize supply assurance over unit cost.
Supply Chain Analysis
Maltose feedstock from corn and wheat starch processing anchors trehalose production economics, with supply chains drawing from agricultural commodity markets in the United States, Brazil, and Ukraine. Corynebacterium glutamicum cultures and trehalose synthase enzymes constitute critical bioprocessing inputs. Single-source vulnerability concentrates in Okayama for pharmaceutical-grade output, where PMDA validation creates switching costs. Distribution runs through direct sales relationships with pharmaceutical and large food manufacturers, supplemented by regional chemical distributors for mid-tier cosmetic and research segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The trehalose market is recovering from a cyclical trough driven by post-pandemic normalization of mRNA vaccine production schedules and inventory destocking across Asian fermentation corridors.
For Market Incumbents: Build pharmacopeial certification moats by securing simultaneous PMDA-NMPA-MFDS validation, insulating against regulatory divergence that fragments competitor access. Defensive moves center on backward integration into maltose supply through captive starch processing partnerships in Shandong, and capacity addition in Okayama to capture biologics contract manufacturing expansion. The threat of enzymatic route cost convergence demands pre-emptive fermentation yield improvements. For New Entrants and Emerging Players: Southeast Asian cosmetic formulators represent underpenetrated demand with lower certification barriers than pharmaceutical channels. White-space targets include Indonesian and Vietnamese K-beauty supply chains seeking clean-label cryoprotectants, and North American freeze-dried food processors outside Cargill's captive network. A technical service-led go-to-market angle—offering formulation co-development for cell-culture media reformulation—differentiates against commodity distributors. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among pharmaceutical-grade validators with multi-year excipient contracts and mandatory audit rights embedded in procurement terms. Long-term viability favors acquisition targets possessing dual PMDA-NMPA track records and established relationships with Japanese contract manufacturing organizations. The signal to watch is NMPA GB standard harmonization progress, which will determine certification moat durability for early-compliant foreign suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmacopeial Certification Campaign | Dual PMDA-NMPA validation secures preferential access to mRNA vaccine excipient contracts in East Asia. |
| Backward Integration into Maltose Supply | Captive starch processing partnerships in Shandong Province compress feedstock cost volatility exposure. |
| Continuous-Flow Enzymatic Reactor Deployment | Immobilized enzyme systems reduce solvent use and downstream purification costs for biopharmaceutical manufacturers. |
| Cell-Culture Media Co-Development Partnership | Technical service bundling with biotechnology laboratories displaces sucrose in mammalian cell-line applications. |
| Cosmetic-Grade Regional Distribution Expansion | Local inventory positioning in Indonesia and Vietnam captures K-beauty clean-label ingredient replacement demand. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade databases, and industry association reports, combining structured interviews with fermentation plant managers, pharmaceutical procurement leads, and cosmetic formulators with bottom-up capacity modeling and top-down demand triangulation. Secondary validation draws from NMPA registration databases, PMDA pharmacopeial updates, customs export records, and SEC filings of listed ingredient suppliers. Cross-referencing across these sources isolates capacity utilization signals and procurement pattern shifts.
Forecast inputs span grade tier, end-use application, and regional regulatory cluster, with analytical framework approach projecting volume and value across the analysis window. CAGRs derive from segmented demand modeling incorporating biologics manufacturing expansion, cell-culture media reformulation velocity, and food preservation substitution rates. Industry-specific inputs include maltose feedstock cost trajectories and pharmacopeial harmonization timelines between Japanese, Chinese, and South Korean regulators.
Practitioners should monitor NMPA GB standard enforcement intensity and mRNA vaccine production schedule volatility for early signals of demand revision. Forecasts reflect assumptions about regulatory alignment persistence and fermentation yield improvement trajectories. Cross-checking against customs trade data and pharmaceutical excipient procurement disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Intensive Sweeteners Market
Sweeteners
Xylose Market
Sweeteners
Sugar Free Lifesavers Market
Sweeteners
Floral Nectar Market
Sweeteners
North America Low-Calorie Sweeteners Market
Sweeteners
Europe Natural Sweetener Market
Sweeteners
Smoked Sugar Market
Sweeteners
Digestion Resistant Maltodextrin Market
Sweeteners
Italy Food Sweetener Market
Sweeteners
Sweet Modulator Market
Sweeteners
Europe Low-Calorie Sweeteners Market
Sweeteners
Plant-Derived Sweetener Market
Sweeteners
Asia-Pacific Low-Calorie Sweeteners Market
Sweeteners
Tapioca Maltodextrin Market
Sweeteners
White Sugar Market
Sweeteners
Rice Syrup Market