
 RTD Protein Beverages Market | 2026-2036
RTD Protein Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
RTD Protein Beverages Market Intelligence
Aftermarket service revenue in subscription-based replenishment programs is rewriting profit allocation across the RTD protein value chain. Danone SA leverages its specialized nutrition infrastructure to sustain premium positioning in medical and sports applications. Abbott Nutrition anchors its portfolio through clinical credibility and pharmacy channel control. Glanbia PLC competes on dairy and plant protein sourcing scale across multiple continents.
RTD protein beverages are shelf-stable, pre-mixed drinks delivering 15-40 grams of protein per serving through ultrahigh-temperature processing and aseptic filling, designed for post-exercise recovery, meal replacement, or clinical nutrition support. Plant-Based formulations represent the fastest-growing product category as oat, pea, and fava protein extraction costs decline. Dairy-Based SKUs still occupy the dominant margin pool due to established whey protein isolate supply chains and familiar taste profiles among older consumers. Health-Conscious Consumers as an end-user segment leads volume expansion through mainstream grocery channel penetration.
FDA nutrition labeling requirements and EFSA health claim verification shape product positioning and restrict unsubstantiated performance marketing in the United States and European Union. The USDA organic certification and Non-GMO Project standards further segment pricing tiers and retail access for premium entrants. Stakeholders must monitor evolving protein content thresholds and sugar reduction mandates as regulators tighten functional beverage classifications.
Market Dynamics
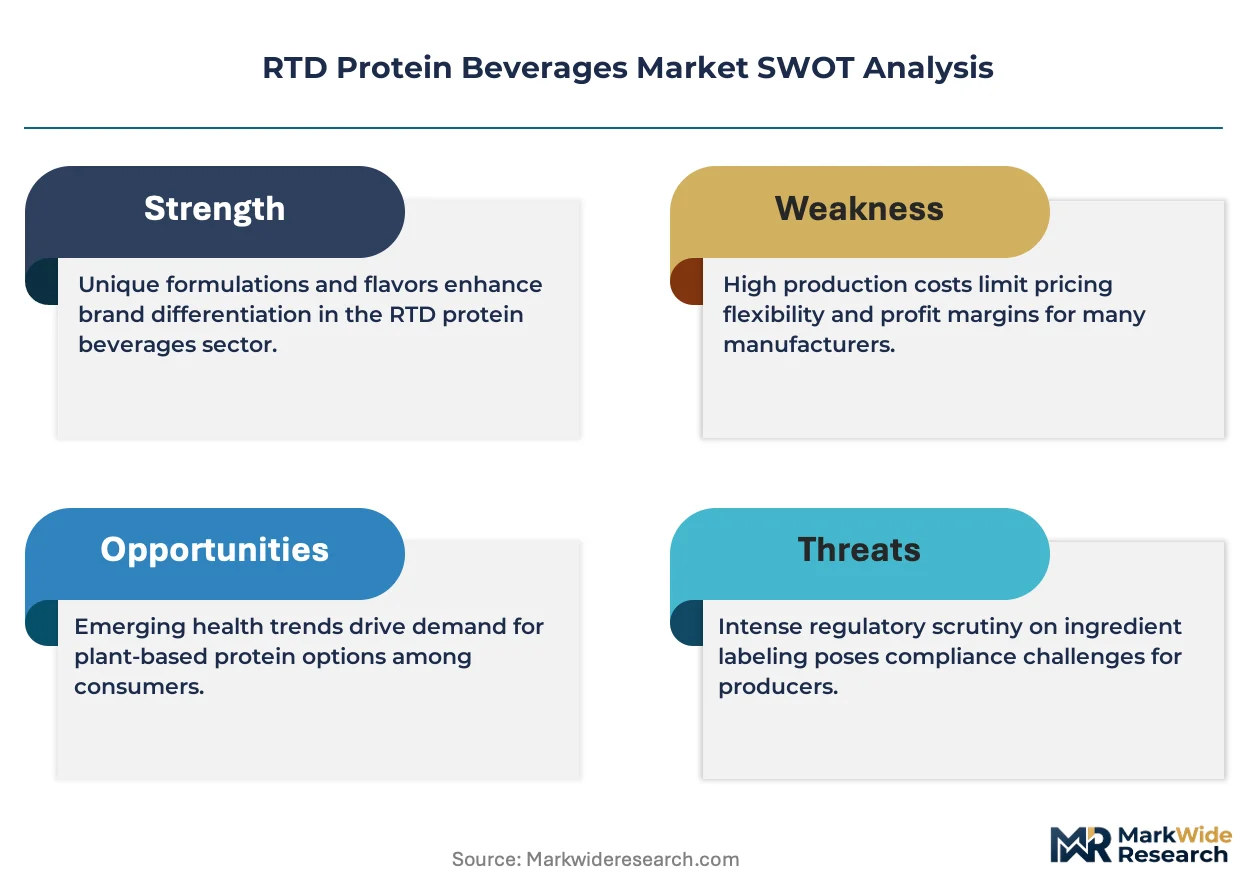
Clean-label certification requirements under FDA and EFSA guidelines are fragmenting supplier tiers and forcing reformulation investments that reshape competitive economics across the RTD protein value chain.
Growth Catalysts
- Post-Workout Recovery Protocols:Fitness enthusiasts now prioritize portable nutrition formats over traditional whole-food options, compressing consumption occasions into single-serve RTD formats.
- EFSA Health Claim Verification:Validated protein content claims unlock pharmacy and clinical nutrition channels previously inaccessible to functional beverage entrants.
- Oat Protein Extraction Scale:Declining input costs for plant-based protein isolates enable price parity with dairy-based formulations in European and North American retail.
Market Restraints
- Whey Isolate Supply Concentration:Dairy-based SKU margins remain vulnerable to New Zealand and European Union milk powder export volatility.
- USDA Organic Certification Timelines:Eighteen-month approval windows delay premium positioning for new entrants targeting Whole Foods and natural channel distribution.
- Sugar Reduction Mandates:FDA added sugar labeling requirements force reformulation that degrades taste profiles in legacy chocolate and vanilla SKUs.
Strategic Opportunities
- German Pharmacy Channel Penetration:Medical nutrition positioning under BfArM guidelines opens reimbursement-adjacent revenue streams for clinical-grade formulations.
- Direct-to-Consumer Subscription Models:Replenishment programs capture lifetime value through personalized flavor rotation and adaptive protein dosing algorithms.
- Dual Carbon Goals (China):Plant-based protein localization aligns with MEE emissions targets and unlocks state-backed manufacturing incentives.
Industry Challenges
- Aseptic Filling Technician Scarcity:Ultrahigh-temperature processing expertise concentrates among legacy dairy engineering talent pools nearing retirement.
- Non-GMO Project Verification Backlogs:Six-month queue delays product launches during peak Q1 fitness seasonality windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RTD Protein Beverages Market |
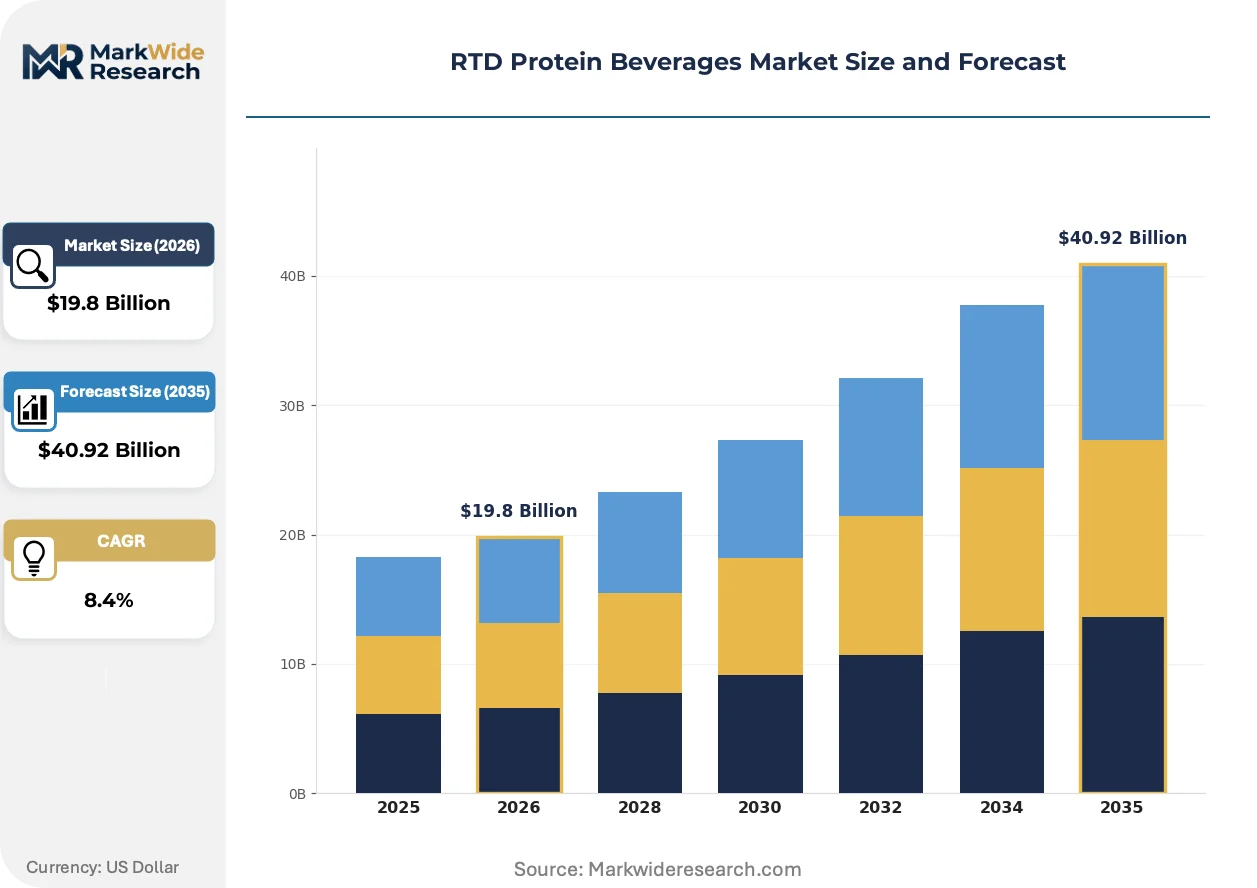
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $40.92 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dairy-Based, Plant-Based, Nutritional Shakes, Energy-Infused End User: Athletes, Fitness Enthusiasts, Busy Professionals, Health-Conscious Consumers Packaging Type: Bottles, Cans, Tetra Packs, Pouches Flavor Profile: Chocolate, Vanilla, Strawberry, Coffee |
| Companies Covered | Danone SA, Abbott Nutrition, Glanbia PLC, Vital Proteins, Post Holdings Inc., PepsiCo Inc., Nestlé S.A., Koia Inc., The Coca-Cola Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RTD Protein Beverages Market Strategic Shifts & Innovations
Reformulation science and channel restructuring are compressing traditional competitive moats. Three forces now determine which formulations capture shelf space and consumer loyalty.
Precision fermentation-derived whey proteins from Perfect Day and similar biotech platforms are rendering obsolete conventional dairy supply chains for premium-positioned SKUs. Early adopters in the sports nutrition segment now specify lab-grown protein isolates in RFPs. This biotechnology is rendering obsolete the geographic constraints that historically tied protein sourcing to pastureland availability.
EU Green Deal nutritional labeling requirements now mandate front-of-pack environmental scoring that penalizes high-carbon dairy formulations. Industrial consequence: reformulation teams prioritize pea and fava blends to maintain retail access in France and Germany. Medical nutrition applications face compressed margins as EFSA tightens substantiation standards for muscle-maintenance claims.
Retail buyers now unbundle after-sales service from product procurement, demanding separate accountability for spoilage rates and velocity data. Convenience store chains in the United States are replacing traditional distributor relationships with direct manufacturer partnerships that include real-time inventory monitoring. This disintermediation is most visible in Texas and Florida, where Buc-ee's and Wawa are building captive RTD protein sets.
RTD Protein Beverages Market Segmentation
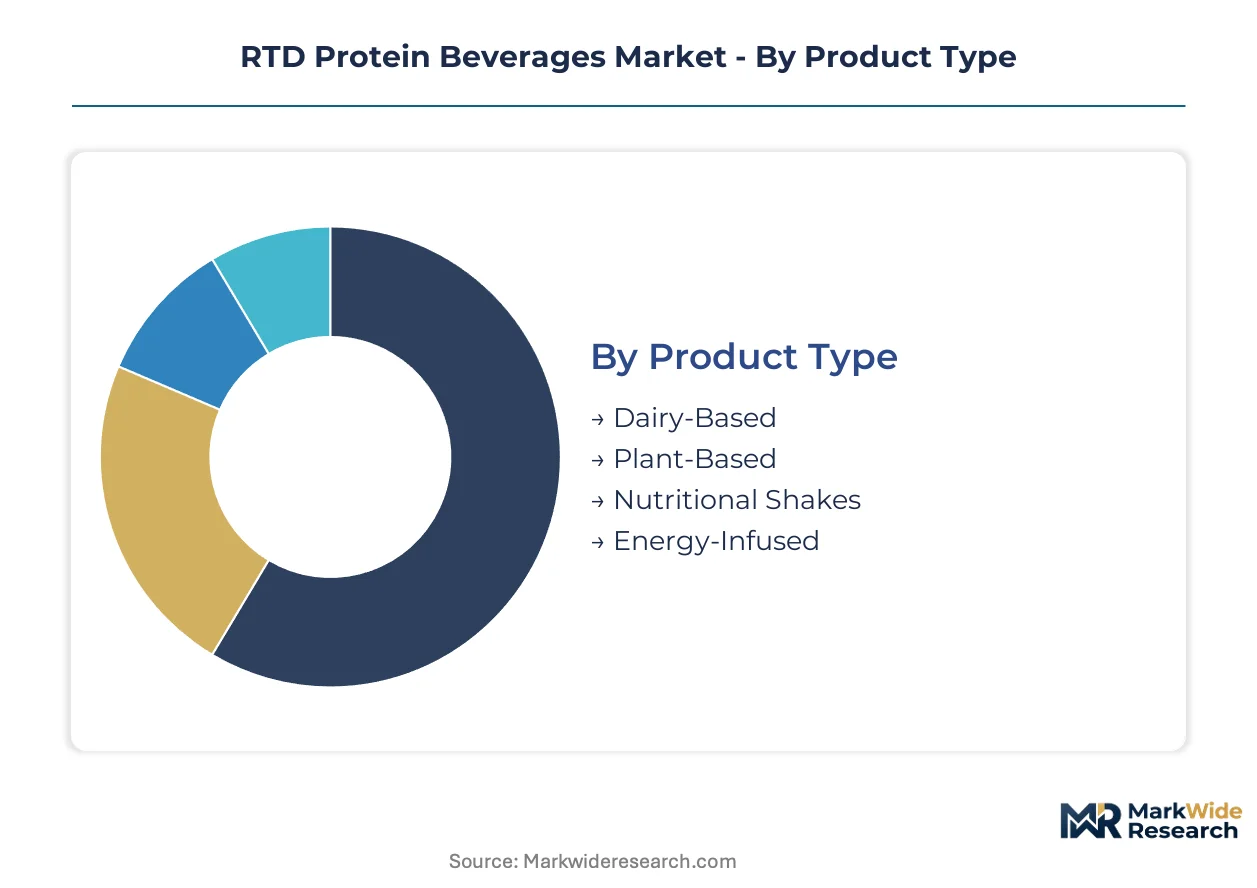
Segmentation in RTD protein beverages determines formulation priorities, shelf placement, and margin architecture. Product type and end-user alignment dictate whether brands compete on clinical credibility, taste accessibility, or convenience velocity. Packaging and flavor choices further stratify price tiers and channel access across retail environments.
Product Type:
Cost tier differentiation separates commodity-adjacent formulations from premium-positioned clinical and sports nutrition SKUs. Each product architecture carries distinct supply chain requirements and certification burdens that reshape competitive economics.
- Dairy-Based:Whey and casein isolates deliver complete amino acid profiles with established bioavailability metrics. Demand concentrates among older consumers in the United States where familiar taste profiles support premium pricing at convenience retail. FDA nutrition labeling compliance and established whey protein isolate supply chains sustain margin pools despite New Zealand milk powder export volatility.
- Plant-Based:Oat, pea, and fava protein extractions now achieve price parity with dairy formulations in North American and European retail. Fitness enthusiasts in Germany and France drive volume as EU Green Deal front-of-pack environmental scoring penalizes high-carbon alternatives. Declining input costs and MEE dual carbon alignment in China accelerate manufacturing localization.
- Nutritional Shakes:Meal-replacement formulations with vitamin fortification target clinical nutrition and weight management applications.
- Energy-Infused:Caffeine and adaptogen additions compete with coffee and energy drink categories for morning consumption occasions.
Dairy-Based commands the established base. The steepest expansion runs through Plant-Based.
End User:
Customer type segmentation maps protein consumption occasions to distinct channel strategies and messaging architectures. Each cohort presents divergent price sensitivity and loyalty patterns.
- Fitness Enthusiasts:Post-workout recovery protocols now prioritize portable single-serve formats over whole-food alternatives. This cohort expands fastest in the United States where gym culture penetration and subscription replenishment programs capture lifetime value through personalized dosing algorithms.
- Health-Conscious Consumers:Mainstream grocery channel penetration drives volume expansion through familiar flavor profiles and clean-label certification. USDA organic and Non-GMO Project standards segment pricing tiers at Whole Foods and natural channel retail.
- Athletes:Competitive and collegiate sports programs demand batch-tested formulations with banned-substance certification.
- Busy Professionals:Meal-replacement positioning targets morning and afternoon consumption occasions in urban convenience retail.
Health-Conscious Consumers anchor volume scale. Fitness Enthusiasts generate the steepest growth trajectory.
Packaging Type:
Volume and shelf-life requirements dictate aseptic processing investments and distribution radius economics. Format choice directly determines channel access and spoilage risk profiles.
- Bottles:PET and HDPE formats dominate convenience store and gym vending placement with resealable functionality. United States retail buyers now demand real-time inventory monitoring and separate accountability for spoilage rates through direct manufacturer partnerships.
- Tetra Packs:Aseptic carton technology enables ambient distribution with extended shelf life for pharmacy and clinical nutrition channels. BfArM guidelines in Germany open reimbursement-adjacent positioning for medical-grade formulations.
- Cans:Aluminum formats compete in energy drink adjacent positioning with superior chill speed and recycling credentials.
- Pouches:Flexible packaging reduces shipping cube for direct-to-consumer subscription models and outdoor recreation use cases.
Bottles maintain channel dominance. Tetra Packs climb fastest through pharmacy and clinical expansion.
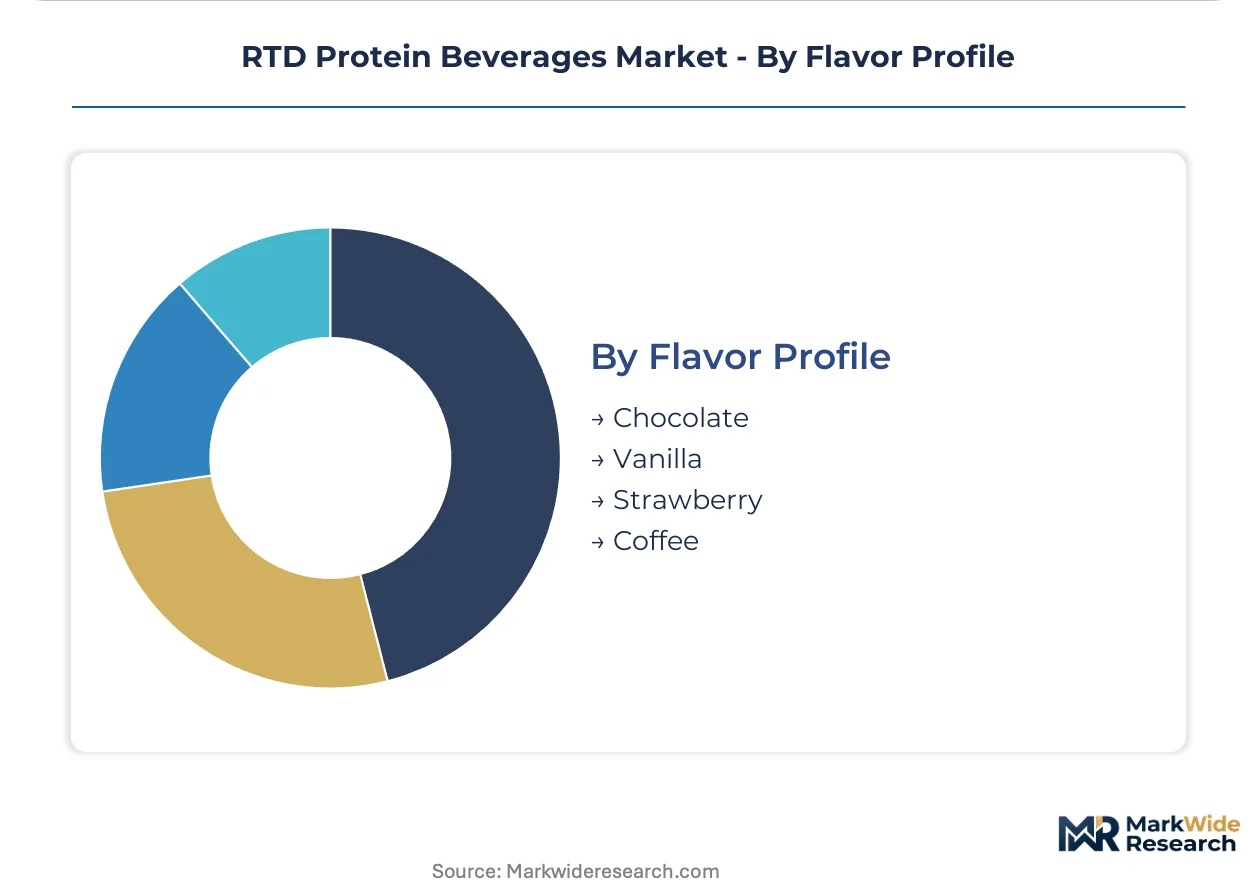
Flavor Profile:
Maturity and taste accessibility stratify consumer acquisition costs and reformulation risk across the installed base. Legacy flavors carry sugar reduction compliance burdens while novel profiles drive trial.
- Chocolate:Dominant SKU across dairy and plant-based portfolios with established cocoa masking capabilities for protein off-notes. FDA added sugar labeling requirements force reformulation that degrades taste profiles in legacy formulations.
- Coffee:Caffeine synergy positions against Starbucks and energy drink categories for morning consumption occasions. Flavor rotation algorithms in subscription programs personalize dosing for United States urban professionals.
- Vanilla:Neutral base for smoothie customization and clinical nutrition applications with minimal allergen risk.
- Strawberry:Fruit positioning targets younger demographics and female-skewed health-conscious segments.
Chocolate retains the volume base. Coffee gains share fastest through energy category adjacency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across geographies. United States consumers absorb premium pricing for functional convenience, while Chinese buyers demand localization subsidies and European purchasers weight environmental scoring into willingness-to-pay calculations.
United States
Gym culture penetration and convenience retail density sustain premium pricing for single-serve formats. FDA nutrition labeling requirements and added sugar disclosure mandates force reformulation investments that reshape competitive economics. Texas and Florida convenience chains now demand direct manufacturer partnerships with real-time inventory monitoring, bypassing traditional distributor tiers.
Germany
Medical nutrition positioning under BfArM guidelines opens pharmacy channel access for clinical-grade formulations. EU Green Deal front-of-pack environmental scoring penalizes high-carbon dairy SKUs, accelerating pea and fava protein adoption. Industrial concentration in Bavaria and North Rhine-Westphalia hosts precision fermentation scale-up facilities serving European sports nutrition brands.
China
State-backed manufacturing incentives under MEE dual carbon targets accelerate plant-based protein localization. SAMR functional food registration requirements create compliance barriers for imported clinical nutrition entrants. Yangtze River Delta and Pearl River Delta clusters concentrate aseptic filling capacity for domestic brands targeting fitness enthusiasts in Shanghai and Shenzhen.
United Kingdom
Subscription replenishment programs capture lifetime value among London-based urban professionals seeking personalized dosing algorithms. FSA novel food approval timelines delay precision fermentation protein launches relative to EU counterparts. Southeast England logistics hubs service direct-to-consumer brands competing with Boots and Holland & Barrett pharmacy placements.
India
FSSAI functional beverage classification tightening restricts unsubstantiated performance marketing for imported brands. PLI scheme incentives for food processing infrastructure attract contract manufacturing investment in Maharashtra and Gujarat. Mumbai and Bangalore fitness studio chains now specify clean-label certification in procurement tenders for post-workout recovery formats.
RTD Protein Beverages Market Key Industry Players
Capability concentration sits with specialized nutrition formulators; scale advantage sits with diversified beverage conglomerates. The market structures around three tiers: clinical credibility anchors, dairy and plant protein sourcing specialists, and convenience velocity platforms. Strategic moves concentrate on direct-to-consumer subscription capture and precision fermentation protein integration.
Within the specialized nutrition tier, Danone SA and Abbott Nutrition exemplify divergent archetypes—one leveraging dairy infrastructure for medical applications, the other anchoring through pharmacy channel control. Glanbia PLC occupies a position at the sourcing-scale intersection, spanning dairy and plant protein supply chains across multiple continents. These three entities represent the capability-scale tension that defines competitive positioning in clinical and sports nutrition segments.
| Leading Market Players |
|---|
| Danone SA |
| Abbott Nutrition |
| Glanbia PLC |
| Vital Proteins |
| Post Holdings Inc. |
| PepsiCo Inc. |
| Nestlé S.A. |
| Koia Inc. |
| The Coca-Cola Company |
| Others |
Cost & Logistics Intelligence
Whey isolate supply concentration in New Zealand and the European Union creates simultaneous pricing volatility and geographic dependency that compresses margins for dairy-based SKUs while forcing plant-based reformulation investments across tiered positioning strategies.
Pricing Analysis
Subscription replenishment revenue drives lifetime value capture through personalized flavor rotation and adaptive protein dosing algorithms. Three-tier pricing structure across premium, standard, and economy levels separates clinical-grade formulations with EFSA verification from mainstream grocery SKUs and private-label alternatives. Pricing pressure stems from oat and pea protein extraction cost declines enabling price parity with dairy formulations. Health-conscious consumers in mainstream retail exhibit highest price sensitivity; fitness enthusiasts in direct-to-consumer channels absorb premium positioning.
Supply Chain Analysis
Upstream feedstock for whey protein isolates draws from New Zealand dairy cooperatives and European Union milk powder exporters, while plant-based inputs source from Canadian pea protein processors and Nordic oat extraction facilities. Raw material dependencies center on whey isolate supply contracts, pea protein concentrate shipments, and aseptic packaging film imports. Single-source vulnerability concentrates in New Zealand whey exports subject to climate-driven production swings. Distribution runs through direct manufacturer partnerships with convenience chains in Texas and Florida, bypassing traditional distributor tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
RTD protein beverages track a cyclical recovery driven by post-pandemic gym culture renormalization and subscription replenishment program maturation that recaptures pre-2020 consumption velocity.
For Market Incumbents: Build certification moats through accelerated EFSA health claim verification and USDA organic certification investments that lock pharmacy and natural channel access against emerging precision fermentation entrants. Consolidate aseptic filling technician pipelines through apprenticeship partnerships with Bavarian dairy engineering programs to offset retirement-driven capability scarcity.
For New Entrants and Emerging Players: Build out German pharmacy channel positioning under BfArM guidelines where reimbursement-adjacent revenue streams remain underpenetrated by global brands. Target precision fermentation-derived protein integration for sports nutrition RFPs, leveraging lab-grown isolate specifications to bypass geographic supply constraints.
For Investors and Strategic Acquirers: EU Green Deal front-of-pack environmental scoring reshapes the acquisition landscape toward plant-based formulation capabilities with established clean-label certification. Long-term viability centers on dual carbon alignment and MEE incentive access in China. Watch FDA added sugar labeling enforcement intensity as the inflection signal for reformulation-driven consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Protein Integration | Lab-grown whey isolates from Perfect Day platforms eliminate pastureland-dependent supply constraints for premium SKUs. |
| Direct-to-Consumer Subscription Launch | Replenishment programs capture lifetime value through adaptive dosing algorithms for United States fitness enthusiasts. |
| German Pharmacy Channel Expansion | BfArM-compliant formulations unlock reimbursement-adjacent revenue streams previously inaccessible to functional beverage entrants. |
| Clean-Label Certification Acceleration | USDA organic and Non-GMO Project verification secures Whole Foods placement against private-label competition. |
| Aseptic Filling Technician Pipeline | Apprenticeship partnerships with legacy dairy engineering programs offset retirement-driven capability scarcity. |
Research Approach
A standing panel of brand managers, category buyers at convenience retailers, supply planners, and sports nutrition formulators provided ongoing calibration through quarterly interviews. Primary fieldwork combined with secondary validation from FDA nutrition labeling databases, EFSA health claim registers, Nielsen retail audit data, and customs import records. Bottom-up SKU-level volume builds triangulated against top-down category expenditure estimates.
Scenario-bracketing framed projections across the modeling period, with segmentation dimensions spanning product type, end-user cohort, packaging format, and regional regulatory cluster. CAGRs derived from historical trajectory analysis and elasticity-adjusted penetration modeling. Forecast inputs incorporated gym membership recovery curves, subscription program adoption rates, and plant-based protein cost decline slopes.
The forecast holds incumbent behavior within observed patterns; aggressive moves by precision fermentation biotechnology platforms or state-backed Chinese manufacturing consortia would shift outcomes. Cross-checking against Euromonitor packaged beverage volume data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Functional Shots Market
Functional Food and Beverage
Europe Medical Foods Market
Functional Food and Beverage
Vegan Brain Food Market
Functional Food and Beverage
Functional Dairy Products Market
Functional Food and Beverage
Vitamin Functional Water Market
Functional Food and Beverage
Saudi Arabia Protein Bar Market
Functional Food and Beverage
Functional Foods and Natural Health Products Market
Functional Food and Beverage
Galacto Oligosaccharides (GOS) Market
Functional Food and Beverage
Asia-Pacific Functional Mushroom Market
Functional Food and Beverage
Asia-Pacific Beauty Drinks Market
Functional Food and Beverage
Functional Chewing Gums Market
Functional Food and Beverage
Natural Functional Food Market
Functional Food and Beverage
Digestive Health Drinks Market
Functional Food and Beverage
Protein-Based Fat Replacer Market
Functional Food and Beverage
APAC Functional Food Ingredients Market
Functional Food and Beverage
Very Low Calorie Desserts Market