
 Functional Food and Beverage Market | 2026-2036
Functional Food and Beverage Market Size, Share, and Industry Trends Forecast 2026-2036
Functional Food and Beverage Market Intelligence
Market Context
Germany is narrowing its functional ingredient production gap through expanded fermentation capacity and contract manufacturing partnerships. Nestlé S.A. leverages its dairy science heritage to dominate probiotic yogurt platforms across European retail channels. Danone S.A. sustains competitive pressure through specialized digestive health positioning and medical nutrition credibility. PepsiCo, Inc. anchors its portfolio with fortified snack and beverage hybrids that bridge indulgence and wellness positioning.
Technical Definition and Segment Structure
Functional food and beverage denotes edible products formulated with bioactive compounds, live microbial cultures, or nutrient fortificants that deliver targeted physiological benefits beyond basic nutrition, typically standardized to minimum viable counts or concentration thresholds. Industrial purpose centers on preventive health maintenance, performance optimization, and disease-risk reduction for consumer and clinical channels. Probiotic drinks command the largest revenue pool due to established gut-health messaging and refrigerated distribution infrastructure, while plant-based proteins represent the fastest-expanding category as formulation science improves amino acid completeness and taste parity. Nutraceutical supplements concentrate margin pools through direct-to-consumer subscription models and practitioner-channel exclusivity.
Regulatory Framework
EFSA health-claim authorization processes, FDA qualified health claim pathways, and Japan's FOSHU regulatory system collectively determine which functional benefits manufacturers may communicate on-label and in advertising. These frameworks create divergent market access conditions, with stricter jurisdictions favoring firms with dedicated regulatory affairs capacity and clinical trial investment. Stakeholders must monitor evolving probiotic strain-specific approvals and emerging precision-fermentation ingredient classifications to anticipate reformulation requirements and first-mover positioning.
Market Dynamics
Precision fermentation infrastructure is compressing ingredient production timelines while EFSA and FDA probiotic strain approvals are fragmenting formulation pipelines across jurisdictions. Contract manufacturers in Germany and China are capturing margin pools previously held by integrated CPG conglomerates through specialized bioreactor capacity.
Growth Catalysts
- FOSHU regulatory pathway:Japan's Foods for Specified Health Uses framework accelerates gut-health product commercialization by pre-approving functional claims, reducing time-to-shelf for fermented dairy entrants targeting digestive wellness positioning.
- Aging demographics in Germany:Medical nutrition demand from institutional healthcare channels pulls fortified beverage volumes through pharmacy and hospital procurement systems, creating dedicated distribution infrastructure for clinical-grade formulations.
- Bioreactor scale-up:Single-use fermentation systems enable rapid strain switching and smaller batch economics, allowing mid-sized producers to compete with legacy dairy giants on probiotic viability and customization speed.
Market Restraints
- Protein input volatility:Pea and fava bean concentrate prices fluctuate with Canadian and Baltic harvest cycles, compressing plant-based yogurt margins during drought periods and forcing reformulation toward less optimal amino acid profiles.
- Strain patent thickets:Exclusive licensing agreements around Lactobacillus and Bifidobacterium variants concentrate viable commercial strains among three European culture collections, raising royalty burdens for new market entrants.
- EFSA health-claim rejection rate:The European regulator's 80% plus refusal rate on gut-microbiome claims forces costly clinical trial investments with uncertain authorization outcomes, freezing marketing messaging for prebiotic fiber products.
Strategic Opportunities
- India's FSSAI functional food notification:The 2024 streamlined approval pathway for probiotics and omega-3 fortification opens retail access for international brands previously blocked by lengthy safety assessment queues, with urban pharmacy chains as primary launch channels.
- Postbiotic ingredient classification:Heat-inactivated microbial metabolites bypass cold-chain requirements and extended stability concerns of live cultures, enabling ambient distribution into convenience retail formats previously inaccessible to probiotic beverages.
- Sports nutrition-practitioner channel convergence:Registered dietitian networks in the United States are adopting direct-dispense models for clinical-grade protein and recovery formulations, bypassing mass retail slotting fees and capturing higher per-unit economics through subscription protocols.
Industry Challenges
- Microbiome assay standardization:Inconsistent CFU enumeration methods across ISO 7889, FDA BAM, and proprietary rapid tests create batch-release disputes between contract manufacturers and brand owners, delaying inventory releases and triggering penalty clauses.
- Clean-label formulation trade-offs:Removal of synthetic preservatives and emulsifiers to meet retailer ingredient blacklists compromises shelf stability in ambient plant-based beverages, forcing accelerated turnover requirements and shrinkage absorption by distributors.
Report Scope
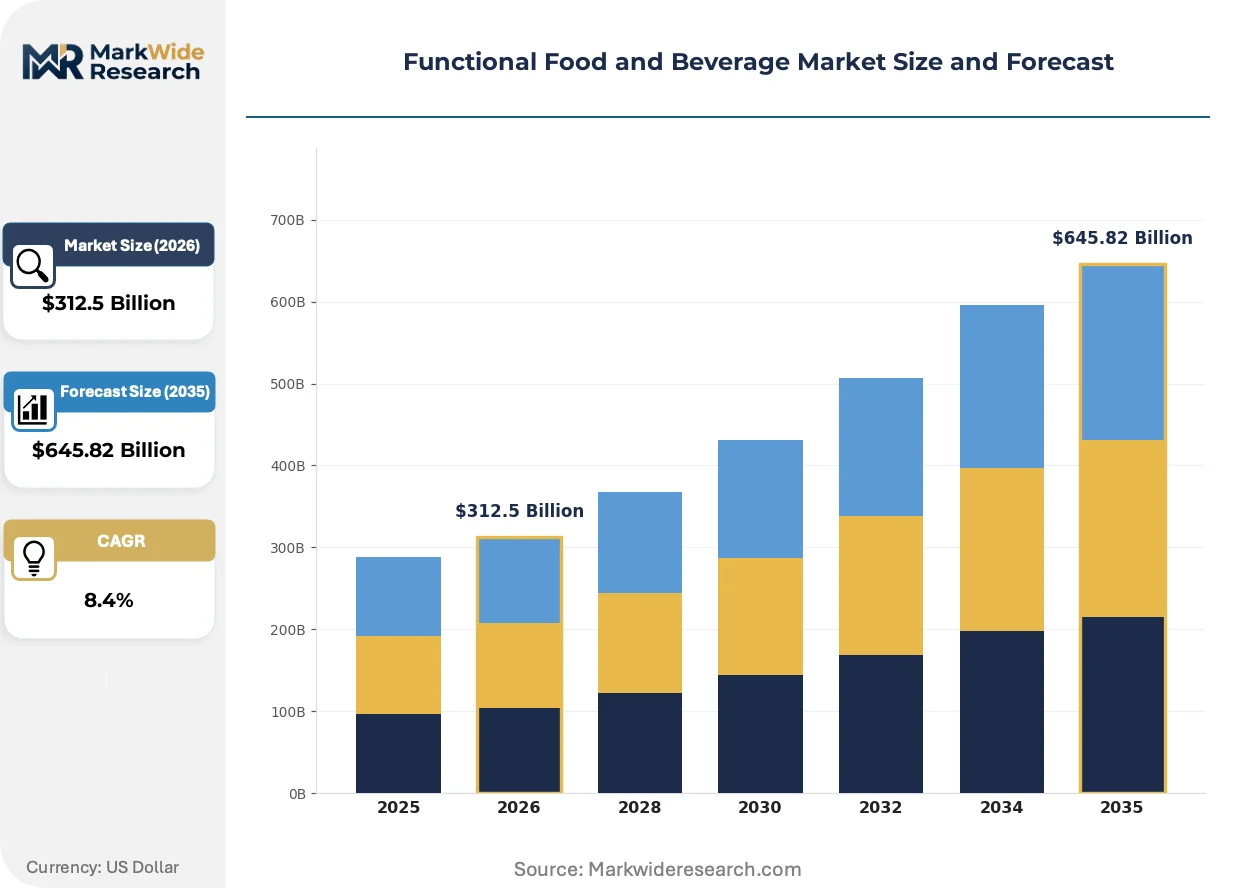
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Functional Food and Beverage Market |
| Market Size in 2026 | $312.5 Billion |
| Market Size in 2035 | $645.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Probiotic Drinks, Fortified Cereals, Nutraceutical Supplements, Dietary Fibers, Omega-3 Enriched Products, Plant-Based Proteins Application: Digestive Health, Immune Support, Weight Management, Cardiovascular Wellness, Bone Strength, Cognitive Enhancement End User: Fitness Enthusiasts, Elderly Consumers, Children & Adolescents, Pregnant Women, Weight Watchers, Vegetarians Distribution Channel: Supermarkets, Specialty Health Stores, Online Retailers, Pharmacies, Direct Selling, Convenience Stores |
| Companies Covered | Red Bull GmbH, Danone S.A., Nestlé S.A., Keurig Dr Pepper Inc., General Mills, Inc., PepsiCo, Inc., Monster Beverage Corporation, Suntory Beverage & Food Limited, The Coca-Cola Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Functional Food and Beverage Market Strategic Shifts & Innovations
Bioprocessing advances are collapsing the boundary between pharmaceutical-grade precision and food-scale economics, while regulatory divergence between EFSA's evidence thresholds and FDA's enforcement discretion creates parallel formulation tracks for Atlantic-facing producers.
Precision fermentation-derived whey proteins are hybridizing dairy and alternative protein supply chains by delivering identical amino acid sequences without lactose or environmental grazing footprints. Sports nutrition formulators in the United States and Germany are adopting these ingredients at pilot scale, replacing both conventional dairy isolates and first-generation pea proteins. The technology is hybridizing competitive positioning by enabling legacy dairy processors to enter plant-based segments without alienating core farm-supplier relationships or investing in crop-sourcing infrastructure.
EFSA's 2024 updated guidance on beneficial physiological effect substantiation tightens statistical power requirements for gut-microbiome trials, forcing sponsors toward larger cohort sizes and extended intervention periods. The industrial consequence is consolidation of clinical trial execution among three European CROs with dedicated nutrition expertise, raising barriers for mid-sized ingredient suppliers. Probiotic yogurt platforms targeting Northern European retail channels are most affected, with several brands withdrawing immunity-related claims and pivoting to softer wellness positioning pending dossier resubmission.
Direct-to-practitioner distribution is displacing mass retail as the primary growth channel for clinical nutrition segments in Germany and the United States. Registered dietitians and sports medicine physicians are curating personalized supplement protocols through white-label platforms, capturing patient adherence data that informs iterative formulation. This channel rotation is most visible in metabolic health and recovery nutrition verticals, where reimbursement codes and insurance pre-authorization workflows create stickier customer relationships than supermarket repeat purchase patterns.
Functional Food and Beverage Market Segmentation
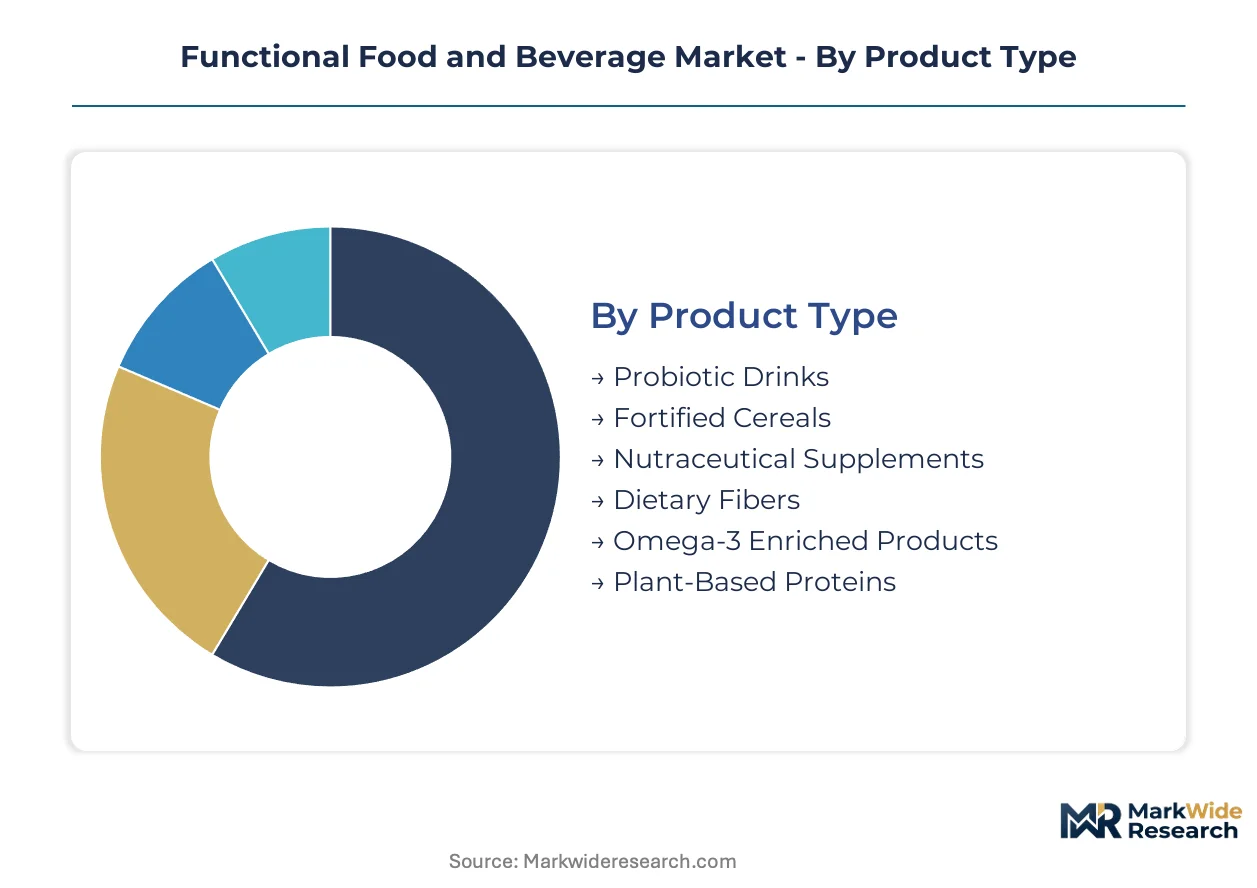
Functional food and beverage segmentation reveals distinct formulation, distribution, and consumer targeting strategies that separate mass-market penetration from premium clinical positioning. Manufacturers align R&D investment and regulatory dossier preparation with specific segment economics rather than pursuing horizontal coverage.
Product Type:
Cost tier differentiation separates refrigerated live-culture platforms from ambient-stable fortification formats, with production infrastructure requirements determining competitive entry points.
- Probiotic Drinks:Fermented dairy and non-dairy beverages containing live microbial cultures standardized to minimum CFU counts at expiration. German and Chinese contract manufacturers dominate refrigerated supply chains for European and Asian retail channels, though cold-chain dependency limits rural penetration.
- Plant-Based Proteins:Pea, fava, and precision-fermentation-derived protein isolates formulated for amino acid completeness. Sports nutrition brands in the United States and Germany are accelerating adoption as taste parity improves and sustainability credentials harden procurement specifications.
- Fortified Cereals:Grain-based breakfast products with added vitamins, minerals, or fiber matrices.
- Nutraceutical Supplements:Concentrated bioactive compounds in capsule, tablet, or powder delivery formats.
- Dietary Fibers:Soluble and insoluble fiber isolates targeting digestive health applications.
- Omega-3 Enriched Products:EPA and DHA fortification across beverages, dairy, and bakery categories.
Probiotic drinks command the established base. The steepest expansion runs through plant-based proteins.
Application:
Application focus determines clinical trial investment intensity and regulatory pathway selection, with EFSA health-claim substantiation requirements varying sharply across physiological benefit categories.
- Digestive Health:Gut-microbiome modulation through live cultures, prebiotic fibers, or postbiotic metabolites. EFSA's 80%-plus rejection rate on gut-health claims has forced reformulation toward softer wellness positioning in European markets pending dossier resubmission.
- Sports Nutrition:Performance optimization and recovery acceleration through protein timing and amino acid profiles. Registered dietitian networks in the United States are adopting direct-dispense models, bypassing mass retail slotting fees through subscription protocols.
- Immune Support:Vitamin, mineral, and botanical formulations targeting pathogen resistance.
- Weight Management:Satiety-inducing fibers and meal-replacement formats.
- Cardiovascular Wellness:Lipid-modulating omega-3 and plant sterol applications.
- Bone Strength:Calcium and vitamin D fortification for aging demographics.
- Cognitive Enhancement:Nootropic and phospholipid interventions for mental performance.
Digestive health absorbs the largest clinical trial budgets. Sports nutrition is climbing the fastest as practitioner-channel distribution displaces retail.
End User:
Customer type segmentation aligns formulation potency, packaging format, and channel strategy with distinct purchasing triggers and compliance patterns.
- Fitness Enthusiasts:High-protein, low-sugar formulations with transparent labeling and batch-testing certifications. German sports nutrition brands prioritize this segment through specialized retail and gym-based vending.
- Elderly Consumers:Texture-modified, nutrient-dense formats addressing sarcopenia and micronutrient deficiencies. Medical nutrition demand from German institutional healthcare channels pulls fortified beverage volumes through pharmacy and hospital procurement systems.
- Children & Adolescents:Palatability-optimized fortification with stringent safety dossier requirements.
- Pregnant Women:Folate, DHA, and iron-focused formulations with obstetrician endorsement protocols.
- Weight Watchers:Portion-controlled, satiety-engineered meal replacements.
- Vegetarians:Complete-protein and B12-fortified alternatives to animal-derived nutrition.
Elderly consumers anchor institutional procurement volumes. Fitness enthusiasts are gaining share fastest through direct-to-consumer subscription models.
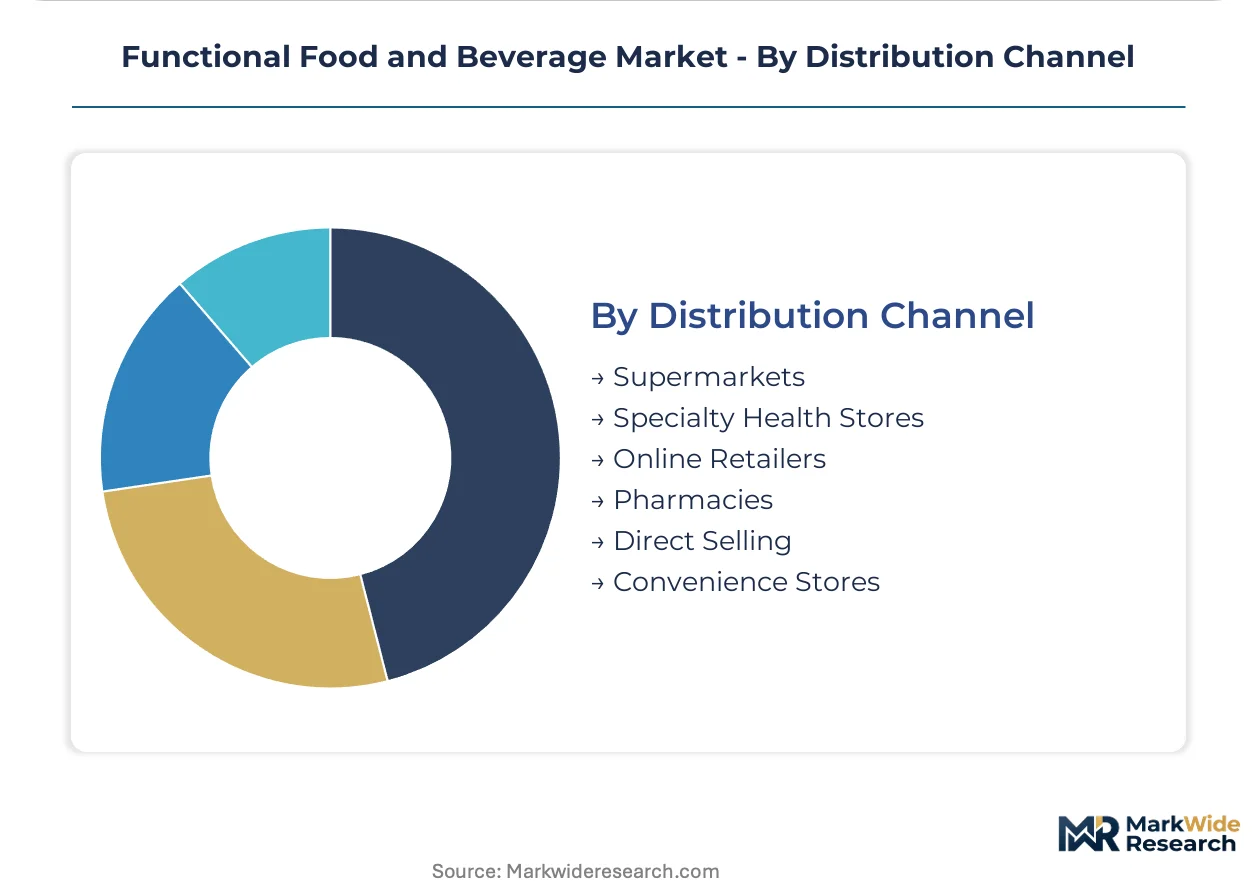
Distribution Channel:
Channel selection determines margin structure, shelf-life requirements, and consumer education intensity, with ambient-stable formats accessing broader retail footprints than cold-chain-dependent alternatives.
- Supermarkets:Mass-market penetration for established brands with slotting fee capacity and promotional calendar alignment. Clean-label requirements from German and US retail chains are forcing preservative reformulation and accelerated turnover.
- Online Retailers:Direct-to-consumer platforms enabling subscription protocols and personalized bundling. India's urban pharmacy chains are emerging as primary launch channels for international brands following FSSAI's streamlined approval pathway.
- Specialty Health Stores:Curated assortments with practitioner endorsement and education support.
- Pharmacies:Clinical-grade formulations with reimbursement code access.
- Direct Selling:Network marketing models with high-touch customer education.
- Convenience Stores:Impulse-oriented single-serve formats with ambient stability requirements.
Supermarkets maintain the volume base. Online retailers are expanding most quickly as postbiotic ingredients enable ambient distribution previously inaccessible to live-culture products.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA qualified health claim pathways anchor the United States as the dominant geography, while EFSA authorization processes and Japan's FOSHU framework create divergent market access conditions across Atlantic and Pacific markets. Manufacturing capacity concentrates in Germany, China, and the United States, with contract fermentation facilities capturing margin pools from integrated conglomerates.
United States
Fitness enthusiasts and aging demographics drive demand for sports nutrition and clinical nutrition segments. FDA enforcement discretion on structure-function claims enables faster commercialization than EFSA jurisdictions, though qualified health claims require substantial clinical evidence. Texas and California host the largest precision fermentation scale-up facilities, with single-use bioreactor systems enabling rapid strain switching for mid-sized producers.
Germany
Medical nutrition demand from institutional healthcare channels pulls fortified beverage volumes through pharmacy and hospital procurement systems. EFSA's 80%-plus rejection rate on gut-microbiome claims forces costly clinical trial investments with uncertain authorization outcomes. Bavaria and North Rhine-Westphalia concentrate contract manufacturing partnerships and expanded fermentation capacity, narrowing the functional ingredient production gap.
China
Urban middle-class consumers and aging populations fuel probiotic yogurt and fortified beverage uptake. SAMR regulations on health-food registration and dual carbon goals reshape manufacturing compliance requirements. Yangtze River Delta and Pearl River Delta clusters dominate domestic production capacity, with local brands leveraging cold-chain infrastructure for refrigerated distribution.
Japan
FOSHU regulatory pre-approval of functional claims accelerates gut-health product commercialization, reducing time-to-shelf for fermented dairy entrants. METI industrial policy supports precision fermentation research and postbiotic ingredient development. Kanto and Kansai regions maintain concentrated retail and manufacturing infrastructure for functional beverage distribution.
India
FSSAI's 2024 streamlined approval pathway for probiotics and omega-3 fortification opens retail access for international brands previously blocked by lengthy safety assessment queues. Urban pharmacy chains emerge as primary launch channels for clinical-grade formulations. Maharashtra and Karnataka concentrate manufacturing investments and direct-to-consumer subscription platform development.
Functional Food and Beverage Market Key Industry Players
Integrated beverage conglomerates and specialized dairy-science groups split the market between mass retail penetration and clinical nutrition credibility. The vendor base organizes around three strategic archetypes: legacy CPG giants with slotting fee capacity, fermentation-focused contract manufacturers with bioreactor specialization, and direct-to-practitioner platforms capturing subscription economics. Dominant competitive moves include precision fermentation capacity expansion and practitioner-channel partnership formation to bypass supermarket slotting requirements.
Among Swiss and French integrated conglomerates, Nestlé S.A. and Danone S.A. exemplify the dairy-science heritage archetype, leveraging probiotic yogurt platforms and medical nutrition credibility across European retail and institutional channels. PepsiCo, Inc. occupies a position within the fortified snack and beverage hybrid segment, bridging indulgence and wellness positioning through ambient-stable distribution formats. These three entities represent contrasting strategic postures: clinical-grade formulation depth versus mass-market formulation breadth versus hybrid category creation.
| Leading Market Players |
|---|
| Red Bull GmbH |
| Danone S.A. |
| Nestlé S.A. |
| Keurig Dr Pepper Inc. |
| General Mills, Inc. |
| PepsiCo, Inc. |
| Monster Beverage Corporation |
| Suntory Beverage & Food Limited |
| The Coca-Cola Company |
| Others |
Cost & Logistics Intelligence
Canadian and Baltic pea protein concentrates anchor upstream supply for plant-based formulations, concentrating margin capture with crop processors and leaving finished goods manufacturers exposed to harvest volatility and forced reformulation cycles. This feedstock dependency cascades downstream through cold-chain logistics costs and strain licensing royalties, compressing workable price bands for mid-tier entrants.
Pricing Analysis
German refrigerated probiotic drinks command substantial premiums over ambient-stable Asian equivalents, reflecting cold-chain infrastructure investments and EFSA dossier amortization. Three-tier pricing structure across premium clinical-grade, standard mass-market, and economy private-label tiers separates pharmacy-dispensed medical nutrition from supermarket wellness positioning. Cost compression in economy plant-based yogurts is intensifying because pea concentrate drought premiums force amino acid profile compromises. Fitness enthusiasts demonstrate lowest price sensitivity through subscription protocols, while elderly institutional procurement shows highest sensitivity to per-unit reimbursement thresholds.
Supply Chain Analysis
Pea and fava bean protein isolates draw from Canadian prairie harvests and Baltic processing facilities, with precision fermentation capacity scaling in Germany and the United States as alternative supply anchors. Live probiotic cultures, omega-3 algal oils, and postbiotic metabolites constitute critical input dependencies. Single-source vulnerability concentrates around three European culture collections controlling Lactobacillus and Bifidobacterium strain patents. Distribution runs through refrigerated trucking networks for live-culture products and ambient parcel logistics for postbiotic-enabled direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation infrastructure is collapsing traditional boundaries between pharmaceutical-grade and food-scale economics, creating platform interoperability between clinical nutrition and mass-market wellness segments.
For Market Incumbents: Insulate core dairy-science positions through captive strain development partnerships that bypass European culture collection royalty structures. Backward integration into single-use bioreactor capacity in Bavaria and Texas reduces dependency on contract manufacturing margin capture. EFSA's tightened statistical power requirements for gut-microbiome claims threaten incumbent marketing architectures, necessitating dossier resubmission reserves and softer wellness pivot capabilities. For New Entrants and Emerging Players: Build out direct-to-practitioner distribution infrastructure targeting registered dietitian networks in Germany and the United States, bypassing supermarket slotting fee barriers entirely. India's FSSAI streamlined approval pathway represents the most penetrable regulatory entry point for international probiotic and omega-3 brands, with urban pharmacy chains as the specific go-to-market anchor. Postbiotic ingredient classification enables ambient distribution into convenience retail formats previously inaccessible to live-culture competitors. For Investors and Strategic Acquirers: Capital is best deployed toward precision fermentation specialists with demonstrated strain-switching agility and pharmaceutical-grade quality systems. Long-term viability across the analysis window favors assets capable of serving both clinical nutrition reimbursement channels and mass-market wellness positioning. Watch for FSSAI approval velocity in India as the specific signal indicating whether regulatory streamlining translates to sustainable market access or triggers competitive oversupply.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Expansion | Single-use bioreactor deployment in Texas and Bavaria collapses production timelines for probiotic strain customization. |
| Direct-to-Practitioner Channel Development | Registered dietitian network partnerships in Germany capture subscription economics beyond mass retail slotting constraints. |
| Postbiotic Ingredient Classification Investment | Heat-inactivated metabolite formulations bypass cold-chain requirements for convenience retail ambient distribution access. |
| EFSA Dossier Resubmission Capability | Clinical trial execution partnerships with European CROs preserve gut-health claim authorization optionality. |
| FSSAI Regulatory Pathway Navigation | Streamlined probiotic approval processes in India unlock pharmacy chain launch channels for international brands. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with fermentation technology directors, regulatory affairs leads at functional ingredient suppliers, pharmacy chain category managers, and sports nutrition brand managers; and secondary validation through EFSA health-claim authorization databases, FDA qualified health claim filings, FSSAI notification records, and customs trade data on pea protein concentrate flows. Bottom-up volume modeling triangulated against top-down expenditure estimates from institutional healthcare procurement systems.
Forecast inputs considered probiotic strain approval velocity, precision fermentation scale-up economics, and practitioner-channel adoption curves across the projection horizon. Segmentation dimensions modeled include product format stability requirements, application-specific clinical trial investment intensity, end-user compliance patterns, and distribution channel margin structures. CAGRs derived from iterative convergence between historical capacity expansion rates and regulatory pathway duration benchmarks, with specific weighting for EFSA rejection probability and FSSAI processing efficiency.
The forecast holds incumbent behavior within observed patterns; aggressive moves by precision fermentation specialists or regulatory arbitrageurs would shift outcomes substantially. Cross-checking against EMA nutrition-focused CRO pipeline data and Indian pharmacy chain expansion announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Functional Powdered Lipids Market
Functional Food and Beverage
Reduced Sugar Food and Beverages Market
Functional Food and Beverage
Functional Chewing Gums Market
Functional Food and Beverage
Digestive Health Drinks Market
Functional Food and Beverage
Functional Shots Market
Functional Food and Beverage
Middle East and Africa Protein Bar Market
Functional Food and Beverage
Protein-Based Fat Replacer Market
Functional Food and Beverage
Hydrogen Water Market
Functional Food and Beverage
Low Fat and Low Cholesterol Diet Foods Market
Functional Food and Beverage
Global Functional Mushrooms Market
Functional Food and Beverage
RTD Protein Beverages Market
Functional Food and Beverage
Instant Protein Beverages Market
Functional Food and Beverage
GCC Functional Food & Beverage Market
Functional Food and Beverage
Functional Flavor Market
Functional Food and Beverage
North America Functional Beverage Market
Functional Food and Beverage
North America Functional Water Market