
 France Food Acidulants Market | 2026-2036
France Food Acidulants Market Size, Share, and Industry Trends Forecast 2026-2036
France Food Acidulants Market Foresight
Asset-light leasing models for fermentation capacity is fragmenting competitive entry barriers in French acidulant supply. Jungbunzlauer Holding AG leverages captive citric acid fermentation networks across Eastern France. Corbion N.V. sustains lactic acid specialization through biotechnology-driven purity grades. Tate & Lyle PLC anchors its position via bulk logistics integration with Paris basin beverage bottlers.
Food acidulants comprise organic acids—citric, lactic, acetic, malic, and tartaric—typically manufactured through submerged fermentation or chemical synthesis, functioning to lower pH, enhance microbial stability, and modulate flavor profiles in processed foods. Citric acid dominates volume flows due to its versatility across beverages and confectionery, while malic acid captures faster growth in low-sugar formulation segments where tartness replacement becomes critical. Application segmentation shows beverages commanding the largest share of acidulant offtake, with dairy alternatives emerging as a structurally expanding niche as plant-based product lines multiply.
ANSM monitors acidulant safety thresholds under EU food additive frameworks, while DGCCRF enforces origin labeling and purity standards at retail level. FSSAI-aligned import checks on non-EU acidulant shipments create additional compliance layers for French ingredient distributors. Stakeholders must track evolving EU novel food consultations and fermentation-derived acid classifications to anticipate reformulation mandates and sourcing adjustments.
Market Dynamics
Clean-label formulation mandates from ANSM and DGCCRF are compressing acidulant specification windows, forcing beverage and dairy processors to validate fermentation-derived purity grades that exceed baseline EU thresholds.
Growth Catalysts
- EU Green Deal decarbonization targets:Fermentation-based citric acid production qualifies for carbon accounting advantages, pulling investment toward bioprocess capacity expansion in the Paris basin.
- Ready-to-drink beverage proliferation:Shelf-stable format demand concentrates acidulant offtake around high-volume bottling corridors in Rhône-Alpes and Île-de-France.
- Plant-based dairy alternatives:Oat and almond milk processors require malic acid for pH stabilization, creating new volume anchors outside traditional dairy acidification.
Market Restraints
- Input cost volatility:Molasses and corn syrup feedstock prices fluctuate with biofuel policy arbitrage, squeezing fermentation economics for domestic citric acid producers.
- Supply concentration risk:Eastern European fermentation capacity controls bulk citric acid import flows into France, exposing formulation houses to cross-border logistics friction.
- Regulatory friction:FSSAI-aligned import documentation requirements for non-EU acidulant shipments add compliance layers that delay just-in-time sourcing from Asian suppliers.
Strategic Opportunities
- Underpenetrated precision fermentation:Alsace biotechnology clusters could anchor microbial cell factory deployment for specialty acidulants currently imported from North American biotech suppliers.
- Regulatory tailwind from CSRD:Scope 3 emissions disclosure requirements favor local fermentation sourcing, rewarding French acidulant producers with carbon transparency advantages.
- Emerging clean-meat applications:Cultured protein startups in the Paris-Saclay ecosystem require food-grade acidulants for growth medium pH control, opening non-traditional demand channels.
Industry Challenges
- Fermentation engineering talent scarcity:Industrial microbiology and bioprocess optimization skill gaps constrain scale-up velocity for domestic acidulant biotechnology ventures.
- Legacy equipment retrofit costs:Existing chemical synthesis acidulant facilities face stranded asset risk as clean-label mandates accelerate fermentation adoption timelines.
- Multi-jurisdiction certification complexity:Simultaneous ANSM, DGCCRF, and evolving EFSA novel food consultations create overlapping compliance timelines that delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Food Acidulants Market |
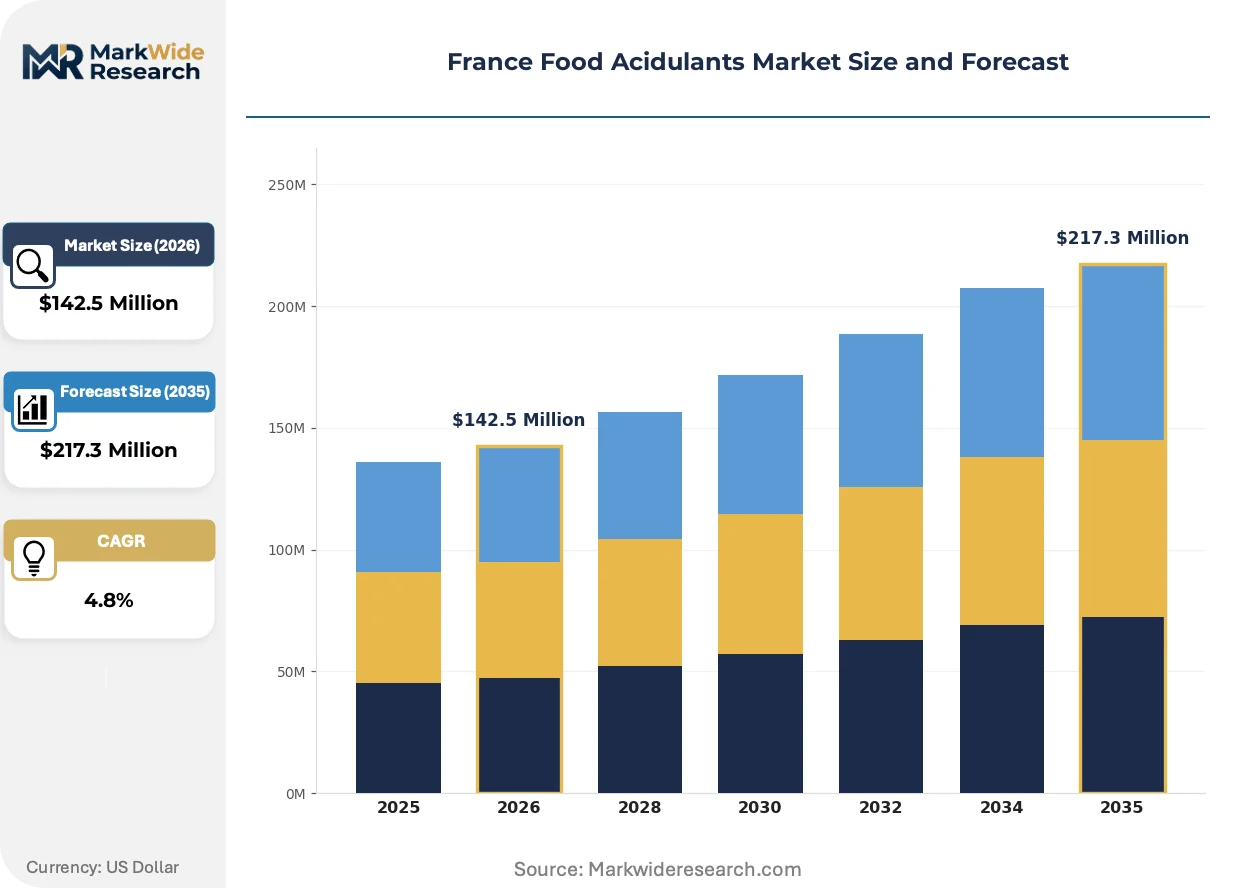
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $217.3 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Citric Acid, Lactic Acid, Acetic Acid, Malic Acid, Tartaric Acid Application: Beverages, Bakery Products, Confectionery, Dairy Alternatives, Meat Processing End User: Food Manufacturers, Foodservice Providers, Ingredient Suppliers, Retail Chains, Exporters Packaging Type: Bulk Bags, Retail Packs, Drums, Sachets, Cartons |
| Companies Covered | Tate & Lyle PLC, Brenntag AG, Jungbunzlauer Holding AG, Corbion N.V., Cargill, Incorporated, ADM, DuPont de Nemours, Inc., Kerry Group plc, Univar Solutions LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Food Acidulants Market Shifts & Advancements
Bioprocess automation and regulatory disclosure mandates are converging to reshape how acidulant purity is verified, traced, and contracted across French food manufacturing networks.
Precision fermentation control systems are digitizing acidulant batch consistency. Beverage bottlers in the Paris basin deploy real-time bioreactor monitoring to lock citric acid purity specifications. This compression of quality variance is digitizing supplier qualification timelines and reducing incoming inspection overhead.
CSRD sustainability reporting requirements now mandate Scope 3 ingredient disclosure. Acidulant buyers must document fermentation feedstock origins and carbon intensity. Food manufacturers in Rhône-Alpes are requalifying suppliers based on lifecycle data transparency, shifting contract terms toward emissions-linked pricing.
Direct procurement from fermentation facilities is displacing distributor intermediation. Large dairy alternative processors negotiate volume commitments with biotechnology producers for malic acid supply security. This channel compression concentrates buying power among scaled end-users while fragmenting service expectations for smaller formulation houses.
France Food Acidulants Market Segmentation
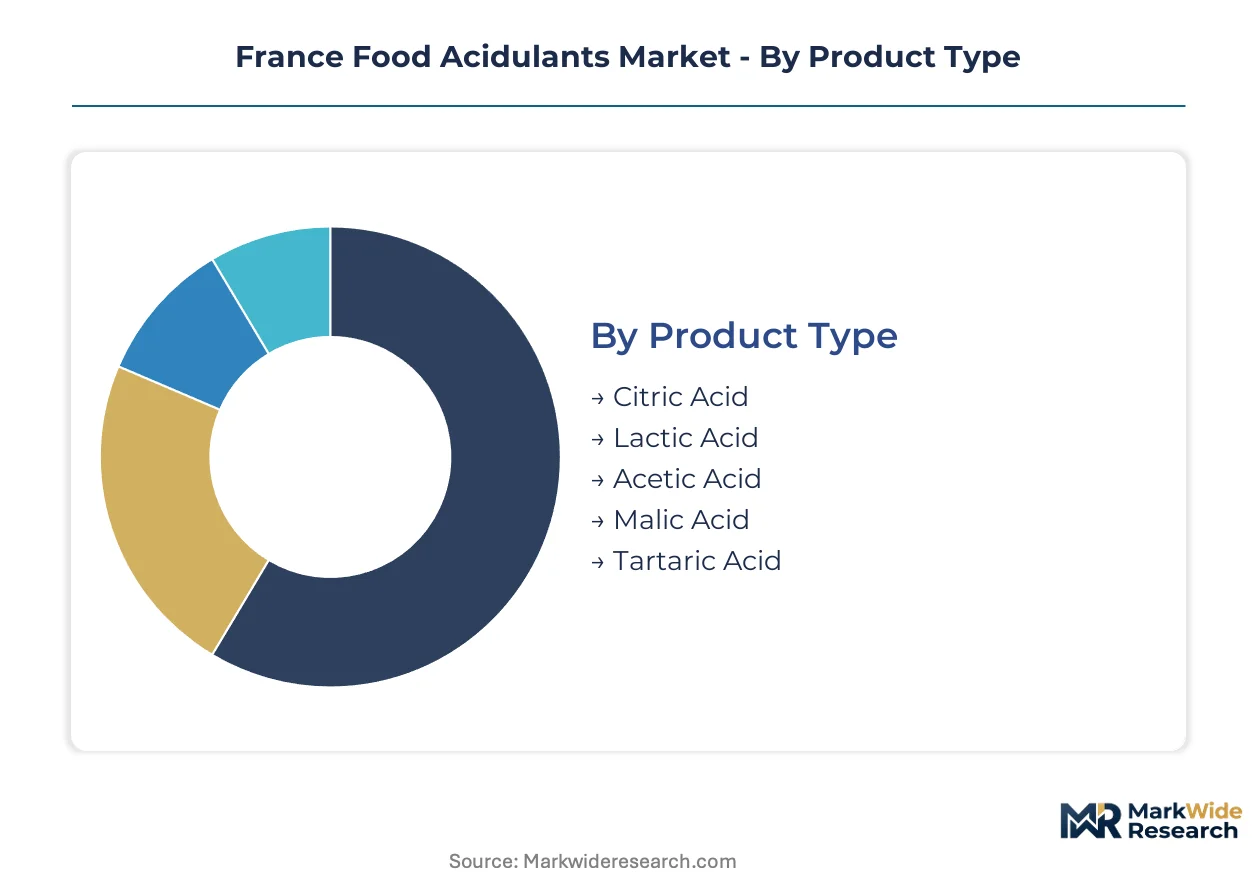
Acidulant procurement patterns in France diverge sharply across product chemistry and end-use specifications. Beverage bottlers in the Paris basin negotiate fermentation-grade citric acid on quarterly cycles, while meat processors in Brittany source acetic acid through annual tenders tied to pork slaughter volumes.
Product Type:
Citric acid turns inventory fastest in Île-de-France beverage corridors, while tartaric acid sits longest in Bordeaux wine-country warehouses awaiting seasonal blending schedules.
- Citric Acid:Fermentation-derived crystals dominate pH adjustment across carbonated and still beverages. Paris basin bottlers consume bulk volumes for shelf-stable lemonade and sports drink formulations, with ANSM purity documentation required per delivery batch.
- Malic Acid:Synthetic and fermentation grades deliver sharper tartness profiles at lower dosage rates than citric alternatives. Plant-based dairy processors in Rhône-Alpes specify malic acid for oat milk pH stabilization, where clean-label positioning commands premium formulation costs.
- Lactic Acid:Biotech-produced grades serve dairy alternative fermentation and meat preservation. Corbion N.V. supplies high-purity lactic acid to Lyonnaise charcuterie houses for shelf-life extension.
- Acetic Acid:Synthetic and biomass-derived forms acidify pickles, mustards, and processed meats. Bretagne condiment manufacturers source diluted acetic acid through port-of-Brest import channels.
- Tartaric Acid:Wine industry byproduct and synthetic sources support confectionery and baking applications. Alsace tartaric acid refiners supply pharmaceutical-grade material for effervescent tablet production.
Citric acid dominates installed base. Malic acid is where expansion concentrates.
Application:
Cost tier stratification separates commodity beverage acidification from precision pH control in cultured protein growth media.
- Beverages:Carbonated soft drinks, fruit nectars, and functional waters absorb the largest acidulant volumes. Rhône-Alpes bottling corridors specify citric-malic acid blends for balanced tartness in reduced-sugar formulations.
- Dairy Alternatives:Oat, almond, and soy milk processors require malic and lactic acid for protein stability and microbial control. Paris-Saclay plant-based startups drive specification tightening for fermentation-derived purity grades.
- Confectionery:Gummy candies and sour coatings deploy citric acid for surface crystallization and tartness delivery. Strasbourg confectioners import tartaric acid for traditional berlingot hard candies.
- Bakery Products:Leavening acidulants and mold inhibitors use blended acid systems. Northern French industrial bakeries specify encapsulated citric acid for controlled-release in frozen dough applications.
- Meat Processing:Fermented and dried meat products rely on lactic acid for pathogen inhibition. Lyonnaise sausage houses source liquid lactic acid for fermentation starter culture activation.
Beverages anchor volume throughput. Dairy alternatives represent the steepest expansion trajectory.
End User:
Customer type determines contract structure, with food manufacturers locking annual volumes while foodservice operators buy spot through distributor networks.
- Food Manufacturers:Industrial processors of beverages, baked goods, and meat products negotiate direct fermentation facility contracts. Danone and Bel Group acidulant procurement teams qualify suppliers on CSRD carbon disclosure compliance.
- Ingredient Suppliers:Distributors and blenders aggregate acidulant volumes for resale to smaller formulation houses. Lyon-based ingredient traders stock citric and malic acid for just-in-time delivery to Rhône-Alpes food clusters.
- Foodservice Providers:Restaurant chains and catering operators purchase pre-diluted acidulant solutions for kitchen use. Parisian hospitality groups source vinegar concentrates and citrus acid blends through broadline distributors.
- Retail Chains:Private-label product development teams specify acidulants for house-brand beverages and condiments. Carrefour and E.Leclerc formulation labs validate citric acid grades for shelf-stable juice lines.
- Exporters:French acidulant traders ship fermentation-derived citric acid to North African and West African food processors. Marseille port facilities handle bulk acidulant transshipment to Moroccan beverage bottlers.
Food manufacturers dominate installed base. Exporters are where expansion concentrates.
Packaging Type:
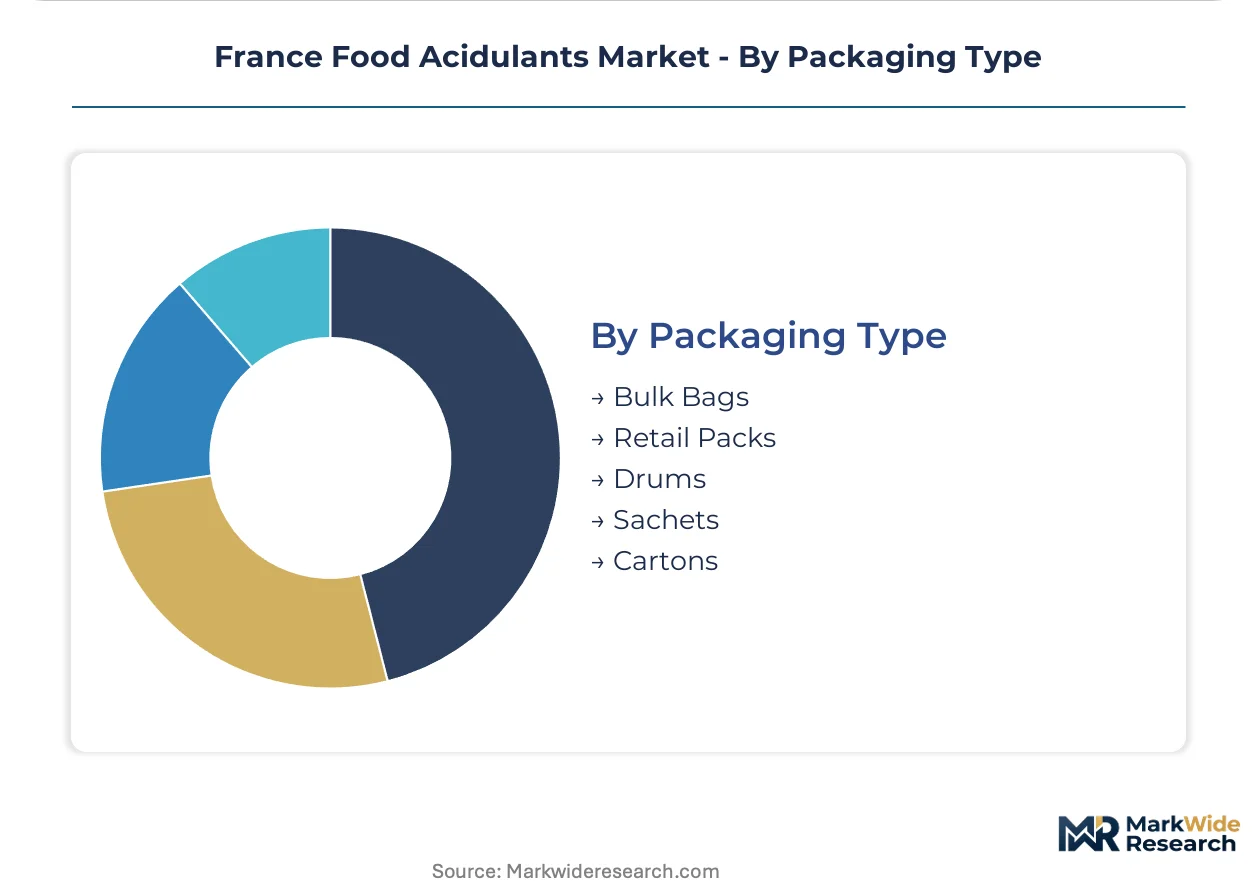
Volume scale dictates packaging economics, with bulk bags serving high-throughput bottlers and sachets reaching artisanal formulation kitchens.
- Bulk Bags:One-ton flexible intermediate bulk containers serve high-volume beverage and dairy alternative processors. Paris basin bottlers receive citric acid in bulk bags with integrated discharge systems for pneumatic conveying.
- Drums:200-liter polyethylene drums deliver liquid lactic and acetic acid to medium-scale meat and condiment manufacturers. Lyonnaise charcuterie houses specify drum delivery for fermentation room integration.
- Retail Packs:Consumer-sized containers reach home preservers and small commercial kitchens. French supermarket chains stock 500-gram citric acid pouches for domestic jam making.
- Sachets:Single-use packets serve foodservice portion control and artisanal scale operations. Parisian pastry chefs purchase tartaric acid sachets for precise meringue stabilization.
- Cartons:Boxed liquid and crystalline formats support mid-scale bakery and confectionery procurement. Alsace gingerbread producers receive molasses-cartoned acidulant blends for seasonal production ramps.
Bulk bags dominate installed base. Sachets are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food acidulant procurement concentrates around beverage bottlers in the Paris basin and dairy alternative processors in Rhône-Alpes, with regulatory enforcement from ANSM and DGCCRF tightening specification windows across all manufacturing corridors.
Île-de-France
Carbonated soft drink and functional water bottlers drive citric acid volumes through high-throughput production lines. ANSM purity documentation requirements accompany every delivery batch to facilities around Paris. The Paris-Saclay biotechnology cluster incubates cultured protein startups requiring food-grade acidulants for growth medium pH control.
Auvergne-Rhône-Alpes
Plant-based dairy processors specify malic and lactic acid for oat and almond milk stabilization. EU Green Deal decarbonization targets pull investment toward bioprocess capacity expansion in Lyon and Grenoble. Precision fermentation specialists in the region negotiate direct supply contracts with biotechnology producers for volume security.
Provence-Alpes-Côte d'Azur
Marseille port facilities handle bulk acidulant transshipment to North African beverage bottlers, anchoring export-oriented trading activity. CSRD Scope 3 emissions disclosure requirements favor local fermentation sourcing for regional food manufacturers. Coastal condiment producers source acetic acid through Mediterranean import channels.
Hauts-de-France
Industrial bakeries in the northern corridor specify encapsulated citric acid for controlled-release applications in frozen dough. DGCCRF enforcement of origin labeling and purity standards operates at retail level throughout Lille and surrounding manufacturing zones. Molasses feedstock price volatility squeezes fermentation economics for regional acidulant distributors.
Nouvelle-Aquitaine
Bordeaux wine-country warehouses hold tartaric acid inventories awaiting seasonal blending schedules for confectionery and pharmaceutical applications. Tartaric acid refiners in Alsace supply pharmaceutical-grade material for effervescent tablet production to facilities across southwestern France. Regional procurement patterns favor annual tender structures tied to agricultural processing cycles.
France Food Acidulants Market Competitive Landscape
Channel-controlling players compete with product-specialist players for formulation house relationships across French food manufacturing networks. The vendor base organizes around fermentation-grade purity specialists, bulk logistics integrators, and regional distribution aggregators. Three archetypes dominate: biotechnology-driven purity grade suppliers, captive fermentation network operators, and distributor-intermediaries with just-in-time delivery capabilities. Competitive moves concentrate on direct procurement channel compression and CSRD-aligned carbon transparency qualification.
Among fermentation-specialist suppliers, Jungbunzlauer Holding AG and Corbion N.V. occupy positions anchored in biotechnology-driven production architectures. Tate & Lyle PLC represents the bulk logistics integration archetype, with positioning tied to beverage bottler relationships in the Paris basin. These three companies exemplify the strategic segmentation between purity-grade fermentation specialists and volume-scale supply chain operators.
| Leading Market Players |
|---|
| Tate & Lyle PLC |
| Brenntag AG |
| Jungbunzlauer Holding AG |
| Corbion N.V. |
| Cargill, Incorporated |
| ADM |
| DuPont de Nemours, Inc. |
| Kerry Group plc |
| Univar Solutions LLC |
| Others |
Supply & Pricing Matrix
Paris-Rotterdam barge freight corridors anchor acidulant cost structures, with molasses feedstock indexation and fermentation capacity concentration in Eastern Europe compressing margin buffers for French formulation houses while amplifying price differentiation between fermentation-grade and synthetic acid tiers.
Pricing Analysis
Cost-plus contracts indexed to molasses futures dominate citric acid procurement, with ANSM purity documentation premiums separating fermentation-grade from synthetic alternatives. Price differentiation rests on carbon intensity disclosure under CSRD mandates and volume scale commitments from Paris basin bottlers. Pricing pressure stems from biofuel policy arbitrage squeezing molasses availability. Small artisanal confectioners exhibit highest price sensitivity, while dairy alternative processors prioritize purity-grade security over unit cost.
Supply Chain Analysis
EU dual-use export controls on precision fermentation bioreactor technology limit domestic capacity expansion, forcing French buyers to source bulk citric acid from Polish and Hungarian fermentation facilities. Raw material flows draw from Ukrainian beet molasses, Brazilian cane syrup, and French corn starch processors. Single-source vulnerability concentrates in Eastern European citric acid corridors. Distribution runs through Lyon-based ingredient traders aggregating volumes for Rhône-Alpes food clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern acidulant procurement as CSRD carbon disclosure requirements create interoperability standards between fermentation facilities and food manufacturer ERP systems, with Paris-Saclay biotechnology clusters incubating the API layers enabling this shift.
For Market Incumbents: Harden fermentation network control through captive molasses storage capacity in Hauts-de-France and ANSM certification pre-qualification programs. Bioprocess automation startups threaten purity-grade premiums. Backward integration into feedstock origination secures margin buffers against biofuel policy volatility.
For New Entrants and Emerging Players: Alsace precision fermentation infrastructure represents the most penetrable entry point for specialty acidulants currently imported from North American biotech suppliers. Cultured protein growth medium applications in Île-de-France offer volume anchors outside commodity beverage markets. Direct procurement platform development targets mid-scale formulation houses bypassing distributor intermediation.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with stranded acidulant synthesis assets facing clean-label obsolescence. Long-term viability centers on fermentation-derived purity grade positioning and CSRD-aligned carbon transparency infrastructure. Monitor EU novel food consultation outcomes for acidulant reclassification signals forcing sector-wide reformulation.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Buildout | Alsace biotechnology clusters anchor microbial cell factory deployment for specialty acidulant domestication. |
| CSRD-Aligned Carbon Disclosure Integration | Scope 3 emissions documentation requalifies supplier relationships toward lifecycle transparency contracts. |
| Direct Procurement Channel Development | Large dairy alternative processors negotiate volume commitments bypassing Lyon-based distributor intermediation. |
| Molasses Feedstock Storage Infrastructure | Hauts-de-France captive storage buffers Eastern European supply concentration risk for citric acid producers. |
| ANSM Purity Grade Pre-Certification | Batch documentation standardization compresses incoming inspection timelines for Paris basin bottlers. |
Research Methodology
Cross-validation between fermentation facility production records and customs import declarations anchors the qualitative findings. Primary interviews with bioprocess engineers at acidulant manufacturers, procurement leads at Paris basin beverage bottlers, ANSM regulatory affairs specialists, and Lyonnaise charcuterie technical directors combined with secondary validation from DGCCRF enforcement bulletins, EU Green Deal policy frameworks, and CSRD implementation guidance. Bottom-up volume modeling triangulates against top-down expenditure flows from food manufacturer ingredient cost disclosures.
Calibration against historical molasses price volatility and biofuel policy shifts shapes the analytical framework across the projection horizon. Segmentation dimensions include acid chemistry type, application end-use, purity grade tier, packaging format, and regional manufacturing cluster. CAGRs derive from installed capacity utilization rates and substitution elasticity between fermentation-derived and synthetic acid sources. Forecast inputs incorporate EU novel food consultation timelines and precision fermentation scale-up velocity from Alsace biotechnology incubators.
Practitioners should monitor ANSM additive reclassification proceedings and Eastern European fermentation capacity expansion announcements for early signals. Forecasts reflect assumptions around CSRD disclosure enforcement timelines and molasses feedstock availability under EU biofuel mandates. Material shifts in EU Green Deal carbon accounting rules or novel food acidulant classifications would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
North America Fermented Ingredient Market
Food Additives and Ingredients
Egypt Food Emulsifiers Market
Food Additives and Ingredients
Ammonia Caramel Market
Food Additives and Ingredients
Mexico Food Acidulants Market
Food Additives and Ingredients
South America Food Colorants Market
Food Additives and Ingredients
Oxygen Absorbers Market
Food Additives and Ingredients
Canada Food Preservatives Market
Food Additives and Ingredients
Global Integrated Food Ingredient Market
Food Additives and Ingredients
Nanoencapsulated Food Additives Market
Food Additives and Ingredients
Gelatin Films Market
Food Additives and Ingredients
PVPP Beer Stabilizer Market
Food Additives and Ingredients
Locust Bean Gum Market
Food Additives and Ingredients
Dairy Starter Culture Market
Food Additives and Ingredients
Emulsified Shortenings Market
Food Additives and Ingredients
Annatto Food Colors Market
Food Additives and Ingredients
Food Grade Ammonium Bicarbonate Market