
 Global Canthaxanthin Market | 2026-2036
Global Canthaxanthin Market Size, Share, and Industry Trends Forecast 2026-2036
Global Canthaxanthin Market Foresight
Chinese carotenoid fermentation capacity is broadening as domestic producers scale biosynthetic platforms. DSM-Firmenich leverages integrated biotechnology operations across multiple continents to sustain supply reliability. BASF SE anchors its position through backward integration into precursor chemicals, while Kemin Industries differentiates via specialized extraction technologies for high-purity grades.
Canthaxanthin is a ketocarotenoid pigment with the molecular formula C40H52O2, synthesized naturally by microorganisms or produced through chemical synthesis for commercial scale, primarily functioning as a color additive and antioxidant across feed, food, and nutraceutical applications. Crystalline powder formulations dominate volume sales due to stability advantages in extended shelf-life applications, while oleoresin variants command premium positioning in cosmetics and personal care formulations where solubility performance determines formulation compatibility. Animal feed applications absorb the largest share of output, though dietary supplements represent the fastest-expanding consumption channel as consumer preference shifts toward natural-source antioxidant ingredients.
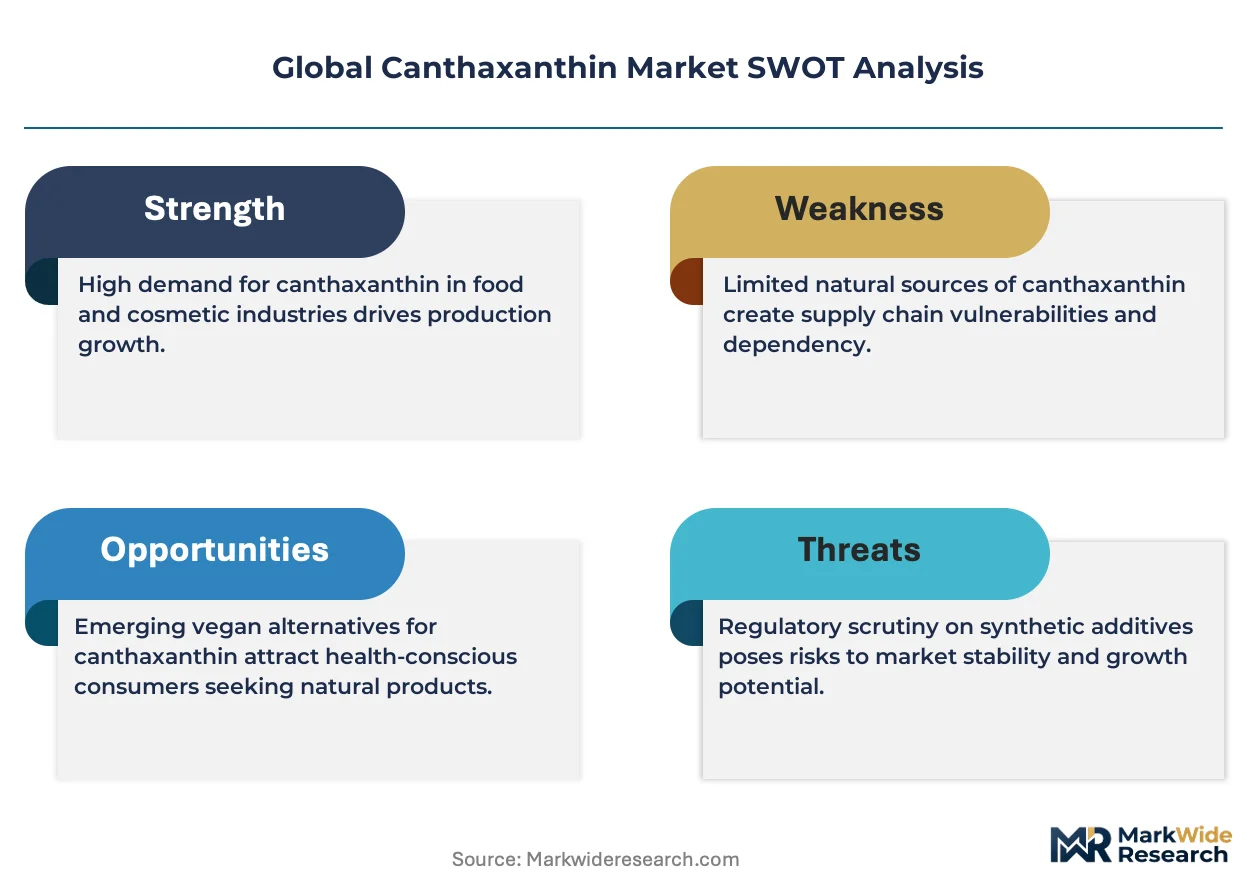
FDA color additive regulations, EFSA feed additive authorizations, and China's GB standards collectively define product purity thresholds and label claim requirements that manufacturers must satisfy for market access across major consumption regions. REACH registration obligations in Europe and evolving EPA environmental release guidelines in the United States impose additional compliance burdens on synthetic production pathways. Stakeholders must monitor regulatory divergence between biosynthetic and chemically derived sourcing classifications, as this distinction increasingly determines tariff treatment and end-use eligibility in key importing jurisdictions.
Market Dynamics
Feed pigment standardization across Southeast Asian aquaculture operations is compressing supplier margins while elevating volume commitments, as integrated shrimp and salmon farming conglomerates consolidate procurement around certified canthaxanthin grades.
Growth Catalysts
- EU F-Gas Regulation tightening:Synthetic production pathways face escalating compliance costs, redirecting capital toward biosynthetic fermentation capacity expansion in China and India.
- Aquaculture pigment intensification:Vietnamese and Indonesian shrimp producers are doubling canthaxanthin inclusion rates to meet export color-grade specifications for EU and Japanese buyers.
- Antioxidant substitution in poultry:Feed formulators are displacing synthetic ethoxyquin with canthaxanthin-derived antioxidant complexes to satisfy clean-label retail requirements.
Market Restraints
- Precursor chemical volatility:Acetone and beta-ionone feedstock prices swing with petrochemical refinery output schedules, squeezing margin predictability for chemical synthesis operators.
- Chinese supply concentration:Over sixty percent of crystalline powder capacity clusters in Shandong and Jiangsu provinces, exposing buyers to regional environmental enforcement shutdowns.
- REACH registration friction:ECHA data requirements for synthetic carotenoid dossiers impose eighteen-month approval timelines that lock out smaller producers from EU feed additive markets.
Strategic Opportunities
- Brazilian aquaculture penetration:Underdeveloped tilapia and catfish pigment protocols in Mato Grosso and Pará states present first-mover positioning for certified suppliers.
- Nutraceutical encapsulation formats:Softgel and liposomal delivery systems for antioxidant supplements command three-to-four-fold premia over bulk powder in North American direct-to-consumer channels.
- China dual carbon alignment:Provincial green financing incentives for low-carbon fermentation processes are accelerating biosynthetic platform upgrades with subsidized utility rates.
Industry Challenges
- Fermentation scale-up talent scarcity:Industrial microbiologists with carotenoid strain optimization experience command premium compensation in Shanghai and Shenzhen biotech clusters.
- Multi-jurisdiction dossier synchronization:Feed additive manufacturers must reconcile divergent purity specifications between FDA color additive regulations, EFSA authorizations, and China's GB standards.
- Legacy chemical synthesis asset stranding:European producers face accelerated depreciation on petrochemical-based production lines as biosynthetic output achieves cost parity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Canthaxanthin Market |
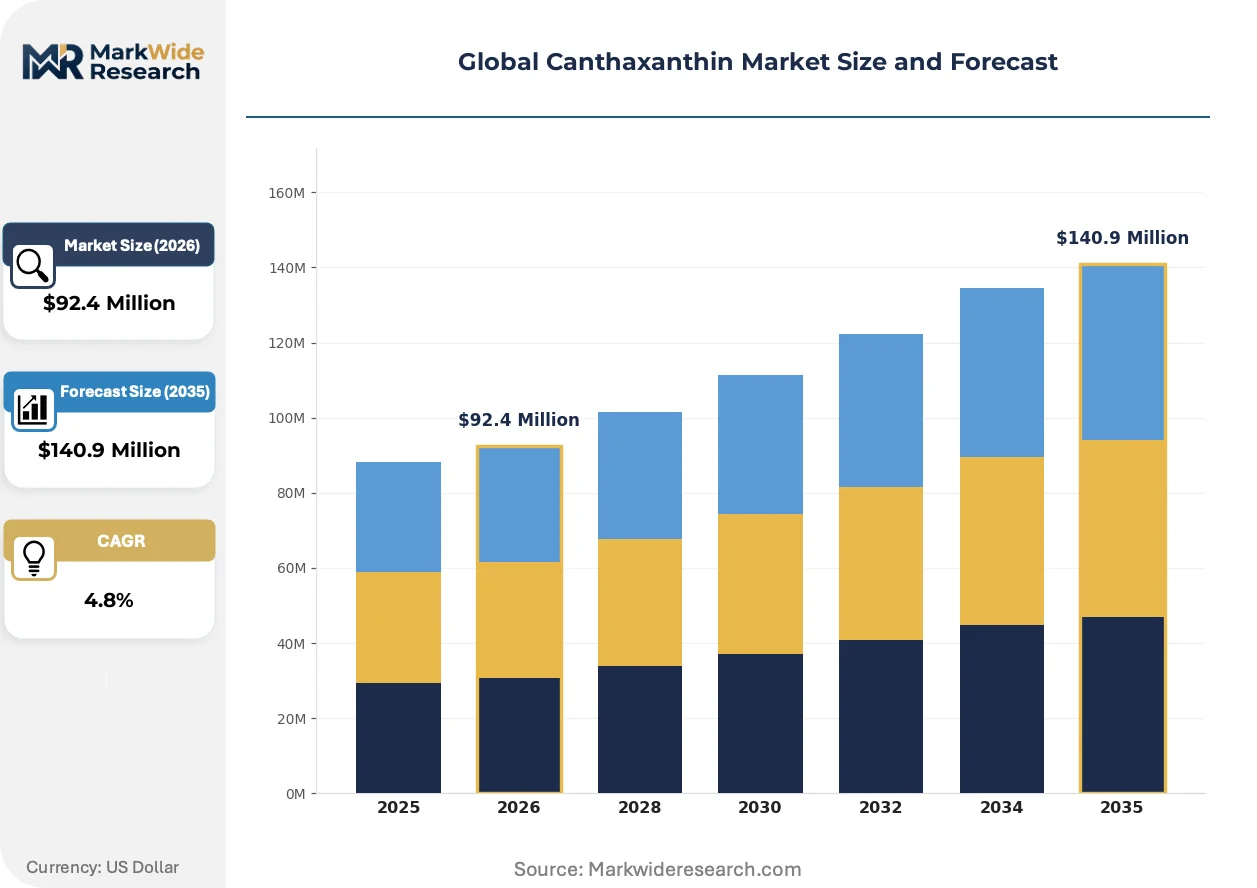
| Market Size in 2026 | $92.4 Million |
| Market Size in 2035 | $140.9 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crystalline Powder, Liquids, Oleoresins, Granules Application: Animal Feed, Dietary Supplements, Cosmetics, Food Colorants, Pharmaceuticals End User: Feed Manufacturers, Nutraceutical Companies, Personal Care Brands, Food & Beverage Producers Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | DSM-Firmenich, BASF SE, Allied Biotech Corporation, Sensient Technologies Corporation, Divi's Nutraceuticals, Merck Group, Novepha Company, NHU, Kemin Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Canthaxanthin Market Shifts & Advancements
Biosynthetic production platforms are compressing the cost structure of pharmaceutical-grade canthaxanthin while regulatory divergence between chemical and fermentation-derived classifications is fragmenting procurement strategies across major feed markets.
Continuous fermentation technology with real-time metabolite monitoring is modularizing production economics for high-purity canthaxanthin. Contract manufacturers serving European nutraceutical brands are adopting these skid-mounted systems to reduce batch-to-batch variability. The technology is modularizing capital deployment, allowing mid-scale entrants to compete without billion-liter fermentation commitments.
REACH registration obligations for synthetic carotenoids are tightening substance volume thresholds and toxicity data requirements. Chemical producers face escalating dossier maintenance costs that biosynthetic competitors avoid through different regulatory classification. Feed additive distributors in Germany and the Netherlands are requalifying supply chains around fermentation-derived grades to preempt authorization gaps.
Buyer consolidation among Southeast Asian aquafeed conglomerates is compressing supplier negotiation cycles from annual to quarterly price reviews. Integrated shrimp farming groups in Vietnam and Thailand are unbundling pigment procurement from complete feed contracts, forcing canthaxanthin specialists to establish direct technical service relationships. This pattern is most visible in the Mekong Delta, where vertical integration between hatcheries and processing plants has eliminated independent feed mill intermediaries.
Global Canthaxanthin Market Segmentation
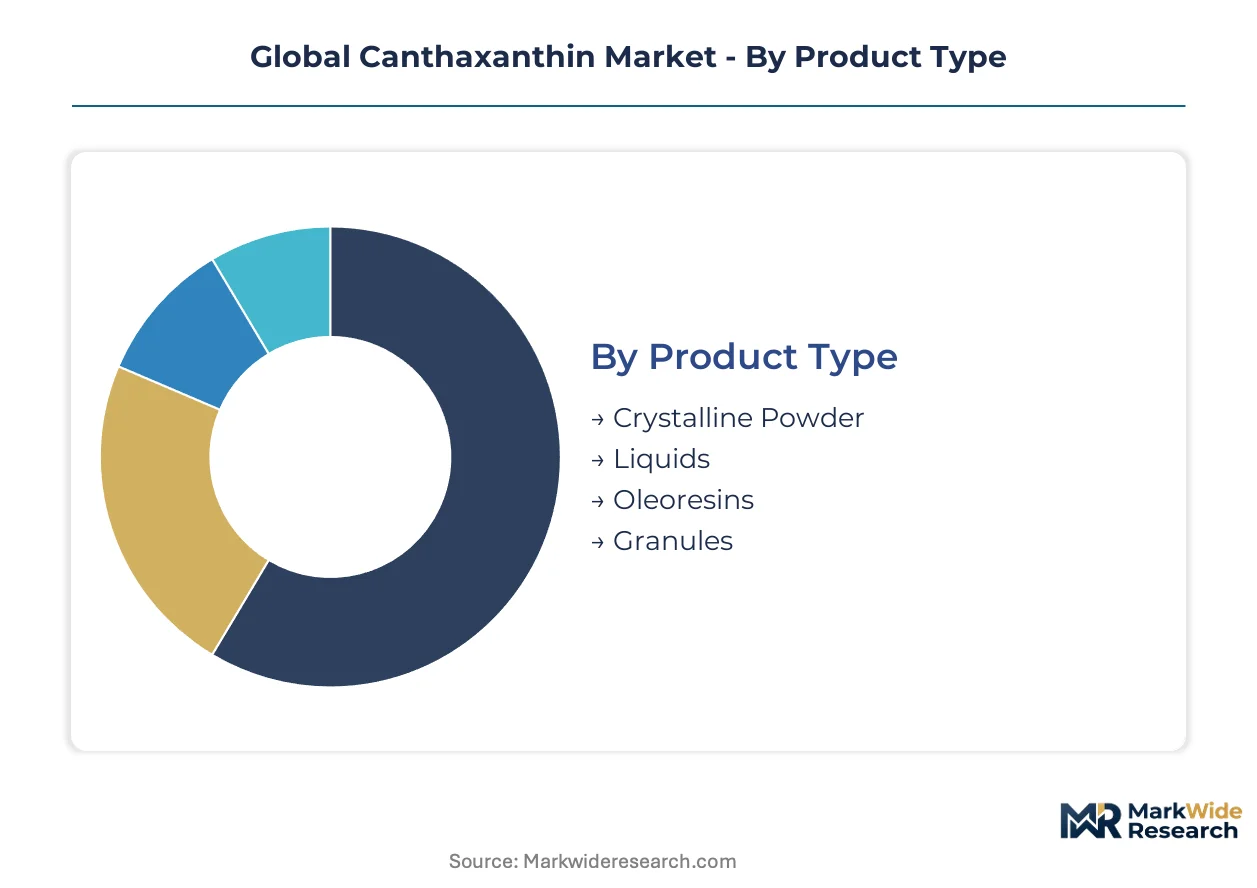
Canthaxanthin procurement patterns diverge sharply across product formats and end-use specifications, with regulatory classification determining which segments command premium positioning versus commodity volume plays. Feed additive buyers prioritize stability and batch consistency, while nutraceutical and cosmetic formulators emphasize solubility and purity thresholds that dictate manufacturing technology choices.
Product Type:
Crystalline powder and oleoresin variants carry divergent certification burdens under FDA color additive regulations and EFSA feed additive authorizations, with powder grades requiring stricter heavy metal documentation for animal feed applications.
- Crystalline Powder:High-purity solid form with superior oxidative stability in extended shelf-life feed formulations. Vietnamese and Indonesian shrimp farming conglomerates concentrate procurement around certified crystalline grades to satisfy EU and Japanese export color specifications, though Chinese environmental enforcement shutdowns in Shandong province periodically disrupt supply security.
- Oleoresins:Oil-dispersed concentrates optimized for solubility in lipid-based cosmetic and personal care matrices. Demand concentrates in European nutraceutical encapsulation operations where liposomal delivery systems command substantial premia over bulk powder in direct-to-consumer channels, constrained by REACH registration obligations for synthetic-derived batches.
- Liquids:Ready-to-dispense aqueous suspensions for automated feed mill integration.
- Granules:Flowable dry forms engineered for uniform distribution in poultry premix applications.
Crystalline powder sits at the top of the volume ranking, with oleoresins climbing the fastest.
Application:
Cost tier differentiation separates commodity feed pigment demand from pharmaceutical-grade antioxidant positioning, with regulatory complexity escalating across the value chain.
- Animal Feed:Dominant consumption channel absorbing standardized pigment volumes for aquaculture and poultry pigmentation. Southeast Asian integrated farming operations are unbundling pigment procurement from complete feed contracts, forcing direct technical service relationships as Mekong Delta vertical integration eliminates independent feed mill intermediaries.
- Dietary Supplements:Antioxidant capsules and softgels targeting consumer preference shifts toward natural-source ingredients. North American direct-to-consumer channels drive formulation innovation, with encapsulation formats expanding most quickly as manufacturers displace synthetic ethoxyquin with canthaxanthin-derived antioxidant complexes.
- Cosmetics:Colorant and UV-protective applications in premium skincare formulations.
- Food Colorants:Restricted use in specific jurisdictions under varying purity thresholds.
- Pharmaceuticals:Investigational and approved therapeutic applications requiring GMP manufacturing compliance.
Animal feed maintains volume leadership, while dietary supplements gain share fastest.
End User:
Customer type determines procurement cycle length and technical service intensity, with integrated conglomerates compressing negotiation timelines against specialized ingredient distributors.
- Feed Manufacturers:Volume buyers consolidating around quarterly price reviews and certified grade specifications. Procurement is shifting toward direct supplier relationships as Vietnamese and Thai aquafeed conglomerates bypass traditional distribution layers, with pigment standardization compressing margins while elevating minimum volume commitments.
- Nutraceutical Companies:Premium-positioned formulators prioritizing encapsulation technology and delivery system innovation. Contract manufacturers serving European brands adopt modular continuous fermentation systems to reduce batch-to-batch variability, with real-time metabolite monitoring enabling mid-scale competition without billion-liter commitments.
- Personal Care Brands:Cosmetic houses emphasizing solubility performance and formulation compatibility.
- Food & Beverage Producers:Constrained end-use segment limited by jurisdiction-specific color additive approvals.
Feed manufacturers dominate volume absorption, with nutraceutical companies expanding most quickly.
Distribution Channel:
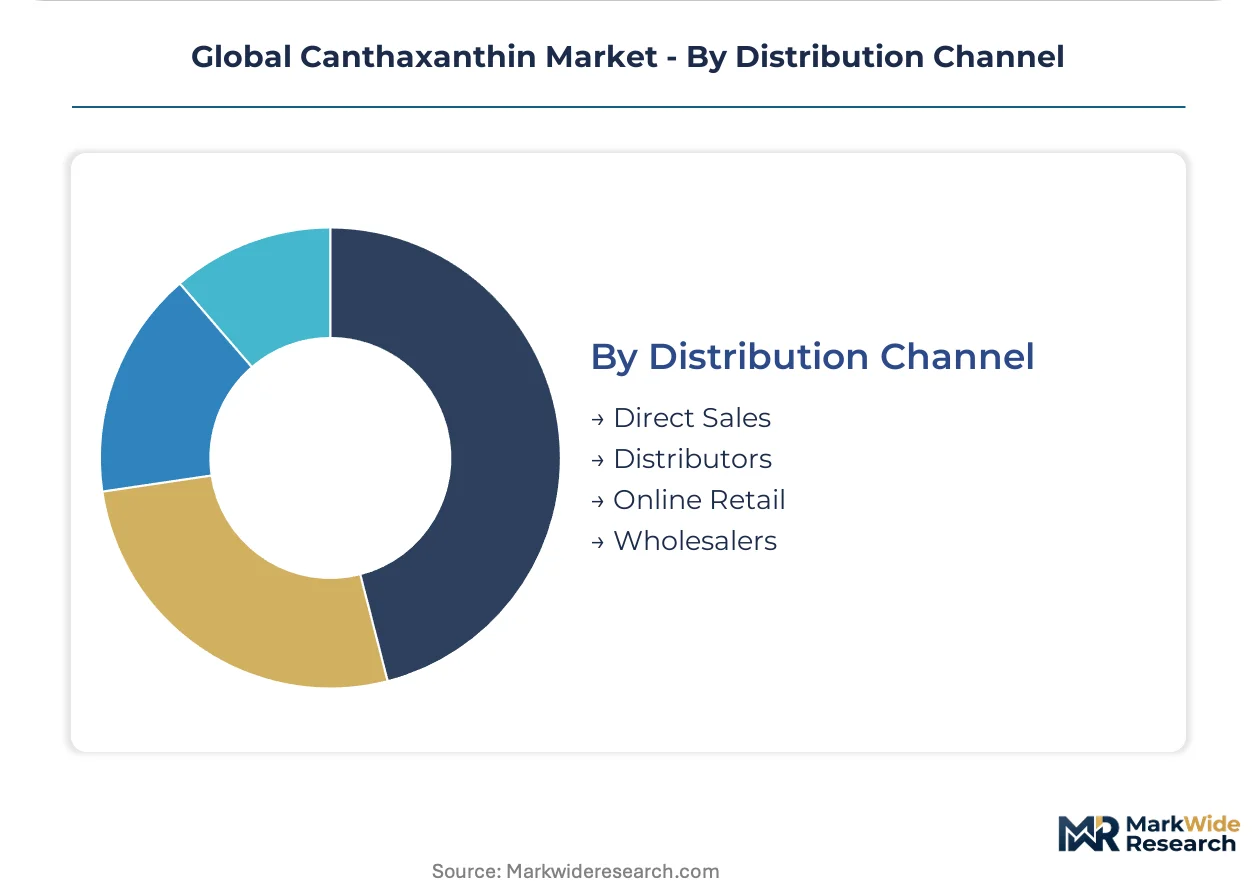
Supply concentration in Chinese manufacturing clusters shapes channel strategy, with direct sales gaining ground as buyer consolidation eliminates intermediary layers.
- Direct Sales:Technical service-intensive relationships for high-volume aquafeed and poultry integrators. Direct engagement is accelerating as Southeast Asian farming conglomerates consolidate procurement around certified grades, with DSM-Firmenich and BASF SE leveraging integrated biotechnology operations to sustain supply reliability against regional environmental enforcement risks.
- Distributors:Traditional intermediaries facing margin compression from unbundled pigment procurement.
- Online Retail:Emerging channel for small-batch nutraceutical and cosmetic ingredient sourcing.
- Wholesalers:Commodity bulk handlers serving regional feed compounders with lower technical requirements.
Direct sales command the volume ranking, with online retail climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands crystalline powder capacity while Vietnam drives aquaculture pigment consumption, creating divergent regulatory exposure across the value chain. German distributors requalify supply chains around fermentation-derived grades. Brazilian tilapia producers present untapped penetration opportunities.
China
Shandong and Jiangsu provinces cluster over sixty percent of global crystalline powder capacity, with domestic feed additive consumption climbing as biosynthetic fermentation platforms scale. Provincial green financing incentives under dual carbon goals accelerate low-carbon process upgrades with subsidized utility rates. Shanghai and Shenzhen biotech clusters compete aggressively for industrial microbiologists with carotenoid strain optimization experience.
Germany
REACH registration obligations impose eighteen-month approval timelines for synthetic carotenoid dossiers, locking out smaller producers from feed additive markets. ECHA data requirements for toxicity documentation escalate dossier maintenance costs that biosynthetic competitors avoid. Feed additive distributors in Germany and the Netherlands actively requalify supply chains around fermentation-derived grades to preempt authorization gaps.
Vietnam
Mekong Delta shrimp farming conglomerates unbundle pigment procurement from complete feed contracts, forcing direct technical service relationships with canthaxanthin specialists. Integrated hatcheries and processing plants eliminate independent feed mill intermediaries, compressing supplier negotiation cycles to quarterly price reviews. Vietnamese producers double inclusion rates to satisfy EU and Japanese export color-grade specifications.
Brazil
Mato Grosso and Pará states present first-mover positioning for certified suppliers as underdeveloped tilapia and catfish pigment protocols create penetration gaps. ANVISA feed additive regulations shape import qualification requirements for crystalline powder grades. Regional feed compounders lack established relationships with Asian pigment specialists, opening channel development opportunities.
United States
FDA color additive regulations define product purity thresholds and label claim requirements for nutraceutical and food applications. EPA environmental release guidelines impose compliance burdens on synthetic production pathways that biosynthetic alternatives circumvent. North American direct-to-consumer channels drive softgel and liposomal delivery system innovation for antioxidant supplements.
Global Canthaxanthin Market Competitive Landscape
Chinese producers anchor the volume tier; European and North American specialists hold premium positioning through certification depth. The vendor base concentrates around integrated biotechnology operations and backward-integrated chemical synthesis, with mid-scale fermentation entrants modularizing capital deployment. Three archetypes dominate: multinational life science conglomerates with continental manufacturing footprints, specialized carotenoid extractors with high-purity processing capabilities, and contract fermentation operators serving branded nutraceutical houses. Competitive moves center on supply chain requalification around biosynthetic grades and direct technical service relationships with consolidated aquafeed buyers.
Within the multinational tier, DSM-Firmenich exemplifies integrated biotechnology operations across multiple continents, while BASF SE anchors positioning through upstream control into precursor chemicals. Kemin Industries occupies a specialist position via extraction technologies for high-purity grades. These three represent divergent strategic vectors: continental supply reliability, petrochemical backward integration, and processing technology differentiation.
| Leading Market Players |
|---|
| DSM-Firmenich |
| BASF SE |
| Allied Biotech Corporation |
| Sensient Technologies Corporation |
| Divi's Nutraceuticals |
| Merck Group |
| Novepha Company |
| NHU |
| Kemin Industries |
| Others |
Supply & Pricing Matrix
Acetone and beta-ionone price indices cascade through canthaxanthin production economics, compressing margins for chemical synthesis operators while biosynthetic fermentation platforms in Shandong province exploit subsidized utility rates to undercut commodity-grade pricing. This feedstock volatility fragments procurement strategies, with Vietnamese shrimp farming conglomerates consolidating around quarterly price reviews that privilege supply security over unit cost minimization.
Pricing Analysis
Distributor margin layers in European feed additive channels absorb differential REACH compliance costs, with synthetic-derived crystalline powder carrying eighteen-month registration overhead that fermentation competitors bypass. Three-tier pricing structure across pharmaceutical-grade, feed-certified, and industrial pigment levels separates purity thresholds from volume scale. Cost compression in commodity crystalline grades intensifies as Chinese environmental enforcement shutdowns in Jiangsu province trigger spot-market premiums. Feed manufacturers exhibit highest price sensitivity, while nutraceutical encapsulation specialists accept substantial premia for liposomal delivery compatibility.
Supply Chain Analysis
Industrial microbiologists with carotenoid strain optimization experience command premium compensation in Shanghai and Shenzhen, constraining fermentation scale-up velocity for mid-scale entrants. Manufacturing gravity centers on China, India, and select European biotech clusters, with crystalline powder output drawing from acetone, beta-ionone, and glucose feedstock streams. Single-source vulnerability concentrates in Shandong province environmental enforcement exposure, where regional shutdowns propagate through Vietnamese and Indonesian aquaculture procurement cycles. Distribution runs through direct technical service relationships with integrated farming conglomerates, bypassing traditional feed mill intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canthaxanthin functions as a stable compounder anchored by aquaculture pigment standardization, with Vietnamese and Indonesian shrimp producers locked into inclusion rate commitments that sustain volume absorption regardless of feed cost cycles.
For Market Incumbents: To counter biosynthetic cost parity achievement in Chinese fermentation platforms, European chemical synthesis operators should accelerate backward integration into precursor chemical production and redirect capital toward modular continuous fermentation systems. REACH registration friction for synthetic dossiers demands preemptive supply chain requalification around fermentation-derived grades to preserve EU feed additive market access. For New Entrants and Emerging Players: Begin with Brazilian tilapia and catfish pigment protocol development in Mato Grosso and Pará states, where ANVISA feed additive regulations create qualification gaps unaddressed by established Asian suppliers. Direct technical service relationships with regional feed compounders lacking established pigment procurement channels offer the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Consolidation pressure builds where fermentation scale-up talent scarcity in Shanghai and Shenzhen biotech clusters constrains mid-scale entrant expansion. Five-to-ten year viability favors contract fermentation operators serving branded nutraceutical houses with modular skid-mounted systems. Watch for provincial green financing incentive expansion under China's dual carbon goals as inflection signal for biosynthetic platform economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Chemicals | BASF SE anchors positioning through upstream control over beta-ionone supply security. |
| Modular Continuous Fermentation Deployment | Contract manufacturers reduce batch-to-batch variability for European nutraceutical brands. |
| Direct Technical Service Relationships | DSM-Firmenich sustains supply reliability against Shandong environmental enforcement risks. |
| REACH-Compliant Supply Chain Requalification | German distributors preempt authorization gaps by shifting to fermentation-derived grades. |
| Brazilian Channel Development | First-mover positioning in Mato Grosso tilapia operations exploits underdeveloped pigment protocols. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with feed formulators, aquaculture operations managers, fermentation plant engineers, and regulatory affairs specialists with secondary validation against FDA color additive filings, ECHA REACH dossier databases, Chinese customs trade data, and GB standards documentation. Bottom-up capacity assessments across Shandong and Jiangsu manufacturing clusters triangulated against top-down demand modeling from Vietnamese and Indonesian aquaculture production statistics.
Segment-weighting approaches distributed value and volume across crystalline powder, oleoresin, liquid, and granule product formats, intersecting with animal feed, dietary supplement, cosmetic, food colorant, and pharmaceutical application channels. CAGRs derived from production capacity expansion schedules, feed inclusion rate trajectories, and regulatory authorization timelines across the analysis window. Industry-specific inputs incorporated provincial green financing incentive disbursement rates and EFSA feed additive authorization pipeline status.
Several conditions sit outside the modeled scope, including abrupt REACH substance volume threshold revisions, Chinese environmental enforcement campaign intensity variations, and Brazilian ANVISA regulatory acceleration. Forecasts reflect assumptions regarding fermentation scale-up talent availability and dual carbon policy continuity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
China Anti-Caking Market
Food Additives and Ingredients
Yeast Extract and Beta Glucan Market
Food Additives and Ingredients
Baking Enzymes Market
Food Additives and Ingredients
Sugar Reduction Technology Market
Food Additives and Ingredients
North America Food Starch Market
Food Additives and Ingredients
Beverage Encapsulants Market
Food Additives and Ingredients
Lycopene Food Colors Market
Food Additives and Ingredients
Potassium Polymetaphosphate Food Additives Market
Food Additives and Ingredients
Gum Hydrocolloid Market
Food Additives and Ingredients
Food Fungal Enzyme Market
Food Additives and Ingredients
Beverage Clarifier and Stabilizer Market
Food Additives and Ingredients
Fat-Replacing Starch Market
Food Additives and Ingredients
Food Grade Sodium Selenite Market
Food Additives and Ingredients
Russia Food Acidulants Market
Food Additives and Ingredients
Anti-Caking Market
Food Additives and Ingredients
Bakery Stabilizers Market