
 Leavening Acids Market | 2026-2036
Leavening Acids Market Size, Share, and Industry Trends Forecast 2026-2036
Leavening Acids Market Foresight
Project finance for specialty chemical production is rewriting competitive entry barriers in leavening acids. Corbion leverages bio-based fermentation platforms to differentiate its citric acid portfolio. Associated British Foods anchors supply security through backward integration into tartaric acid feedstocks. Cargill competes on agricultural origination scale, converting corn-derived dextrose into sodium acid pyrophosphate at cost-advantaged positions.
Leavening acids are inorganic or organic compounds that release carbon dioxide when combined with alkaline bases, typically operating at pH thresholds between 3.0 and 6.5 to control reaction timing in dough matrices. Their primary commercial purpose is to engineer predictable gas-cell expansion in baked goods, replacing or supplementing biological fermentation. Phosphate acids dominate volume in industrial bakeries where thermal stability and delayed action prove critical for high-speed production lines. Citric acid and cream of tartar capture premium positioning among clean-label and organic formulations where phosphate-free positioning commands shelf price advantages. Powder form leads across all application segments due to dosing precision and extended shelf stability, though liquid concentrates gain traction in automated continuous-mix systems.
The FDA's GRAS self-affirmation pathway and EPA effluent guidelines for phosphorus discharge shape formulation choices and plant siting decisions in the United States. The EU's REACH registration requirements and EFSA phosphate intake limits constrain additive portfolios and force reformulation investments among suppliers serving European food manufacturers. Stakeholders must monitor evolving sodium reduction mandates from WHO guidance and national health agencies, as these will determine whether potassium-based phosphate alternatives capture meaningful share from traditional sodium acid pyrophosphate systems.
Market Dynamics
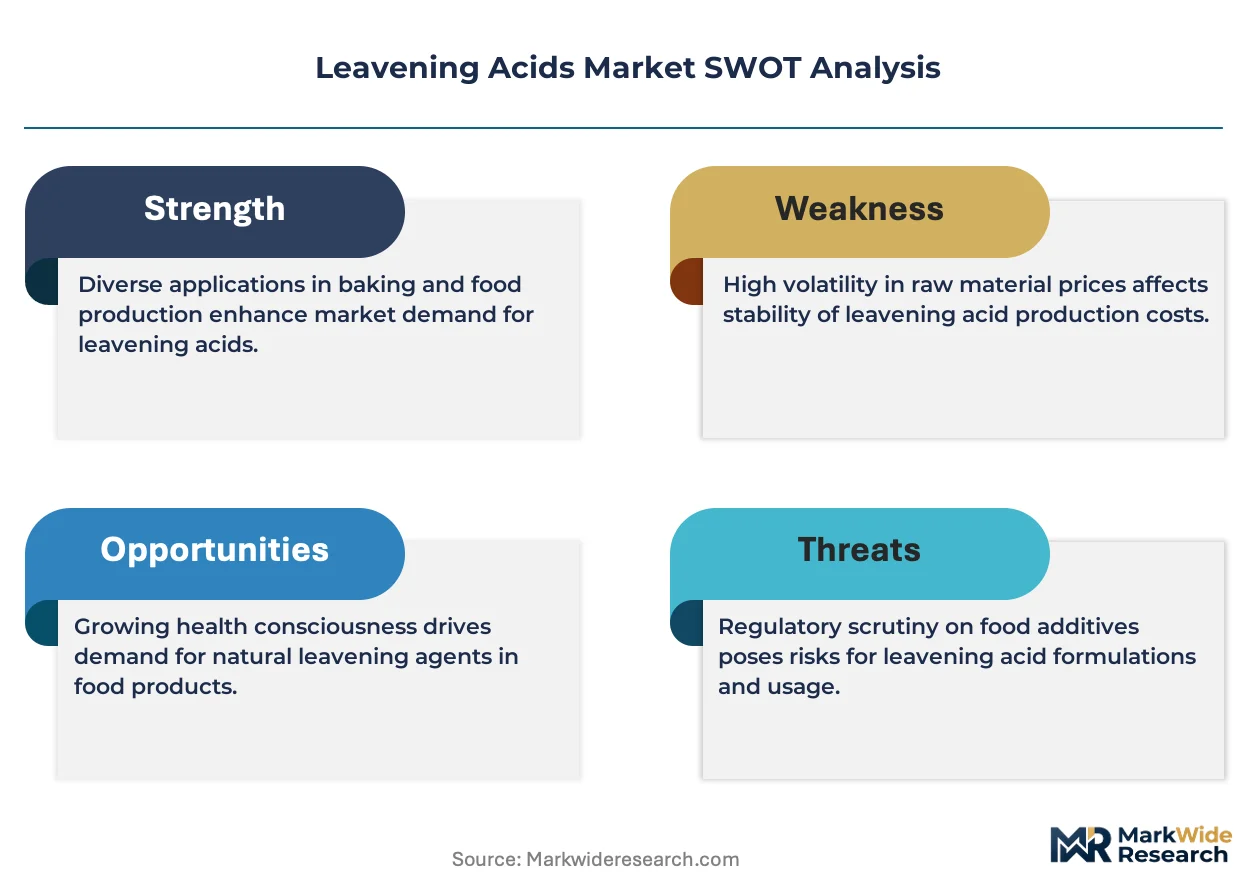
Clean-label mandates from EFSA and WHO sodium reduction guidance are forcing simultaneous reformulation of phosphate-based leavening systems, compressing R&D timelines and supplier qualification windows across industrial bakery supply chains.
Growth Catalysts
- F-Gas Regulation compliance:The EU's tightening fluorinated gas controls are accelerating phosphate alternative adoption as bakeries seek thermal stability without environmental liability exposure.
- Industrial bakery automation:High-speed production lines in Germany and the Netherlands demand precisely timed acid-base reactions that only engineered leavening acids deliver.
- Bio-based fermentation platforms:Microbial citric acid production is displacing petrochemical routes, offering carbon accounting advantages for Scope 3 reporting.
Market Restraints
- Phosphate rock concentration:Moroccan and Chinese state-controlled suppliers dominate upstream phosphate ore, creating geopolitical exposure for sodium acid pyrophosphate producers.
- REACH registration costs:ECHA's substance evaluation fees and toxicity testing requirements impose six-figure barriers for new acid entrants seeking EU market access.
- Potassium bicarbonate substitution:Sodium reduction mandates in the UK and France are pushing some formulators toward potassium-based systems that bypass traditional phosphate acids entirely.
Strategic Opportunities
- Clean-label contract manufacturing:Toll production partnerships with organic-certified facilities in Italy and Spain enable rapid portfolio extension without capital-intensive plant construction.
- WHO sodium guidance implementation:National health agencies in Germany and France are translating WHO targets into binding reformulation deadlines, creating pull-through demand for reduced-sodium acid systems.
- Liquid concentrate dosing systems:Continuous-mix bakery installations in Belgium and Denmark favor pumpable acid solutions over powder handling, opening service-based revenue models.
Industry Challenges
- Acid-base reaction calibration:Precision control of CO2 release rates across variable dough temperatures and hydration levels demands specialized food engineering expertise that remains scarce.
- Dual certification timelines:Simultaneous organic and kosher/halal qualification processes stretch 18-24 months, delaying product launches and locking working capital in inventory.
- Legacy equipment retrofit costs:Powder-handling systems in established industrial bakeries require pneumatic conveyor modifications to accommodate hygroscopic acid blends.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Leavening Acids Market |
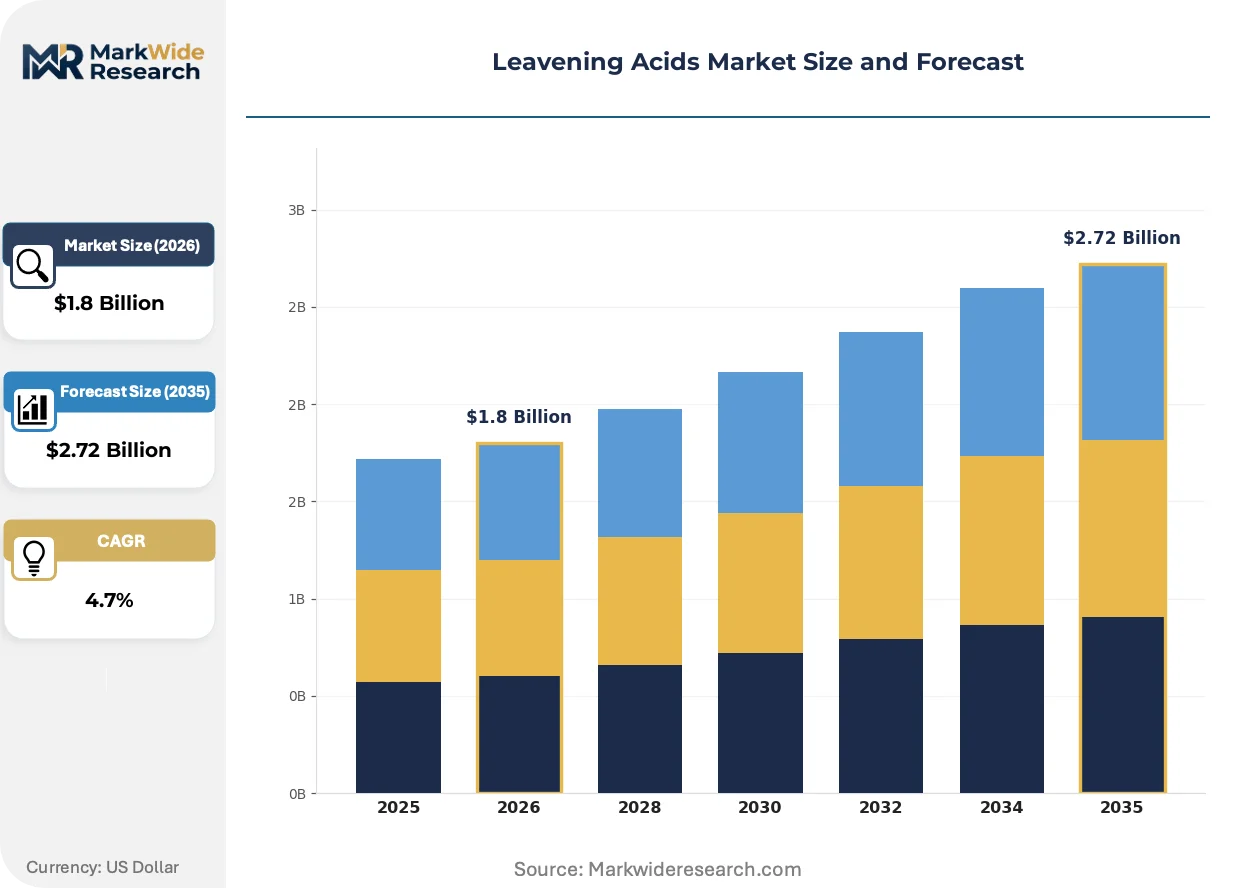
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Cream of Tartar, Citric Acid, Phosphate Acids, Tartaric Acid Application: Bakery Products, Confectionery, Dairy Products, Food & Beverages Form: Powder, Liquid, Granular, Tablets End User: Bakers, Food Manufacturers, Restaurants, Home Cooks |
| Companies Covered | Archer Daniels Midland Company, Cargill, Kerry Group, Corbion, Associated British Foods, Lesaffre Group, DuPont de Nemours, Koninklijke DSM, Puratos Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Leavening Acids Market Shifts & Advancements
Digital process control and bio-based feedstock substitution are converging to redefine leavening acid specification criteria, shifting competitive advantage from commodity scale to formulation precision and carbon transparency.
Encapsulated acid technologies are digitizing release kinetics in industrial baking. Microencapsulated citric and fumaric acids enable programmable CO2 liberation triggered by specific thermal thresholds. German and Dutch industrial bakeries are adopting these systems for frozen dough applications where delayed action proves critical. The technology is digitizing quality control protocols, replacing manual bench testing with sensor-fed batch consistency monitoring.
REACH authorization requirements are tightening acid additive portfolios across EU member states. ECHA's sunset date scheduling for certain phosphate compounds is forcing preemptive reformulation investments. Medium-sized bakery ingredient suppliers serving France and Italy face particular pressure, as their customer bases lack the technical resources to manage multiple qualification cycles simultaneously.
Direct supplier relationships are displacing traditional distribution tiers in leavening acid procurement. Large industrial bakery groups in Germany and Belgium are negotiating frame contracts directly with acid manufacturers, bypassing regional ingredient distributors. This consolidation concentrates volume with fewer suppliers while demanding technical service capabilities that distributors historically provided. The shift is most visible in private-label bakery manufacturing, where margin compression drives aggressive input cost management.
Leavening Acids Market Segmentation
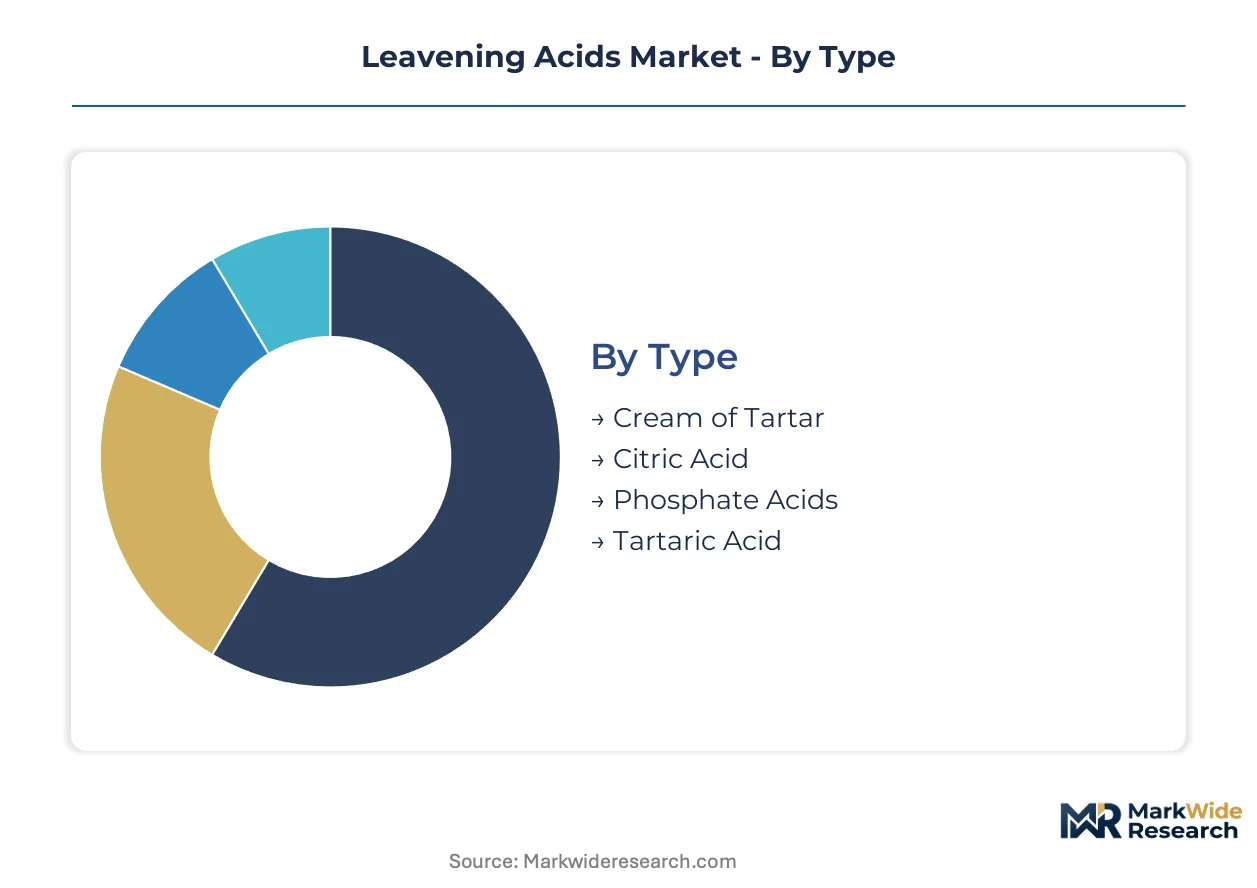
Leavening acid procurement splits sharply between industrial scale and artisanal precision, with formulation chemistry and handling logistics driving divergent specification requirements across end-use tiers.
Type:
Industrial bakeries demand thermal stability across frozen-to-oven processing windows, while clean-label positioning reshapes acid selection in premium retail channels.
- Phosphate Acids:Sodium acid pyrophosphate and monocalcium phosphate dominate high-speed production lines through delayed-action CO2 release calibrated to mechanical dough development. German industrial bakeries anchor procurement volumes for this segment, though EFSA phosphate intake limits are compressing growth ceilings in EU formulations.
- Citric Acid:Microbial fermentation platforms now supply food-grade citric acid with carbon accounting advantages for Scope 3 reporting, displacing petrochemical routes in organic-certified applications. Bio-based positioning commands shelf price premiums in French and Italian clean-label retail channels.
- Cream of Tartar:Potassium bitartrate from wine industry byproducts serves niche organic baking segments requiring phosphate-free positioning.
- Tartaric Acid:Associated British Foods' backward integration into grape-derived feedstocks secures supply for confectionery acidulation.
The dominant share belongs to Phosphate Acids, while Citric Acid is closing the gap fastest.
Application:
Volume concentrates where dough conditioning demands precise gas-cell engineering across temperature-variable processing environments.
- Bakery Products:Bread, cake, and pastry applications consume the majority of leavening acid volumes, with industrial manufacturers specifying acid blends for controlled expansion in high-hydration doughs. Frozen dough applications in Belgium and the Netherlands are adopting encapsulated acid systems for programmable release kinetics.
- Confectionery:Acid sanding and center-fill applications require anhydrous acid grades with low hygroscopicity to prevent caking during storage. Tartaric acid dominates hard candy acidulation for its clean flavor profile.
- Dairy Products:Acid-set cheeses and cultured dairy applications employ citric and phosphoric acids for pH reduction with minimal flavor interference.
- Food & Beverages:Carbonated beverage acidulation and dry mix applications pull food-grade phosphoric and citric acids from shared supply chains.
Bakery Products retains the largest installed base, though Confectionery applications are expanding most quickly as premium candy segments absorb higher acid input costs.
Form:
Handling economics and dosing precision determine format selection, with automation penetration driving divergence between established and emerging processing technologies.
- Powder:Free-flowing acid salts and crystalline organic acids enable gravimetric dosing accuracy in batch mixing systems. Extended shelf stability and low moisture sensitivity support regional distribution networks serving fragmented bakery operations.
- Liquid:Pumpable concentrates integrate with continuous-mix installations in Belgian and Danish industrial bakeries, eliminating powder handling infrastructure. Metering accuracy improves batch consistency while reducing airborne dust exposure.
- Granular:Intermediate particle sizing bridges powder flowability and liquid dosing precision for mid-scale manufacturers.
- Tablets:Unit-dose formats serve home baking and small commercial operations with minimal weighing equipment.
Powder maintains volume leadership, though Liquid formats are gaining share fastest as continuous processing investments accelerate.
End User:
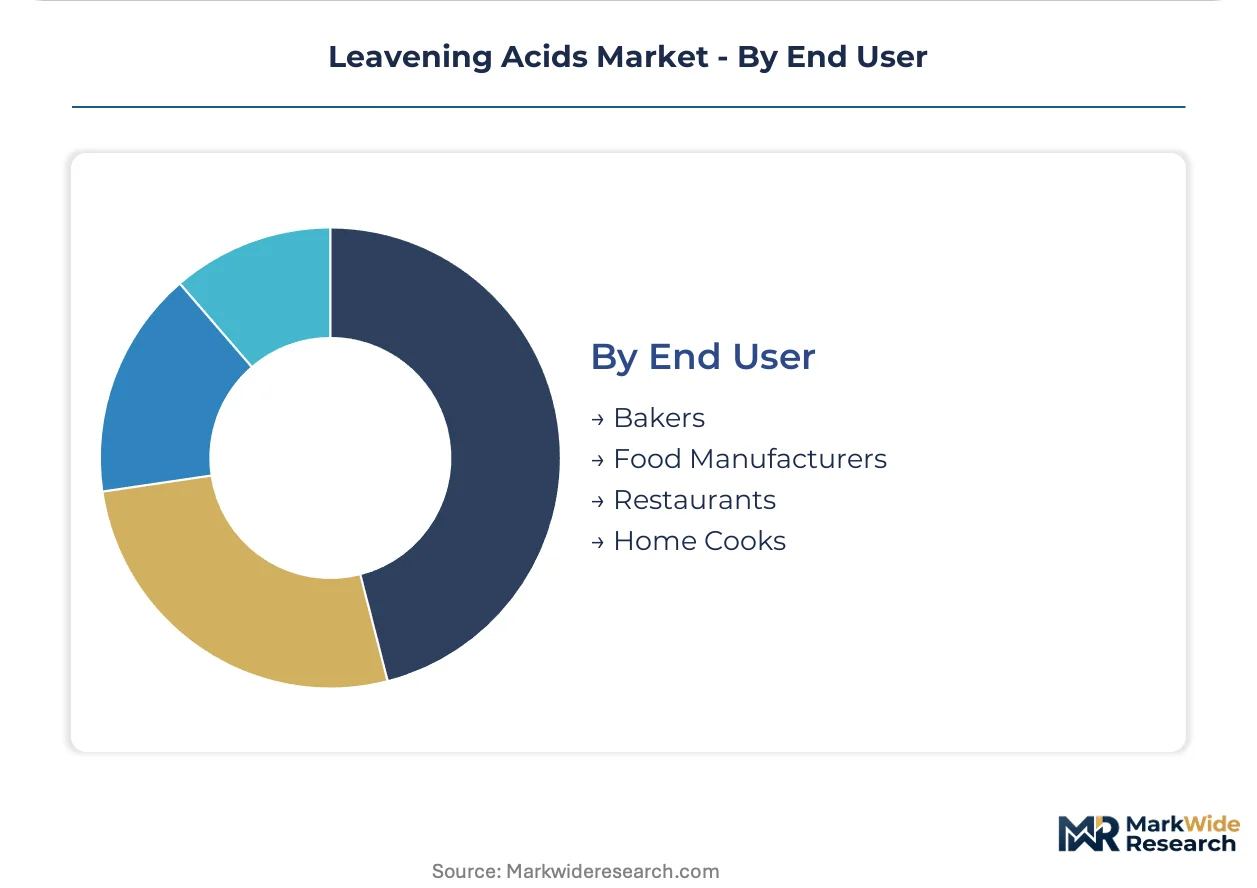
Procurement scale and technical capability split the customer base between specification-driven industrial buyers and price-sensitive fragmented operators.
- Food Manufacturers:Industrial bakery groups and co-manufacturers negotiate frame contracts directly with acid producers, bypassing distribution tiers. Technical service demands include reformulation support for sodium reduction mandates and clean-label transitions.
- Bakers:Independent and regional bakery operations purchase through ingredient distributors, prioritizing consistent quality and reliable delivery over innovation access.
- Restaurants:Foodservice channels require food safety documentation and halal/kosher certification for multi-ethnic menu applications.
- Home Cooks:Retail package sizing and brand recognition dominate this price-sensitive segment with minimal technical specification requirements.
Food Manufacturers command the largest contract values, while Restaurants are climbing the fastest as foodservice recovery drives acid demand for prepared dough systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH compliance deadlines and WHO sodium reduction guidance are redrawing procurement priorities across industrial bakery clusters. National regulators are translating these frameworks into binding reformulation mandates that reshape acid specification criteria.
Germany
Industrial bakeries in North Rhine-Westphalia anchor European phosphate acid consumption for frozen dough applications. The Federal Office of Consumer Protection and Food Safety enforces strict additive labeling under the EU Food Information Regulation. Stuttgart-based equipment manufacturers are retrofitting continuous-mix lines for liquid concentrate dosing systems.
France
Clean-label positioning drives citric acid demand in Parisian premium retail channels. ANSM enforces EFSA phosphate intake limits through national dietary surveillance programs. Lyon and Bordeaux industrial zones are consolidating toll manufacturing partnerships for organic-certified acid blends.
United States
High-speed commercial bakeries in the Midwest specify delayed-action phosphate acids for automated production. FDA GRAS self-affirmation pathways accelerate novel acid approvals, while EPA effluent guidelines constrain phosphorus discharge at manufacturing sites. Chicago and Minneapolis-St. Paul host the largest industrial bakery concentration outside Europe.
Netherlands
Belgian-Dutch cross-border supply chains favor pumpable liquid acid concentrates for continuous processing. The Dutch Food and Consumer Product Safety Authority implements EU F-Gas Regulation compliance checks on refrigeration-dependent bakery operations. Eindhoven and Rotterdam industrial zones are piloting encapsulated acid systems for programmable release kinetics.
Italy
Organic-certified facilities in Emilia-Romagna and Lombardy specialize in cream of tartar production from wine industry byproducts. The Ministry of Health enforces EU organic regulation standards for acid additive certification. Parma and Modena food clusters are expanding clean-label contract manufacturing capacity for pan-European distribution.
Leavening Acids Market Competitive Landscape
On the supply side, the industry is consolidating around agricultural origination scale and fermentation platform specialization. Three strategic archetypes dominate: crop-processing conglomerates with backward integration into feedstock supply, bio-based fermentation specialists leveraging microbial production routes, and diversified ingredient houses with bakery technical service capabilities. Capacity expansion and direct frame contract negotiation with industrial bakery groups represent the primary competitive moves reshaping supplier relationships.
Among agricultural-origination conglomerates, Cargill and Archer Daniels Midland Company occupy positions anchored by corn-derived dextrose conversion capabilities. Corbion exemplifies the fermentation platform archetype through microbial citric acid production. Associated British Foods sits within the integrated food group tier with captive tartaric acid feedstock control.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill |
| Kerry Group |
| Corbion |
| Associated British Foods |
| Lesaffre Group |
| DuPont de Nemours |
| Koninklijke DSM |
| Puratos Group |
| Others |
Supply & Pricing Matrix
Moroccan and Chinese state-controlled phosphate ore suppliers anchor upstream raw material flows, concentrating margin capture with integrated acid manufacturers while squeezing toll processors and regional distributors. This upstream bottleneck forces downstream buyers into long-term offtake contracts or premium spot-market exposure, reshaping procurement risk allocation across European industrial bakeries.
Pricing Analysis
Certification grade creates the primary spread between commodity phosphates and organic-certified alternatives, with REACH-registered and bio-based citric acid commanding shelf price premiums in French and Italian retail channels. Three-tier pricing structure across premium, standard, and economy levels reflects clean-label positioning, volume scale, and technical service bundling. Cost compression in standard phosphate grades is intensifying because Moroccan ore export quotas tighten feedstock availability. Artisanal bakers and home baking segments exhibit highest price sensitivity, while German industrial bakery groups prioritize supply security over unit cost.
Supply Chain Analysis
EU F-Gas Regulation compliance requirements and REACH authorization timelines restrict acid additive flows into European food manufacturing, extending supplier qualification cycles. Manufacturing concentrates in Germany, Belgium, and the Netherlands for phosphate acid processing, with Italy and Spain hosting organic-certified fermentation facilities for citric and tartaric acids. Phosphate rock from Morocco, corn-derived dextrose from US Midwest agricultural processors, and wine industry byproducts from Italian vineyards constitute critical input dependencies. Single-source vulnerability around Moroccan phosphate ore creates geopolitical exposure. Distribution runs through direct frame contracts between acid manufacturers and large industrial bakery groups, bypassing traditional regional ingredient distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Leavening acids sit in early-cycle expansion as clean-label mandates and sodium reduction frameworks penetrate beyond premium retail into mainstream industrial baking, accelerating reformulation service demand and bio-based acid adoption.
For Market Incumbents: Entrench technical service capabilities around sodium reduction reformulation and encapsulated acid systems to defend against bio-based fermentation specialists and potassium bicarbonate substitution threats. Deepen backward integration into phosphate ore offtake agreements or corn origination contracts to secure feedstock margin control. Prioritize organic and kosher/halal certification investments to extend qualification moats. For New Entrants and Emerging Players: Mid-scale organic-certified toll manufacturing capacity in Italy and Spain represents the most penetrable entry point, serving French and German clean-label contract manufacturing demand without capital-intensive greenfield construction. Liquid concentrate dosing system partnerships with Belgian and Danish continuous-mix bakeries offer service-based revenue models distinct from commodity acid sales. Go-to-market positioning should emphasize carbon accounting transparency for Scope 3 reporting compliance. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed fermentation platform specialists possessing microbial citric acid production capabilities and established EU organic certification. Five-to-ten year viability hinges on clean-label penetration rates outpacing potassium-based bypass technologies. Monitor ECHA sunset date scheduling for phosphate compound authorizations as the critical inflection signal for portfolio rebalancing toward bio-based alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Ore | Cargill and ADM secure Moroccan offtake agreements to bypass state-controlled supplier concentration. |
| Bio-based Fermentation Scale-Up | Corbion expands microbial citric acid capacity to capture EFSA phosphate limit-driven substitution demand. |
| Encapsulation Technology Licensing | German equipment manufacturers program CO2 release kinetics for frozen dough applications. |
| Clean-Label Contract Manufacturing | Italian toll producers extend organic-certified capacity for pan-European bakery ingredient supply. |
| Liquid Concentrate Dosing Partnerships | Belgian industrial bakeries adopt pumpable acid systems eliminating powder handling infrastructure. |
Research Methodology
Initial hypotheses were tested against primary input from technical R&D directors at acid manufacturers, procurement leads at German and French industrial bakery groups, plant managers at fermentation facilities, and distribution channel partners, then refined through secondary validation. Sources included ECHA substance registration databases, EU customs trade flows for phosphate and organic acid categories, SEC 10-K filings from agricultural processing conglomerates, and Cefic specialty chemical industry reports. Bottom-up volume modeling triangulated against top-down market sizing across acid type, application, and form factor segments.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions covering phosphate versus organic acid chemistry, bakery versus confectionery versus dairy end-use, powder versus liquid versus granular form, and industrial manufacturer versus artisanal baker customer archetype. CAGRs derived from production capacity expansion announcements, customer procurement pipeline visibility, and regulatory deadline pacing. Industry-specific forecast inputs included EFSA phosphate intake limit implementation schedules and WHO sodium reduction guidance adoption timelines.
Practitioners should monitor ECHA authorization sunset dates, Moroccan phosphate export policy shifts, and national sodium reduction mandate enactments for early signals requiring forecast reassessment. Material shifts in clean-label penetration rates or potassium bicarbonate substitution economics would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Emulsifiers Market
Food Additives and Ingredients
North America Anti-Caking Market
Food Additives and Ingredients
China Anti-Caking Market
Food Additives and Ingredients
Natural Food Additives Market
Food Additives and Ingredients
Cream Emulsifier Market
Food Additives and Ingredients
Gellan Gum Market
Food Additives and Ingredients
Clean Label Emulsifiers Market
Food Additives and Ingredients
Italy Food Emulsifier Market
Food Additives and Ingredients
Amaranth (E123) Market
Food Additives and Ingredients
Natural Food Preservatives Market
Food Additives and Ingredients
Food Acidulants Market
Food Additives and Ingredients
Brazil Food Emulsifiers Market
Food Additives and Ingredients
Potassium Propionate Market
Food Additives and Ingredients
Fatty Esters Market
Food Additives and Ingredients
Carrageenan Market
Food Additives and Ingredients
Beta Agonist Feed Additive Market