
 Achiote Powder Market | 2026-2036
Achiote Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Achiote Powder Market Outlook
Food industry applications are recalibrating demand patterns as clean-label trends push manufacturers toward plant-derived colorants. Kalsec Inc. leverages its botanical extraction expertise to supply standardized bixin and norbixin formulations for processed meats and dairy. Sensient Technologies Corporation anchors its position through integrated color systems that blend achiote with other natural pigments for consistent hue stability. DDW, The Color House competes by specializing in custom color matching services for multinational food brands seeking regulatory compliance across multiple jurisdictions.
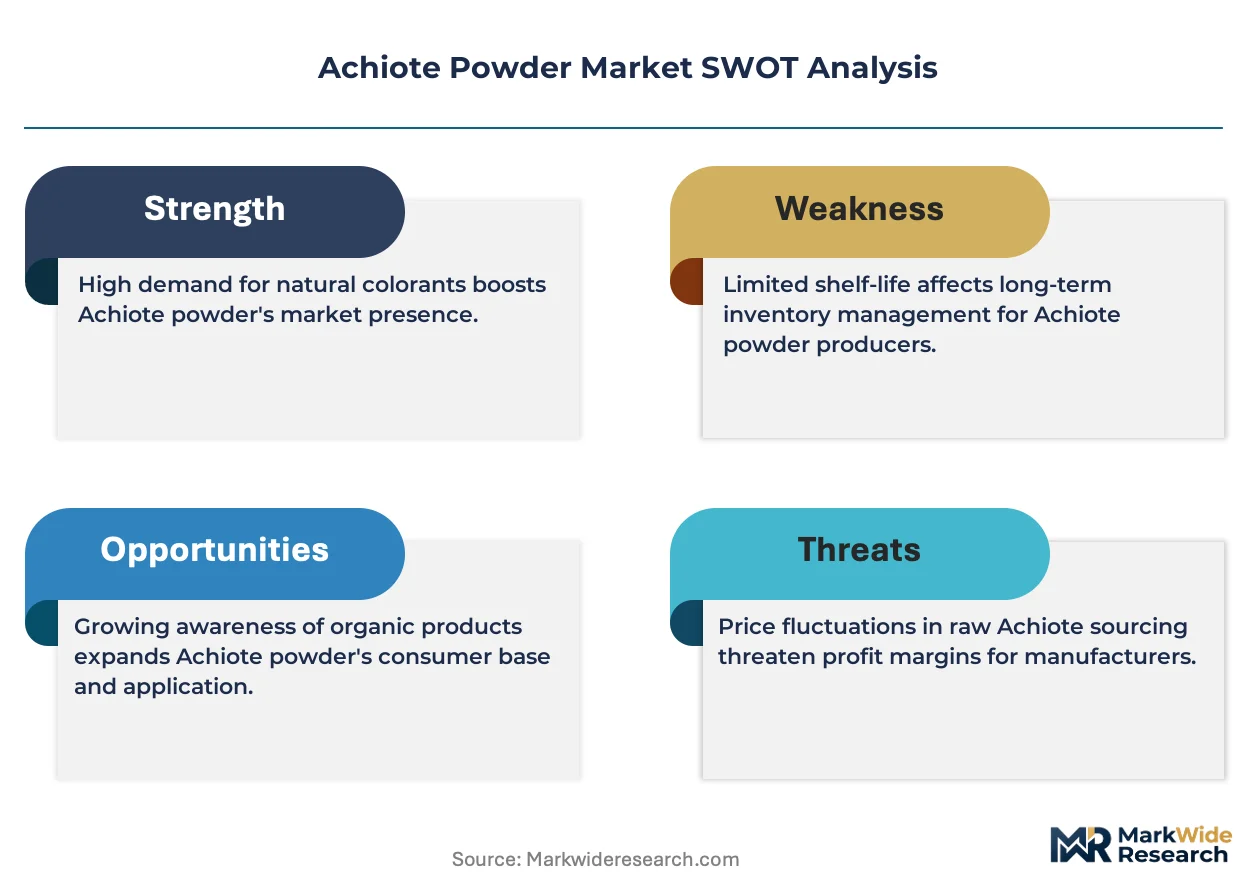
Achiote powder consists of dried and pulverized seeds from Bixa orellana L., a tropical shrub native to the Americas, containing carotenoid pigments primarily bixin and norbixin that deliver yellow to orange coloration with heat and light stability varying by extraction method. The powder serves industrial markets as a natural colorant replacing synthetic azo dyes in food matrices, cosmetics, and pharmaceutical coatings where regulatory restrictions on artificial additives have tightened. Organic product type commands premium positioning as certified cultivation protocols and traceability requirements add cost but secure access to EU and North American retail channels. Food industry application dominates volume consumption, though cosmetics represents the fastest-expanding segment as formulators seek natural alternatives for lip and cheek products. Powder form maintains the largest share due to handling efficiency and shelf stability, while extract form captures margin pools in high-concentration pharmaceutical and personal care applications.
FDA color additive regulations and EFSA natural food colorant evaluations shape product specifications and safety documentation requirements for cross-border trade. BIS standards in India and ANVISA requirements in Brazil add compliance layers for exporters targeting emerging processing hubs. Stakeholders must monitor evolving maximum permitted levels for bixin in infant and specialty foods across jurisdictions while building regional extraction partnerships to secure supply continuity.
Market Dynamics
Clean-label regulatory mandates across the European Union and North America are systematically displacing synthetic azo dyes in processed food matrices, forcing reformulation cycles that favor bixin and norbixin extracts from standardized achiote seed processing.
Growth Catalysts
- EFSA natural food colorant evaluations:The European Food Safety Authority's favorable scientific opinions on bixin safety profiles have accelerated approval timelines for achiote-derived colorants in dairy and confectionery applications.
- Cosmetics formulators:Personal care manufacturers in France and Germany are integrating achiote pigments into lip and cheek products as mineral-based alternatives face microplastic scrutiny under REACH annex revisions.
- Peruvian export clusters:Concentrated processing infrastructure around Piura and Tumbes is expanding cold-press extraction capacity to serve North American natural product distributors.
Market Restraints
- Seed supply volatility:Bixa orellana cultivation remains concentrated in tropical Latin American zones where erratic rainfall patterns disrupt raw material availability for European processors.
- Turmeric and paprika substitution:Lower-cost carotenoid alternatives from Indian and Spanish supply bases capture price-sensitive applications in snack seasoning and beverage coloration.
- BIS standard harmonization delays:India's Bureau of Indian Standards maintains divergent purity specifications for bixin content that fragment export documentation requirements.
Strategic Opportunities
- Infant nutrition white space:ANVISA in Brazil and FDA in the United States are evaluating expanded maximum permitted levels for bixin in formula applications, opening premium positioning for certified-organic achiote extracts.
- Direct-to-manufacturer digital platforms:Specialty ingredient marketplaces are disintermediating traditional spice traders, allowing Mexican and Peruvian processors to capture margin from European cosmetics SMEs.
- Carbon accounting integration:EU Green Deal supply chain disclosure rules favor achiote over petrochemical-derived colorants in corporate Scope 3 reduction strategies.
Industry Challenges
- Chromatographic analysis talent scarcity:Standardized bixin quantification requires HPLC expertise that remains concentrated in pharmaceutical testing labs rather than food-grade extraction facilities.
- Organic certification timeline compression:EU organic equivalence negotiations with Peruvian certifying bodies create 18-24 month approval gaps that block harvest-to-market continuity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Achiote Powder Market |
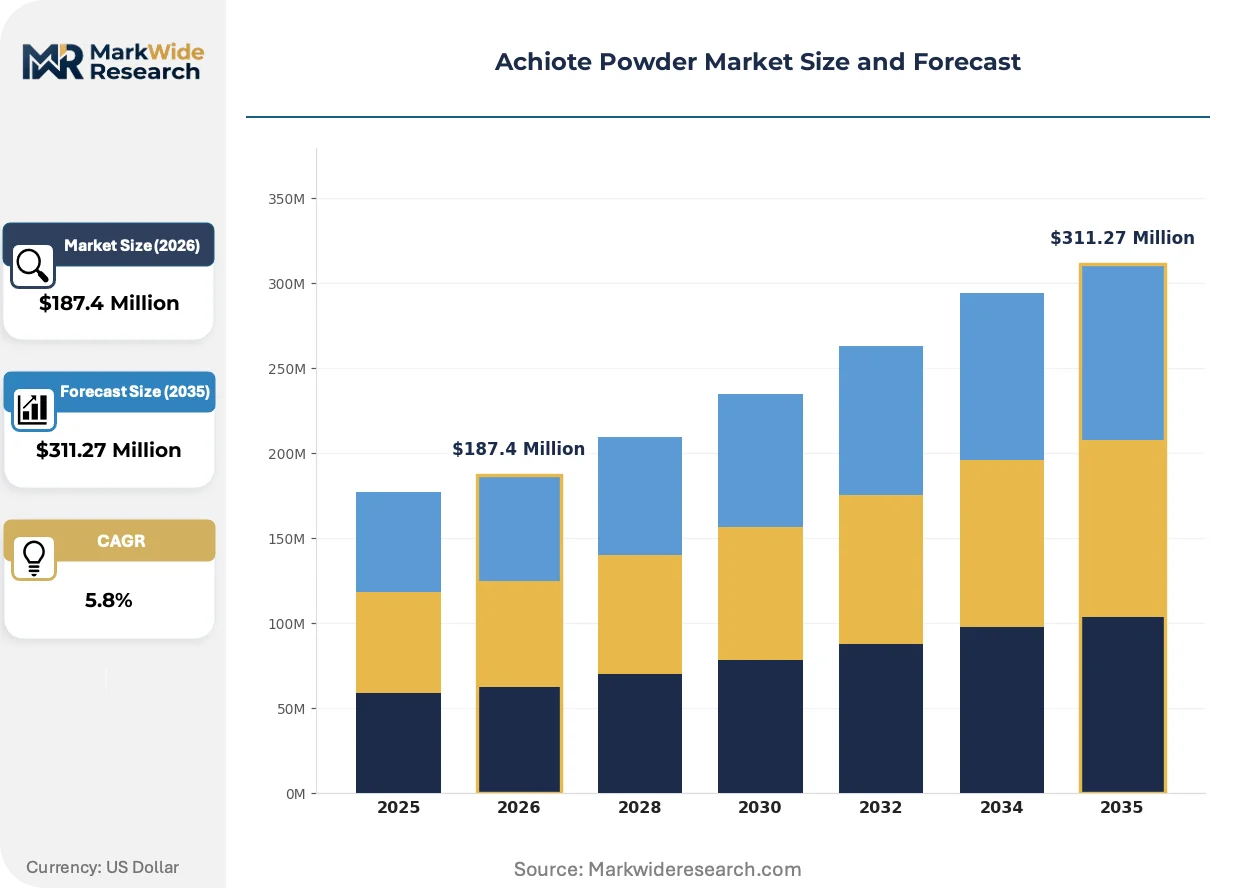
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Conventional, Ground, Whole Seeds Application: Food Industry, Cosmetics, Pharmaceuticals, Textile Dyes Form: Powder, Paste, Extract, Whole Packaging Type: Bags, Jars, Tins, Pouches |
| Companies Covered | Kalsec Inc., Sensient Technologies Corporation, DDW, The Color House, BioconColors, Chr. Hansen Holding A/S, Sabinsa Corporation, Amerilure Inc., ADM, Naturex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Achiote Powder Market Strategic Shifts
Extraction technology and regulatory science are converging to redefine how achiote processors capture value across food, cosmetics, and pharmaceutical grade tiers.
Supercritical CO2 extraction is decentralizing colorant production away from centralized solvent-based facilities in Mexico and Peru. Mid-scale processors in Colombia and Ecuador are adopting modular supercritical units to produce pharmaceutical-grade norbixin for coating applications. This distributed processing architecture compresses lead times for European cosmetics formulators while reducing solvent residue compliance burdens.
EFSA's 2023 updated exposure assessment for annatto extracts has tightened purity specifications for infant food applications. The regulation now mandates sub-part-per-million detection thresholds for heavy metal contaminants that legacy solvent extraction methods struggle to meet. German and Dutch ingredient distributors are qualifying only supercritical-derived supplies for pediatric nutrition contracts.
Beauty sector buyers are consolidating supplier relationships around vertically integrated achiote processors with in-house chromatography labs. French cosmetics houses now require batch-specific bixin certificates rather than generic origin documentation. This behavioral shift favors Peruvian exporters with captive analytical capabilities over traditional commodity traders in Rotterdam and Hamburg.
Achiote Powder Market Segmentation
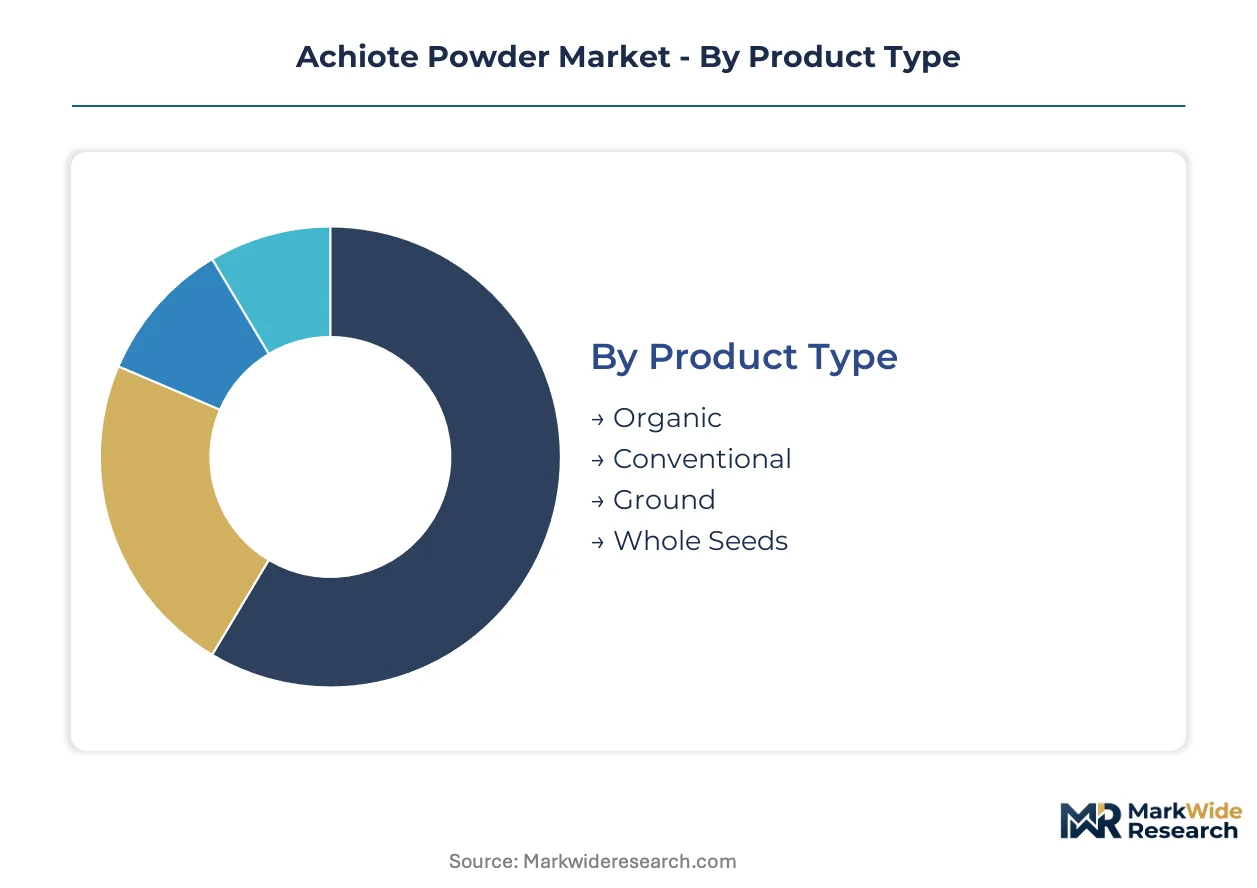
Achiote powder segmentation reflects divergent value capture strategies across certification tiers, concentration levels, and end-use specifications. Manufacturers configure production lines differently for organic food-grade extracts versus conventional textile dyes, with equipment interchangeability limited by residue management protocols.
Product Type:
Certification requirements and traceability obligations create a steep cost gradient from organic to conventional grades, with processing infrastructure largely non-overlapping between tiers.
- Organic:Certified cultivation under EU organic equivalence or USDA NOP mandates HPLC-verified pesticide absence and lot-level traceability. Demand concentrates in infant nutrition and premium cosmetics formulations where EFSA purity thresholds for heavy metals apply. Peruvian Piura processors command premium positioning through captive organic acreage and in-house chromatography labs.
- Conventional:Standard agricultural protocols without third-party certification serve price-sensitive food coloring and textile applications. Mexican Guanajuato processors dominate volume through solvent-extracted bixin for processed meat matrices where color stability outweighs clean-label positioning.
- Ground:Pulverized seed form retains fiber content and delivers rustic flavor profiles for traditional Latin American cooking. Brazilian Amazonas cooperatives supply ethnic retail channels in Miami and Los Angeles with minimal processing overhead.
- Whole Seeds:Intact annatto seeds enable custom extraction by end-users and command longest shelf life in tropical storage conditions. Caribbean spice traders stock whole seeds for re-export to European cosmetics SMEs seeking batch-specific pigment control.
Most installed capacity flows through Conventional. Expansion is steepest in Organic.
Application:
End-use specifications fragment the market into food-grade, pharmaceutical-grade, and technical-grade tiers with incompatible purity documentation requirements.
- Food Industry:Dairy, confectionery, and processed meat matrices require standardized bixin concentrations between 0.1% and 2.0% by weight. FDA color additive regulations and EFSA natural food colorant evaluations mandate separate safety dossiers for each application subcategory.
- Cosmetics:Lip and cheek products drive demand for norbixin-rich extracts with sub-part-per-million heavy metal thresholds. French and German formulators under REACH annex revisions are displacing mineral pigments with plant-derived alternatives.
- Pharmaceuticals:Tablet coating applications require supercritical CO2-derived extracts with solvent residue below detection limits. Colombian processors are installing modular extraction units to serve this specification tier.
- Textile Dyes:Conventional ground powder serves natural fiber coloring where lightfastness requirements are modest. Indian Rajasthan handloom cooperatives import Peruvian achiote for organic cotton certification compliance.
Food Industry absorbs the majority of volume throughput. Cosmetics is climbing the fastest as mineral pigment restrictions tighten.
Form:
Physical state determines handling economics, shelf stability, and concentration ratios across downstream manufacturing processes.
- Powder:Spray-dried or mechanically pulverized material offers lowest moisture activity and longest ambient storage life. Mexican industrial processors supply bulk powder to North American meatpacking facilities through just-in-time distribution agreements.
- Paste:Oil-based suspensions of ground seed in vegetable carriers deliver ready-to-use colorant for small-batch food manufacturers. Brazilian São Paulo distributors package paste in retail tubes for restaurant and catering segments.
- Extract:Solvent or supercritical-derived concentrated bixin and norbixin enable precise dosing in pharmaceutical and personal care matrices. German and Dutch ingredient houses qualify only supercritical-derived supplies for pediatric nutrition contracts following EFSA's updated exposure assessment.
- Whole:Unprocessed seeds allow end-user control over extraction method and final pigment concentration. Traditional Caribbean and Central American cooks prefer whole seeds for achiote oil preparation in home and restaurant settings.
Powder commands the largest share of commercial volume. Extract is gaining share fastest in premium pharmaceutical and cosmetics applications.
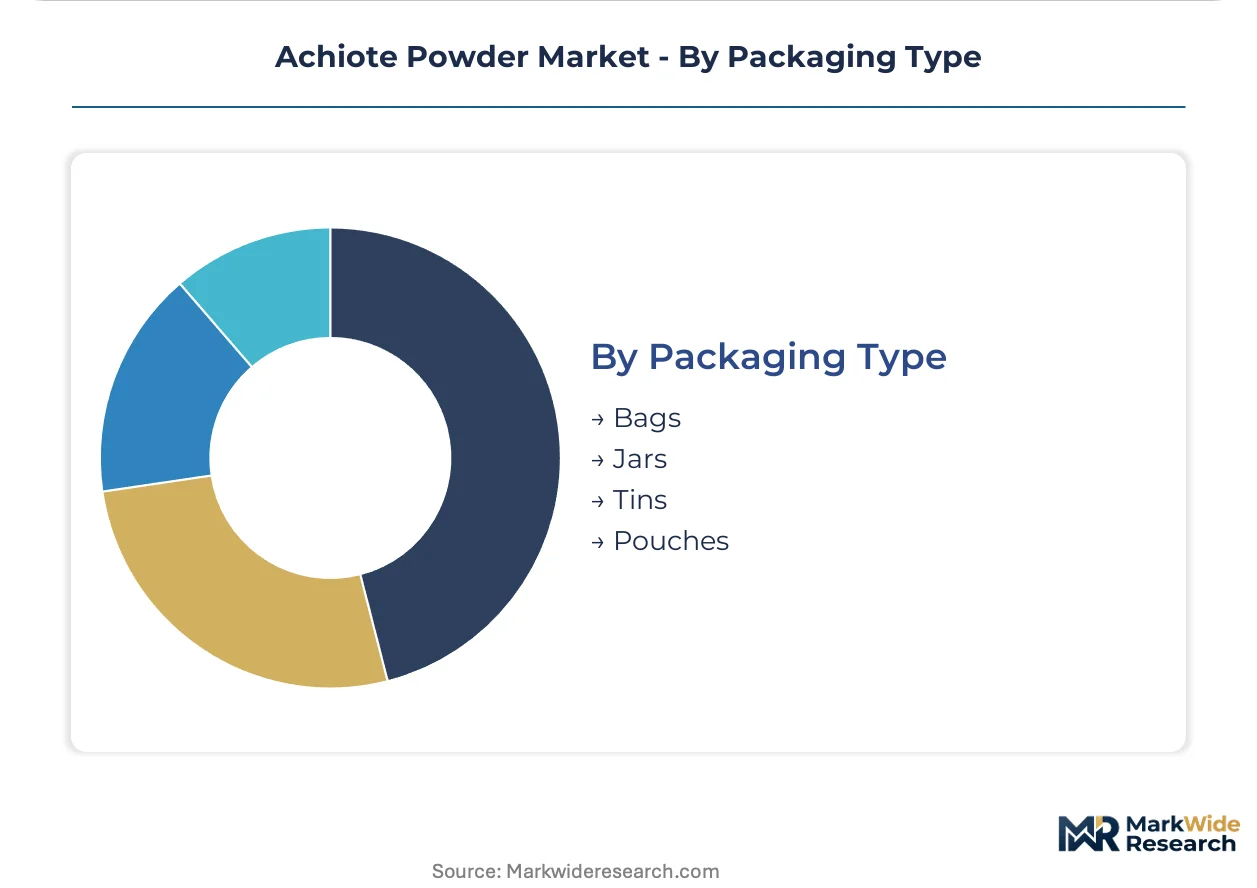
Packaging Type:
Packaging configuration aligns with customer scale, regulatory labeling requirements, and moisture protection needs across distribution channels.
- Bags:Multi-layer kraft or woven polypropylene sacks of 10-25 kilograms serve industrial food processors with high-throughput grinding and extraction operations. Peruvian export clusters ship containerized bagged powder to Rotterdam and Hamburg for European redistribution.
- Jars:Glass or PET containers with tamper-evident closures target retail spice shelves and professional kitchens requiring visible product quality assessment. Mexican brands dominate Hispanic grocery retail in Texas and California through jarred presentation.
- Tins:Metal canisters with hermetic seals provide maximum moisture and oxygen barrier for premium organic grades with extended ambient storage requirements. French cosmetics ingredient distributors specify tin packaging for pharmaceutical-grade extracts.
- Pouches:Flexible laminate sachets enable single-use portioning for foodservice and small-batch manufacturing. Colombian processors are piloting pouch formats for direct-to-manufacturer digital platforms serving European cosmetics SMEs.
Industrial procurement flows predominantly through Bags. Pouch configurations are expanding most quickly in direct digital channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping achiote processing geography as EU purity mandates push extraction capacity toward Latin American supply zones with lower cost-of-compliance structures. Processors migrate to jurisdictions where organic certification timelines and heavy metal testing burdens compress operational overhead.
Mexico
Processed meat manufacturers in Guanajuato and Jalisco drive solvent-extracted bixin demand for color-stable formulations. FDA color additive regulations govern cross-border shipments to Texas and California meatpacking facilities. Mexican industrial processors supply bulk powder through just-in-time distribution agreements with North American distributors.
Peru
Piura and Tumbes clusters expand cold-press extraction capacity to serve natural product distributors in Germany and the Netherlands. EFSA natural food colorant evaluations determine eligibility for dairy and confectionery applications in EU member states. Peruvian exporters with captive organic acreage and in-house chromatography labs command premium positioning in infant nutrition contracts.
Brazil
ANVISA requirements for maximum permitted bixin levels in formula applications create compliance benchmarks for export-oriented processors. São Paulo distributors package oil-based paste suspensions for restaurant and catering segments across Mercosur trade zones. Amazonas cooperatives supply ethnic retail channels in Miami and Los Angeles with minimal processing overhead.
Germany
REACH annex revisions on mineral pigments accelerate displacement by plant-derived alternatives in lip and cheek formulations. German ingredient houses qualify only supercritical-derived supplies for pediatric nutrition contracts following EFSA's updated exposure assessment. Cologne and Hamburg distributors consolidate supplier relationships around vertically integrated processors with batch-specific bixin certificates.
United States
Clean-label procurement from multinational food brands tightens specifications for standardized norbixin concentrations in dairy matrices. USDA organic equivalence negotiations with Peruvian certifying bodies create approval gaps that block harvest-to-market continuity for some importers. California and Texas-based meatpackers maintain direct procurement relationships with Mexican solvent-extraction facilities.
Achiote Powder Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with extraction technology capabilities determining tier boundaries. The vendor base concentrates around three strategic archetypes: integrated botanical extractors with captive cultivation, specialty color houses with custom formulation services, and regional commodity processors serving price-sensitive industrial accounts. Competitive moves center on supercritical CO2 capacity installation and organic certification pipeline development.
Within the integrated extractor tier, Kalsec Inc. and Sensient Technologies Corporation exemplify archetypes built on botanical sourcing networks and standardized pigment formulations. DDW, The Color House occupies a position among specialty color houses competing through regulatory compliance documentation across multiple jurisdictions. These three anchors illustrate how competitive positioning depends on extraction method certification and analytical capability depth rather than scale alone.
| Leading Market Players |
|---|
| Kalsec Inc. |
| Sensient Technologies Corporation |
| DDW, The Color House |
| BioconColors |
| Chr. Hansen Holding A/S |
| Sabinsa Corporation |
| Amerilure Inc. |
| ADM |
| Naturex |
| Others |
Value Chain & Pricing Dynamics
Multinational food brands and European cosmetics SMEs concentrate procurement power through consolidated supplier relationships, anchoring contract-based long-term offtake pricing with volume-tier discounts and certification-grade premiums. This buyer concentration forces processors to absorb upstream cost volatility while competing on EFSA-compliant documentation and organic traceability.
Pricing Analysis
Distributor margins for achiote extracts typically run 15-25 percent above processor gate prices, with Rotterdam and Hamburg ingredient houses capturing value through batch-specific chromatography certification. Three-tier pricing structure across organic pharmaceutical-grade, conventional food-grade, and ground seed economy levels reflects HPLC verification costs and EU organic equivalence timelines. Cost compression in conventional solvent-extracted bixin is intensifying because Mexican processors face turmeric and paprika substitution in price-sensitive snack seasoning. Small-batch cosmetics formulators show highest price sensitivity, while infant nutrition contract manufacturers accept substantial premiums for supercritical-derived norbixin with sub-part-per-million heavy metal documentation.
Supply Chain Analysis
Direct-to-manufacturer digital platforms are disintermediating traditional spice traders, allowing Peruvian and Colombian processors to capture margin previously lost to Rotterdam and Hamburg redistribution. Raw material supply draws from Bixa orellana cultivation clusters in Peru, Mexico, and Brazil, with seed availability tethered to erratic rainfall patterns in tropical Latin American zones. Chromatographic analysis talent scarcity creates single-source vulnerability for standardized bixin quantification, as HPLC expertise remains concentrated in pharmaceutical testing labs rather than food-grade extraction facilities. Distribution runs through containerized bulk shipments to European port hubs, with final-mile delivery to cosmetics formulators and pharmaceutical coaters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in achiote powder hinges on supercritical CO2 extraction cost curves flattening and organic certification pipeline compression, enabling processors to capture pharmaceutical-grade premiums without legacy solvent-extraction overhead.
For Market Incumbents: Lock in captive organic acreage through long-term grower contracts in Piura and Tumbes, insulating against seed supply volatility while securing EU organic equivalence continuity. Invest in modular supercritical capacity to displace centralized solvent facilities and meet EFSA's tightened infant nutrition purity thresholds. Turmeric and paprika substitution in price-sensitive applications demands defensive positioning through backward integration into seed processing. For New Entrants and Emerging Players: Launch via direct-to-manufacturer digital platforms serving French and German cosmetics SMEs, bypassing established Rotterdam and Hamburg distributor margins. Target pharmaceutical-grade norbixin for tablet coating applications, where Colombian processors are still installing modular extraction units and incumbent capacity remains thin. Infant nutrition white space offers the most penetrable segment, with ANVISA and FDA evaluating expanded maximum permitted bixin levels. For Investors and Strategic Acquirers: Specialty color houses with custom formulation services are the most active acquirer in this space, seeking vertical integration into botanical extraction to secure supply continuity and batch-specific certification capabilities. Acquisition target archetype: Peruvian or Colombian processors with captive organic acreage, in-house HPLC labs, and existing EFSA-compliant documentation. Watch for EU Green Deal supply chain disclosure rules tightening corporate Scope 3 reduction strategies as inflection indicator for natural colorant preference acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Capacity Installation | Modular units in Colombia and Ecuador meet EFSA infant nutrition purity thresholds. |
| Organic Certification Pipeline Development | EU equivalence negotiations with Peruvian certifying bodies compress 18-24 month approval gaps. |
| Backward Integration into Seed Cultivation | Captive acreage in Piura insulates processors from tropical rainfall volatility. |
| Direct-to-Manufacturer Digital Platform Launch | Disintermediation captures margin from European cosmetics SMEs seeking batch-specific pigment control. |
| Pharmaceutical-Grade Extract Capacity Expansion | Supercritical-derived norbixin serves tablet coating demand with solvent residue below detection limits. |
Study Parameters
Multiple input streams — primary interviews with extraction facility managers, regulatory affairs specialists at EFSA and ANVISA, and procurement leads at multinational food brands — were reconciled against secondary validation from customs trade data, FDA color additive filings, and EU organic certification databases. Bottom-up triangulation across processor capacity surveys and top-down demand modeling from end-use consumption patterns ensured cross-verified volume and value estimates.
Data-stream reconciliation anchored the analytical framework across the projection horizon, with segmentation modeling across certification tier, concentration level, end-use specification, and regional processing hub. CAGRs were derived from fitted growth curves against historical trade flow trajectories, incorporating bixin price series volatility and organic premium persistence as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under seed supply disruptions from climate volatility or delays in EU organic equivalence negotiations. Periodic stress-testing of base assumptions is recommended, particularly regarding EFSA maximum permitted level revisions and REACH annex pigment substitution timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Europe and Asia Juniper Berries Market
Spices and Seasonings
Incense Sticks (Agarbatti) Market
Spices and Seasonings
Global Black Pepper Market
Spices and Seasonings
Fennel Powder Market
Spices and Seasonings
Gourmet Seaweed Seasoning Market
Spices and Seasonings
Pink Himalayan Salt Market
Spices and Seasonings
Africa Spice and Herb Extracts Market
Spices and Seasonings
Low Sodium Sea Salt Market
Spices and Seasonings
White Pepper Market
Spices and Seasonings
Cardamom Oil Market
Spices and Seasonings
US Spice and Seasonings Market
Spices and Seasonings
Onion Essential Oil Market
Spices and Seasonings
Middle East and Africa Food Micronized Salt Market
Spices and Seasonings
Onion Powder Market
Spices and Seasonings
Saffron Market
Spices and Seasonings
Onion Salt Market