
 Asia-Pacific Malt Ingredient Market | 2026-2036
Asia-Pacific Malt Ingredient Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Malt Ingredient Market Outlook
Malting technician shortages across Australia and New Zealand are redrawing production capacity timelines for regional suppliers. Cargill leverages its integrated grain origination network to secure barley feedstock across the Australian wheat belt. Muntons PLC anchors its Asia-Pacific presence through specialized malt extract formulations tailored to Japanese beverage manufacturers. Malteurop China dominates import substitution by operating domestic malting plants that reduce cross-border raw material exposure.
Malt ingredients comprise germinated cereal grains—typically barley—dried in kilns to develop enzymatic activity, diastatic power, and color compounds measured in EBC or Lovibond units, primarily serving fermentation feedstock and flavoring functions for beverage and food systems. Malt extract leads product type value capture due to its concentrated solubility and extended shelf stability in industrial formulations. Beverage application growth outpaces baking and confectionery segments as regional craft brewing expands, though animal feed malt co-products sustain margin recovery from otherwise spent grain streams.
China's SAMR enforces GB standards for food-grade malt specifications, while Australia's FSANZ governs maximum moisture and protein thresholds for imported malting barley. India's FSSAI fortification rules for malt-based health drinks are tightening additive disclosure requirements and pushing reformulation timelines. Breweries and ingredient buyers must track evolving mycotoxin testing protocols across multiple national food safety regimes to avoid border detention and contract penalties.
Market Dynamics
Craft brewing proliferation across Southeast Asia and India's FSSAI fortification mandates for malt-based nutritional products are compressing ingredient specification timelines and forcing procurement model evolution among regional malt suppliers.
Growth Catalysts
- India's FSSAI fortification mandates:Tighter additive disclosure requirements for malt-based health drinks are accelerating reformulation cycles and expanding addressable demand for certified malt extracts.
- Specialty malt procurement:Southeast Asian craft breweries are accelerating procurement of specialty malt extracts with distinct enzymatic profiles for differentiated fermentation outcomes.
- Shandong Province malting clusters:Concentrated malting infrastructure in China's Shandong Province enables integrated supply to both domestic brewers and export channels, reducing logistics friction.
Market Restraints
- Barley feedstock volatility:Australian wheat belt weather variability and export competition from livestock feed markets compress margin stability for regional maltsters.
- Malting technician scarcity:Australia and New Zealand face acute shortages of trained kiln operators and germination specialists, extending production capacity timelines by 18-24 months.
- Cross-border raw material exposure:Import-dependent maltsters without domestic malting plants remain exposed to China's SAMR border detention protocols for mycotoxin non-compliance.
Strategic Opportunities
- Vietnam craft brewing white space:Underpenetrated craft beer distribution in Ho Chi Minh City and Hanoi creates first-mover positioning for specialty malt extract suppliers.
- Japan beverage convergence:Convergence of traditional sake brewing with malt-based RTD formulations opens formulation partnerships with Japanese beverage manufacturers.
- FSSAI disclosure tailwinds:India's tightening additive disclosure rules favor transparent supply chain operators with integrated traceability systems.
Industry Challenges
- Diastatic power certification delays:Multi-jurisdictional testing for enzymatic activity against EBC and Lovibond standards extends product qualification timelines by 4-6 months.
- Legacy kiln infrastructure retrofitting:Southeast Asian maltsters face capital intensity in upgrading coal-fired kilns to meet Australia's FSANZ moisture threshold requirements for export eligibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Malt Ingredient Market |
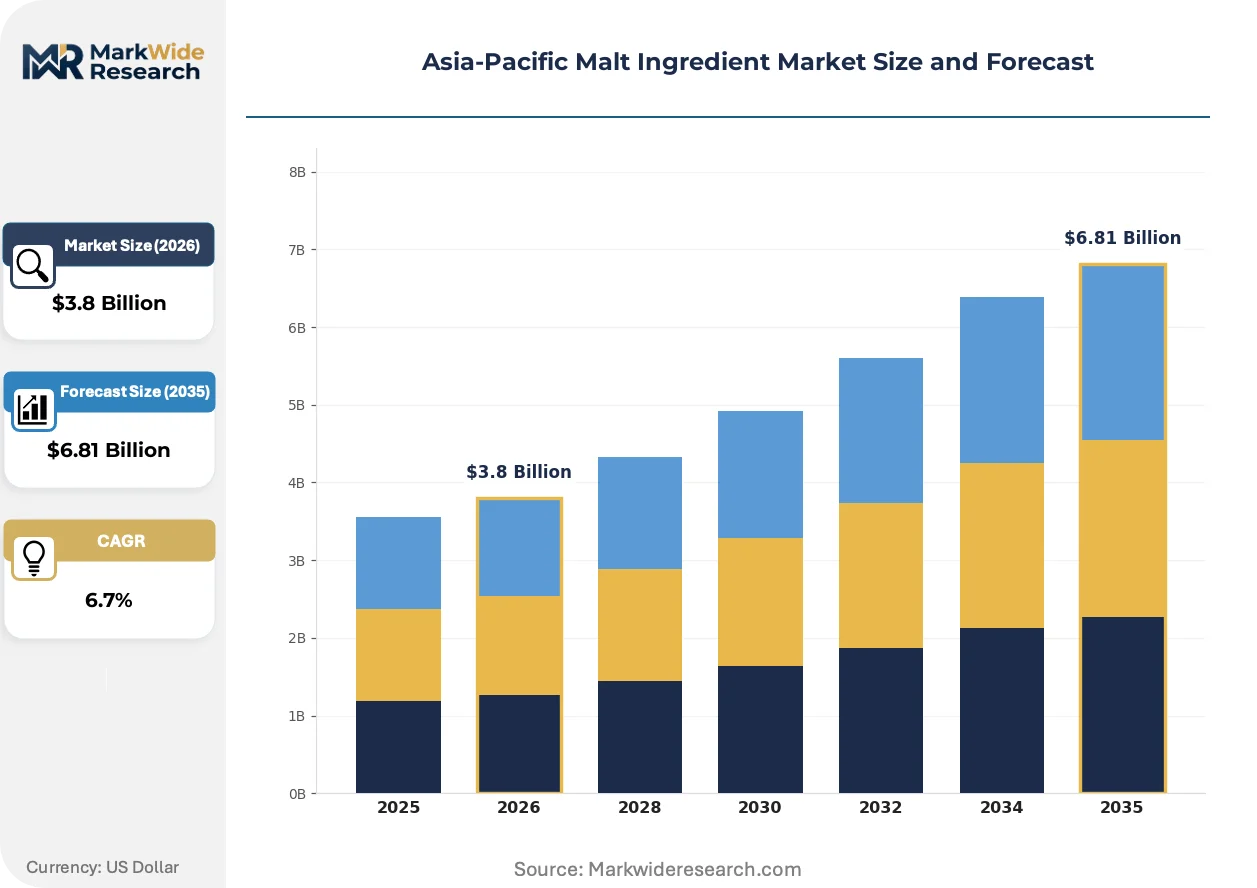
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Malt Extract, Malted Barley, Malted Wheat, Liquid Malt Application: Beverages, Baking, Confectionery, Animal Feed End User: Beverage Manufacturers, Food Processors, Breweries, Distilleries Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Rahr Corporation, VIVESCIA Group, Puremalt Products Ltd., Malteurop China, Barrett Burston Malting, Muntons PLC, Axereal, Cargill, GrainCorp Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Malt Ingredient Market Strategic Shifts
Precision germination control systems and automated kiln monitoring are compressing traditional malting cycles while regional regulators tighten mycotoxin surveillance protocols across import channels.
Automated steeping and germination control systems using IoT-enabled moisture sensors and AI-driven temperature modulation are decomposing the traditional 7-9 day floor malting cycle into 4-5 day continuous-flow operations. Mid-scale craft maltsters in Australia's Riverina region and New Zealand's Canterbury Plains are piloting these systems to match specialty batch consistency with industrial throughput. The technology is decomposing the historical trade-off between artisanal flavor development and production scalability that has constrained regional supplier expansion.
China's SAMR enforcement of GB standards for food-grade malt specifications is tightening mycotoxin testing protocols for aflatoxin B1 and ochratoxin A with reduced maximum residue limits. Australian and New Zealand malt exporters face expanded pre-shipment certification requirements and border inspection frequency, compressing contract fulfillment windows. Malt extract suppliers serving China's Shandong brewing clusters are responding by integrating third-party laboratory partnerships into their quality assurance workflows.
Brewery technical buyers are consolidating supplier relationships around integrated grain-to-glass traceability platforms that document varietal origin, malting parameters, and batch-specific enzymatic certificates. Direct procurement contracts with designated malting facilities are displacing spot-market commodity purchasing among Vietnam's emerging craft brewery segment. This behavioral shift is most visible in Ho Chi Minh City, where brewery founders prioritize supply chain transparency for consumer-facing marketing differentiation.
Asia-Pacific Malt Ingredient Market Segmentation
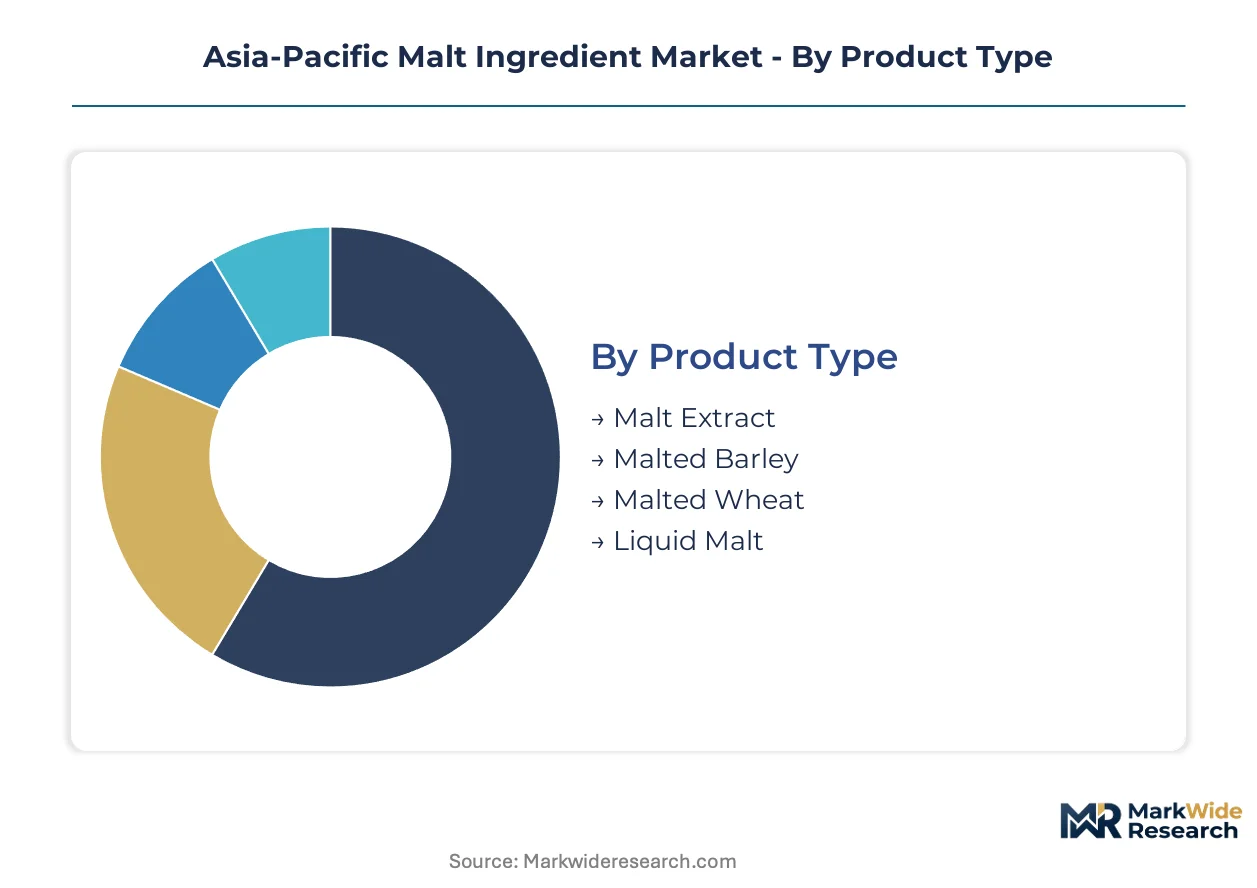
Malt ingredient buyers segment procurement by solubility requirements, enzymatic specifications, and shelf stability needs. Distinct margin profiles emerge across liquid concentrates versus dried extracts, while application-driven certification demands reshape supplier qualification workflows across the Asia-Pacific brewing and food processing sectors.
Product Type:
Highest margin capture concentrates in concentrated soluble formats that reduce downstream processing costs for beverage manufacturers.
- Malt Extract:Concentrated soluble syrup or powder derived from mashed malted grains, delivering standardized diastatic power and color compounds measured in EBC units. Beverage manufacturers across China's Shandong Province anchor procurement volumes here, drawn by extended shelf stability and batch consistency in industrial-scale brewing. India's FSSAI fortification mandates for malt-based nutritional products are accelerating certified extract demand.
- Malted Barley:Whole germinated barley kernels kiln-dried to develop enzymatic activity for traditional mashing processes. Craft breweries in Vietnam's Ho Chi Minh City and Hanoi prioritize specialty roasted varieties for flavor differentiation in emerging distribution channels.
- Malted Wheat:Germinated wheat subjected to controlled kilning, offering distinct protein profiles and hazier fermentation outcomes. Japanese beverage manufacturers incorporate wheat malt into RTD formulation experiments blending sake and malt bases.
- Liquid Malt:Unconcentrated aqueous malt solution requiring refrigerated logistics but preserving volatile aromatic compounds. Australian craft maltsters in the Riverina region supply regional distilleries seeking fresh enzymatic activity for specialty spirits production.
Malt extract holds installed capacity across Shandong's integrated malting clusters. Liquid malt is rotating up the share rankings among premium craft distilleries prioritizing aromatic freshness over logistics convenience.
Application:
Volume concentration tilts toward fermentation feedstock applications, though co-product valorization in adjacent sectors sustains margin recovery.
- Beverages:Primary fermentation substrate for beer, malt-based RTDs, and traditional cereal beverages. Southeast Asian craft brewing expansion across Thailand, Vietnam, and the Philippines is compressing specialty malt procurement timelines and forcing supplier certification upgrades.
- Baking:Enzymatic flour conditioning and flavor enhancement in commercial bread production. India's organized bakery sector sources malt extracts for standardized browning reactions in industrial tunnel ovens.
- Confectionery:Color development and flavor modulation in chocolate and caramel formulations. Japanese confectionery manufacturers specify low-diastatic extracts to prevent unwanted enzymatic activity in finished products.
- Animal Feed:Spent grain streams and malt co-products repurposed for livestock nutrition. Australian maltsters recover margin from otherwise waste streams by supplying the country's wheat belt cattle operations.
Beverages command the steepest expansion trajectory as regional craft brewing scales. Animal feed is climbing fastest as sustainability mandates pressure zero-waste commitments across malting facilities.
End User:
Procurement sophistication diverges sharply between multinational beverage manufacturers and emerging craft operators.
- Beverage Manufacturers:Large-scale producers of malt-based RTDs, ready-to-serve cereals, and functional drinks. India's FSSAI disclosure requirements are forcing integrated traceability system investments among suppliers serving this tier.
- Food Processors:Industrial bakeries, confectionery manufacturers, and prepared food companies. China's SAMR GB standards compliance costs filter supplier pools to certified operators with third-party laboratory partnerships.
- Breweries:Traditional beer producers spanning multinational lager operations to craft specialists. Vietnam's underpenetrated craft segment consolidates supplier relationships around direct procurement contracts displacing spot-market purchasing.
- Distilleries:Spirits producers utilizing malted grains for whiskey, vodka, and traditional Asian spirits. New Zealand's Canterbury Plains craft distillers pilot precision germination systems for specialty batch consistency.
Beverage manufacturers hold installed capacity through long-term supply agreements. Breweries are rotating up the share rankings as Southeast Asian craft segment procurement scales.
Distribution Channel:
Channel selection reflects order scale, certification documentation requirements, and geographic proximity to malting infrastructure.
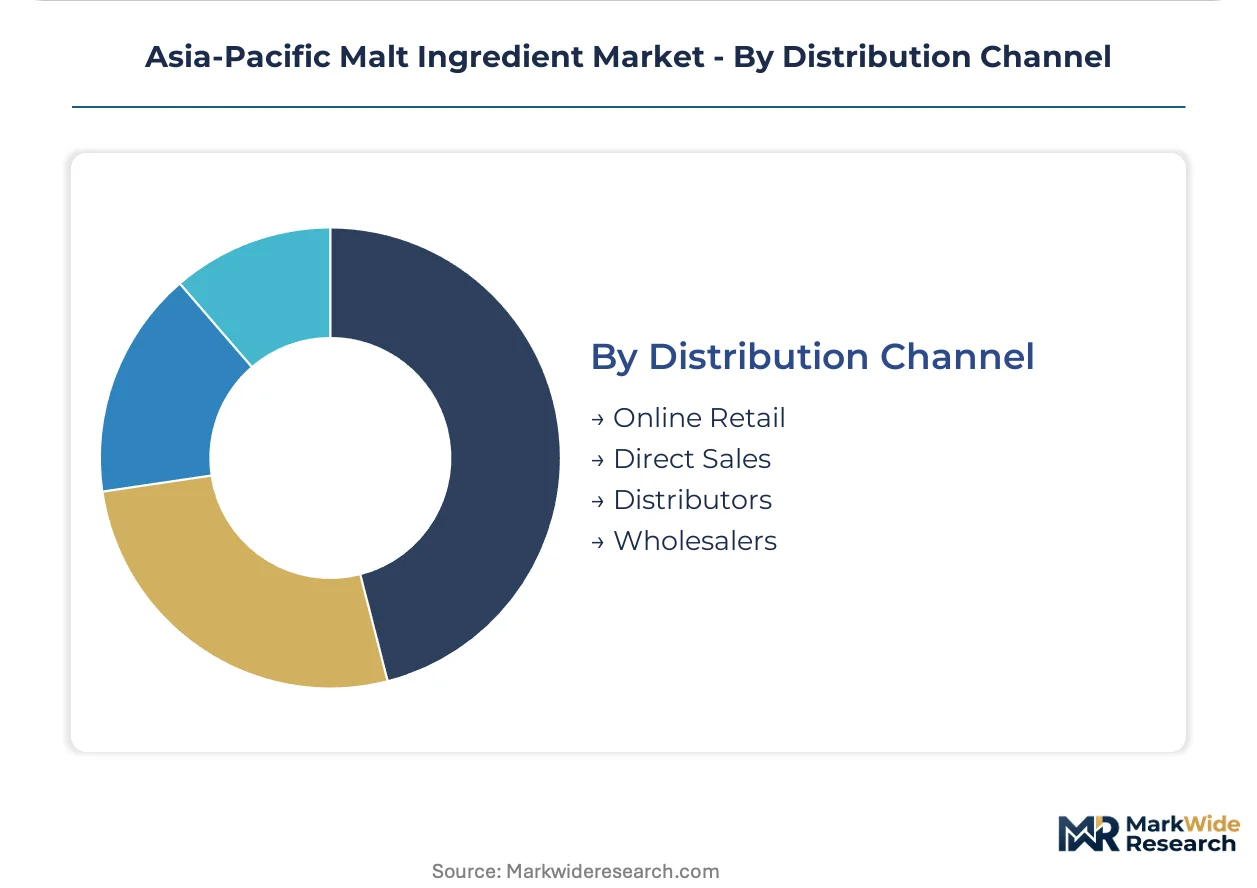
- Direct Sales:Long-term contracts between maltsters and large-volume beverage manufacturers. Malteurop China's domestic plant network eliminates cross-border exposure for Shandong brewing clusters through captive supply relationships.
- Distributors:Regional intermediaries consolidating specialty malt portfolios for craft brewery segments. Australian maltsters leverage distributor networks to reach Southeast Asian markets without direct regulatory compliance investments.
- Wholesalers:Bulk commodity handlers serving commodity-grade malted barley for animal feed and basic baking applications. India's fragmented wholesale channel faces pressure from FSSAI additive disclosure documentation requirements.
- Online Retail:E-commerce platforms enabling small-batch specialty malt access for homebrewers and micro-distilleries. Japanese beverage convergence experiments source experimental wheat malt varieties through specialized online channels.
Direct sales hold installed capacity among multinational beverage manufacturers. Distributors are rotating up the share rankings as Southeast Asian craft brewery procurement consolidates around regional specialty portfolios.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across the Asia-Pacific malt ingredient landscape. China's Shandong Province drives industrial-scale extract demand for mass-market brewing, while Vietnam's emerging craft segment sources specialty roasted varieties for flavor differentiation. Australia's Riverina region supplies fresh liquid malt to premium distilleries prioritizing aromatic intensity over logistics convenience.
China
Shandong Province's integrated malting clusters anchor regional supply for both domestic brewers and export channels, compressing logistics friction through captive infrastructure. SAMR enforces tightened GB standards for mycotoxin surveillance, expanding pre-shipment certification burdens on Australian and New Zealand exporters. Malteurop China's domestic plant network eliminates cross-border raw material exposure for brewing clusters in Qingdao and Jinan.
India
FSSAI fortification mandates for malt-based nutritional products are accelerating certified extract procurement from organized bakery and RTD manufacturers. Tighter additive disclosure requirements compress reformulation timelines and favor suppliers with integrated traceability systems. Maharashtra's industrial corridor concentrates demand from health drink formulators serving urban distribution networks.
Vietnam
Underpenetrated craft beer distribution in Ho Chi Minh City and Hanoi creates first-mover positioning for specialty malt extract suppliers with distinct enzymatic profiles. Brewery technical buyers consolidate supplier relationships around direct procurement contracts displacing spot-market commodity purchasing. The Mekong Delta lacks malting infrastructure, forcing ingredient imports through distributor networks.
Australia
Acute shortages of trained kiln operators and germination specialists across the Riverina and wheat belt regions extend production capacity timelines by 18-24 months. FSANZ moisture threshold requirements for imported malting barley force capital-intensive retrofitting of legacy kiln infrastructure. Cargill leverages its integrated grain origination network to secure barley feedstock across drought-variable growing regions.
Japan
Convergence of traditional sake brewing with malt-based RTD formulations opens formulation partnerships for specialty wheat malt varieties. METI industrial standards govern enzymatic activity certification for beverage applications. Osaka and Tokyo metropolitan areas concentrate experimental procurement through specialized online channels serving beverage convergence projects.
Asia-Pacific Malt Ingredient Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the Asia-Pacific malt ingredient market. Cargill and Malteurop China anchor the upper tier through captive grain origination and domestic plant networks respectively, while mid-scale craft maltsters populate the specialist layer. Three archetypes dominate: integrated agribusiness conglomerates with backward grain control, specialized malt extract formulators serving beverage manufacturers, and regional craft maltsters piloting precision germination systems. Competitive moves concentrate on geographic expansion through domestic plant licensing and portfolio diversification into specialty roasted varieties.
Among Asia-Pacific-based operators, Malteurop China exemplifies the import-substitution archetype through domestic malting infrastructure that reduces cross-border exposure. Muntons PLC represents the specialized formulation tier, with its regional presence anchored in tailored extract development. Cargill occupies the integrated agribusiness position, leveraging upstream grain origination networks across Australian supply basins. These three players collectively illustrate the strategic segmentation between scale-driven commodity supply and precision-formulated specialty extraction.
| Leading Market Players |
|---|
| Rahr Corporation |
| VIVESCIA Group |
| Puremalt Products Ltd. |
| Malteurop China |
| Barrett Burston Malting |
| Muntons PLC |
| Axereal |
| Cargill |
| GrainCorp Group |
| Others |
Value Chain & Pricing Dynamics
China's SAMR GB standards for food-grade malt specifications gate both supplier qualification and price differentiation simultaneously, as certification tiers separate certified extract suppliers from commodity malt handlers while FSSAI disclosure mandates in India create premium pricing bands for traceability-integrated operators.
Pricing Analysis
Long-term offtake contracts dominate procurement between Shandong Province malting clusters and large-scale beverage manufacturers, while spot-market purchasing persists among Vietnam's emerging craft breweries. Price differentiation stems from certification grade against SAMR mycotoxin protocols and volume scale commitments. Cost compression in specialty roasted varieties is intensifying because Australian kiln operator scarcity extends production timelines. Craft distilleries in New Zealand's Canterbury Plains show least price sensitivity due to aromatic freshness premiums, whereas Indian health drink formulators face acute margin pressure from FSSAI reformulation mandates.
Supply Chain Analysis
Inventory lead times stretch 18-24 months for Australian maltsters facing germination specialist shortages across the Riverina and wheat belt regions. Geographic supply concentrates in China's Shandong Province, Australia's wheat belt, and New Zealand's Canterbury Plains. Raw material flows draw from Australian barley origination networks, Indian wheat belt procurement, and Japanese specialty wheat varieties. Single-source vulnerability runs through China's SAMR border detention protocols for mycotoxin non-compliance. Distribution runs through direct sales contracts for multinational beverage manufacturers and regional distributor networks serving Southeast Asian craft segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific malt ingredient procurement is accelerating through a regulatory inflection as India's FSSAI fortification mandates and China's SAMR mycotoxin surveillance compress supplier qualification timelines and reshape competitive positioning.
For Market Incumbents: Shield installed capacity positions in Shandong Province by accelerating backward integration into captive barley origination networks across Australian drought-variable growing regions. Deepen certification investments against evolving SAMR GB standards and FSANZ moisture thresholds to preempt border detention exposure. Consolidate distributor relationships in Vietnam before specialty malt procurement consolidates around direct contracts.
For New Entrants and Emerging Players: FSSAI certification fast-tracks offer entry velocity into India's Maharashtra industrial corridor health drink formulation segment. Target Vietnam's underpenetrated Ho Chi Minh City craft brewing distribution for specialty roasted malt varieties with distinct enzymatic profiles. Leverage precision germination system partnerships as a go-to-market angle to match artisanal consistency with industrial throughput.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated kiln monitoring and IoT-enabled steeping systems as mid-scale craft maltsters retrofit legacy infrastructure. Long-term viability over a 5-10 year window favors operators with integrated grain-to-glass traceability platforms and domestic malting plant networks that eliminate cross-border raw material exposure. Monitor SAMR enforcement frequency against Australian and New Zealand exporters as an inflection indicator for import-substitution tailwinds.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Barley Origination | Cargill leverages Australian wheat belt networks to secure drought-variable feedstock against livestock export competition. |
| Precision Germination System Deployment | Riverina and Canterbury Plains maltsters compress 7-9 day floor cycles into 4-5 day continuous-flow operations. |
| FSSAI Certification Fast-Track Investment | Suppliers with integrated traceability systems capture Maharashtra health drink procurement from reformulating manufacturers. |
| Domestic Malting Plant Licensing | Malteurop China eliminates cross-border exposure for Qingdao and Jinan brewing clusters through captive supply. |
| Specialty Roasted Variety Portfolio Expansion | Vietnam craft breweries in Ho Chi Minh City consolidate supplier relationships around flavor differentiation procurement. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs and trade data, FSSAI regulatory filings, SAMR GB standard documentation, and SEC disclosures from listed agribusiness conglomerates. Primary interviews engaged malting plant managers, procurement leads at Shandong beverage manufacturers, distributor channel partners in Vietnam, and technical R&D directors at Japanese RTD formulators. Bottom-up volume triangulation from malting facility capacity assessments cross-validates against top-down demand aggregation from brewery procurement surveys.
Segmentation dimensions modeled span product type hierarchy, application verticals across beverage and nutritional categories, end-user sophistication tiers, and distribution channel structures across the analysis window. CAGRs derive from regression against macroeconomic indicators and industry-specific inputs including craft brewery formation rates in Southeast Asia and FSSAI fortification compliance timelines. Forecast inputs incorporate kiln retrofitting capital cycles and germination technician training pipeline constraints.
Underlying assumptions cover regulatory enforcement continuity, barley yield variability in Australian growing regions, and craft brewing penetration trajectories in Vietnam, with deviation risk concentrated in SAMR mycotoxin protocol amendments and FSANZ moisture threshold revisions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Global Edible Films and Coatings for Fruits and Vegetables Market
Food Additives and Ingredients
Food Processing Ingredients Market
Food Additives and Ingredients
Pet Food Emulsifier Market
Food Additives and Ingredients
Vinasse Market
Food Additives and Ingredients
Powdered Fats Market
Food Additives and Ingredients
Food Encapsulation Market
Food Additives and Ingredients
Alpha-Linolenic Acid Market
Food Additives and Ingredients
Food Grade Acetic Acid Market
Food Additives and Ingredients
Semi-Finished Pastry Ingredients Market
Food Additives and Ingredients
Pea Starch Concentrate Market
Food Additives and Ingredients
North America Food Preservatives Market
Food Additives and Ingredients
United Kingdom Food Emulsifier Market
Food Additives and Ingredients
Non-GMO Citric Acid Market
Food Additives and Ingredients
Food Fungal Enzyme Market
Food Additives and Ingredients
Global Canthaxanthin Market
Food Additives and Ingredients
Neohesperidin Market