
 South America Anti Caking Market | 2026-2036
South America Anti Caking Market Size, Share, and Industry Trends Forecast 2026-2036
South America Anti Caking Market Analytics
The premium anti-caking additive tier is consolidating around specialized silicon dioxide grades for hygroscopic pharmaceutical actives, while commodity calcium carbonate blends face price compression from regional bulk chemical suppliers. BASF SE leverages its technical service network to sustain formulation partnerships with multinational food manufacturers across São Paulo state. Cargill Inc. anchors its position through backward integration into agricultural-derived carrier materials for fertilizer applications. J.M. Huber Corp. competes on mineral purity specifications for high-humidity Latin American storage conditions.
Anti-caking agents are functional additives—typically inorganic salts, silicates, or modified starches applied at 0.1–2.0% w/w—that interrupt crystal bridge formation between hygroscopic particles through moisture absorption or physical barrier mechanisms. Their primary purpose is preserving free-flow characteristics in powdered and granulated products during manufacturing, transport, and shelf storage. Silicon dioxide variants command margin premiums in pharmaceutical applications where USP-NF purity grades prevent degradation of moisture-sensitive APIs. Calcium carbonate dominates agricultural volume due to its dual role as both anti-caking aid and soil pH modifier in compound fertilizers. Talc retains niche positioning in cosmetic powder formulations where lubricity and skin-feel properties outweigh cost considerations.
ANVISA governs food-grade anti-caking authorization through positive list mechanisms, while Brazil's Ministry of Agriculture enforces residue thresholds for agricultural chemical formulations. Argentina's national food safety authority aligns Mercosur additive harmonization with domestic pharmaceutical GMP standards. Peru and Chile apply REACH-inspired chemical registration frameworks that extend approval timelines for imported silicon dioxide grades. Stakeholders must monitor regulatory divergence between Mercosur harmonization efforts and country-specific pharmaceutical purity mandates.
Market Dynamics
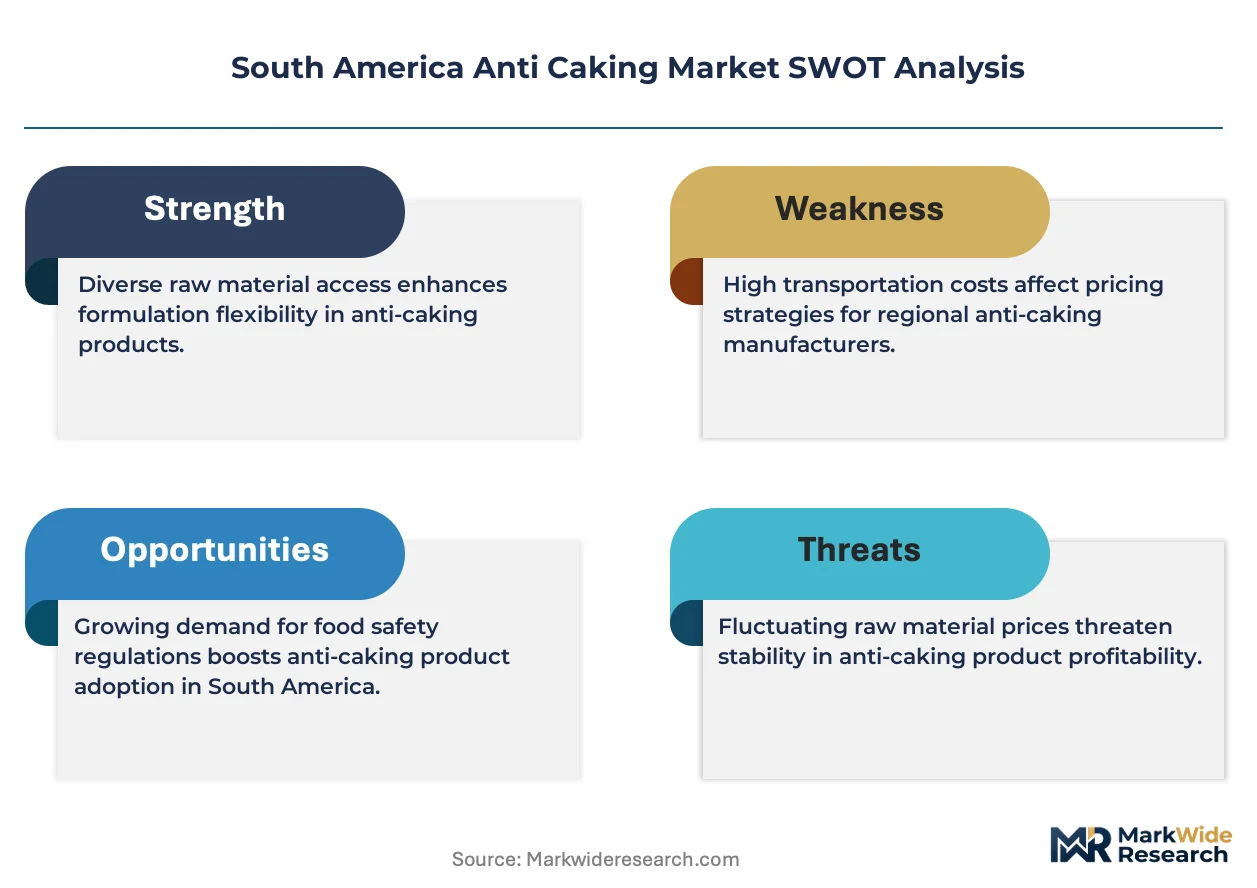
ANVISA's tightening purity mandates for food-grade silicon dioxide are compressing formulation windows for multinational manufacturers operating across Brazil's southeastern industrial corridor.
Growth Catalysts
- Fertilizer sector expansion:Brazil's agricultural ministry reports rising compound fertilizer output driving calcium carbonate anti-caking consumption in Mato Grosso and Paraná production zones.
- REACH-inspired registration frameworks:Peru and Chile have extended chemical approval timelines for imported silicon dioxide, creating captive demand for locally tested grades.
- Pharmaceutical storage requirements:High-humidity conditions across Amazon basin distribution networks necessitate specialized hygroscopic particle management in API formulations.
Market Restraints
- Input cost volatility:Natural gas price fluctuations directly impact precipitated silica production economics for Brazilian silicon dioxide manufacturers.
- Supply concentration risk:Argentina's fertilizer additive supply depends heavily on Mercosur cross-border chemical flows subject to customs harmonization delays.
- Technical limitation:Calcium carbonate efficacy degrades above 75% relative humidity, restricting deployment in coastal Brazilian storage facilities without climate control.
Strategic Opportunities
- Underpenetrated geography:Colombia's emerging processed food sector lacks dedicated anti-caking technical service infrastructure present in São Paulo state.
- Regulatory tailwind:Mercosur additive harmonization protocols may streamline multi-country registration for compliant silicon dioxide grades.
- Technology convergence:Combination of modified starches with mineral carriers is opening dual-function formulations for humidity-variable fertilizer applications.
Industry Challenges
- Certification timeline compression:ANVISA's evolving positive list mechanisms require reformulation cycles that outpace standard product development schedules.
- Capex intensity for purity upgrades:USP-NF grade silicon dioxide production demands filtration infrastructure investments exceeding mid-tier processor capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Anti Caking Market |
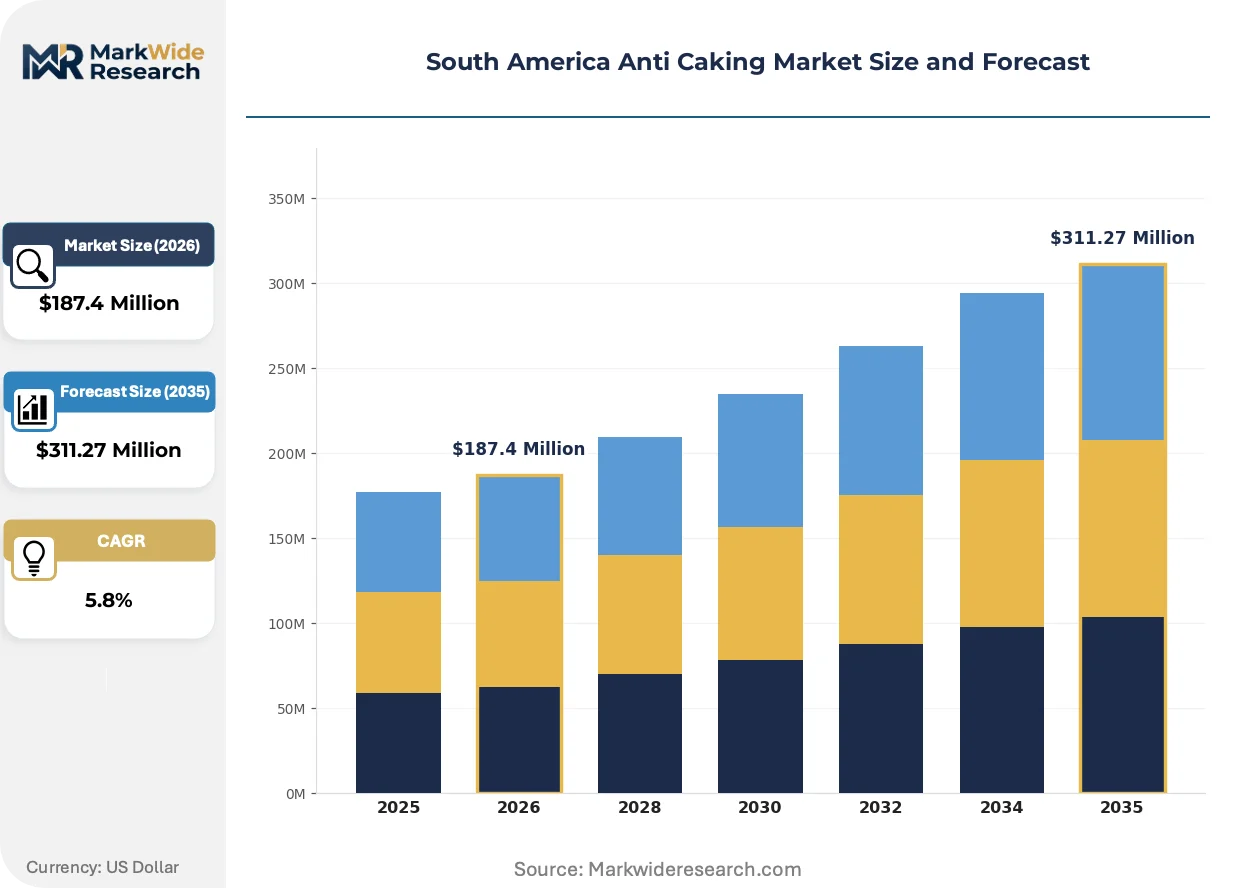
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Food Processing, Pharmaceuticals, Agriculture, Chemicals Type: Calcium Carbonate, Silicon Dioxide, Talc, Magnesium Carbonate End User: Food Manufacturers, Cosmetic Companies, Fertilizer Producers, Pharmaceutical Firms Form: Powder, Granule, Pellet, Solution |
| Companies Covered | Brasilminas, Chemipol S.A., Sasol Wax, Fuji Chemicals Industries, Roquette Frères, Kao Corporation, BASF SE, Cargill Inc., J.M. Huber Corp., Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Anti Caking Market Evolving Landscape
Formulation science is pivoting toward multi-functional additives that combine flow assurance with nutritional or pH-modifying properties, collapsing separate additive categories into single-ingredient solutions.
Surface-modified silicon dioxide variants with enhanced moisture absorption capacity are electrifying pharmaceutical packaging specifications across Brazil's generic drug manufacturing sector. São Paulo-based formulators are adopting these grades at accelerated rates to meet ANVISA stability requirements for moisture-sensitive APIs. This electrifying shift is compressing demand for conventional uncoated silica carriers in premium therapeutic categories.
ANVISA's 2023 update to food additive positive list mechanisms has narrowed authorized silicon dioxide particle size distributions for direct food contact applications. Manufacturers now face reformulation costs to source compliant grades or shift toward alternative silicates. Brazil's dairy powder and seasoning blend sectors are most affected, with larger processors accelerating supplier qualification timelines.
Buyer concentration among Brazilian multinational food manufacturers is compressing procurement cycles and demanding extended technical service commitments from additive suppliers. Mid-sized regional processors are being displaced from preferred vendor status as volume thresholds rise. This pattern is most visible in São Paulo state's condensed milk and instant beverage manufacturing clusters.
South America Anti Caking Market Segmentation
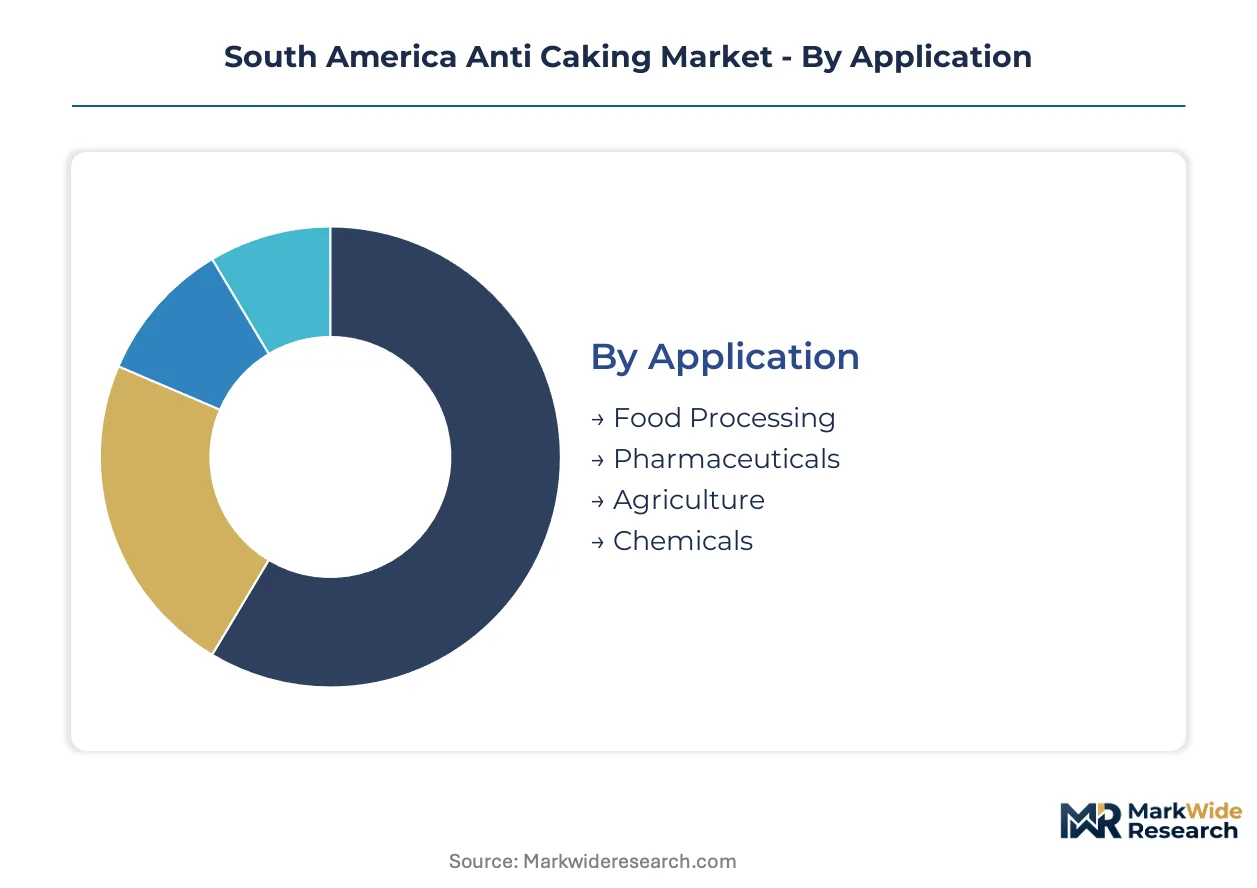
Anti-caking agent procurement patterns diverge sharply across South American end-use sectors. Pharmaceutical and fertilizer buyers prioritize mineral purity certifications, while food processors weigh cost against ANVISA compliance timelines.
Application:
Formulators select anti-caking chemistry based on moisture sensitivity of the host powder and regulatory pathway complexity.
- Food Processing:ANVISA's positive list mechanisms restrict silicon dioxide particle sizes for dairy powders and seasoning blends. Brazilian condensed milk manufacturers in São Paulo state drive specification tightening.
- Pharmaceuticals:USP-NF grade silicon dioxide prevents API degradation in high-humidity Amazon basin distribution networks. Generic drug manufacturers absorb margin premiums for stability assurance.
- Agriculture:Calcium carbonate serves dual function as anti-caking aid and soil pH modifier in Mato Grosso fertilizer compounds.
- Chemicals:Industrial salt and pigment processors apply modified starches for humidity-variable storage conditions.
Volume sits with Agriculture; growth tilts toward Pharmaceuticals.
Type:
Raw material sourcing economics and purification infrastructure requirements separate premium mineral grades from commodity alternatives.
- Calcium Carbonate:Abundant regional limestone deposits support fertilizer sector scale. Efficacy degrades above 75% relative humidity, limiting coastal Brazilian deployment without climate control.
- Silicon Dioxide:Precipitated silica production depends on natural gas pricing volatility. USP-NF filtration investments exceed mid-tier processor capacity.
- Talc:Cosmetic powder formulators in Brazil prioritize lubricity and skin-feel over cost optimization.
- Magnesium Carbonate:Niche positioning in pharmaceutical tablet formulations where alkalinity buffers acid-labile actives.
Calcium Carbonate dominates tonnage; Silicon Dioxide captures margin expansion.
End User:
Procurement scale and technical service demands stratify supplier relationships across buyer categories.
- Food Manufacturers:Multinational processors in São Paulo's instant beverage clusters compress supplier qualification timelines. Volume thresholds displace mid-sized regional vendors.
- Cosmetic Companies:Talc specifications prioritize particle morphology for pressed powder applications. Brazilian personal care brands source through specialized mineral distributors.
- Fertilizer Producers:Backward integration into agricultural-derived carriers anchors supply security for Paraná compound fertilizer operations.
- Pharmaceutical Firms:ANVISA stability requirements for moisture-sensitive APIs accelerate adoption of surface-modified silicon dioxide grades.
Fertilizer Producers anchor volume; Pharmaceutical Firms drive specification upgrades.
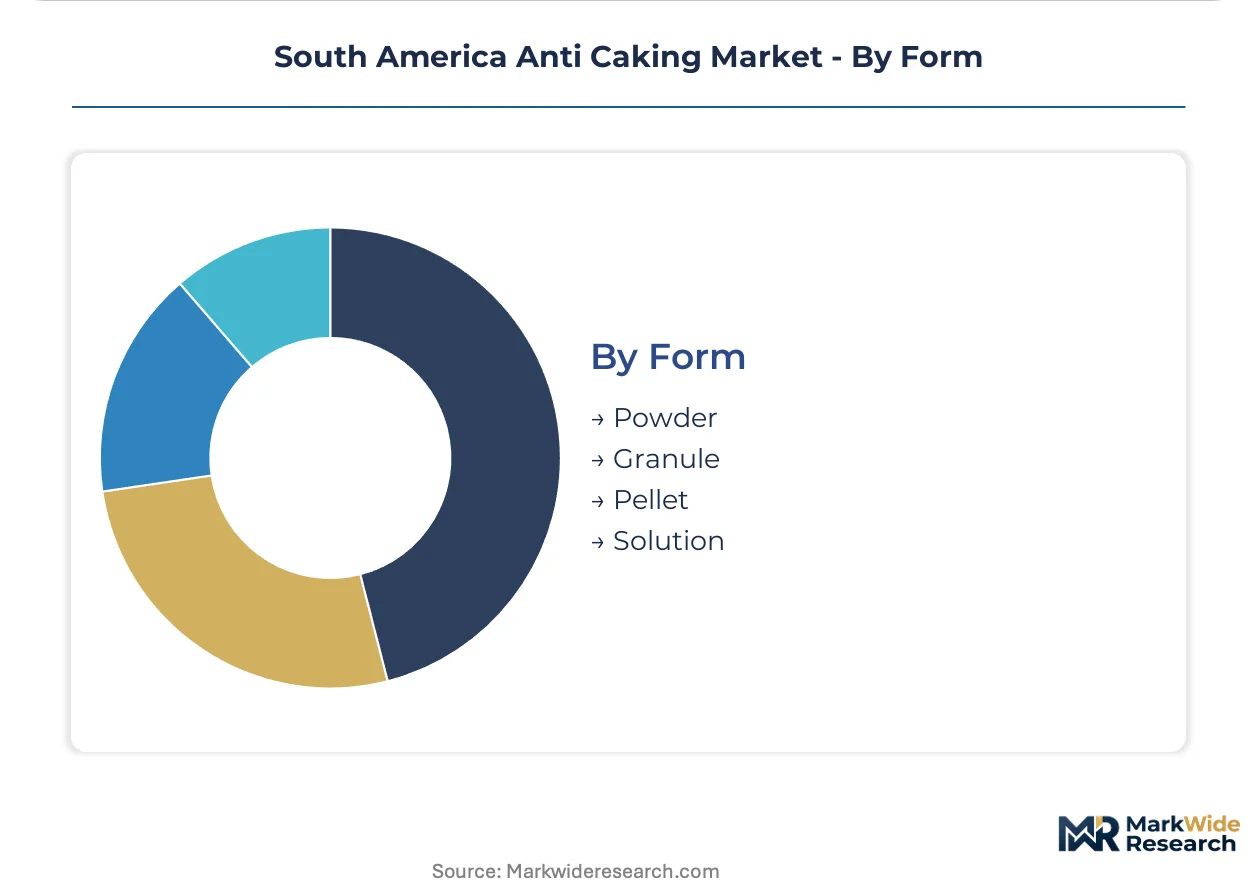
Form:
Physical state determines dosing precision, dust exposure, and compatibility with existing manufacturing equipment.
- Powder:Standard format for high-shear blending operations. Dust control requirements intensify in pharmaceutical cleanroom environments.
- Granule:Reduced dusting suits agricultural bulk handling. Flowability optimization targets pneumatic conveyor compatibility.
- Pellet:Controlled dissolution rates for slow-release fertilizer applications. Compression strength withstands mechanized spreading equipment.
- Solution:Liquid application systems for continuous spray coating of hygroscopic crystals. Concentrated formulations reduce shipping costs.
Powder commands installed base; Granule gains share in agricultural mechanization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo's southeastern manufacturing corridor concentrates South American anti-caking demand through its dairy powder, instant beverage, and pharmaceutical formulation clusters. ANVISA's regulatory gravity pulls technical service infrastructure toward this industrial axis.
Brazil
Mato Grosso and Paraná fertilizer compounds drive calcium carbonate consumption for dual-function pH modification. ANVISA's evolving positive list mechanisms for food-grade silicon dioxide compress formulation windows for multinational manufacturers. São Paulo state's condensed milk processors absorb margin premiums for compliant particle size specifications.
Argentina
Buenos Aires-based pharmaceutical formulators source USP-NF grade silicon dioxide for moisture-sensitive API stability. The national food safety authority aligns Mercosur additive harmonization with domestic pharmaceutical GMP standards. Rosario's agricultural chemical corridor depends on cross-border Mercosur chemical flows for fertilizer additive supply security.
Chile
REACH-inspired chemical registration frameworks extend approval timelines for imported silicon dioxide grades, creating captive demand for locally tested alternatives. The mining sector's industrial salt processors apply modified starches for humidity-variable Atacama storage conditions. Santiago's chemical distribution networks prioritize pneumatic conveyor-compatible granule formats.
Colombia
Bogotá's emerging processed food sector lacks dedicated anti-caking technical service infrastructure present in São Paulo. Modified starch combinations with mineral carriers are penetrating humidity-variable fertilizer applications in the eastern plains agricultural zones. Medellín's personal care manufacturers source talc through specialized mineral distributors for pressed powder formulations.
Peru
Lima's pharmaceutical packaging specifications are electrifying toward surface-modified silicon dioxide variants with enhanced moisture absorption capacity. The country's chemical registration framework mirrors Chile's REACH-inspired approval timelines for imported grades. Coastal storage facilities face calcium carbonate efficacy degradation above 75% relative humidity without climate control investment.
South America Anti Caking Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-grade and technical-service dimensions in South American anti-caking supply. BASF SE and Cargill Inc. anchor the upper tier through formulation partnerships and backward integration into agricultural-derived carriers. The market structures around three archetypes: multinational chemical conglomerates with technical service networks, agricultural processors with captive mineral sourcing, and regional mineral specialists with purity specifications. Dominant competitive moves include supplier qualification timeline acceleration and filtration infrastructure investment for USP-NF grade production.
Within the multinational chemical tier, BASF SE and Cargill Inc. exemplify divergent strategic anchoring—BASF through technical service depth across São Paulo state food manufacturers, Cargill through upstream control over agricultural-derived carrier materials for fertilizer applications. J.M. Huber Corp. occupies a position among mineral purity specialists competing on specifications for high-humidity Latin American storage conditions. Brasilminas and Chemipol S.A. represent regional supply-side anchors with geographic proximity to Brazilian and Argentine demand clusters respectively.
| Leading Market Players |
|---|
| Brasilminas |
| Chemipol S.A. |
| Sasol Wax |
| Fuji Chemicals Industries |
| Roquette Frères |
| Kao Corporation |
| BASF SE |
| Cargill Inc. |
| J.M. Huber Corp. |
| Others |
Value Network & Pricing Analysis
Natural gas pricing volatility cascades through precipitated silica production economics in Brazil, compressing margins for domestic silicon dioxide manufacturers while amplifying premium tiers for USP-NF grade imports that fertilizer and pharmaceutical buyers absorb downstream.
Pricing Analysis
Yield-based pricing anchors premium silicon dioxide tiers to API stability outcomes in pharmaceutical applications, separating certified grades from commodity alternatives. Three-tier pricing structure across premium, standard, and economy levels stratifies by mineral purity certification and technical service bundling. Cost compression in calcium carbonate runs through regional bulk chemical suppliers flooding fertilizer markets. Agricultural processors exhibit highest price sensitivity, while generic drug manufacturers absorb margin premiums for ANVISA-compliant moisture management.
Supply Chain Analysis
Direct-to-fertilizer-producer channels handle bulk calcium carbonate demand in Mato Grosso and Paraná, bypassing distributor markups for compound fertilizer operations. Distribution runs through São Paulo's southeastern manufacturing corridor for food-grade silicon dioxide serving dairy powder and instant beverage clusters. Raw material sourcing draws from regional limestone deposits, imported precipitated silica feedstocks, and specialized talc morphologies. Mercosur cross-border chemical flows concentrate supply risk for Argentina's Rosario agricultural corridor through customs harmonization delays.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ANVISA's tightening purity mandates and certification timeline compression are forcing mid-tier processors toward exit or acquisition, consolidating vendor relationships around filtration-capable suppliers.
For Market Incumbents: Lock in formulation partnerships with multinational food manufacturers through extended technical service commitments and accelerated supplier qualification timelines. Backward integration into agricultural-derived carrier materials secures supply anchors for Paraná fertilizer compounds against Mercosur flow disruptions. Surface-modified silicon dioxide R&D investment defends position against generic silica commoditization in pharmaceutical applications. For New Entrants and Emerging Players: Specialized mineral distributors in Colombia's Bogotá processed food corridor offer channel access without São Paulo infrastructure investment. Humidity-variable fertilizer applications in Colombia's eastern plains present the most penetrable white-space for modified starch-mineral carrier combinations. Technical service partnerships with regional processors bypass volume thresholds that exclude mid-sized vendors from Brazilian multinational procurement. For Investors and Strategic Acquirers: Distressed-cycle entries favor USP-NF filtration-capable processors in Brazil's southeastern corridor where capex intensity exceeds mid-tier capacity. Long-term viability centers on regulatory compliance infrastructure rather than commodity scale. Watch ANVISA positive list expansion velocity as inflection indicator for reformulation demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| USP-NF Filtration Infrastructure Investment | Captures pharmaceutical margin premiums in São Paulo generic drug manufacturing. |
| Backward Integration into Agricultural Carriers | Secures supply for Paraná fertilizer compounds amid Mercosur flow uncertainty. |
| Surface-Modified Silica R&D Partnership | Addresses ANVISA stability requirements for moisture-sensitive API formulations. |
| Technical Service Network Expansion | Penetrates Colombia's underdeveloped processed food additive infrastructure. |
| Modified Starch-Mineral Carrier Joint Venture | Opens dual-function formulations for humidity-variable fertilizer applications. |
Research Methodology
Document review covered ANVISA regulatory filings, Brazilian Ministry of Agriculture fertilizer output reports, and Mercosur additive harmonization protocols, complemented by interviews with plant managers at calcium carbonate processors, procurement leads at São Paulo dairy powder manufacturers, technical R&D directors at silicon dioxide suppliers, and regulatory affairs specialists navigating REACH-inspired frameworks in Peru and Chile. Secondary validation drew from customs trade data, SEC filings of multinational additive suppliers, and pharmaceutical GMP inspection records. Bottom-up volume modeling triangulated against top-down market sizing across application segments.
Historical consumption patterns cross-referenced with panel input from fertilizer sector procurement officers and pharmaceutical formulators anchored growth trajectory assumptions across the analysis window. Segmentation dimensions modeled include mineral grade tier, end-use application, regulatory compliance pathway, and regional production hub concentration. CAGRs derived from elasticity-adjusted demand curves incorporating natural gas price sensitivity for precipitated silica and limestone availability indices for calcium carbonate.
Caveats apply where ANVISA positive list revisions or Mercosur customs harmonization delays could materially shift the outlook for imported silicon dioxide grades. Forecasts embed assumptions regarding fertilizer sector expansion rates and pharmaceutical humidity management specification evolution. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Argentina Sodium Reduction Ingredient Market
Food Additives and Ingredients
Natural Ferulic Acid Market
Food Additives and Ingredients
Lycopene Food Colors Market
Food Additives and Ingredients
Food Grade Ammonium Carbonate Market
Food Additives and Ingredients
Australia Food Colorants Market
Food Additives and Ingredients
Food Inclusions Market
Food Additives and Ingredients
Resistant Dextrin Market
Food Additives and Ingredients
Microencapsulated Food Ingredient Market
Food Additives and Ingredients
Africa Food Additives Market
Food Additives and Ingredients
Isodecanol Market
Food Additives and Ingredients
Non-GMO Citric Acid Market
Food Additives and Ingredients
Mexico Food Additives Market
Food Additives and Ingredients
Salt Substitutes Market
Food Additives and Ingredients
South America Food Preservatives Market
Food Additives and Ingredients
Egypt Food Enzymes Market
Food Additives and Ingredients
South America Food Emulsifiers Market