
 Africa Food Stabilizers Market | 2026-2036
Africa Food Stabilizers Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Food Stabilizers Market Outlook
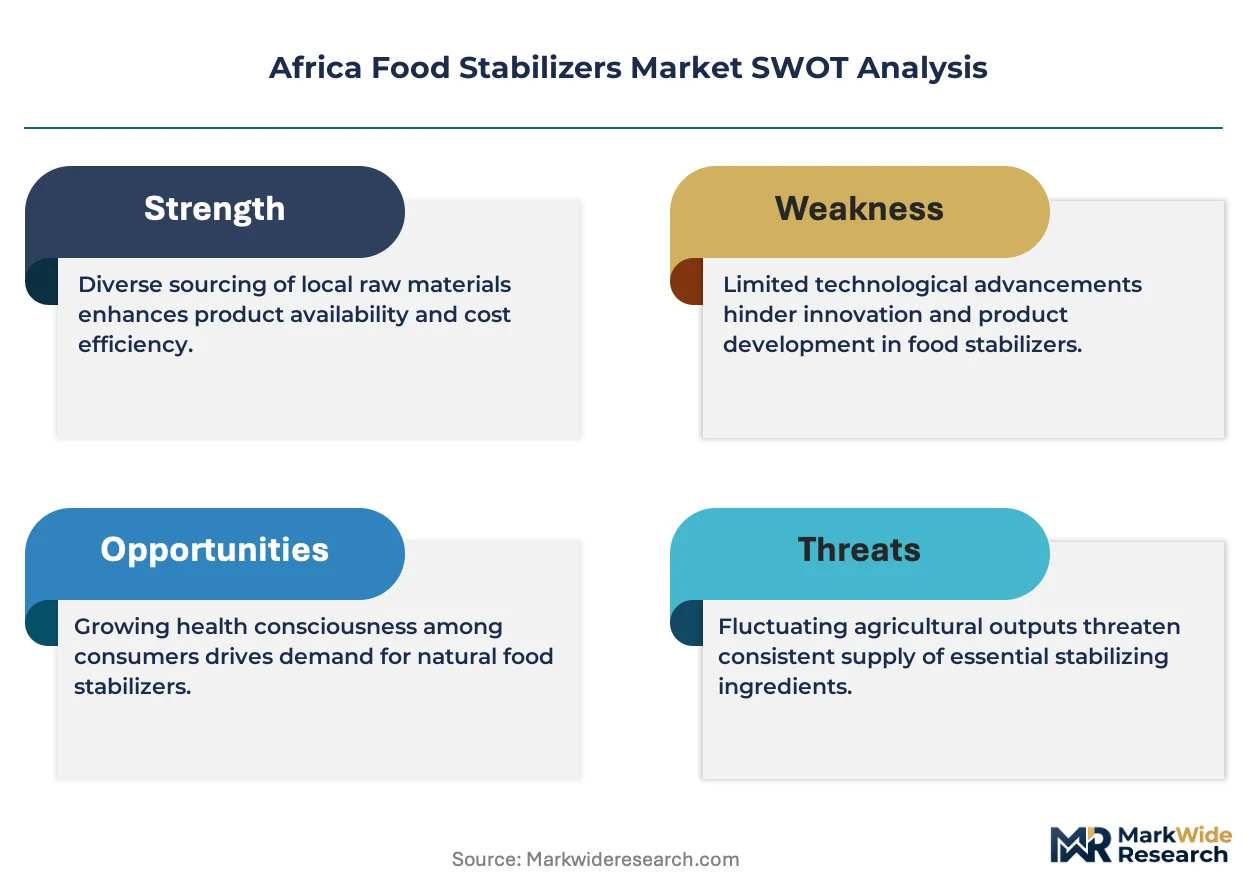
Buyer concentration among African dairy processors and beverage bottlers is expanding as mid-sized manufacturers scale pasteurized and UHT production. Palsgaard A/S leverages its emulsifier-blend expertise to supply industrial cheese and ice cream makers across East Africa. Cargill anchors its position through regional distribution hubs serving Nigerian and Kenyan food manufacturers. BASF SE competes on modified starch and hydrocolloid portfolios tailored to tropical climate stability requirements.
Food stabilizers comprise hydrocolloids, emulsifiers, and gelling agents that control water mobility, prevent syneresis, and maintain viscosity in processed foods under thermal stress and freeze-thaw cycles, typically functioning at concentrations between 0.1% and 2.0% by weight. Thickeners dominate current volume demand in sauces and ready-to-drink beverages where mouthfeel consistency commands formulation priority. Emulsifiers represent the fastest-growing product category as African dairy processors adopt shelf-life extension for ambient distribution. Gelling agents capture concentrated margin pools in confectionery and specialized bakery applications where texture precision justifies premium positioning.
South Africa's Department of Health enforces food additive standards aligned with Codex Alimentarius, while Nigeria's National Agency for Food and Drug Administration and Control monitors import compliance for hydrocolloid raw materials. Kenya's Bureau of Standards certifies stabilizer purity grades for dairy sector procurement. Stakeholders must track evolving national registration requirements as harmonized standards develop across the African Continental Free Trade Area implementation zones.
Market Dynamics
Food stabilizer procurement across Africa is consolidating around FSSAI-aligned safety protocols, with Nigeria's NAFDAC and Kenya's Bureau of Standards tightening additive approval pathways and forcing reformulation investments from dairy processors scaling pasteurized production.
Growth Catalysts
- UHT Dairy Expansion:Nigerian and Kenyan processors are retrofitting lines for ambient distribution, creating pull for emulsifier systems that withstand thermal stress and freeze-thaw cycles without syneresis.
- West African Beverage Corridors:Ready-to-drink formulation demand in Lagos and Accra is accelerating hydrocolloid adoption for mouthfeel consistency in tropical storage conditions.
- Codex Harmonization:South Africa's Department of Health alignment with Codex Alimentarius standards is reducing technical barriers for stabilizer imports across Southern African Customs Union members.
Market Restraints
- Import-Dependent Hydrocolloid Supply:Guar gum and locust bean gum raw material sourcing concentrates in South Asian processing hubs, exposing African formulators to currency volatility and shipping disruptions.
- Technical Limitation of Native Starches:Unmodified cassava and maize starches fail under tropical climate stability requirements, forcing reliance on premium modified starch imports that compress processor margins.
- Regulatory Fragmentation:Divergent national registration requirements across African Continental Free Trade Area implementation zones create compliance duplication costs for multi-market suppliers.
Strategic Opportunities
- Ethiopian Dairy Greenfield:Underpenetrated pasteurized milk processing capacity in Addis Ababa and Dire Dawa offers first-mover positioning for stabilizer suppliers establishing local technical service presence.
- Clean-Label Hydrocolloid Blends:Consumer preference shifts in South African retail channels are creating demand for pectin-locust bean gum systems that replace synthetic emulsifiers in premium ice cream.
- Regional Distribution Hub Consolidation:East African logistics corridors through Mombasa and Dar es Salaam enable single-point supply to Kenyan, Tanzanian, and Rwandan processors seeking reduced lead times.
Industry Challenges
- Food Technologist Scarcity:Formulation expertise for hydrocolloid-protein interactions in UHT dairy remains concentrated in South African and Nigerian technical centers, constraining replication speed in secondary markets.
- Certification Timeline Compression:NAFDAC's tightened purity grade documentation requirements for hydrocolloid raw materials are extending procurement cycles for mid-sized manufacturers without dedicated regulatory affairs functions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Food Stabilizers Market |
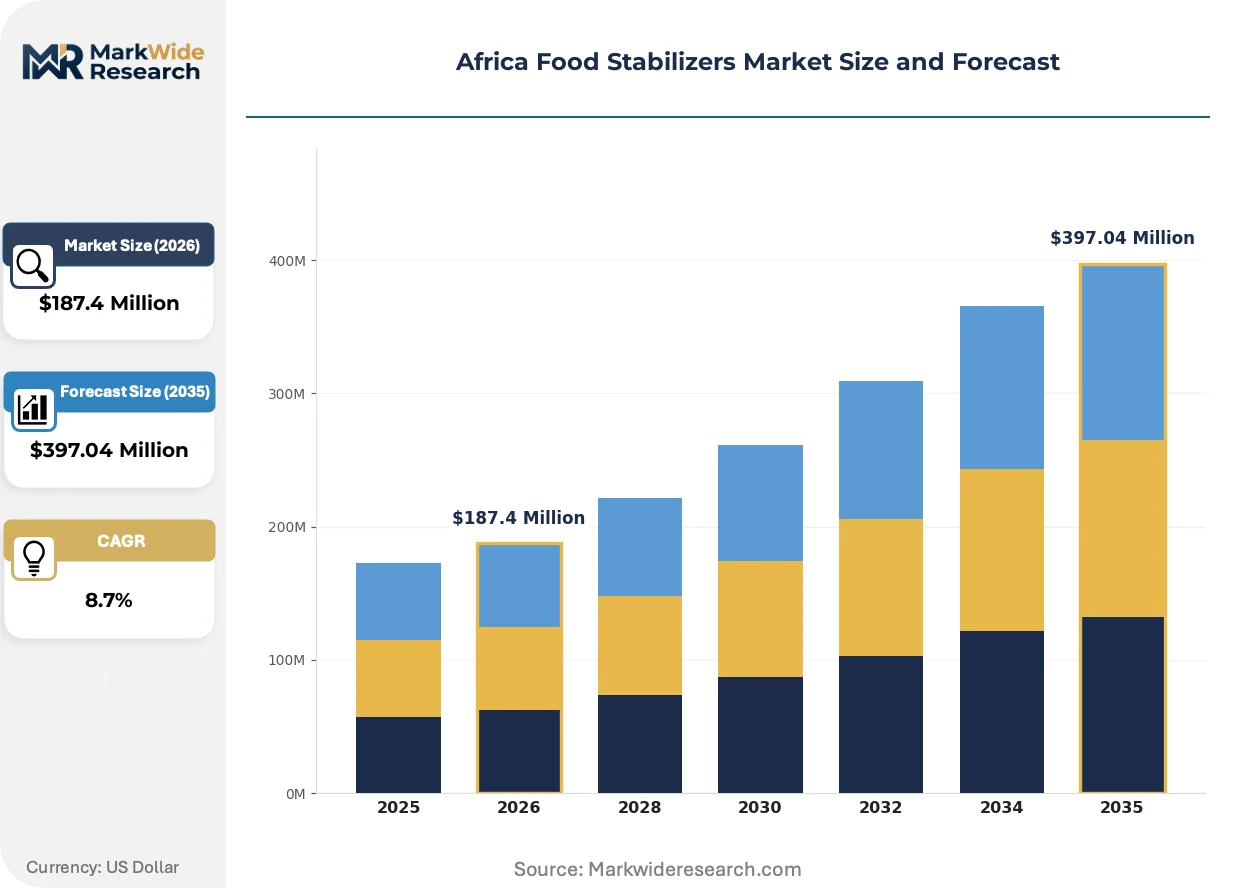
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsifiers, Gelling Agents, Thickeners, Stabilizers Application: Dairy Products, Bakery Goods, Sauces, Beverages End User: Food Manufacturers, Restaurants, Retailers, Food Service Providers Form: Powder, Liquid, Gel, Granules |
| Companies Covered | BASF SE, Tate & Lyle PLC, Barentz International BV, Palsgaard A/S, Kayo Fine Chemicals, Hydrosol GmbH & Co KG, Cape Food Ingredients, Omnia Group (Protea Chemicals), Cargill, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Food Stabilizers Market Strategic Shifts
Stabilizer technology deployment across African food manufacturing is pivoting from commodity thickener sourcing toward integrated texture systems that address tropical climate stability and clean-label positioning simultaneously.
Dual-function hydrocolloid-emulsifier complexes are modularizing formulation workflows for Nigerian dairy processors. Palsgaard A/S and regional distributors supply pre-blended systems that eliminate in-house compounding steps. This modularizing architecture compresses technical onboarding timelines from months to weeks for mid-sized cheese and ice cream manufacturers entering UHT segments.
Kenya's Bureau of Standards certification requirements for stabilizer purity grades are tightening procurement specifications for dairy sector buyers. Industrial consequence includes mandatory third-party testing documentation for hydrocolloid imports. East African processors are responding by consolidating supplier relationships with distributors offering bundled compliance packages.
Direct technical service engagement is displacing traditional broker-mediated procurement in West African beverage corridors. Lagos-based formulators now expect on-site viscosity profiling and shelf-life modeling from stabilizer suppliers. This pattern concentrates most visibly among Nigerian ready-to-drink juice processors scaling tetra-pak lines for ambient distribution.
Africa Food Stabilizers Market Segmentation
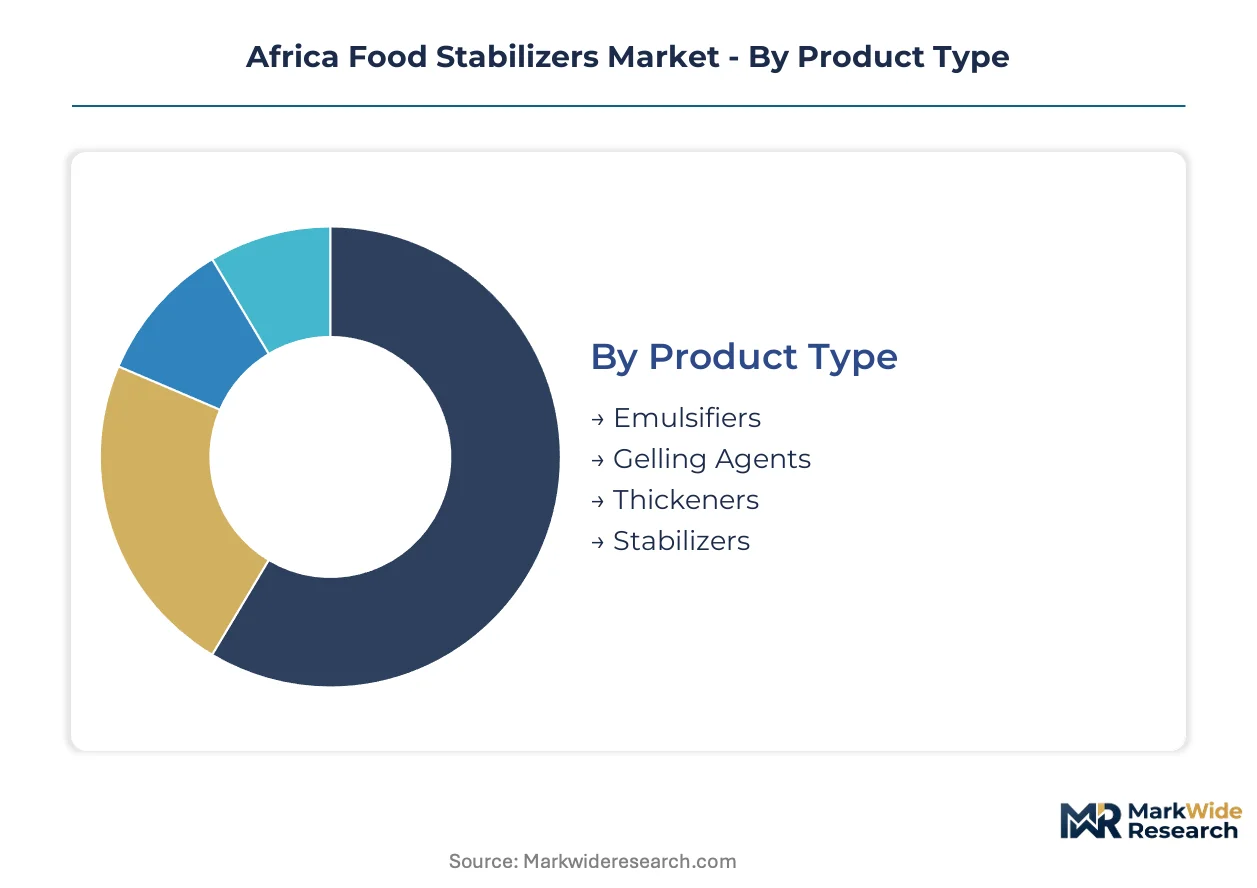
Segmentation reveals how stabilizer functionality maps to distinct processing environments across African food manufacturing. Procurement patterns diverge sharply between integrated dairy processors seeking complete texture systems and standalone ingredient buyers serving fragmented bakery and foodservice channels.
Product Type:
Integration depth varies substantially: emulsifiers and hydrocolloid stabilizers typically embed in pre-blended systems supplied to large processors, while gelling agents and thickeners often move as standalone ingredients for smaller manufacturers.
- Emulsifiers:Lecithin and mono-diglyceride systems control fat-water interfaces in UHT dairy and ambient beverages. Nigerian processors retrofitting tetra-pak lines for Lagos and Abuja distribution are accelerating procurement of heat-stable emulsifier complexes.
- Gelling Agents:Pectin, agar, and carrageenan establish firm-set textures in confectionery and specialized bakery applications. Premium ice cream manufacturers in South African retail channels are shifting toward pectin-locust bean gum systems to replace synthetic alternatives.
- Thickeners:Guar gum and xanthan gum dominate sauces and ready-to-drink beverages where mouthfeel consistency commands formulation priority under tropical storage stress.
- Stabilizers:Hydrocolloid blends prevent syneresis and control water mobility across freeze-thaw cycles in processed cheese and frozen desserts.
Thickeners lead volumes today; emulsifiers are gaining share fastest.
Application:
Cost tier stratification separates commodity sauce applications from premium dairy and beverage segments where technical service bundling justifies supplier margin.
- Dairy Products:Pasteurized milk, UHT cream, and ice cream formulations demand hydrocolloid-protein interaction expertise. Kenyan processors scaling production face food technologist scarcity that concentrates procurement among suppliers offering on-site viscosity profiling.
- Beverages:Ready-to-drink juices and dairy-based drinks in Lagos and Accra corridors require tropical-climate stability systems. Direct technical service engagement is displacing broker-mediated procurement as formulators expect shelf-life modeling support.
- Bakery Goods:Bread improvers and cake emulsifiers represent volume applications with thinner margins and less supplier differentiation.
- Sauces:Tomato-based and mayonnaise systems utilize xanthan and guar gum thickeners for viscosity control in ambient distribution.
Dairy products anchor procurement value; beverages show the steepest expansion trajectory.
End User:
Customer type determines procurement channel structure: large food manufacturers consolidate around technical partnerships while restaurants and foodservice buy through distributor intermediaries.
- Food Manufacturers:Industrial dairy and beverage processors in Nigeria, Kenya, and South Africa drive specification-grade stabilizer demand. These buyers consolidate supplier relationships to capture bundled compliance packages for purity grade documentation.
- Food Service Providers:Institutional caterers and quick-service chains utilize pre-blended stabilizer systems for consistency across distributed kitchen networks.
- Restaurants:Independent and chain restaurants represent fragmented demand for small-format ingredient packaging.
- Retailers:Private-label food producers and ingredient resellers serve secondary markets with limited technical specification requirements.
Food manufacturers dominate absolute consumption; food service providers are expanding procurement most quickly.
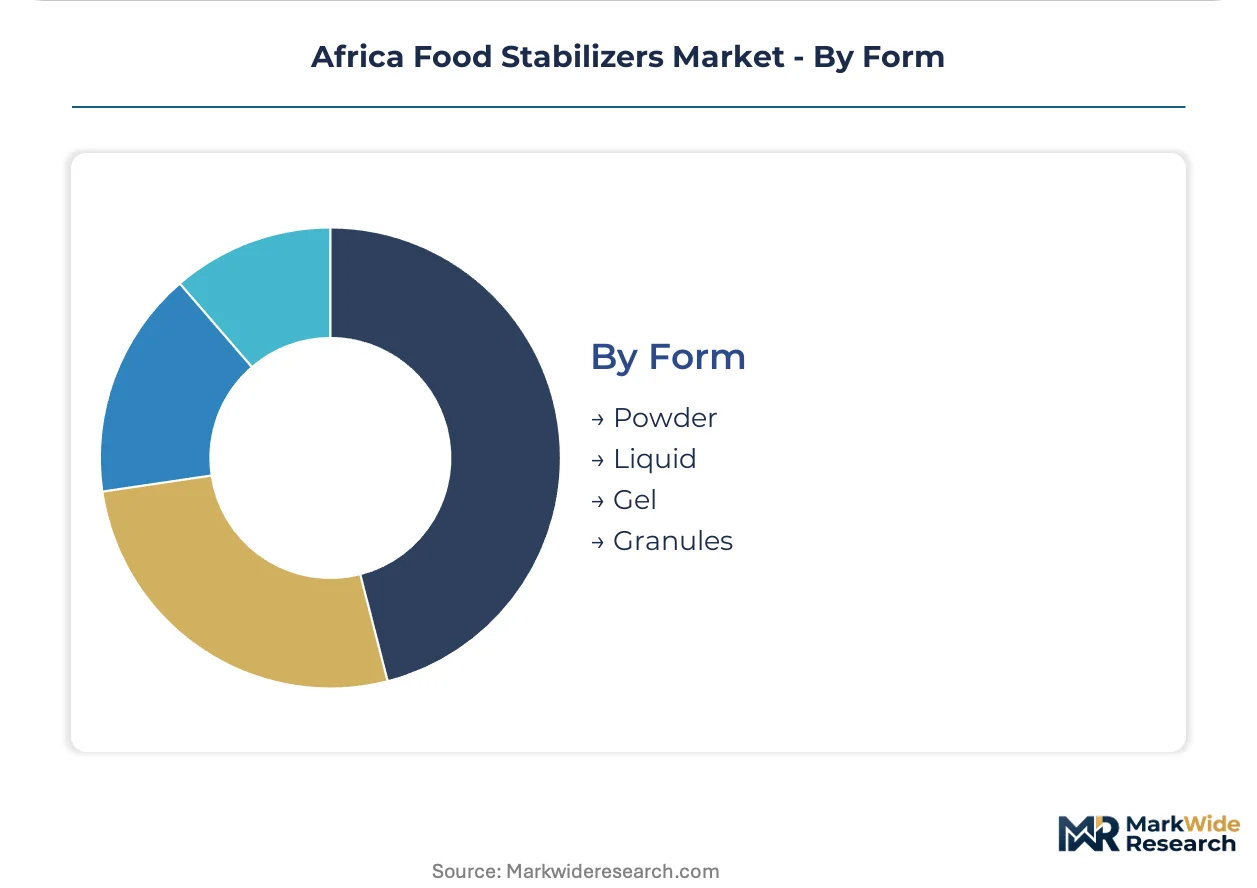
Form:
Supply concentration favors powder formats for shipping economics, though liquid and gel systems reduce handling steps for specific high-volume processors.
- Powder:Standard format for hydrocolloids and emulsifier blends enables tropical climate storage and containerized import through Mombasa and Lagos ports.
- Liquid:Pre-hydrated emulsifier dispersions eliminate compounding steps for mid-sized cheese and ice cream manufacturers entering UHT segments.
- Gel:Concentrated pectin and carrageenan preparations serve confectionery specialists requiring precise texture control.
- Granules:Modified starch formats offer dust-reduced handling for bakery and sauce applications.
Powder leads volumes today; liquid formats are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nigeria's UHT dairy retrofitting outpaces Kenya's pasteurized milk scaling, yet both markets tighten purity documentation for hydrocolloid imports. South Africa anchors Southern African Customs Union harmonization, while Ethiopia and Ghana present underpenetrated expansion corridors for technical service deployment.
Nigeria
Lagos and Abuja beverage bottlers accelerate ready-to-drink tetra-pak line investments, pulling emulsifier systems for tropical stability. NAFDAC enforces tightened hydrocolloid raw material purity grade documentation, extending procurement cycles for mid-sized manufacturers. The Lagos corridor concentrates direct technical service engagement as formulators demand on-site viscosity profiling.
Kenya
Nairobi dairy processors scale pasteurized and UHT production, consolidating supplier relationships around bundled compliance packages. The Bureau of Standards certifies stabilizer purity grades, mandating third-party testing documentation for imports. Mombasa port logistics enable regional distribution to Tanzanian and Rwandan processors seeking reduced lead times.
South Africa
Premium ice cream manufacturers shift toward pectin-locust bean gum systems to replace synthetic emulsifiers in retail channels. The Department of Health aligns additive standards with Codex Alimentarius, reducing technical barriers across Southern African Customs Union members. Cape Town and Johannesburg industrial zones anchor clean-label hydrocolloid blend formulation expertise.
Ethiopia
Addis Ababa and Dire Dawa pasteurized milk processing capacity remains underpenetrated, offering first-mover positioning for stabilizer suppliers. The country's national food and drug administration monitors import compliance for hydrocolloid raw materials. Local technical service presence remains sparse, constraining formulation replication speed relative to East African peers.
Ghana
Accra ready-to-drink beverage corridors accelerate hydrocolloid adoption for mouthfeel consistency under tropical storage stress. The country's national standards authority develops alignment with FSSAI protocols, tightening additive approval pathways. Tema port industrial zones concentrate mid-sized processor demand for pre-blended stabilizer systems.
Africa Food Stabilizers Market Competitive Environment
European producers anchor the premium hydrocolloid and emulsifier tier; Asian specialists hold commodity thickener supply. The vendor base stratifies across integrated texture system suppliers, regional distribution hub operators, and standalone ingredient traders. Three archetypes dominate: multinational blenders with technical service bundling, regional distributors offering compliance packages, and commodity brokers serving fragmented bakery channels. Competitive moves concentrate on M&A for African distribution assets and portfolio diversification into clean-label systems.
Within the integrated blender tier, Palsgaard A/S and BASF SE exemplify technical service-intensive positioning, while Cargill anchors regional distribution hub consolidation. These entities represent the shift from commodity sourcing toward modularized stabilizer-emulsifier complexes that compress onboarding timelines for mid-sized dairy processors. Kayo Fine Chemicals and Cape Food Ingredients occupy positions within regional specialist distribution, bridging multinational supply and local procurement consolidation.
| Leading Market Players |
|---|
| BASF SE |
| Tate & Lyle PLC |
| Barentz International BV |
| Palsgaard A/S |
| Kayo Fine Chemicals |
| Hydrosol GmbH & Co KG |
| Cape Food Ingredients |
| Omnia Group (Protea Chemicals) |
| Cargill |
| Others |
Value Chain & Pricing Dynamics
Food technologist concentration in South African and Nigerian technical centers creates labor-cost differentials that widen pricing-tier spreads between premium formulation services and commodity ingredient trading. These skill premiums compound with import duties on hydrocolloid raw materials to stratify procurement costs across African processor tiers.
Pricing Analysis
Capacity additions in Nigerian UHT dairy retrofitting are reshaping price floors for emulsifier systems as mid-sized processors scale tetra-pak lines. Contract-based long-term offtake dominates large dairy procurement, while spot purchasing persists among fragmented bakery channels. Price differentiation hinges on Bureau of Standards certification grade and bundled technical service inclusion. Cost compression in standard-grade hydrocolloids is intensifying because Asian commodity suppliers are expanding guar gum processing volumes. Mid-sized manufacturers without dedicated regulatory affairs functions exhibit highest price sensitivity; integrated dairy processors with compliance teams absorb premium tiering.
Supply Chain Analysis
Nigeria's NAFDAC-mandated local-content documentation requirements for hydrocolloid purity grades are reshaping sourcing toward distributors offering bundled compliance packages. Geographic supply concentrates in India, Pakistan, and China for guar gum and locust bean gum raw materials. African formulators draw from South Asian processing hubs for modified starches and xanthan gum. Single-source vulnerability runs through Mombasa and Lagos port chokepoints where containerized hydrocolloid imports face customs inspection delays. Distribution runs through regional hub operators like Cargill's Nigerian and Kenyan facilities serving multi-market processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where regulatory compliance cost differentials between Nigeria's extended NAFDAC timelines and South Africa's Codex-aligned streamlined approvals create tiered entry barriers.
For Market Incumbents: Anchor defensive positioning through backward integration into regional distribution assets and certification investment for FSSAI-aligned purity documentation. Palsgaard A/S and BASF SE face emerging threat from Asian commodity suppliers expanding direct technical service presence in Lagos and Nairobi. Channel control over Mombasa and Dar es Salaam logistics corridors represents the critical lever for margin defense against price-aggressive entrants.
For New Entrants and Emerging Players: Launch via direct technical service engagement targeting Ethiopian dairy greenfield capacity in Addis Ababa and Dire Dawa where local formulation expertise remains sparse. Underpenetrated pasteurized milk processing offers the most penetrable white space. Clean-label hydrocolloid blends for South African premium ice cream channels provide secondary entry angle through pectin-locust bean gum system specialization.
For Investors and Strategic Acquirers: Regional distribution specialists with compliance bundling capabilities are the most active acquirer category in this space. Long-term viability over the next decade rests on African Continental Free Trade Area harmonization execution. Acquisition target archetype: mid-cap distributors with Bureau of Standards certification relationships and Mombasa port access. The signal to watch is NAFDAC approval timeline compression for hydrocolloid raw materials as indicator of regulatory efficiency gains.
| Strategic Initiative | Industry Significance |
|---|---|
| Regional Distribution Hub Consolidation | Cargill's Nigerian and Kenyan facilities reduce lead times for Tanzanian and Rwandan processors. |
| Clean-Label Hydrocolloid Blend Development | Pectin-locust bean gum systems replace synthetic emulsifiers in South African premium retail channels. |
| Backward Integration into Compliance Services | Bundled third-party testing documentation addresses NAFDAC's tightened purity grade requirements. |
| Direct Technical Service Deployment | On-site viscosity profiling displaces broker-mediated procurement in Lagos beverage corridors. |
| Long-Term Supply Agreement Structuring | Contract-based offtake stabilizes guar gum and locust bean gum cost exposure for UHT dairy processors. |
Study Parameters
Bottom-up dairy and beverage processor modeling reconciled against top-down hydrocolloid import tracking forms the analytical core of this study. Primary interviews with Nigerian and Kenyan dairy procurement managers, South African food technologists, Lagos-based formulation specialists, and Mombasa port logistics coordinators combined with secondary validation from NAFDAC regulatory filings, Kenya Bureau of Standards certification databases, South African Department of Health additive registries, and customs trade records. Triangulation across these sources anchored volume and value estimates.
Input-output matrices mapped hydrocolloid functionality requirements to specific processing environments across product type, application, end user, and form segmentation dimensions. CAGRs were derived through regression analysis of historical procurement patterns projected across the analysis window. Industry-specific forecast inputs included UHT line retrofitting timelines in Nigeria and pasteurized milk capacity scaling in Kenya.
Forecast precision tightens around the base case; tail outcomes carry wider variance under African Continental Free Trade Area implementation delays or prolonged shipping disruptions through South Asian processing hubs. Forecasts reflect documented assumptions regarding regulatory harmonization velocity and food technologist training pipeline expansion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Film Forming Starches Market
Food Additives and Ingredients
North America Microencapsulation Market
Food Additives and Ingredients
Aluminum-Free Natural Food Color Market
Food Additives and Ingredients
Acetylated Distarch Adipate Market
Food Additives and Ingredients
Mexico Food Acidulants Market
Food Additives and Ingredients
Synthetic Food Preservatives Market
Food Additives and Ingredients
Chymosine Market
Food Additives and Ingredients
South America Food Enzymes Market
Food Additives and Ingredients
France Food Enzymes Market
Food Additives and Ingredients
South America Food Emulsifiers Market
Food Additives and Ingredients
Egypt Food Emulsifiers Market
Food Additives and Ingredients
Bulking Agents Market
Food Additives and Ingredients
Argentina Food Colorants Market
Food Additives and Ingredients
South Africa Food Preservatives Market
Food Additives and Ingredients
North America Feed Anti-Caking Agents Market
Food Additives and Ingredients
Global Lactase Market