
 Middle East and Africa Primary Angle-Closure Glaucoma Market | 2026-2036
Middle East and Africa Primary Angle-Closure Glaucoma Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Primary Angle-Closure Glaucoma Market Foresight
Competitive Dynamics
The capital-intensity divergence between multinational pharmaceutical conglomerates and regional distributors is rotating competitive advantage toward entities with direct manufacturing partnerships. Alcon AG leverages its vertically integrated ophthalmic surgical portfolio to sustain premium positioning across Gulf Cooperation Council markets. Sun Pharmaceutical Industries Ltd anchors its presence through cost-competitive generic formulations that dominate public hospital procurement channels in South Africa and Nigeria.
Product and Segment Structure
Primary angle-closure glaucoma denotes an ocular condition characterized by mechanical obstruction of aqueous humor outflow through the anterior chamber angle, typically precipitated by pupillary block mechanisms, with intraocular pressure elevation constituting the primary pathophysiological parameter requiring urgent clinical intervention. The condition demands therapeutic modalities spanning pharmacological pressure reduction, laser peripheral iridotomy, and surgical intervention to restore aqueous drainage and prevent optic nerve damage. Topical agents occupy the largest revenue share due to their role as first-line chronic management, while laser therapies represent the fastest-expanding segment as Saudi Arabian and Emirati clinics invest in selective laser trabeculoplasty platforms. Combination therapies command margin premiums where physicians seek simplified dosing regimens for elderly patients with medication adherence challenges.
Regulatory Environment
Saudi Arabia's SFDA, South Africa's SAHPRA, and the UAE's MOHAP collectively govern ophthalmic pharmaceutical and device market access through divergent but increasingly harmonized registration frameworks. SFDA's accelerated pathway for innovative glaucoma devices and SAHPRA's emphasis on bioequivalence data for generic prostaglandin analogs shape product launch sequencing and local partnership requirements across the region. Stakeholders must monitor evolving reimbursement negotiations between national health insurers and manufacturers, as these agreements will determine whether premium surgical interventions penetrate beyond private hospital networks into publicly funded care systems.
Market Dynamics
Minimally invasive glaucoma surgery platforms are restructuring competitive advantage across Middle Eastern and African ophthalmology departments, compressing traditional trabeculectomy volumes while forcing device manufacturers to reconfigure service architectures around laser-based outpatient workflows.
Growth Catalysts
- SFDA Accelerated Device Pathway:Saudi Arabia's streamlined registration for innovative glaucoma implants reduces time-to-market for selective laser trabeculoplasty platforms, enabling earlier clinic adoption in Riyadh and Jeddah.
- Specialized Center Construction:Dubai Healthcare City and Abu Dhabi's Cleveland Clinic Abu Dhabi are building dedicated glaucoma units with integrated diagnostic-surgical suites, concentrating patient flow and equipment procurement.
- Prostaglandin Analog Formulation Advances:Fixed-dose combination therapies combining beta-blockers with prostaglandins simplify elderly patient adherence, expanding addressable populations in South African public health systems.
Market Restraints
- Excimer Laser System Concentration:Manufacturing of selective laser trabecuoplasty platforms concentrates among three European and American suppliers, creating import dependency and extended maintenance timelines for Gulf clinics.
- SAHPRA Bioequivalence Requirements:South Africa's stringent generic prostaglandin analog testing protocols delay market entry for cost-competitive formulations, preserving incumbent pricing power.
- Trabeculectomy Skill Bottleneck:Filtration surgery expertise concentrates among aging specialists in Cairo and Johannesburg, constraining surgical capacity expansion despite rising case volumes.
Strategic Opportunities
- Nigerian Public Hospital Penetration:Lagos and Abuja federal medical centers lack dedicated glaucoma screening infrastructure, creating first-mover advantage for mobile diagnostic platforms paired with telemedicine triage.
- AI-Enhanced Optical Coherence Tomography:Machine learning algorithms for anterior segment angle analysis are converging with swept-source imaging, enabling technician-operated screening in understaffed Egyptian provincial clinics.
- MOHAP Reimbursement Expansion:The UAE's Ministry of Health and Prevention is negotiating coverage for outpatient laser procedures, potentially shifting surgical volumes from inpatient to ambulatory settings.
Industry Challenges
- Gonioscopy Training Deficits:Accurate anterior chamber angle assessment requires specialized slit-lamp skills that residency programs in Khartoum and Nairobi undersupply, leading to misdiagnosis and delayed intervention.
- Device-Pharmaceutical Integration Complexity:Hospitals combining Alcon surgical platforms with competing generic medication formularies face workflow fragmentation and inventory reconciliation burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Primary Angle-Closure Glaucoma Market |
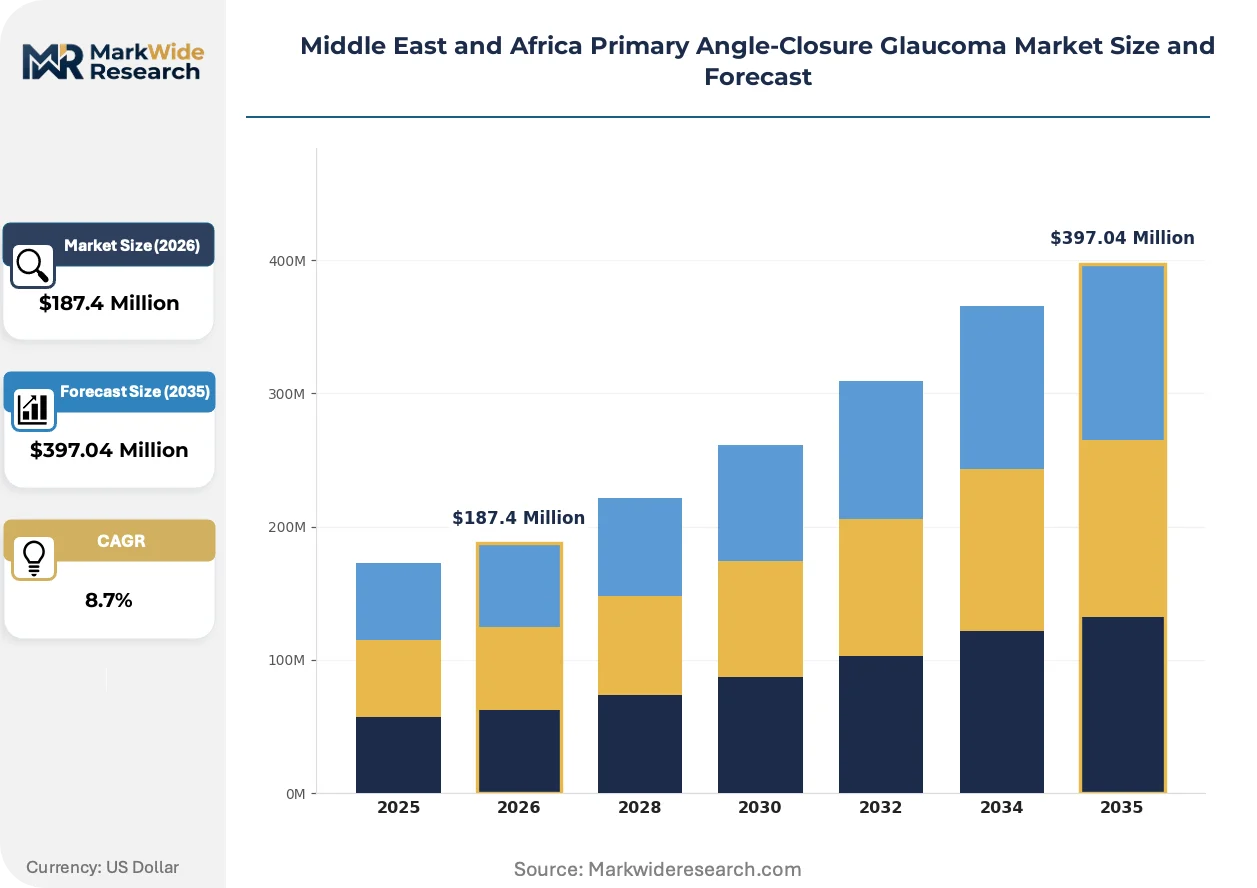
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Agents, Surgical Treatments, Laser Therapies, Combination Therapies Delivery Mode: Intraocular, Oral, Injectable, Transdermal End User: Ophthalmic Clinics, Hospitals, Research Institutes, Homecare Settings Treatment Stage: Acute Phase, Chronic Phase, Preoperative Phase, Postoperative Phase |
| Companies Covered | Alcon AG, AbbVie Inc, Bausch & Lomb Inc, Viatris Inc, Novartis AG, Sun Pharmaceutical Industries Ltd, Santen Pharmaceutical Co., Ltd., Pfizer Inc., Teva Pharmaceutical Industries Ltd., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Primary Angle-Closure Glaucoma Market Shifts & Advancements
Diagnostic automation and reimbursement restructuring are converging to displace conventional care pathways across Middle Eastern and African glaucoma management, with technology vendors and hospital systems recalibrating around outpatient efficiency metrics.
Micro-invasive glaucoma stents are supplanting trabeculectomy as the preferred surgical intervention for moderate angle-closure cases. Saudi Arabian and Emirati private hospital chains are adopting these devices at accelerating cadence, compressing average length-of-stay from three days to same-day discharge and forcing traditional filtration surgeons to retrain or lose referral volumes.
SAHPRA's 2023 guidance on real-world evidence for ophthalmic device registration is reshaping clinical trial design across southern Africa. Manufacturers must now incorporate South African patient demographic data into premarket submissions, extending study timelines but improving post-approval safety surveillance for angle-closure interventions in high-pigment populations.
Hospital procurement committees in the Gulf are unbundling device purchases from mandatory service contracts, reversing decade-long bundled pricing conventions. This fragmentation allows Saudi Arabian ministry hospitals to source maintenance from third-party technical services, pressuring original equipment manufacturers to compete on discrete service pricing or risk margin erosion across their installed base.
Middle East and Africa Primary Angle-Closure Glaucoma Market Segmentation
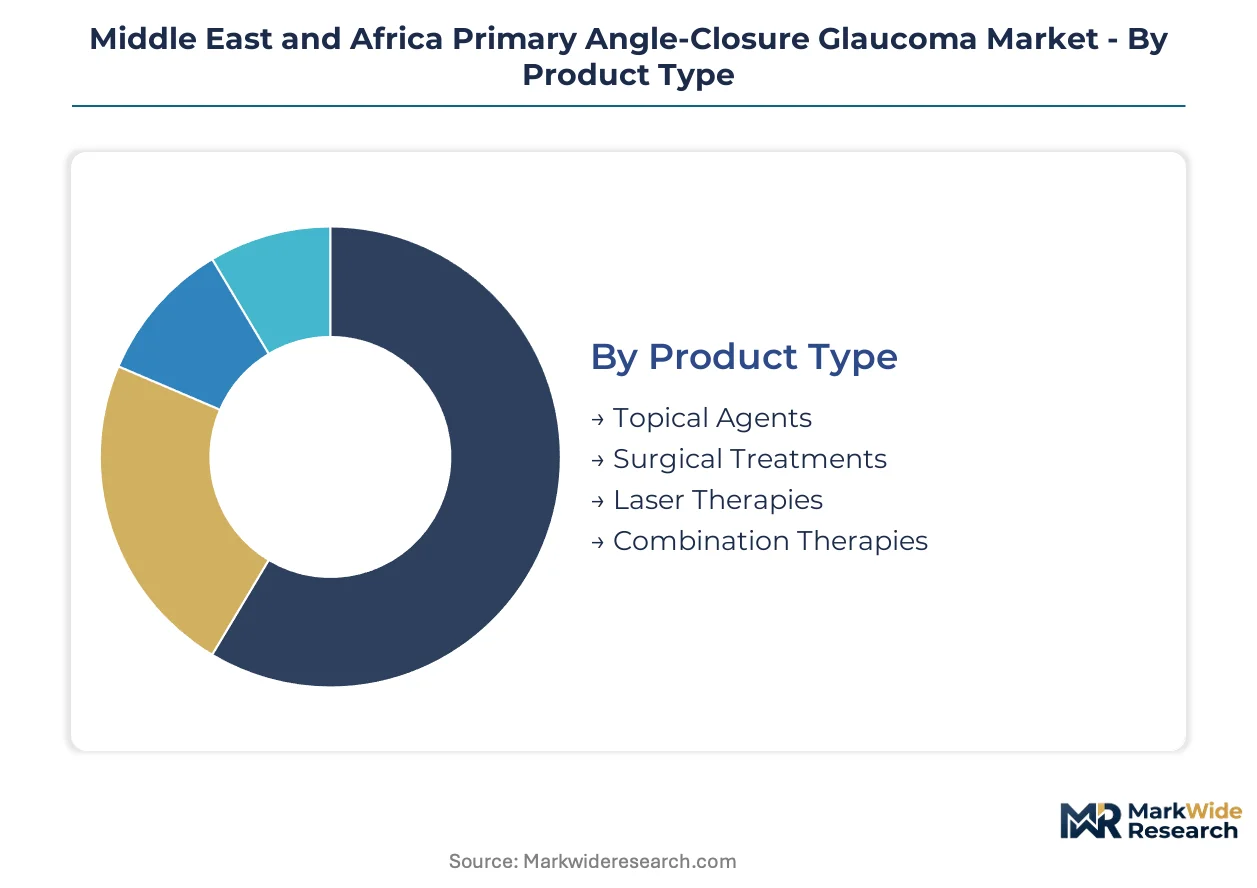
Primary angle-closure glaucoma management fragments across four distinct dimensions, each shaped by divergent reimbursement pathways and clinical workflow constraints. Understanding substitution pressures between pharmacological and interventional modalities reveals where capital investment concentrates versus where volume persists.
Product Type:
Laser therapies face the most acute substitution threat as micro-invasive stents capture moderate cases, while topical agents defend their chronic-phase stronghold through adherence economics.
- Topical Agents:Prostaglandin analogs, beta-blockers, and carbonic anhydrase inhibitors delivered as eye drops constitute the chronic management backbone. Demand clusters in South African public hospital formularies and Saudi ministry procurement channels where once-daily dosing regimens reduce nursing burden and patient dropout.
- Laser Therapies:Selective laser trabeculoplasty and laser peripheral iridotomy platforms enable outpatient angle intervention without incisional risk. Dubai Healthcare City clinics and Abu Dhabi's specialized ophthalmology units are acquiring these systems fastest, displacing trabeculectomy referrals for early-to-moderate cases.
- Surgical Treatments:Trabeculectomy, goniotomy, and micro-invasive glaucoma stent implantation address refractory pressure elevation.
- Combination Therapies:Fixed-dose formulations merge two drug classes into single bottles.
Topical agents retain volume leadership; laser therapies hold the steepest expansion curve.
Delivery Mode:
Cost tiering separates invasive surgical delivery from ambulatory alternatives, with reimbursement depth determining which modalities penetrate public versus private care strata.
- Intraocular:Implants, stents, and sustained-release devices placed within the anterior chamber or trabecular meshwork. Saudi private hospital chains in Riyadh and Jeddah prioritize these for same-day discharge protocols that maximize surgical suite turnover.
- Injectable:Intravitreal or periocular depot formulations extend dosing intervals. Research institutes in Cairo and Johannesburg are piloting these for patients with demonstrated topical adherence failure.
- Oral:Systemic carbonic anhydrase inhibitors and hyperosmotic agents for acute pressure spikes.
- Transdermal:Experimental patches and iontophoretic systems remain preclinical.
Intraocular delivery commands margin premiums; injectable formats are climbing fastest as adherence economics improve.
End User:
Customer type fragmentation mirrors the Gulf-Africa divide in infrastructure depth, with capital-intensive settings concentrating in the UAE and Saudi Arabia while volume disperses across under-equipped African facilities.
- Hospitals:Tertiary centers with integrated operating suites and anesthesia support perform complex filtration surgery and manage acute angle-closure crises. Nigeria's federal medical centers in Lagos and Abuja lack dedicated glaucoma units, creating equipment gaps that mobile surgical platforms could address.
- Ophthalmic Clinics:Specialized outpatient facilities in Dubai Healthcare City and Jeddah's private medical districts focus on laser trabeculoplasty and medical management, referring surgery to affiliated hospital networks.
- Research Institutes:Academic medical centers in Cairo, Johannesburg, and Riyadh conduct device trials and train gonioscopy skills.
- Homecare Settings:Self-administered topical regimens dominate chronic phase management.
Hospitals retain procedural revenue concentration; ophthalmic clinics are expanding fastest as laser platforms enable ambulatory migration.
Treatment Stage:
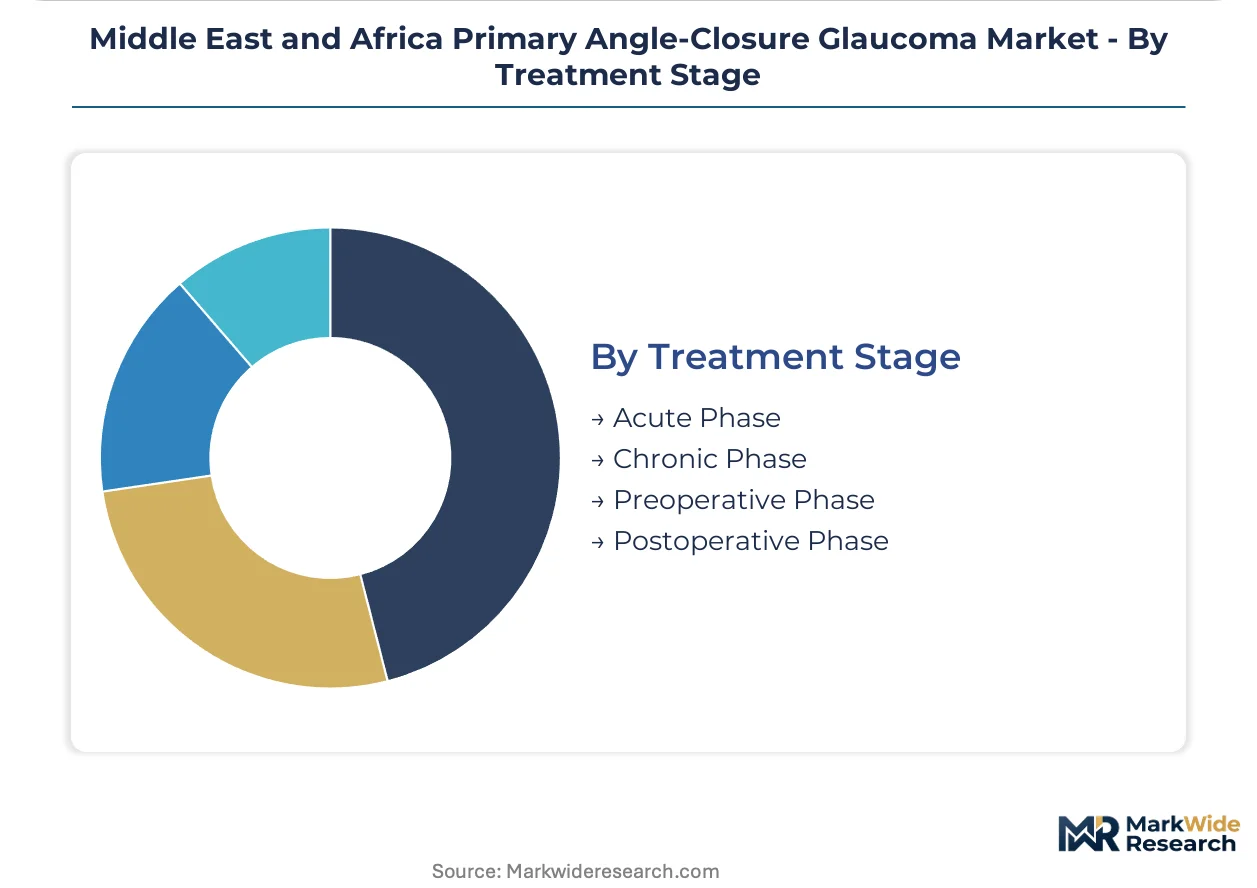
Maturity differentiation separates established chronic-phase protocols from emerging preoperative optimization approaches, with acute-phase intervention remaining the most resource-intensive.
- Chronic Phase:Long-term pressure control through medication, monitoring, and selective laser intervention. South Africa's public health system manages the largest chronic cohorts, with SAHPRA-regulated generic prostaglandins containing costs.
- Acute Phase:Emergency pressure reduction through systemic and topical agents, laser iridotomy, or surgical intervention. Cairo's Kasr Al-Ainy Hospital and Johannesburg's Charlotte Maxeke Academic Hospital serve as regional referral hubs for angle-closure attacks.
- Preoperative Phase:Pressure optimization and anterior chamber preparation before filtration surgery.
- Postoperative Phase:Wound healing management, bleb monitoring, and adjunctive medication.
Chronic phase commands patient volume; preoperative optimization is gaining traction as MIGS platforms require standardized preparation protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
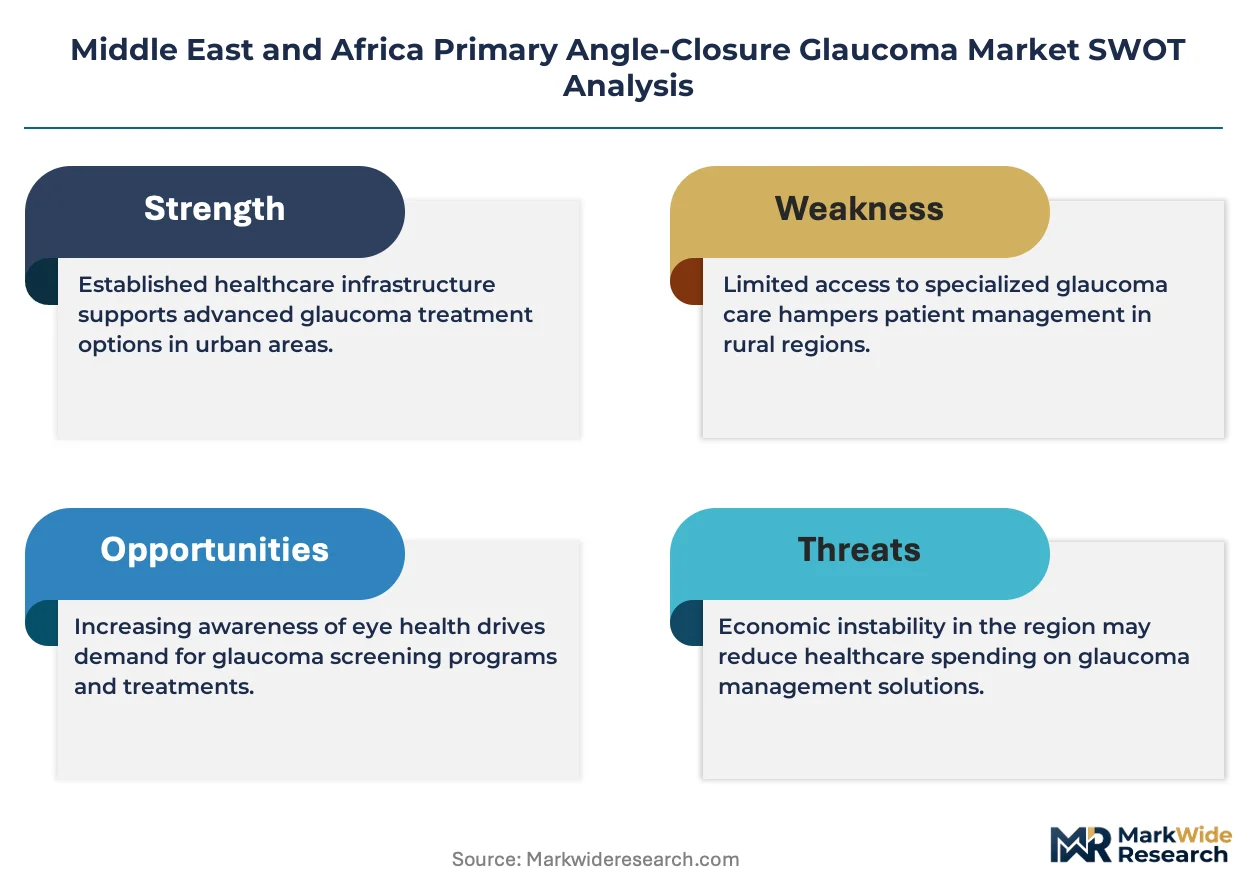
Demand elasticity splits sharply across the Middle East and Africa, with Gulf Cooperation Council buyers absorbing premium surgical platforms while African public health systems prioritize cost-containment in pharmaceutical procurement.
Saudi Arabia
SFDA's accelerated device pathway compresses registration timelines for selective laser trabeculoplasty platforms, stimulating private hospital investment in Riyadh and Jeddah. The kingdom's Vision 2030 healthcare privatization agenda channels capital toward specialized ophthalmology centers in King Faisal Specialist Hospital networks. Ministry of Health procurement tenders increasingly specify same-day discharge protocols that favor micro-invasive stent adoption over conventional filtration surgery.
United Arab Emirates
MOHAP reimbursement negotiations for outpatient laser procedures are shifting surgical volumes from inpatient to ambulatory settings across Dubai Healthcare City clusters. Cleveland Clinic Abu Dhabi and Sheikh Khalifa Medical City anchor glaucoma service line expansion with integrated diagnostic-surgical suites. Private insurance penetration in Dubai and Abu Dhabi enables premium device procurement that public systems elsewhere in the region cannot replicate.
South Africa
SAHPRA bioequivalence requirements for generic prostaglandin analogs preserve incumbent pricing power while delaying cost-competitive formulation entry into public hospital formularies. Charlotte Maxeke Academic Hospital and Groote Schuur Hospital concentrate surgical expertise for angle-closure emergencies, yet gonioscopy training deficits constrain diagnostic capacity in provincial facilities. The national health insurance rollout timeline will determine whether premium interventions penetrate beyond private hospital networks.
Egypt
Kasr Al-Ainy Hospital and Ain Shams University hospitals serve as regional referral hubs for acute angle-closure attacks across North Africa, yet equipment maintenance dependencies on European suppliers create downtime risks. The country's national pharmaceutical regulator emphasizes import licensing for sustained-release ocular implants, slowing novel delivery format adoption. Cairo-based research institutes pilot AI-enhanced anterior segment imaging to compensate for specialist shortages in Upper Egypt and Delta provinces.
Nigeria
Federal medical centers in Lagos and Abuja lack dedicated glaucoma screening infrastructure, creating equipment gaps that mobile diagnostic platforms could address. The national health ministry's essential medicines list prioritizes topical beta-blockers over prostaglandin analogs on cost grounds, constraining therapeutic escalation pathways. Private ophthalmology clinics in Lagos Island and Ikeja concentrate paying patients, while public sector volume remains underserved.
Middle East and Africa Primary Angle-Closure Glaucoma Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with multinational pharmaceutical conglomerates commanding surgical device portfolios while regional distributors anchor generic medication supply. Market structure reflects capital-intensity divergence: vertically integrated ophthalmic surgical manufacturers sustain premium positioning through direct hospital relationships, while formulation specialists compete on tender pricing in public procurement channels. Three archetypes dominate—integrated surgical platform vendors, generic pharmaceutical manufacturers, and regional distribution specialists. Competitive dynamics center on manufacturing partnerships that secure local registration advantages and service contract unbundling that fragments traditional bundled pricing conventions.
Within the integrated surgical tier, Alcon AG occupies a position exemplifying vertical control over ophthalmic device portfolios across Gulf Cooperation Council markets. Among generic pharmaceutical specialists, Sun Pharmaceutical Industries Ltd and Teva Pharmaceutical Industries Ltd represent cost-competitive formulation archetypes that dominate public hospital procurement channels in South Africa and Nigeria.
| Leading Market Players |
|---|
| Alcon AG |
| AbbVie Inc |
| Bausch & Lomb Inc |
| Viatris Inc |
| Novartis AG |
| Sun Pharmaceutical Industries Ltd |
| Santen Pharmaceutical Co., Ltd. |
| Pfizer Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Others |
Supply & Pricing Matrix
Long-term service contracts bundled with selective laser trabecuoplasty platforms lock in both supply access and price visibility for Gulf Cooperation Council hospital procurement committees, compressing third-party maintenance margins while securing predictable aftermarket revenue streams for original equipment manufacturers across Riyadh and Dubai Healthcare City installations.
Pricing Analysis
After-sales service revenue tiers including extended maintenance contracts and replacement consumables drive lifetime value for micro-invasive glaucoma device vendors. Three-tier pricing structure across premium, standard, and economy levels separates Alcon's vertically integrated surgical platforms from regional distributors' generic pharmaceutical offerings. Pricing pressure stems from Gulf hospital procurement committees unbundling device purchases from mandatory service agreements. Public hospital formularies in South Africa and Nigeria exhibit highest price sensitivity, while Emirati private insurance networks absorb premium surgical platform costs.
Supply Chain Analysis
Strategic stockpile preferences dominate inventory strategy for excimer laser components given European and American supplier concentration and extended replacement timelines. Manufacturing of selective laser trabecuoplasty platforms concentrates in Germany, the United States, and Switzerland. Raw material dependencies include precision optical components, solid-state laser crystals, and surgical-grade titanium alloys. Single-source vulnerability constrains Gulf clinic operational continuity. Distribution runs through regional distribution specialists with direct manufacturing partnerships for pharmaceutical formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story anchored in regulatory entrenchment: SFDA and SAHPRA registration pathways create multi-year barriers that protect incumbent positions while complicating new entrant market access across the Middle East and Africa.
For Market Incumbents: Compound service contract penetration among installed selective laser trabecuoplasty platforms in Saudi private hospital networks to offset unbundling pressure from procurement committees. Deepen backward integration into sustained-release ocular implant manufacturing to reduce dependency on European component suppliers. Threat substitution from AI-enhanced diagnostic platforms demands preemptive software companion development. For New Entrants and Emerging Players: Differentiate on mobile diagnostic platform deployment paired with telemedicine triage to penetrate Nigerian federal medical centers lacking dedicated glaucoma screening infrastructure. Target Lagos and Abuja public hospital systems as the most penetrable geography given equipment gaps and underserved patient volumes. Pursue partnership-based go-to-market models with established regional distributors to navigate SAHPRA bioequivalence requirements. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated surgical platform vendors with captive service contract portfolios across Gulf Cooperation Council markets. Long-term viability hinges on exposure to ambulatory surgical migration and premium private insurance reimbursement depth. Acquisition target archetype: regional distributors with direct manufacturing partnerships and established SFDA registration track records. Signal to watch: MOHAP reimbursement expansion for outpatient laser procedures crossing implementation thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Accelerated Device Registration | Compresses time-to-market for innovative glaucoma implants in Riyadh and Jeddah hospital networks. |
| Mobile Diagnostic Platform Deployment | Addresses equipment gaps in Nigerian federal medical centers lacking dedicated glaucoma screening infrastructure. |
| Service Contract Unbundling Response | Pressures original equipment manufacturers to compete on discrete maintenance pricing across Saudi ministry hospitals. |
| AI-Enhanced OCT Integration | Enables technician-operated screening in understaffed Egyptian provincial clinics through machine learning algorithms. |
| Generic Prostaglandin Bioequivalence Investment | Accelerates SAHPRA approval for cost-competitive formulations targeting South African public hospital formularies. |
Research Methodology
Initial hypotheses were tested against primary input from ophthalmology department heads, hospital procurement managers, regulatory affairs specialists at SFDA and SAHPRA, and biomedical engineers, then refined through secondary validation against FDA 510(k) filings, EMA medical device registrations, ClinicalTrials.gov ophthalmology trial records, and Gulf Cooperation Council customs import data. Bottom-up patient volume modeling and top-down pharmaceutical expenditure triangulation converged on segment-level estimates.
Variance-decomposition across product type, delivery mode, end user, and treatment stage dimensions structured the analytical framework over the projection horizon. CAGRs were derived from segmented volume projections weighted by pricing tier assumptions. Forecast inputs incorporated SFDA registration pipeline velocity, MOHAP reimbursement negotiation status, and SAHPRA bioequivalence approval timelines.
Forecasts assume regulatory continuity in Saudi SFDA, South African SAHPRA, and UAE MOHAP regimes; material policy shifts would require re-modeling. Revision becomes warranted when ambulatory surgical reimbursement coverage crosses implementation thresholds or when excimer laser supply disruptions exceed sixty-day replacement timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Facial Paralysis Market
Specialty Medicine
Nuclear Medicine Therapeutics Market
Specialty Medicine
Ovarian Cancer Therapeutics Market
Specialty Medicine
Chronic Idiopathic Constipation Treatment Market
Specialty Medicine
Scleritis Market
Specialty Medicine
Eosinophilic Granulomatosis with Polyangiitis Treatment Market
Specialty Medicine
Post-Traumatic Stress Disorder Treatment Market
Specialty Medicine
Dry Eye Syndrome Market
Specialty Medicine
Toxoplasmosis Treatment Market
Specialty Medicine
Adult Malignant Glioma Therapeutics Market
Specialty Medicine
Global Bile Duct Cancer Market
Specialty Medicine
China Ulcerative Colitis Market
Specialty Medicine
Osteomyelitis Market
Specialty Medicine
Hemangioma Market
Specialty Medicine
Anaplastic Large Cell Lymphoma (ALCL) Therapeutics Market
Specialty Medicine
Global Autism Spectrum Disorders Treatment Market