
 Global Industrial Sludge Treatment Chemicals Market | 2026-2036
Global Industrial Sludge Treatment Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial Sludge Treatment Chemicals Market Foresight
China is tilting toward expanded flocculant and coagulant manufacturing capacity to serve its domestic metal finishing and textile sectors. Ecolab leverages its integrated water-chemical-service model across North American and European industrial accounts. BASF SE anchors its position through backward integration into acrylamide monomer production, a critical feedstock for polymeric flocculants. Kemira competes in the Nordic and Baltic markets with specialized cationic polymer formulations for cold-climate dewatering.
Industrial sludge treatment chemicals comprise formulated reagents designed to modify the physical and chemical properties of wastewater residuals, typically achieving solids content increases from two percent to twenty percent through dewatering processes. These chemicals function primarily to reduce disposal volumes, stabilize organic matter, and ensure effluent compliance before landfill or thermal treatment. Flocculants command the largest share of the chemical type dimension due to their universal deployment across thickening and clarification stages, while biocides represent the fastest-growing category as odor control regulations tighten around anaerobic sludge storage. Within applications, dewatering concentrates margin pools because chemical selection directly determines cake dryness and subsequent hauling costs for end users in mining and pulp processing.
The EPA enforces landfill disposal criteria under 40 CFR Part 503, which mandates pathogen reduction and vector attraction control through chemical stabilization or alternative technologies. REACH registration requirements in Europe govern the import and manufacture of polymer-based flocculants, while China's MEE enforces stricter COD and heavy metal discharge limits that expand chemical dosing at industrial pretreatment facilities. Stakeholders must monitor how the EU Green Deal's zero-pollution ambition will recalibrate allowable polymer residuals in treated biosolids destined for agricultural land application.
Market Dynamics
The EU Urban Wastewater Treatment Directive revision is tightening discharge limits across industrial clusters, forcing facilities to upgrade chemical dosing systems and expand procurement of advanced flocculant formulations.
Growth Catalysts
- COD and heavy metal discharge limits:China's MEE enforces stricter pretreatment standards at industrial facilities, expanding chemical dosing requirements for metal finishing and textile plants in the Yangtze River Delta.
- Zero-pollution ambition:The EU Green Deal recalibrates allowable polymer residuals in treated biosolids, driving demand for next-generation biodegradable flocculants in agricultural land application.
- Cold-climate dewatering specialization:Nordic municipalities require cationic polymer formulations engineered for low-temperature sludge conditioning, creating specialized demand pockets.
Market Restraints
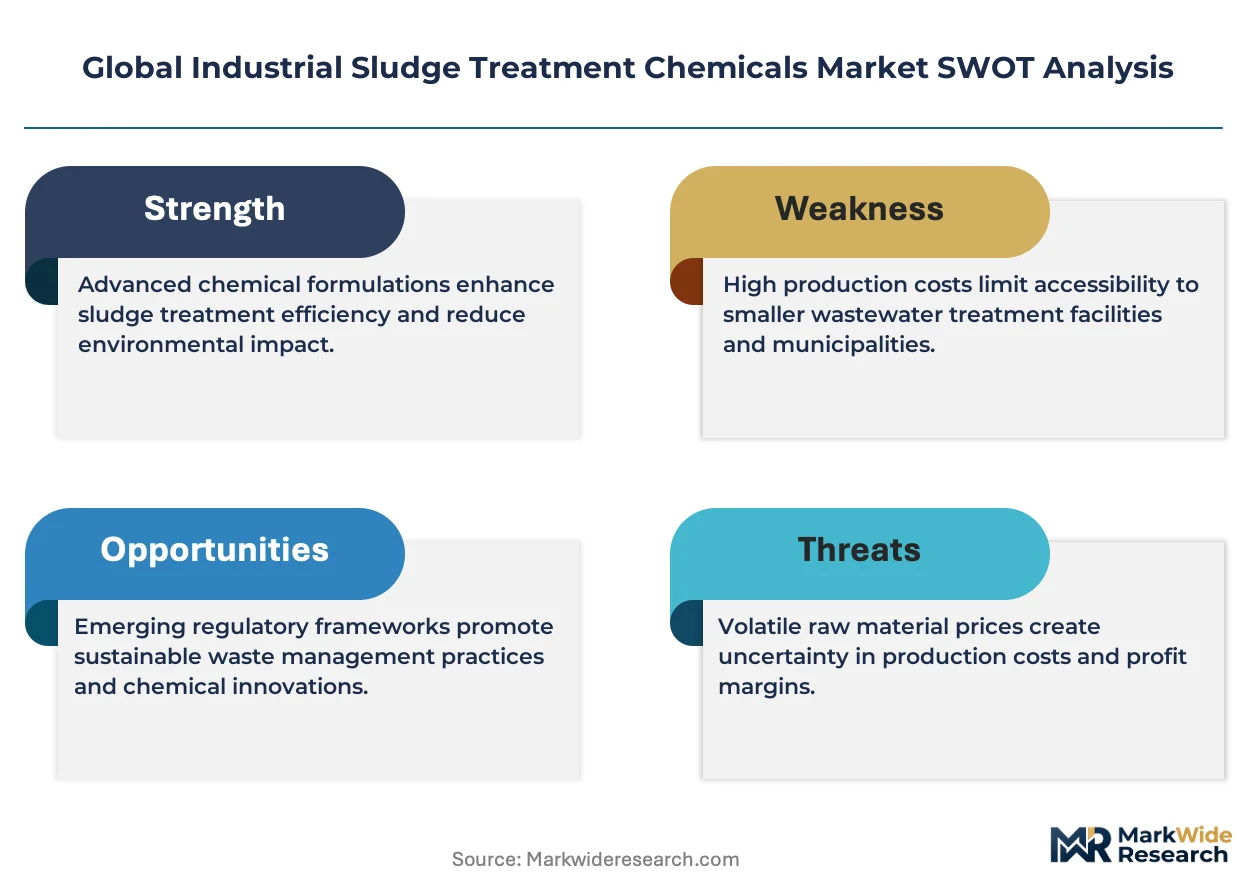
- Acrylamide monomer supply concentration:Backward integration into this critical feedstock for polymeric flocculants concentrates among a limited supplier base, creating input cost volatility.
- REACH registration friction:Polymer-based flocculant manufacturers face extended compliance timelines and testing burdens for European market entry.
- Mechanical dewatering substitution:Advanced centrifuge and belt press technologies reduce chemical dependency in high-volume mining and pulp processing applications.
Strategic Opportunities
- Baltic market penetration:Underdeveloped chemical service infrastructure in Estonia, Latvia, and Lithuania creates white space for integrated water-chemical-service models.
- Odor control biocide expansion:Tightening regulations around anaerobic sludge storage open growth corridors for specialized antimicrobial formulations.
- Digital dosing system convergence:IoT-enabled chemical feed controls combined with predictive analytics enable precision dosing contracts in North American industrial accounts.
Industry Challenges
- Polymer residual certification complexity:Agricultural land application approvals require multi-year field trials and soil ecology assessments, extending commercialization timelines.
- Legacy SCADA integration:Retrofitting automated chemical dosing systems into existing wastewater plant control architectures demands specialized protocol translation and downtime coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial Sludge Treatment Chemicals Market |
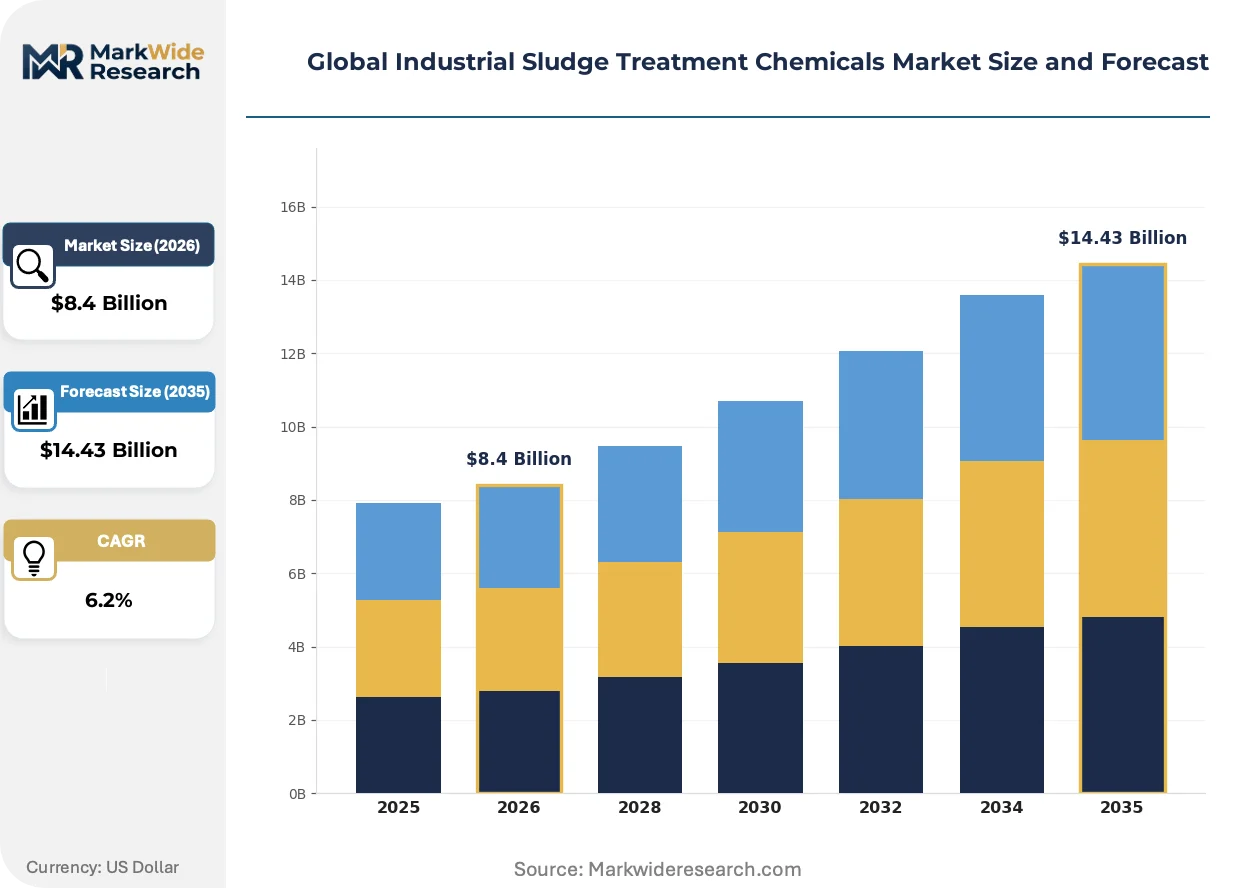
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $14.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Chemical Type: Flocculants, Coagulants, Biocides, pH Adjusters, Defoamers End User Industry: Pulp & Paper, Textile Processing, Metal Finishing, Food Processing, Mining Application: Thickening, Dewatering, Stabilization, Odor Control, Toxicity Reduction Packaging Type: Liquid, Powder, Granules, Bulk Bags, Drums |
| Companies Covered | Ecolab, AMCON INC, BASF SE, SNF Group, Kurita Water Industries Ltd, Veolia Water Technologies, Ovivo, Solenis, Kemira, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial Sludge Treatment Chemicals Market Shifts & Advancements
Formulation chemistry and regulatory chemistry are advancing in parallel, with biodegradable polymer architectures and digital dosing controls reshaping how industrial facilities manage sludge conditioning costs.
Natural-based flocculants derived from chitosan and starch graft copolymers are collapsing the performance gap with synthetic polyacrylamides in municipal dewatering applications. Scandinavian water utilities are piloting these bio-alternatives at full scale. The technology is collapsing the historical price-performance trade-off that locked municipalities into petroleum-derived chemistry.
REACH registration requirements now govern polymer-based flocculant imports and manufacture across the European Economic Area. ECHA's updated guidance on polymer substance characterization demands expanded analytical testing and dossier preparation. German and Dutch formulators are responding by consolidating product portfolios to focus on high-volume SKUs with defensible registration packages.
Integrated service contracts now bundle chemical supply with equipment maintenance and performance guarantees, displacing traditional transactional procurement. Mining operators in Western Australia and Chile are adopting these full-risk arrangements. The shift is most visible in high-volume dewatering applications where chemical costs represent a measurable share of total sludge management spend.
Global Industrial Sludge Treatment Chemicals Market Segmentation
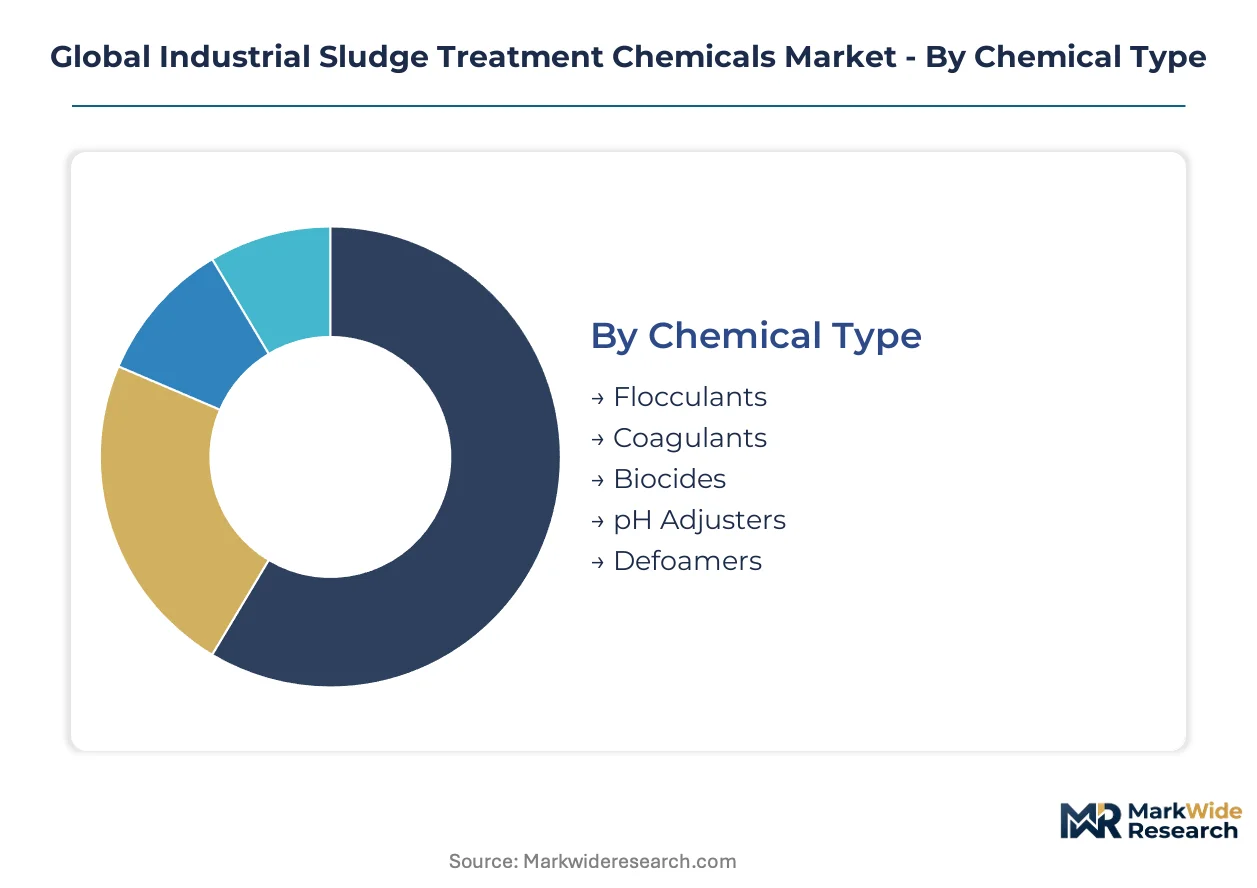
Industrial sludge treatment chemicals serve heterogeneous operational requirements across wastewater infrastructure. Chemical selection varies dramatically by sludge source characteristics, regulatory discharge limits, and downstream disposal pathways. Segmentation reveals where margin pools concentrate and which formulations command premium positioning.
Chemical Type:
Formulation chemistry spans synthetic polymers, mineral salts, and biological agents with distinct performance profiles and cost structures.
- Flocculants:Long-chain polyacrylamide polymers bridge suspended particles into settleable flocs through charge neutralization and bridging mechanisms. Demand concentrates in municipal dewatering facilities across Germany and the Netherlands where polymer-assisted belt press operations achieve 18-22 percent cake solids. REACH registration complexity favors established suppliers with dossier-ready high-volume SKUs.
- Biocides:Oxidizing and non-oxidizing antimicrobial formulations suppress anaerobic bacterial activity in stored sludge to prevent sulfide generation. Adoption accelerates in Swedish and Finnish pulp mills facing tightening odor emission limits around lagoon storage. The category climbs the fastest as land application restrictions extend storage durations.
- Coagulants:Aluminum sulfate and ferric chloride salts destabilize colloidal suspensions through charge neutralization.
- pH Adjusters:Sulfuric acid, caustic soda, and lime products condition sludge for downstream biological or chemical processes.
- Defoamers:Silicone and mineral oil formulations suppress foam generation in aerobic digestion and mechanical dewatering equipment.
Established volume favors Flocculants; emerging adoption favors Biocides.
End User Industry:
Sludge characteristics and chemical intensity diverge sharply across industrial verticals.
- Metal Finishing:Electroplating and surface treatment operations generate hydroxide-laden sludges with elevated heavy metal content requiring specialized chelating polymer formulations. Facilities in China's Guangdong province expand chemical procurement as MEE enforcement tightens COD discharge limits. Chemical costs represent 8-12 percent of total sludge management spend.
- Mining:Mineral processing tailings demand high-dose flocculant programs for thickening and tailings dam management. Copper and iron ore operations in Western Australia and Chile adopt integrated service contracts bundling chemical supply with thickener performance guarantees. Mechanical dewatering substitution threatens chemical volume in high-tonnage applications.
- Pulp & Paper:Fiber-rich primary sludge and biological secondary sludge require distinct conditioning chemistries.
- Textile Processing:Dye-laden sludge with variable pH demands flexible coagulant and pH adjustment protocols.
- Food Processing:High-organic sludge with odor challenges drives biocide and stabilization chemical demand.
Process intensity concentrates in Metal Finishing; contract innovation concentrates in Mining.
Application:
Process stage determines chemical specification, dosage rates, and performance metrics.
- Dewatering:Pre-conditioning chemicals directly determine cake dryness, hauling frequency, and landfill tipping costs. Centrifuge and belt press operations in North American industrial accounts specify cationic polymer charge density and molecular weight to optimize solids capture. Digital dosing system convergence enables precision feed control and outcome-based contracting.
- Odor Control:Chemical and biological agents intercept hydrogen sulfide and volatile organic compound emissions from anaerobic sludge storage. Nordic municipalities pilot bio-based alternatives as EU Green Deal zero-pollution ambitions recalibrate allowable residuals in land-applied biosolids.
- Thickening:Gravity and flotation thickening operations use coagulants and flocculants to increase solids concentration prior to digestion or dewatering.
- Stabilization:Lime and alkaline materials reduce pathogen levels and vector attraction for landfill disposal compliance.
- Toxicity Reduction:Chemical precipitation and oxidation processes immobilize heavy metals and persistent organics.
Margin capture concentrates in Dewatering; regulatory pressure concentrates in Odor Control.
Packaging Type:
Physical form factors align with dosing infrastructure, transport economics, and shelf stability requirements.
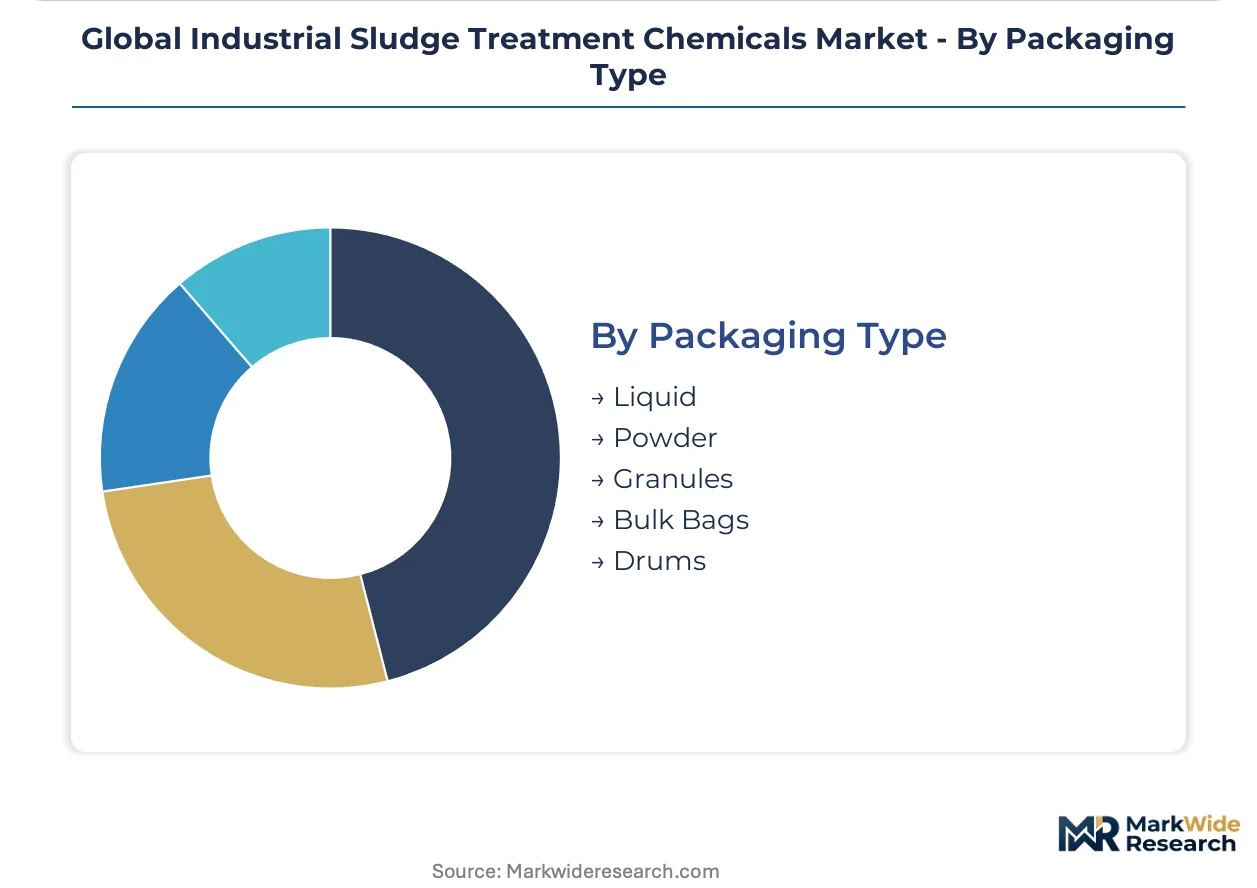
- Liquid:Emulsion and solution polymers enable automated pump feeding and rapid dispersion without dissolution equipment. North American municipal accounts favor bulk liquid delivery for high-volume dewatering programs. Formulation stability and freeze-thaw sensitivity constrain distribution geography.
- Powder:Dry polymer grades offer transport cost advantages and extended shelf life for remote mining and pulp processing sites. Dust control and dissolution system requirements add capital burden.
- Granules:Low-dust handling characteristics suit intermediate-volume applications with manual or semi-automated feeding.
- Bulk Bags:Intermediate bulk containers balance handling efficiency with inventory flexibility for mid-scale industrial users.
- Drums:Standardized containment suits low-volume specialty formulations and maintenance dosing applications.
Automation compatibility favors Liquid; logistics flexibility favors Powder.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MEE anchors the dominant geography through stricter COD and heavy metal discharge limits that expand chemical dosing at industrial pretreatment facilities across the Yangtze River Delta.
China
Metal finishing and textile plants in Guangdong province drive expanded flocculant procurement as MEE enforcement tightens pretreatment standards. The country's dual carbon goals accelerate chemical efficiency upgrades at municipal wastewater facilities. Industrial clusters in the Pearl River Delta generate high volumes of conditioned sludge requiring specialized polymer formulations.
Germany
REACH registration requirements govern polymer-based flocculant manufacture and import across the European Economic Area. ECHA's updated polymer substance characterization guidance demands expanded analytical testing from German formulators. The Ruhr industrial region concentrates demand from legacy manufacturing sites upgrading chemical dosing infrastructure.
United States
EPA enforcement of landfill disposal criteria under 40 CFR Part 503 mandates pathogen reduction through chemical stabilization at municipal facilities. Industrial accounts across the Great Lakes region specify cationic polymer charge density for centrifuge optimization. Mining operators in Arizona and Nevada adopt integrated service contracts bundling chemical supply with thickener performance guarantees.
Sweden
Nordic municipalities require cationic polymer formulations engineered for low-temperature sludge conditioning in subarctic climates. The EU Green Deal's zero-pollution ambition recalibrates allowable polymer residuals in agricultural land application. Pulp mills in the Västra Götaland region pilot bio-based flocculants as alternatives to petroleum-derived chemistry.
Australia
Western Australian copper and iron ore operations drive high-dose flocculant programs for tailings dam management. The country's national environmental regulator enforces stricter discharge limits at mineral processing facilities. Remote mining sites in the Pilbara region favor powder polymer grades for transport cost advantages and extended shelf life.
Global Industrial Sludge Treatment Chemicals Market Competitive Landscape
Capability concentration sits with specialized formulators; scale advantage sits with integrated water-chemical-service platforms. The vendor base organizes around three strategic archetypes: backward-integrated petrochemical majors controlling acrylamide monomer supply, regional specialists with climate-specific formulation expertise, and full-service providers bundling equipment maintenance with chemical procurement. Dominant competitive moves include geographic expansion into underdeveloped Baltic service infrastructure and portfolio consolidation to focus on high-volume SKUs with defensible REACH registration packages.
Among integrated service providers, Ecolab occupies a position exemplifying the bundled water-chemical-service model across North American and European industrial accounts. BASF SE represents the backward-integrated tier through its captive acrylamide monomer production. Kemira sits within the regional specialist archetype, anchoring cold-climate formulation expertise in Nordic and Baltic markets.
| Leading Market Players |
|---|
| Ecolab |
| AMCON INC |
| BASF SE |
| SNF Group |
| Kurita Water Industries Ltd |
| Veolia Water Technologies |
| Ovivo |
| Solenis |
| Kemira |
| Others |
Supply & Pricing Matrix
The Yangtze River Delta acrylamide monomer capacity concentration grants Chinese formulators substantial downstream pricing leverage over European and North American polymer compounders. This geographic supply asymmetry forces non-integrated buyers to absorb feedstock volatility or cede margin through long-term offtake commitments.
Pricing Analysis
Regional price spreads between German REACH-registered formulations and Chinese export grades span 40-60 percent depending on duty structures and logistics modes. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and volume commitment, with municipal utilities commanding lowest unit costs through multi-year framework agreements. Cost compression in standard-grade polyacrylamides is intensifying because BASF and SNF Group are expanding European compounding capacity. Mining operators exhibit highest price sensitivity due to chemical costs representing measurable shares of tailings management spend, while Nordic municipalities show lowest sensitivity given regulatory mandates for cold-climate performance.
Supply Chain Analysis
Extended payment terms now stretch to 90-120 days for established mining and pulp accounts, with supply-chain finance facilities from institutional lenders filling working capital gaps for mid-tier formulators. Acrylamide monomer production concentrates in China, Germany, and the United States, with polymer compounding and emulsification distributed across regional hubs. Formulation chemistry draws from petroleum-derived acrylamide, bio-based chitosan feedstocks, and mineral salt precursors. Single-source vulnerability persists in high-purity cationic monomer supply for specialized cold-climate applications. Distribution runs through integrated water-chemical-service platforms in North America and bulk liquid tanker networks in European industrial corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across regulatory compliance tiers creates niche opportunities for specialized formulators as REACH complexity and biodegradable certification demands multiply product variants. The divergence between legacy petroleum-derived chemistry and next-generation bio-based alternatives splinters procurement patterns.
For Market Incumbents: Entrench position through captive acrylamide supply and REACH dossier consolidation to raise compliance barriers against Asian exporters. Backward integration into monomer production defends margin structure against feedstock volatility from Chinese state-owned petrochemicals. Capacity addition in the Baltic states captures underdeveloped service infrastructure before regional specialists establish beachheads. For New Entrants and Emerging Players: Estonia, Latvia, and Lithuania present immediate white-space targets where chemical service infrastructure lags Nordic sophistication. Bio-based flocculant formulations for EU Green Deal agricultural land application represent the most penetrable segment given multi-year certification timelines locking out established synthetic suppliers. Go-to-market through pilot-scale partnerships with Scandinavian water utilities testing chitosan-derived alternatives at full scale. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors regional specialists with climate-specific formulation expertise over commodity polymer compounders facing mechanical dewatering substitution. Long-term viability rests on biodegradable certification capabilities and digital dosing system integration rather than volume scale. Acquisition targets should demonstrate established ECHA registration packages and cold-climate application track records. The signal to watch is EU polymer residual limit tightening in agricultural biosolids standards, which would accelerate bio-alternative adoption curves.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive acrylamide production insulates BASF and SNF from Chinese feedstock volatility. |
| Green Manufacturing Transition | Chitosan and starch graft copolymer R&D addresses EU Green Deal zero-pollution ambitions. |
| Long-term Supply Agreement | Integrated service contracts bundle chemical procurement with thickener performance guarantees at Chilean copper operations. |
| Joint Venture | Digital dosing system partnerships with IoT platform vendors enable precision feed controls. |
| Capacity Expansion | Emulsion polymer plants in the Pearl River Delta serve Guangdong metal finishing demand. |
Research Methodology
A standing panel of wastewater plant managers, chemical procurement leads at mining operators, distribution channel partners, and technical R&D directors provided ongoing calibration against operational realities. Primary interviews combined with secondary validation from customs and trade data, Cefic industry reports, SEC 10-K filings, and MEE discharge enforcement records. Bottom-up volume modeling across flocculant, biocide, and coagulant segments triangulated against top-down chemical intensity benchmarks by end-use industry.
Scenario-bracketing around regulatory enforcement intensity and mechanical dewatering substitution rates bounded growth estimates across the projection horizon. Segmentation dimensions modeled include chemical type, end-use industry, application stage, and packaging format, with regional production hub differentiation. CAGRs derived from chemical intensity coefficients applied to sludge generation forecasts by industrial vertical. Industry-specific inputs incorporated REACH registration timelines and MEE pretreatment expansion schedules.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-owned petrochemicals or accelerated biodegradable certification by Scandinavian specialists would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Europe Membrane Water and Wastewater Treatment (WWT) Market
Water & Sludge Treatment
Membrane Filtration Systems Market
Water & Sludge Treatment
India Water Treatment Market
Water & Sludge Treatment
Process Water Treatment Market
Water & Sludge Treatment
Polish Water Treatment Chemicals Market
Water & Sludge Treatment
Process Chemicals for Water Treatment Market
Water & Sludge Treatment
Drinking Water Adsorbents Market
Water & Sludge Treatment
CMP Slurry Blend and Delivery Systems Market
Water & Sludge Treatment
Global Water Clarifiers Market
Water & Sludge Treatment
Global Municipal Water Treatment Chemicals Market
Water & Sludge Treatment
Semiconductor Wastewater Treatment Market
Water & Sludge Treatment
Global Sludge Treatment Chemicals Market
Water & Sludge Treatment
Saudi Arabia Industrial Hazardous Waste Management Market
Water & Sludge Treatment
Water Dispersible Granules Market
Water & Sludge Treatment
North America Industrial Water Treatment Market
Water & Sludge Treatment
Mexico Water Treatment Chemicals Market