
 China Water Treatment Chemicals Market | 2026-2036
China Water Treatment Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
China Water Treatment Chemicals Market Outlook
Pharmaceutical-grade purity specifications for boiler feedwater chemicals is redrawing competitive boundaries in the China Water Treatment Chemicals Market. Kemira leverages its captive polymer production in Shandong to control raw material costs for high-molecular-weight flocculants. BASF anchors its position through membrane-compatible antiscalant formulations serving power plant customers. Shandong Taihe Technologies specializes in zwitterionic dispersants for reverse osmosis systems, occupying a narrow but defensible technical niche.
Water treatment chemicals comprise engineered formulations—coagulants, flocculants, disinfectants, and pH adjusters—designed to remove suspended solids, control microbial growth, and maintain operational integrity in industrial and municipal water systems, with active concentrations typically measured in parts per million and performance validated against turbidity reduction and corrosion rate benchmarks. Coagulants and flocculants dominate volume flows in wastewater treatment applications where suspended solids removal drives chemical consumption. Disinfectants command premium pricing in municipal drinking water systems due to residual chlorine compliance mandates. pH adjusters sustain steady demand from power generation end users managing boiler water alkalinity.
MEE enforces stricter discharge permits under evolving environmental compliance frameworks, while GB standards issued by SAMR define product quality thresholds for drinking water contact chemicals. The dual carbon goals policy accelerates adoption of low-carbon manufacturing processes for chemical synthesis. Stakeholders must monitor regulatory alignment between provincial environmental bureaus and national standards to anticipate compliance-driven product reformulation cycles.
Market Dynamics
GB standards tightening for reclaimed water quality is forcing municipal treatment plants across Jiangsu and Zhejiang to upgrade from secondary to tertiary processes, triggering a wave of coagulant and membrane-compatible antiscalant procurement.
Growth Catalysts
- Dual carbon goals policy:China's national decarbonization mandate accelerates adoption of low-carbon chemical synthesis routes for flocculant production, favoring suppliers with captive renewable energy.
- Power generation alkalinity management:Coal and nuclear plants in Shandong province sustain steady consumption of pH adjusters for boiler water chemistry control.
- Reverse osmosis proliferation:Industrial clusters in eastern coastal provinces are deploying membrane-based desalination systems, expanding demand for zwitterionic dispersants and specialized antiscalants.
Market Restraints
- Acrylamide monomer cost volatility:Polyacrylamide flocculant margins compress when propylene feedstock prices spike, squeezing non-integrated compounders.
- Shandong production concentration:Captive polymer manufacturing clusters in this province create supply vulnerability during environmental compliance shutdowns.
- Chlorine alternative substitution:UV and ozone disinfection systems are capturing municipal drinking water contracts, constraining residual chlorine disinfectant volumes.
Strategic Opportunities
- Western province underpenetration:Sichuan and Shaanxi municipal networks lag eastern benchmarks in tertiary treatment deployment, offering first-mover expansion corridors.
- Pharmaceutical-grade boiler feedwater:Biologics manufacturing facilities require ultrapure water chemistry, opening premium formulation tiers for membrane-compatible chemistries.
- MEE discharge permit tightening:Evolving environmental compliance frameworks create recurring reformulation cycles that favor technical service-oriented suppliers.
Industry Challenges
- Polymer synthesis technician scarcity:High-molecular-weight flocculant production requires specialized reactor operators, with talent concentrated in Shandong and Jiangsu.
- GB standard certification timelines:SAMR drinking water contact approvals extend 18-24 months, delaying product launches and freezing working capital.
- Legacy DCS integration friction:Chemical dosing automation in older municipal plants demands custom protocol bridges, complicating smart monitoring deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Water Treatment Chemicals Market |
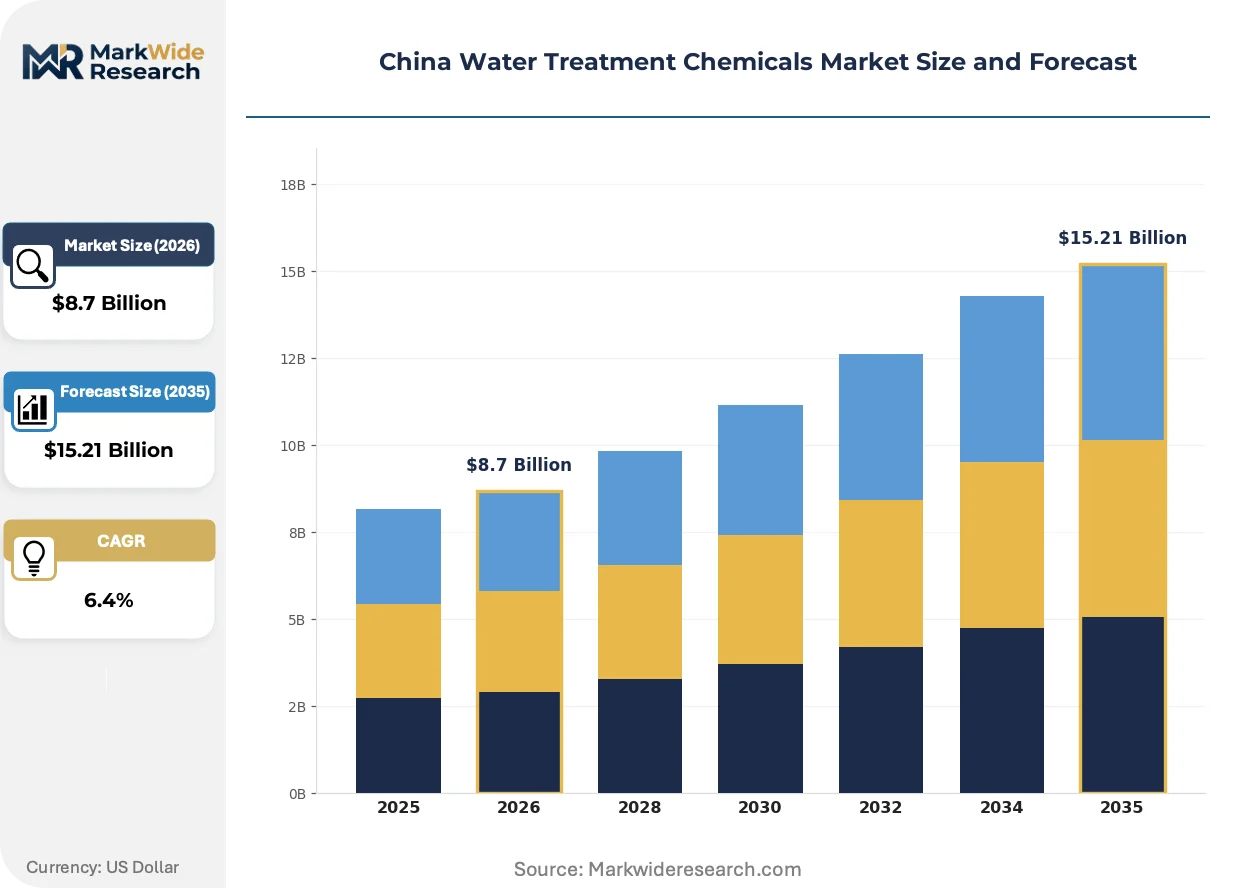
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coagulants, Flocculants, Disinfectants, pH Adjusters Application: Industrial Water Treatment, Municipal Water Treatment, Pool Water Treatment, Wastewater Treatment End User: Power Generation, Oil & Gas, Manufacturing, Municipalities Distribution Channel: Direct Sales, Distributors, E-commerce, Retailers |
| Companies Covered | Kemira, Ecolab, SNF, Dow, Shandong Taihe Technologies, China National Bluestar, Nalco, Shandong IRO Water Treatment, BASF, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Water Treatment Chemicals Market Strategic Shifts
Membrane-based water treatment is displacing conventional separation methods across China's industrial and municipal sectors, reshaping chemical formulation requirements and supplier technical capabilities.
Polymer-assisted ultrafiltration is displacing alum-based coagulation in Jiangsu textile wastewater plants. Dyeing and finishing facilities are adopting high-molecular-weight flocculants to reduce sludge volumes. This displacement is compressing commodity alum margins while expanding specialty polymer premiums.
MEE's evolving discharge permit framework is tightening COD and nitrogen limits for coastal industrial zones. Chemical-intensive tertiary treatment becomes mandatory for permit renewal. Zhejiang chemical parks are responding by consolidating procurement through designated chemical service providers.
Performance-based chemical supply contracts are replacing traditional tonnage purchasing in municipal wastewater operations. Shanghai and Suzhou treatment authorities now tie supplier payments to turbidity reduction and corrosion rate benchmarks. This shift concentrates vendor selection on technical service depth rather than unit pricing.
China Water Treatment Chemicals Market Segmentation
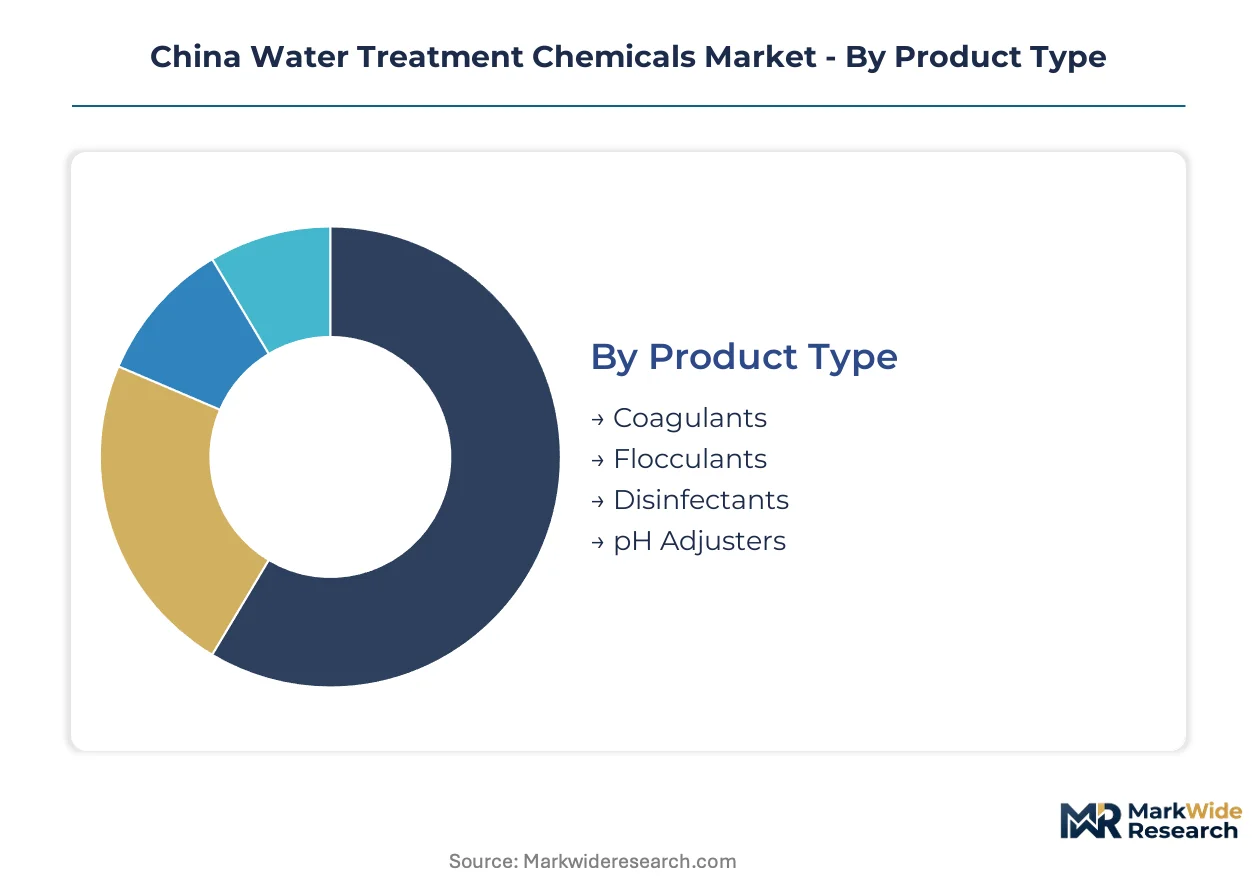
Water treatment chemicals serve distinct functional roles across China's regulatory and operational landscape. Segmentation reveals where GB standards, membrane technology adoption, and procurement centralization are reshaping demand patterns.
Product Type:
Flocculants face the most acute substitution pressure as polymer-assisted ultrafiltration displaces alum-based coagulation in Jiangsu textile plants.
- Coagulants:Aluminum sulfate and ferric chloride formulations precipitate suspended solids through charge neutralization. Municipal plants in Zhejiang chemical parks are consolidating procurement through designated service providers, compressing spot-market volumes.
- Flocculants:Polyacrylamide chains with molecular weights exceeding 10 million Da bridge fine particles into settleable flocs. Shandong's captive polymer production clusters control cost structures for high-molecular-weight grades serving tertiary wastewater expansion.
- Disinfectants:Chlorine-based residuals face UV and ozone substitution in municipal drinking water contracts.
- pH Adjusters:Sulfuric acid and caustic soda sustain steady demand from Shandong power plants managing boiler alkalinity.
Coagulants anchor the volume base while flocculants gain share at the steepest rate.
Application:
Cost tier stratification separates commodity municipal contracts from premium industrial membrane-compatible formulations.
- Industrial Water Treatment:Reverse osmosis proliferation in eastern coastal clusters demands zwitterionic dispersants and specialized antiscalants with pharmaceutical-grade purity specifications.
- Municipal Water Treatment:GB standards tightening for reclaimed water quality forces Jiangsu and Zhejiang plants to upgrade from secondary to tertiary processes, triggering coagulant and antiscalant procurement waves.
- Pool Water Treatment:Residential and commercial aquatic facilities use stabilized chlorine and algaecide maintenance programs.
- Wastewater Treatment:MEE discharge permit tightening for COD and nitrogen limits makes chemical-intensive tertiary treatment mandatory for coastal industrial zone permit renewal.
Municipal water treatment commands the largest absolute spend while industrial water treatment expands most quickly.
End User:
Customer type concentration determines whether procurement flows through centralized tenders or direct technical service relationships.
- Power Generation:Coal and nuclear plants in Shandong sustain pH adjuster consumption for boiler feedwater chemistry control.
- Oil & Gas:Produced water treatment and enhanced oil recovery operations use high-salinity-tolerant flocculant formulations.
- Manufacturing:Biologics facilities require ultrapure water chemistry, opening premium tiers for membrane-compatible chemistries.
- Municipalities:Shanghai and Suzhou treatment authorities now tie supplier payments to turbidity reduction and corrosion rate benchmarks, concentrating selection on technical service depth.
Municipalities anchor procurement volumes while manufacturing climbs the fastest on pharmaceutical-grade specifications.
Distribution Channel:
Supply concentration in Shandong production clusters shapes channel economics and environmental compliance vulnerability.
- Direct Sales:Performance-based contracts with municipal wastewater operators require embedded technical service teams for dosing optimization.
- Distributors:Regional chemical service providers consolidate procurement for Zhejiang chemical parks under MEE compliance pressure.
- E-commerce:Standardized commodity grades for small industrial accounts move through digital platforms with transparent pricing.
- Retailers:Pool maintenance chemicals reach residential end users through building materials and specialty store networks.
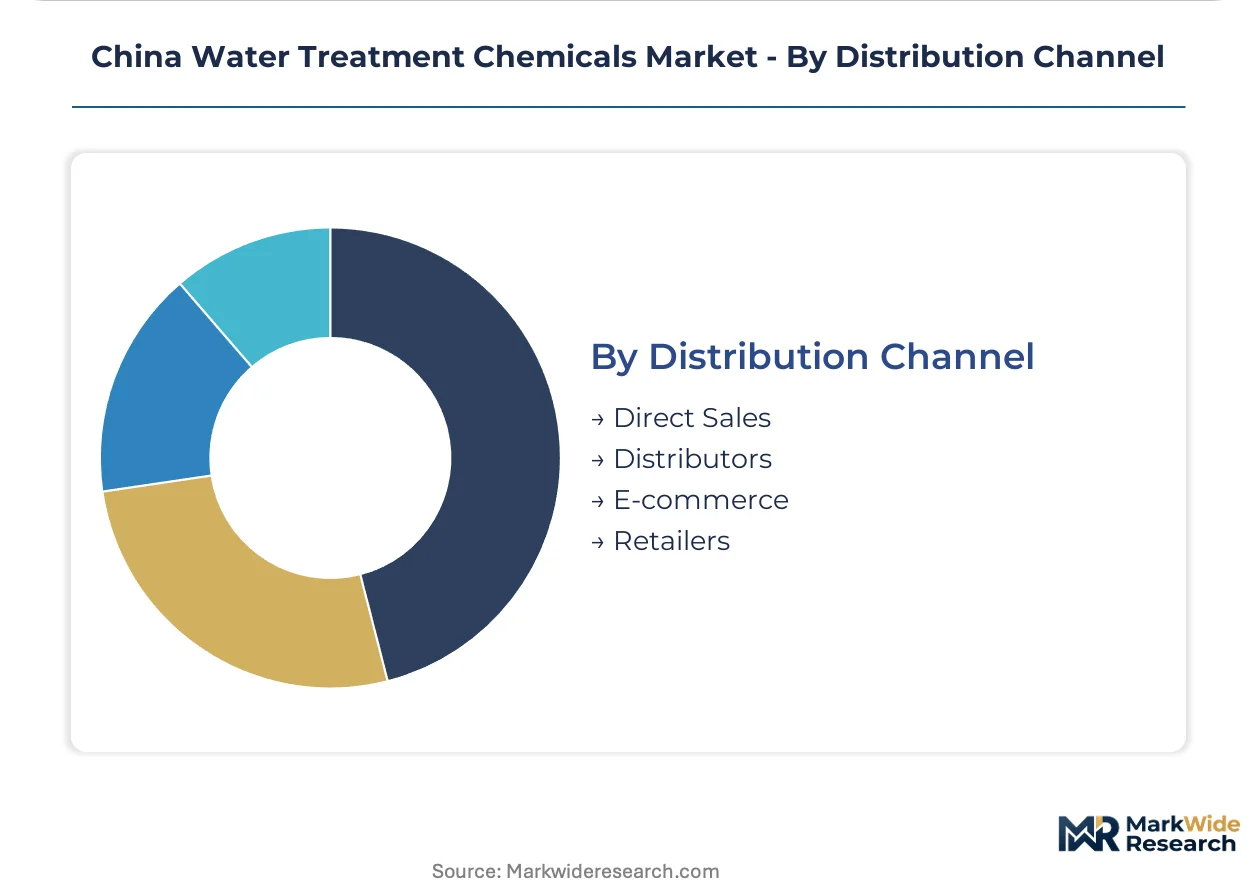
Direct sales capture the highest-value contracts while distributors gain share fastest through chemical park consolidation mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in eastern coastal provinces demonstrate the lowest price elasticity for membrane-compatible specialty chemicals, while inland municipal operators remain highly sensitive to unit dosing costs. This demand-elasticity contrast shapes supplier prioritization and regional investment sequencing.
Jiangsu Province
Textile dyeing and finishing facilities drive specialty flocculant consumption as polymer-assisted ultrafiltration displaces alum-based coagulation. MEE discharge permit tightening for COD limits forces tertiary treatment upgrades. Suzhou and Wuxi industrial clusters are consolidating procurement through designated chemical service providers.
Zhejiang Province
Chemical parks and pharmaceutical manufacturing sustain demand for high-purity antiscalants and zwitterionic dispersants. GB standards tightening for reclaimed water quality triggers secondary-to-tertiary process conversions. Ningbo and Hangzhou treatment authorities now tie supplier payments to turbidity reduction benchmarks.
Shandong Province
Coal and nuclear power plants anchor steady pH adjuster consumption for boiler feedwater alkalinity control. Dual carbon goals policy accelerates adoption of low-carbon chemical synthesis routes for flocculant production. Qingdao and Weihai polymer production clusters control cost structures through captive renewable energy integration.
Sichuan Province
Municipal networks lag eastern benchmarks in tertiary treatment deployment, creating first-mover expansion corridors for technical service-oriented suppliers. Provincial environmental bureaus are aligning with national GB standards under MEE framework evolution. Chengdu metro area is piloting performance-based chemical supply contracts.
Guangdong Province
Electronics manufacturing and biologics facilities drive pharmaceutical-grade boiler feedwater specifications for ultrapure water chemistry. Reverse osmosis proliferation in Shenzhen and Dongguan industrial zones expands demand for membrane-compatible antiscalants. SAMR drinking water contact approvals extend certification timelines for new product launches.
China Water Treatment Chemicals Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the China Water Treatment Chemicals Market. Integrated polymer producers with captive acrylamide supply dominate cost positions for high-molecular-weight flocculants, while specialty formulators with membrane-compatibility expertise command premium pricing in power generation and pharmaceutical end uses. Three archetypes define competitive positioning: Shandong-based integrated manufacturers, multinational technology licensors, and regional technical service specialists. Capacity expansion and backward integration into monomer production represent the dominant competitive moves.
Within the integrated manufacturing tier, Kemira and Shandong Taihe Technologies occupy positions shaped by proximity to polymer production clusters. Kemira leverages its Shandong manufacturing presence to control raw material cost structures. Shandong Taihe Technologies exemplifies the narrow technical specialist archetype focused on zwitterionic dispersant formulations. BASF anchors the multinational technology licensor position through membrane-compatible antiscalant expertise.
| Leading Market Players |
|---|
| Kemira |
| Ecolab |
| SNF |
| Dow |
| Shandong Taihe Technologies |
| China National Bluestar |
| Nalco |
| Shandong IRO Water Treatment |
| BASF |
| Others |
Value Chain & Pricing Dynamics
Performance-based chemical supply contracts lock in multi-year procurement relationships between Jiangsu municipal treatment authorities and technical service-oriented suppliers, anchoring both supply access and price visibility against volatile acrylamide monomer markets.
Pricing Analysis
GB standards issued by SAMR dictate the pricing tier structure across China's water treatment chemicals landscape. Three-tier pricing stratifies across pharmaceutical-grade membrane-compatible formulations, industrial-standard tertiary treatment chemicals, and commodity alum-based coagulants for secondary processes. Pricing pressure stems from acrylamide monomer cost volatility squeezing non-integrated compounders, while municipal buyers in eastern coastal provinces demonstrate the lowest price sensitivity for specialty grades.
Supply Chain Analysis
Shandong and Jiangsu provinces anchor polymer synthesis and flocculant formulation for China's water treatment chemicals sector. Production draws from propylene feedstock streams and captive renewable energy integration under dual carbon goals compliance. Single-source vulnerability concentrates around Shandong environmental compliance shutdowns. Distribution runs through designated chemical service providers consolidating Zhejiang chemical park procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must navigate UV and ozone disinfection substitution threatening residual chlorine disinfectant volumes in municipal drinking water contracts.
For Market Incumbents: Consolidate procurement relationships with Jiangsu and Zhejiang municipal authorities through embedded technical service teams for dosing optimization. Deepen backward integration into acrylamide monomer production to defend margin position against propylene feedstock volatility. Prioritize SAMR drinking water contact certification investment to maintain premium tier access. For New Entrants and Emerging Players: SAMR certification fast-track programs offer expedited pathways for membrane-compatible antiscalant formulations targeting biologics manufacturing facilities. Sichuan and Shaanxi municipal networks present first-mover expansion corridors with lagging tertiary treatment deployment. Lead with performance-based contract structures tying payments to turbidity reduction benchmarks. For Investors and Strategic Acquirers: Capital is best deployed toward technical service specialists with established SAMR certifications and embedded municipal relationships across the analysis window. Target acquisition archetypes combine Shandong polymer production proximity with western province distribution reach. Monitor MEE discharge permit tightening cadence as inflection indicator for reformulation cycle intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylamide Monomer | Captive propylene feedstock control insulates margins from petrochemical volatility. |
| SAMR Drinking Water Contact Certification | GB standards compliance unlocks premium municipal procurement tiers. |
| Western Province Distribution Buildout | Sichuan and Shaanxi underpenetration offers first-mover technical service positioning. |
| Performance-Based Contract Conversion | Turbidity reduction benchmarks concentrate vendor selection on service depth. |
| Green Manufacturing Transition | Dual carbon goals policy favors suppliers with captive renewable energy integration. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with municipal treatment plant managers, chemical procurement leads at Zhejiang industrial parks, polymer synthesis technicians, and technical service directors. Secondary validation drew from MEE discharge permit databases, SAMR GB standards filings, customs trade data for acrylamide imports, and provincial environmental bureau reports. Bottom-up volume estimates triangulated against top-down market sizing.
Across the analysis window, forecasts modeled product type segmentation by grade tier, application by end-use industry, and regional production hub concentration. CAGRs were derived from historical trajectory analysis adjusted for policy inflection points including dual carbon goals acceleration and GB standards tightening. Key inputs included MEE permit issuance rates, Shandong polymer capacity utilization, and municipal tertiary treatment capex pipelines.
Decision-makers should treat outputs as directional under base assumptions of continued MEE enforcement intensity and SAMR certification timeline stability; material deviation in provincial environmental bureau alignment would warrant model refresh. Recalibration cycles align with material shifts in GB standards revision schedules and dual carbon goals implementation cadence.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Global Wood Activated Carbon Market
Water & Sludge Treatment
CMP Slurry Blend and Delivery Systems Market
Water & Sludge Treatment
Mexico Water Treatment Chemicals Market
Water & Sludge Treatment
North America Industrial Water Treatment Market
Water & Sludge Treatment
South America Membrane Water and Wastewater (WWT) Treatment Market
Water & Sludge Treatment
Global Electrodeionization Market
Water & Sludge Treatment
Enzymes for Water Treatment Market
Water & Sludge Treatment
Semiconductor Wastewater Treatment Market
Water & Sludge Treatment
US Water and Wastewater Treatment Market
Water & Sludge Treatment
Swimming Pool Treatment Chemicals Market
Water & Sludge Treatment
Slurry Homogenizer Tank Market
Water & Sludge Treatment
Global Wet Waste Management Market
Water & Sludge Treatment
Flocculants Market
Water & Sludge Treatment
Aquarium Water Treatment Market
Water & Sludge Treatment
Drinking Water Adsorbents Market
Water & Sludge Treatment
Water Purification Systems Market