
 Sludge Treatment and Disposal Equipment Market | 2026-2036
Sludge Treatment and Disposal Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Sludge Treatment and Disposal Equipment Market Analysis
Modular skid-mounted dewatering packages is shifting procurement patterns across municipal and industrial buyers, reducing on-site construction complexity and accelerating commissioning timelines. HUBER SE leverages its integrated manufacturing footprint in Germany to control component sourcing for these pre-assembled systems. Alfa Laval competes through thermal and separation technology leadership, sustaining R&D intensity in high-solids decanter designs. Veolia Water Technologies anchors its position through long-term service contracts bundled with equipment supply, extending revenue visibility beyond initial capital expenditure.
Sludge treatment and disposal equipment encompasses mechanical, thermal, and biological systems engineered to reduce water content, stabilize organic matter, and enable compliant discharge or beneficial reuse of residual solids from wastewater streams. Centrifugal decanters typically achieve dry solids concentrations of 18-25 percent, while filter presses can reach 40-50 percent cake dryness depending on polymer conditioning and feed characteristics. Thickener and decanter configurations command the largest installed base within product type categories, though thermal treatment technology represents the fastest-expanding margin pool as energy recovery economics improve. Anaerobic digestion dominates technology selection for municipal end users seeking biogas capture, while chemical treatment retains niche strength in industrial facilities handling heavy metal-laden metalworking or mining sludges.
EPA biosolids regulations under 40 CFR Part 503 shape pathogen reduction and land application standards across United States installations, directly influencing technology selection and operational compliance costs. EU Urban Wastewater Treatment Directive revisions and REACH chemical restrictions on polymer flocculants are tightening discharge limits and material specifications in parallel across European member states. Japan's METI enforces thermal recycling quotas and landfill diversion targets that redirect industrial sludge toward incineration and cement kiln co-processing. Stakeholders must weigh capital intensity against regulatory trajectory when selecting between biological stabilization and thermal destruction pathways.
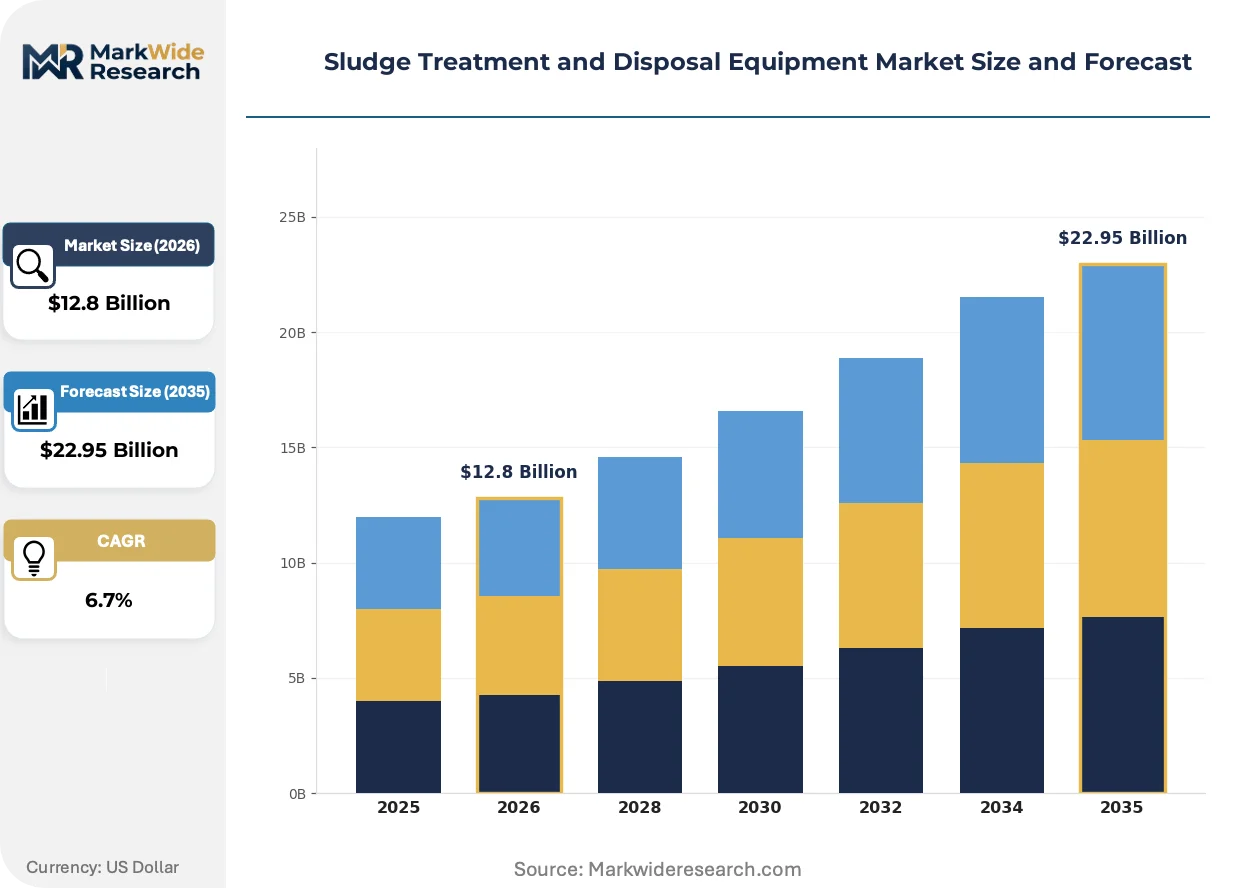
Market Dynamics
Modular skid-mounted dewatering packages are compressing project timelines and redrawing procurement criteria across municipal and industrial buyers, forcing incumbent suppliers to reconfigure assembly footprints and service bundling.
Growth Catalysts
- EU Urban Wastewater Treatment Directive enforcement:Tightened biosolids discharge limits in Germany and France are accelerating anaerobic digestion retrofits at municipal wastewater facilities.
- Industrial cluster concentration in Japan:METI circular economy mandates and landfill scarcity are pushing metalworking and chemical plants toward thermal treatment and cement kiln co-processing.
- High-solids decanter advancement:Improved centrifuge designs achieving 25 percent dry solids are expanding addressable feedstock ranges for energy recovery applications.
Market Restraints
- Polymer flocculant cost volatility:REACH chemical restrictions on acrylamide-based conditioning agents are squeezing operational margins for mechanical dewatering operators.
- Component supply concentration:Precision-manufactured scroll and bowl assemblies for decanters remain concentrated among German and Swiss machining specialists.
- Incineration air emission thresholds:Japan's thermal recycling quotas impose capital-intensive flue gas treatment that blocks smaller industrial generators from compliance.
Strategic Opportunities
- Digestate dewatering aftermarket:Expanding biogas capacity in Denmark and the Netherlands is creating installed base service contracts for secondary thickening and phosphorus recovery.
- Mobile rental fleet deployment:Construction and mining sludge in Australia is shifting toward short-term equipment leasing to avoid stranded asset risk on remote projects.
- Pyrolysis-gasification convergence:Combined thermal oxidation and syngas capture systems are opening alternative revenue streams from industrial sludge destruction.
Industry Challenges
- Process control engineering scarcity:Automated polymer dosing and centrifuge torque optimization require specialized technicians that outpace vocational training pipeline output.
- 40 CFR Part 503 pathogen certification timelines:EPA Class A biosolids validation extends commissioning schedules and delays revenue recognition for US municipal contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sludge Treatment and Disposal Equipment Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thickeners, Decanters, Filter Presses, Pumps Technology: Aerobic Digestion, Anaerobic Digestion, Thermal Treatment, Chemical Treatment End User: Wastewater Treatment Plants, Industrial Facilities, Municipalities, Agricultural Sector Application: Water Recovery, Bioenergy Production, Composting, Fertilizer Production |
| Companies Covered | HUBER SE, Flottweg SE, Alfa Laval, Phoenix Process Equipment, Komline-Sanderson, ANDRITZ, Evoqua Water Technologies, Kurita Water Industries, Veolia Water Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sludge Treatment and Disposal Equipment Market Emerging Trajectories
Equipment miniaturization, regulatory chemistry restrictions, and outcome-based contracting are converging to compress capital deployment cycles and restructure vendor-customer relationships across treatment pathways.
Membrane thickening technology is overtaking gravity-based alternatives in space-constrained European installations. Municipal utilities in the Netherlands and Belgium are specifying submerged membrane modules for primary sludge concentration. This shift is compressing footprint requirements by half while elevating energy demand specifications in tender documents.
REACH polymer flocculant restrictions are forcing reformulation investments across European chemical conditioning supply chains. Cationic polymer specifications for belt press and centrifuge operations now face substitution audits under ECHA substance evaluation protocols. German equipment suppliers are responding with vendor-managed inventory contracts that bundle chemical supply with mechanical service agreements.
Performance-guaranteed dewatering contracts are displacing traditional capital purchase models in Scandinavian municipal markets. Danish and Swedish wastewater utilities now specify cake dryness outcomes rather than equipment technical parameters in procurement documents. This transfer of operational risk to OEMs is visible most acutely in framework agreements covering ten-year service horizons.
Sludge Treatment and Disposal Equipment Market Segmentation
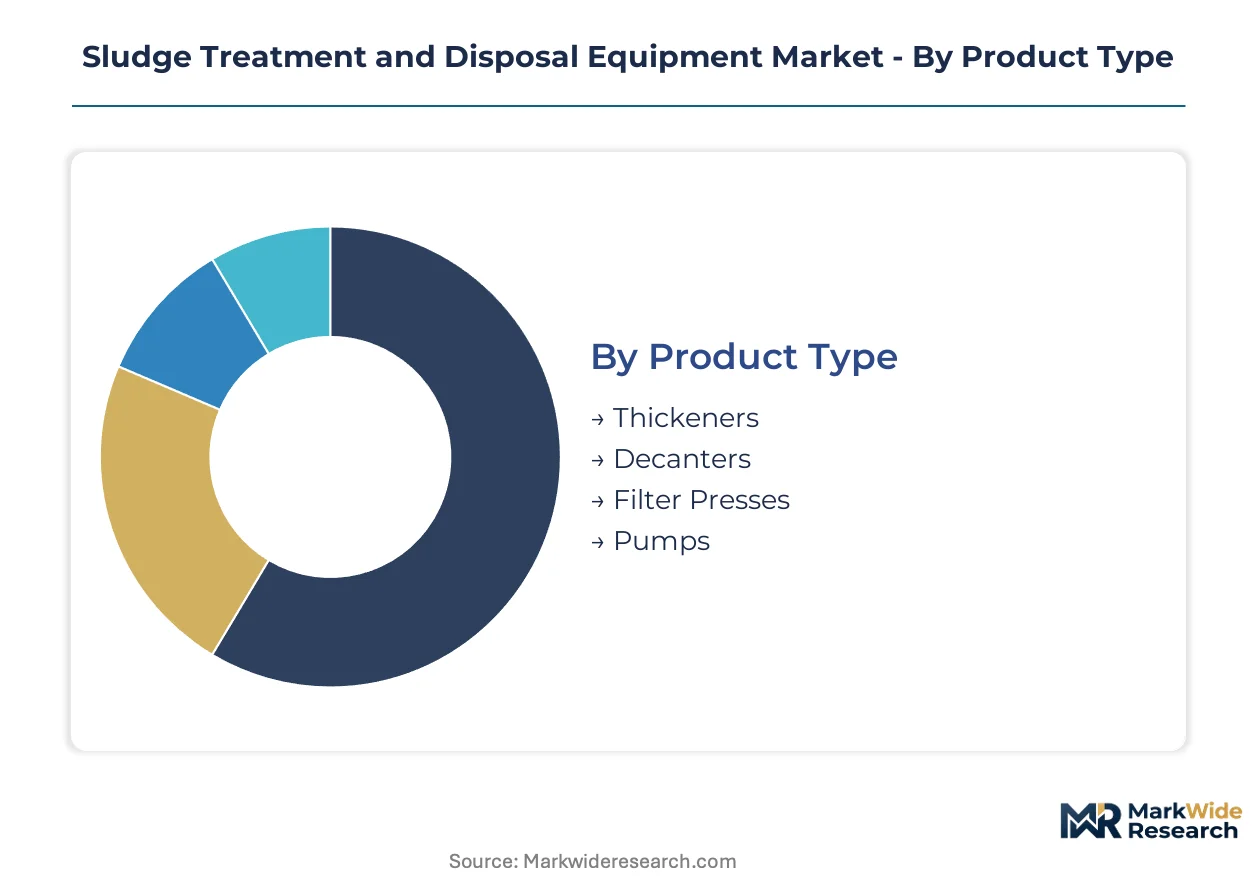
Equipment selection in sludge treatment hinges on feedstock characteristics, regulatory discharge limits, and capital recovery timelines. Procurement patterns diverge sharply between municipal utilities prioritizing biogas capture and industrial operators seeking volume reduction for hazardous waste compliance.
Product Type:
Buyers weigh footprint constraints against dry solids targets when specifying mechanical dewatering equipment.
- Thickeners:Gravity and dissolved air flotation configurations concentrate sludge to 4-8 percent solids upstream of dewatering stages. Dutch and Belgian utilities specify submerged membrane thickeners to halve installation footprints despite elevated energy demand.
- Decanters:Horizontal centrifugal designs with scroll conveyors achieve 18-25 percent dry solids through differential speed control. German machining specialists dominate precision scroll and bowl assembly supply, creating procurement concentration risk for operators.
- Filter Presses:Chamber and membrane plate configurations reach 40-50 percent cake dryness with optimized polymer conditioning.
- Pumps:Progressive cavity and piston designs handle high-viscosity thickened sludge with minimal shear degradation.
Volume sits with decanters; growth tilts toward filter presses.
Technology:
Regulatory trajectory determines technology adoption more than capital cost differentials.
- Aerobic Digestion:Open tank and pure oxygen systems stabilize organic matter through extended detention, producing Class B biosolids suitable for land application where EPA 40 CFR Part 503 permits. US municipal utilities favor this pathway for operational simplicity despite higher energy intensity than anaerobic alternatives.
- Anaerobic Digestion:Mesophilic and thermophilic configurations capture biogas for combined heat and power while reducing volatile solids by 40-60 percent. EU Urban Wastewater Treatment Directive enforcement is accelerating retrofits across German and French wastewater facilities.
- Thermal Treatment:Fluidized bed incineration and pyrolysis-gasification systems destroy organic contaminants while enabling phosphorus recovery from ash.
- Chemical Treatment:Acid digestion and alkaline stabilization retain niche strength for heavy metal-laden industrial sludges from metalworking and mining operations.
Installed base concentrates in anaerobic digestion; thermal treatment climbs the fastest.
End User:
Contracting structures and compliance horizons diverge across customer archetypes.
- Wastewater Treatment Plants:Large-scale facilities processing mixed municipal-industrial flows specify integrated thickening-dewatering-digestion trains with decade-long service bundling.
- Industrial Facilities:Chemical, food processing, and pulp and paper plants prioritize volume reduction for hazardous waste cost avoidance.
- Municipalities:Smaller utilities under 50,000 population equivalents favor skid-mounted packages to compress commissioning timelines and limit specialized staffing requirements.
- Agricultural Sector:Dairy and livestock operations deploy anaerobic digesters with on-farm biogas utilization, though equipment scale sits below industrial thresholds.
Capital deployment concentrates with wastewater treatment plants; agricultural uptake expands most quickly.
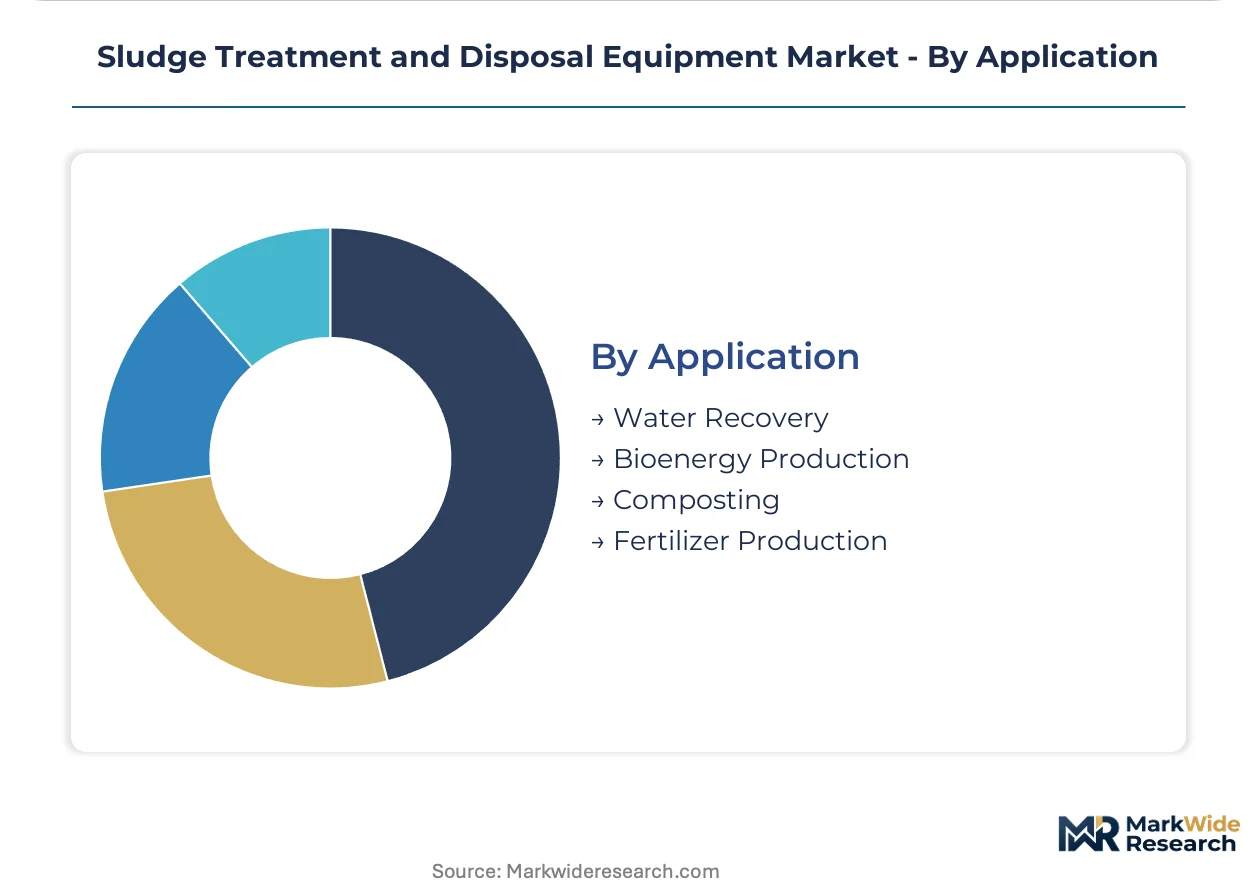
Application:
Revenue model innovation is restructuring vendor relationships around guaranteed outcomes rather than equipment specifications.
- Water Recovery:Centrate and filtrate return to headworks reduces freshwater intake and effluent discharge volumes. Scandinavian utilities now specify cake dryness outcomes in procurement documents, transferring operational risk to OEMs through ten-year framework agreements.
- Bioenergy Production:Biogas upgrading to biomethane or combined heat and power improves project economics. Danish and Dutch digestate dewatering aftermarket is creating installed base service contracts for secondary thickening and phosphorus recovery.
- Composting:Dewatered cake blending with carbon sources produces Class A biosolids for horticultural and soil amendment markets.
- Fertilizer Production:Struvite precipitation and ash phosphorus extraction closes nutrient loops for agricultural reuse.
Water recovery dominates current deployment; bioenergy production shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates precision component manufacturing for decanter assemblies while Japan and the United States drive thermal treatment adoption. Equipment demand patterns diverge sharply between EU biogas expansion and Asia-Pacific landfill diversion mandates.
Germany
Municipal utilities in North Rhine-Westphalia and Bavaria are expanding anaerobic digestion trains under tightened EU Urban Wastewater Treatment Directive enforcement. The country's national environmental regulator is accelerating biosolids discharge limit compliance timelines through 2027. Stuttgart and Munich industrial clusters anchor precision machining supply for scroll and bowl assemblies serving European decanter operators.
Japan
Metalworking plants in the Chubu region and chemical facilities in Kansai are redirecting sludge toward cement kiln co-processing amid acute landfill scarcity. METI circular economy mandates enforce thermal recycling quotas that block conventional disposal pathways. Osaka and Nagoya industrial zones concentrate fluidized bed incineration capacity for energy recovery applications.
United States
Large-scale wastewater treatment facilities in California and Texas favor aerobic digestion for operational simplicity despite higher energy intensity. EPA biosolids regulations under 40 CFR Part 503 extend pathogen certification timelines that delay municipal contract commissioning. The Great Lakes industrial corridor maintains chemical treatment niche strength for heavy metal-laden metalworking sludges.
Netherlands
Submerged membrane thickeners are displacing gravity-based alternatives across Randstad municipal utilities seeking footprint compression. ECHA substance evaluation protocols under REACH are forcing polymer flocculant reformulation audits for belt press operations. The Rotterdam-The Hague metropolitan cluster leads digestate dewatering aftermarket development for phosphorus recovery service contracts.
Australia
Construction and mining operations in Western Australia and Queensland are shifting toward mobile rental fleets to avoid stranded asset risk on remote projects. The country's national environmental protection framework imposes hazardous waste transport restrictions that elevate on-site volume reduction economics. Perth and Brisbane equipment depots anchor short-term leasing networks for dewatering package deployment.
Sludge Treatment and Disposal Equipment Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across equipment categories. The vendor base organizes into three tiers: integrated environmental service providers bundling long-term contracts, precision machining specialists controlling critical decanter components, and regional fabricators supplying skid-mounted packages. Consolidation pressure concentrates in membrane thickening and thermal treatment segments where technology licensing accelerates capability acquisition. Geographic expansion and outcome-based contracting represent the dominant competitive vectors reshaping vendor-customer relationships.
Among German-based precision manufacturers, HUBER SE and Flottweg SE exemplify the component-integrated archetype controlling scroll and bowl assembly supply chains. Alfa Laval occupies a position representing Nordic thermal and separation technology leadership. Veolia Water Technologies anchors the service-bundling tier through long-term framework agreements extending revenue visibility beyond initial capital expenditure. These three entities collectively illustrate the strategic divergence between manufacturing depth and service integration.
| Leading Market Players |
|---|
| HUBER SE |
| Flottweg SE |
| Alfa Laval |
| Phoenix Process Equipment |
| Komline-Sanderson |
| ANDRITZ |
| Evoqua Water Technologies |
| Kurita Water Industries |
| Veolia Water Technologies |
| Others |
Supply Flow & Price Mechanics
Precision machining specialists in southern Germany command wage premiums that propagate through three-tier pricing structures separating premium decanter assemblies from standard skid packages and economy-grade thickeners. Labor-cost differentials between Bavarian manufacturing clusters and Eastern European fabrication hubs widen spreads across equipment categories.
Pricing Analysis
Margin tightening in standard-tier equipment reflects REACH polymer flocculant reformulation costs passed through chemical conditioning supply chains. Three-tier pricing structure across premium, standard, and economy levels stratifies by dry solids performance certification and bundled service horizons. Municipal utilities under 50,000 population equivalents exhibit acute price sensitivity, while integrated wastewater treatment plants prioritize guaranteed cake dryness outcomes over capital expenditure minimization.
Supply Chain Analysis
Freight cost escalation on precision scroll and bowl assemblies from Stuttgart and Munich machining centers elevates landed costs for North American and Asia-Pacific operators. Component supply concentrates in Germany and Switzerland for decanter assemblies, with polymer flocculant feedstocks drawing from Belgian and Dutch chemical manufacturers. Single-source vulnerability in precision-machined rotating assemblies creates procurement concentration risk. Distribution runs through OEM direct sales for large municipal contracts and regional equipment distributors for skid-mounted packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
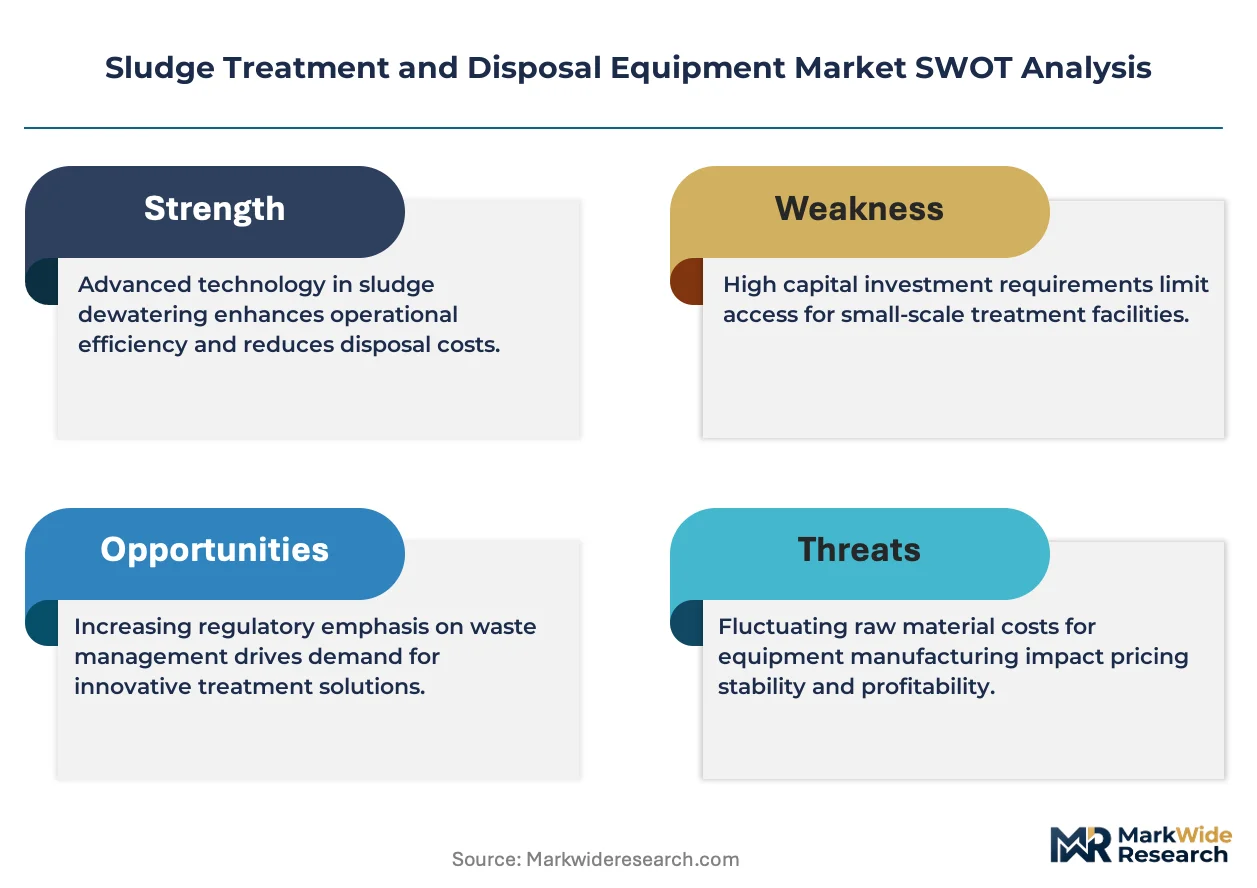
Specialized process control engineers for automated polymer dosing and centrifuge torque optimization represent the binding capacity constraint sustaining pricing power across equipment tiers.
For Market Incumbents: Anticipate pyrolysis-gasification technology licensing from European specialists eroding thermal treatment margins, and respond through backward integration into precision scroll machining capacity in Bavaria plus ten-year service contract extensions that lock municipal revenue visibility. For New Entrants and Emerging Players: Australian mining and construction operators seeking mobile rental fleets present the most penetrable buyer archetype, with short-term leasing models avoiding stranded asset risk on remote projects offering a service-based entry angle distinct from capital equipment sales. For Investors and Strategic Acquirers: The window for entry favors membrane thickening technology specialists with submerged module IP, as Randstad municipal specifications displace gravity-based alternatives; watch for ECHA substance evaluation protocol expansions triggering polymer flocculant substitution demand as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Machining | Captive supply of scroll and bowl assemblies insulates German OEMs from component procurement concentration risk. |
| Performance-Guaranteed Service Contracting | Danish and Swedish utilities now specify cake dryness outcomes rather than equipment technical parameters. |
| Mobile Rental Fleet Deployment | Western Australian mining operators avoid stranded asset risk through short-term dewatering package leasing. |
| Digestate Dewatering Aftermarket Expansion | Biogas capacity growth in Denmark and Netherlands creates installed base service contracts for phosphorus recovery. |
| Pyrolysis-Gasification Technology Licensing | Combined thermal oxidation and syngas capture systems open alternative revenue streams from industrial sludge destruction. |
Methodological Framework
Multi-period observation of anaerobic digestion retrofit timelines, polymer flocculant price indices, and membrane thickener installation rates anchored the trend analysis, supplemented by interviews with wastewater treatment plant engineers, municipal procurement officers, precision machining plant managers, polymer chemical formulators, and aftermarket service directors. Secondary validation drew from EPA 40 CFR Part 503 enforcement data, EU Urban Wastewater Treatment Directive implementation reports, METI circular economy mandate disclosures, and customs records of decanter component trade. Bottom-up equipment shipment tracking and top-down utility capital expenditure surveys were triangulated to verify volume estimates.
The input-output matrix connected feedstock characteristics, regulatory discharge limits, and capital recovery timelines across product type, technology, end user, and application dimensions. CAGRs were derived from regression analysis of historical deployment rates against enforcement milestone schedules. Industry-specific forecast inputs included biogas capacity expansion pipelines and REACH chemical restriction phase-in calendars.
Revisions become necessary when EU Urban Wastewater Treatment Directive enforcement timelines accelerate, polymer flocculant substitution protocols expand, or precision machining capacity constraints ease. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Water Purification Systems Market
Water & Sludge Treatment
Drinking Water Adsorbents Market
Water & Sludge Treatment
Sludge Heater Market
Water & Sludge Treatment
North America Boiler Water Treatment Chemicals Market
Water & Sludge Treatment
Liquid Waste Container Market
Water & Sludge Treatment
North America Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Produced Water Treatment Market
Water & Sludge Treatment
United Kingdom Water Treatment Chemicals Market
Water & Sludge Treatment
Australia Water Treatment Chemicals Market
Water & Sludge Treatment
Enzymes for Water Treatment Market
Water & Sludge Treatment
US Water and Wastewater Treatment Market
Water & Sludge Treatment
Alkalinity Control Chemicals Market
Water & Sludge Treatment
Water Treatment Market
Water & Sludge Treatment
Global Wood Activated Carbon Market
Water & Sludge Treatment
Flocculants Market
Water & Sludge Treatment
Process Chemicals for Water Treatment Market