
 Australia & New Zealand Water Treatment Chemicals Market | 2026-2036
Australia & New Zealand Water Treatment Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Australia & New Zealand Water Treatment Chemicals Market Insights
Municipal procurement is collapsing toward larger consolidated contracts as Australian water utilities merge operations and centralize chemical buying. Ixom leverages its domestic manufacturing footprint to anchor supply contracts across eastern seaboard utilities. Kemira Oyj competes through specialized coagulant formulations tailored to high-turbidity source waters. Ecolab differentiates with integrated service models combining chemical delivery with monitoring equipment.
Water treatment chemicals encompass coagulants, disinfectants, pH adjusters, and corrosion inhibitors formulated for purification, disinfection, and system protection across municipal and industrial infrastructure. These formulations typically operate within specified dosage ranges measured in parts per million to achieve regulatory compliance while minimizing residual by-products. Coagulants dominate product type revenue due to universal application in sediment removal, while corrosion inhibitors represent the fastest-expanding category as aging pipeline networks require chemical preservation. Among end users, municipal systems occupy the largest volume share though industrial process water generates superior margins through customized technical service requirements.
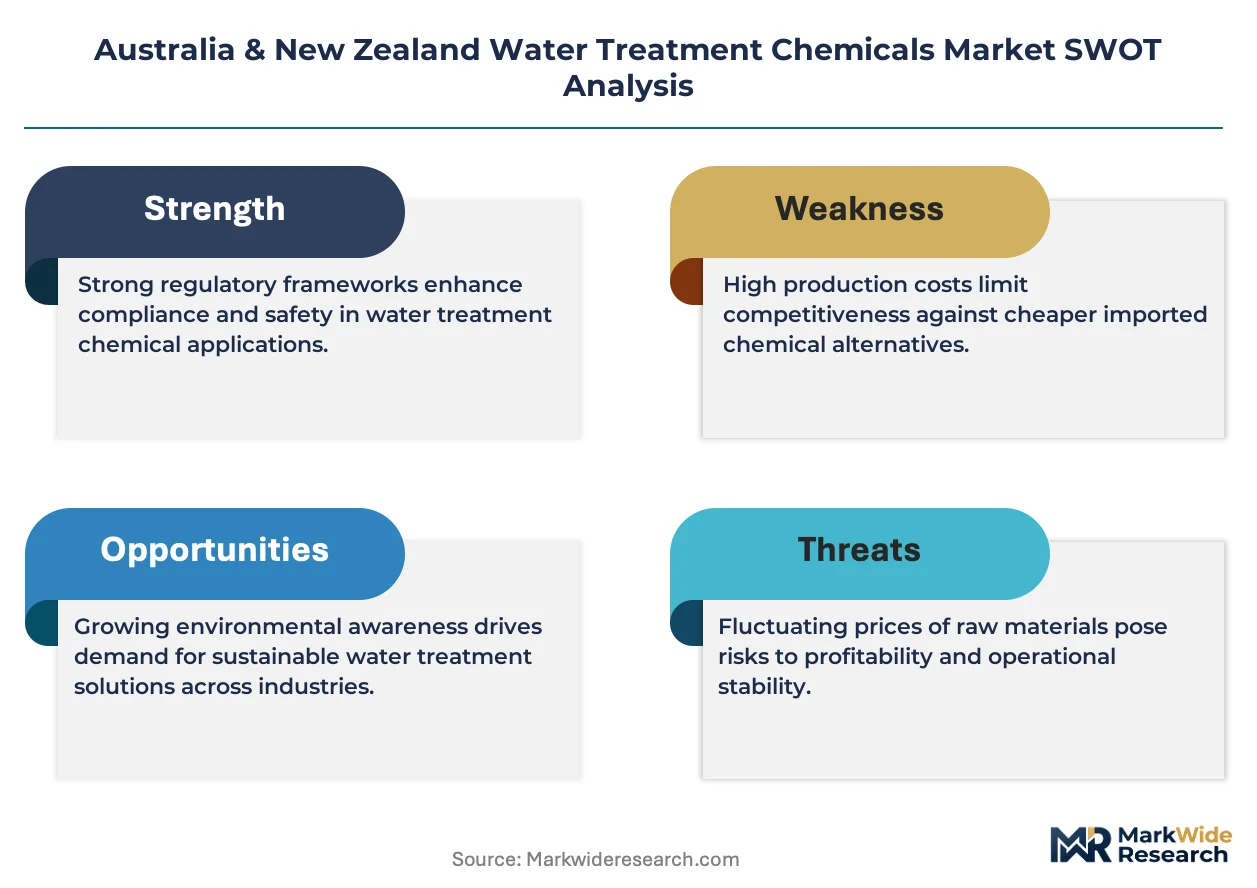
Australia's National Water Quality Management Strategy and New Zealand's Taumata Arowai drinking water regulator shape product registration, dosing protocols, and residual limits across both jurisdictions. The Resource Management Act and Australian Drinking Water Guidelines together force utilities toward higher-performance chemistries that reduce disinfection by-product formation. Stakeholders must monitor evolving PFAS restrictions and their downstream impact on fluoropolymer-based membrane compatibility and alternative chemical selection criteria.
Market Dynamics
Municipal water utilities across Australia and New Zealand are consolidating chemical procurement into fewer, larger contracts as operational mergers accelerate. This structural concentration is reshaping supplier relationships and pricing power across the trans-Tasman market.
Growth Catalysts
- Australian Drinking Water Guidelines:Stricter disinfection by-product limits are forcing utilities to upgrade coagulant and oxidant chemistries. Queensland's mining corridor shows the steepest procurement acceleration.
- Resource Management Act amendments:New Zealand's regional councils are tightening wastewater discharge consents. Auckland's metropolitan water network is expanding chemical dosing infrastructure to meet new nitrogen and phosphorus thresholds.
- Aging pipeline networks:Corrosion inhibitor demand is surging as both countries confront decades-old distribution infrastructure. Western Australia's Pilbara mining towns exemplify the replacement cycle urgency.
Market Restraints
- Alumina and ferric chloride feedstock volatility:Coagulant manufacturers face input cost swings tied to bauxite processing and steel by-product availability. Australian producers lack captive supply of these precursor materials.
- Domestic manufacturing concentration:Bulk chemical synthesis concentrates in eastern seaboard industrial zones. Freight costs to South Australia and Western Australia create persistent supply cost disadvantages.
- PFAS contamination liabilities:Emerging restrictions on fluoropolymer-based membrane systems are forcing premature equipment replacement. Utilities hesitate to commit to long-term chemical contracts amid regulatory uncertainty.
Strategic Opportunities
- Tasmanian municipal systems:Smaller island utilities remain underpenetrated by integrated service providers. Remote operation requirements favor suppliers with telemetry-enabled dosing systems.
- On-site chlorine dioxide generation:Transport safety regulations are pushing bulk hypochlorite users toward electrochemical cell technologies. This convergence of chemical and equipment supply opens bundled contract possibilities.
- Taumata Arowai registration pathways:New Zealand's drinking water regulator is streamlining product approval timelines. Early entrants gain preferred supplier status before procurement centralization completes.
Industry Challenges
- Certified water treatment operator scarcity:Both jurisdictions face shortages of personnel qualified under the Australian Drinking Water Guidelines and Taumata Arowai competency frameworks. Training pipeline gaps delay plant upgrades.
- Legacy SCADA integration:Automated chemical dosing systems must interface with decades-old control architectures. Retrofit complexity extends project timelines and inflates implementation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia & New Zealand Water Treatment Chemicals Market |
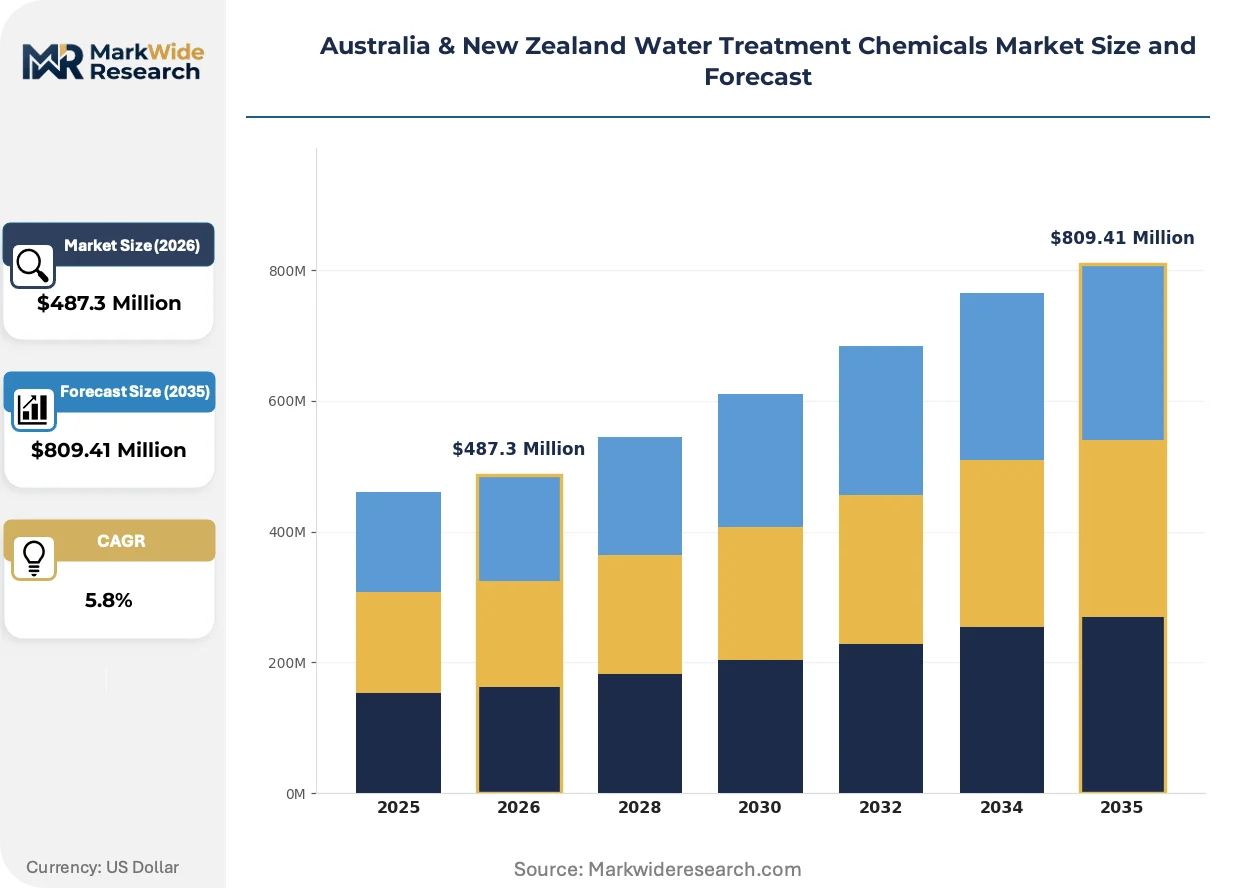
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coagulants, Disinfectants, PH Adjusters, Corrosion Inhibitors Application: Potable Water, Wastewater Treatment, Industrial Process Water, Cooling Water End User: Municipal, Industrial, Agricultural, Recreational Distribution Channel: Direct Sales, Distributors, Online Retail, Third-party Suppliers |
| Companies Covered | SNF, Albemarle Corporation, Ecolab, Veolia Water Technologies, Dow, Kemira Oyj, Ixom, Solvay, Solenis, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia & New Zealand Water Treatment Chemicals Market Trends and Innovations
Digital monitoring platforms and electrochemical generation technologies are displacing conventional bulk chemical delivery models. These shifts compress working capital cycles while raising technical service requirements across municipal and industrial accounts.
Membrane bioreactor pre-treatment chemistries are displacing traditional coagulation-flocculation sequences in high-recovery industrial water reuse applications. Mining operators in Western Australia's Goldfields region are piloting these integrated systems to reduce freshwater intake from depleted aquifers. The technology is displacing alum-based clarification in sites where brine management costs dominate operational economics.
Taumata Arowai's emerging drinking water standards are mandating enhanced pathogen monitoring and residual control protocols. Treatment plants must install continuous analyzer networks and document dose-response relationships. Small-to-medium municipal systems in New Zealand's South Island face the steepest compliance cost burden relative to ratepayer bases.
Performance-based chemical supply contracts are replacing unit-price procurement across Australian state-owned water corporations. These arrangements transfer dosing optimization risk to suppliers while locking in multi-year volume commitments. Victoria's regional water utilities have moved fastest toward this model, with metropolitan Melbourne networks now evaluating pilot implementations.
Australia & New Zealand Water Treatment Chemicals Market Segmentation
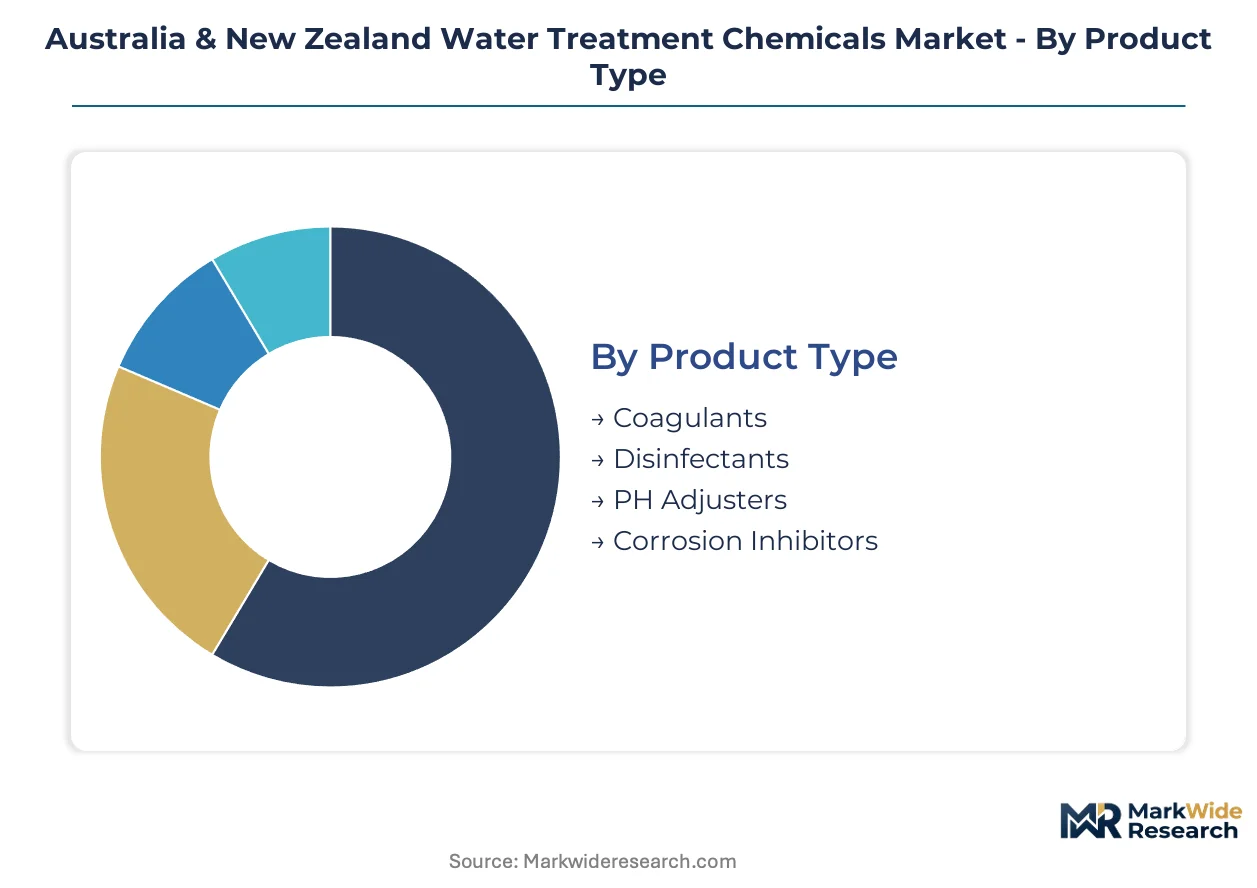
Water treatment chemical procurement patterns diver sharply across product formulations and end-use contexts in Australia and New Zealand. Regulatory thresholds under the Australian Drinking Water Guidelines and Taumata Arowai create distinct compliance burdens that reshape segment prioritization for suppliers and utilities alike.
Product Type:
Taumata Arowai's residual limit protocols and the Australian Drinking Water Guidelines' disinfection by-product caps force differentiated formulation choices across each chemistry class.
- Coagulants:Aluminum sulfate and ferric chloride formulations dominate municipal clarification trains for turbidity reduction. Queensland's mining corridor utilities are accelerating procurement of high-basicity polyaluminum chloride variants to meet stricter residual aluminum thresholds under revised guidelines.
- Corrosion Inhibitors:Phosphate-based and silicate chemistries protect aging cast-iron and asbestos-cement distribution networks. Western Australia's Pilbara mining towns exemplify urgent demand concentration as decades-old pipeline infrastructure faces replacement-cycle pressure.
- Disinfectants:Chlorine gas, sodium hypochlorite, and chlorine dioxide generators serve primary and secondary disinfection stages across municipal plants.
- PH Adjusters:Sulfuric acid, caustic soda, and lime formulations correct source water alkalinity and optimize coagulation pH windows.
Established volume favors coagulants; emerging adoption favors corrosion inhibitors.
Application:
Capital intensity and operational complexity separate high-touch industrial process water from standardized municipal applications.
- Industrial Process Water:Customized chemical programs serve mining leach circuits, food processing CIP systems, and power plant boiler feeds. Western Australia's Goldfields mining operators are piloting membrane bioreactor pre-treatment chemistries to reduce freshwater intake from depleted aquifers.
- Potable Water:Municipal treatment plants deploy coagulation, filtration, and disinfection sequences to meet Australian Drinking Water Guidelines compliance. Auckland's metropolitan water network is expanding chemical dosing infrastructure to address pathogen monitoring mandates.
- Wastewater Treatment:Nutrient removal chemistries address nitrogen and phosphorus thresholds under Resource Management Act discharge consents.
- Cooling Water:Scale inhibitors and biocides protect recirculating systems in power generation and heavy industrial facilities.
Margin concentration sits with industrial process water; volume scale sits with potable water.
End User:
Procurement centralization patterns diverge between consolidated state-owned corporations and fragmented industrial accounts.
- Municipal:State-owned water utilities in Australia and council-controlled networks in New Zealand dominate volume procurement. Victoria's regional water utilities have moved fastest toward performance-based chemical supply contracts that transfer dosing optimization risk to suppliers.
- Industrial:Mining, food processing, and power generation operators demand customized technical service and telemetry-enabled dosing systems. Remote Pilbara and Goldfields sites favor suppliers with integrated equipment-chemical bundles.
- Agricultural:Irrigation system treatment and livestock water quality management drive seasonal demand patterns.
- Recreational:Swimming pool and spa sanitation chemistries serve commercial and residential segments.
Contract duration favors municipal accounts; margin expansion favors industrial end users.
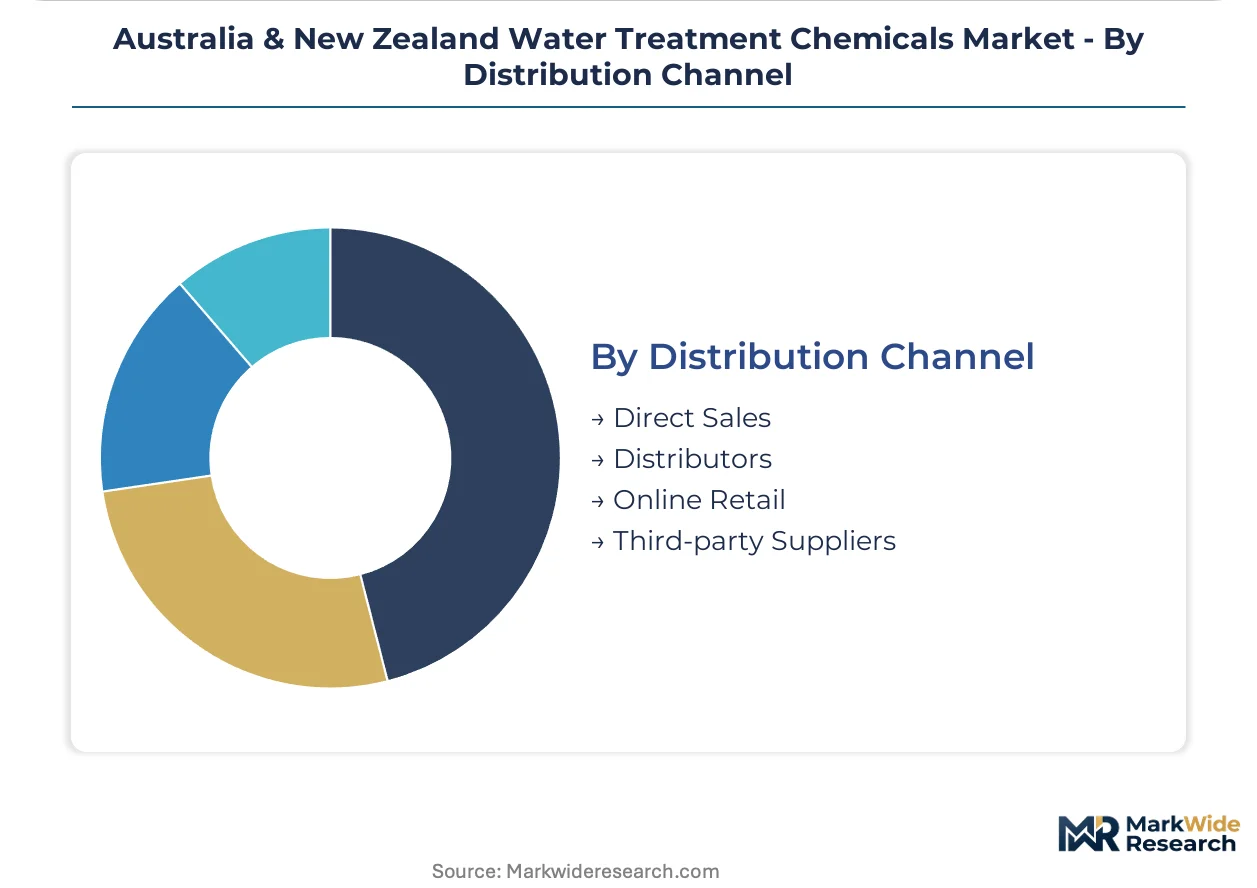
Distribution Channel:
Freight economics and technical service requirements fragment channel structure across the trans-Tasman market.
- Direct Sales:Bulk chemical manufacturers maintain dedicated account teams for major state-owned water corporations and mining houses. Eastern seaboard manufacturing concentration enables tanker-truck delivery economics to metropolitan utilities.
- Distributors:Regional chemical distributors serve smaller municipal systems and industrial accounts outside major corridors. South Australia and Western Australia face persistent supply cost disadvantages due to freight distances from synthesis centers.
- Third-party Suppliers:Integrated service providers bundle chemical delivery with monitoring equipment and technical support.
- Online Retail:Specialty chemistries and small-volume consumables move through digital procurement platforms.
Volume consolidation favors direct sales; geographic coverage favors distributor networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-owned water corporations and council-controlled utilities dominate procurement volumes across the trans-Tasman market. Queensland's mining corridor and Auckland's metropolitan network anchor chemical consumption. TGA and Taumata Arowai standards reshape formulation requirements state by state.
New South Wales
Sydney Water's procurement centralization drives consolidated chemical contracts across Greater Sydney and regional networks. The Australian Drinking Water Guidelines' residual aluminum thresholds force utilities toward polyaluminum chloride variants. Hunter Valley mining operations generate industrial process water demand for customized coagulation programs.
Victoria
Regional water utilities have migrated fastest toward performance-based chemical supply contracts that transfer dosing optimization risk to suppliers. Melbourne's metropolitan networks now evaluate pilot implementations of bundled chemical-equipment service models. Yarra Valley food processing facilities sustain seasonal demand spikes for specialized sanitization chemistries.
Queensland
The mining corridor from Mount Isa to the Bowen Basin shows the steepest procurement acceleration for high-basicity coagulants and corrosion inhibitors. Seqwater's bulk chemical tenders consolidate demand from Brisbane and Gold Coast municipal systems. Fitzroy Basin coal seam gas operators require tailored produced water treatment chemistries.
Western Australia
Pilbara mining towns face urgent pipeline replacement cycles that surge demand for phosphate-based and silicate corrosion inhibitors. Freight costs from eastern seaboard synthesis centers create persistent supply disadvantages for Perth and Kalgoorlie utilities. Goldfields mining operators pilot membrane bioreactor pre-treatment chemistries to reduce freshwater intake from depleted aquifers.
New Zealand
Auckland's metropolitan water network expands chemical dosing infrastructure to meet Taumata Arowai pathogen monitoring mandates. Canterbury regional councils tighten wastewater discharge consents under Resource Management Act amendments. South Island small-to-medium municipal systems confront the steepest compliance cost burden relative to ratepayer bases.
Australia & New Zealand Water Treatment Chemicals Market Competitive Landscape
Player mix skews toward integrated chemical-equipment providers and specialized coagulant formulators. Three tiers structure competitive positioning: multinational service integrators with telemetry-enabled dosing platforms, regional manufacturers with captive eastern seaboard production assets, and niche consultants focused on regulatory compliance pathways. Dominant competitive moves include procurement centralization partnerships with merged utilities and backward integration into precursor material sourcing.
Among trans-Tasman specialists, Ixom leverages its domestic manufacturing footprint to anchor supply contracts across eastern seaboard utilities. Kemira Oyj competes through specialized coagulant formulations tailored to high-turbidity source waters. Ecolab exemplifies the integrated service model, combining chemical delivery with monitoring equipment to capture performance-based contract opportunities.
| Leading Market Players |
|---|
| SNF |
| Albemarle Corporation |
| Ecolab |
| Veolia Water Technologies |
| Dow |
| Kemira Oyj |
| Ixom |
| Solvay |
| Solenis |
| Others |
Pricing and Supply Chain Analysis
Polyaluminum chloride substitution for conventional alum formulations redraws procurement geography across the trans-Tasman market while compressing delivered price spreads between eastern seaboard manufacturers and distant utilities. This chemistry shift simultaneously elevates freight cost sensitivity and rewards suppliers with coastal synthesis assets.
Pricing Analysis
Cost-plus contracts indexed to alumina and ferric chloride feedstock benchmarks dominate municipal procurement across Australian state-owned water corporations. Price differentiation separates high-basicity polyaluminum chloride grades meeting stricter residual aluminum thresholds from commodity alum formulations, with certification tier and geographic delivery cost as primary drivers. Pricing pressure stems from feedstock volatility tied to bauxite processing economics, squeezing margins for non-integrated suppliers. Small-to-medium municipal systems in South Australia and Western Australia exhibit highest price sensitivity due to freight disadvantages, while Queensland mining operators show lowest sensitivity given process water criticality.
Supply Chain Analysis
Strategic stockpiling of precursor materials prevails among major formulators given alumina and ferric chloride price volatility, contrasting with just-in-time delivery preferences for finished coagulants at municipal dosing sites. Supply concentrates in eastern Australia manufacturing corridors, with raw material dependencies on bauxite processing outputs and steel by-product streams. Single-source vulnerability from limited domestic precursor production creates structural risk for western utilities. Distribution runs through tanker-truck direct delivery to metropolitan accounts and regional distributor networks for remote sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Taumata Arowai's pathogen monitoring mandates and electrochemical generation technology maturation together constitute a regulatory-technological inflection reshaping competitive economics across the Australia & New Zealand Water Treatment Chemicals Market.
For Market Incumbents: Compound telemetry-enabled dosing capabilities with performance-based contract structures to lock in merged utility accounts before procurement centralization completes. Anchor backward integration into precursor sourcing to neutralize alumina price volatility threatening margin stability. Priority defensive moves center on securing Taumata Arowai registration pathways ahead of competitor filings and expanding electrochemical cell manufacturing partnerships to capture chlorine dioxide generation demand. For New Entrants and Emerging Players: Remote telemetry service gaps in Tasmanian municipal systems and South Island small-to-medium utilities offer penetrable white-space where integrated incumbents under-serve. Target membrane bioreactor pre-treatment chemistry programs in Western Australia mining corridors where freshwater scarcity intensifies technical service willingness-to-pay. Go-to-market leverage rests on bundling chemical supply with continuous analyzer networks rather than competing on commodity formulation pricing. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed regional distributors holding eastern seaboard logistics networks but lacking technical service depth. Five-to-ten year viability favors acquisition targets with Taumata Arowai product registrations and Pilbara mining corridor relationships. Signal to monitor: electrochemical generation equipment adoption rates crossing threshold where bundled chemical-equipment contracts displace bulk hypochlorite procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Sourcing | Captive alumina supply neutralizes feedstock volatility squeezing non-integrated Queensland formulators. |
| Taumata Arowai Registration Acceleration | Early product approval secures preferred supplier status before New Zealand procurement centralization finalizes. |
| Electrochemical Generation Partnership | Chlorine dioxide cell technology bundling captures safety-regulation-driven displacement of bulk hypochlorite transport. |
| Telemetry-Enabled Dosing Platform Deployment | Remote monitoring capabilities penetrate Tasmanian and South Island utilities where technical service scarcity persists. |
| Performance-Based Contract Conversion | Dosing optimization risk transfer locks multi-year volume commitments from Victoria's regional water utilities. |
Research Methodology
A spread of perspectives from municipal procurement directors, chemical plant managers, Taumata Arowai compliance officers, and mining water treatment engineers converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation drawing from Australian Bureau of Agricultural and Resource Economics trade data, Taumata Arowai drinking water registration databases, state water corporation annual reports, and Australian Drinking Water Guidelines amendment notices. Bottom-up utility procurement volume estimates triangulated against top-down chemical manufacturer capacity disclosures.
Segmentation dimensions modeled span product type tier, end-use application, and geographic supply corridor across the projection horizon. CAGRs derived from utility capital expenditure pipelines, regulatory compliance cost burdens, and chemistry substitution elasticities. Industry-specific forecast inputs incorporated membrane bioreactor adoption curves in Western Australia mining regions and performance-based contract penetration rates across Victorian water utilities.
Underlying assumptions cover alumina price stability, freight cost persistence, and Taumata Arowai enforcement intensity, with deviation risk concentrated in PFAS regulatory expansion and electrochemical generation technology cost curves. Revision becomes warranted when electrochemical chlorine dioxide capital costs cross threshold parity with bulk hypochlorite lifecycle economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
South America Water Treatment Chemicals Market
Water & Sludge Treatment
Ballast Water Treatment Market
Water & Sludge Treatment
Produced Water Treatment Market
Water & Sludge Treatment
Water Recycle and Reuse Technologies Market
Water & Sludge Treatment
Global Wood Activated Carbon Market
Water & Sludge Treatment
Sludge Heater Market
Water & Sludge Treatment
Hypochlorous Acid Water Generator Market
Water & Sludge Treatment
South America Membrane Water and Wastewater (WWT) Treatment Market
Water & Sludge Treatment
Asia-Pacific Boiler Water Treatment Chemicals Market
Water & Sludge Treatment
Wastewater Treatment Chemicals Market
Water & Sludge Treatment
Europe Membrane Bioreactor (MBR) Market
Water & Sludge Treatment
Europe Water Treatment Chemicals Market
Water & Sludge Treatment
Pool and Spa Water Treatment Chemicals for Hotels and Clubs Market
Water & Sludge Treatment
Liquid Waste Container Market
Water & Sludge Treatment
Europe Boiler Water Treatment Chemicals Market
Water & Sludge Treatment
Middle-East and Africa Membrane Water Treatment Chemicals Market