
 Swimming Pool Treatment Chemicals Market | 2026-2036
Swimming Pool Treatment Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Swimming Pool Treatment Chemicals Market Outlook
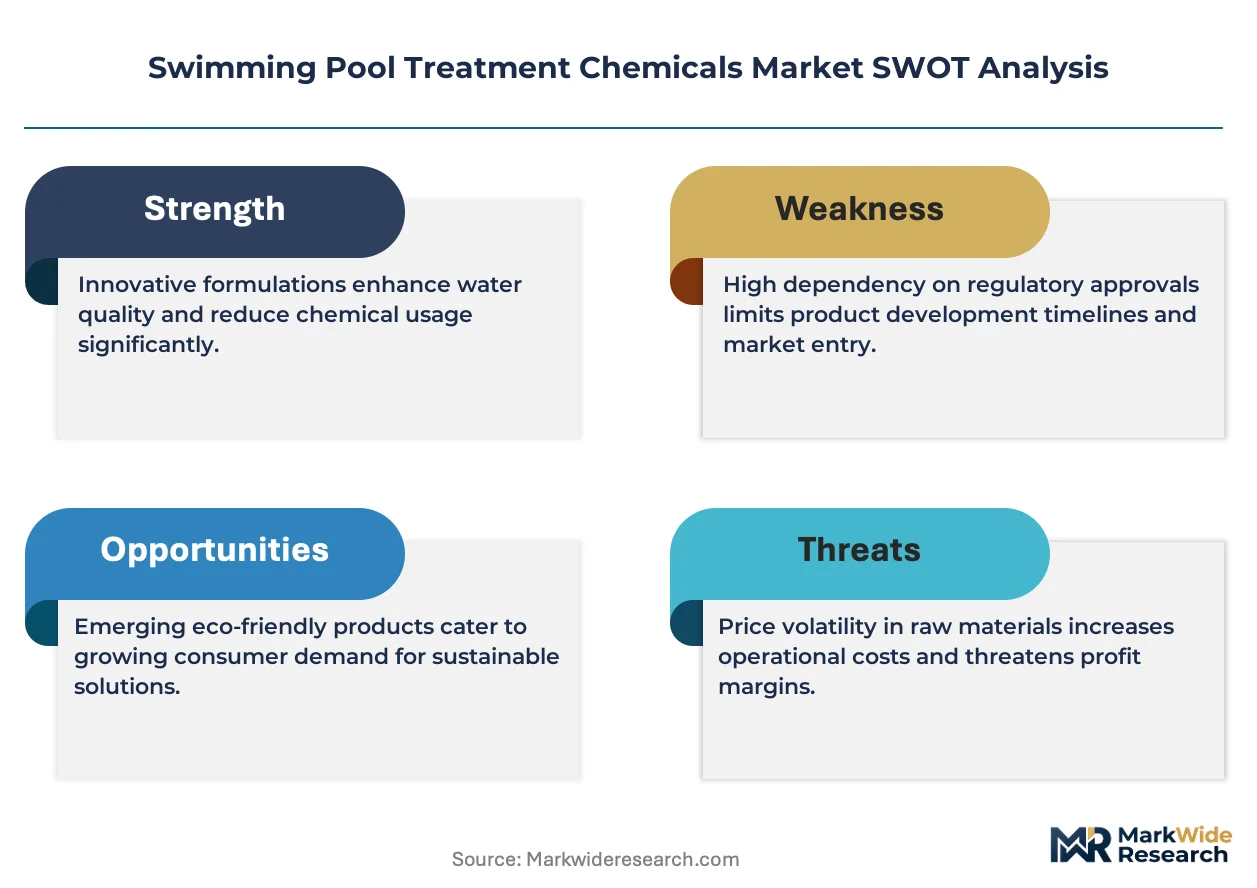
Buyer concentration among commercial pool management companies is pivoting as hospitality chains consolidate vendor contracts across property portfolios. Ecolab Inc. leverages its institutional sanitation footprint to cross-sell pool treatment bundles into hotel and resort accounts. Lonza Group anchors European supply through specialized tablet and granular production lines. Olin Corporation sustains North American chlorine derivative availability via integrated chlor-alkali manufacturing.
Swimming pool treatment chemicals comprise formulated biocides, oxidizers, pH modifiers, and coagulants engineered to maintain water within 7.2–7.8 pH, below 4 ppm free chlorine, and under 1 ppm combined chlorine per health standards. Sanitizers dominate product-type revenue due to mandatory continuous disinfection, while algaecides capture margin premiums in warm-climate regions with extended swim seasons. Water parks represent the fastest-growing application segment as developers add aquatic attractions to entertainment complexes. Tablet-form products command distribution preference in residential channels for dosing convenience, though liquid formulations retain commercial dominance for automated feed systems.
EPA regulations under FIFRA govern pesticide and algaecide registration, while OSHA standards address chemical handling exposure limits for pool service technicians. State health departments in Florida, California, and Arizona enforce supplemental testing frequencies that exceed federal baselines. The EU REACH framework restricts certain quaternary ammonium compounds, redirecting formulation strategies for exporters serving European commercial pools. Stakeholders must monitor evolving PFAS scrutiny, as precursor chemicals in some membrane clarifiers face emerging restriction proposals that could force reformulation investments.
Market Dynamics
Commercial hospitality chains are consolidating vendor contracts across property portfolios, concentrating procurement power among fewer buyers and forcing chemical suppliers to bundle sanitation services with product supply.
Growth Catalysts
- EPA FIFRA Registration Requirements:Mandatory federal pesticide and algaecide registration creates compliance barriers that protect established suppliers from unqualified entrants.
- Water Park Construction Boom:Entertainment complex developers are adding aquatic attractions at accelerating rates, expanding addressable chemical demand beyond traditional pool installations.
- Tablet Formulation Convenience:Residential pool owners prefer solid-dose products for simplified handling, driving channel preference shifts in consumer-facing distribution.
Market Restraints
- Chlor-Alkali Feedstock Concentration:North American chlorine derivative availability depends on integrated petrochemical manufacturing clusters concentrated along the Gulf Coast.
- EU REACH Compound Restrictions:The European Chemicals Agency's limitations on quaternary ammonium compounds force exporters to maintain parallel formulation strategies.
- Liquid Chlorine Transportation Costs:Corrosive liquid sanitizers require specialized hazmat logistics that inflate delivered costs versus solid alternatives.
Strategic Opportunities
- Automated Feed System Integration:Commercial facilities are retrofitting legacy pools with sensor-driven chemical dosing, opening hardware-chemical bundled service models.
- Warm-Climate Algaecide Premiums:Extended swim seasons in Florida, Arizona, and Southern California create year-round demand cycles absent in temperate markets.
- PFAS-Free Clarifier Reformulation:Emerging precursor chemical scrutiny positions early movers to capture share as membrane clarifier standards tighten.
Industry Challenges
- Certified Pool Operator Shortage:State health departments mandate CPO credentials for commercial facility compliance, constraining service technician availability.
- Residual Chlorine Reporting Burden:Municipal health departments in high-enforcement states require documentation frequencies that strain small operator administrative capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Swimming Pool Treatment Chemicals Market |
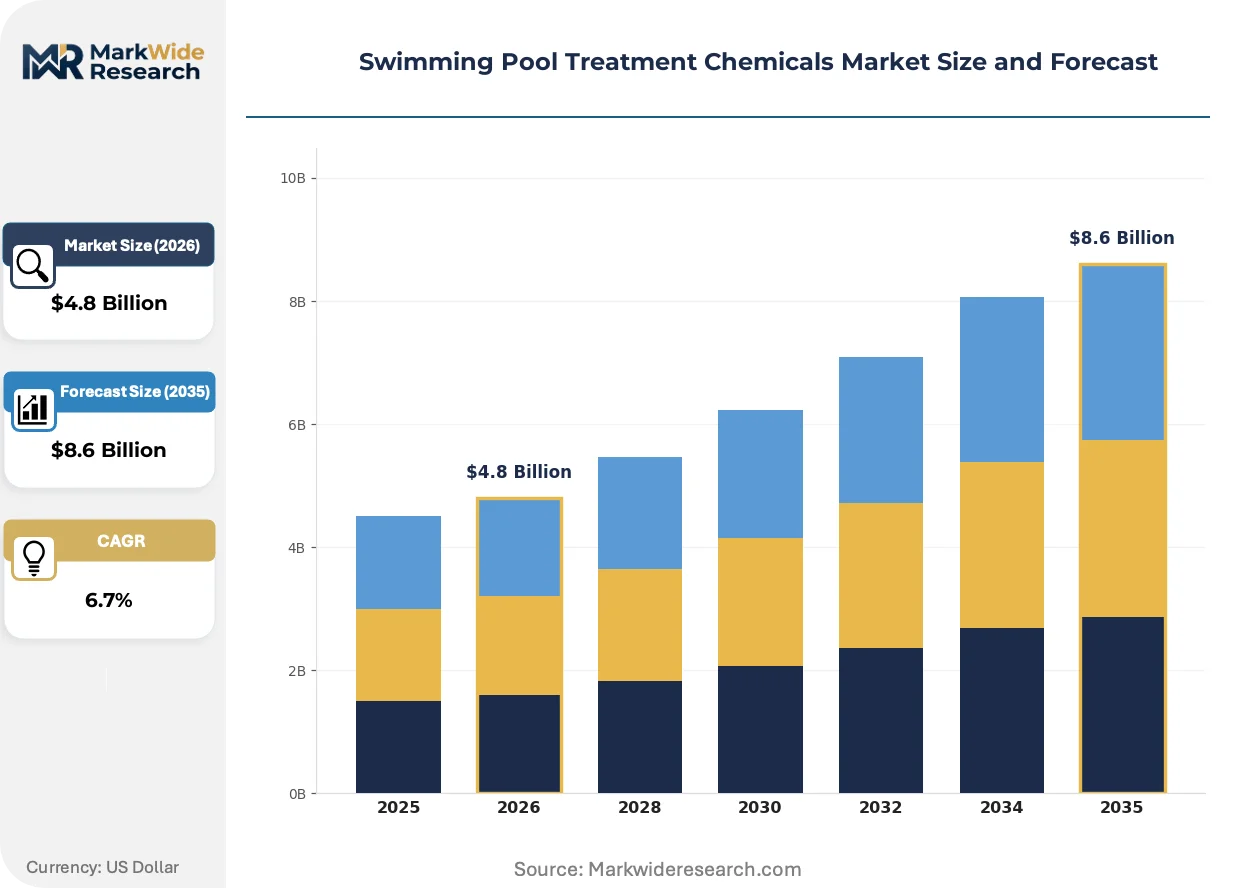
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sanitizers, Algaecides, pH Balancers, Water Clarifiers Application: Residential Pools, Commercial Pools, Spas, Water Parks Distribution Channel: Retail, Online, Direct Sales, Wholesale Form: Liquid, Granular, Tablet, Powder |
| Companies Covered | Ecolab Inc., Olin Corporation, BASF SE, Nippon Soda Co. Ltd., Kemira Oyj, Lonza Group, FMC Corporation, Arkema, AkzoNobel N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Swimming Pool Treatment Chemicals Market Strategic Shifts
Digital water quality monitoring is compressing service intervals and enabling predictive chemical dosing, reshaping how suppliers interact with facility operators.
Smart sensor networks are unifying pH, oxidation-reduction potential, and free chlorine measurement into single-platform dashboards. Resort and hotel chains are deploying these systems across property portfolios to standardize water quality protocols. This convergence is unifying previously separate testing equipment markets into integrated IoT ecosystems.
REACH framework restrictions on quaternary ammonium biocides are forcing European formulation pivots toward alternative algaecide chemistries. Manufacturers serving EU commercial pools must maintain dual product lines or absorb reformulation costs. Tablet and granular specialists with flexible production assets are capturing redirected demand as liquid quaternary formulations face phase-down timelines.
Facility operators are consolidating chemical procurement through national service contracts rather than regional distributor relationships. Hospitality property management companies now negotiate enterprise pricing with suppliers capable of multi-state logistics coverage. This concentration is most visible in the United States, where REITs and hotel chains standardize vendor panels across hundreds of locations.
Swimming Pool Treatment Chemicals Market Segmentation
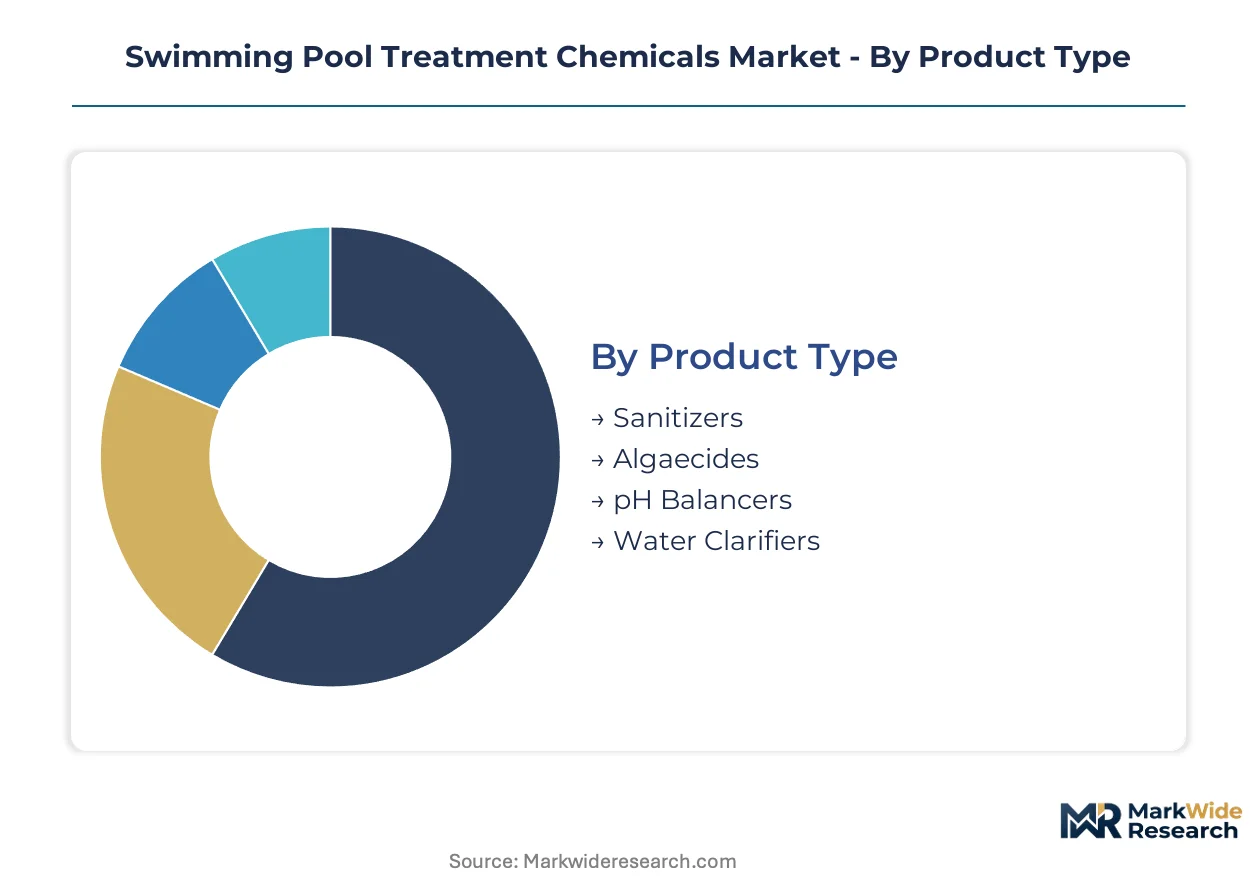
Pool treatment chemical suppliers configure product portfolios across four distinct axes. Each segmentation dimension shapes pricing architecture, channel strategy, and regulatory compliance requirements differently.
Product Type:
Technical performance specifications determine procurement priority and margin structure across the category.
- Sanitizers:Chlorine-based and bromine-based formulations provide continuous disinfection to maintain free chlorine below 4 ppm and combined chlorine under 1 ppm per health standards. Municipal health departments in Florida, California, and Arizona mandate residual reporting frequencies that sustain institutional procurement volumes.
- Algaecides:Quaternary ammonium compounds and copper-based formulations prevent algae proliferation in warm-climate pools with extended swim seasons. REACH framework restrictions in Europe are forcing exporters toward alternative chemistries as quaternary formulations face phase-down timelines.
- pH Balancers:Sodium carbonate and muriatic acid derivatives adjust alkalinity to maintain 7.2–7.8 pH ranges required for sanitizer efficacy and swimmer comfort.
- Water Clarifiers:Polymer-based and natural flocculants aggregate suspended particles for filtration removal; emerging PFAS scrutiny of precursor chemicals is positioning early reformulators for share capture.
Sanitizers lead on scale; algaecides lead on momentum.
Application:
Facility scale and operational intensity create divergent chemical consumption profiles and service relationships.
- Residential Pools:Individual homeowners prioritize dosing convenience and storage safety, driving tablet-form preference through retail channels with seasonal purchase patterns concentrated in temperate climate spring preparation periods.
- Commercial Pools:Hospitality chains and municipal facilities require automated feed systems with continuous monitoring, consolidating procurement through national service contracts that bundle chemicals with equipment maintenance and compliance documentation.
- Spas:Elevated temperature and bather load conditions demand specialized bromine formulations and more frequent water replacement cycles than conventional pools.
- Water Parks:High-volume aquatic attractions with wave pools and lazy rivers represent the steepest expansion trajectory as entertainment complex developers accelerate attraction additions beyond traditional pool installations.
Commercial pools dominate volume concentration; water parks show the sharpest growth slope.
Distribution Channel:
Channel selection reflects buyer sophistication, order scale, and service integration requirements.
- Retail:Big-box hardware and pool specialty stores serve residential owners with immediate-need replenishment and seasonal stocking, though shelf space constraints limit formulation variety.
- Online:E-commerce platforms capture tablet and granular product demand from informed residential buyers seeking price transparency and bulk purchasing options without geographic distributor limitations.
- Direct Sales:National chemical suppliers contract directly with hospitality REITs and property management companies for enterprise pricing across multi-state portfolios with standardized water quality protocols.
- Wholesale:Regional distributors maintain local inventory positions for pool service technicians requiring same-day availability for commercial facility maintenance calls.
Direct sales commands the largest contract values; online channels are expanding most quickly.
Form:
Physical state determines handling logistics, dosing precision, and compatibility with feed system infrastructure.
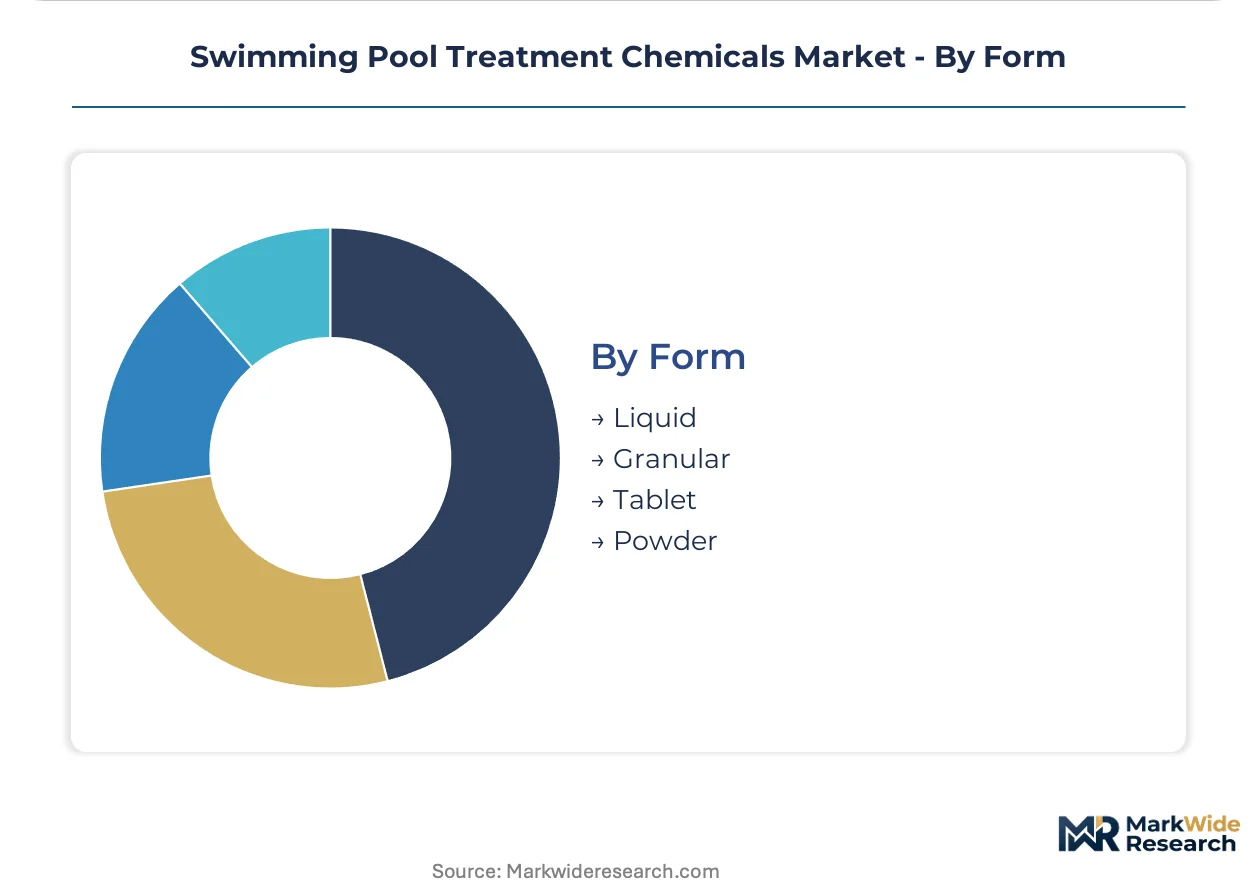
- Liquid:Sodium hypochlorite and muriatic acid solutions enable precise automated dosing in commercial facilities with sensor-driven feed systems, though corrosive properties require specialized hazmat transportation that inflates delivered costs versus solid alternatives.
- Granular:Calcium hypochlorite and dichlor formulations dissolve rapidly for shock treatment applications, offering storage stability advantages over liquid alternatives in warm climates.
- Tablet:Trichlor and bromine tablets provide slow-release dosing convenience preferred by residential owners, commanding distribution preference in consumer-facing channels despite higher per-unit active ingredient costs.
- Powder:Diatomaceous earth and specialty clarifier powders support filtration system maintenance with precise application control in commercial facilities with trained technician staff.
Tablet form leads residential convenience; liquid form anchors commercial automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States enforces stricter recreational water codes than Germany, where commercial pool operators face less frequent residual chlorine reporting. China and Japan concentrate manufacturing capacity for tablet and granular formulations, while Australia maintains distinct seasonal demand patterns tied to temperate climate swim seasons.
United States
Commercial hospitality chains and municipal health departments drive procurement concentration across Florida, California, and Arizona. The EPA's FIFRA registration requirements govern pesticide and algaecide compliance, creating barriers for unqualified entrants. The Gulf Coast chlor-alkali manufacturing cluster sustains North American chlorine derivative availability through integrated petrochemical operations.
Germany
Commercial facility operators prioritize automated feed systems with sensor-driven dosing precision. The EU REACH framework restricts quaternary ammonium compounds, redirecting formulation strategies toward alternative algaecide chemistries. The Rhine-Ruhr industrial corridor anchors European chemical production with specialized tablet and granular manufacturing lines.
China
Domestic water park construction and residential pool installation accelerate chemical consumption across entertainment complexes. The country's national chemical regulator enforces production safety standards for chlor-alkali derivatives and biocide formulations. The Yangtze River Delta manufacturing base supplies solid-dose products for export markets with flexible production assets.
Japan
Metropolitan onsen facilities and commercial spa operators sustain specialized bromine formulation demand. METI standards address chemical handling exposure limits for pool service technicians in commercial environments. The Kansai region maintains legacy chlor-alkali production capacity serving domestic sanitizer requirements.
Australia
Extended swim seasons in Queensland and New South Wales create year-round algaecide consumption cycles absent in temperate markets. State health departments enforce supplemental testing frequencies for commercial facilities that exceed federal baselines. The Sydney-Melbourne corridor concentrates pool service technician networks and wholesale distribution infrastructure.
Swimming Pool Treatment Chemicals Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base organizes around three strategic archetypes: integrated chemical manufacturers with chlor-alkali feedstock control, formulated product specialists with flexible tablet and granular assets, and institutional sanitation providers cross-selling bundled service models. Competitive moves concentrate on national service contract consolidation and automated feed system integration partnerships.
Among North American integrated manufacturers, Olin Corporation exemplifies captive chlor-alkali supply advantages, while Ecolab Inc. occupies a position within institutional sanitation bundling. Lonza Group anchors European tablet and granular specialization. These three represent distinct competitive vectors: upstream feedstock security, cross-category service integration, and regional formulation flexibility.
| Leading Market Players |
|---|
| Ecolab Inc. |
| Olin Corporation |
| BASF SE |
| Nippon Soda Co. Ltd. |
| Kemira Oyj |
| Lonza Group |
| FMC Corporation |
| Arkema |
| AkzoNobel N.V. |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up pool service specialists have consolidated regional technician networks across the Sun Belt, concentrating procurement leverage and compressing margins for undifferentiated sanitizer suppliers while rewarding vendors with captive chlor-alkali production and multi-state logistics capabilities.
Pricing Analysis
Capacity additions in China's Yangtze River Delta manufacturing base are reshaping price floors for solid-dose products, forcing North American tablet specialists toward three-tier pricing structure across premium, standard, and economy levels differentiated by dissolution speed and certification grade. Price differentiation stems from EPA FIFRA registration status and automated feed system compatibility. Cost compression in liquid chlorine runs through specialized hazmat transportation requirements. Residential retail channels exhibit highest price sensitivity; commercial hospitality chains prioritize total service cost over unit pricing.
Supply Chain Analysis
Single-source vulnerability sits with Gulf Coast chlor-alkali manufacturing clusters concentrated in Texas and Louisiana, where integrated petrochemical operations feed North American chlorine derivative availability. Raw material dependencies encompass salt brine feedstock, caustic soda co-products, and specialized tablet binding agents. Supply chain risk centers on hurricane-season logistics disruptions to liquid chlorine distribution. Distribution runs through national service contracts for commercial accounts and wholesale regional distributors for technician-serviced facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in algaecide reformulation and automated dosing hardware bundling, as warm-climate operators absorb premium pricing for PFAS-free clarifiers and sensor-driven chemical management systems reduce per-site service labor intensity.
For Market Incumbents: Extend captive chlor-alkali supply advantages through backward integration into tablet and granular finishing capacity, defending against Chinese solid-dose import competition. Fortify national service contract positions by embedding automated feed system partnerships that raise switching costs for hospitality REITs. Prioritize PFAS-free clarifier R&D investments ahead of emerging EPA precursor chemical restrictions. For New Entrants and Emerging Players: Sensor-driven dosing platforms offer a technology-first wedge into mid-sized commercial pool operators underserved by legacy distributor relationships. Target water park developers in secondary entertainment markets with bundled chemical-hardware service models absent from incumbent portfolios. Pursue white-label tablet production for private-equity-rolled-up service networks seeking supply chain control. For Investors and Strategic Acquirers: Valuations sit cheapest among regional wholesale distributors lacking automated system integration capabilities or direct hospitality contract access. Long-term viability favors assets with flexible formulation assets capable of serving both REACH-compliant European export and domestic FIFRA-registered product lines. Monitor EPA PFAS regulatory advance notice as inflection indicator for clarifier reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tablet Production | Captive finishing capacity insulates margin from Chinese solid-dose import pricing pressure. |
| Automated Feed System Partnership | Sensor-driven dosing bundling raises switching costs for commercial hospitality accounts. |
| PFAS-Free Clarifier Reformulation | Early EPA compliance positioning captures share as membrane clarifier standards tighten. |
| Water Park Service Contract Expansion | Entertainment complex developers accelerate aquatic attraction additions beyond traditional pools. |
| REACH-Compliant Algaecide Line | Dual formulation capability maintains European commercial pool access as quaternary compounds phase down. |
Study Parameters
Direct dialogue with pool service technicians, commercial facility maintenance directors, hospitality procurement managers, and chlor-alkali plant operations heads grounded demand-side validation. Secondary sources encompassed EPA FIFRA registration databases, state health department recreational water codes, customs trade data on chlorine derivative imports, and SEC filings from integrated chemical manufacturers. Bottom-up volume estimates triangulated against top-down market sizing across product type, application, and regional regulatory clusters.
Segment-level projections incorporated sanitizer, algaecide, pH balancer, and clarifier demand trajectories across residential, commercial, spa, and water park applications throughout the forecast period. CAGRs derived from historical consumption elasticity to pool installation rates, bather load intensity, and regulatory testing frequency mandates. Industry-specific inputs included chlor-alkali capacity utilization rates, water park construction permits, and CPO certification pipeline data.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EPA PFAS regulatory timing, Gulf Coast hurricane disruption frequency, and hospitality REIT consolidation pace. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Water Treatment Polymers Market
Water & Sludge Treatment
Water and Wastewater Treatment Technologies Market
Water & Sludge Treatment
Global Industrial Sludge Treatment Chemicals Market
Water & Sludge Treatment
Low-Dosage Hydrate Inhibitors (Ldhis) Market
Water & Sludge Treatment
India Water Treatment Chemicals Market
Water & Sludge Treatment
Saudi Arabia Industrial Hazardous Waste Management Market
Water & Sludge Treatment
Asia-Pacific Drilling Waste Management Services Market
Water & Sludge Treatment
Global Water Clarifiers Market
Water & Sludge Treatment
India Water Treatment Market
Water & Sludge Treatment
Water Treatment Chemicals Market
Water & Sludge Treatment
Aquarium Water Treatment Market
Water & Sludge Treatment
Middle-East and Africa Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
North America Membrane Water and Wastewater Treatment (WWT) Market
Water & Sludge Treatment
North America Water Treatment Chemicals Market
Water & Sludge Treatment
Global Wet Waste Management Market
Water & Sludge Treatment
India Water and Wastewater Treatment (WWT) Technology Market