
 Nano and Microsatellite Market | 2026-2036
Nano and Microsatellite Market Size, Share, and Industry Trends Forecast 2026-2036
Nano and Microsatellite Market Outlook
FCC streamlined spectrum licensing is recalibrating the cost-of-entry calculus for constellation operators seeking rapid deployment. Planet Labs Inc. leverages its vertically integrated manufacturing to control imagery production from satellite build to data delivery. AAC Clyde Space anchors its position through Scottish-based CubeSat assembly lines serving European institutional clients. Spire Global, Inc. differentiates via its weather-forecasting constellation, sustaining recurring revenue through maritime and aviation data subscriptions.
Nano and microsatellites are spacecraft with wet masses between 1 kg and 100 kg, typically employing standardized CubeSat form factors with aluminum alloy frames, commercial off-the-shelf electronics, and deployable solar arrays generating 1–50 watts. These platforms serve Earth observation, telecommunications, and scientific missions at unit costs one to two orders of magnitude below traditional geostationary satellites. Nanosatellites occupy the fastest-expanding tier, driven by ride-share launch economics that slash per-kilogram orbital insertion costs. The defense end-user segment leads absolute spending, though academic technology demonstration missions represent the most price-sensitive demand pool with minimal margin contribution. Ride-share launch methods dominate deployment volume, while dedicated launches command premium pricing for precise orbital insertion requirements.
FAA Office of Commercial Space Transportation governs U.S. launch licensing, imposing payload review standards that directly shape satellite design safety margins. FCC orbital debris mitigation rules mandate disclosure of collision avoidance capabilities, filtering market access toward operators with propulsion-equipped platforms. ISO 17770 and NASA-STD-8719.14 establish reliability benchmarks that insurance underwriters reference when pricing on-orbit coverage. Stakeholders must monitor evolving debris remediation mandates, as pending regulatory requirements for active deorbit systems will force hardware redesigns across the sub-100 kg class.
Market Dynamics
Ride-share launch economics are compressing orbital insertion costs below dedicated launch premiums, forcing constellation operators to reoptimize satellite design for standardized deployment geometries rather than bespoke orbital parameters.
Growth Catalysts
- Defense constellation procurement:Space Force modernization and tactical reconnaissance mandates are accelerating small satellite procurement cycles. Military end-users now specify rapid-replenishment architectures.
- Streamlined spectrum licensing:FCC orbital debris mitigation rules favor propulsion-equipped platforms, filtering market access toward operators with collision avoidance capabilities. This accelerates qualified vendor consolidation.
- Commercial lunar payload services:NASA's CLPS program creates anchor demand for lunar communication relay satellites, pulling terrestrial nano-satellite manufacturing capacity into cislunar applications.
Market Restraints
- Launch slot scarcity:Ride-share manifests concentrate through SpaceX Falcon 9 and Rocket Lab Electron, creating single-source dependency for cost-sensitive operators.
- Propulsion system costs:Miniaturized electric thrusters and cold-gas systems add 15-25% unit cost premiums, eroding the cost advantage that defines sub-100 kg class competitiveness.
- Debris remediation mandates:Pending FCC requirements for active deorbit systems will force hardware redesigns across existing satellite fleets, straining operator capex.
Strategic Opportunities
- Maritime weather data subscriptions:Spire Global's recurring revenue model demonstrates path to SaaS-like economics. Aviation and shipping insurers represent underpenetrated buyers.
- Scottish manufacturing cluster:AAC Clyde Space's Glasgow assembly lines serve European institutional clients with shorter procurement cycles than US defense programs.
- AI-driven on-board processing:Edge computing convergence with synthetic aperture radar enables real-time imagery classification, reducing downlink bandwidth requirements and ground infrastructure costs.
Industry Challenges
- Collision avoidance software talent:Autonomous maneuvering algorithms require astrodynamics specialists scarce outside legacy aerospace primes and national space agencies.
- ISO 17770 certification timelines:Reliability benchmarking for insurance coverage extends development cycles 8-14 months, compressing revenue recognition windows.
- Legacy ground station integration:Defense operators require compatibility with existing TT&C networks, forcing radio frequency and protocol compromises that limit payload optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nano and Microsatellite Market |
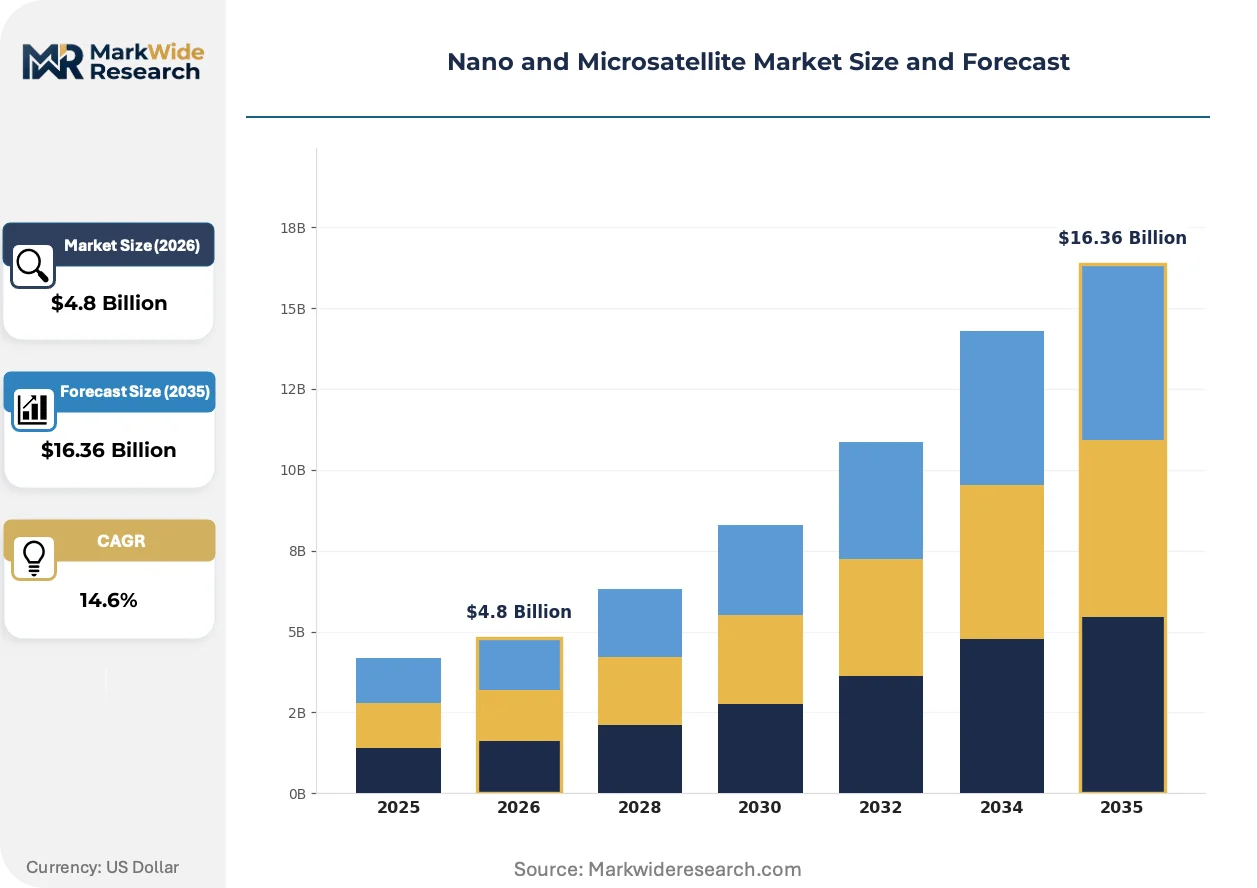
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Satellite Type: Nanosatellites, Microsatellites, CubeSats, SmallSats Launch Method: Dedicated Launch, Ride-share, Expendable Rockets, Reusable Rockets End User: Government, Commercial, Academic, Defense Application: Earth Observation, Communication, Scientific Research, Technology Demonstration |
| Companies Covered | Planet Labs Inc., AAC Clyde Space, Surrey Satellite Technology Ltd., GomSpace, Axelspace Corporation, Lockheed Martin Corporation, Terran Orbital, Kongsberg NanoAvionics, Spire Global, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nano and Microsatellite Market Strategic Shifts
Standardized CubeSat form factors are enabling manufacturing automation previously impossible with bespoke satellite architectures, while regulatory pressure on orbital debris is accelerating propulsion miniaturization. These forces are compressing the traditional satellite development cycle.
Synthetic aperture radar is converging with commercial off-the-shelf electronics to enable all-weather Earth observation at unit costs previously restricted to optical systems. Agricultural commodity traders and maritime surveillance operators are adopting these platforms fastest. The technology is converging with on-board machine learning to enable tip-and-cue tasking without ground station intervention.
EU Space Surveillance and Tracking framework mandates are forcing operators to demonstrate conjunction assessment capabilities before licensing. This industrial consequence elevates propulsion-equipped platforms from optional to baseline specification. Smallsat builders serving European institutional clients are redesigning power budgets to accommodate collision avoidance thrusters.
Subscription-based data licensing is displacing per-image transactional sales across Earth observation verticals. Maritime weather and aviation routing data buyers now expect API-delivered streams rather than archive downloads. This pattern is most visible in North American and European defense-adjacent commercial markets where operators integrate satellite feeds directly into operational workflows.
Nano and Microsatellite Market Segmentation
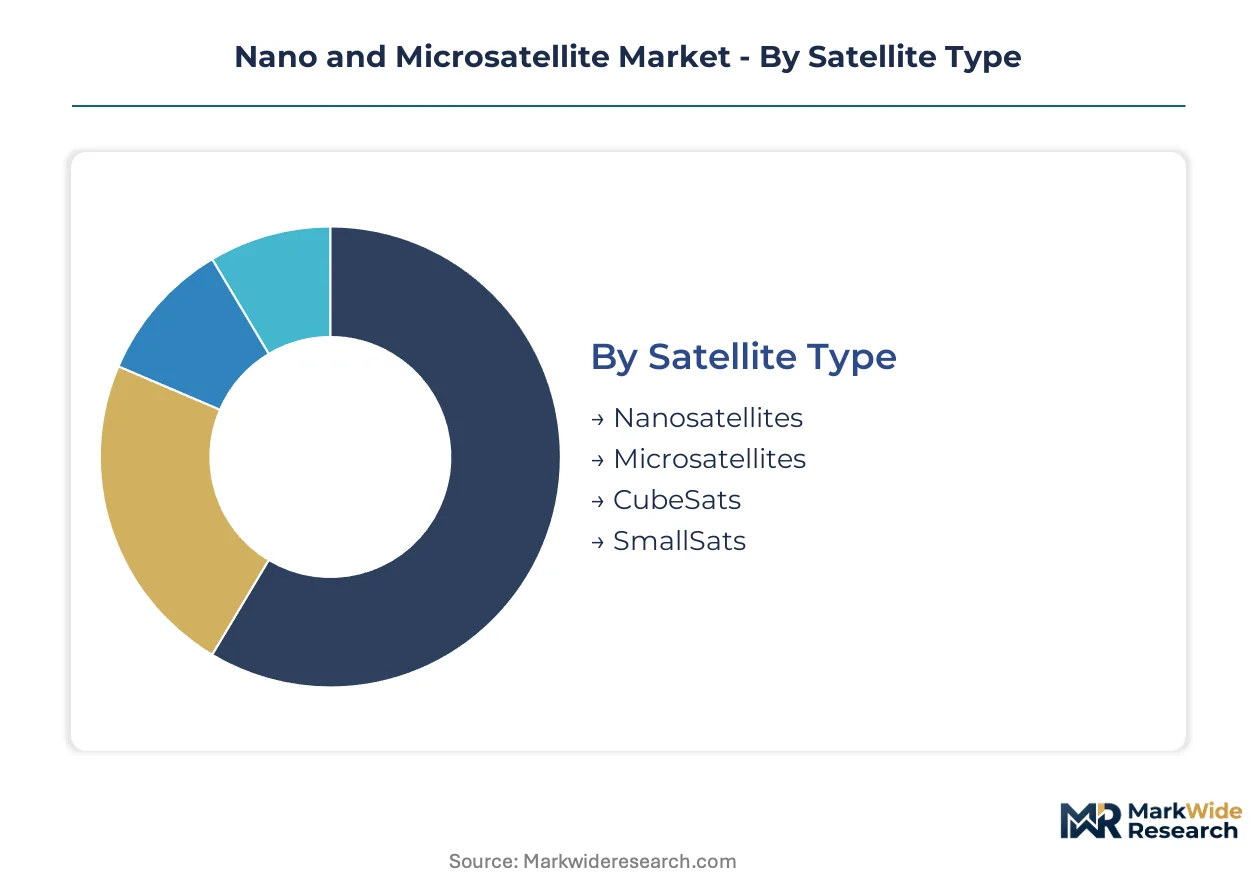
Segmentation in the nano and microsatellite market reveals how procurement priorities diverge across mission profiles. Defense buyers prioritize rapid replenishment architectures, while commercial operators optimize for ride-share launch economics.
Satellite Type:
Mass thresholds determine manufacturing automation potential and launch slot compatibility.
- Nanosatellites:Wet masses below 10 kg employ standardized CubeSat form factors with aluminum alloy frames and commercial off-the-shelf electronics. Defense agencies in the United States are accelerating procurement of nanosatellite constellations for tactical reconnaissance, driving volume through Space Force modernization programs.
- Microsatellites:Platforms between 10 kg and 100 kg wet mass accommodate larger deployable solar arrays generating 10–50 watts and miniaturized propulsion systems. European institutional clients favor microsatellites for Earth observation missions requiring greater payload capacity than CubeSat architectures permit.
- CubeSats:Standardized 10×10×10 cm units enable university technology demonstration missions at minimal unit cost.
- SmallSats:Broader category spanning 1–180 kg captures experimental platforms outside strict nano/micro boundaries.
Nanosatellites lead on scale; microsatellites lead on momentum.
Launch Method:
Orbital insertion economics shape constellation architecture decisions more than payload design in many procurement cycles.
- Ride-share:Secondary payload arrangements on Falcon 9 and Electron launches dominate deployment volume, compressing per-kilogram costs below dedicated alternatives. Commercial operators in the United States accept orbital parameter compromises to access SpaceX manifests, creating single-source dependency risks.
- Dedicated Launch:Primary payload status commands premium pricing for precise orbital insertion and schedule certainty. Defense end-users specify dedicated launches for rapid-replenishment architectures requiring specific inclinations and phasing.
- Expendable Rockets:Legacy launch vehicles retain niche demand for high-energy orbits beyond ride-share capabilities.
- Reusable Rockets:First-stage recovery economics are reshaping cost structures for constellation operators planning multi-launch campaigns.
Ride-share leads on scale; dedicated launch leads on momentum.
End User:
Budget cycles and mission requirements create distinct specification patterns across customer categories.
- Defense:Military end-users specify rapid-replenishment architectures with propulsion-equipped platforms for collision avoidance. The U.S. Space Force modernization priorities are accelerating small satellite procurement cycles beyond traditional geostationary replacement timelines.
- Commercial:Maritime weather data and aviation routing subscriptions drive recurring revenue models. Spire Global's API-delivered streams demonstrate SaaS-like economics that attract shipping insurers and commodity traders.
- Government:Civil space agencies anchor demand for lunar communication relay satellites through NASA's Commercial Lunar Payload Services program.
- Academic:Technology demonstration missions represent the most price-sensitive demand pool with minimal margin contribution for manufacturers.
Defense leads on scale; commercial leads on momentum.
Application:
Mission objectives determine payload sensor selection and on-board processing requirements.
- Earth Observation:Synthetic aperture radar convergence with commercial off-the-shelf electronics enables all-weather imaging at unit costs previously restricted to optical systems. Agricultural commodity traders in North America are adopting these platforms fastest.
- Communication:Constellation operators leverage streamlined FCC spectrum licensing for non-geostationary orbit systems, recalibrating cost-of-entry calculus for rapid deployment.
- Scientific Research:Space weather monitoring and ionospheric studies drive demand for distributed sensor networks.
- Technology Demonstration:Pathfinder missions validate miniaturized propulsion and edge computing payloads before operational deployment.
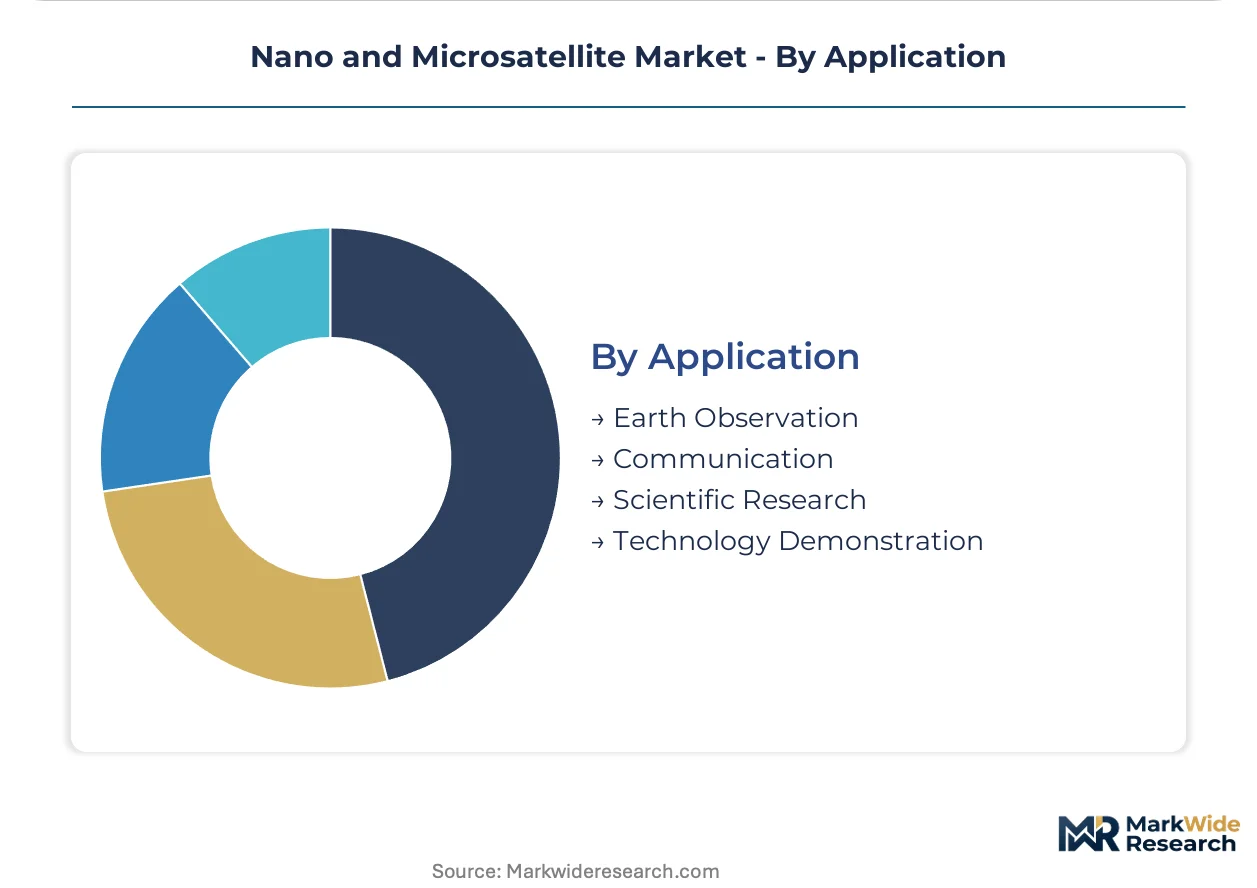
Earth observation leads on scale; communication leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Astrodynamics specialists and satellite systems engineers concentrate in established aerospace corridors across five nations, with talent pools clustering near legacy defense contractors and national space agencies.
United States
Space Force modernization and NASA's Commercial Lunar Payload Services program anchor procurement demand. FCC streamlined spectrum licensing for non-geostationary orbit systems accelerates constellation deployment timelines. California's Los Angeles basin hosts vertically integrated manufacturers serving defense and commercial operators.
United Kingdom
Earth observation missions requiring greater payload capacity than CubeSat architectures permit drive institutional demand. ISO 17770 reliability benchmarks shape insurance underwriting for on-orbit coverage. Scotland's Glasgow assembly lines serve European clients with shortened procurement cycles.
Japan
Maritime weather data subscriptions and aviation routing services pull demand from shipping insurers and commodity traders. METI industrial policy supports miniaturized propulsion development for collision avoidance capabilities. Tokyo-Yokohama corridor houses synthetic aperture radar specialists converging with commercial off-the-shelf electronics.
Germany
EU Space Surveillance and Tracking framework mandates force operators to demonstrate conjunction assessment capabilities before licensing. REACH and RoHS compliance requirements filter component sourcing toward qualified European vendors. Bavaria's precision manufacturing base supplies miniaturized electric thruster subsystems.
India
Academic technology demonstration missions represent price-sensitive demand for university-built CubeSats. ISRO's commercial arm Antrix facilitates ride-share launch access for domestic operators. Bengaluru's aerospace cluster integrates software-defined radio payloads with standardized form factors.
Nano and Microsatellite Market Competitive Environment
The competitive structure tilts toward vertically integrated imagery operators and regional manufacturing specialists. Consolidation pressures favor entities controlling satellite build through data delivery. Three archetypes dominate: constellation operators with recurring revenue models, hardware-agnostic data brokers, and captive suppliers serving institutional programs. M&A activity concentrates on propulsion subsystem acquisition and ground station network expansion.
Among vertically integrated operators, Planet Labs Inc. exemplifies the end-to-end imagery production archetype, while AAC Clyde Space anchors European institutional supply through Scottish-based manufacturing. Spire Global, Inc. occupies a position demonstrating SaaS-like economics via maritime and aviation data subscriptions.
| Leading Market Players |
|---|
| Planet Labs Inc. |
| AAC Clyde Space |
| Surrey Satellite Technology Ltd. |
| GomSpace |
| Axelspace Corporation |
| Lockheed Martin Corporation |
| Terran Orbital |
| Kongsberg NanoAvionics |
| Spire Global, Inc. |
| Others |
Value Chain & Pricing Dynamics
Space Force rapid-replenishment mandates are forcing manufacturers to absorb propulsion system premiums without passing full costs to defense buyers, compressing margins on fixed-price contracts and accelerating consolidation toward vertically integrated producers with captive thruster supply.
Pricing Analysis
Bundled data-subscription services separate from unbundled satellite hardware sales, with Spire Global's API-delivered maritime weather streams commanding recurring revenue premiums against Planet Labs' per-image transactional heritage. Three-tier pricing structure across propulsion-equipped defense platforms, ride-share optimized commercial units, and bare-bones academic demonstrators reflects certification grade and collision avoidance capability. Pricing pressure stems from FCC debris mitigation rules filtering market access toward qualified vendors with maneuvering systems, raising baseline costs. Academic technology demonstration missions exhibit highest price sensitivity, while defense rapid-replenishment programs demonstrate lowest sensitivity to unit cost escalation.
Supply Chain Analysis
End-of-life satellite deorbit and refurbishment flows remain underdeveloped, with no established reverse logistics infrastructure for aluminum alloy CubeSat frame recovery or commercial off-the-shelf electronics remanufacturing. Manufacturing concentrates in the United States, Scotland, and Japan, drawing from gallium arsenide solar cell supply anchored in China, miniaturized electric thruster subsystems from Germany, and radiation-hardened electronics from domestic defense-qualified vendors. Single-source vulnerability runs through SpaceX Falcon 9 ride-share manifests, which dominate deployment volume. Distribution runs through direct constellation operator procurement for defense and commercial end-users, with academic buyers accessing hardware through distributor channels serving university programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with FCC orbital debris mitigation rules and EU Space Surveillance and Tracking mandates accelerating demand for propulsion-equipped platforms and filtering vendor qualification toward collision avoidance capability.
For Market Incumbents: Lock in propulsion subsystem supply through backward integration or long-term offtake agreements with Bavarian electric thruster specialists, defending against margin erosion from FCC-mandated hardware redesigns. Secure ISO 17770 certification ahead of pending debris remediation requirements to maintain insurance access and exclude unqualified competitors from defense procurement cycles. Prioritize Scottish and California manufacturing footprint expansion to serve European institutional clients and Space Force modernization programs with shortened delivery timelines. For New Entrants and Emerging Players: Enter via maritime weather data subscriptions for Asian shipping insurers, the most penetrable segment demonstrating SaaS-like economics with underexploited buyer concentration in Tokyo-Yokohama and Singapore corridors. Target academic technology demonstration missions as initial reference customers, leveraging ISRO Antrix ride-share access for low-cost orbital insertion. Pursue AI-driven on-board processing partnerships with synthetic aperture radar specialists to differentiate against established imagery operators. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated constellation operators controlling satellite build through data delivery, particularly those with recurring revenue models in defense-adjacent commercial markets. Long-term viability favors entities with demonstrated conjunction assessment capabilities and propulsion-equipped fleet heritage, as regulatory filtering intensifies across the analysis window. Monitor FCC active deorbit system rulemaking timeline as inflection indicator for hardware redesign capex cycles and vendor consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Propulsion Subsystem Acquisition | Captive supply of miniaturized electric thrusters secures FCC compliance and excludes unqualified competitors from defense procurement. |
| ISO 17770 Certification Investment | Reliability benchmarking accelerates insurance underwriting and filters market access toward qualified satellite manufacturers. |
| Ground Station Network Expansion | Direct TT&C infrastructure reduces dependency on legacy defense networks and enables payload optimization without protocol compromise. |
| AI-Driven On-Board Processing Partnership | Edge computing convergence with synthetic aperture radar reduces downlink bandwidth requirements and ground infrastructure costs. |
| Scottish Manufacturing Footprint Expansion | Glasgow assembly lines serve European institutional clients with shortened procurement cycles compared to US defense programs. |
Study Parameters
Multiple input streams — constellation operator procurement directors, satellite systems engineers at vertically integrated manufacturers, FCC licensing attorneys, and insurance underwriters specializing in on-orbit coverage — were reconciled against secondary validation from FAA Office of Commercial Space Transportation filings, FCC orbital debris mitigation rulemaking dockets, ISO 17770 reliability standards documentation, and NASA-STD-8719.14 safety guidelines. Primary interviews with defense program managers at Space Force modernization offices and commercial data buyers at maritime shipping insurers were cross-referenced with SEC filings from publicly traded satellite operators and customs records for aluminum alloy frame and solar array imports. Bottom-up unit economics modeling and top-down market sizing triangulation were applied across the analysis window.
Historical deployment volume trajectories were cross-referenced against expert panel inputs from astrodynamics specialists and launch manifest planners to construct segmentation-specific forecasts. Modeled dimensions span satellite type, launch method, end user category, and application vertical, with additional granularity on propulsion system configuration and collision avoidance capability tier. CAGRs were derived from slope analysis of ride-share launch cost compression curves and defense procurement cycle acceleration patterns. Industry-specific forecast inputs include SpaceX Falcon 9 manifest availability assumptions and FCC licensing queue processing rates.
The model holds under sustained ride-share launch economics and stable regulatory timelines; deviation in debris remediation mandate acceleration or single-source launch provider disruption would shift vendor consolidation trajectories and hardware redesign capex cycles. Forecasts reflect documented assumptions regarding defense budget priority continuity and commercial data subscription renewal rates. Periodic stress-testing of base assumptions is recommended against FCC rulemaking updates and EU Space Surveillance and Tracking enforcement patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Aviation Satellite Antenna Systems Market
Satellite
Asia-Pacific Satellite IoT Market
Satellite
Global Satellite Based Earth Observation Market
Satellite
Satellite Data Analytics Services Market
Satellite
China Satellite-Based Earth Observation Market
Satellite
Saudi Arabia Satellite Imagery Services Market
Satellite
Satellite Amplifier Market
Satellite
North America Satellite Launch Vehicle Market
Satellite
Satellite Link Emulator Market
Satellite
North America Small Satellite Market
Satellite
Russia Satellite Communications Market
Satellite
South Korea Satellite Connectivity Market
Satellite
Europe Satellite Bus Market
Satellite
Tactical Satellite Market
Satellite
North America Satellite Manufacturing and Launch Systems Market
Satellite
Satellite Parts and Components Market