
 Europe Satellite Bus Market | 2026-2036
Europe Satellite Bus Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Satellite Bus Market Insights
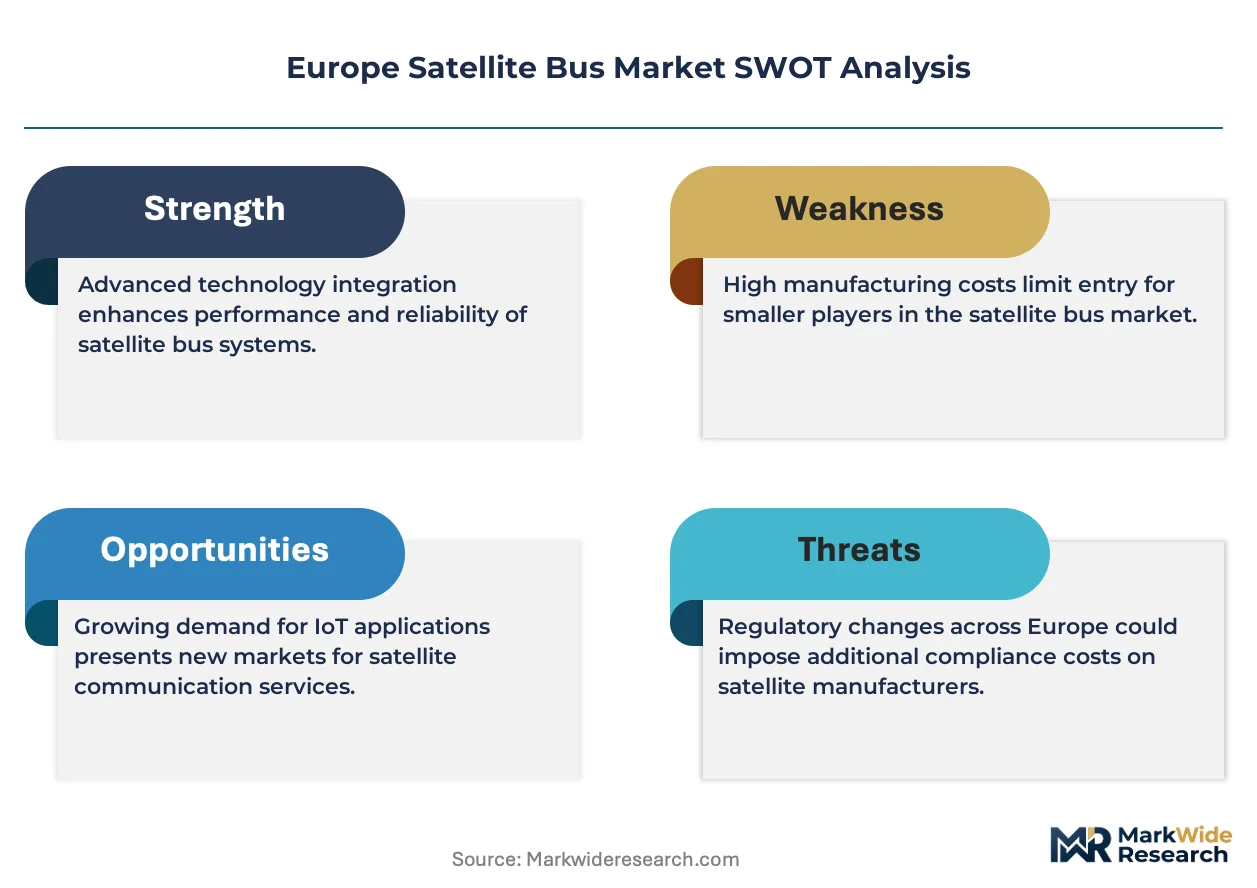
Project finance and sovereign-backed leasing structures are reshaping who can compete in European satellite bus procurement, lowering barriers for emerging constellation operators. Airbus SE leverages its integrated manufacturing footprint across France, Germany, and Spain to sustain cost advantages on large geostationary platforms. Thales Alenia Space anchors its position through dual-use technology leadership spanning civilian and defense applications. OHB SE specializes in smaller, modular bus architectures that compete aggressively for ESA science and navigation missions.
A satellite bus comprises the structural frame, power distribution, thermal control, attitude determination, propulsion, and telemetry systems that support a payload without performing the primary mission itself. European buses typically employ aluminum-lithium alloy primary structures with composite panel substrates, redundant 28-volt power buses, and bipropellant or electric propulsion for orbit maintenance. Small Satellite and Nano Satellite platforms represent the fastest-expanding product categories as constellation operators prioritize rapid replenishment cycles. Low Earth Orbit technology dominates new bookings, while Geostationary Orbit retains higher absolute margins due to longer operational lifespans and complex thermal management requirements. Aerospace Agencies and Telecommunications end users generate the largest combined revenue pool, though Commercial Enterprises represent the most volatile growth vector.
ESA procurement rules, EU Space Programme regulations, and national export control frameworks administered by France's DGAC and Germany's BAFA govern platform sourcing and technology transfer. REACH compliance and the EU Green Deal's embodied carbon requirements are forcing material substitutions in bus manufacturing, particularly in composite resins and electronics coatings. Stakeholders must monitor how IRIS² implementation timelines and evolving space debris mitigation standards under the Space Surveillance and Tracking framework reshape platform design requirements and supplier qualification criteria.
Market Dynamics
ESA's IRIS² constellation mandate and the EU Space Surveillance and Tracking framework are compressing platform development cycles while forcing simultaneous compliance with debris mitigation and carbon accounting rules.
Growth Catalysts
- IRIS² Secure Connectivity Mandate:The EU's sovereign broadband constellation program is generating multi-year procurement pipelines for medium and small satellite buses across member states.
- Earth Observation Constellation Expansion:Copernicus program augmentation is driving demand for standardized bus architectures capable of rapid replication and orbital replenishment.
- Electric Propulsion Maturation:Hall-effect and gridded ion thruster technologies are extending operational lifespans while reducing launch mass requirements for Low Earth Orbit platforms.
Market Restraints
- Launch Cost Volatility:Dependence on Ariane 6 and external launch providers creates pricing uncertainty for constellation deployment schedules.
- Supply Concentration in Toulouse-Munich Axis:Structural subsystems and avionics sourcing clusters around southwestern France and southern Germany, limiting supplier diversification.
- REACH-Compliant Material Substitution:Restrictions on hexavalent chromium coatings and specific composite resins are forcing qualification delays for thermal control components.
Strategic Opportunities
- Polish and Romanian Manufacturing Uplift:Emerging Eastern European aerospace clusters offer cost-competitive assembly capacity outside traditional Franco-German-Italian centers.
- Dual-Use Technology Convergence:Civilian Earth observation buses are incorporating military-grade encryption and anti-jamming capabilities, opening defense procurement channels.
- EU Green Deal Embodied Carbon Incentives:Manufacturers qualifying for sustainable production certifications gain preferential scoring in ESA and national agency tenders.
Industry Challenges
- Embedded Software Talent Scarcity:Flight software engineering for autonomous orbital maneuvering competes with automotive and fintech sectors for specialized programmers.
- Space Debris Mitigation Certification Complexity:Passive deorbit mechanism validation and active collision avoidance system verification extend qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Satellite Bus Market |
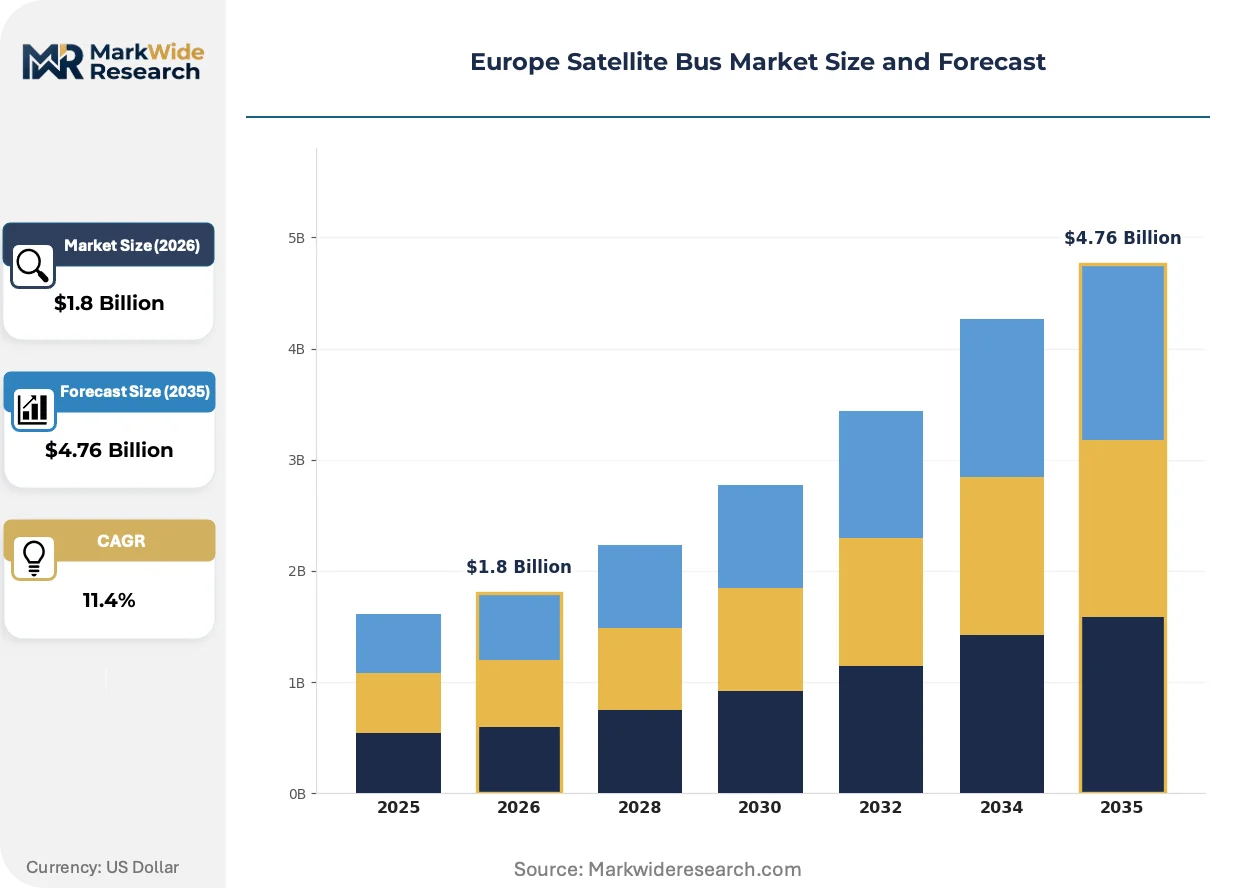
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Small Satellite, Medium Satellite, Large Satellite, Nano Satellite Technology: Geostationary Orbit, Low Earth Orbit, Medium Earth Orbit, Hybrid Orbit End User: Aerospace Agencies, Telecommunications, Research Institutions, Commercial Enterprises Service Type: Launch Services, Ground Control Services, Maintenance Services, Development Services |
| Companies Covered | Airbus SE, Thales Alenia Space, OHB SE, Honeywell International, Lockheed Martin Corporation, Northrop Grumman Corporation, AAC Clyde Space AB, GomSpace A/S, ArianeGroup, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Satellite Bus Market Trends and Innovations
Platform architectures are fragmenting between heritage geostationary designs and radically miniaturized constellation buses, with propulsion and power subsystems undergoing the most rapid technical turnover.
Electric propulsion is migrating from niche station-keeping applications to primary orbit insertion and constellation phasing maneuvers. Smallsat constellation operators in Low Earth Orbit are adopting Hall-effect thrusters as standard fit, compressing the addressable market for chemical propulsion suppliers. This technology shift is enabling single-launch deployment of twenty-plus satellite stacks, fundamentally altering launch economics and bus structural design priorities.
The EU Space Surveillance and Tracking framework is mandating end-of-life disposal reliability thresholds and active debris removal compatibility. Bus manufacturers must now integrate passive deorbit sails or active propulsion reserves into baseline designs, adding mass and complexity penalties. Geostationary platform suppliers face the steepest redesign burden, as their operational altitudes fall outside natural atmospheric decay zones.
Consolidated procurement by sovereign constellation programs is displacing fragmented national agency purchasing. ESA's batch procurement for IRIS² and Copernicus augmentation is concentrating buyer power, forcing bus suppliers toward fixed-price, multi-unit contracts with extended performance guarantees. French and German prime contractors are responding by internalizing subsystem production previously sourced from specialized suppliers.
Europe Satellite Bus Market Segmentation
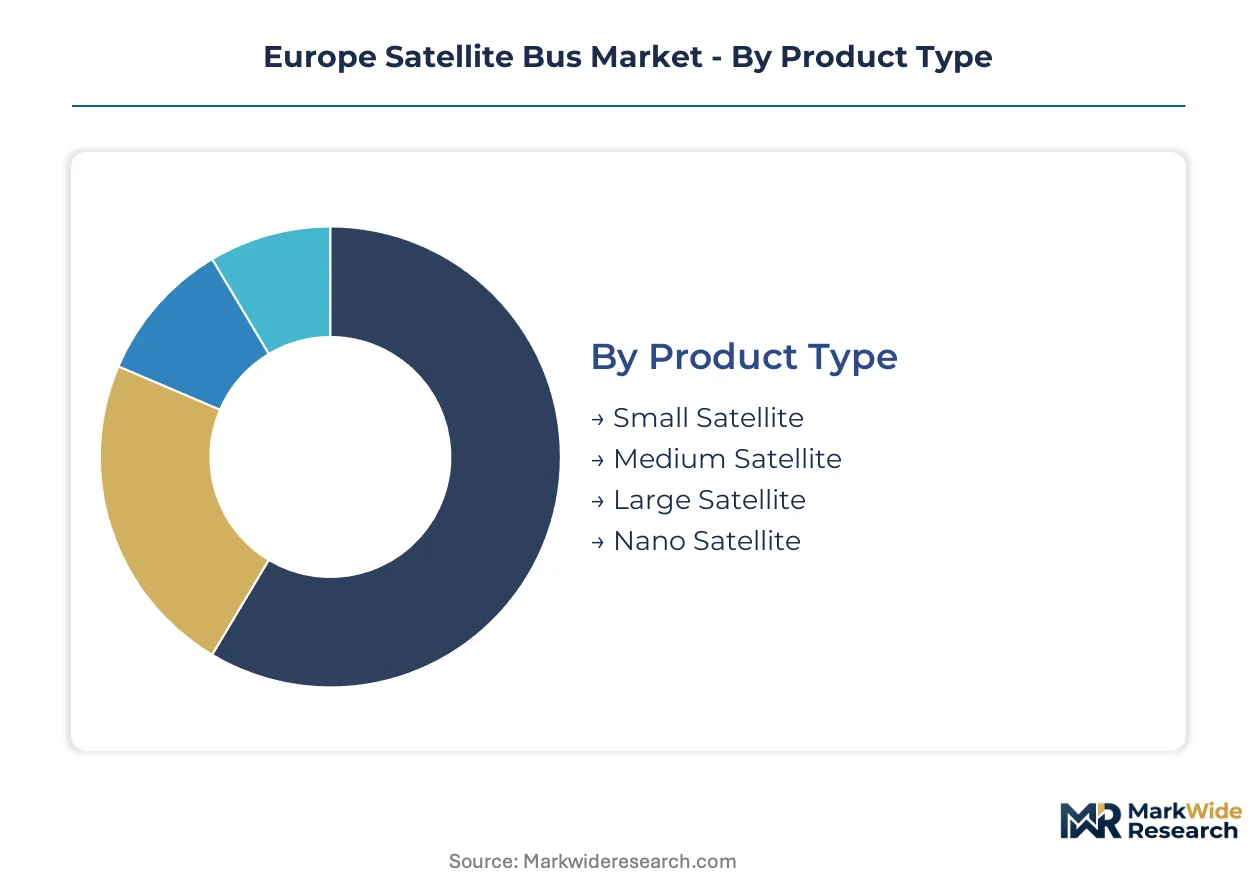
Segmentation in the Europe Satellite Bus Market reveals how procurement concentration around sovereign constellation programs is reshaping platform specifications. Bus architectures now diverge sharply between legacy geostationary designs and mass-produced small satellite platforms optimized for rapid replenishment cycles.
Product Type:
Mature large satellite platforms coexist with emerging nano satellite architectures as constellation operators prioritize disposability over longevity.
- Small Satellite:Modular bus designs weighing 100-500 kg dominate IRIS² and Copernicus augmentation tenders. French and German prime contractors are internalizing subsystem production to meet fixed-price, multi-unit contract terms for these standardized platforms.
- Nano Satellite:Sub-10 kg architectures enable single-launch deployment of twenty-plus satellite stacks, fundamentally altering launch economics. Demand concentrates among Polish and Romanian emerging operators seeking cost-competitive capacity outside traditional Toulouse-Munich supply clusters.
- Medium Satellite:500-1000 kg platforms serve dual-use Earth observation missions requiring military-grade encryption integration.
- Large Satellite:Geostationary buses retain higher absolute margins through complex thermal management and extended operational lifespans.
Small Satellite retains volume leadership; Nano Satellite holds the steepest expansion curve.
Technology:
Cost tier stratification separates premium geostationary platforms from economy-class low Earth orbit buses.
- Low Earth Orbit:Hall-effect thruster integration enables primary orbit insertion and constellation phasing maneuvers, compressing chemical propulsion's addressable market. ESA's batch procurement for IRIS² concentrates buyer power on these standardized platforms.
- Geostationary Orbit:Operational altitudes outside natural atmospheric decay zones impose the steepest redesign burden under EU Space Surveillance and Tracking disposal reliability mandates. Italian and Spanish operators maintain procurement preference for these high-margin platforms.
- Medium Earth Orbit:Navigation constellation buses require precise atomic clock integration and radiation-hardened avionics.
- Hybrid Orbit:Dual-purpose architectures serving both Earth observation and secure communications face extended qualification timelines.
Low Earth Orbit dominates new bookings volume; Hybrid Orbit climbs the fastest as dual-use requirements converge.
End User:
Customer type fragmentation separates sovereign-backed volume procurement from volatile commercial demand patterns.
- Aerospace Agencies:ESA and national space agencies generate the largest combined revenue pool through multi-year procurement pipelines. REACH-compliant material substitutions and EU Green Deal embodied carbon requirements are forcing qualification delays in thermal control component sourcing.
- Commercial Enterprises:Constellation operators represent the most volatile growth vector as project finance and sovereign-backed leasing structures lower market entry barriers. Demand volatility tracks launch cost uncertainty tied to Ariane 6 deployment schedules.
- Telecommunications:Secure broadband mandates under IRIS² are displacing fragmented national agency purchasing with consolidated sovereign programs.
- Research Institutions:Science missions prioritize modular bus architectures capable of rapid payload reconfiguration.
Aerospace Agencies retain volume leadership; Commercial Enterprises hold the steepest expansion curve.
Service Type:
Supply concentration across the service stack favors integrated prime contractors over specialized subsystem vendors.
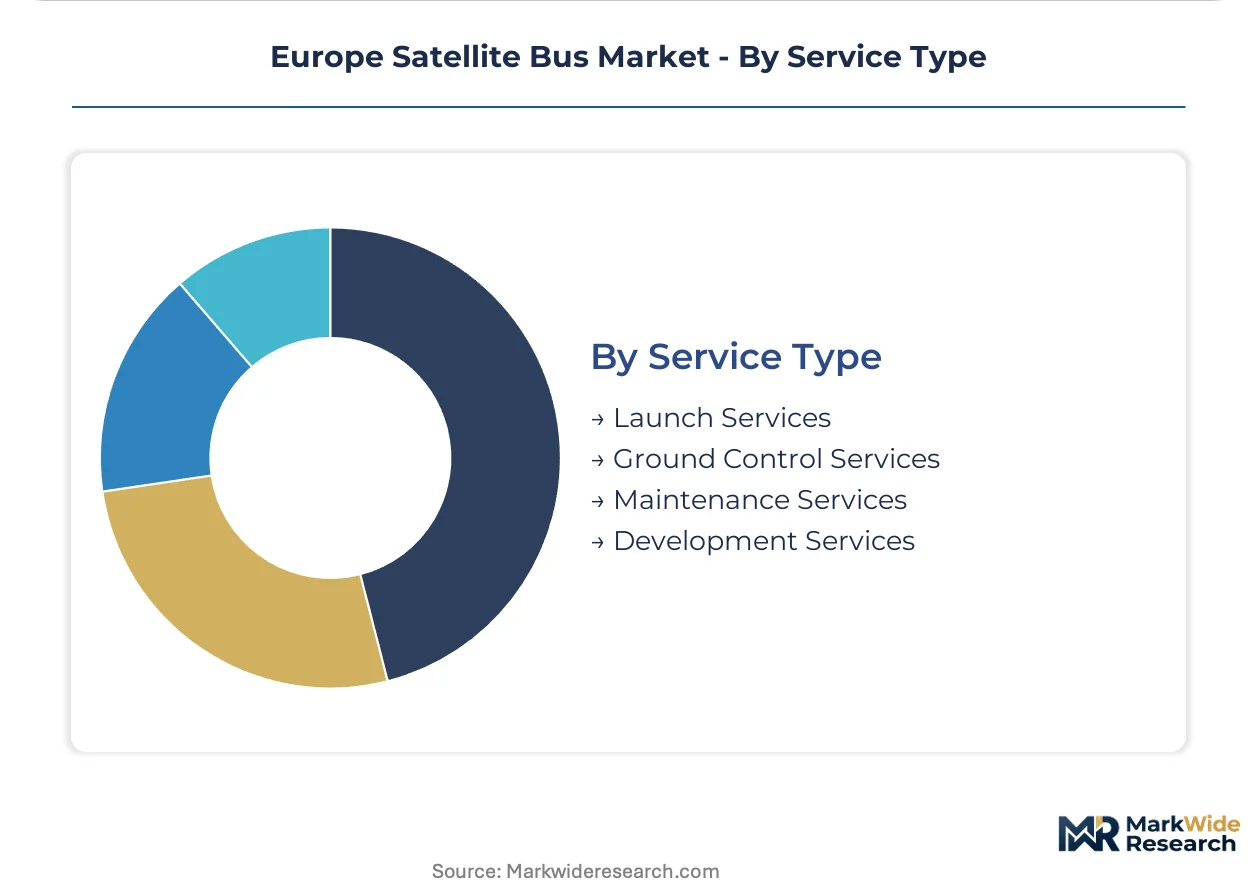
- Development Services:Flight software engineering for autonomous orbital maneuvering competes with automotive and fintech sectors for specialized programmers. French DGAC and German BAFA export control frameworks govern technology transfer in these engagements.
- Ground Control Services:Military-grade encryption and anti-jamming capabilities are opening defense procurement channels previously restricted to civilian Earth observation buses.
- Launch Services:Dependence on Ariane 6 and external providers creates pricing uncertainty for constellation deployment schedules.
- Maintenance Services:Electric propulsion maturation is extending operational lifespans while reducing on-orbit servicing requirements.
Development Services retains volume leadership; Ground Control Services holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ESA procurement concentration and sovereign constellation mandates concentrate buyer power in France, Germany, and Italy, while emerging Eastern European assembly capacity is reshaping supplier geography.
France
Toulouse anchors European satellite bus manufacturing through Airbus SE and Thales Alenia Space integrated facilities. DGAC export control frameworks govern technology transfer for dual-use platforms. The Occitanie aerospace cluster concentrates structural subsystem and avionics sourcing for IRIS² and Copernicus programs.
Germany
Munich and Bremen host OHB SE and ArianeGroup production sites specializing in modular small satellite architectures. BAFA national export control administration regulates component sourcing for science and navigation missions. Bavaria's precision manufacturing base supplies electric propulsion thrusters and radiation-hardened electronics.
Italy
Rome and Turin maintain procurement preference for geostationary platforms through Thales Alenia Space Italian operations. National space agency ASI coordinates with ESA on Earth observation constellation expansion. Piedmont's aerospace supply chain delivers thermal control components and composite structures.
United Kingdom
Surrey Satellite Technology heritage and emerging Scottish spaceports position the UK for small satellite export manufacturing. UK Space Agency funding supports modular bus development for commercial constellation operators. Harwell Science and Innovation Campus clusters payload integration and ground control service providers.
Poland
Warsaw and emerging regional aerospace hubs offer cost-competitive assembly capacity outside traditional Franco-German centers. EU structural funds accelerate cleanroom and test facility investment. Polish operators leverage REACH-compliant material substitution incentives to qualify for ESA tender preferential scoring.
Europe Satellite Bus Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three structural tiers. Prime contractors with sovereign agency relationships dominate large platform procurement through integrated manufacturing footprints. Mid-tier modular specialists capture small satellite volume via standardized architectures. Niche electric propulsion and flight software vendors supply subsystems under fixed-price, multi-unit contract pressure. Consolidation is accelerating through internalization of previously outsourced structural and avionics production.
Within the prime contractor tier, Airbus SE represents integrated European manufacturing spanning France, Germany, and Spain. Thales Alenia Space exemplifies dual-use technology convergence across civilian and defense applications. OHB SE anchors the modular specialist segment with smaller bus architectures for ESA science missions.
| Leading Market Players |
|---|
| Airbus SE |
| Thales Alenia Space |
| OHB SE |
| Honeywell International |
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| AAC Clyde Space AB |
| GomSpace A/S |
| ArianeGroup |
| Others |
Pricing and Supply Chain Analysis
The Toulouse-Munich freight corridor's elevated logistics costs amplify price spreads between Franco-German prime contractors and Eastern European assembly alternatives, compressing margins for mid-tier suppliers while rewarding integrated manufacturers with captive subsystem production.
Pricing Analysis
Cost-plus contracts with aerospace-grade aluminum-lithium alloy indexation dominate ESA and national agency procurement, insulating prime contractors from raw material volatility while exposing specialized subsystem vendors to margin compression. Price differentiation separates heritage geostationary platforms with extended performance guarantees from standardized small satellite buses sold on fixed-price, multi-unit terms. Pricing pressure intensifies as sovereign constellation programs consolidate buyer power through batch procurement for IRIS² and Copernicus augmentation. Commercial constellation operators exhibit the highest price sensitivity, while defense procurement channels tolerate premium positioning for military-grade encryption integration.
Supply Chain Analysis
Supplier-financing facilities with 180-day extended payment terms have become standard for avionics and thermal control component vendors serving Toulouse and Munich primes. Manufacturing gravity centers on France, Germany, and Italy for structural subsystems and flight software, while Poland and Romania emerge as cost-competitive assembly alternatives. The supply chain draws from aluminum-lithium alloy mills in southern Germany, radiation-hardened electronics fabricators in Bavaria, and REACH-compliant composite resin suppliers in northern Italy. Single-source vulnerability concentrates in Hall-effect thruster production anchored in German precision manufacturing clusters. Distribution runs through ESA-coordinated procurement frameworks and national space agency tender processes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Satellite Bus Market exhibits cyclical recovery characteristics as sovereign constellation deployment schedules accelerate following Ariane 6 operational certification, releasing pent-up procurement demand deferred from earlier launch uncertainty.
For Market Incumbents: Pre-empt margin erosion in small satellite buses by internalizing electric propulsion subsystem production currently sourced from specialized Bavarian vendors. Consolidate position through backward integration into aluminum-lithium alloy machining capacity in Toulouse and Munich, reducing exposure to aerospace metal price indexation. Counter Polish and Romanian emerging competitors by leveraging ESA relationship depth for preferential scoring on IRIS² batch awards. For New Entrants and Emerging Players: Establish a beachhead in nano satellite ground control services, where military-grade encryption integration creates defense procurement access without requiring full platform manufacturing capability. Target Polish and Romanian aerospace clusters for cost-competitive assembly partnerships outside traditional Toulouse-Munich supply concentration. Pursue ESA technology transfer programs as the primary go-to-market channel for qualification of REACH-compliant thermal control components. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with non-core satellite subsystem divisions facing fixed-price contract pressure from consolidated sovereign procurement. Long-term viability hinges on positioning within electric propulsion or autonomous flight software niches as constellation replenishment cycles accelerate. Watch IRIS² implementation timeline adherence as the critical inflection signal for procurement volume release.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Propulsion Integration | Hall-effect thruster internalization captures margin from Bavarian specialist suppliers. |
| REACH-Compliant Material Certification | EU Green Deal qualification unlocks preferential ESA tender scoring. |
| Dual-Use Technology Convergence | Military-grade encryption integration opens defense procurement channels. |
| Eastern European Assembly Expansion | Polish and Romanian capacity reduces cost base outside Toulouse-Munich axis. |
| Batch Procurement Contract Structuring | Fixed-price, multi-unit terms align with ESA IRIS² consolidated buying power. |
Research Methodology
Cross-validation between executive interviews at French and German prime contractors and ESA procurement documentation anchors the qualitative findings on sovereign constellation demand patterns. Primary fieldwork encompassed satellite platform engineering directors, ESA program managers, national space agency procurement leads, and thermal control subsystem specialists. Secondary validation drew from ESA tender announcements, EU Space Programme regulation filings, REACH compliance databases, and national export control registers. Bottom-up segment sizing triangulated against top-down aerospace agency budget appropriation analysis.
Calibration against historical ESA contract award patterns and ArianeGroup launch manifest disclosures informed the analytical framework across the projection horizon. Segmentation dimensions modeled include platform mass class, orbital regime, end-user procurement type, and propulsion architecture. CAGRs derived from unit economics analysis of disclosed contract values and platform deployment schedules. Industry-specific forecast inputs encompassed electric propulsion technology maturation curves and EU Space Surveillance and Tracking compliance cost burdens.
Sensitivities concentrate around Ariane 6 deployment reliability and REACH material substitution qualification timelines. Forecasts reflect assumptions on sovereign budget continuity and constellation replenishment cycle acceleration. Macroeconomic contraction affecting national space agency appropriations, regulatory expansion of debris mitigation requirements, or breakthrough advances in low-cost launch alternatives would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
China Satellite Imagery Services Market
Satellite
Optical Satellite Communication Market
Satellite
Satellite Communication Equipment Market
Satellite
UK Satellite-Based Earth Observation Market
Satellite
North America Satellite Bus Market
Satellite
M2M Satellite Communication Market
Satellite
Satellite Operation Service Market
Satellite
Indonesia Satellite Communications Market
Satellite
Electric Propulsion Satellite Market
Satellite
Fixed Satellite Services (FSS) Market
Satellite
Satellite Communication System Market
Satellite
Italy Satellite Imagery Services Market
Satellite
LEO and GEO Satellite Market
Satellite
Global Satellite Modem Market
Satellite
North America Satellite IoT Market
Satellite
Eastern Europe and North Africa Satellite Communication Market