
 Global Nanosatellite and Microsatellite Market | 2026-2036
Global Nanosatellite and Microsatellite Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nanosatellite and Microsatellite Market Foresight
The FCC's streamlined small-satellite licensing framework is realigning the cost-of-entry calculus for new constellation operators. Planet Labs leverages its integrated manufacturing-to-imagery pipeline to sustain rapid refresh rates for Earth observation customers. Sierra Nevada Corporation anchors its position through specialized small-satellite buses designed for defense and scientific payloads. NanoAvionics competes by offering modular platform architectures that reduce integration timelines for commercial missions.
Nanosatellites and microsatellites are spacecraft with wet masses between 1 kg and 100 kg, typically employing standardized CubeSat form factors with aluminum alloy frames and off-the-shelf electronic components to achieve orbital functionality at radically lower cost than traditional satellites. Their primary purpose is to deliver targeted data services—Earth imagery, communications relay, or scientific measurements—from low-Earth orbit constellations that can be deployed incrementally. The satellite type dimension shows nanosatellites capturing the fastest growth trajectory as ride-share launch availability expands, while microsatellites retain the deepest margin pools due to their greater payload flexibility and longer operational lifespans. Within the application dimension, Earth observation dominates current deployment volumes as commercial operators and defense organizations seek persistent revisit capabilities over strategic areas.
The FCC in the United States, ESA's regulatory coordination across Europe, and China's SAMR standards collectively shape market access through spectrum allocation, debris mitigation requirements, and export control classifications that determine which technologies cross borders. NASA's Commercial Lunar Payload Services program and the EU Space Programme are redirecting procurement toward qualified small-satellite vendors, tightening the link between certification and contract eligibility. Stakeholders must monitor how national security reviews of foreign-owned satellite operators reshape partnership structures and supply chain geography.
Market Dynamics
Ride-share launch economics are compressing constellation deployment costs below the threshold where commercial operators can amortize hardware across shorter mission lifespans, triggering a wave of capital reallocation toward rapid-refresh orbital architectures.
Growth Catalysts
- FCC Streamlined Licensing:The FCC's small-satellite licensing framework reduces approval timelines for US operators, enabling faster constellation deployment cycles and lower pre-launch capital lockup.
- Earth Observation Demand:Precision agriculture operators in the US and Germany are contracting persistent revisit capabilities, driving volume commitments that justify dedicated manufacturing lines.
- Standardized CubeSat Form Factors:Aluminum alloy frame standardization is automating integration workflows, cutting assembly labor hours and enabling parallel production across multiple facilities.
Market Restraints
- Launch Capacity Concentration:Ride-share availability clusters with SpaceX and a handful of Chinese providers, creating queue bottlenecks that delay revenue-generating operations for months.
- Radiation-Hardened Component Costs:Off-the-shelf electronics face higher failure rates in low-Earth orbit, forcing tradeoffs between mission lifespan and hardware expenditure that erode unit economics.
- Spectrum Allocation Friction:ITU coordination timelines and national licensing fragmentation in Europe and Asia-Pacific extend time-to-first-revenue beyond initial capital planning horizons.
Strategic Opportunities
- Defense Procurement Pipelines:NATO member states and the US Department of Defense are qualifying small-satellite vendors for tactical communications and ISR missions, opening premium-margin contract channels.
- Scientific Payload Convergence:Universities and national space agencies in Germany and Japan are bundling instruments across shared bus architectures, spreading fixed costs across multiple research programs.
- In-Space Servicing Infrastructure:Emerging orbital tugging and refueling capabilities are extending operational lifespans for microsatellites, improving return-on-asset calculations for fleet operators.
Industry Challenges
- RF Engineering Talent Scarcity:Demand for phased-array antenna specialists and embedded flight software engineers exceeds supply in the US and European labor markets, inflating compensation costs and project delays.
- Debris Mitigation Compliance:ESA's design-for-demise requirements and FCC orbital disposal rules impose additional subsystem mass and complexity penalties that reduce payload capacity margins.
- Supply Chain Reconfiguration:Export control reclassifications under US ITAR and EU dual-use regulations are forcing component sourcing shifts that disrupt qualified vendor relationships and restart qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nanosatellite and Microsatellite Market |
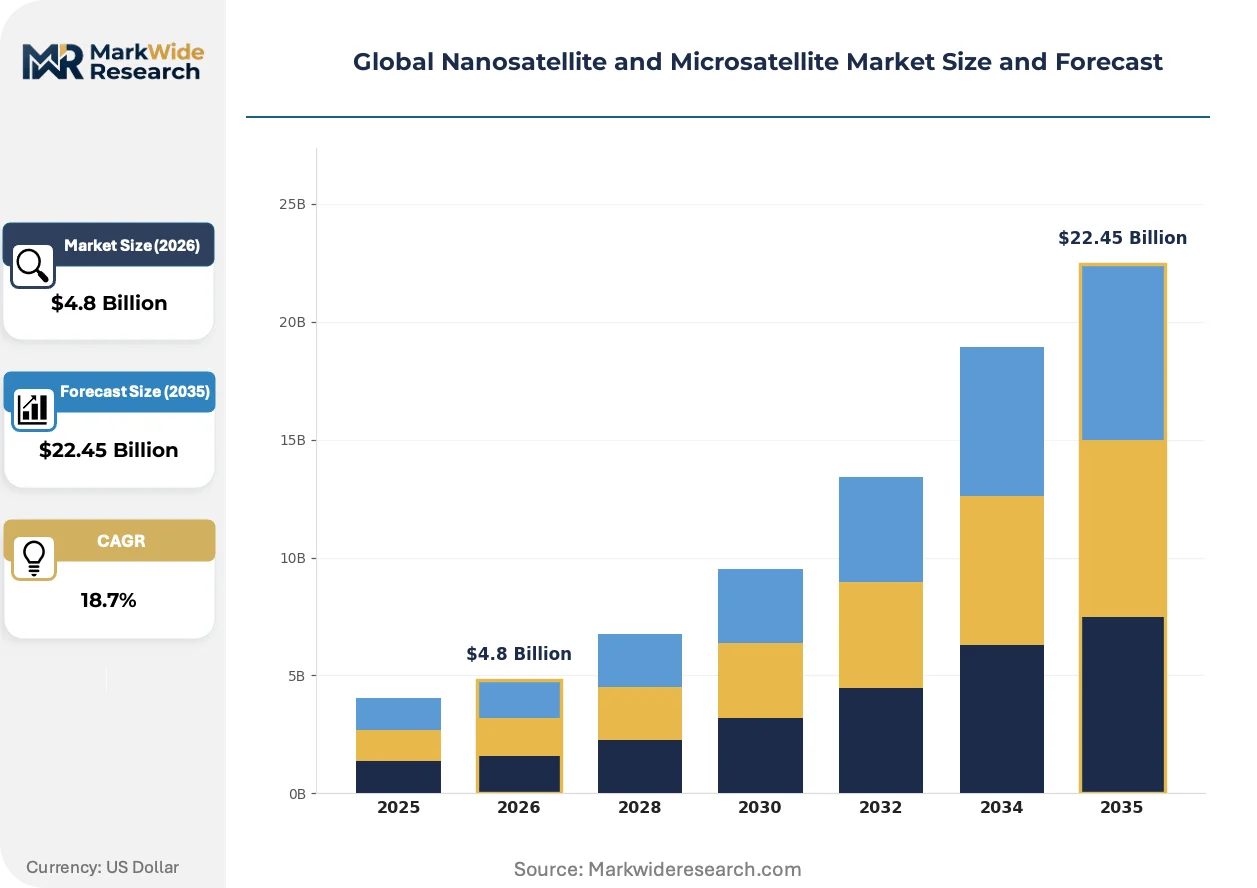
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.45 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Satellite Type: Nanosatellites, Microsatellites, Minisatellites, Picosatellites Technology: CubeSat, SmallSat Bus, Modular Sat, PicoSat Architecture Application: Earth Observation, Scientific Research, Telecommunications, Space Exploration End User: Space Agencies, Defense Organizations, Research Institutions, Commercial Operators |
| Companies Covered | Planet Labs, Sierra Nevada Corporation, Surrey Satellite Technology Ltd., GomSpace, Lockheed Martin Corporation, AAC Clyde Space, Tyvak Nano-Satellite Systems, Inc., NanoAvionics, Spire Global, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nanosatellite and Microsatellite Market Shifts & Advancements
Software-defined payload architectures are displacing fixed-function hardware, enabling operators to reconfigure mission parameters post-launch and extend asset utility across multiple revenue streams.
Artificial intelligence-driven autonomous operations is automating spacecraft health monitoring, anomaly detection, and orbital maneuver planning. Commercial constellation operators in the US and China are deploying these systems to reduce ground station staffing requirements and compress response latency for time-critical imaging tasks. The technology is automating the shift from crew-intensive mission control to lights-out operations, restructuring cost models toward variable bandwidth rather than fixed labor.
ESA's debris mitigation guidelines and the FCC's orbital disposal mandates are hardening design requirements across European and US manufacturing bases. Satellite builders must now demonstrate passive de-orbit capability or active removal systems, adding subsystem mass and testing protocols that extend development schedules. Microsatellite platforms above 50 kg wet mass face the steepest compliance penalties, pushing some operators toward smaller form factors that qualify for simplified regulatory pathways.
Subscription-based imagery and data-service contracts are displacing traditional perpetual-license sales in Earth observation segments. Agriculture and insurance underwriters in Germany and the US are favoring pay-per-acre or event-triggered pricing that aligns vendor compensation with measurable outcome delivery. This model compresses customer switching costs and intensifies competitive pressure on refresh rates and data latency performance.
Global Nanosatellite and Microsatellite Market Segmentation
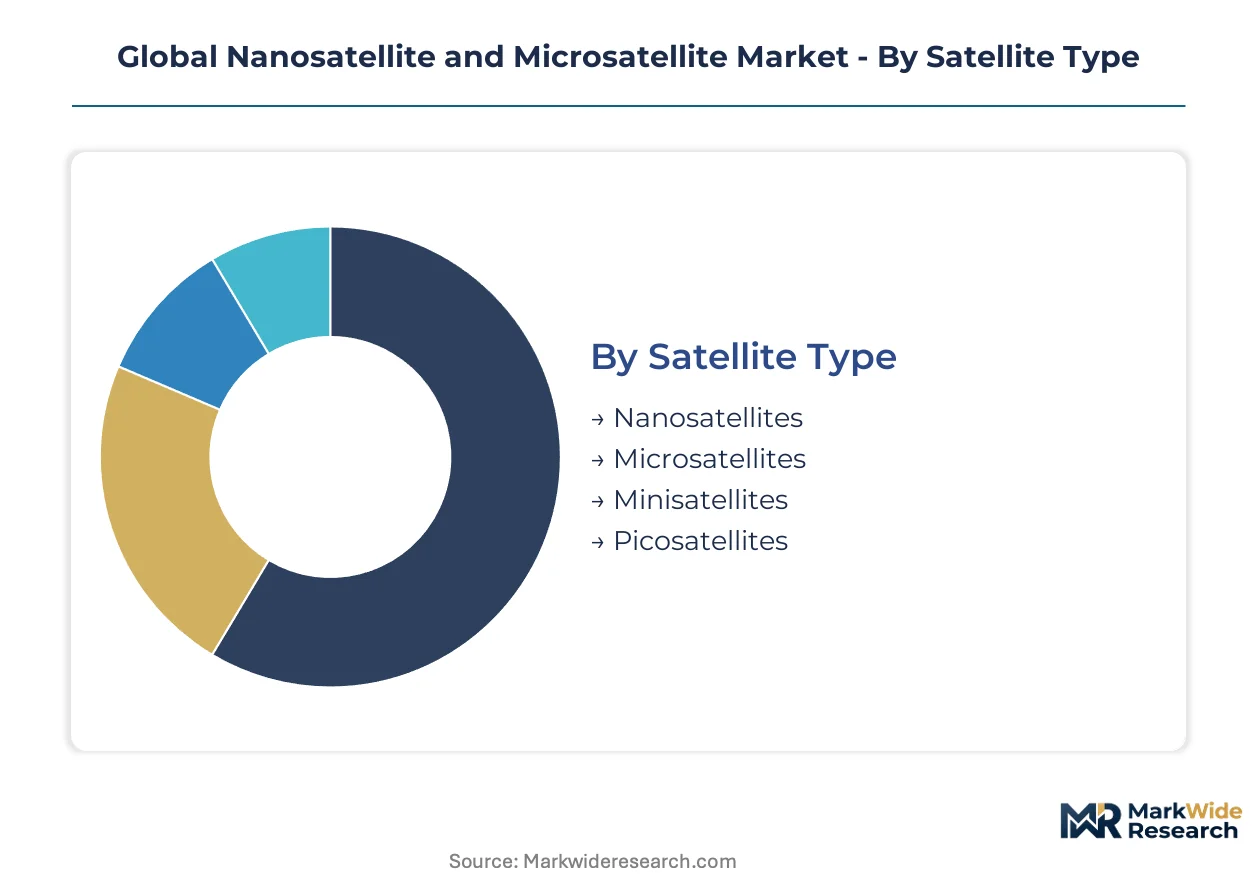
Nanosatellite and microsatellite markets fragment across four critical dimensions: physical scale, architectural approach, mission purpose, and procurement authority. Each segmentation axis reveals distinct margin structures, qualification barriers, and technology refresh cycles that determine vendor positioning.
Satellite Type:
Replacement cycles accelerate as ride-share economics compress mission lifespans from decade-long assets to refreshable orbital infrastructure. Operators now design for 3-5 year operational windows rather than 15-year traditional satellite durability.
- Nanosatellites:Wet masses between 1-10 kg deploy standardized CubeSat frames with commercial off-the-shelf electronics. Persistent revisit contracts from US precision agriculture operators and German logistics firms concentrate demand for rapid-refresh constellations. Ride-share launch availability from SpaceX and Chinese providers enables incremental deployment without dedicated mission costs.
- Microsatellites:10-100 kg platforms accommodate larger aperture optics and radiation-hardened power systems. Defense organizations in the United States and NATO member states favor this class for tactical communications and ISR payloads requiring greater payload flexibility and extended orbital lifespans.
- Minisatellites:100-500 kg wet mass bridges traditional small-satellite and full-scale spacecraft categories.
- Picosatellites:Sub-1 kg platforms serve university research programs and technology demonstration missions with minimal subsystem redundancy.
Volume placements concentrate in nanosatellites; the faster expansion belongs to microsatellites.
Technology:
Cost tiers separate qualified vendors from commodity integrators based on flight heritage and subsystem reliability.
- CubeSat:Aluminum alloy frame standardization with 10×10×10 cm unit modules enables parallel manufacturing across multiple facilities. Automated integration workflows cut assembly labor hours. German and Japanese research institutions bundle instruments across shared bus architectures.
- SmallSat Bus:Proprietary platform designs from Sierra Nevada Corporation and specialized vendors anchor defense and scientific procurement pipelines. Custom power distribution and thermal management subsystems command premium margins.
- Modular Sat:Interchangeable payload interfaces reduce integration timelines for commercial missions.
- PicoSat Architecture:Minimalist designs prioritize launch access over operational durability.
Flight heritage accumulates fastest in CubeSat implementations; the steepest margin expansion sits with SmallSat Bus platforms.
Application:
Customer type determines pricing power and contract duration across mission categories.
- Earth Observation:Multispectral and synthetic aperture radar payloads deliver persistent coverage for agriculture, insurance, and defense intelligence. Subscription-based contracts from German underwriters and US commodity traders displace perpetual licenses with pay-per-acre or event-triggered pricing.
- Scientific Research:Universities and national space agencies in Germany and Japan spread fixed costs across shared instrumentation programs. NASA's Commercial Lunar Payload Services redirects procurement toward qualified small-satellite vendors.
- Telecommunications:Narrowband IoT relay and store-forward messaging constellations serve remote asset monitoring.
- Space Exploration:Technology demonstration and precursor missions to lunar and cislunar orbits.
Contract velocity runs highest in Earth Observation; the longest qualification timelines attach to Space Exploration.
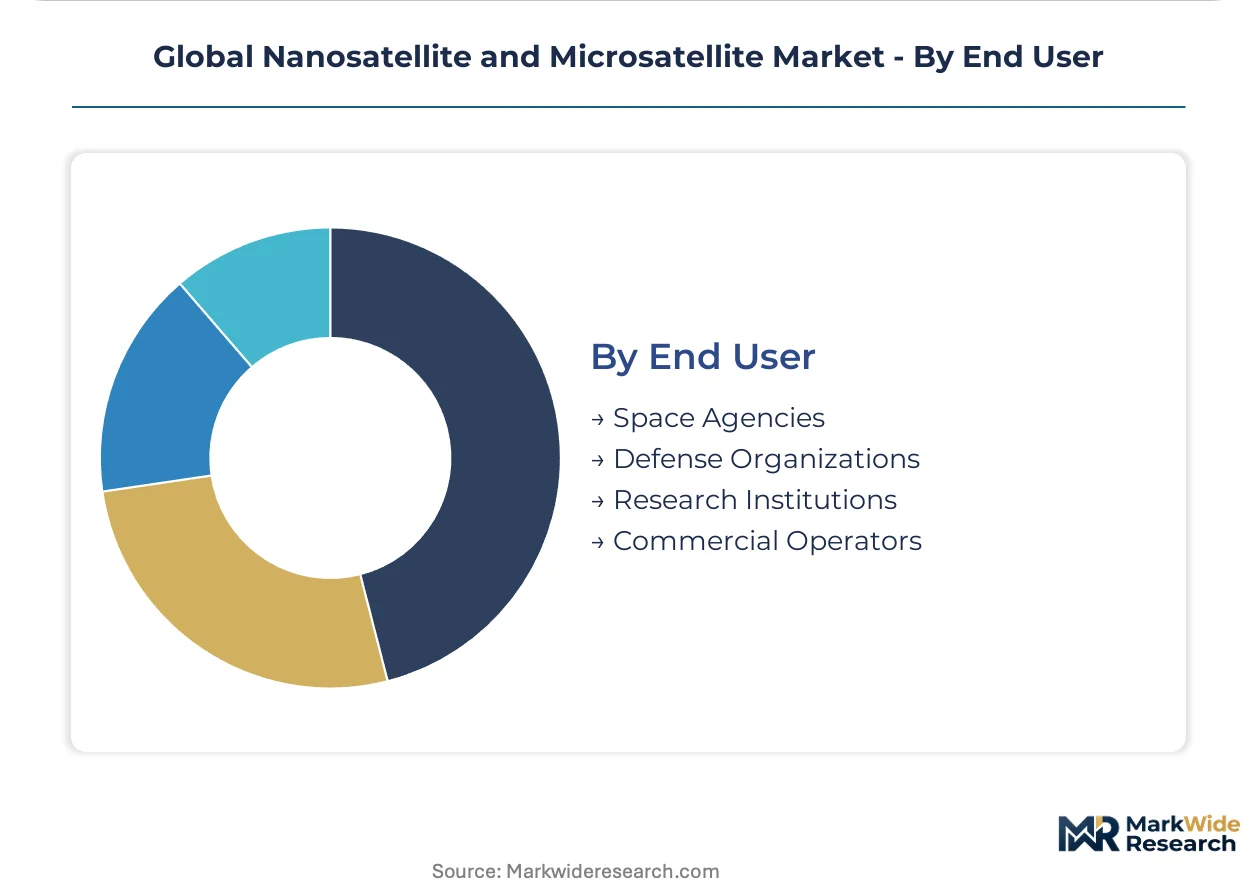
End User:
Supply concentration varies sharply across procurement authority types, with defense and space agency channels demanding distinct certification regimes.
- Space Agencies:NASA, ESA, and national programs impose rigorous environmental testing and orbital debris mitigation compliance. The FCC's streamlined licensing and ESA's design-for-demise requirements filter vendor eligibility.
- Defense Organizations:US Department of Defense and NATO member states qualify vendors through security clearance and ITAR-controlled supply chain verification. Premium-margin tactical communications contracts reward specialized small-satellite bus manufacturers.
- Research Institutions:University programs prioritize launch access and cost minimization over operational lifespan.
- Commercial Operators:Planet Labs and agricultural logistics firms scale constellation deployments based on refresh rate economics and data latency performance.
Procurement volume clusters with Commercial Operators; the tightest vendor qualification standards apply to Defense Organizations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spaceport development zones in Florida and California concentrate US launch infrastructure, while Germany's Bavaria and China's Hubei province anchor satellite manufacturing clusters through targeted R&D tax credits and special economic zone status.
United States
Defense procurement pipelines and precision agriculture contracts drive constellation deployment volumes. The FCC's streamlined small-satellite licensing framework compresses approval timelines from months to weeks. Cape Canaveral and Vandenberg Space Force Base host the densest ride-share launch queues, with SpaceX dominating orbital insertion capacity for commercial operators.
China
National space program budgets and commercial IoT demand accelerate small-satellite production scale-up. SAMR technical standards and spectrum allocation rules govern market access for domestic and foreign operators. Wuhan and Shanghai manufacturing corridors specialize in CubeSat frame production and payload integration for regional constellation deployments.
Germany
Insurance underwriters and logistics operators contract persistent Earth observation services, creating stable demand for revisit-capable microsatellites. ESA's design-for-demise debris mitigation requirements filter vendor eligibility for European procurement. Munich and Stuttgart industrial clusters concentrate specialized bus manufacturers serving defense and scientific research missions.
Japan
Universities and METI-funded research programs bundle instruments across shared small-satellite architectures to spread fixed mission costs. National space agency qualification standards prioritize flight heritage and radiation-hardened subsystem reliability. Tokyo-Osaka corridor facilities automate integration workflows for standardized nanosatellite platforms.
United Kingdom
Scotland's emerging spaceport infrastructure and Surrey-based satellite engineering heritage position the country for vertical launch and manufacturing integration. UK Space Agency funding redirects procurement toward qualified small-satellite vendors for Earth observation and telecommunications missions. Glasgow and Edinburgh clusters specialize in software-defined payload development for commercial constellation operators.
Global Nanosatellite and Microsatellite Market Competitive Landscape
United States producers anchor one tier; European specialists hold certification advantages in ESA-qualified procurement channels. The vendor base separates into three strata: integrated constellation operators with captive manufacturing, specialized bus designers serving defense and scientific markets, and modular platform integrators targeting rapid commercial deployment cycles. Consolidation pressure intensifies as ride-share economics compress mission lifespans and reward fleet scale. Strategic partnerships between launch providers and satellite builders, plus backward integration into component manufacturing, represent the dominant competitive moves reshaping supplier relationships.
Within the integrated operator tier, Planet Labs and Spire Global exemplify end-to-end control from manufacturing through data service delivery. Sierra Nevada Corporation occupies a position among specialized bus designers, anchoring defense-oriented procurement pipelines through proprietary platform architectures. These three entities represent distinct strategic archetypes: vertical integration for refresh-rate economics, premium positioning through mission-specific customization, and modular scalability for commercial volume deployment.
| Leading Market Players |
|---|
| Planet Labs |
| Sierra Nevada Corporation |
| Surrey Satellite Technology Ltd. |
| GomSpace |
| Lockheed Martin Corporation |
| AAC Clyde Space |
| Tyvak Nano-Satellite Systems, Inc. |
| NanoAvionics |
| Spire Global, Inc. |
| Others |
Supply & Pricing Matrix
Subscription contract preferences from German insurance underwriters and US precision agriculture operators are compressing acceptable price points for Earth observation data services, forcing manufacturers to automate CubeSat integration workflows and source aluminum alloy frames from higher-volume Chinese suppliers to preserve margin.
Pricing Analysis
Lead-time premiums dominate pricing differentiation in the small-satellite procurement channel. Three-tier pricing structure across premium, standard, and economy levels separates flight-proven bus platforms from first-mission CubeSat integrators and university demonstrator kits. Price differentiation hinges on radiation-hardened component certification and volume scale of constellation orders. Cost compression in the economy tier is intensifying because ride-share launch queue congestion extends time-to-revenue for smaller operators. Commercial Earth observation fleet operators exhibit the highest price sensitivity; defense procurement channels show the least.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale constellation operator demand for standardized nanosatellite platforms, while specialized bus manufacturers serve defense contractors through security-cleared distribution networks. Manufacturing gravity centers on the United States, China, and Germany for frame fabrication and payload integration. The supply chain draws from gallium arsenide solar cells, radiation-hardened field-programmable gate arrays, and precision reaction wheels as critical inputs. Single-source vulnerability concentrates in SpaceX-dominated ride-share launch capacity. Distribution runs through qualified vendor lists maintained by NASA, ESA, and national defense procurement offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around fleet-scale operators capable of amortizing manufacturing investments across rapid-refresh constellations; ride-share economics are squeezing sub-scale players unable to secure queue priority.
For Market Incumbents: Lock in launch queue priority through multi-mission block buys with SpaceX and Chinese providers. Anchor backward integration into aluminum alloy frame production and solar cell qualification to defend against modular platform competitors. The FCC's streamlined licensing timeline advantage erodes for operators without captive manufacturing throughput. For New Entrants and Emerging Players: Capture scientific payload bundling opportunities across German and Japanese university consortiums seeking shared bus architectures. The most penetrable segment sits with regional IoT constellation operators in Southeast Asia and Latin America lacking indigenous manufacturing. A go-to-market angle through modular platform leasing with integrated launch brokerage reduces capital barriers. For Investors and Strategic Acquirers: The window for entry favors vertically integrated constellation operators with demonstrated flight heritage and defense qualification pathways. Long-term viability rests on securing recurring subscription revenue from agriculture and insurance verticals rather than transactional hardware sales. Watch for FCC licensing backlog expansion as an inflection signal indicating queue congestion pricing power shifting toward launch providers.| Strategic Initiative | Industry Significance |
|---|---|
| Launch Queue Block Purchase | Multi-mission agreements with SpaceX secure orbital insertion priority for commercial constellation operators. |
| Software-Defined Payload Integration | Reconfigurable mission architectures extend asset utility across Earth observation and telecommunications revenue streams. |
| Defense Qualification Pathway | ITAR-controlled supply chain certification opens premium-margin tactical communications procurement channels. |
| Regional Manufacturing Footprint | Production facilities in Germany and China reduce logistics exposure to export control reclassifications. |
| Subscription Service Transition | Pay-per-acre pricing models align vendor compensation with measurable agricultural outcome delivery. |
Research Methodology
Independent corroboration across constellation operator executives, launch provider sales directors, and defense procurement officers underwrites the qualitative findings in this study. Primary interviews with satellite bus engineering leads, ground station operations managers, and regulatory affairs specialists at FCC and ESA were cross-referenced against secondary validation from SEC filings of publicly traded operators, NASA Commercial Lunar Payload Services contract announcements, and ESA procurement databases. Bottom-up unit deployment estimates and top-down addressable market sizing were reconciled through iterative triangulation.
Rate-of-change decomposition across the analysis window segments volume trajectories by satellite type, application, and end-user procurement authority. The analytical framework models nanosatellite versus microsatellite refresh cycles, Earth observation subscription contract velocity, and defense qualification pipeline throughput as core segmentation dimensions. CAGRs were derived from fitted growth curves applied to historical deployment data and projected launch capacity expansion. Industry-specific inputs include ride-share launch queue depth and radiation-hardened component lead time fluctuations.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ITAR export control reclassifications and debris mitigation mass penalty revisions. Forecasts reflect documented assumptions regarding SpaceX launch pricing stability and Chinese provider market access continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Saudi Arabia Satellite Communications Market
Satellite
Saudi Arabia Satellite Imagery Services Market
Satellite
Low-Cost Satellite Market
Satellite
Global Enterprise VSAT System Market
Satellite
Global Commercial Satellite Broadband Market
Satellite
Europe Military Satellite Market
Satellite
Spain Satellite Imagery Services Market
Satellite
LEO Satellite Constellation Market
Satellite
Satellite Communication (SATCOM) Market
Satellite
Israel Satellite Imagery Services Market
Satellite
Russia Satellite Communications Market
Satellite
Global Maritime Satellite Communication Market
Satellite
Europe Satellite Manufacturing and Launch Systems Market
Satellite
France Satellite Imagery Services Market
Satellite
France Satellite-Based Earth Observation Market
Satellite
UK Satellite-Based Earth Observation Market