
 North America Small Satellite Market | 2026-2036
North America Small Satellite Market Size, Share, and Industry Trends Forecast 2026-2036
North America Small Satellite Market Analytics
Aftermarket service revenue is narrowing as manufacturers pursue captive lifecycle contracts. Space Exploration Technologies Corp leverages vertical integration across launch and satellite production to capture recurring service streams. Ball Corporation sustains its position through specialized optical payload manufacturing for government missions. Planet Labs Inc anchors its model with high-frequency Earth imagery subscriptions that reduce customer capital expenditure.
A small satellite denotes a spacecraft with mass below 500 kilograms, typically employing commercial off-the-shelf electronics, standardized form factors, and modular subsystems for rapid assembly. These platforms deliver remote sensing data, communications relay, and scientific measurement functions at fractionated cost structures compared to traditional geostationary spacecraft. NanoSat and MicroSat categories lead current production volumes due to their compatibility with rideshare launch economics and constellation architectures. Earth Observation applications command the largest revenue share while Technology Demonstration segments show the fastest expansion as startups validate novel sensors and propulsion systems.
The Federal Communications Commission governs spectrum allocation and orbital debris mitigation requirements for commercial operators, while the FAA Office of Commercial Space Transportation regulates launch licensing and safety protocols. NASA's CubeSat Launch Initiative and the Department of Defense's Space Development Agency create parallel demand channels through dedicated procurement programs. Stakeholders must monitor evolving debris mitigation rules and spectrum auction outcomes to calibrate constellation deployment schedules and capital allocation priorities.
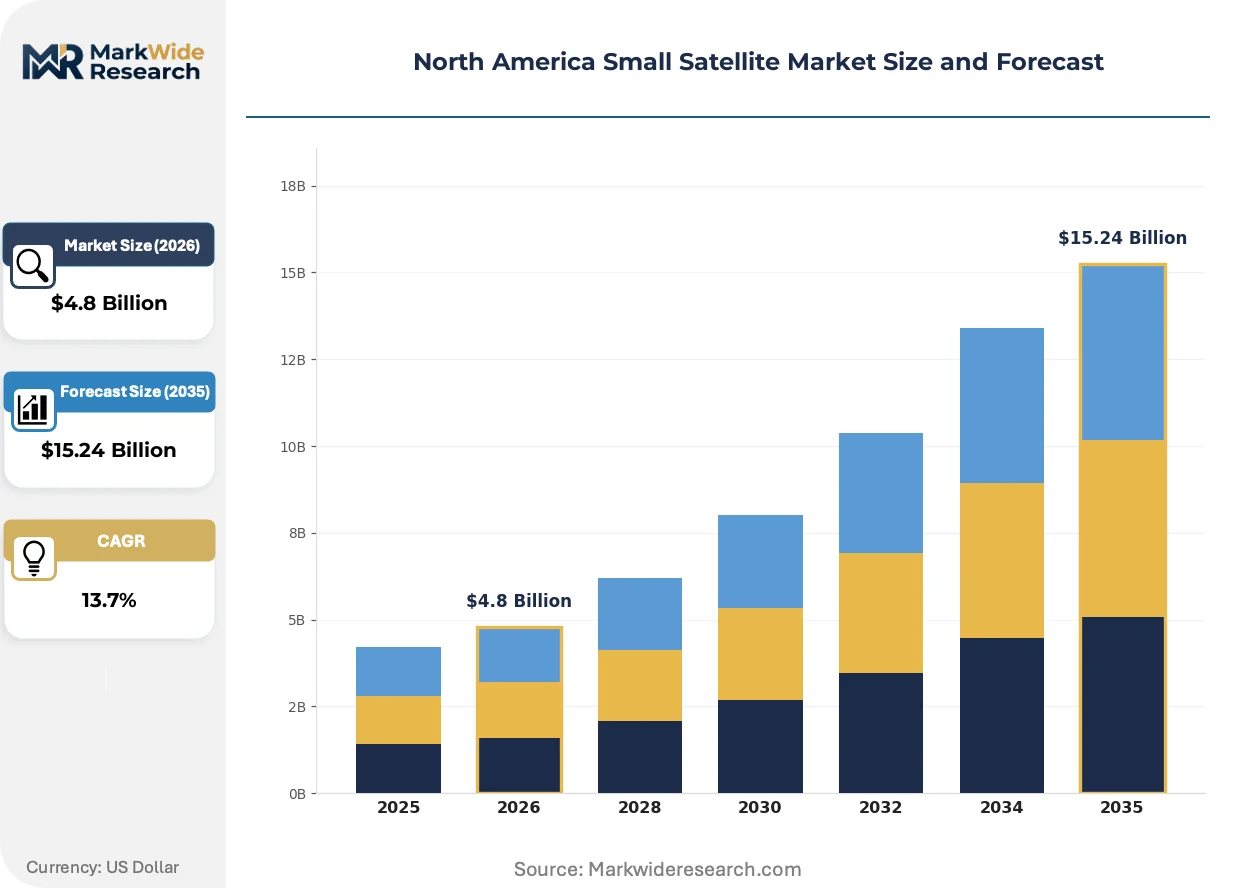
Market Dynamics
The FCC's streamlined Part 25 licensing framework compresses deployment timelines from 24 months to under six months, accelerating constellation buildouts across the United States and Canada. This regulatory velocity is concentrating manufacturing activity within California's aerospace corridor while pulling venture capital toward rapid-iteration satellite startups.
Growth Catalysts
- Orbital debris mitigation rules:The FCC's updated disposal requirements mandate deorbit timelines within five years post-mission, stimulating demand for propulsion miniaturization and active debris removal services.
- Precision agriculture analytics:Crop monitoring providers in the US Midwest and Canadian prairies are contracting high-revisit Earth observation constellations to optimize irrigation and yield forecasting.
- Rideshare launch economics:Secondary payload opportunities aboard SpaceX Falcon 9 and Rocket Lab Electron flights reduce per-kilogram launch costs for university and government CubeSat programs.
Market Restraints
- Radio frequency spectrum scarcity:Ka-band and V-band congestion around 27 GHz limits constellation expansion for broadband providers, forcing costly coordination with incumbent geostationary operators.
- Launch capacity concentration:Three providers control over 90% of small satellite launch slots to sun-synchronous orbit, creating queue bottlenecks for commercial operators.
- Optical payload supply constraints:Specialized sensor-grade silicon carbide mirrors face 18-month procurement lead times from a single German supplier base.
Strategic Opportunities
- Canadian Arctic connectivity:Indigenous communities and resource extraction operators across Nunavut and the Northwest Territories lack reliable broadband, creating addressable demand for LEO relay constellations.
- Hyperspectral imaging convergence:Integration of short-wave infrared sensors with machine learning classification algorithms opens defense and mineral exploration contracts previously served by aerial platforms.
- NASA's Commercial Lunar Payload Services:The Artemis program's demand for lunar orbiters and surface communicators offers qualification pathways for radiation-hardened small satellite buses.
Industry Challenges
- Radiation-hardened electronics procurement:Qualified component vendors number fewer than fifteen globally, constraining production scaling for missions beyond low Earth orbit.
- ITAR compliance complexity:US State Department export controls on satellite subsystems fragment supply chains, preventing Canadian and Mexican partners from accessing critical propulsion technologies.
- Integration with legacy ground infrastructure:Defense and intelligence customers require compatibility with 1990s-era S-band tracking networks, forcing expensive waveform adaptation onto modern software-defined radios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Small Satellite Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.24 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Satellite Type: CubeSat, NanoSat, MicroSat, PicoSat Application: Earth Observation, Communication, Scientific Research, Technology Demonstration End User: Government, Commercial, Educational Institutions, Military Launch Vehicle: Dedicated Launchers, Rideshare, Small Launch Vehicles, Hybrid Solutions |
| Companies Covered | Space Exploration Technologies Corp, Ball Corporation, Capella Space Corp, Planet Labs Inc, LeoStella, Northrop Grumman, Lockheed Martin Corporation, L3Harris Technologies Inc, Sierra Nevada Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Small Satellite Market Evolving Landscape
Propulsion miniaturization and software-defined payloads are compressing satellite refresh cycles from decade-long replacements to three-year technology insertions. These shifts are fragmenting traditional prime contractor relationships while elevating subsystem specialists.
Electric propulsion systems utilizing iodine as a propellant alternative to xenon are rendering obsolete chemical thruster architectures for station-keeping and deorbit maneuvers. Constellation operators in the United States are adopting iodine-fed Hall-effect thrusters for 150-kilogram platforms, cutting propellant mass fractions from 15% to 4% and extending operational lifespans without launch mass penalties.
The FCC's September 2024 orbital debris mitigation order imposes casualty risk thresholds below 1 in 10,000 for uncontrolled reentries. This regulatory pressure is forcing satellite designers to incorporate deployable drag sails and dedicated propulsion for controlled deorbit, with the greatest compliance burden falling on university CubeSat programs lacking prior flight heritage in active disposal systems.
Service contracts are unbundling hardware ownership from data delivery across Earth observation verticals. Agricultural analytics providers in California's Central Valley now subscribe to daily imagery feeds rather than procuring dedicated satellites, compressing customer capital deployment and shifting revenue recognition toward recurring software licensing models.
North America Small Satellite Market Segmentation
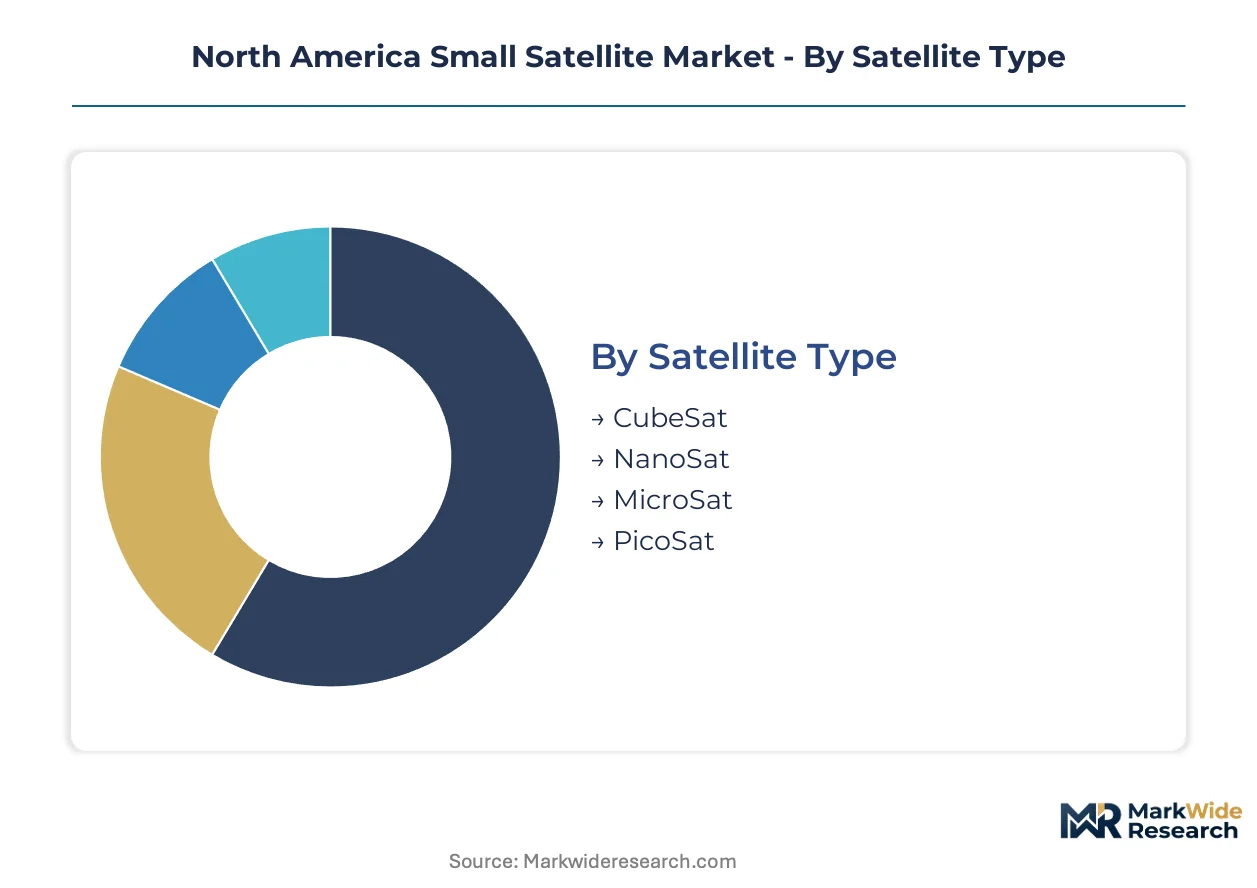
Segmentation reveals how small satellite demand fragments across mass classes, mission profiles, and procurement channels. Each dimension carries distinct margin structures and regulatory exposure that shape vendor positioning.
Satellite Type:
Mature platforms dominate current revenue while emerging form factors capture venture funding for novel constellations.
- CubeSat:Standardized 10x10x10 cm units deploy from commercial launchers and ISS cargo vehicles. University programs across California and Texas concentrate procurement here, constrained by FCC debris mitigation rules requiring active disposal systems for sub-5 kg platforms lacking natural orbital decay.
- NanoSat:1-10 kg spacecraft integrate commercial off-the-shelf electronics with standardized backplanes. Agricultural analytics providers in the US Midwest contract high-revisit NanoSat constellations for crop monitoring, driving demand for compact optical payloads and software-defined radios.
- MicroSat:10-100 kg buses accommodate dedicated propulsion and steerable antennas. Defense and intelligence agencies favor this class for responsive space missions requiring rapid reconstitution.
- PicoSat:Sub-1 kg platforms deploy as technology demonstrators and educational payloads. Limited operational utility restricts commercial adoption outside university CubeSat Launch Initiative slots.
NanoSat handles the majority of throughput; Technology Demonstration missions are expanding most quickly on share.
Application:
Volume concentrates in established service verticals while experimental categories attract subsystem innovation.
- Earth Observation:Multispectral and hyperspectral imaging platforms deliver daily revisit coverage for precision agriculture and defense intelligence. California's Central Valley growers subscribe to imagery feeds rather than owning hardware, shifting revenue toward recurring data licensing.
- Communication:LEO relay constellations provide broadband to Canadian Arctic communities lacking fiber infrastructure. Indigenous nations across Nunavut represent addressable demand as FCC spectrum auctions allocate Ka-band capacity.
- Scientific Research:Ionospheric monitoring and space weather sensors support NASA heliophysics missions. University principal investigators compete for limited ride-share slots to sun-synchronous orbit.
- Technology Demonstration:Novel propulsion, artificial intelligence, and quantum communication payloads qualify for operational missions. Startups in Los Angeles and San Francisco Bay Area clusters leverage rapid iteration to compress validation timelines.
Earth Observation commands the largest revenue base; Technology Demonstration climbs the fastest as venture capital flows toward unproven sensor architectures.
End User:
Procurement authority separates stable program funding from cyclical commercial investment.
- Government:NASA and NOAA missions prioritize climate monitoring and space situational awareness. Multi-year appropriations provide predictable demand despite federal budget volatility.
- Commercial:Agricultural analytics, maritime tracking, and broadband providers operate on private capital cycles. Venture funding concentration in California aerospace corridors accelerates constellation deployment timelines.
- Educational Institutions:University CubeSat programs access subsidized launch through NASA's CubeSat Launch Initiative. FCC debris mitigation compliance burdens strain programs lacking prior flight heritage in active disposal.
- Military:Space Development Agency proliferated architectures demand responsive launch and rapid reconstitution. ITAR controls fragment supply chains, preventing Canadian and Mexican partners from accessing critical propulsion technologies.
Commercial end users drive volume expansion; Military procurement is gaining share fastest through Space Development Agency proliferated architectures.
Launch Vehicle:
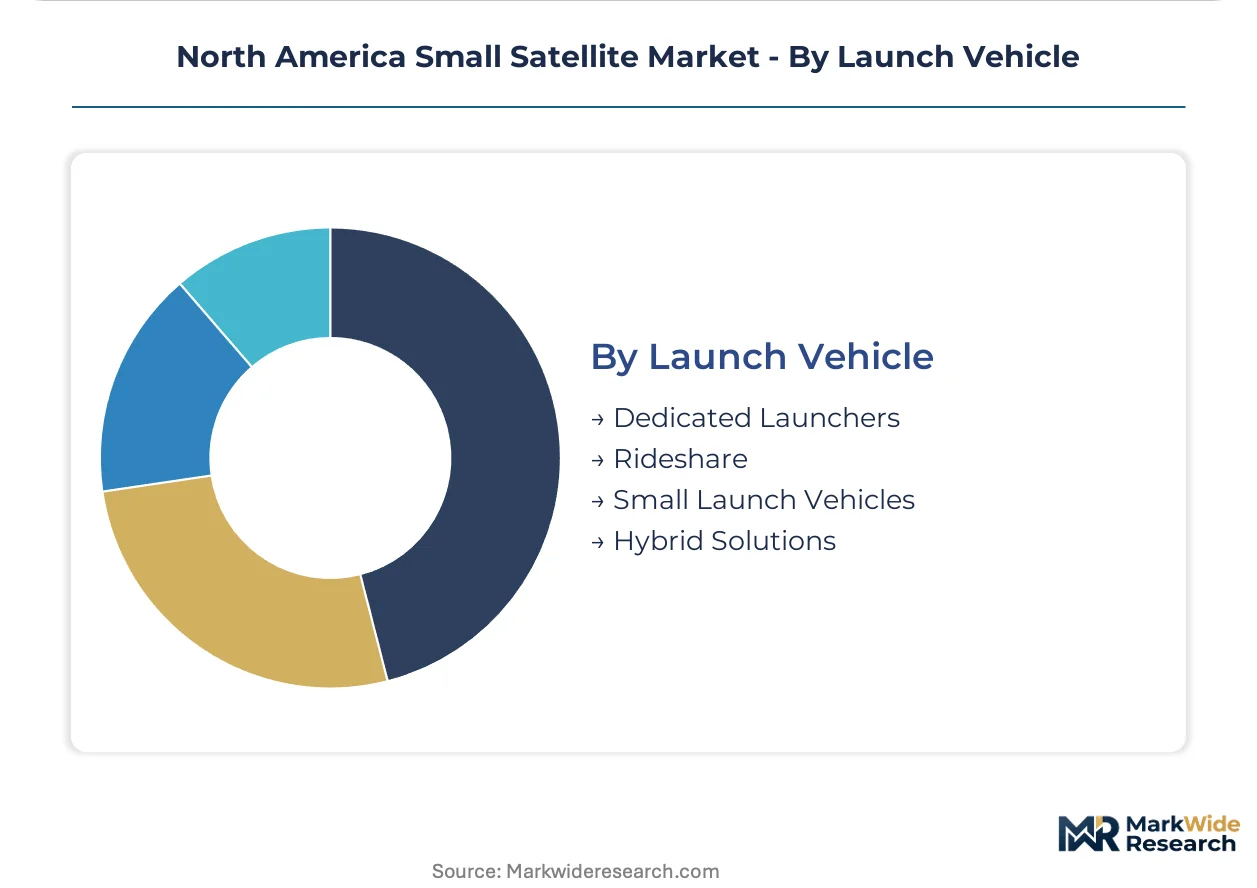
Cost structure and schedule certainty vary dramatically across access modes.
- Dedicated Launchers:Single-manifest missions offer precise orbital insertion and schedule control. Premium pricing restricts adoption to high-value government and military payloads.
- Rideshare:Secondary payload opportunities aboard Falcon 9 and Electron flights reduce per-kilogram costs. Queue bottlenecks emerge as three providers control over 90% of small satellite slots to sun-synchronous orbit.
- Small Launch Vehicles:Purpose-built rockets like Rocket Lab Electron serve responsive launch requirements. Limited payload capacity constrains MicroSat and larger platform deployment.
- Hybrid Solutions:Multi-manifest missions combine dedicated and rideshare elements for constellation deployment. Emerging operators in Texas and Florida test orbital transfer vehicles to extend rideshare flexibility.
Rideshare handles the majority of throughput; Hybrid Solutions are climbing fastest as constellation operators seek schedule-certainty compromises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada deploys small satellites primarily for Arctic connectivity and broadband gap-filling, while the United States concentrates on commercial Earth observation constellations and defense-responsive architectures. Mexico's emerging space program emphasizes technology demonstration and university partnerships rather than operational service delivery.
United States
Commercial Earth observation providers and defense-responsive space missions drive procurement volumes across the country. The FCC's streamlined Part 25 licensing framework compresses deployment timelines from 24 months to under six months for constellation operators. California's aerospace corridor spanning Los Angeles and San Francisco Bay Area clusters concentrates manufacturing activity and venture capital flows toward rapid-iteration satellite startups.
Canada
Indigenous communities and resource extraction operators across Nunavut and the Northwest Territories generate demand for LEO relay constellations addressing broadband infrastructure gaps. The Canadian Space Agency's CubeSat program provides subsidized launch access for university technology demonstration missions. Ontario and Quebec host emerging satellite component suppliers serving both domestic operators and cross-border aerospace supply chains.
Mexico
University CubeSat programs and government technology demonstration initiatives constitute the primary demand channel for sub-50 kg platforms. The Mexican Space Agency coordinates rideshare launch opportunities through NASA's CubeSat Launch Initiative and bilateral agreements with US operators. Mexico City and Querétaro host emerging aerospace engineering talent pools supporting regional satellite subsystem integration.
North America Small Satellite Market Competitive Landscape
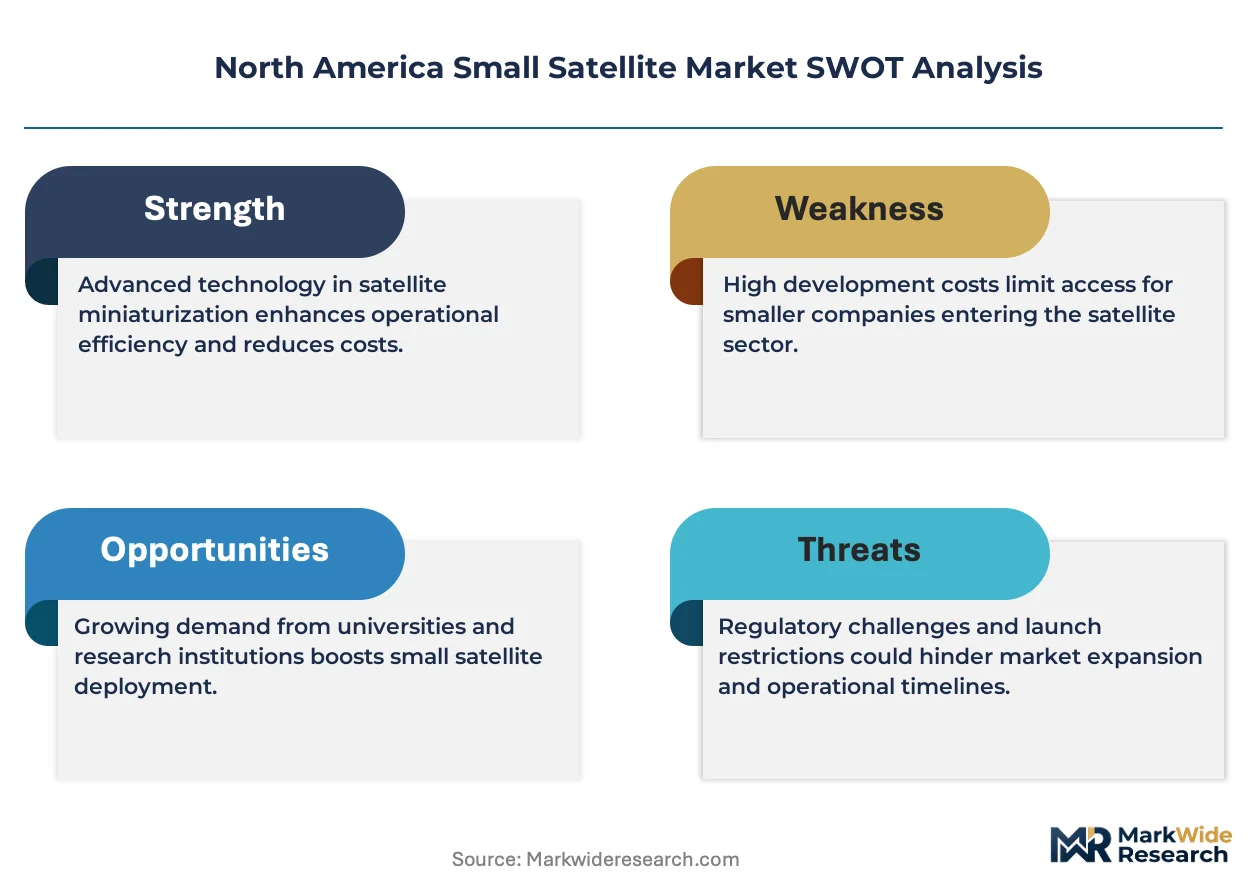
Capability concentration sits with vertically integrated launch-and-satellite producers; scale advantage sits with specialized component manufacturers serving multi-customer demand. The vendor base separates into three functional tiers: full-stack operators controlling launch through data delivery, payload specialists supplying optical and RF subsystems, and bus integrators assembling standardized platforms for mission-specific customization. Consolidation pressure intensifies as full-stack operators capture recurring service revenue previously accruing to hardware vendors. Dominant competitive moves include backward integration into propulsion and sensor manufacturing, plus captive service contract structures displacing aftermarket revenue streams.
Within the full-stack operator tier, Space Exploration Technologies Corp exemplifies vertical integration across launch and satellite production, while Planet Labs Inc anchors the Earth observation subscription model. Ball Corporation occupies a position among specialized optical payload manufacturers serving government mission requirements. These three entities represent distinct competitive archetypes: launch-captured hardware ownership, data-as-a-service platform economics, and precision component supply to mission-critical programs.
| Leading Market Players |
|---|
| Space Exploration Technologies Corp |
| Ball Corporation |
| Capella Space Corp |
| Planet Labs Inc |
| LeoStella |
| Northrop Grumman |
| Lockheed Martin Corporation |
| L3Harris Technologies Inc |
| Sierra Nevada Corporation |
| Others |
Value Network & Pricing Analysis
German silicon carbide mirror suppliers command 18-month procurement lead times, concentrating margin capture upstream while satellite integrators downstream absorb schedule risk and quality premiums. This upstream bottleneck shapes contract structures across the North American value chain, forcing downstream players to lock capacity early or accept extended delivery windows.
Pricing Analysis
Long-term offtake agreements dominate procurement for radiation-hardened electronics and specialized optical payloads, while spot-market transactions govern commercial off-the-shelf components and rideshare launch slots. Price differentiation rests on ITAR certification tier and launch schedule certainty, with defense missions paying premiums for priority orbital insertion. Pricing pressure stems from rideshare queue bottlenecks as three providers control over 90% of sun-synchronous access. University CubeSat programs exhibit highest price sensitivity, while Space Development Agency proliferated architectures demonstrate lowest sensitivity due to mission-critical requirements.
Supply Chain Analysis
Contract manufacturing concentrates with Tier 1 satellite bus integrators in California's Los Angeles corridor and specialized payload foundries in the San Francisco Bay Area. Geographic supply concentration spans Germany for optical substrates, Taiwan for radiation-hardened semiconductors, and domestic cleanrooms for final assembly. Raw material dependencies include silicon carbide for mirrors, iodine for electric propulsion, and space-grade aluminum alloys for structural bus components. Single-source vulnerability in German optical supply creates exposure to transatlantic logistics disruption. Distribution runs through direct OEM relationships for government missions and subscription platforms for commercial Earth observation data.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from vertically integrated launch operators capturing recurring service revenue previously accruing to hardware vendors, demanding defensive repositioning across the value chain.
For Market Incumbents: Insulate margin pools by securing captive supply agreements with German optical substrate suppliers and pursuing backward integration into iodine-fed propulsion manufacturing. The SpaceX Starlink service model threatens standalone satellite manufacturers with disintermediation. Priority investment in FCC Part 25 licensing expertise accelerates customer deployment timelines and locks out slower competitors. For New Entrants and Emerging Players: Canadian Arctic connectivity gaps represent the most penetrable entry point, with Indigenous communities across Nunavut lacking reliable broadband infrastructure and underserved by incumbent LEO constellations. Technology demonstration missions for NASA's Commercial Lunar Payload Services offer qualification pathways with lower competitive density than Earth observation. Go-to-market execution should emphasize software-defined payload architectures enabling rapid sensor reconfiguration without hardware replacement. For Investors and Strategic Acquirers: Capital is best deployed toward subsystem specialists with ITAR-cleared manufacturing and proven flight heritage in active debris mitigation systems. Long-term viability over the coming decade hinges on regulatory compliance capabilities as FCC disposal mandates tighten. The signal to watch is Space Development Agency procurement acceleration indicating defense demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propulsion | Captive iodine Hall-effect thruster production cuts propellant mass fractions from 15% to 4%. |
| FCC Part 25 Licensing Investment | Deployment timeline compression from 24 months to under six months accelerates constellation buildouts. |
| Arctic Connectivity Partnership | Indigenous nation contracts across Nunavut address broadband gaps left by incumbent operators. |
| Active Debris Mitigation Certification | Deployable drag sail and controlled deorbit capabilities satisfy FCC casualty risk thresholds. |
| Hyperspectral Sensor Development | Short-wave infrared integration opens defense and mineral exploration contracts from aerial platforms. |
Research Methodology
Desk research of FCC licensing databases, NASA procurement records, and satellite industry trade publications preceded structured interviews with constellation operators, launch service providers, and optical payload engineers. Primary fieldwork captured demand-side perspectives from agricultural analytics providers in California's Central Valley and defense program managers at the Space Development Agency. Secondary validation drew from FAA launch manifests, Canadian Space Agency funding disclosures, and university CubeSat program documentation. Bottom-up unit economics modeling triangulated against top-down addressable market sizing across the analysis window.
Assumption sets held fixed the FCC's five-year deorbit mandate and current ITAR export control frameworks while varying rideshare launch cost trajectories and Ka-band spectrum auction outcomes. Segmentation dimensions modeled include satellite mass class, application vertical, end-user procurement channel, and launch vehicle access mode. CAGRs derived from logistic diffusion curves fitted to constellation deployment schedules and subscription revenue recognition patterns. Industry-specific forecast inputs encompassed SpaceX Falcon 9 manifest density and Planet Labs imagery feed pricing evolution.
Macroeconomic conditions sit as an overlay; deviation in venture capital availability for rapid-iteration startups and federal defense appropriations volatility would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory stability and launch provider market concentration. Quarterly review of FCC debris mitigation rulemaking and Space Development Agency procurement announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Germany Satellite-Based Earth Observation Market
Satellite
Optical Satellite Communication Market
Satellite
Asia-Pacific Small Satellite Market
Satellite
Spain Satellite Imagery Services Market
Satellite
Satellite Communication Equipment Market
Satellite
Medium and Large Satellite Market
Satellite
Russia Satellite-Based Earth Observation Market
Satellite
China Satellite Connectivity Market
Satellite
South Korea Satellite Imagery Services Market
Satellite
Global Satellite Modem Market
Satellite
Europe Satellite Connectivity Market
Satellite
Satellite Market
Satellite
Europe Satellite Bus Market
Satellite
Satellite Data Analytics Services Market
Satellite
Sudan Satellite Transponder Market
Satellite
Europe Satellite Attitude and Orbit Control System Market