
 Endothelial Dysfunction Market | 2026-2036
Endothelial Dysfunction Market Size, Share, and Industry Trends Forecast 2026-2036
Endothelial Dysfunction Market Foresight
Hospital-based cardiovascular departments are redrawing procurement priorities for endothelial assessment tools, while homecare and clinic segments recede in relative share. Abbott Laboratories leverages its diagnostic platform breadth to anchor hospital contracts across multiple continents. Pfizer Inc sustains R&D intensity in vascular-targeted therapeutics through dedicated cardiovascular units. Novartis AG differentiates via biologics pipelines addressing endothelial inflammation pathways.
Endothelial dysfunction denotes impaired vasodilation, increased permeability, and prothrombotic surface shifts in the single-cell lining of blood vessels, measurable through flow-mediated dilation percentages, circulating endothelial progenitor cell counts, or biomarkers such as von Willebrand factor and soluble intercellular adhesion molecule-1. Pharmaceuticals dominates current revenue pools due to entrenched statin and ACE inhibitor prescribing patterns, though Devices is expanding fastest as non-invasive endothelial function monitors displace catheter-based assessments in outpatient settings. Biologics occupies a narrower but higher-margin position, with monoclonal antibodies targeting vascular inflammation commanding premium pricing in refractory populations.
The FDA governs diagnostic device clearances and therapeutic approvals, while the EMA's MDR framework shapes conformity requirements for European market access and ISO 13485 certifications underpin quality management for device manufacturers worldwide. Stakeholders must monitor how biomarker qualification pathways evolve, as regulatory acceptance of novel endothelial integrity indicators will determine which testing platforms achieve reimbursable status in major health systems.
Market Dynamics
Cardiovascular hospital systems are consolidating endothelial assessment procurement around integrated diagnostic platforms, compressing vendor selection cycles and favoring suppliers with multi-parameter testing breadth over single-modality specialists.
Growth Catalysts
- MDR Conformity Requirements:The EU's Medical Device Regulation framework is accelerating hospital upgrades to certified non-invasive endothelial function monitors, creating replacement demand across German and French cardiovascular centers.
- Flow-Mediated Dilation Standardization:Cardiology societies are embedding FMD testing protocols into hypertension management guidelines, expanding reimbursable indications beyond research settings.
- Integrated Health Network Consolidation:Northeast and California health systems are centralizing endothelial testing contracts, creating volume concentration that rewards platform vendors with multi-site service capabilities.
Market Restraints
- Biomarker Qualification Uncertainty:The FDA's evolving guidance on novel endothelial integrity indicators creates reimbursement lag for emerging testing platforms, delaying commercial traction.
- Capital Equipment Intensity:High-acuity endothelial function monitors require substantial upfront investment, limiting penetration in independent cardiology practices and smaller community hospitals.
- Specialized Technician Dependency:Accurate FMD measurement demands trained sonographers, creating operational bottlenecks in settings without dedicated vascular imaging staff.
Strategic Opportunities
- Home-Based Monitoring Convergence:Wearable photoplethysmography sensors combined with cloud-based analytics are opening remote endothelial assessment channels beyond traditional clinic settings.
- Biologics Pipeline Expansion:Monoclonal antibodies targeting vascular inflammation pathways command premium positioning in statin-refractory patient populations.
- Biomarker Panel Integration:Multiplex assays measuring von Willebrand factor alongside soluble intercellular adhesion molecule-1 are creating differentiated testing menus for precision cardiovascular risk stratification.
Industry Challenges
- ISO 13485 Certification Timelines:Device manufacturers face extended quality management system audits, compressing product launch windows against competitive pressure.
- Legacy EHR Integration Complexity:New endothelial testing platforms must interface with entrenched hospital information systems, adding implementation cost and technical risk.
- Reimbursement Code Fragmentation:Inconsistent CPT coding across payers for novel endothelial assessment modalities creates revenue recognition uncertainty for testing providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Endothelial Dysfunction Market |
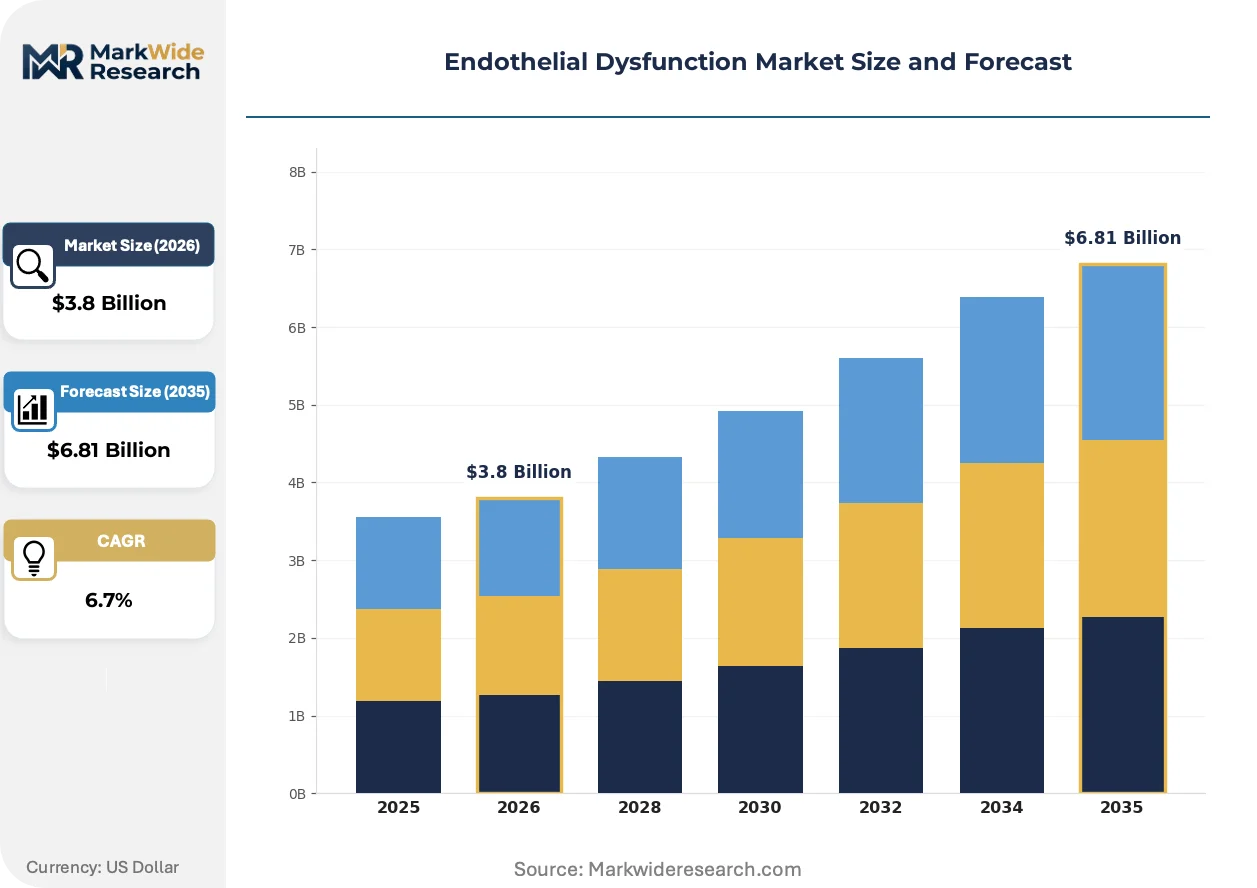
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceuticals, Biologics, Nutraceuticals, Devices Therapy Area: CVD, Diabetes, Hypertension, Renal Disease Delivery Mode: Oral, Injectable, Transdermal, Intravenous End User: Hospitals, Clinics, Homecare, Research Centers |
| Companies Covered | ZOLL Medical Corp, Sphingo Tec GmbH, Endothelix Inc, Perimed AB, SMART Medical Ltd, Everist Health Inc, Abbott Laboratories, Pfizer Inc, Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Endothelial Dysfunction Market Shifts & Advancements
Non-invasive endothelial function assessment is fragmenting across multiple technological modalities, with each approach carving distinct clinical niches based on throughput, accuracy, and point-of-care suitability.
Digital thermal monitoring is decomposing the traditional catheter-based assessment paradigm by enabling continuous endothelial function tracking without vascular access. Outpatient cardiology clinics in the United States are piloting these systems for serial monitoring of therapeutic response. The technology is decomposing revenue concentration among invasive diagnostic specialists and redistributing value toward ambulatory monitoring platforms.
REACH regulatory frameworks in Europe are tightening substance safety requirements for contrast agents used in legacy endothelial imaging, accelerating hospital migration to dye-free alternatives. Manufacturers are reformulating product portfolios to eliminate high-risk chemical components ahead of compliance deadlines. German cardiovascular centers are leading this transition, driven by liability-conscious procurement committees.
Hospital supply committees are unbundling endothelial testing from bundled cardiovascular service contracts, creating standalone procurement categories with discrete budget lines. This pattern disrupts traditional diagnostic vendor relationships that relied on cross-subsidy across modality portfolios. The Northeast United States exhibits the most pronounced unbundling, with integrated delivery networks negotiating direct endothelial monitor contracts separate from broader imaging equipment agreements.
Endothelial Dysfunction Market Segmentation
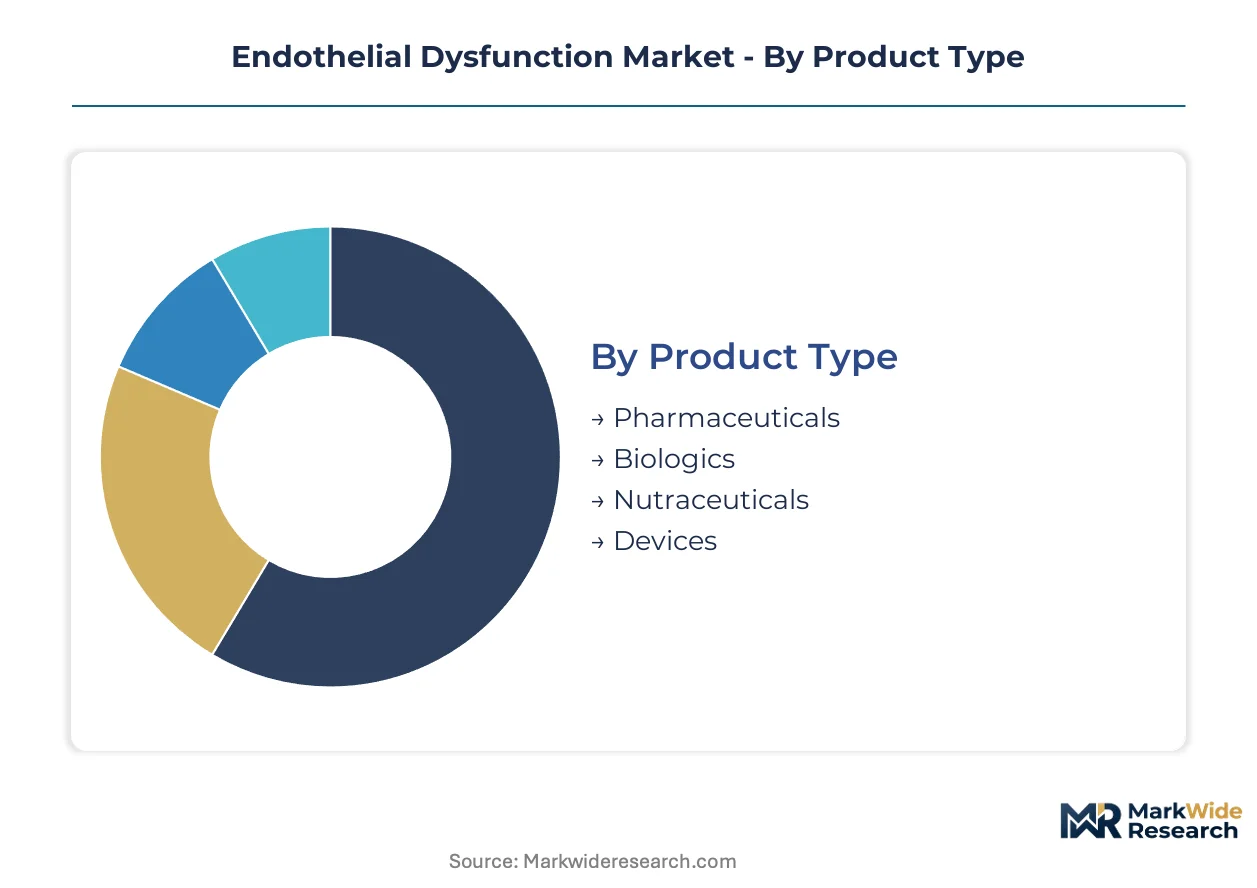
Segmentation in endothelial dysfunction markets reveals distinct procurement and prescribing pathways. Hospital cardiovascular departments concentrate demand around integrated diagnostic platforms, while outpatient settings fragment across specialty clinics and remote monitoring channels.
Product Type:
Pharmaceuticals flow through established hospital formularies and retail pharmacy networks. Biologics and devices concentrate in tertiary cardiovascular centers with specialized infusion and imaging capabilities. Nutraceuticals distribute through direct-to-consumer and preventive cardiology channels.
- Pharmaceuticals:Small-molecule therapeutics including statins, ACE inhibitors, and ARBs constitute the foundational prescribing pattern in cardiovascular hospital systems. Demand concentrates in integrated health networks across the United States, particularly where bundled payment models incentivize standardized therapeutic protocols.
- Biologics:Monoclonal antibodies targeting vascular inflammation pathways require cold-chain logistics and specialty pharmacy administration. Tertiary cardiovascular centers in Germany and France anchor European demand, driven by EMA-approved indications for statin-refractory populations.
- Nutraceuticals:L-arginine, CoQ10, and polyphenol formulations circulate through preventive cardiology practices and direct-to-consumer channels.
- Devices:Non-invasive endothelial function monitors displace catheter-based assessments in outpatient settings.
By volume, Pharmaceuticals leads. By growth pace, Devices is expanding most quickly.
Therapy Area:
Cost tier stratification shapes therapeutic investment across indication areas. CVD commands premium pricing and dedicated cardiovascular unit resources. Hypertension and diabetes operate under tighter reimbursement constraints. Renal disease represents emerging indication expansion.
- CVD:Coronary artery disease and heart failure drive the highest per-patient therapeutic expenditure, with endothelial dysfunction assessment embedded in pre-interventional workups. Northeast United States hospital systems prioritize CVD-linked testing protocols within value-based care contracts.
- Diabetes:Microvascular complications create sustained demand for endothelial monitoring in endocrinology practices. German diabetes centers integrate FMD testing into complication screening pathways under national disease management program reimbursement.
- Hypertension:Resistant hypertension populations generate specialized referral demand for endothelial phenotyping.
- Renal Disease:Chronic kidney disease-associated cardiovascular risk drives emerging testing adoption in nephrology clinics.
By patient volume, Hypertension leads. By revenue intensity per case, CVD commands the steepest premium.
Delivery Mode:
Application setting determines modality selection. Acute care environments favor intravenous and injectable routes. Ambulatory and home settings shift toward oral and transdermal alternatives. Patient compliance requirements increasingly influence formulation decisions.
- Oral:Small-molecule cardiovascular therapeutics and nutraceutical supplements dominate outpatient prescribing. California integrated health networks emphasize oral regimen adherence through pharmacy benefit management integration.
- Injectable:Biologic monoclonal antibodies and GLP-1 receptor agonists require specialty pharmacy infrastructure and patient education programs. French hospital outpatient departments anchor European injectable volume.
- Transdermal:Nitrate patches and emerging topical vasodilators serve home-based chronic management.
- Intravenous:Acute endothelial-targeted therapies concentrate in coronary care units and cardiac catheterization laboratories.
By prescription volume, Oral formulations lead. By revenue expansion trajectory, Injectable biologics is climbing the fastest.
End User:
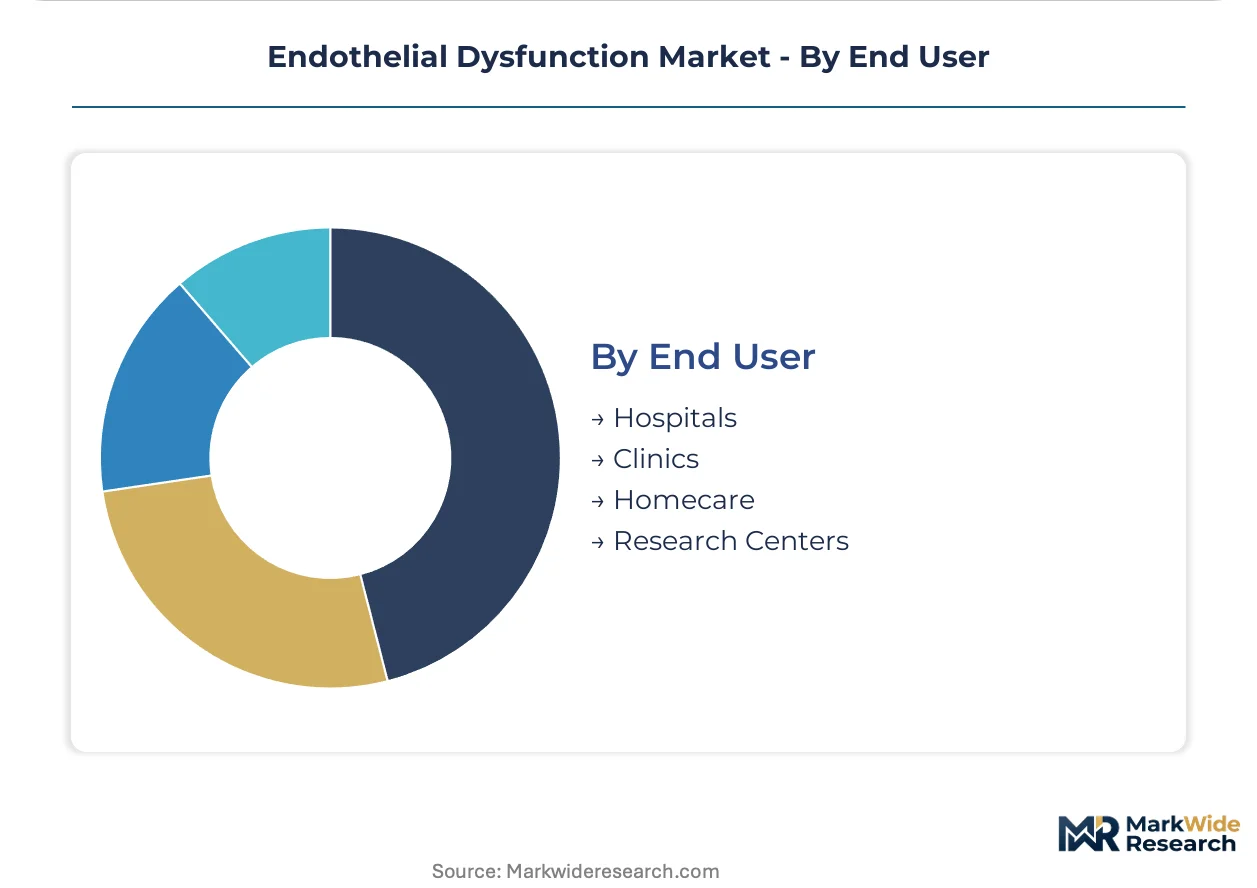
Customer type concentration is reshaping vendor go-to-market strategies. Hospital procurement committees consolidate purchasing power around multi-parameter platforms. Homecare and research settings fragment across specialized single-purpose devices.
- Hospitals:Cardiovascular hospital systems centralize endothelial assessment procurement around integrated diagnostic platforms with EHR connectivity. Abbott Laboratories anchors multi-continent hospital contracts through diagnostic platform breadth.
- Clinics:Independent cardiology practices and specialty vascular clinics favor lower-capital point-of-care devices. California ambulatory surgery centers pilot digital thermal monitoring for serial therapeutic response tracking.
- Homecare:Wearable photoplethysmography sensors combined with cloud analytics are opening remote assessment channels.
- Research Centers:Academic medical centers drive biomarker qualification studies and novel testing platform validation.
By capital expenditure concentration, Hospitals dominate. By growth velocity, Homecare channels are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam anchors European distribution for endothelial function diagnostics, while the Los Angeles-Long Beach port complex underwrites Pacific Rim supply chains. These infrastructure assets determine regional procurement velocity and regulatory compliance sequencing.
United States
Northeast integrated health networks and California cardiology clusters drive hospital-based endothelial testing procurement. FDA biomarker qualification pathways determine which novel diagnostics achieve reimbursable status. The Boston-Cambridge corridor concentrates digital thermal monitoring pilot programs within academic medical centers.
Germany
REACH regulatory frameworks accelerate hospital migration to dye-free endothelial imaging alternatives ahead of compliance deadlines. Bavarian cardiovascular centers lead procurement of MDR-certified non-invasive monitors. Munich-based hospital supply committees negotiate standalone endothelial testing contracts separate from bundled imaging agreements.
France
Tertiary cardiovascular centers in Paris and Lyon anchor European demand for biologic monoclonal antibodies targeting vascular inflammation. ANSM oversight shapes contrast agent safety requirements for legacy imaging protocols. The Île-de-France region concentrates EMA-aligned clinical trial activity for novel endothelial integrity indicators.
Japan
PMDA regulatory timelines influence device manufacturer entry strategies for non-invasive endothelial monitors. The Kanto region's cardiovascular hospital systems prioritize ISO 13485-certified platforms with embedded Japanese language interfaces. Tokyo-based procurement committees emphasize EHR integration capabilities in vendor selection.
United Kingdom
NHS England value-based care contracts embed endothelial dysfunction assessment within cardiovascular prevention pathways. MHRA post-Brexit regulatory divergence creates compliance complexity for multi-territory device launches. The Greater Manchester health system pilots remote monitoring integration for wearable photoplethysmography sensors.
Endothelial Dysfunction Market Competitive Landscape
Concentration sits with diversified diagnostic platform vendors and specialized cardiovascular device manufacturers. Hospital procurement committees compress vendor selection cycles around multi-parameter testing breadth. Three archetypes dominate: integrated diagnostic conglomerates with cross-continental service networks, mid-cap device specialists with point-of-care focus, and biologics developers with inflammation-targeting pipelines. Competitive moves center on EHR integration partnerships and MDR certification acceleration.
Among diversified diagnostic conglomerates, Abbott Laboratories anchors multi-continent hospital contracts through platform breadth. Pfizer Inc occupies a position within vascular-targeted therapeutic development. Novartis AG exemplifies the biologics archetype through inflammation pathway specialization. These three entities represent distinct competitive vectors without overlapping core positioning.
| Leading Market Players |
|---|
| ZOLL Medical Corp |
| Sphingo Tec GmbH |
| Endothelix Inc |
| Perimed AB |
| SMART Medical Ltd |
| Everist Health Inc |
| Abbott Laboratories |
| Pfizer Inc |
| Novartis AG |
| Others |
Supply & Pricing Matrix
Dye-free endothelial imaging alternatives replacing contrast-agent-dependent legacy systems are redistributing manufacturing value from chemical suppliers in Germany toward sensor fabricators in Japan and Taiwan, compressing margin pools for incumbent imaging consumables while elevating capital-equipment pricing power for MDR-certified monitor producers.
Pricing Analysis
Volume-discount tiering structures stratify across hospital system scale, with integrated delivery networks in the United States commanding 15-25 point spreads over independent cardiology practices. Three-tier pricing separates MDR-certified premium platforms from standard ISO 13485-compliant systems and economy-grade research-use monitors. Pricing pressure stems from procurement committee unbundling of endothelial testing from bundled cardiovascular contracts. Independent practices exhibit highest price sensitivity; tertiary cardiovascular centers with dedicated vascular imaging units demonstrate lowest.
Supply Chain Analysis
Just-in-time inventory strategies dominate device assembly for non-invasive monitors, though strategic stockpiling of photoplethysmography sensors persists among Japanese manufacturers facing PMDA certification timelines. Component sourcing draws from Taiwan for semiconductor substrates, Germany for precision optical assemblies, and the United States for EHR-embedded software modules. Single-source vulnerability concentrates in specialized ultrasound transducer supply. Distribution runs through hospital procurement committees with direct vendor contracting authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle recovery following MDR-induced equipment replacement waves, with hospital capital expenditure normalization in Germany and France providing cyclical lift through certified non-invasive monitor deployment.
For Market Incumbents: Compound platform breadth advantages through EHR integration partnerships with Epic and Cerner installations across Northeast United States health systems. Deepen backward integration into photoplethysmography sensor production to offset transducer supply vulnerability. Accelerate MDR certification timelines for next-generation thermal monitoring platforms before REACH compliance deadlines tighten.
For New Entrants and Emerging Players: Differentiate on homecare channel enablement through wearable-software bundles targeting California ambulatory surgery centers and Greater Manchester NHS pilot programs. Penetrable white space sits in remote monitoring integration for resistant hypertension populations. Pursue direct-to-clinic sales models bypassing consolidated hospital procurement committees.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platform vendors with multi-parameter testing breadth over single-modality specialists. Long-term viability hinges on reimbursement code capture for novel endothelial integrity indicators. Target acquisition archetypes include point-of-care device specialists with FDA 510(k) clearances. Watch FDA biomarker qualification pathway acceleration as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR Certification Acceleration | EU hospital procurement committees now require MDR conformity for endothelial monitor tenders, excluding legacy CE-marked devices. |
| EHR Integration Partnership | Epic and Cerner embedded connectivity reduces implementation friction for cardiovascular hospital systems evaluating platform switches. |
| Homecare Channel Development | Wearable photoplethysmography sensors with cloud analytics open reimbursement pathways beyond traditional clinic settings. |
| Biomarker Panel Expansion | Multiplex assays measuring von Willebrand factor alongside sICAM-1 create differentiated testing menus for precision risk stratification. |
| Backward Integration into Sensors | In-house production of specialized transducers mitigates single-source supply risk from German and Japanese component vendors. |
Research Methodology
Operator-level perspectives from hospital procurement managers, cardiovascular department heads, biomedical engineers, and GPO contracts specialists anchored the qualitative base. Secondary validation drew from FDA 510(k) filings, EMA MDR certification databases, CMS Medicare reimbursement schedules, and hospital equipment procurement records. Bottom-up demand modeling triangulated against top-down epidemiological projections for cardiovascular disease prevalence.
Sensitivity analysis tested forecast outputs against variable reimbursement code adoption timelines and MDR certification completion rates across the projection horizon. Segmentation dimensions included product type, therapy area, delivery mode, and end-user setting with regional regulatory cluster overlays. CAGRs derived from equipment replacement cycle analysis and therapeutic protocol penetration curves. Forecast inputs incorporated hospital capital expenditure survey data and cardiology society guideline revision schedules.
The analysis sits within stated boundaries; outcomes outside sustained FDA biomarker qualification progress or accelerated REACH compliance enforcement would require recalibration. Forecasts reflect documented assumptions regarding hospital procurement centralization and homecare channel reimbursement expansion. Revision becomes warranted when MDR certification backlogs exceed 18-month processing thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Brugada Syndrome Treatment Market
Cardiovascular
Eisenmenger Syndrome Treatment Market
Cardiovascular
Ischemia Reperfusion Injury Therapeutics Market
Cardiovascular
Asia-Pacific Acute Coronary Syndrome Market
Cardiovascular
Europe Acute Coronary Syndrome Market
Cardiovascular
Atherosclerosis Therapeutics Market
Cardiovascular
Myocardial Infarction Therapeutics Market
Cardiovascular
United States Cardiometabolic Fixed-Dose Combinations Market
Cardiovascular
Genetic Cardiomyopathies Market
Cardiovascular
Atherosclerosis Market
Cardiovascular
Treatment-Resistant Hypertension Management Market
Cardiovascular
Prinzmetal Angina Therapeutics Market
Cardiovascular
Fractional Flow Reserve Market
Cardiovascular
High-Sensitivity Cardiac Biomarker Market
Cardiovascular
Portal Hypertension Management Market
Cardiovascular
Heterozygous Familial Hypercholesterolemia (HEFH) Management Market