
 Myanmar Battery Market | 2026-2036
Myanmar Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Myanmar Battery Market Outlook
Modular rack configurations for telecom backup power is pivoting buyer choice away from monolithic lead-acid blocks toward scalable lithium-ion strings. Toyo Battery Myanmar Co. Ltd leverages its Yangon assembly footprint to compete on delivery speed for industrial accounts. Panasonic Corporation anchors premium positioning through cylindrical cell technology leadership in consumer electronics channels. First National Battery (Myanmar) Ltd dominates the automotive starter battery aftermarket through dense distributor relationships across Mandalay and Naypyitaw.
A battery converts electrochemical energy into direct-current electricity through redox reactions between anode and cathode materials, with lithium-ion variants achieving energy densities of 150-250 Wh/kg through layered oxide cathodes and graphite intercalation anodes. Lead-acid chemistry retains cost advantage for heavy-cycling industrial applications where weight tolerance permits, while lithium-ion segments capture margin pools in electric vehicle and renewable energy storage deployments. The energy storage application commands attention from project developers pairing solar arrays with four-hour discharge systems in off-grid townships. Portable devices remains a volume anchor for alkaline and small-format lithium cells distributed through consumer retail networks.
Myanmar's Department of Electric Power and the Ministry of Industry shape market access through import licensing requirements and local content rules for electrification projects. The country's national standards body enforces safety testing protocols that favor suppliers with established certification pathways, filtering informal traders from utility-scale procurement. Stakeholders must monitor how proposed amendments to foreign investment rules affect joint-venture requirements for battery manufacturing facilities.
Market Dynamics
Myanmar's battery market pivots on the Department of Electric Power's accelerated off-grid electrification mandates, which channel procurement toward domestic assembly partnerships while grid reliability deteriorates across rural Sagaing and Chin states.
Growth Catalysts
- Telecom Infrastructure Mandates:Tower operators in Sagaing and Chin states now procure lithium-ion backup units as grid instability forces energy autonomy requirements.
- Industrial Corridor Density:Manufacturing clusters and port logistics in Yangon generate captive consumption for both lead-acid and advanced chemistry storage systems.
- Local Content Rules:The Ministry of Industry's joint-venture requirements for battery manufacturing facilities incentivize foreign assemblers to establish Yangon-based production footprints.
Market Restraints
- Raw Material Import Dependency:Lithium carbonate and cobalt sulfate enter through Thai and Chinese transit routes, exposing margins to regional logistics bottlenecks.
- Certification Pathway Concentration:Myanmar's national standards body enforces safety testing protocols that filter informal traders from utility-scale procurement.
- Lead-Acid Cost Floor:Heavy-cycling industrial applications retain tolerance for weight penalties, compressing lithium-ion penetration in price-sensitive forklift and stationary backup segments.
Strategic Opportunities
- Renewable Pairing Deployments:Project developers are pairing solar arrays with four-hour discharge systems in off-grid townships across Magway and Ayeyarwady regions.
- Consumer Electronics Channel Expansion:Alkaline and small-format lithium cells distributed through Yangon retail networks serve underpenetrated secondary cities.
- Automotive Aftermarket Consolidation:Dense distributor relationships across Mandalay and Naypyitaw create acquisition targets for organized battery service networks.
Industry Challenges
- Electrochemical Engineering Talent Scarcity:Battery assembly operations in Yangon Industrial Zone compete for technicians trained in lithium-ion formation and cell balancing protocols.
- Foreign Investment Rule Uncertainty:Proposed amendments to joint-venture requirements delay facility commissioning timelines for international manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Myanmar Battery Market |
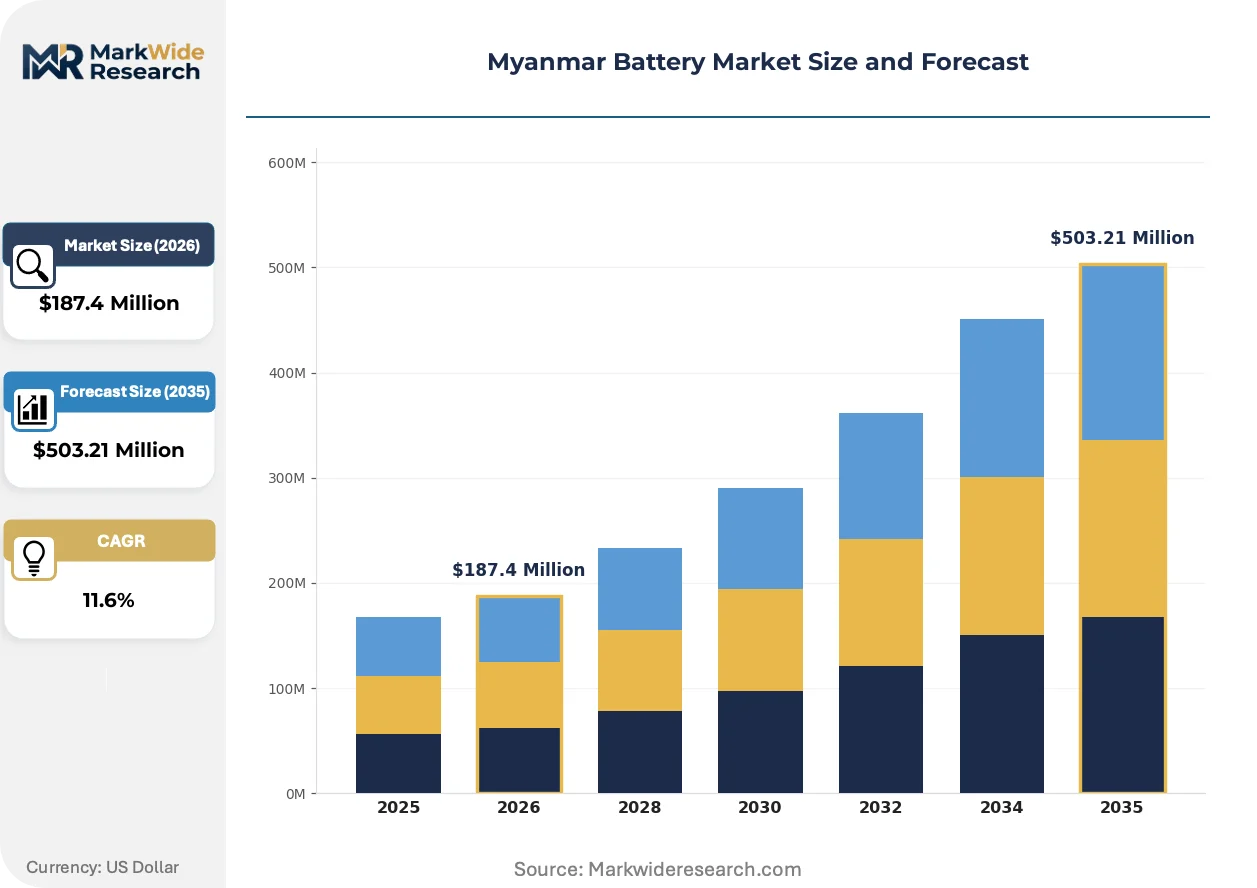
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead-Acid, Lithium-Ion, Nickel-Cadmium, Alkaline End User: Consumer Electronics, Automotive, Industrial, Renewable Energy Application: Energy Storage, Electric Vehicles, Portable Devices, Backup Power Capacity: Less than 5Ah, 5Ah to 50Ah, 50Ah to 200Ah, More than 200Ah |
| Companies Covered | Toyo Battery Myanmar Co. Ltd, GS Battery (M) Sdn. Bhd., Panasonic Corporation, Exide Technologies, Ritar Power Myanmar, Schneider Electric SE, Yuasa Battery (Thailand) Co., Ltd., First National Battery (Myanmar) Ltd., Siam GS Battery Myanmar Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Myanmar Battery Market Strategic Shifts
Modular rack configurations are actively reshaping procurement patterns across Myanmar's telecom and industrial segments, compressing delivery cycles and enabling scalable capacity expansion without monolithic infrastructure commitments.
Lithium-ion string architectures with rack-mounted battery management systems are decentralizing power backup deployment across rural telecom towers. Tower operators in Chin State now specify 48V modular strings that technicians can swap without crane equipment. This topology is decentralizing maintenance access and reducing site visit costs for operators managing dispersed assets across mountainous terrain.
The Department of Electric Power's local content rules are restructuring supplier qualification pathways for electrification tenders. Foreign manufacturers must demonstrate Yangon-based assembly capacity to bid on township-level solar-plus-storage projects. Industrial accounts in the manufacturing corridor are responding by qualifying dual-source suppliers with certified domestic footprints.
Industrial buyers in Yangon's port logistics zone now specify performance-based service agreements rather than unit purchase contracts. Battery suppliers retain ownership of installed assets and charge per available kilowatt-hour. This model is concentrating supplier relationships around operators with predictive maintenance capabilities and spare inventory positioned within the industrial corridor.
Myanmar Battery Market Segmentation
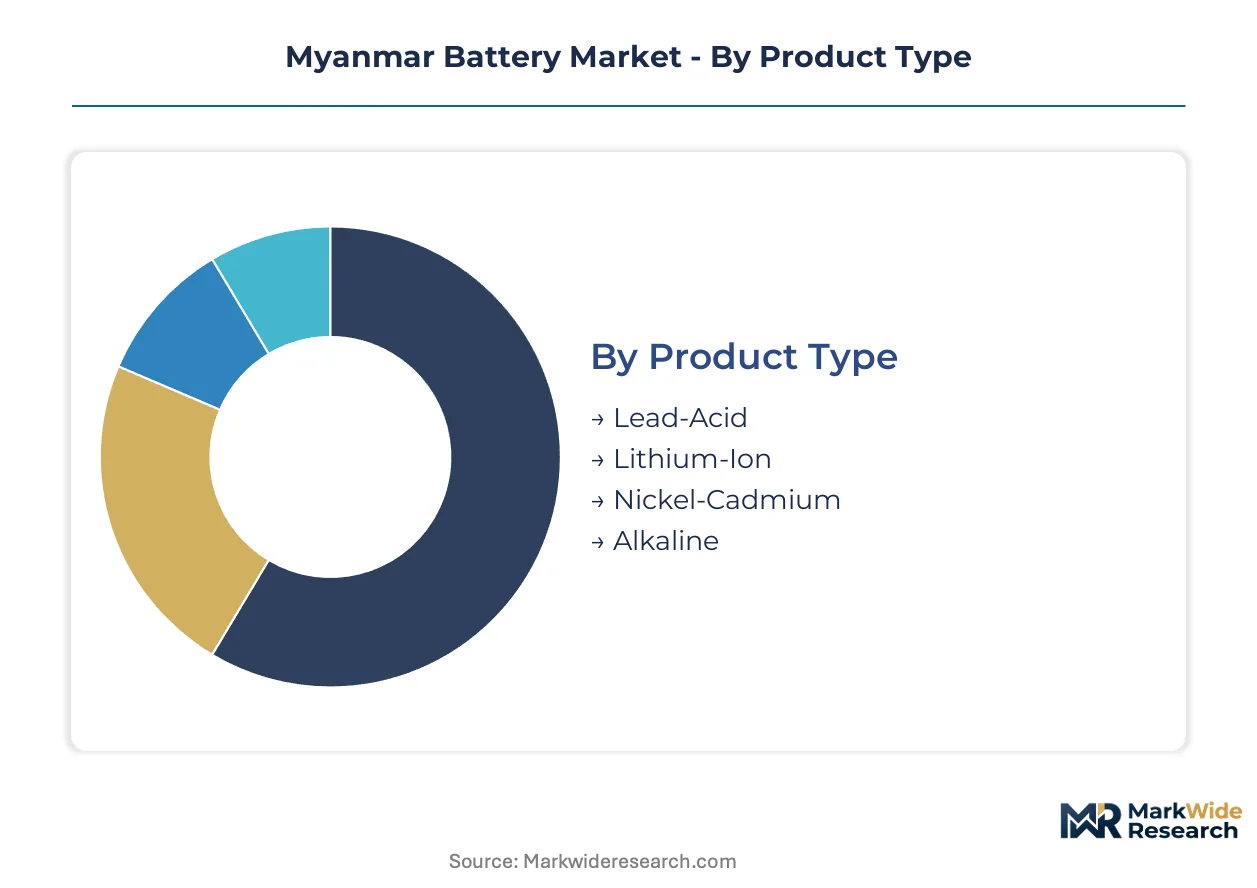
Battery procurement in Myanmar fragments across electrochemical chemistries, end-use verticals, and capacity tiers that reflect divergent performance requirements and cost tolerances. Suppliers configure product portfolios around grid reliability gaps in rural states, industrial density in Yangon, and electrification mandates from the Department of Electric Power.
Product Type:
Customization intensity spans from commodity lead-acid blocks to precision-engineered lithium-ion strings with integrated battery management systems.
- Lead-Acid:Flooded and valve-regulated designs dominate forklift fleets and stationary backup installations across Yangon's manufacturing corridor. The chemistry retains cost advantage where weight tolerance permits, though lithium-ion encroaches in telecom applications requiring rapid cycling.
- Lithium-Ion:Layered oxide cathodes paired with graphite intercalation anodes achieve 150-250 Wh/kg densities essential for solar-plus-storage deployments in off-grid Magway and Ayeyarwady townships. The Department of Electric Power's local content rules channel procurement toward Yangon-assembled strings.
- Nickel-Cadmium:Sintered plate construction tolerates extreme temperature swings in aviation and rail signaling applications.
- Alkaline:Zinc-manganese dioxide chemistry anchors disposable cell demand through Yangon retail networks serving underpenetrated secondary cities.
Leading the category by volume: Lead-Acid. Growing fastest: Lithium-Ion.
End User:
Margin profiles diverge sharply between price-sensitive automotive aftermarket accounts and performance-driven renewable energy developers.
- Automotive:Starter battery replacement cycles concentrate in Mandalay and Naypyitaw distributor networks, with organized service networks consolidating fragmented aftermarket channels.
- Industrial:Port logistics operators in Yangon now specify performance-based service agreements charging per available kilowatt-hour rather than unit purchases.
- Consumer Electronics:Cylindrical and prismatic cells power smartphones and laptops distributed through retail networks with premium positioning in urban centers.
- Renewable Energy:Project developers pair four-hour discharge systems with solar arrays across rural electrification zones, qualifying suppliers with certified domestic assembly footprints.
Highest margin concentration: Renewable Energy. Steepest volume trajectory: Industrial.
Application:
Deployment complexity escalates from plug-and-play portable devices to engineered energy storage systems requiring site-specific integration.
- Energy Storage:Containerized lithium-ion systems with rack-mounted battery management systems decentralize power backup across Chin State telecom towers. Technicians swap 48V modular strings without crane equipment, reducing site visit costs for dispersed mountainous assets.
- Backup Power:Tower operators in Sagaing and Chin states procure lithium-ion units as grid instability forces energy autonomy requirements, displacing monolithic lead-acid blocks with scalable string architectures.
- Electric Vehicles:Two-wheeler and light commercial vehicle segments drive cell demand through Yangon-based assembly partnerships.
- Portable Devices:Alkaline and small-format lithium cells serve volume demand through consumer retail networks.
Fastest capacity expansion: Energy Storage. Most mature procurement standards: Backup Power.
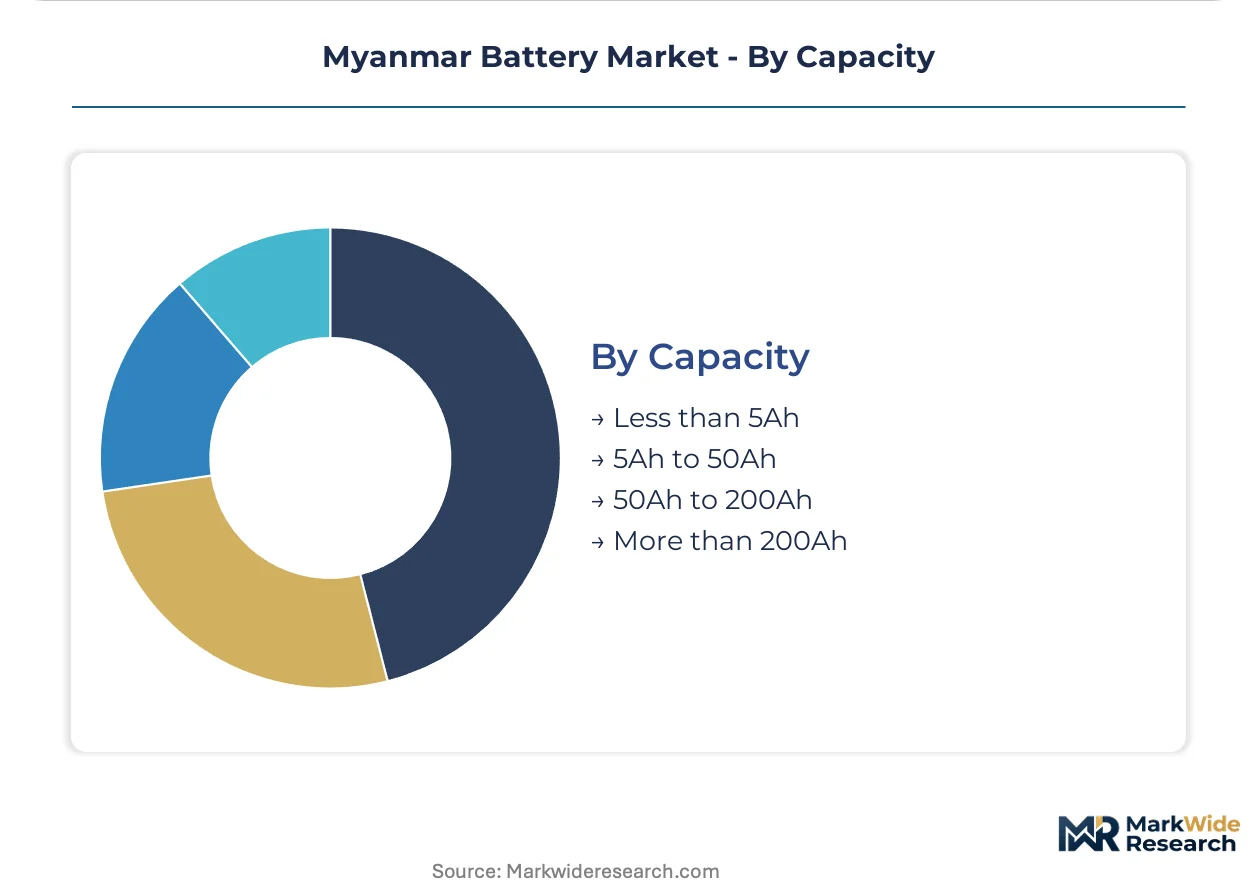
Capacity:
Unit economics invert across the ampere-hour spectrum, with small cells optimized for manufacturing scale and large systems engineered for cycle life.
- More than 200Ah:Industrial forklift and stationary storage applications in Yangon's port logistics zone specify these heavy-cycling units, where weight penalties are operationally tolerable.
- 50Ah to 200Ah:Telecom backup and light electric vehicle segments concentrate demand here, with modular rack configurations enabling scalable capacity expansion.
- 5Ah to 50Ah:Power tools and residential solar backup systems populate this mid-range tier.
- Less than 5Ah:Consumer electronics and medical devices drive volume through precision manufacturing of cylindrical and prismatic formats.
Fastest-growing demand tier: 50Ah to 200Ah. Highest shipment volumes: Less than 5Ah.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yangon Industrial Zone functions as Myanmar's battery manufacturing nucleus, with special economic zone tax incentives drawing foreign assemblers into joint-venture partnerships with domestic distributors.
Yangon Region
Port logistics operators and manufacturing clusters generate captive consumption for lead-acid and lithium-ion storage systems. The Department of Electric Power channels township-level solar-plus-storage procurement toward Yangon-based assembly partners. Industrial accounts in the port zone now specify performance-based service agreements charging per available kilowatt-hour.
Mandalay Region
Automotive starter battery replacement cycles concentrate in dense distributor networks across the city. The Ministry of Industry's local content rules incentivize battery service networks to consolidate fragmented aftermarket channels. Organized distributors compete for fleet maintenance contracts from commercial vehicle operators.
Sagaing State
Telecom tower operators procure lithium-ion backup units as grid reliability deteriorates across rural terrain. The Department of Electric Power's off-grid electrification mandates accelerate solar-plus-storage deployment in remote townships. Modular 48V rack configurations enable technician-level maintenance without crane equipment.
Chin State
Mountainous geography forces energy autonomy requirements upon dispersed telecom infrastructure. Tower operators specify scalable lithium-ion strings that reduce site visit costs for asset managers. The national standards body's safety testing protocols filter informal traders from utility-scale procurement.
Naypyitaw Union Territory
Government fleet electrification and administrative vehicle maintenance anchor lead-acid demand. Central procurement offices enforce certification pathways that favor suppliers with established domestic footprints. Battery service networks position inventory to capture institutional maintenance contracts.
Myanmar Battery Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across Myanmar's battery procurement channels. The market structure tilts toward joint-venture formations, with foreign cell manufacturers pairing with domestic distributors to satisfy local content rules. Three archetypes dominate: regional Asian battery specialists with Myanmar assembly footprints, global electronics conglomerates leveraging cylindrical cell technology, and automotive aftermarket consolidators with dense provincial distribution. Competitive moves center on Yangon-based capacity expansion and performance-based service contract offerings.
Among regional specialists, Toyo Battery Myanmar Co. Ltd and Yuasa Battery (Thailand) Co., Ltd. exemplify the joint-venture archetype, positioning assembly capacity within Yangon Industrial Zone to capture telecom and industrial procurement. Panasonic Corporation anchors premium positioning through technology leadership in consumer electronics channels. First National Battery (Myanmar) Ltd. occupies the automotive aftermarket consolidation tier, leveraging distributor relationships across Mandalay and Naypyitaw.
| Leading Market Players |
|---|
| Toyo Battery Myanmar Co. Ltd |
| GS Battery (M) Sdn. Bhd. |
| Panasonic Corporation |
| Exide Technologies |
| Ritar Power Myanmar |
| Schneider Electric SE |
| Yuasa Battery (Thailand) Co., Ltd. |
| First National Battery (Myanmar) Ltd. |
| Siam GS Battery Myanmar Limited |
| Others |
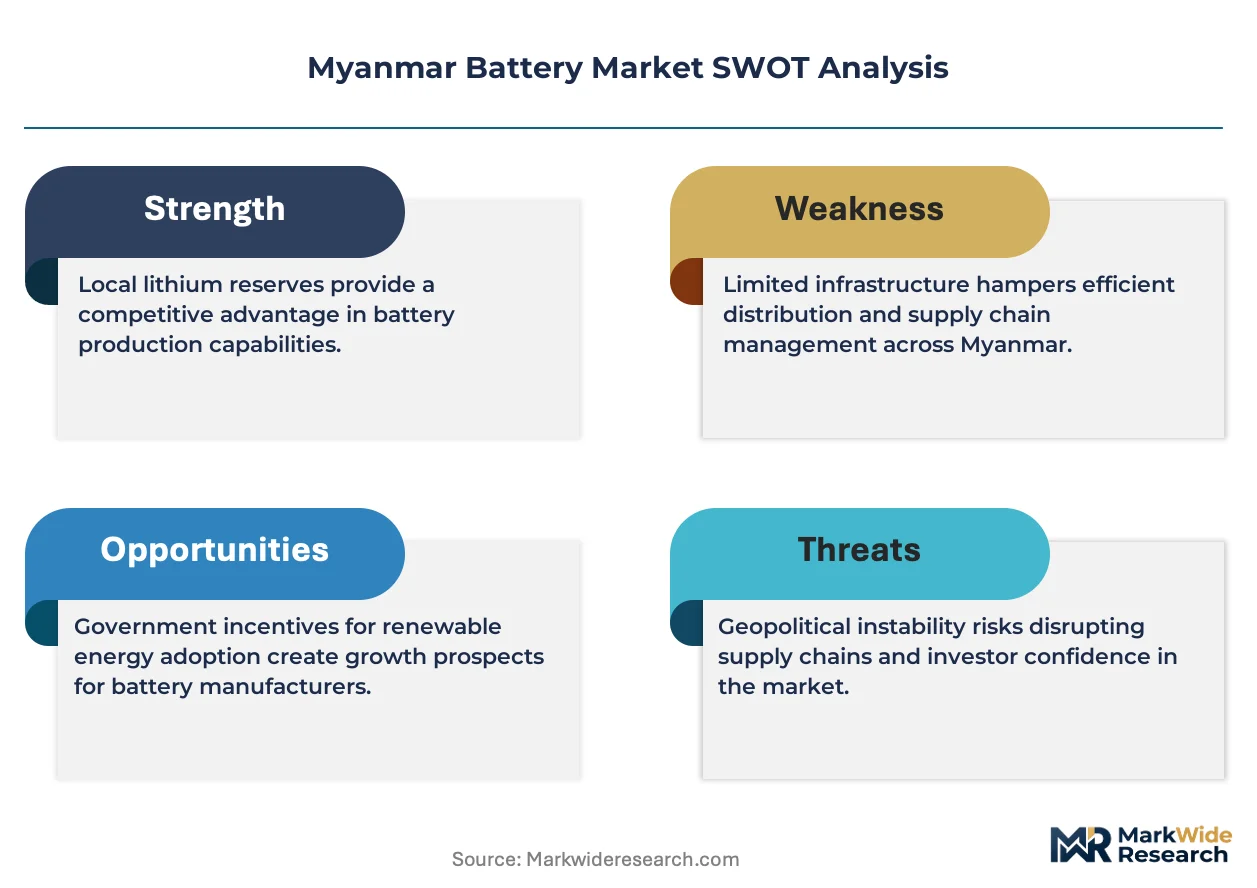
Value Chain & Pricing Dynamics
Modular lithium-ion string architectures are compressing manufacturing cycle times while concentrating procurement leverage among Yangon-based assemblers with certified domestic footprints. The Department of Electric Power's local content rules simultaneously reshape cost structures and supplier qualification pathways, rewarding joint-venture operators with preferential tender access.
Pricing Analysis
Lead-time premiums dominate pricing differentiation in Myanmar's battery procurement, with industrial accounts paying substantial markups for sub-48-hour delivery from Yangon Industrial Zone inventory against spot-market discounts for Chinese-imported cells with 3-4 week transit exposure. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales bundling, with Panasonic-anchored cylindrical cells commanding brand premiums in consumer channels. Cost compression in lead-acid forklift segments is intensifying because Thai and Chinese transit bottlenecks squeeze importer margins. Automotive aftermarket distributors in Mandalay exhibit highest price sensitivity, while renewable energy developers prioritize performance guarantees over unit economics.
Supply Chain Analysis
Reverse-logistics networks for telecom backup batteries remain nascent, with tower operators discarding failed lithium-ion modules rather than refurbishing due to absent cell-level reconditioning infrastructure. Raw material supply concentrates in China, South Korea, and Japan, with lithium carbonate and cobalt sulfate drawing from Thai and Chinese transit routes. Myanmar's assembly operations rest on imported electrode materials, separator films, and electrolyte formulations. Single-source vulnerability pervades the Yangon Industrial Zone, where joint-venture partners lack alternative qualified suppliers for cylindrical cell casings. Distribution runs through Ministry of Industry-licensed importers into provincial distributor networks anchored in Mandalay and Naypyitaw.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Myanmar's battery market sits in a technology-transition phase, with modular lithium-ion strings displacing monolithic lead-acid blocks across telecom and industrial backup applications.
For Market Incumbents: Lock in Yangon-based assembly capacity to defend against emerging pure-play lithium-ion specialists from Thailand and Vietnam. Prioritize certification investment with Myanmar's national standards body to filter informal traders from utility-scale procurement. Deepen backward integration into electrode coating operations to reduce exposure to Chinese material transit bottlenecks. For New Entrants and Emerging Players: The Department of Electric Power's off-grid electrification mandates in Magway and Ayeyarwady regions open a window for solar-plus-storage system integrators with certified domestic footprints. Target township-level electrification tenders where foreign assemblers lacking Yangon joint-venture partnerships face disqualification. Lead with performance-based service agreements charging per available kilowatt-hour rather than unit sales to bypass capital-constrained buyer budgets. For Investors and Strategic Acquirers: Exit pathways concentrate in regional battery specialists seeking Myanmar manufacturing beachheads to satisfy Southeast Asian electrification demand. Five-to-ten year viability hinges on whether proposed foreign investment rule amendments relax joint-venture requirements or harden localization mandates. Monitor certification pathway concentration at Myanmar's national standards body as inflection indicator for supplier consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Yangon Assembly Footprint Establishment | Joint-venture partnerships with domestic distributors unlock Department of Electric Power tender participation. |
| Performance-Based Service Contract Launch | Industrial accounts in port logistics zone now specify per-kilowatt-hour charging over unit purchases. |
| Telecom Modular String Certification | 48V rack-mounted battery management systems qualify for Chin State tower operator procurement. |
| Automotive Aftermarket Channel Consolidation | Dense distributor relationships across Mandalay create acquisition platforms for organized service networks. |
| Renewable Energy Pairing Deployment | Four-hour discharge systems paired with solar arrays capture Magway and Ayeyarwady township electrification mandates. |
Study Parameters
Multi-period observation of lithium-ion string adoption rates, lead-acid displacement patterns, and joint-venture formation timelines anchored the trend analysis, supplemented by interviews with Department of Electric Power procurement officers, Yangon Industrial Zone plant managers, telecom tower maintenance directors, automotive distributor network heads, and renewable energy project developers. Secondary validation drew from Myanmar customs trade records, Ministry of Industry licensing disclosures, national standards body certification registries, and ASEAN battery trade association publications. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Input-output matrices mapped electrochemical chemistry demand to end-use vertical capacity requirements across the projection horizon. Segmentation dimensions spanned product type, end user, application, and capacity tier, with additional modeling of certification-grade stratification. CAGRs derived from regression analysis of historical procurement volumes against electrification mandate acceleration curves and grid reliability deterioration indices in rural states.
Caveats apply where proposed amendments to foreign investment rules, raw material transit disruptions through Thai logistics corridors, or electrochemical engineering talent scarcity could materially shift the outlook. Practitioners should monitor certification pathway rulings from Myanmar's national standards body and lithium carbonate import volume trends for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Romania Rechargeable Battery Market
Batteries
Thin Film Photovoltaic and Batteries Market
Batteries
Aluminum-Air Battery Market
Batteries
Modular Battery Pack Platforms for Skateboard EVs Market
Batteries
Lithium Starters Market
Batteries
Grid-Scale Lead-Acid Battery Market
Batteries
Lithium-Fluorinated Graphite Batteries Market
Batteries
Consumer Battery Market
Batteries
China Battery Market
Batteries
Solid-State Car Battery Market
Batteries
Printable Battery Market
Batteries
Primary Battery Market
Batteries
South Europe Battery Market
Batteries
Global Primary Cells Market
Batteries
Liquid Metal Battery Market
Batteries
South and Central America Battery Market