
 China Battery Market | 2026-2036
China Battery Market Size, Share, and Industry Trends Forecast 2026-2036
China Battery Market Analysis
China's dual carbon goals are realigning procurement priorities across the battery value chain, compelling automakers and grid operators to prioritize cells with verified low-carbon footprints. CATL leverages its integrated mining-to-pack architecture to secure cathode supply stability. BYD anchors its competitive position through in-house blade battery production for passenger and commercial vehicle lines. Gotion High-tech specializes in lithium iron phosphate formulations for utility-scale energy storage deployments.
A battery is an electrochemical device comprising an anode, cathode, electrolyte, and separator that stores and releases electrical energy through reversible redox reactions, with energy density typically measured in watt-hours per kilogram and cycle life spanning 500 to 8,000 charge-discharge iterations depending on chemistry. Its primary commercial purpose is to decouple electricity generation from consumption, enabling mobility, portable electronics, and grid stabilization. Lithium-ion chemistry dominates installed capacity due to its superior energy density and declining cost curve, while solid-state technology attracts concentrated R&D investment as manufacturers pursue enhanced safety margins and higher volumetric efficiency. Energy storage applications represent the fastest-expanding demand segment as provincial grid operators deploy gigawatt-hour scale systems to absorb intermittent renewable generation.
MIIT enforces GB standards for battery safety, energy density, and recycling recovery rates, while SAMR monitors market concentration and pricing conduct among dominant cell producers. MEE implements environmental compliance audits across cathode material refining facilities, elevating capital requirements for new entrants. Stakeholders must monitor how forthcoming recycling mandates and carbon accounting rules reshape supplier qualification criteria and contract structures.
Market Dynamics
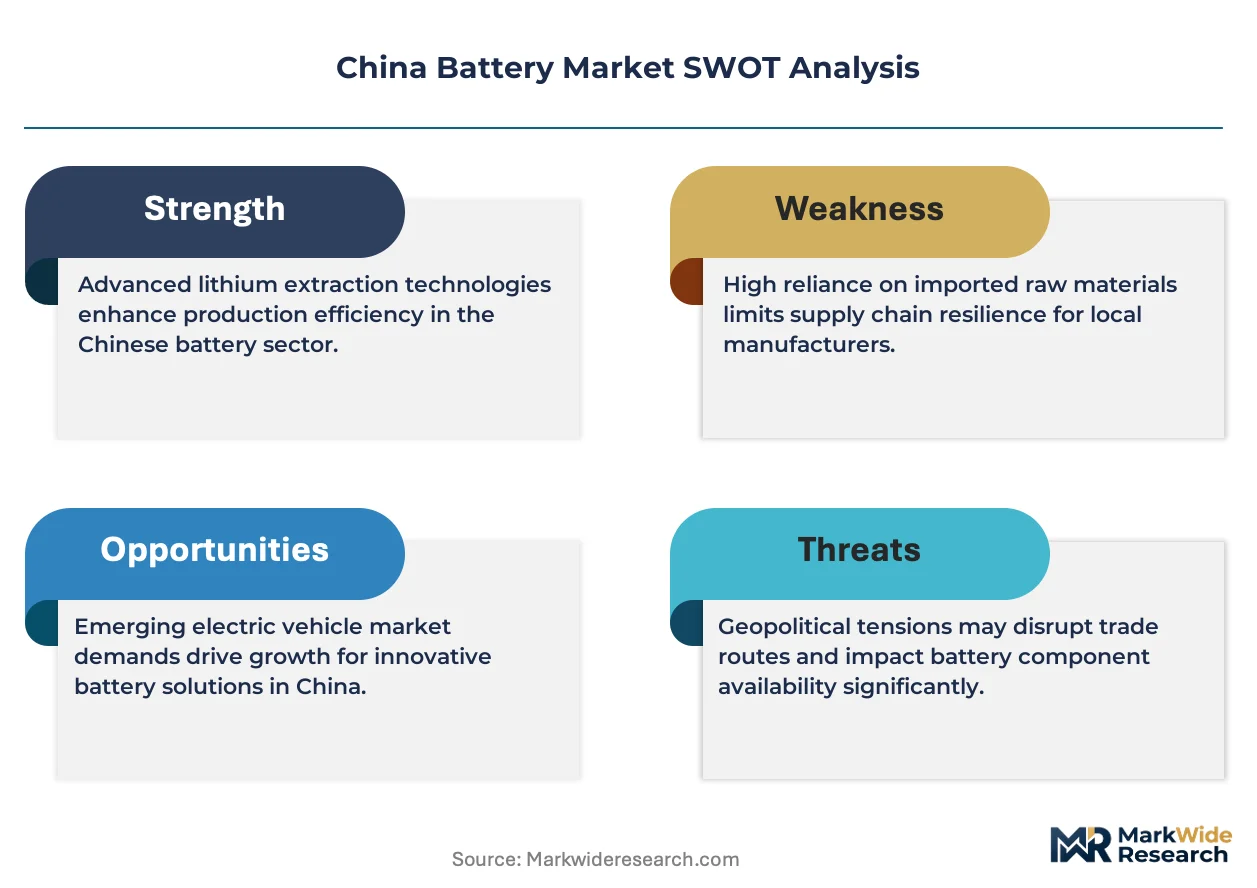
China's dual carbon goals are compressing the transition timeline from cobalt-nickel chemistries to lithium iron phosphate architectures, forcing cathode procurement contracts to reprice around carbon intensity metrics rather than pure cost-per-kilogram.
Growth Catalysts
- MIIT energy density mandates:Minimum thresholds for passenger vehicle packs are pushing cell makers toward higher-nickel cathode formulations and silicon-anode blends.
- Yangtze River Delta clustering:Shanghai-Ningbo-Changzhou corridor concentrates 60% of national cathode refining capacity, slashing logistics costs for downstream integrators.
- Grid-scale storage procurement:Provincial operators in Jiangsu and Guangdong are issuing 10-year offtake agreements for utility battery systems exceeding 100 MWh per installation.
Market Restraints
- Lithium carbonate volatility:Qinghai and Sichuan brine extraction bottlenecks create 40-60% input cost swings that cell producers cannot fully pass through.
- Graphite anode concentration:Heilongjiang and Shandong provinces control 80% of domestic spherical graphite supply, exposing mid-tier cell makers to single-source risk.
- Solid-state electrolyte immaturity:Sulfide-based ceramic conductors remain below 400 Wh/kg in pilot production, delaying commercial deployment past 2030.
Strategic Opportunities
- Western China manufacturing migration:Sichuan and Yunnan provinces offer hydropower-priced electricity below 0.25 yuan/kWh for new giga-factory sites.
- Second-life battery arbitrage:Retired EV packs from Shenzhen and Hangzhou fleets are being refurbished for 4-hour grid storage applications.
- SAMR recycling mandates:Forthcoming rules requiring 85% lithium recovery from black mass are creating licensing opportunities for hydrometallurgical specialists.
Industry Challenges
- Dry electrode coating expertise:Solvent-free cathode manufacturing requires rare combinations of polymer science and roll-to-roll engineering that command 40% wage premiums.
- GB 38031 certification timelines:New thermal runaway propagation tests add 8-14 months to pack approval cycles for commercial vehicle platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Battery Market |
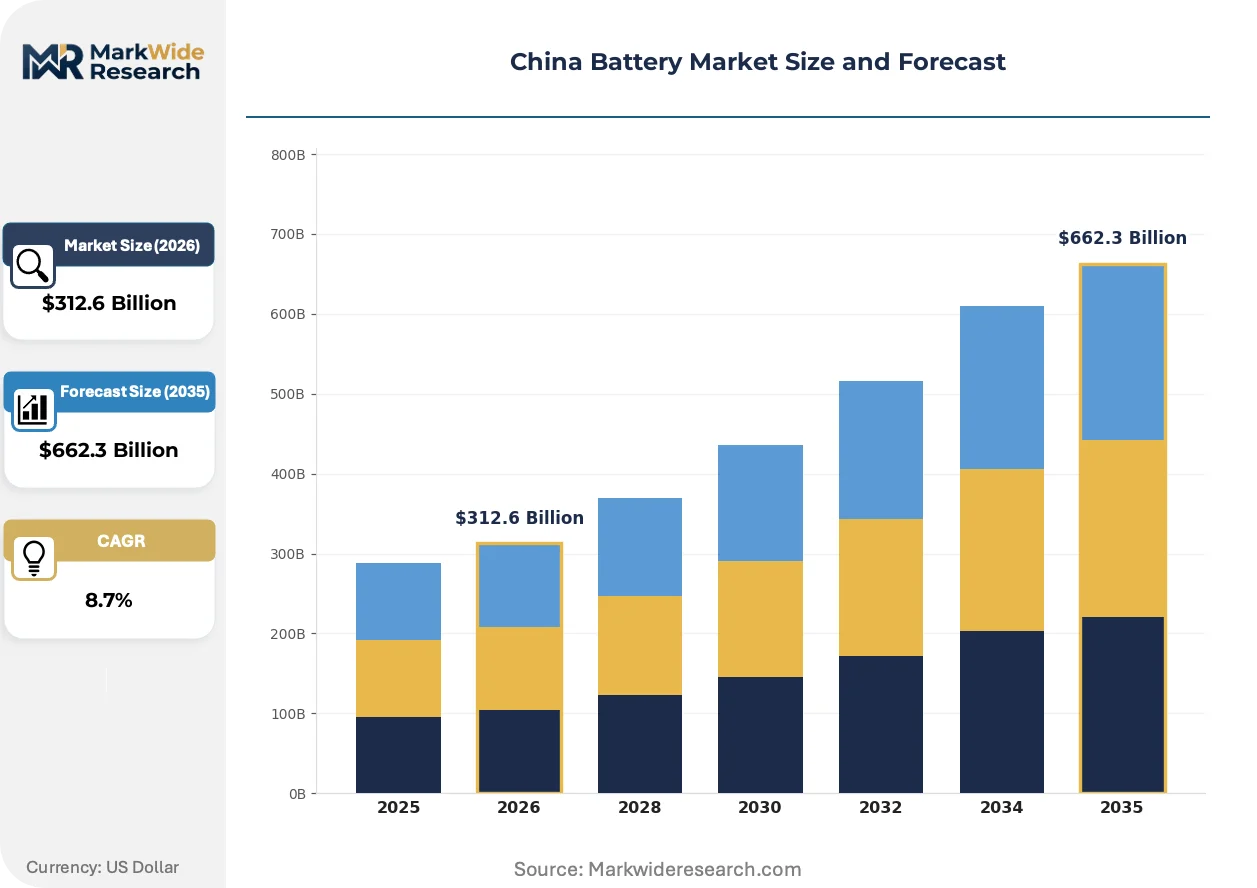
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $662.3 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Lead-acid, Nickel-cadmium, Flow Batteries Application: Electric Vehicles, Consumer Electronics, Energy Storage, Industrial Equipment End User: Automotive Sector, Electronics Manufacturers, Telecommunications, Renewable Energy Technology: Solid-state, Lithium-sulfur, Hybrid, Traditional |
| Companies Covered | Eve Energy, Svolt Energy, CATL, Zenergy, Sunwoda, BYD, CALB, Rept Battero Energy, Gotion High-tech, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Battery Market Emerging Trajectories
Cell-to-pack architectures are collapsing traditional module boundaries, compressing bill-of-materials costs while forcing thermal management systems to integrate at the cell level rather than the module level.
Sodium-ion chemistry is modularizing around Prussian blue cathode variants for sub-300 km urban vehicle segments. BYD and CATL are scaling 160 Wh/kg cells for A00-class vehicles where lithium iron phosphate cost premiums cannot be absorbed. This chemistry is compressing the addressable market for low-energy-density lithium-ion variants in price-sensitive applications.
MEE environmental compliance audits are elevating capital barriers for new cathode entrants. Refining facilities in Hunan and Jiangxi now face mandatory wastewater treatment investments exceeding 200 million yuan per site. Tier-two material suppliers are consolidating or exiting rather than absorbing these fixed costs.
Fleet operators in Beijing and Guangzhou are consolidating procurement through battery-as-a-service contracts that unbundle cell ownership from vehicle financing. State-owned logistics groups now prefer per-kilometer pricing models over upfront pack purchases. This shift is most visible in commercial electric van deployments where utilization rates exceed 300 km daily.
China Battery Market Segmentation
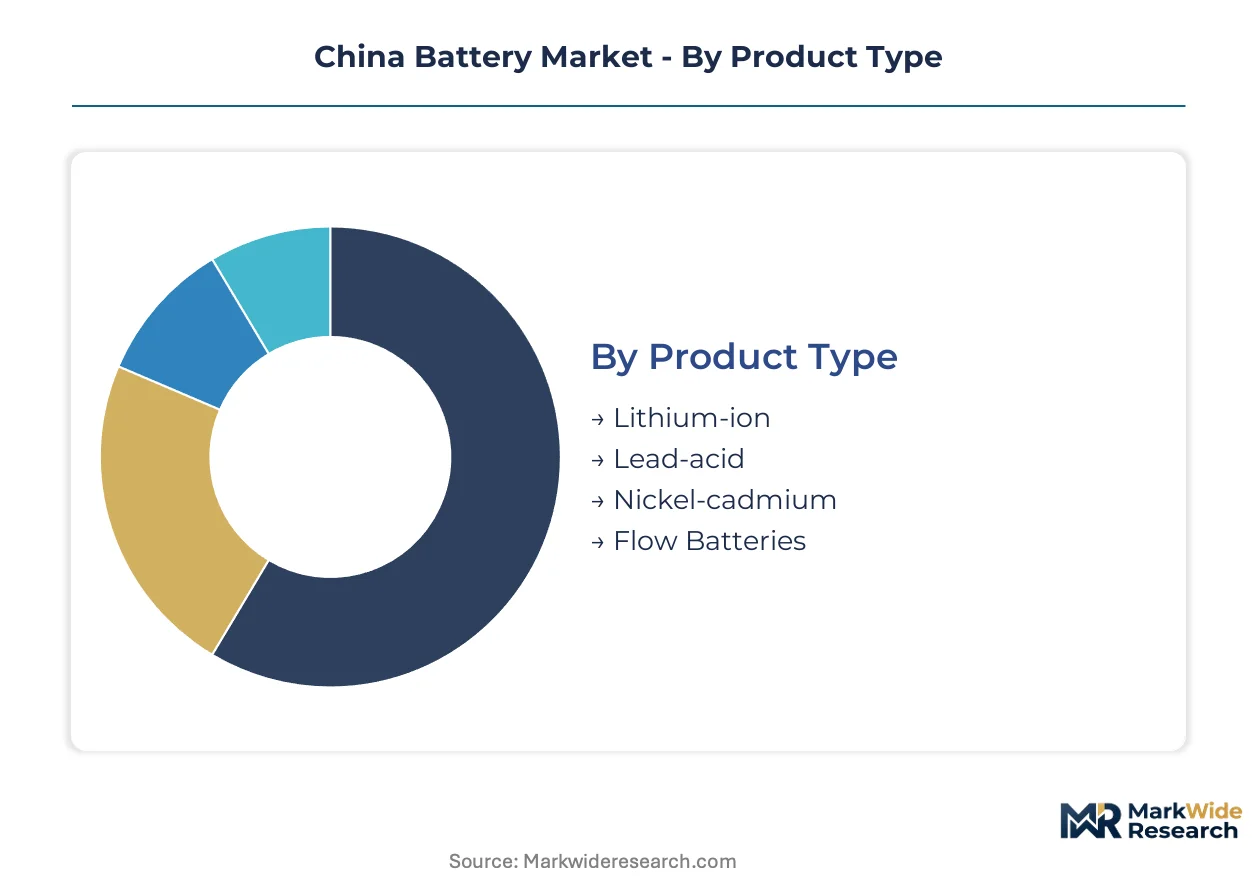
China's battery market segmentation reveals how capital deployment, regulatory thresholds, and chemistry choices fragment procurement patterns across automotive, grid, and industrial applications. Understanding these divides exposes where pricing power concentrates and where commoditization pressures erode margins.
Product Type:
Lithium-ion and lead-acid architectures demand fundamentally different capital commitments, with cathode material refining and formation cycling representing the dominant cost tiers.
- Lithium-ion:Dominant chemistry spans nickel-cobalt-manganese, lithium iron phosphate, and high-nickel variants with energy densities from 160 to 300 Wh/kg. CATL and BYD absorb 70% of national cell output through Yangtze River Delta integration corridors serving Shanghai-based EV assemblers.
- Lead-acid:Mature flooded and absorbed glass mat designs persist in commercial vehicle starting-lighting-ignition applications and low-cost motive power. Tianneng and Chaowei maintain pricing discipline through captive recycling networks in Zhejiang and Jiangsu provinces.
- Nickel-cadmium:Aviation and rail signaling applications in Chengdu and Xi'an retain demand for this chemistry's extreme temperature tolerance despite cadmium toxicity restrictions under MEE hazardous substance protocols.
- Flow Batteries:Vanadium redox systems scale through 100 MWh+ installations in Gansu and Qinghai grid storage tenders where 20-year cycle life offsets upfront electrolyte costs.
Most installed capacity flows through lithium-ion chemistries. Expansion is steepest in lithium iron phosphate variants for grid storage and entry-level electric vehicles.
Application:
Volume concentration and margin structure diverge sharply between mobility platforms and stationary systems, with automotive qualification cycles demanding 3-5 year validation timelines.
- Electric Vehicles:Passenger and commercial platforms drive 60% of national cell consumption through NCM and LFP pack configurations. MIIT energy density mandates above 180 Wh/kg force chemistry upgrades for subsidy eligibility.
- Consumer Electronics:Cylindrical and pouch cells for smartphones, laptops, and power tools operate on 6-12 month product cycles with thinner margin profiles than automotive.
- Energy Storage:Utility-scale deployments in Jiangsu and Guangdong provinces absorb gigawatt-hour volumes through 10-year offtake structures with mandatory fire suppression under GB 51048 standards.
- Industrial Equipment:Forklift, mining vehicle, and port crane electrification in Shenzhen and Ningbo relies on heavy-duty lithium iron phosphate packs with 8,000+ cycle ratings.
Electric vehicles anchor volume demand. Energy storage applications are gaining share fastest as provincial grid operators absorb renewable intermittency.
End User:
Procurement sophistication and contract structures vary from state-owned fleet aggregators to fragmented electronics assemblers, reshaping supplier qualification requirements.
- Automotive Sector:BYD, NIO, and state-owned SAIC deploy direct cell supply agreements with CATL and Gotion, often with equity stakes or joint venture structures for capacity reservation.
- Electronics Manufacturers:Foxconn, Xiaomi, and Huawei source cylindrical and pouch cells through competitive bidding with 12-month price lock provisions.
- Telecommunications:China Mobile and China Tower deploy backup power systems with 48V rack configurations, prioritizing cycle life over energy density for base station redundancy.
- Renewable Energy:Wind and solar developers in Inner Mongolia and Xinjiang procure containerized storage systems through provincial tender processes with local content requirements.
Automotive offtake commands the largest share of premium cell output. Renewable energy integration is climbing the fastest as western provinces accelerate wind-solar-storage hybrid projects.
Technology:
R&D intensity and commercial readiness separate pilot-stage architectures from scaled manufacturing, with solid-state attracting concentrated investment despite delayed deployment timelines.
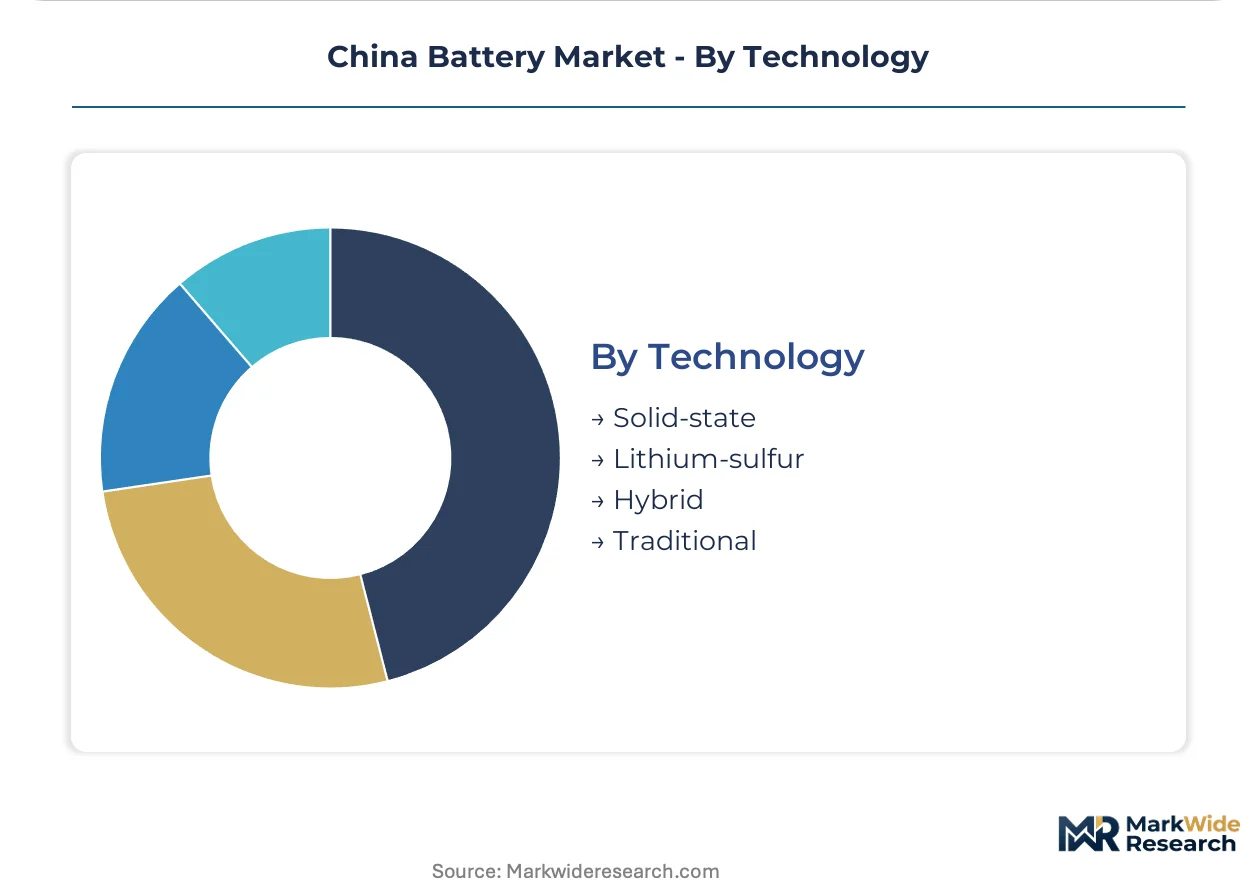
- Solid-state:Sulfide and oxide electrolyte variants promise 400+ Wh/kg density with eliminated thermal runaway risk. Qing Tao Energy and WeLion run pilot lines but commercial volumes remain below automotive qualification thresholds.
- Lithium-sulfur:Theoretical energy density exceeds 500 Wh/kg but polysulfide shuttle degradation limits cycle life to under 500 iterations, restricting use to aerospace and defense applications.
- Hybrid:Supercapacitor-battery combinations serve high-pulse applications in hybrid transit buses and port equipment where rapid charge acceptance complements energy storage.
- Traditional:Conventional liquid electrolyte lithium-ion with graphite anodes and metal oxide cathodes retains cost advantages across 90% of installed capacity.
Traditional liquid electrolyte systems dominate current installations. Solid-state platforms are expanding most quickly in pilot funding and patent filings despite production lag.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's battery industry traces its scaling momentum to the 2010s state-led push for electric vehicle industrialization, with the Yangtze River Delta emerging as the foundational manufacturing corridor before capacity radiated to interior provinces seeking cheaper power and raw material proximity.
Yangtze River Delta
Shanghai-Ningbo-Changzhou concentration hosts 60% of national cathode refining capacity and the headquarters of CATL and Gotion High-tech. MIIT energy density mandates flow through this corridor first, pressuring pack integrators to qualify higher-nickel formulations ahead of subsidy deadlines. Ningbo's port infrastructure handles cobalt hydroxide imports from the Democratic Republic of Congo while Changzhou's dry electrode coating specialists command wage premiums.
Pearl River Delta
Shenzhen and Dongguan absorb retired EV packs for second-life grid storage refurbishment, creating arbitrage opportunities between mobility and stationary applications. MEE hazardous substance protocols enforce cadmium recovery standards at Tianneng's Zhejiang recycling facilities serving this southern demand cluster. BYD anchors blade battery production across its Shenzhen and Huizhou sites for passenger and commercial vehicle lines.
Beijing-Tianjin-Hebei
State-owned fleet operators in Beijing consolidate procurement through battery-as-a-service contracts with per-kilometer pricing models. SAMR monitors market concentration among cell producers supplying SAIC and BAIC joint ventures in this northern corridor. Tianjin's port processes lithium spodumene concentrates from Australia and Zimbabwe for distribution to Hebei cathode material plants.
Sichuan-Chongqing
Yajiang and Ganzi counties in western Sichuan host hard rock lithium mining operations feeding provincial giga-factories with hydropower-priced electricity below 0.25 yuan/kWh. MEE environmental compliance audits have elevated capital barriers for new cathode entrants in this migration zone. Chongqing's automotive assembly plants from Changan and Ford source LFP packs from local CATL joint ventures.
Shandong Peninsula
Heilongjiang and Shandong provinces control 80% of domestic spherical graphite anode supply, exposing mid-tier cell makers to single-source risk in this northern concentration. Qingdao and Yantai ports handle synthetic graphite precursor shipments to Yangtze River Delta cell plants. GB 38031 thermal runaway propagation testing facilities in Jinan add 8-14 months to commercial vehicle pack approval cycles.
China Battery Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across China's battery value chain, with integrated mining-to-pack architectures facing modular cell specialists in contract manufacturing arrangements. The market structure tilts toward oligopoly at the cell tier while fragmenting across cathode material refining and recycling recovery services. Three archetypes dominate: state-backed conglomerates with captive automotive demand, independent cell pure-plays serving multiple OEMs, and material specialists controlling specific chemistry inputs. Competitive intensity centers on capacity reservation agreements and equity-backed joint ventures rather than price undercutting.
Among Yangtze River Delta-anchored producers, CATL, BYD, and Gotion High-tech occupy positions across the integrated-to-specialist spectrum. CATL exemplifies the diversified supply archetype through multi-OEM offtake structures. BYD represents captive demand integration with in-house vehicle deployment. Gotion High-tech sits within the utility-scale storage specialization tier. These three entities anchor the competitive geometry that shapes qualification timelines, pricing benchmarks, and technology roadmapping across domestic and export markets.
| Leading Market Players |
|---|
| Eve Energy |
| Svolt Energy |
| CATL |
| Zenergy |
| Sunwoda |
| BYD |
| CALB |
| Rept Battero Energy |
| Gotion High-tech |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed producers with state equity stakes anchor pricing discipline across China's battery value chain, compressing margin volatility through long-term offtake structures while feeding procurement preferences into cathode material contract terms. Their dominance in Yangtze River Delta giga-factories shapes how lithium carbonate input costs transmit downstream to automotive and grid storage buyers.
Pricing Analysis
Long-term contract-based offtake structures dominate volume transactions, with pricing stratifying across automotive qualification tier, volume commitment scale, and carbon intensity certification under MIIT protocols. Price differentiation hinges on cathode chemistry grade and verified low-carbon footprint credentials rather than pure energy density metrics. Cost compression in entry-level lithium iron phosphate cells is intensifying because sodium-ion alternatives are eroding addressable demand. Fleet operators and provincial grid procurement offices exhibit the sharpest price sensitivity, while premium passenger vehicle platforms absorb nickel-cobalt-manganese premiums for subsidy eligibility.
Supply Chain Analysis
Reverse-logistics flows for retired electric vehicle packs are creating secondary supply channels, with Shenzhen and Hangzhou refurbishment hubs feeding grid storage deployments at 40-60% of new cell cost. Raw material sourcing draws from Australian spodumene concentrates, Chilean and Argentine brine operations, and Democratic Republic of Congo cobalt hydroxide shipments through Ningbo port. Single-source vulnerability concentrates in Heilongjiang and Shandong spherical graphite anode supply, exposing mid-tier producers to disruption. Distribution runs through Yangtze River Delta cathode refining corridors before final pack integration at OEM-adjacent facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's battery market functions as a stable compounder, with dual carbon policy enforcement and provincial renewable integration mandates ensuring sustained demand visibility across automotive and grid storage applications.
For Market Incumbents: Hedge against sodium-ion displacement in sub-300 km vehicle segments by accelerating silicon-anode and solid-state pilot investments before automotive qualification thresholds tighten. Lock cathode supply through backward integration into Sichuan lithium mining or equity stakes in Yangtze River Delta refining capacity. Defend margin position against emerging dry electrode coating specialists by acquiring rare polymer science talent pools commanding wage premiums. For New Entrants and Emerging Players: Solid-state electrolyte material innovation offers the most penetrable wedge, with sulfide and oxide conductor variants still below automotive scale thresholds and incumbent R&D timelines extending past commercial deployment windows. Target western China manufacturing migration zones where Sichuan and Yunnan hydropower-priced electricity undercuts coastal production economics. Pursue licensing partnerships with provincial grid operators for 100 MWh+ vanadium redox or lithium iron phosphate installations rather than competing directly for automotive qualification cycles. For Investors and Strategic Acquirers: Valuations sit cheapest among hydrometallurgical recycling specialists positioned to capture SAMR-mandated 85% lithium recovery licensing opportunities as black mass processing rules formalize. Long-term viability favors asset-light technology licensors over capital-intensive giga-factory operators given cell-to-pack architecture commoditization pressures. Monitor MIIT energy density mandate threshold announcements as the critical inflection signal for chemistry transition timing and cathode material demand shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Cell-to-Pack Architecture Adoption | CATL and BYD compression of module boundaries reduces bill-of-materials costs while forcing thermal management integration at cell level. |
| Sodium-Ion Chemistry Scale-Up | Prussian blue cathode variants for A00-class vehicles displace low-energy-density lithium-ion in sub-300 km urban segments. |
| Western China Manufacturing Migration | Sichuan and Yunnan hydropower-priced electricity below 0.25 yuan/kWh attracts giga-factory investment away from coastal corridors. |
| Second-Life Battery Arbitrage | Retired Shenzhen and Hangzhou EV packs refurbished for 4-hour grid storage applications create circular supply channels. |
| Solid-State Electrolyte Pilot Investment | Qing Tao Energy and WeLion sulfide-based ceramic conductor development targets 400+ Wh/kg density with eliminated thermal runaway risk. |
Methodological Framework
Multiple input streams — cell producer procurement executives, provincial grid operator planning officers, cathode material plant managers, and MIIT regulatory affairs specialists — were reconciled against customs trade databases, MIIT GB standard filings, and SAMR market concentration disclosures. Secondary validation drew from EIA international energy data, IEA battery technology roadmaps, and vehicle production registration databases. Bottom-up capacity installation tallies and top-down demand elasticity models were cross-referenced to establish volume baselines.
Historical deployment trajectories were cross-referenced against expert panel assessments of solid-state commercialization timelines and sodium-ion cost curves across the analysis window. Segmentation dimensions modeled include chemistry type, application vertical, end-user procurement sophistication, and technology readiness tier. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion announcements. Industry-specific forecast inputs incorporated lithium carbonate price volatility bands and MIIT subsidy threshold revision scenarios.
The model holds under sustained dual carbon policy enforcement and provincial renewable integration commitments; deviation in lithium brine extraction bottlenecks or solid-state breakthrough acceleration would shift chemistry transition timelines. Forecasts embed assumptions regarding SAMR recycling mandate implementation and MEE environmental audit stringency. Practitioners should monitor MIIT energy density threshold announcements and lithium carbonate spot price movements for early signals of contract repricing pressure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Rechargeable Battery Market
Batteries
18650 And 21700 Battery Market
Batteries
Deep Cycle Battery Market
Batteries
Europe Consumer Battery Market
Batteries
Second-Life EV Battery Module Qualification Test Systems Market
Batteries
China Electric Vehicle Vrla Batteries Market
Batteries
N-Type Battery Market
Batteries
India Electric Vehicle Battery Electrolyte Market
Batteries
Asia-Pacific Rechargeable Battery Market
Batteries
India Battery Market
Batteries
Europe Battery Cell Market
Batteries
Lithium Marine Battery Market
Batteries
Latin America Automotive Lead-Acid Battery Market
Batteries
North Africa Battery Market
Batteries
United States Household Battery Market
Batteries
Behind-The-Meter (BTM) Battery Market