
 Aluminum-Air Battery Market | 2026-2036
Aluminum-Air Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum-Air Battery Market Analysis
Chinese electrolytic aluminum capacity is decoupling from legacy battery metal supply chains. Phinergy anchors Israel's aluminum-air development through its metal-air technology platform. Alcoa Corporation leverages its upstream aluminum smelting position to supply high-purity anode material. Fuji Pigment specializes in catalytic electrode coatings that extend cell cycle stability.
An aluminum-air battery generates electricity through electrochemical oxidation of an aluminum anode in an alkaline electrolyte, achieving theoretical energy densities exceeding 4,000 Wh/kg. The system employs aqueous electrolytes and air-breathing cathodes, making it suitable for long-duration backup power and electric vehicle range extenders. Primary aluminum-air configurations currently lead commercial deployments due to simpler mechanical design and lower balance-of-plant cost. Secondary and hybrid architectures are gaining engineering attention as electrolyte recovery systems improve round-trip efficiency. Advanced technology variants command development focus where nanostructured cathodes and solid-state electrolyte interfaces promise reduced corrosion rates.
Israel's national innovation authority and China's MIIT both channel public funding into metal-air electrochemistry programs. REACH in Europe governs electrolyte chemical registration and disposal pathways for alkaline systems deployed across member states. Stakeholders must weigh aluminum sourcing security against cathode catalyst cost curves when committing to manufacturing scale.
Market Dynamics
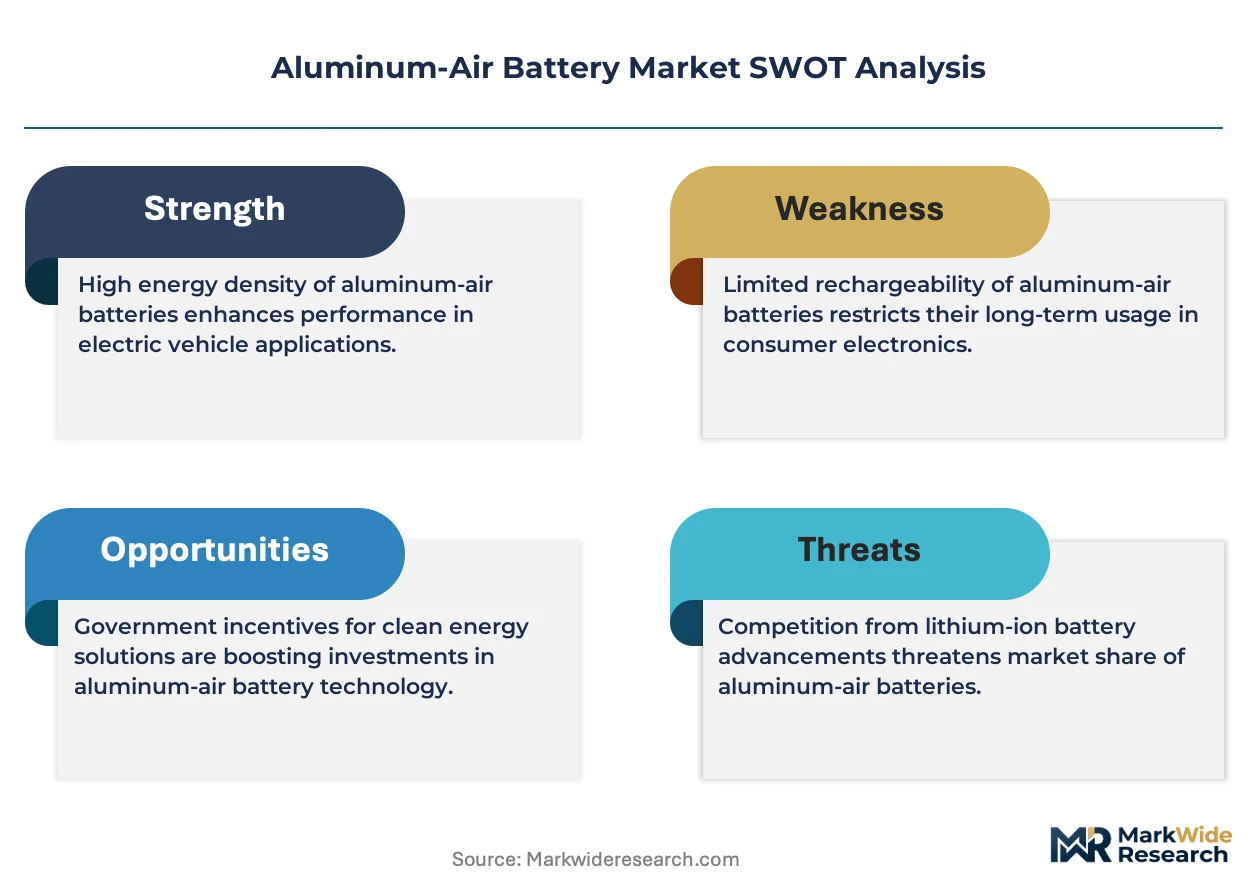
Electrolyte recovery system economics now govern aluminum-air commercialization timelines, forcing developers to prioritize mechanical refueling infrastructure over electrochemical breakthroughs.
Growth Catalysts
- Dual carbon goals from China's MEE:National emissions targets channel public R&D funding toward metal-air electrochemistry platforms that bypass lithium supply constraints.
- Range extender architecture:Electric vehicle fleets in Germany integrate aluminum-air systems as trailer-mounted backup units, eliminating battery swap infrastructure costs.
- Alkaline electrolyte chemistry:Aqueous systems bypass thermal runaway risks that constrain lithium-ion deployment in maritime and aviation applications.
Market Restraints
- Aluminum price volatility:London Metal Exchange pricing for high-purity primary metal creates input cost uncertainty for anode manufacturing.
- Cathode catalyst concentration:Platinum-group metal supply constraints in South Africa and Russia limit air electrode production scaling.
- REACH registration burden:ECHA chemical compliance requirements for potassium hydroxide electrolytes add administrative overhead across EU member state deployments.
Strategic Opportunities
- Israeli energy storage corridor:National innovation authority funding supports pilot manufacturing clusters around Phinergy's metal-air technology platform.
- Maritime decarbonization mandates:International Maritime Organization emission targets position aluminum-air as auxiliary power for container vessels lacking shore charging access.
- Solid-state electrolyte interfaces:Convergence of ceramic membrane technology with aqueous systems promises corrosion rate reduction below 0.1 mm per year.
Industry Challenges
- Electrochemical engineering talent scarcity:Specialized expertise in metal-air corrosion kinetics remains concentrated in Israeli and Chinese research institutions.
- Refueling station capex intensity:Electrolyte regeneration facilities require capital commitments comparable to hydrogen compression infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum-Air Battery Market |
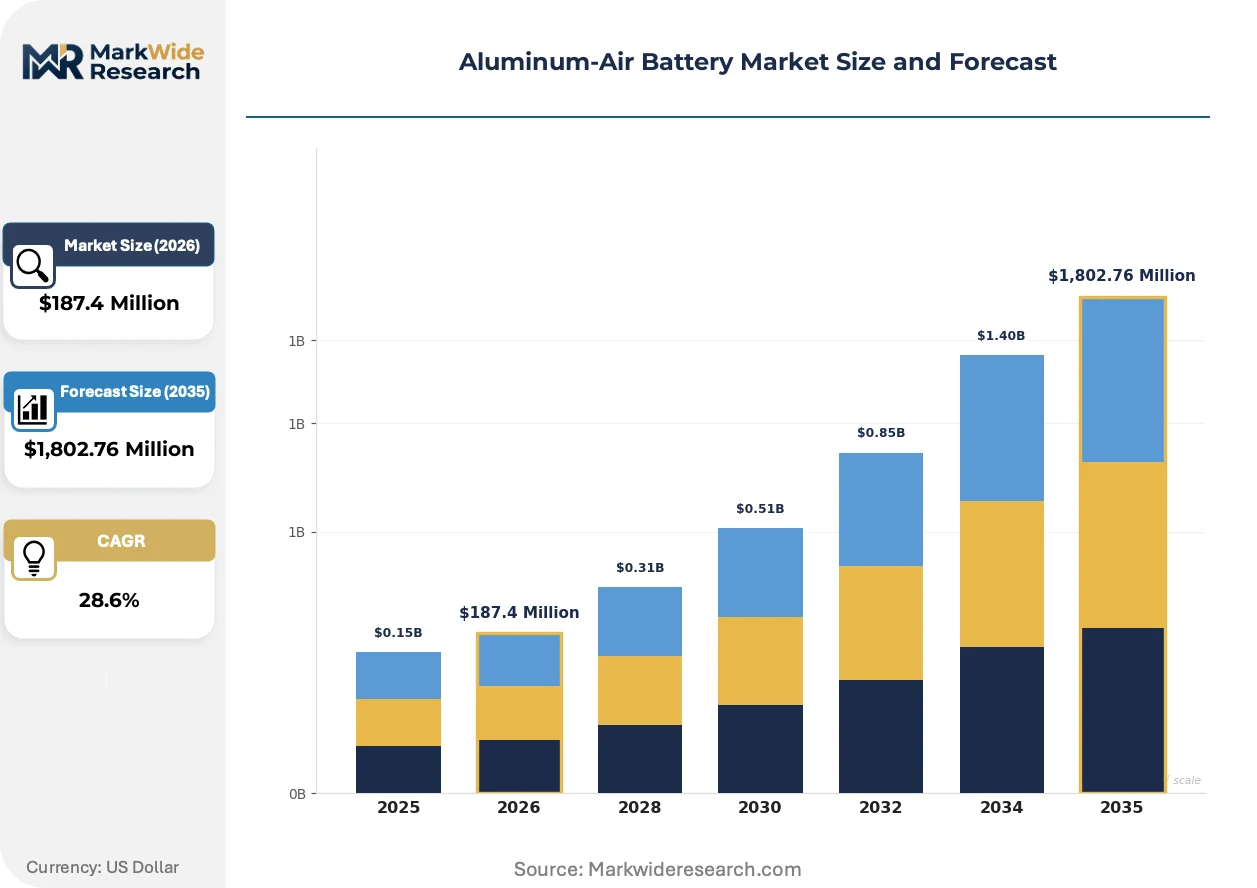
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,802.76 Million |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Primary, Secondary, Hybrid, Rechargeable End User: Aerospace, Automotive, Marine, Industrial Technology: Conventional, Advanced, Microbial, Nanotechnology Application: Energy Storage, Electric Vehicles, Military, Consumer Electronics |
| Companies Covered | Aionics, Xinjiang Joinworld Co., Ltd., Phinergy, De Nora Tech, Inc., ACTXE Limited, AquaMetals, Fuji Pigment, Arotech Corporation, Alcoa Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum-Air Battery Market Emerging Trajectories
Mechanical refueling architectures are displacing electrochemical reversibility as the dominant commercialization pathway, reshaping how developers prioritize engineering resources across primary and secondary system designs.
Nanostructured cathode materials are integrating graphene-based catalyst supports into air electrode manufacturing. Tier-one automotive suppliers in Germany pilot these electrodes for range extender modules. This integration is compressing platinum loading requirements by an order of magnitude while maintaining current density performance.
REACH authorization timelines are tightening electrolyte chemical registration requirements for alkaline systems deployed across EU member states. ECHA's expanded substance evaluation list now captures potassium hydroxide purity grades previously exempt under legacy classifications. Marine propulsion integrators in the Netherlands and Norway are accelerating compliance documentation to maintain port access rights.
Fleet procurement contracts are unbundling battery ownership from vehicle acquisition, shifting capital burden to energy service providers. Logistics operators in Germany and China now lease aluminum-air range extenders under power-by-the-hour arrangements. This restructuring concentrates demand volume with third-party refueling network operators rather than OEM captive finance arms.
Aluminum-Air Battery Market Segmentation
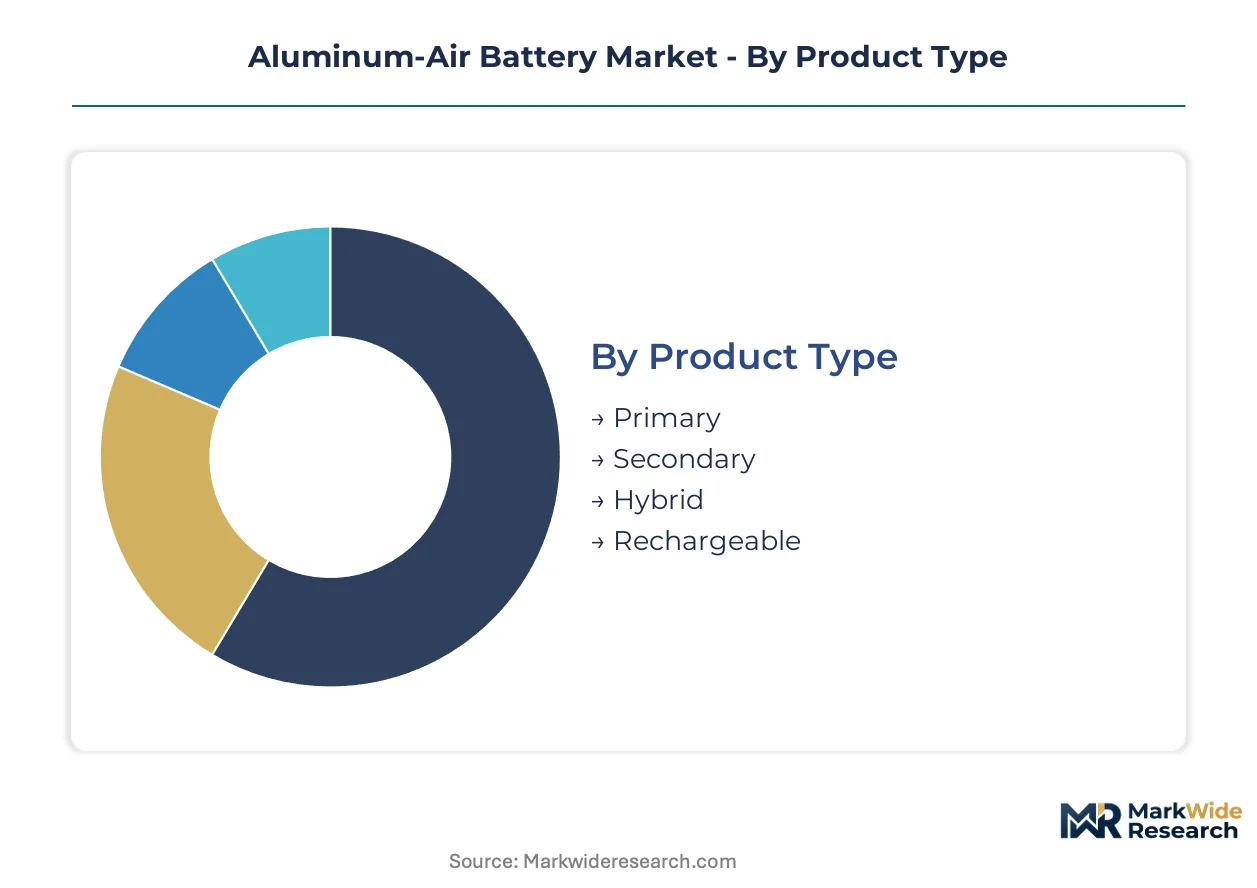
Aluminum-air battery architectures diverge sharply in capital requirements and operational complexity. Each segmentation dimension reveals distinct pathways for engineering investment and commercial deployment across electrochemical system designs.
Product Type:
Capital intensity peaks with secondary and rechargeable architectures due to electrolyte regeneration infrastructure requirements. Primary systems demand minimal balance-of-plant investment.
- Primary:Non-rechargeable configurations employ single-use aluminum anodes with aqueous alkaline electrolytes. German electric vehicle fleets deploy these as trailer-mounted range extenders, eliminating battery swap infrastructure costs while extending driving range.
- Secondary:Partially rechargeable systems integrate mechanical refueling with limited electrochemical reversibility. China's MIIT-funded research programs concentrate development resources here, targeting round-trip efficiency improvements through electrolyte recovery systems.
- Hybrid:Combined architectures pair aluminum-air cells with lithium-ion buffers for power conditioning. Maritime propulsion integrators in the Netherlands pilot these for container vessel auxiliary power.
- Rechargeable:Full electrochemical reversibility remains pre-commercial, requiring solid-state electrolyte interfaces and nanostructured cathodes. Israeli innovation authority grants support Phinergy's development trajectory in this segment.
Primary systems absorb the bulk of installed capacity; rechargeable architectures are expanding most quickly through public R&D funding channels.
End User:
Application risk profiles vary dramatically across sectors, with aerospace and marine imposing the most stringent safety certification burdens.
- Aerospace:Auxiliary power units for electric aircraft require thermal runaway immunity that alkaline electrolyte chemistry provides. FAA certification pathways for metal-air systems remain under development.
- Automotive:Range extender modules dominate commercial traction. German logistics operators lease aluminum-air units under power-by-the-hour arrangements, concentrating demand with third-party refueling network operators.
- Marine:International Maritime Organization emission targets position these systems for container vessels lacking shore charging access. Norwegian and Dutch integrators accelerate REACH compliance documentation for port access rights.
- Industrial:Long-duration backup power for manufacturing facilities leverages aluminum-air's theoretical energy density exceeding 4,000 Wh/kg. Stationary deployments bypass mechanical refueling complexity through centralized electrolyte regeneration.
Automotive applications command the largest addressable market; marine end-use is gaining share fastest under regulatory pressure.
Technology:
Performance differentiation increasingly concentrates at the electrode-electrolyte interface, where nanostructured materials command premium development investment.
- Conventional:Standard aqueous alkaline systems with carbon-based air cathodes. These dominate pilot manufacturing operations in Israel's energy storage corridor.
- Advanced:Nanostructured cathodes integrating graphene-based catalyst supports compress platinum loading requirements by an order of magnitude. Tier-one German automotive suppliers pilot these electrodes for range extender modules.
- Microbial:Bio-electrochemical interfaces using engineered microorganisms for cathode catalysis. Research-stage programs in Chinese national laboratories explore corrosion rate reduction through biological pathways.
- Nanotechnology:Solid-state electrolyte interfaces promise corrosion rates below 0.1 mm per year. Convergence of ceramic membrane technology with aqueous systems drives materials science investment.
Conventional technology retains the largest installed base; advanced nanostructured systems are climbing the fastest through automotive supplier integration.
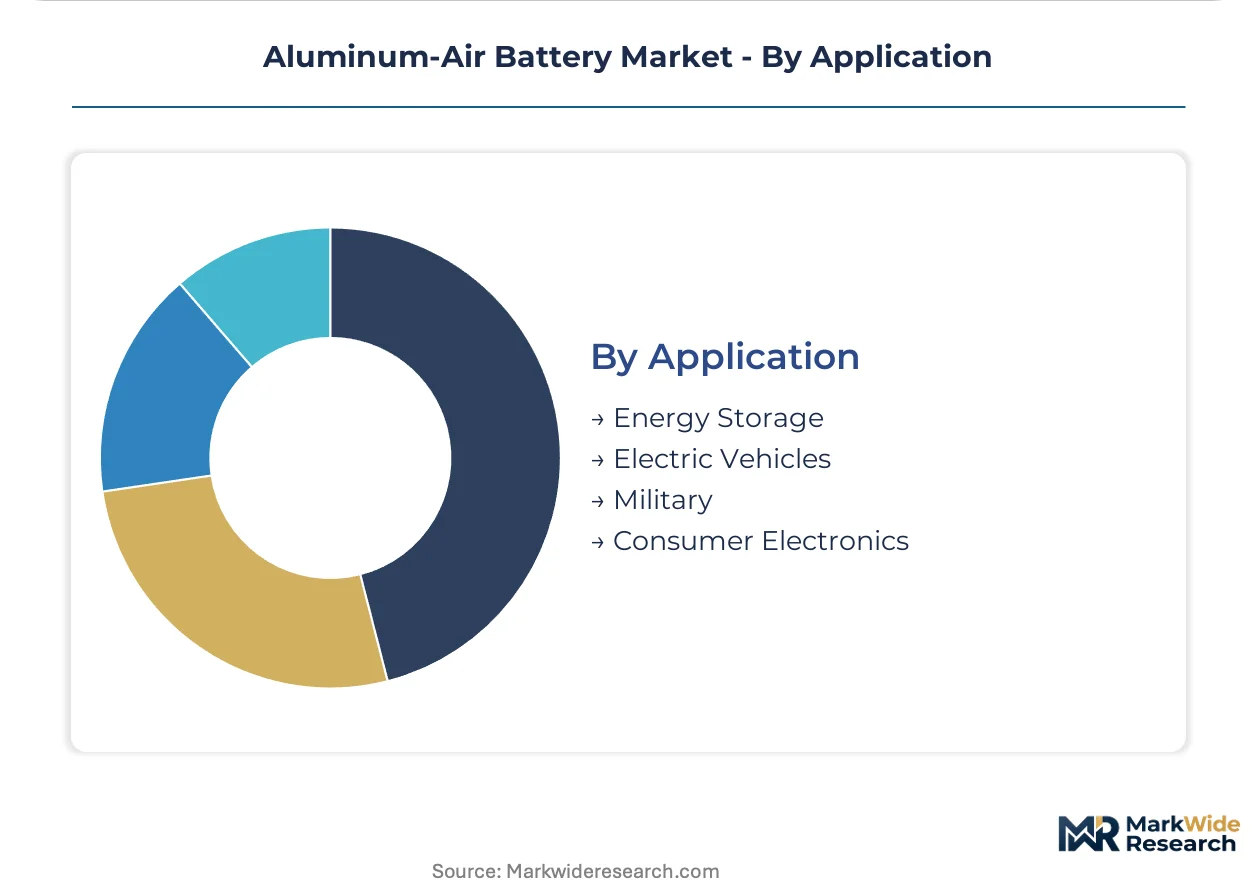
Application:
Procurement patterns diverge between stationary energy storage and mobility applications, with military requirements imposing unique supply security constraints.
- Energy Storage:Grid-scale and industrial backup systems prioritize energy density over power density. Long-duration discharge profiles match aluminum-air's electrochemical characteristics.
- Electric Vehicles:Range extension architectures dominate commercial deployment. Fleet procurement contracts unbundle battery ownership from vehicle acquisition, shifting capital burden to energy service providers.
- Military:Forward operating base power demands silent generation and logistics simplicity. Metal-air systems bypass lithium supply chain vulnerabilities that constrain tactical energy storage.
- Consumer Electronics:Portable power applications remain marginal due to mechanical refueling requirements. Form factor constraints limit penetration against solid-state lithium alternatives.
Energy storage applications anchor current manufacturing volume; electric vehicle integration is gaining share fastest through German and Chinese fleet procurement restructuring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity aluminum smelting capacity in Iceland and Norway underpins European anode supply security. Israel's Dead Sea corridor hosts concentrated metal-air research infrastructure. China's Shandong and Henan provinces anchor electrolytic aluminum output for battery-grade feedstock.
Germany
German electric vehicle fleets deploy trailer-mounted aluminum-air range extenders for logistics corridors. KBA vehicle certification frameworks accommodate metal-air auxiliary power units under amended technical guidelines. Bavaria's automotive supplier cluster around Munich pilots nanostructured cathode integration for tier-one OEM programs.
China
MIIT channels public R&D funding into secondary aluminum-air architectures targeting round-trip efficiency gains. Dual carbon goals from MEE accelerate metal-air battery research as lithium supply hedge. Shandong Province's electrolytic aluminum base supplies high-purity anode material to domestic cell manufacturers.
Israel
National innovation authority grants concentrate metal-air electrochemistry expertise in the Dead Sea research corridor. Phinergy anchors pilot manufacturing operations with public funding support. Tel Aviv-area engineering talent pools specialize in corrosion kinetics for aqueous alkaline systems.
United States
FAA certification pathways for metal-air auxiliary power units remain under development for electric aircraft applications. EPA environmental compliance frameworks govern electrolyte chemical handling for stationary industrial deployments. Michigan's automotive engineering base evaluates range extender architectures for fleet electrification programs.
Netherlands
Maritime propulsion integrators accelerate REACH compliance documentation for potassium hydroxide electrolyte systems. Port of Rotterdam authorities position aluminum-air auxiliary power for container vessels lacking shore charging infrastructure. Eindhoven's materials science cluster advances ceramic membrane interfaces for corrosion rate reduction.
Aluminum-Air Battery Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue advanced nanostructured architectures and solid-state interfaces. The vendor base stratifies across upstream aluminum suppliers, catalytic electrode specialists, and integrated cell developers. Three archetypes dominate: smelter-affiliated anode suppliers, coating technology licensors, and system integrators with refueling network ambitions. Competitive moves concentrate on strategic partnerships for electrolyte regeneration infrastructure and technology licensing for cathode catalyst formulations.
Within the integrated system developer tier, Phinergy and Arotech Corporation exemplify distinct geographic positioning strategies. Alcoa Corporation represents upstream backward integration into battery-grade aluminum supply. Fuji Pigment occupies a specialization position in catalytic electrode coatings. Xinjiang Joinworld Co., Ltd. anchors Chinese electrolytic aluminum capacity serving regional cell manufacturing demand.
| Leading Market Players |
|---|
| Aionics |
| Xinjiang Joinworld Co., Ltd. |
| Phinergy |
| De Nora Tech, Inc. |
| ACTXE Limited |
| AquaMetals |
| Fuji Pigment |
| Arotech Corporation |
| Alcoa Corporation |
| Others |
Supply Flow & Price Mechanics
Captive backward integration into high-purity aluminum smelting anchors both supply security and pricing power for anode suppliers. Alcoa Corporation's upstream control over battery-grade feedstock insulates production costs from London Metal Exchange volatility that squeezes non-integrated cell developers.
Pricing Analysis
Power-by-the-hour leasing arrangements bundle electrolyte regeneration service with hardware deployment, unbundling capital expenditure from operational contracts. German logistics operators favor this structure over outright purchase, compressing upfront pricing while elongating revenue capture timelines. Price differentiation hinges on cathode catalyst grade and REACH compliance certification tier. Cost compression in standard-grade primary systems is intensifying because platinum-group metal supply constraints from South Africa and Russia limit air electrode production scaling. Fleet procurement managers exhibit highest price sensitivity; maritime integrators accepting longer payback periods show lowest.
Supply Chain Analysis
Platinum-group metal supply rests on South African mining output and Russian refining capacity, creating concentrated catalyst sourcing vulnerability. High-purity aluminum anode material draws from Icelandic and Norwegian smelting operations alongside Chinese electrolytic capacity in Shandong and Henan provinces. Graphene-based catalyst support substrates hinge on East Asian specialty chemical producers. Single-source vulnerability in PGM supply generates tariff exposure risk from geopolitical disruption. Distribution runs through third-party refueling network operators rather than OEM captive channels, concentrating logistics control with energy service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH authorization timelines for potassium hydroxide electrolytes erect compliance moats that favor incumbent players with established ECHA documentation. New entrants face 18-24 month registration burdens that delay market access.
For Market Incumbents: Deepen electrolyte regeneration infrastructure deployment across German logistics corridors to lock in fleet leasing contracts. Secure long-term offtake agreements with Icelandic and Norwegian smelters to insulate anode supply from Chinese capacity volatility. Solid-state electrolyte interface R&D represents the critical capability gap separating market leaders from follower tiers.
For New Entrants and Emerging Players: Maritime propulsion integrators in the Netherlands and Norway present the most penetrable entry point given accelerated IMO decarbonization mandates and limited incumbent refueling network presence. Target container vessel auxiliary power applications where shore charging infrastructure gaps persist. Pursue joint development agreements with Eindhoven materials science clusters for ceramic membrane interface technology transfer.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by tier-one automotive suppliers seeking range extender module capabilities. Five-to-ten year viability hinges on mechanical refueling infrastructure achieving cost parity with hydrogen compression systems. Watch for FAA certification pathway finalization for metal-air auxiliary power units as inflection signal for aerospace segment commercialization.
| Strategic Initiative | Industry Significance |
|---|---|
| Electrolyte Regeneration Network Buildout | German fleet operators concentrate demand with third-party refueling infrastructure operators. |
| REACH Compliance Certification Investment | ECHA potassium hydroxide registration creates barrier-to-entry moat for compliant cell developers. |
| Platinum-Group Metal Supply Agreement | Long-term catalyst sourcing contracts insulate air electrode production from South African supply volatility. |
| Solid-State Electrolyte Interface R&D Partnership | Ceramic membrane technology convergence with aqueous systems targets corrosion rates below 0.1 mm per year. |
| Maritime Auxiliary Power Pilot Deployment | Port of Rotterdam authorities position aluminum-air for container vessels lacking shore charging access. |
Methodological Framework
Independent corroboration across cell engineering directors, refueling network operators, and ECHA compliance consultants underwrites the qualitative findings. Primary fieldwork engaged aluminum smelter procurement leads, tier-one automotive supplier battery strategists, and maritime propulsion integrators across Germany, China, Israel, and the Netherlands. Secondary validation drew from MIIT funding disclosure databases, ECHA substance evaluation lists, and International Maritime Organization emission target documentation. Bottom-up cell deployment estimates triangulate against top-down aluminum anode demand projections.
Rate-of-change decomposition separates volume expansion from price trajectory across primary, secondary, hybrid, and rechargeable architecture segments. The analytical framework models product type, end-use application, technology tier, and regional regulatory cluster throughout the forecast period. CAGRs derive from electrolyte recovery system cost curve assumptions and mechanical refueling infrastructure deployment timelines. Nanostructured cathode platinum loading compression and solid-state electrolyte interface development maturity serve as key technology readiness inputs.
Several conditions sit outside the modeled scope, including breakthrough electrochemical reversibility achievements and aluminum price shock scenarios exceeding historical volatility bands. Forecasts reflect documented assumptions regarding MIIT funding continuity and REACH authorization timeline stability. Supply chain disruption from South African PGM export restrictions or Icelandic smelter curtailments warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Coin Cell Lithium Batteries Market
Batteries
India Rechargeable Battery Market
Batteries
Primary Lithium Battery for Industrial Market
Batteries
Battery Voltage Recorder Market
Batteries
Primary Battery Market
Batteries
Japan Rechargeable Battery Market
Batteries
Consumer Battery Market
Batteries
United States SLI Battery Market
Batteries
Two Wheeler Lead Acid Batteries Market
Batteries
Solid-State Car Battery Market
Batteries
Lithium-Fluorinated Graphite Batteries Market
Batteries
Battery Cases Market
Batteries
Potassium-Ion Battery Market
Batteries
Europe SLI Battery Market
Batteries
North America Consumer Battery Market
Batteries
Zinc Carbon Battery Market