
 Global Primary Cells Market | 2026-2036
Global Primary Cells Market Size, Share, and Industry Trends Forecast 2026-2036
Global Primary Cells Market Foresight
Multi-source procurement of human tissue-derived specimens is expanding as biopharma buyers diversify beyond captive donor networks. Thermo Fisher Scientific leverages its global cold-chain infrastructure to sustain just-in-time delivery of cryopreserved hepatocytes. Lonza Group anchors European supply through specialized isolation facilities in Switzerland. PromoCell GmbH competes on GMP-compliant customization, differentiating its donor-characterization protocols for immuno-oncology clients.
Primary cells comprise freshly isolated, non-immortalized human or animal cells maintained in vitro under controlled temperature, pH, and nutrient conditions for limited passage numbers before senescence. These cells retain native physiological receptor expression, metabolic enzyme profiles, and signaling pathways that transformed cell lines lose, making them indispensable for predictive toxicology, disease modeling, and cell therapy manufacturing. Lithium primary cells command premium positioning in medical device applications where stable voltage output and extended shelf life justify unit cost. Zinc-air formulations represent the fastest-growing chemistry segment, driven by hearing aid miniaturization and oxygen-cathode efficiency gains. Button cell and coin cell packaging formats dominate wearable and implantable device integration, where volumetric energy density determines design feasibility.
FDA cGMP guidelines and EMA's ATMP regulation jointly shape manufacturing standards for clinical-grade primary cell products, while ISO 20399 sets broader biosafety testing benchmarks for ancillary materials. The EU AI Act and GDPR provisions increasingly govern digital phenotyping workflows that link donor metadata to cell performance databases. Stakeholders must monitor evolving cross-border tissue traceability requirements and invest in compliant informatics infrastructure before procurement policies harden.
Market Dynamics
FDA's tightened cell-based assay guidance is compressing qualification timelines for human-derived hepatocyte suppliers while biopharma buyers consolidate procurement around vendors with verified cold-chain documentation. This regulatory tightening intersects with donor network scarcity to reshape competitive positioning.
Growth Catalysts
- EMA's ATMP Regulation:Clinical-grade primary cell manufacturing requirements are expanding addressable market for GMP-compliant isolation services across European contract development organizations.
- Immuno-oncology screening:CAR-T developers are accelerating hepatocyte and immune cell consumption for off-target toxicity prediction before IND submission.
- United States procurement concentration:Academic consortia and CROs in Massachusetts and California are aggregating purchase volumes through multi-year supply agreements.
Market Restraints
- Donor tissue scarcity:Ethical sourcing constraints and limited qualified collection sites in Germany and Switzerland restrict hepatocyte batch availability.
- Cryopreservation input costs:Liquid nitrogen logistics and specialized media formulations consume 35-40% of unit economics for distributed suppliers.
- Immortalized cell line substitution:HepG2 and HepaRG alternatives are capturing routine cytotoxicity screening from price-sensitive toxicology departments.
Strategic Opportunities
- Japan's regenerative medicine framework:PMDA's conditional approval pathways for cell therapies are opening demand for clinical-grade human hepatocytes in Osaka and Tokyo clusters.
- Organ-on-chip convergence:Microfluidic liver models integrating primary hepatocytes with endothelial co-cultures are creating premium positioning for characterized donor lots.
- Direct-to-biopharma distribution:Bypassing traditional distributor markups through e-procurement platforms is compressing lead times for urgent toxicity studies.
Industry Challenges
- Isolation technician scarcity:GMP-compliant hepatocyte purification requires specialized cell biology expertise that outpaces training pipeline output in Basel and Boston hubs.
- Cross-border tissue traceability:EU GDPR and US HIPAA divergences are complicating unified donor metadata systems for multinational biopharma clients.
- ISO 20399 certification timelines:Biosafety testing documentation for ancillary materials extends supplier onboarding by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Primary Cells Market |
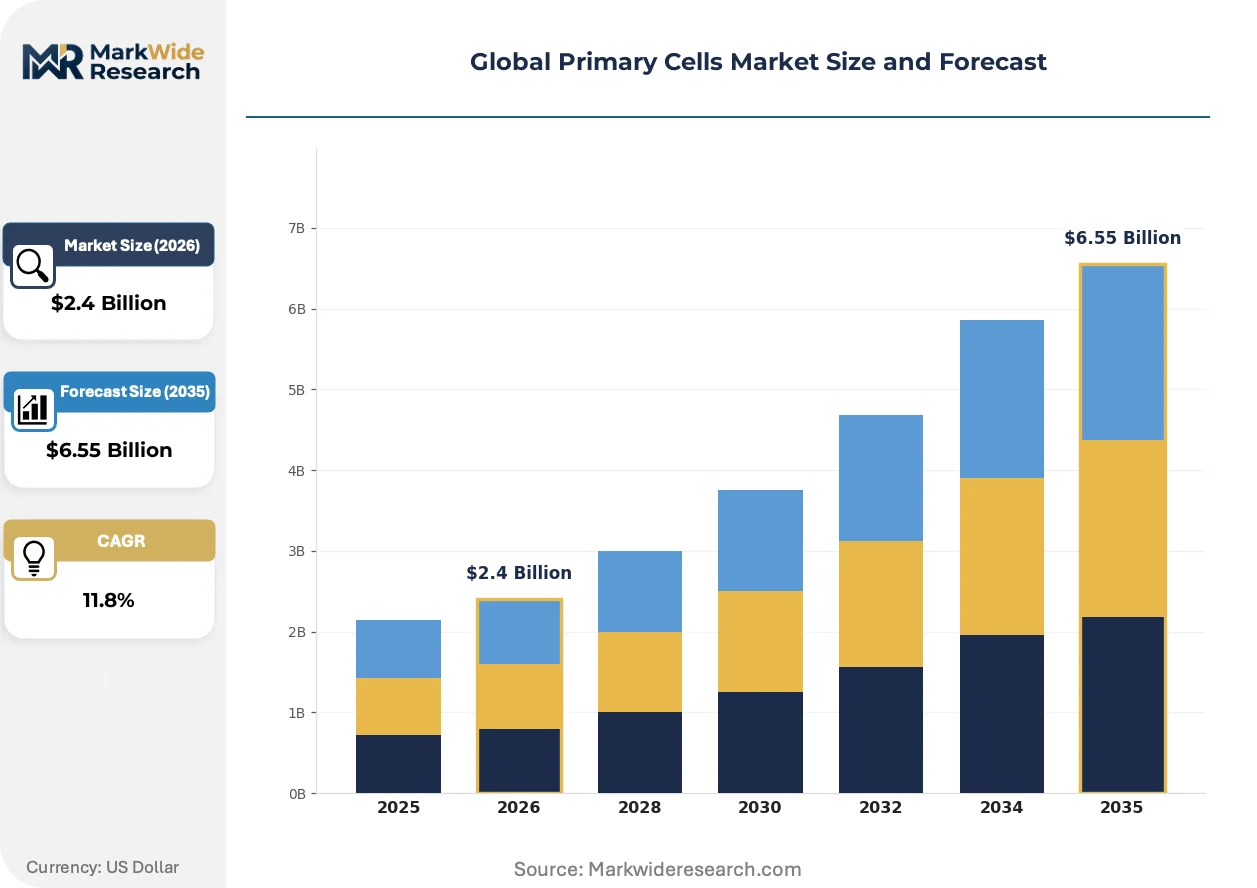
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $6.55 Billion |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Cell Type: Alkaline, Zinc-Carbon, Lithium, Silver Oxide, Zinc-Air Application: Remote Controls, Watches, Smoke Detectors, Calculators, Flashlights Packaging Format: Button Cells, Cylindrical, Prismatic, Coin Cells, Pouch Cells End User: Consumer Electronics, Medical Devices, Industrial Equipment, Military Devices |
| Companies Covered | Cell Biologics, STEMCELL Technologies, Thermo Fisher Scientific, American Type Culture Collection, AllCells, Merck KGaA, PromoCell GmbH, Axol Bioscience, Lonza Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Primary Cells Market Shifts & Advancements
Automated isolation and characterization workflows are compressing batch-to-batch variability while digital phenotyping links donor metadata to performance outcomes. These shifts are reconfiguring supplier capabilities and buyer evaluation criteria.
Robotic liquid handling platforms are automating hepatocyte plating and viability assessment for high-content screening applications. Large toxicology CROs in the United States are deploying these systems at scale to reduce technician-to-technician variation. The technology is automating quality control bottlenecks that previously limited throughput for IND-enabling studies.
EU AI Act provisions governing automated decision-making are imposing documentation burdens on digital phenotyping workflows that correlate donor age, BMI, and metabolic genotype to hepatocyte drug metabolism rates. Cell suppliers using machine learning for batch release must now maintain algorithmic audit trails. This regulatory friction is most acute for Swiss and German vendors serving EU-based biopharma.
Subscription-based cell supply contracts are displacing spot purchasing for repeat toxicology programs. Biopharma procurement teams in California and New Jersey are locking multi-quarter hepatocyte allocations to secure donor-matched consistency across longitudinal studies. This behavioral shift is most visible in immuno-oncology verticals where protocol standardization across sites demands cellular material uniformity.
Global Primary Cells Market Segmentation
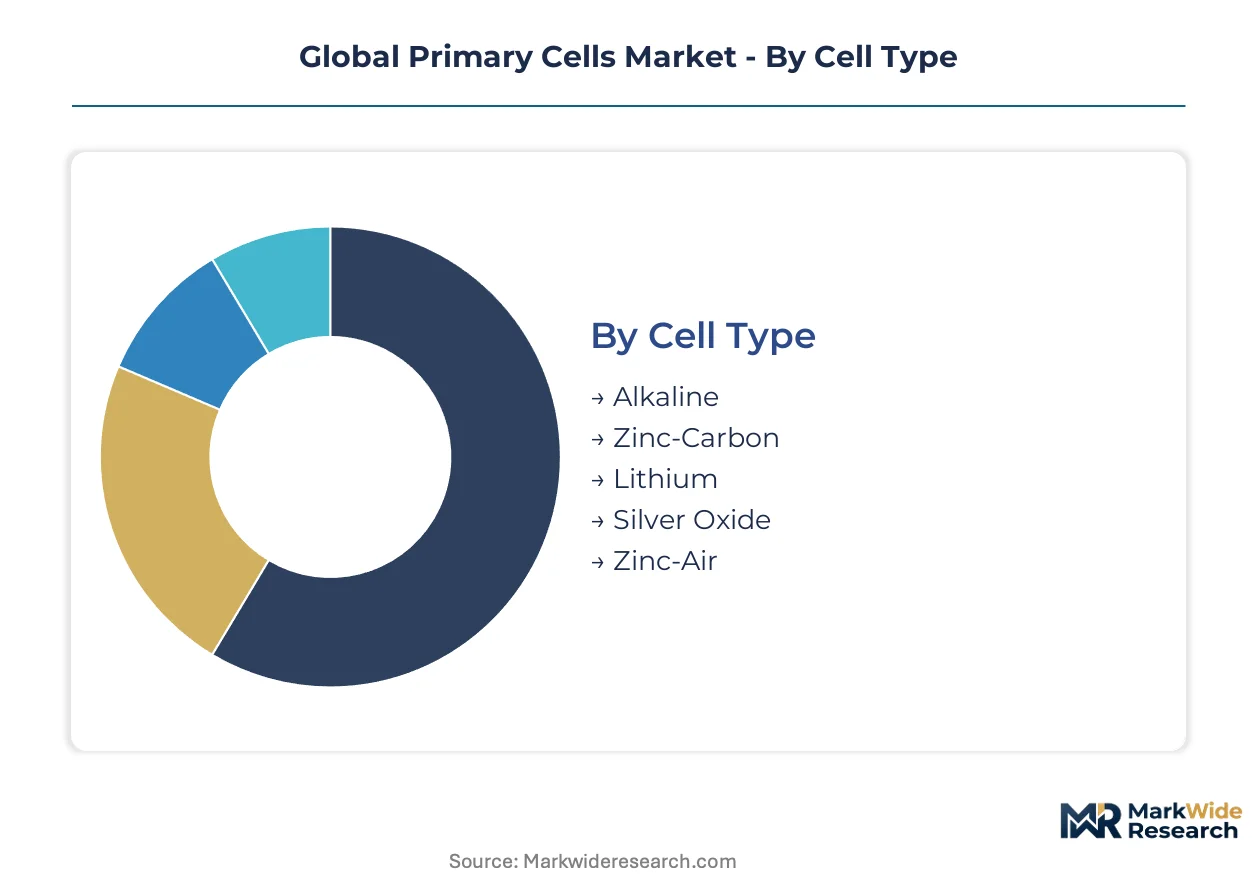
Cell type chemistry determines voltage stability and shelf life specifications that drive procurement decisions across medical device and consumer electronics verticals. Packaging format selection constrains volumetric energy density and integration feasibility for miniaturized applications. Application-specific duty cycles and discharge profiles further segment demand patterns across end-use categories.
Cell Type:
Buyers prioritize energy density and voltage stability when selecting chemistry for mission-critical deployments.
- Lithium:Delivers 3.0V nominal output with flat discharge curves and 10-year shelf stability. Medical device manufacturers in Switzerland and the United States specify lithium primary cells for implantable pacemakers and glucose monitors where battery replacement carries surgical risk.
- Zinc-Air:Achieves highest energy density among aqueous chemistries through oxygen cathode activation. Hearing aid producers in Germany and Japan are converting product lines to zinc-air button cells as device miniaturization demands smaller form factors with extended operational life.
- Alkaline:Balances cost performance for moderate-drain consumer applications with 1.5V output and widespread retail availability.
- Zinc-Carbon:Serves price-sensitive markets with lower energy density for intermittent-use devices in emerging economies.
- Silver Oxide:Provides stable 1.55V output with excellent capacity retention for precision timekeeping instruments.
Volume sits with alkaline chemistry; growth tilts toward zinc-air formulations.
Application:
End-use duty cycles determine cell sizing, chemistry selection, and replacement accessibility requirements.
- Smoke Detectors:Demand ultra-low self-discharge rates for decade-long unattended operation. Residential building codes in California and New York mandate sealed lithium units to eliminate battery replacement failures.
- Medical Devices:Require traceable manufacturing documentation and ISO 20399-compliant ancillary materials. Implantable neurostimulator programs in Massachusetts and Minnesota specify validated cell lots with complete supply chain records.
- Remote Controls:Represent high-volume replacement market with alkaline dominance and retail channel concentration.
- Watches:Favor silver oxide and lithium coin cells for compact dimensions and stable voltage under microamp loads.
- Calculators:Continue transitioning from alkaline to solar-assisted designs with reduced primary cell dependence.
- Flashlights:Shift toward rechargeable lithium-ion for high-drain applications, constraining primary cell penetration.
Procurement volume concentrates in remote controls; medical device applications command steepest expansion trajectory.
Packaging Format:
Physical dimensions and terminal configuration dictate integration feasibility across device architectures.
- Button Cells:Dominate hearing aid and watch applications with standardized diameters from 7.9mm to 11.6mm. Swiss manufacturers optimize automated insertion equipment for CR2032 and PR44 formats.
- Cylindrical:Serve industrial and military applications requiring ruggedized construction and high pulse-current capability.
- Coin Cells:Provide thin-profile solutions for credit-card-sized devices and RFID tags with sub-3mm height constraints.
- Prismatic:Enable custom footprint optimization for space-constrained medical implants with rectangular cross-sections.
- Pouch Cells:Deliver maximum volumetric efficiency for emerging flexible electronics and wearable patches.
Button cells capture current volume leadership; pouch formats are gaining share fastest in next-generation wearable segments.
End User:
Regulatory certification requirements and procurement scale differentiate customer segments.
- Consumer Electronics:Drives replacement market volume through retail and e-commerce channels with price-sensitive sourcing.
- Medical Devices:Mandates FDA cGMP and EMA ATMP compliance for clinical-grade cell integration. Boston and Basel clusters concentrate demand for validated hepatocyte-compatible power solutions in organ-on-chip platforms.
- Industrial Equipment:Requires extended temperature range performance for remote monitoring and pipeline instrumentation.
- Military Devices:Specifies MIL-STD qualification for battlefield electronics with emphasis on shelf life and reliability under extreme conditions.
Consumer electronics anchors present volume; medical device vertical shows strongest margin expansion potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Human liver tissue procurement networks in the United States anchor geographic demand concentration for hepatocyte isolation. Donor network density and regulatory infrastructure determine regional supply reliability.
United States
FDA cGMP compliance requirements and academic consortium purchasing power drive procurement consolidation. The agency's tightened cell-based assay guidance compresses supplier qualification timelines. Massachusetts and California clusters aggregate multi-year supply agreements for IND-enabling toxicology studies.
Germany
EMA ATMP regulation shapes clinical-grade manufacturing standards for European biopharma clients. Ethical sourcing constraints restrict qualified tissue collection site expansion. The Heidelberg and Munich metropolitan areas concentrate specialized hepatocyte isolation facilities serving contract development organizations.
Switzerland
Swissmedic oversight and GDPR-aligned donor metadata protocols govern cross-border tissue traceability. Basel anchors GMP-compliant purification expertise that outpaces technician training pipeline output. Lonza Group's specialized isolation facilities supply characterized immune cell lots for immuno-oncology developers.
Japan
PMDA conditional approval pathways for cell therapies accelerate clinical-grade hepatocyte demand. METI regenerative medicine framework supports Osaka and Tokyo cluster development. Domestic biopharma procurement teams secure donor-matched consistency for longitudinal CAR-T toxicity studies.
United Kingdom
MHRA post-Brexit alignment with EMA standards preserves ATMP regulatory continuity. London-Oxford-Cambridge corridor concentrates organ-on-chip platform developers integrating primary hepatocytes with endothelial co-cultures. Academic medical centers drive characterized donor lot premiums for microfluidic liver models.
Global Primary Cells Market Competitive Landscape
Strategic partnerships dominate the current landscape as suppliers secure captive donor networks and biopharma buyers consolidate procurement. The market structures around three tiers: diversified life science conglomerates with global cold-chain infrastructure, specialized cell biology firms with GMP-certified isolation capabilities, and regional tissue procurement services. Archetypes include integrated platform providers, customization-focused specialists, and scale-driven commodity suppliers. M&A activity and capacity expansion in donor network territories represent the dominant competitive vectors.
Within the integrated platform tier, Thermo Fisher Scientific and Lonza Group exemplify archetypes leveraging global logistics infrastructure and European isolation specialization respectively. PromoCell GmbH occupies a position representing GMP-compliant customization specialists serving immuno-oncology verticals with differentiated donor-characterization protocols. These three anchors illustrate how geographic footprint and regulatory compliance depth determine competitive positioning.
| Leading Market Players |
|---|
| Cell Biologics |
| STEMCELL Technologies |
| Thermo Fisher Scientific |
| American Type Culture Collection |
| AllCells |
| Merck KGaA |
| PromoCell GmbH |
| Axol Bioscience |
| Lonza Group |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up specialist suppliers are consolidating hepatocyte isolation networks across the United States and Europe, tightening pricing discipline while capturing donor network scarcity premiums through multi-year contract lock-ins with biopharma toxicology departments.
Pricing Analysis
Service bundling separates characterized donor lots with full metabolic genotype documentation from unbundled spot purchases lacking cold-chain traceability. Three-tier pricing structure across premium, standard, and economy levels reflects GMP certification grade and donor-matched batch consistency. Pricing pressure stems from immortalized HepG2 cell line substitution in routine cytotoxicity screening, compressing margins for non-specialized hepatocyte suppliers. Academic toxicology departments in California and Massachusetts exhibit highest price sensitivity, while CAR-T developers in Basel and Boston prioritize donor characterization over unit cost.
Supply Chain Analysis
Domestic-content mandates in Japan's regenerative medicine framework are reshaping sourcing patterns, compelling foreign suppliers to establish local isolation partnerships for PMDA-compliant clinical-grade hepatocyte access. Supply concentrates in the United States, Germany, and Switzerland where qualified donor networks and GMP-certified facilities anchor production. The chain draws from human liver tissue procurement, specialized cryopreservation media, and liquid nitrogen logistics infrastructure. Single-source vulnerability runs through limited qualified isolation technicians in Basel and Boston hubs. Distribution runs through direct-to-biopharma e-procurement platforms and specialized life science distributors serving CRO and academic consortium accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Primary Cells Market functions as a cost-of-compliance story where FDA's tightened cell-based assay guidance erects barrier-to-entry moats favoring suppliers with verified cold-chain documentation and ISO 20399-certified ancillary materials.
For Market Incumbents: Hedge against immortalized cell line substitution by deepening hepatocyte characterization capabilities and securing captive donor network expansion in Japan and the United Kingdom. Lock multi-year subscription contracts with Massachusetts and California academic consortia before procurement consolidation hardens. Prioritize GMP certification investment for clinical-grade immune cell manufacturing serving European ATMP-regulated developers. For New Entrants and Emerging Players: PMDA's conditional approval pathways in Japan open a window for clinical-grade hepatocyte supply partnerships with Osaka and Tokyo bioclusters lacking established vendor relationships. Target organ-on-chip platform developers in the London-Oxford-Cambridge corridor seeking characterized donor lots for microfluidic liver models. Lead with automated isolation workflow offerings that compress batch-to-batch variability for high-content screening applications. For Investors and Strategic Acquirers: Multi-year supply agreement announcements between hepatocyte suppliers and CAR-T developers are the leading indicator that procurement consolidation is accelerating toward preferred vendor structures. The analysis window favors platforms combining donor network ownership with GMP-compliant isolation infrastructure over pure-service tissue procurement plays. Watch for EU AI Act enforcement actions against digital phenotyping workflows as signals of compliance cost escalation that favors scaled incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Donor Network Expansion | Captive tissue procurement in Japan and the United Kingdom secures PMDA and MHRA-aligned supply continuity. |
| Automated Isolation Deployment | Robotic liquid handling platforms at US toxicology CROs reduce technician-to-technician variation for IND-enabling studies. |
| GMP Certification Investment | EMA ATMP-compliant manufacturing infrastructure opens clinical-grade addressable market for European contract development organizations. |
| Digital Phenotyping Compliance | Algorithmic audit trail capabilities satisfy EU AI Act provisions governing automated donor-cell performance correlations. |
| Direct E-Procurement Launch | Bypassing distributor markups compresses lead times for urgent hepatocyte toxicity studies in California and New Jersey. |
Research Methodology
Independent corroboration across isolation facility operators, biopharma toxicology directors, and regulatory affairs specialists underwrites the qualitative findings presented in this study. The analysis combines structured primary interviews with drug development executives, hepatocyte procurement managers at CROs, GMP facility auditors, and academic consortium purchasing leads with secondary validation from FDA guidance documents, EMA ATMP submissions, ClinicalTrials.gov cell therapy protocol filings, and ISO 20399 certification registries. Bottom-up donor network capacity estimates and top-down biopharma R&D spending allocation models triangulate market sizing.
Comparable-period anchoring to historical hepatocyte procurement volumes and CAR-T IND submission rates establishes the forecast baseline across the projection horizon. The analytical framework models segmentation dimensions including cell type chemistry, application vertical, packaging format, and end-user regulatory tier alongside geographic procurement cluster concentration. CAGRs derive from trend extrapolation of biopharma outsourcing intensity and clinical-grade cell therapy manufacturing requirements. Forecast inputs incorporate EMA ATMP regulatory expansion timelines and PMDA conditional approval pathway utilization rates.
The model assumes a particular technology adoption path; alternative pathways for organ-on-chip microfluidic integration would alter the outlook if endothelial co-culture standardization accelerates beyond current hepatocyte monoculture dominance. Forecasts reflect assumptions regarding donor network expansion feasibility, cryopreservation cost trajectories, and cross-border tissue traceability regulatory alignment. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
UAV Battery Pack Market
Batteries
Rear Rack Battery Market
Batteries
Middle-East Battery Market
Batteries
Li-Mno2 Button Battery Market
Batteries
East Africa Battery Market
Batteries
China Battery Market
Batteries
Asia-Pacific Battery Market
Batteries
Primary Battery Market
Batteries
Romania Rechargeable Battery Market
Batteries
Carbon Foam Battery Market
Batteries
Absorbent Glass Mat (AGM) Battery Market
Batteries
Cobalt-Free Battery Market
Batteries
Europe Battery Cell Market
Batteries
Nickel-Based Battery Charger Market
Batteries
Thin Film and Printed Battery Market
Batteries
Semi-Solid Flow Battery Market