
 Grid-Scale Lead-Acid Battery Market | 2026-2036
Grid-Scale Lead-Acid Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Grid-Scale Lead-Acid Battery Market Insights
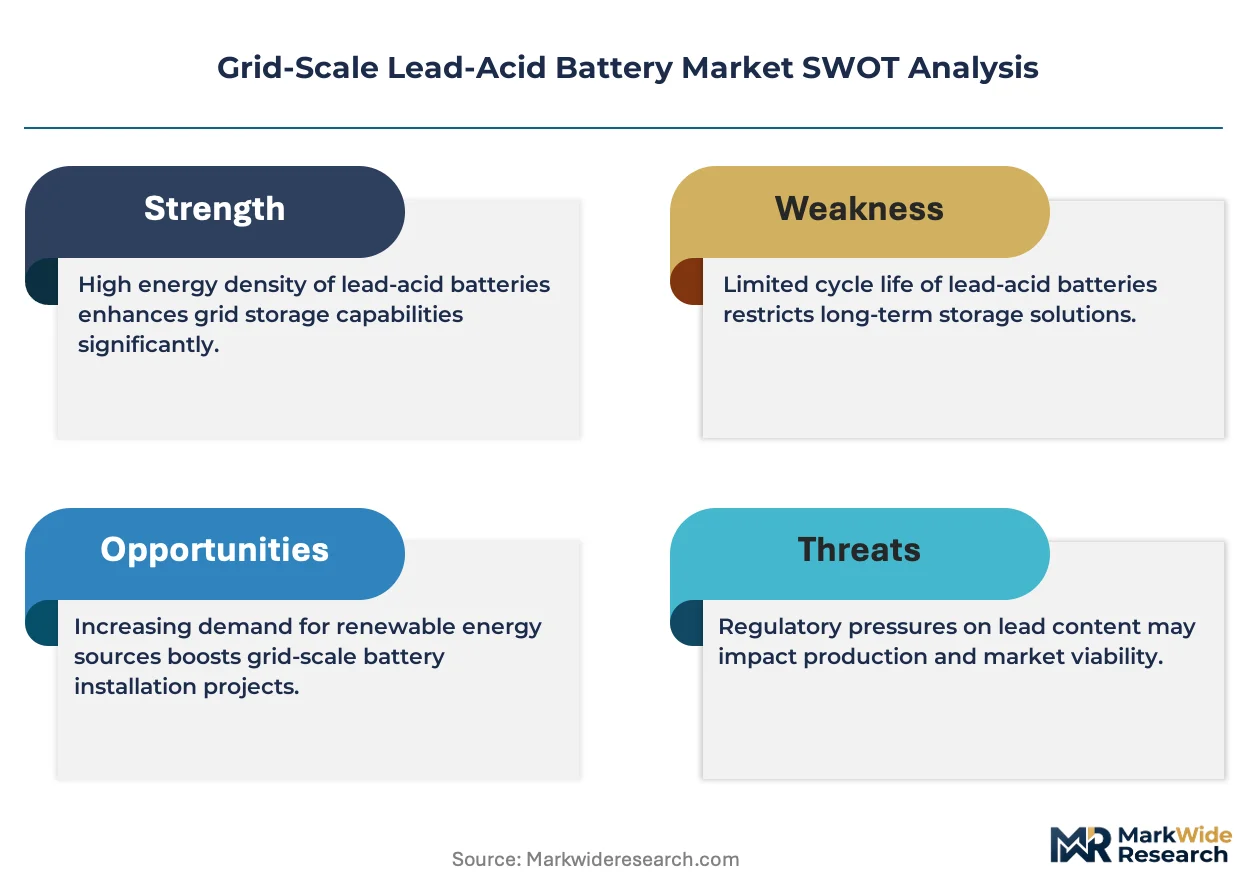
The gap between premium and commodity tiers is expanding in grid-scale lead-acid batteries. Clarios leverages advanced carbon-enhanced negative active material formulations to sustain higher cycle counts in demanding renewable integration deployments. GS Yuasa Corporation anchors its position through deep specialization in valve-regulated lead-acid architectures for Japanese utility specifications. EnerSys competes on manufacturing scale across flooded and absorbent glass mat product lines for North American independent system operators.
Grid-scale lead-acid batteries are electrochemical storage devices using lead dioxide positive plates, sponge lead negative plates, and sulfuric acid electrolyte, engineered for 1,200 to 3,000 deep discharge cycles at 20-hour rates to buffer megawatt-scale grid fluctuations. Absorbent glass mat designs dominate frequency regulation applications where minimal maintenance and low gas emissions prove critical. Flooded lead-acid variants retain cost leadership in bulk energy storage installations where space constraints remain secondary to capital expenditure limits. Deep cycle technology leads technology segmentation as utilities prioritize discharge depth over peak power density in daily cycling regimes.
CEA grid standards in India, EPA lead emissions protocols in the United States, and REACH substance restrictions in Europe collectively shape battery chemistry choices, manufacturing location decisions, and end-of-life recycling obligations. The EU Green Deal battery sustainability rules are forcing producers to document recycled lead content percentages and carbon intensity across supply chains. Stakeholders must monitor how carbon border adjustment mechanisms and evolving utility procurement scoring criteria reweight total cost of ownership against upfront capital metrics.
Market Dynamics
Carbon-enhanced negative active material formulations are compressing cycle-life differentials between lead-acid and lithium-ion alternatives for renewable buffering applications. This electrochemical advancement is restructuring procurement evaluation frameworks across utility-scale storage tenders.
Growth Catalysts
- CEA Mandate for Frequency Regulation:India's Central Electricity Authority requires grid operators to procure buffer capacity, creating dedicated procurement channels for deep-cycle lead-acid systems.
- Carbon Additive Formulations:Advanced negative plate doping extends cycle counts to 3,000 deep discharges, narrowing performance gaps with alternative chemistries in daily cycling regimes.
- Provincial Solar Buildouts:Chinese grid operators in Gansu and Qinghai provinces are installing megawatt-scale lead-acid buffers to manage photovoltaic intermittency.
Market Restraints
- Lead Price Volatility:Primary lead ingot costs fluctuate with London Metal Exchange pricing, compressing margin predictability for flooded battery manufacturers.
- Energy Density Ceiling:Theoretical limits of lead-acid electrochemistry cap gravimetric performance at 40 Wh/kg, constraining footprint-constrained installations.
- REACH Substance Restrictions:ECHA documentation requirements for recycled content percentages add compliance overhead for European supply chains.
Strategic Opportunities
- Retrofit of Aging Substations:North American rural electric cooperatives are replacing legacy nickel-cadmium banks with valve-regulated lead-acid systems for frequency response.
- EU Green Deal Battery Sustainability Rules:Mandated carbon intensity disclosures favor producers with captive recycling infrastructure and low-emission smelting.
- Hybrid Storage Architectures:Coupling lead-acid bulk storage with lithium-ion power density is automating dispatch optimization software for Japanese island grids.
Industry Challenges
- Electrochemical Engineering Talent Scarcity:Specialized expertise in carbon-enhanced negative active material formulation remains concentrated among retiring cohorts at established manufacturers.
- CEA Certification Timelines:Indian grid standards testing protocols extend product qualification cycles to 18-24 months, delaying revenue recognition for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grid-Scale Lead-Acid Battery Market |
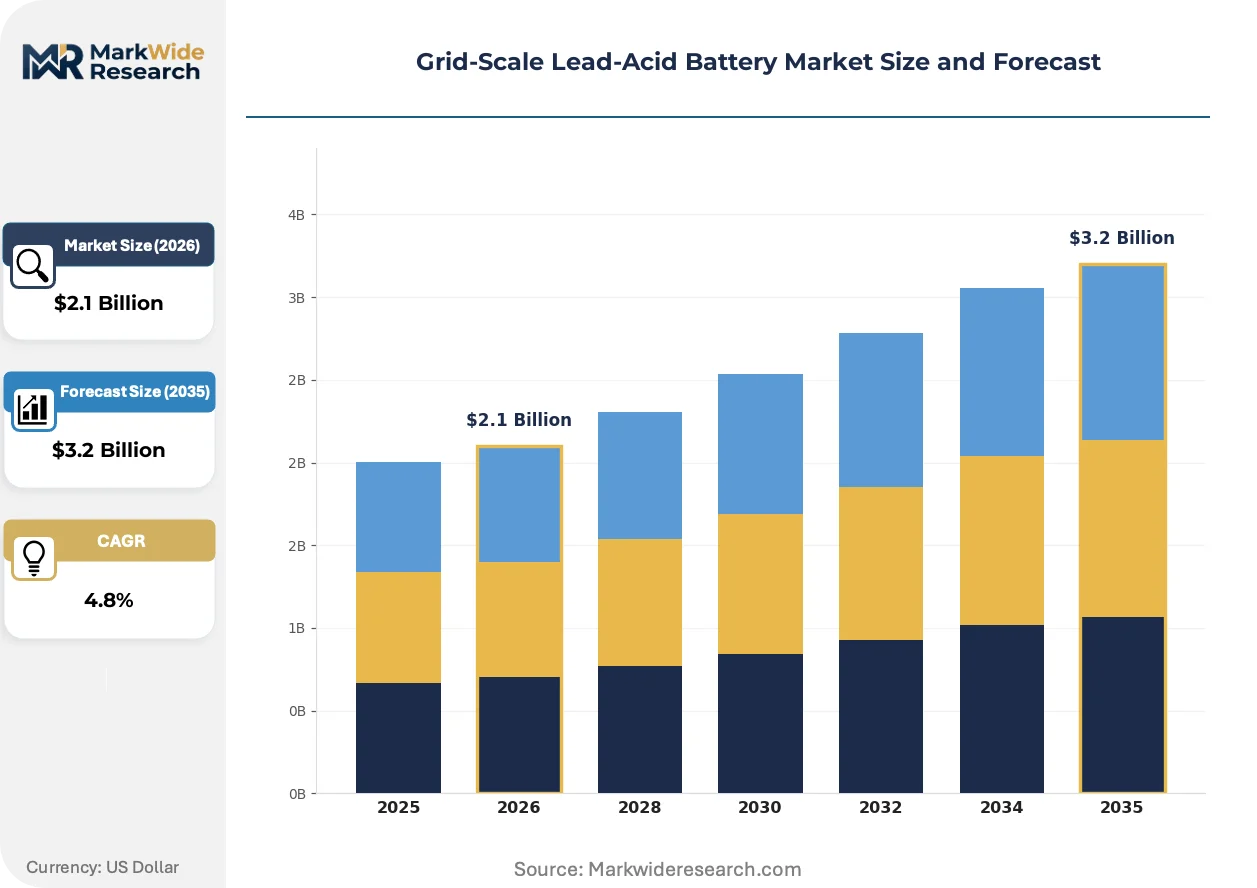
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.2 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flooded Lead-Acid, Absorbent Glass Mat, Gel Battery, Valve-Regulated Lead-Acid Application: Energy Storage, Renewable Integration, Frequency Regulation, Backup Power End User: Utilities, Commercial, Industrial, Renewable Energy Providers Technology: Deep Cycle, Hybrid, Smart Battery Systems, Traditional |
| Companies Covered | Clarios, GS Yuasa Corporation, EnerSys, Exide Industries Ltd., East Penn Manufacturing Co., C&D Technologies, Inc., Camel Group Co., Ltd., ATLASBX Co. Ltd., Johnson Controls, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grid-Scale Lead-Acid Battery Market Trends and Innovations
Intelligent battery management systems are penetrating grid-scale lead-acid installations, transforming passive storage assets into actively dispatchable network resources. This digital layer is compressing operational response times and enabling predictive maintenance protocols.
Carbon-enhanced negative active material technology is automating state-of-charge estimation accuracy in deep-cycle applications. Chinese and Indian utilities deploying these formulations report reduced sulfation-induced capacity fade. The technology is compressing total cost of ownership calculations against alternative chemistries in 4-6 hour discharge applications.
EPA lead emissions protocols are tightening stack monitoring requirements for domestic smelting operations. Secondary lead producers are retrofitting baghouse filtration systems to meet NAAQS ambient air standards. Flooded battery manufacturers sourcing recycled lead from compliant smelters command procurement preference from municipal utilities with sustainability scoring mandates.
Utility procurement evaluation frameworks are unbundling upfront capital metrics from lifecycle performance guarantees. North American independent system operators now weight cycle-life verification data above initial purchase price in tender scoring. This behavioral shift compresses market access for commodity-tier producers lacking validated carbon-enhanced formulations.
Grid-Scale Lead-Acid Battery Market Segmentation
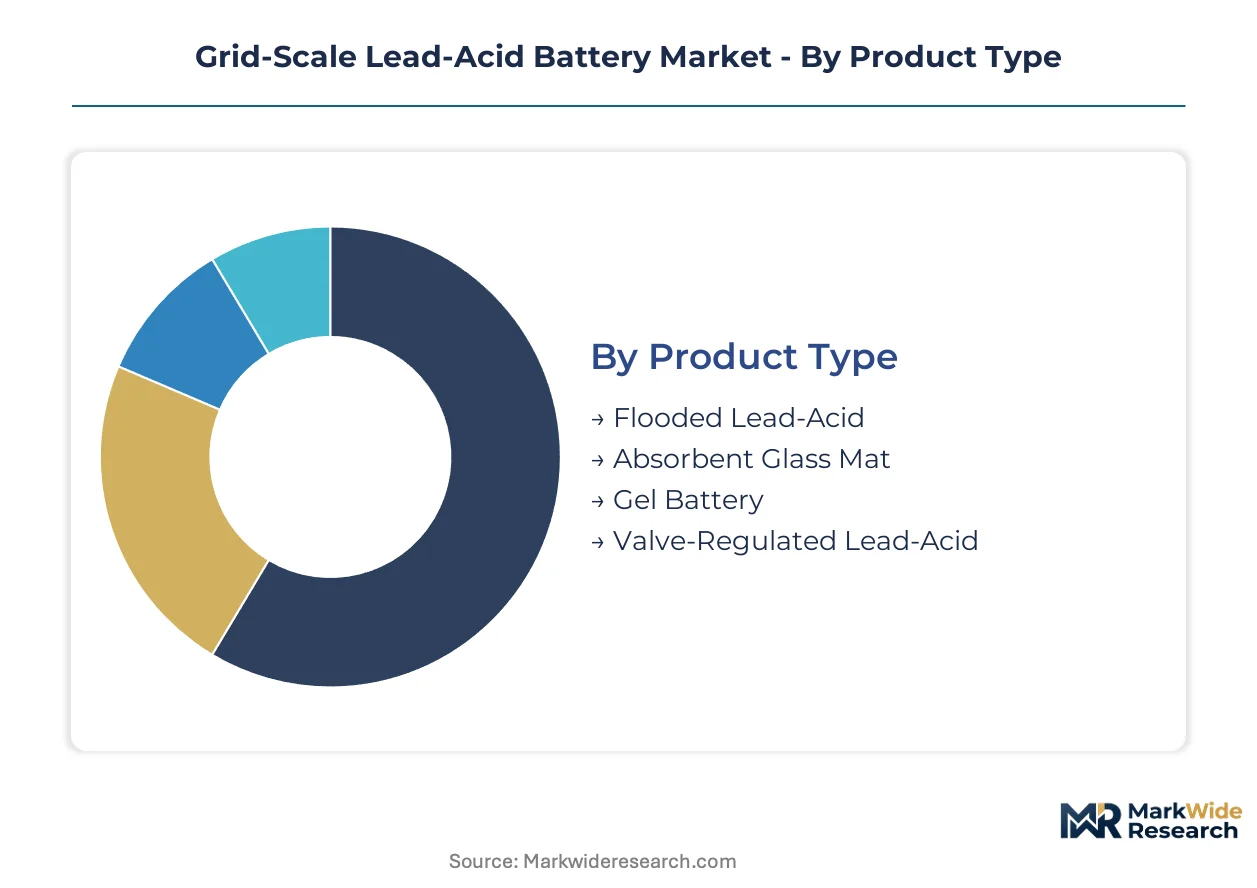
Segmentation in grid-scale lead-acid batteries reveals how procurement criteria diverge across utility specifications, cycling regimes, and capital constraints. Buyers weight total cost of ownership differently depending on discharge duration, maintenance access, and regulatory compliance obligations.
Product Type:
Capital expenditure thresholds and maintenance infrastructure availability drive chemistry selection across installation sites.
- Flooded Lead-Acid:Liquid electrolyte designs with vented gas management deliver the lowest upfront cost per kilowatt-hour for bulk energy storage. Chinese provincial grid operators in Gansu deploy these systems where space constraints remain secondary to capital limits and on-site maintenance crews are available.
- Absorbent Glass Mat:Electrolyte-saturated fiberglass separators enable sealed operation with minimal gas emissions, suiting indoor substations and frequency regulation duties. Indian utilities under CEA mandates favor AGM architectures for urban installations where ventilation infrastructure is limited.
- Gel Battery:Silica-thickened electrolyte resists stratification and thermal runaway in high-temperature environments.
- Valve-Regulated Lead-Acid:Pressure-relief valve designs recombine hydrogen and oxygen internally, eliminating watering requirements for remote renewable sites.
Volume sits with Flooded Lead-Acid; growth tilts toward Absorbent Glass Mat.
Application:
Duty cycle intensity and discharge duration requirements fragment demand across grid services.
- Energy Storage:Bulk arbitrage and peak shaving applications prioritize deep discharge capability over rapid response. North American rural electric cooperatives specify 4-6 hour discharge windows for time-shifted renewable delivery.
- Renewable Integration:Solar and wind buffering demands high cycle counts with partial state-of-charge tolerance. Carbon-enhanced negative active material formulations from Chinese manufacturers address photovoltaic intermittency in Qinghai province.
- Frequency Regulation:Sub-second response requirements favor low-internal-resistance designs with validated cycle-life data.
- Backup Power:Standby duty with infrequent cycling emphasizes float reliability and calendar life over deep-cycle endurance.
Procurement concentrates on Energy Storage; Renewable Integration expands most quickly.
End User:
Procurement scale and technical specification authority shape vendor engagement models.
- Utilities:Transmission and distribution operators with megawatt-scale tenders drive standardization through detailed technical specifications. Indian state distribution companies under CEA mandates issue multi-year framework agreements with lifecycle performance guarantees.
- Commercial:C&I facilities with behind-the-meter storage prioritize compact footprints and rapid installation.
- Industrial:Manufacturing campuses with captive renewable generation seek hybrid storage architectures.
- Renewable Energy Providers:Solar and wind developers specify storage co-located with generation assets.
Contract value aggregates with Utilities; project velocity favors Commercial.
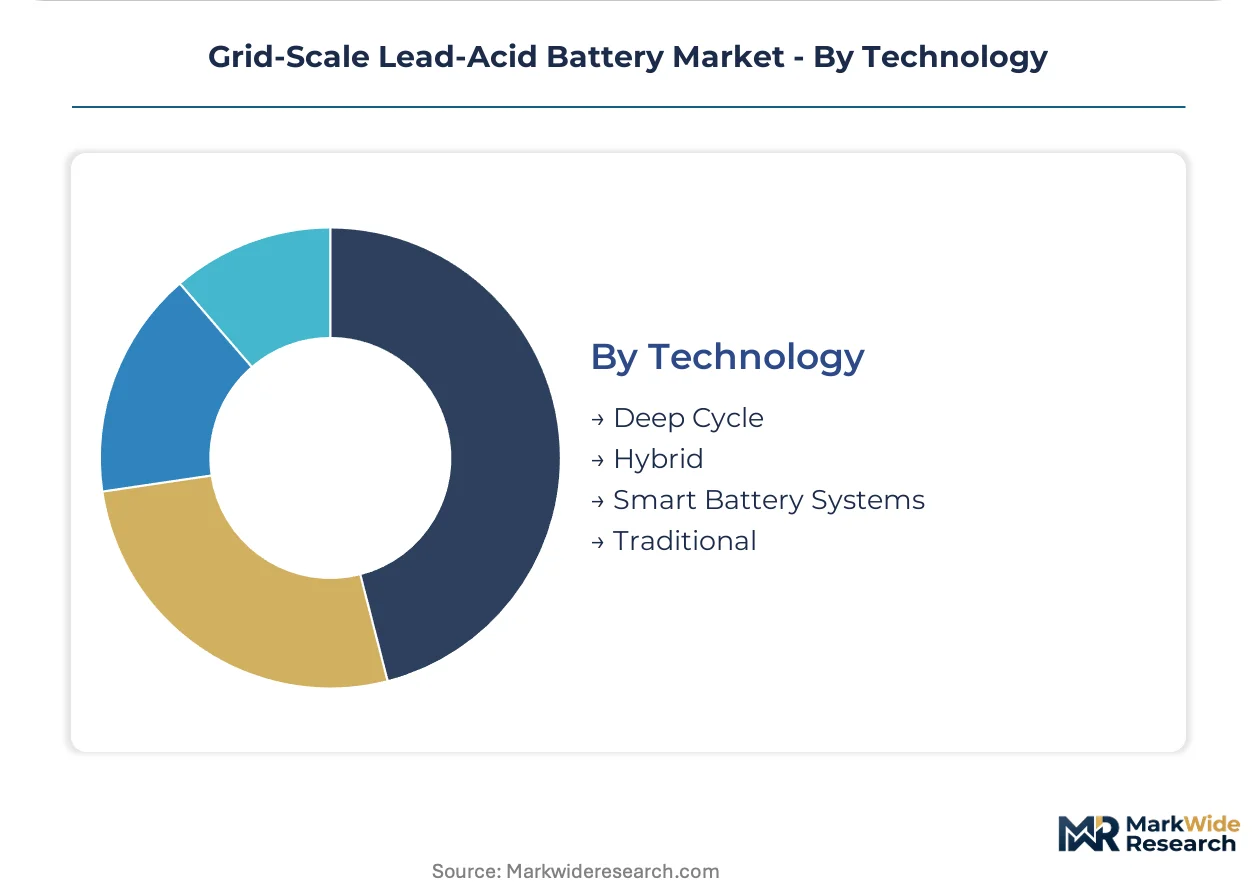
Technology:
Cycle-life validation and digital integration capabilities differentiate competitive positioning.
- Deep Cycle:Thick-plate construction with high-density active material sustains 1,200-3,000 deep discharges at 80% depth of discharge. Japanese island grids specify deep-cycle architectures for daily cycling regimes with 20-year service expectations.
- Hybrid:Coupled lead-acid bulk storage with lithium-ion power density optimizes dispatch economics through software-controlled charge allocation.
- Smart Battery Systems:Integrated battery management systems enable predictive maintenance and remote state-of-health monitoring.
- Traditional:Conventional flooded designs without carbon enhancement serve price-sensitive standby applications.
Deployment volume clusters with Deep Cycle; technology investment flows toward Smart Battery Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tianjin's Binhai New Area anchors grid-scale lead-acid manufacturing for Chinese provincial grid operators building buffer capacity against solar intermittency. Indian state distribution companies under CEA mandates drive procurement volumes through multi-year framework agreements with lifecycle performance guarantees.
China
Provincial grid operators in Gansu and Qinghai provinces deploy megawatt-scale flooded lead-acid systems to manage photovoltaic intermittency from desert solar installations. MIIT dual carbon goals pressure manufacturers to document carbon intensity across smelting and assembly operations. Tianjin and Shandong industrial clusters concentrate carbon-enhanced negative active material production for export markets.
India
State distribution companies under CEA mandates procure deep-cycle valve-regulated lead-acid systems for frequency regulation duties in urban substations. BIS certification requirements extend product qualification timelines to 18-24 months for new market entrants. Maharashtra and Gujarat industrial corridors host assembly operations serving western grid zones with high renewable penetration.
United States
Rural electric cooperatives replace aging nickel-cadmium banks with valve-regulated lead-acid systems for frequency response across independent system operator territories. EPA lead emissions protocols tighten stack monitoring requirements for domestic secondary smelters. Pennsylvania and Ohio manufacturing bases supply flooded variants to municipal utilities with sustainability scoring mandates.
Japan
Island grid operators specify deep-cycle architectures with 20-year service expectations for daily cycling regimes in remote renewable installations. METI technical standards emphasize cycle-life verification data above upfront capital metrics in utility tenders. Osaka-based industrial clusters specialize in absorbent glass mat formulations for minimal-maintenance substation deployments.
Germany
Transmission operators evaluate hybrid storage architectures combining lead-acid bulk capacity with lithium-ion response speed for grid balancing services. ECHA REACH substance restrictions mandate recycled lead content documentation across European supply chains. North Rhine-Westphalia recycling infrastructure supports closed-loop lead recovery for battery manufacturers serving Central European markets.
Grid-Scale Lead-Acid Battery Market Competitive Landscape
Premium-margin players sit above commodity-margin players across carbon-enhanced formulation capabilities and cycle-life validation data. The vendor base stratifies into three tiers: integrated manufacturers with captive smelting and recycling operations, specialized battery producers sourcing refined lead from secondary markets, and regional assemblers competing on upfront capital metrics. Strategic archetypes include technology licensors monetizing carbon-additive patents, scale-driven producers optimizing manufacturing throughput, and utility-focused specialists securing multi-year framework agreements. Dominant competitive moves encompass backward integration into secondary lead smelting and technology licensing partnerships for carbon-enhanced negative active material formulations.
Among established integrated manufacturers, Clarios exemplifies the technology-licensor archetype through advanced carbon-enhanced negative active material capabilities. GS Yuasa Corporation occupies a position within the utility-specialist tier, anchoring Japanese market access through deep-cycle product validation. EnerSys represents the scale-driven archetype, leveraging manufacturing breadth across flooded and absorbent glass mat architectures for North American independent system operators.
| Leading Market Players |
|---|
| Clarios |
| GS Yuasa Corporation |
| EnerSys |
| Exide Industries Ltd. |
| East Penn Manufacturing Co. |
| C&D Technologies, Inc. |
| Camel Group Co., Ltd. |
| ATLASBX Co. Ltd. |
| Johnson Controls |
| Others |
Pricing and Supply Chain Analysis
Secondary lead ingot costs from London Metal Exchange pricing cascade through three distinct pricing tiers for grid-scale lead-acid batteries. Chinese provincial grid operators in Gansu source flooded systems at commodity rates while Japanese island utilities absorb premium valuations for carbon-enhanced deep-cycle architectures with 20-year service guarantees.
Pricing Analysis
Cycle-life verification data anchors value-based pricing for carbon-enhanced negative active material formulations. Three-tier pricing structure across premium, standard, and economy levels separates validated 3,000-cycle systems from commodity flooded alternatives. Cost compression in standard tiers intensifies because Indian state distribution companies under CEA mandates weight upfront capital above lifecycle metrics. Rural electric cooperatives in North America exhibit highest price sensitivity; Japanese transmission operators demonstrate least.
Supply Chain Analysis
Lead feedstock supply rests on secondary smelting operations concentrated in China, India, and Germany. Battery-grade lead oxide, sulfuric acid electrolyte, and carbon additive precursors constitute critical input dependencies. Single-source vulnerability concentrates in Chinese carbon-enhanced negative active material production clusters. Distribution runs through utility procurement frameworks with multi-year framework agreements dominating megawatt-scale tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon-enhanced negative active material technology is displacing conventional flooded architectures in frequency regulation applications. This transition phase rewards producers with validated cycle-life data and captive recycling infrastructure.
For Market Incumbents: Deepen backward integration into secondary lead smelting to secure margin control against London Metal Exchange volatility. Expand carbon-enhanced formulation capacity in Tianjin and Shandong industrial clusters to defend position against lithium-ion substitution in 4-6 hour discharge applications. Prioritize CEA certification investment to compress 18-24 month qualification timelines for Indian utility tenders. For New Entrants and Emerging Players: Direct-to-utility digital procurement platforms offer the lowest-friction route into North American rural electric cooperative segments. Target retrofit of aging nickel-cadmium substations in independent system operator territories where established vendors lack localized service presence. Lead with valve-regulated lead-acid architectures emphasizing minimal maintenance for remote renewable sites. For Investors and Strategic Acquirers: CEA mandate expansion into additional Indian states is the leading indicator that procurement volumes will concentrate further under framework agreements. Five-to-ten year viability favors integrated manufacturers with captive recycling and carbon-enhanced formulation patents. Watch for BIS certification backlog clearance as signal of competitive entry window timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Secondary Smelting | Captive lead supply insulates margins from London Metal Exchange volatility for integrated manufacturers. |
| Carbon-Enhanced Formulation Licensing | Technology monetization extends revenue streams beyond manufacturing into patent royalties from regional assemblers. |
| CEA Certification Fast-Track Investment | Compressed qualification timelines unlock Indian state distribution company framework agreement participation. |
| Hybrid Storage Architecture Development | Software-coupled lead-acid and lithium-ion systems optimize dispatch economics for Japanese island grids. |
| EU Green Deal Compliance Documentation | Recycled content and carbon intensity disclosures secure procurement preference from sustainability-scoring municipal utilities. |
Research Methodology
Document review covered EIA storage deployment databases, CEA procurement circulars, and EPA emissions compliance filings, complemented by interviews with utility planning officers, battery system procurement managers, and secondary lead smelter operations directors. Secondary validation drew from MIIT dual carbon policy documents, REACH substance restriction databases, and independent system operator interconnection queues. Bottom-up installation forecasts triangulated against top-down utility capital expenditure projections across the analysis window.
Market sizing outputs reflect installed capacity and revenue modeling across product type, application, end user, and technology segmentation dimensions. CAGRs derived from regression analysis of historical procurement volumes and policy-mandated storage targets. Carbon additive formulation penetration rates and CEA mandate implementation timelines served as industry-specific forecast inputs throughout the projection horizon.
The model holds under stable lead price corridors and sustained CEA mandate enforcement; deviation in lithium-ion cost curves or REACH restriction tightening would shift competitive positioning. Forecasts reflect documented assumptions regarding cycle-life validation standards and recycling infrastructure capacity expansion. A small set of named triggers warrants ongoing watch: London Metal Exchange lead price volatility, BIS certification timeline compression, and carbon border adjustment mechanism implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Lithium Battery Testing System Market
Batteries
Low Temperature Battery Market
Batteries
Watch Battery Market
Batteries
Japan Battery Market
Batteries
Modular Battery Pack Market
Batteries
Flow Battery Market
Batteries
Solid-State Car Battery Market
Batteries
India Rechargeable Battery Market
Batteries
United Kingdom Rechargeable Battery Market
Batteries
Non-Rechargeable Battery Market
Batteries
North America Industrial Battery Market
Batteries
Middle East and Africa SLI Battery Market
Batteries
US Motive Lead Acid Battery Market
Batteries
High Voltage Battery Market
Batteries
Lithium Carbon Monofluoride Battery Market
Batteries
Nas Battery Market