
 Primary Battery Market | 2026-2036
Primary Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Primary Battery Market Analysis
UN 38.3 lithium battery transportation certification is collapsing the supplier base for international medical and aerospace shipments, eliminating smaller trading houses that lack testing infrastructure. Panasonic leverages in-house cathode production and Japanese manufacturing scale to sustain qualification continuity across aviation and defense channels. Energizer competes through retail shelf dominance and alkaline brand strength, while Varta specializes in European medical OEM contracts with German-engineered coin cell precision.
A primary battery is a non-rechargeable electrochemical cell designed for single-use discharge, typically employing zinc-manganese dioxide, lithium-thionyl chloride, or lithium-iron disulfide chemistries with nominal voltages ranging from 1.5V to 3.6V depending on system architecture. These cells power devices where charging infrastructure is unavailable, replacement must occur after years of dormancy, or electrical isolation from grid systems remains mandatory. Alkaline and lithium types command the largest volume positions, with lithium cells capturing premium margin pools in medical and military applications where shelf life exceeds ten years and temperature tolerance spans negative forty to positive sixty degrees Celsius. Zinc-carbon retains residual share in price-sensitive emerging retail segments, while coin cell form factors dominate hearing aid and wearable biosensor penetration.
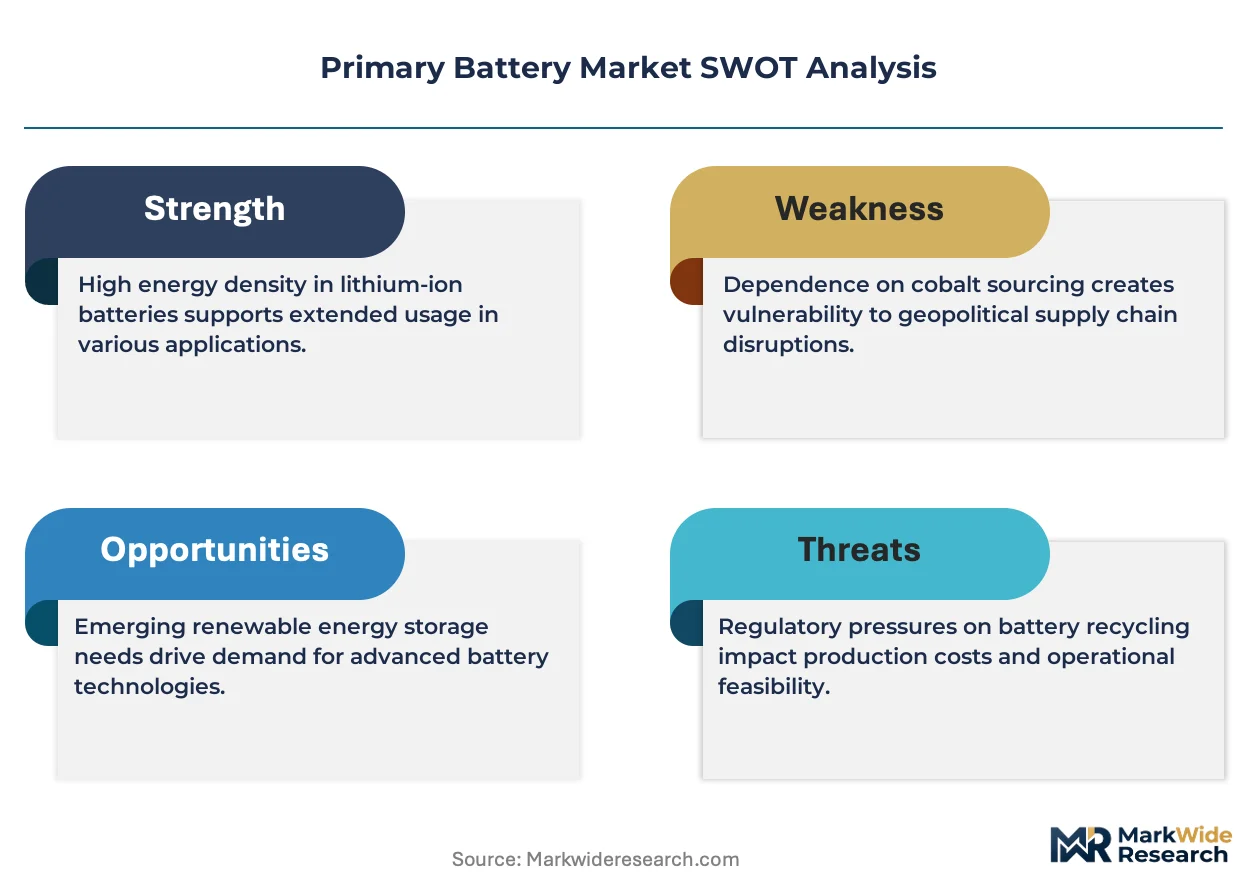
The US Department of Transportation enforces UN 38.3 and FAA packaging standards for lithium primary cell air transport, while the EU Battery Regulation mandates carbon footprint declarations and recycled content thresholds for cells placed on European markets. China's SAMR and GB standards govern domestic lithium battery safety testing, creating divergent qualification burdens for multinational suppliers. Stakeholders must monitor harmonization gaps between regional certification regimes and position manufacturing footprints to preempt compliance fragmentation.
Market Dynamics
UN 38.3 lithium battery transportation certification is compressing the international supplier base, eliminating trading houses lacking in-house testing infrastructure and forcing procurement consolidation around vertically integrated manufacturers with captive qualification capabilities.
Growth Catalysts
- EU Battery Regulation carbon footprint mandates:Tier-1 medical OEMs in Germany are accelerating primary cell procurement to lock in compliant supply chains before recycled content thresholds take effect.
- Lithium-thionyl chloride chemistry:Defense and aerospace contractors specify this chemistry for munitions guidance systems requiring 20-year shelf life and negative 55°C operational tolerance.
- Precision engineering clusters:Stuttgart and Munich anchor European demand for high-specification coin cells in implantable cardiac monitors and continuous glucose sensors.
Market Restraints
- Cobalt and lithium raw material volatility:Primary cell cathode production faces input cost swings tied to DRC mining output and Chilean brine processing capacity.
- East Asian cathode concentration:Japanese and South Korean suppliers control 70% of global lithium primary cell cathode precursor supply, creating single-source vulnerability for European packagers.
- Alkaline substitution ceiling:Zinc-manganese dioxide chemistry hits energy density limits below negative 20°C, freezing it out of Arctic oilfield sensor and aerospace applications.
Strategic Opportunities
- Indian medical device manufacturing:CDSCO regulatory harmonization with EU MDR is opening import substitution opportunities for German-engineered coin cells in domestic hearing aid production.
- Printed battery form factors:Convergence of roll-to-roll electrode manufacturing with flexible polymer substrates enables skin-patch biosensors and disposable environmental monitors.
- US Inflation Reduction Act domestic content bonuses:Defense procurement now weights US-assembled primary cells more heavily in military battery tenders, reshoring incentives for packagers with Arizona or Texas facilities.
Industry Challenges
- UN 38.3 certification timeline compression:Aviation and maritime logistics providers now demand 90-day test completion windows that smaller trading houses cannot meet, forcing exit from international medical shipments.
- Electrochemical engineering talent scarcity:Lithium primary cell formulation expertise concentrates in aging Japanese and German technical workforces with limited university pipeline replenishment.
- REACH SVHC disclosure complexity:European medical OEMs face cascading supplier documentation requirements for thionyl chloride electrolyte constituents, extending qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Primary Battery Market |
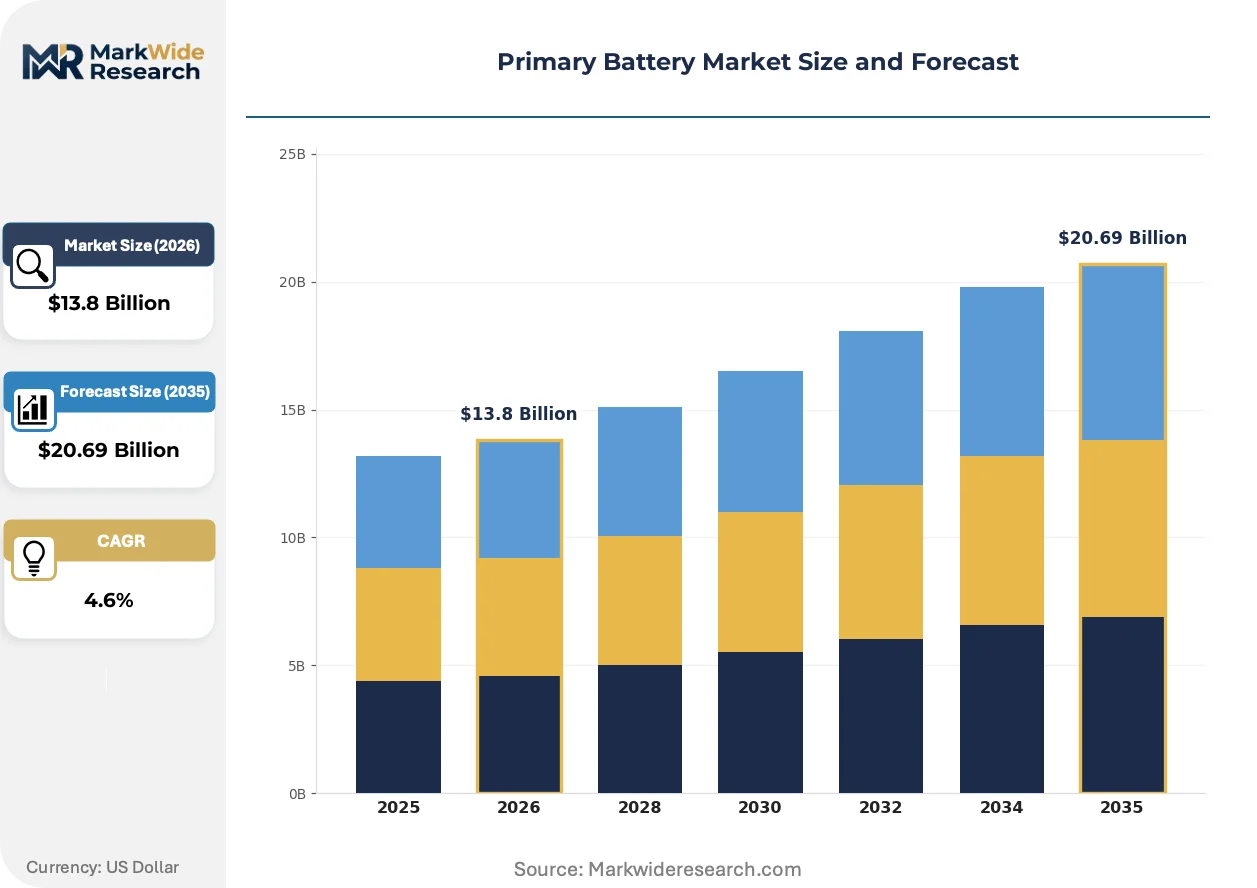
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $20.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Alkaline, Lithium, Zinc-Carbon, NiMH Application: Consumer Electronics, Automotive, Medical Devices, Industrial Equipment End User: Retail, OEMs, Government, Healthcare Form Factor: D Battery, AA Battery, AAA Battery, Coin Cell |
| Companies Covered | Panasonic, Varta, Duracell, Maxell, Rayovac, Energizer, Sony, Fujitsu, GP Batteries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Primary Battery Market Emerging Trajectories
Solid-state electrolyte architectures and printed manufacturing methods are redefining form factor constraints, while regulatory carbon accounting forces material provenance transparency through the entire cell value chain.
Lithium-iron disulfide chemistry delivers 1.5V nominal output with superior low-temperature performance versus alkaline alternatives, attracting cold-chain logistics sensor manufacturers and alpine rescue beacon designers. Military procurement offices in the US and Norway specify this chemistry for Arctic deployment kits. The technology is miniaturizing power sources for disposable asset-tracking tags previously requiring bulkier alkaline packs.
REACH SVHC candidate list expansion now captures thionyl chloride degradation products, compelling German medical OEMs to audit Taiwanese electrolyte suppliers for substitution documentation. ECHA enforcement is tightening post-market surveillance obligations for coin cells in implantable devices. Cardiac pacemaker manufacturers are responding by dual-sourcing electrolyte from Swiss and Japanese suppliers with pre-validated disclosure packages.
Hospital procurement departments are consolidating primary cell purchasing through group purchasing organizations, displacing individual department spot-buying for diagnostic equipment batteries. This concentration favors suppliers offering decade-long shelf-life guarantees with lot-traceable manufacturing records. The shift is most visible in US academic medical centers and German university hospital networks standardizing on single-source agreements for CR2032 and CR2450 formats.
Primary Battery Market Segmentation
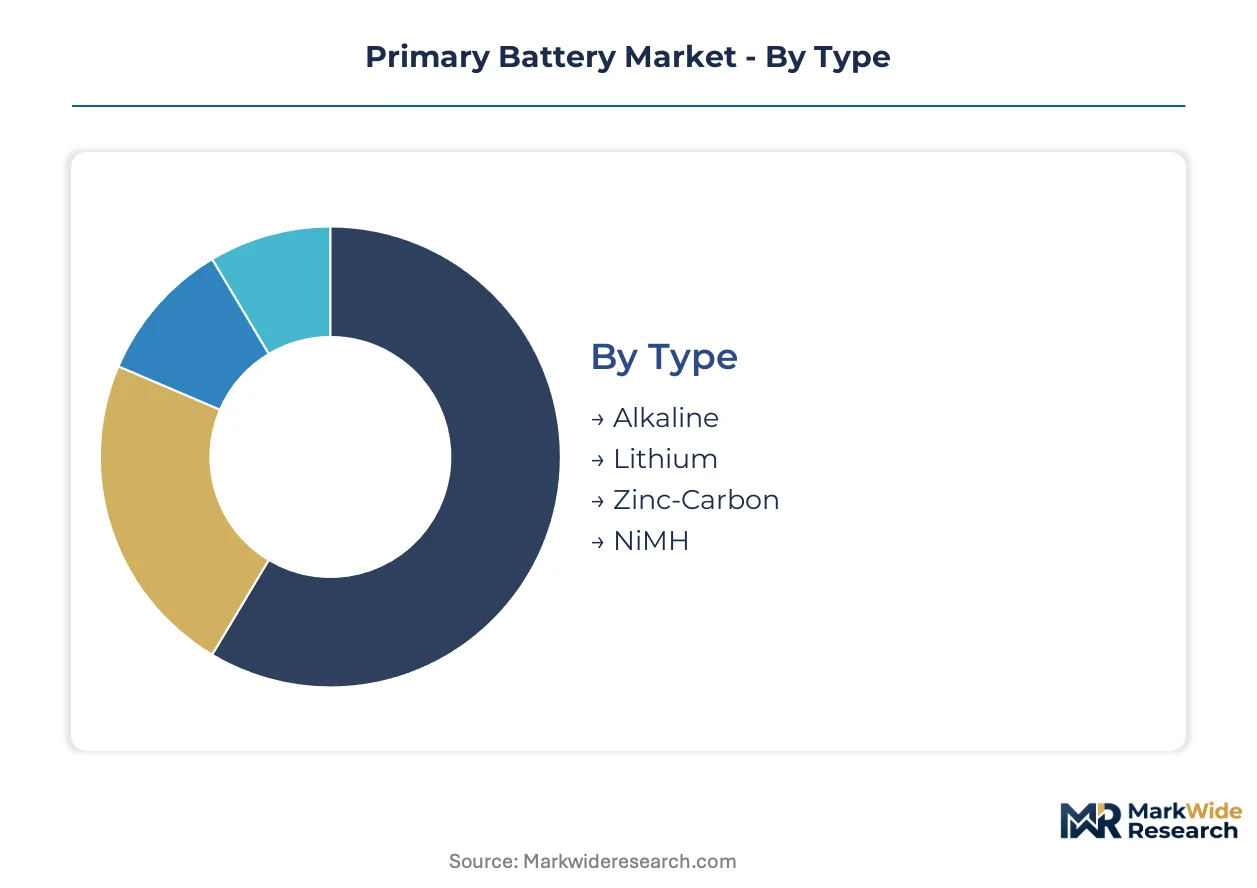
Primary battery segmentation reveals divergent margin structures across chemistry types and form factors. Medical and defense applications command premium pricing through qualification-intensive supply chains, while consumer retail operates on volume-driven alkaline economics.
Type:
Premium margin pools concentrate in lithium chemistry segments where defense and medical OEMs pay for 20-year shelf life and extreme temperature tolerance.
- Alkaline:Zinc-manganese dioxide chemistry delivers 1.5V nominal output with manganese dioxide cathode and zinc anode construction. Mass-market retail in Germany and the US absorbs volume, though energy density limitations below negative 20°C exclude Arctic and aerospace applications.
- Lithium:Lithium-thionyl chloride and lithium-iron disulfide variants dominate implantable cardiac monitors and munitions guidance systems. Stuttgart precision engineering clusters specify these cells for continuous glucose sensors requiring negative 55°C operational tolerance.
- Zinc-Carbon:Leclanché cell architecture retains residual share in price-sensitive emerging market retail segments with lower energy density and shorter shelf life.
- NiMH:Nickel-metal hydride chemistry occupies niche rechargeable-adjacent positioning in hybrid primary-secondary applications, though true primary battery definitions exclude this from core market scope.
The dominant share belongs to Alkaline, while Lithium is closing the gap fastest.
Application:
Volume concentration sits in consumer-facing segments, yet profitability skews toward regulated end-uses with multi-year qualification barriers.
- Consumer Electronics:Remote controls, wireless peripherals, and portable entertainment devices drive AA and AAA format consumption through retail and e-commerce channels. German and US mass-market distribution favors alkaline economics, though premium lithium variants penetrate high-drain gaming peripherals.
- Medical Devices:Implantable cardiac monitors, hearing aids, and continuous glucose sensors demand coin cell precision with decade-long shelf-life guarantees. EU MDR and FDA device regulations enforce lot-traceable manufacturing records that eliminate unqualified suppliers.
- Automotive:Tire pressure monitoring systems, key fobs, and emergency beacon backup power represent distributed low-volume demand with moderate qualification requirements.
- Industrial Equipment:Oilfield sensors, utility metering, and environmental monitors specify lithium-thionyl chloride for negative 40°C to positive 60°C temperature spans in remote deployment scenarios.
Consumer Electronics holds the volume base, with Medical Devices expanding most quickly through implantable device proliferation.
End User:
Procurement consolidation patterns separate fragmented retail spot-buying from centralized OEM and government tender processes.
- Retail:Supermarket, electronics specialty, and e-commerce channels distribute alkaline and lithium primary cells to household consumers through brand-driven purchasing decisions.
- OEMs:Medical device manufacturers in Germany and automotive tier suppliers negotiate multi-year supply agreements with shelf-life guarantees and audit rights over manufacturing facilities.
- Government:Defense procurement offices in the US and Norway specify lithium-iron disulfide for Arctic deployment kits with 20-year dormancy requirements.
- Healthcare:Hospital group purchasing organizations consolidate diagnostic equipment battery buying, displacing individual department spot purchasing with single-source agreements for CR2032 and CR2450 formats.
Retail maintains the broadest reach, while Healthcare procurement consolidation is gaining share fastest.
Form Factor:
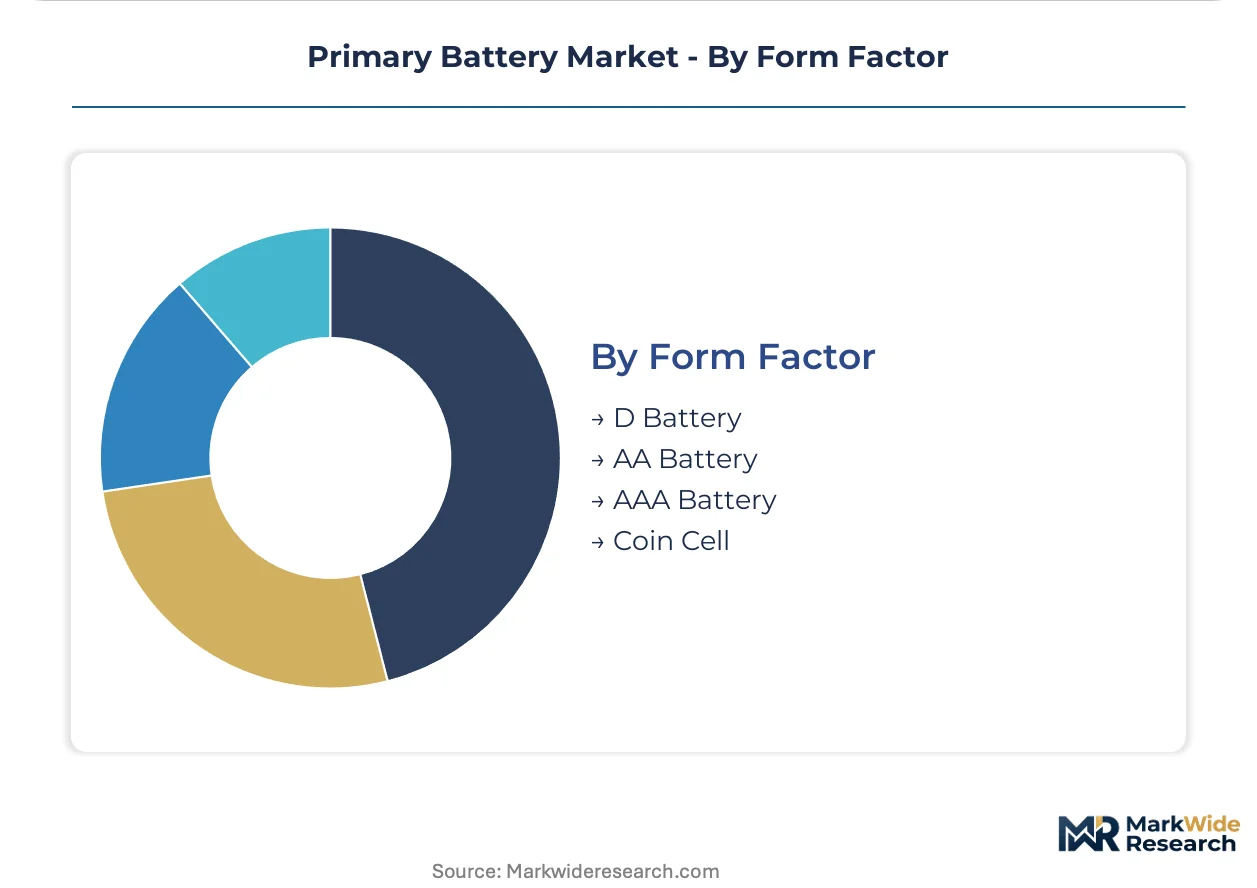
Standard cylindrical formats dominate unit volume, yet coin cell miniaturization captures value through medical device integration density.
- D Battery:Large cylindrical format powering high-drain flashlights, portable radios, and industrial equipment with extended runtime requirements.
- AA Battery:Most ubiquitous cylindrical format across consumer electronics, remote controls, and wireless peripherals with balanced energy density and cost economics.
- AAA Battery:Miniaturized cylindrical variant for slim-profile remote controls, wireless mice, and compact electronic devices with moderate drain characteristics.
- Coin Cell:Flat disc architecture enables implantable cardiac monitors, hearing aids, and wearable biosensors with sub-millimeter height constraints. Stuttgart and Munich precision engineering clusters drive CR2032 and CR2450 specification for continuous glucose sensors.
AA Battery leads in unit shipments, while Coin Cell is climbing the fastest through medical miniaturization trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German medical OEMs and US defense contractors anchor procurement concentration for high-specification primary cells, while East Asian manufacturing clusters supply cathode precursors and precision-engineered coin cell formats.
United States
Defense procurement offices specify lithium-iron disulfide chemistry for Arctic deployment kits requiring 20-year shelf life. The IRA domestic content bonuses now weight US-assembled primary cells more heavily in military tenders. Arizona and Texas host reshoring packagers capturing defense contract flow-downs.
Germany
Stuttgart and Munich precision engineering clusters drive CR2032 and CR2450 consumption for continuous glucose sensors and implantable cardiac monitors. EU Battery Regulation carbon footprint mandates are accelerating OEM procurement to lock in compliant supply chains. REACH SVHC disclosure requirements for thionyl chloride electrolytes extend qualification cycles for Taiwanese suppliers.
Japan
METI-supported manufacturing scale sustains captive cathode production and UN 38.3 qualification continuity across aviation channels. Aging technical workforces concentrate lithium primary cell formulation expertise with limited university pipeline replenishment. Osaka and Nagoya industrial zones maintain electrolyte and precision cell assembly operations.
China
SAMR and GB standards govern domestic lithium battery safety testing, creating divergent qualification burdens for multinational suppliers. GB standards compliance separates export-oriented packagers from domestic-market producers. Shenzhen and Dongguan electronics manufacturing clusters absorb alkaline volume for consumer electronics assembly.
India
CDSCO regulatory harmonization with EU MDR is opening import substitution opportunities for German-engineered coin cells in domestic hearing aid production. Maharashtra and Karnataka medical device manufacturing zones are attracting precision cell distributors. Central government PLI scheme incentives for electronics manufacturing indirectly support battery pack assembly localization.
Primary Battery Market Vendor Landscape
Player mix skews toward vertically integrated manufacturers with captive testing infrastructure and trading houses facing UN 38.3 certification compression. Tier-1 suppliers with in-house cathode production and multi-regional qualification capabilities are consolidating procurement relationships around medical and defense OEMs. Strategic moves center on backward integration into cathode precursor supply and geographic footprint expansion to preempt regulatory fragmentation.
Among Japanese and German integrated manufacturers, Panasonic and Varta exemplify archetypes sustaining qualification continuity across aviation and medical channels. Energizer occupies a position within retail-centric alkaline distribution, while Duracell anchors brand-driven consumer electronics shelf presence. These three names represent the concentration of premium-tier lithium specification and mass-market alkaline volume respectively.
| Leading Market Players |
|---|
| Panasonic |
| Varta |
| Duracell |
| Maxell |
| Rayovac |
| Energizer |
| Sony |
| Fujitsu |
| GP Batteries |
| Others |
Supply Flow & Price Mechanics
UN 38.3 lithium battery transportation certification gates both supplier qualification continuity and price differentiation across medical and defense procurement channels. Medical OEMs in Germany pay premiums for lot-traceable manufacturing records that trading houses cannot provide, while alkaline volume contracts compress margins through spot-buying consolidation.
Pricing Analysis
Cost-plus contracts with lithium carbonate indexation dominate lithium primary cell procurement between German medical OEMs and Japanese suppliers. Price differentiation separates UN 38.3-qualified manufacturers from unqualified trading houses, with certification tier and cathode chemistry grade as primary levers. Pricing pressure stems from cobalt and lithium raw material volatility tied to DRC mining output and Chilean brine processing capacity. Retail alkaline buyers exhibit highest price sensitivity, while defense contractors show lowest sensitivity due to 20-year shelf-life mandates.
Supply Chain Analysis
Just-in-time inventory strategies dominate consumer alkaline distribution, whereas medical and defense buyers maintain strategic stockpiles against qualification timeline compression. Cathode precursor supply concentrates in Japan and South Korea, with electrolyte formulation expertise anchored in Osaka and Nagoya industrial zones. Raw material dependencies center on lithium brine from Chile, cobalt concentrates from the DRC, and manganese dioxide from Gabon. Single-source vulnerability in East Asian cathode production creates structural risk for European packagers. Distribution runs through hospital group purchasing organizations for medical coin cells and mass-market retail channels for alkaline formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Primary battery procurement is consolidating around platform-economics dynamics where UN 38.3 qualification infrastructure functions as the interoperability layer locking in OEM relationships.
For Market Incumbents: Fortify captive cathode production and multi-regional testing infrastructure against UN 38.3 timeline compression eliminating smaller trading houses. Expand Arizona or Texas assembly footprints to capture US Inflation Reduction Act domestic content bonuses in defense tenders. Deepen backward integration into manganese dioxide and lithium carbonate supply to offset raw material volatility. For New Entrants and Emerging Players: Lead with printed battery form factors targeting Indian hearing aid manufacturing zones where CDSCO regulatory harmonization with EU MDR enables import substitution. Penetrate Maharashtra and Karnataka medical device clusters through German-engineered coin cell distribution partnerships. Position roll-to-roll electrode manufacturing capabilities for skin-patch biosensor OEMs seeking flexible polymer substrate integration. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across lithium-thionyl chloride qualification infrastructure as UN 38.3 testing timelines compress to 90-day windows. Long-term viability favors targets with captive electrolyte formulation expertise and pre-validated REACH SVHC disclosure packages. Watch for ECHA enforcement tightening on thionyl chloride degradation products as inflection signal for electrolyte supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Precursors | Captive manganese dioxide supply insulates Panasonic and Varta against DRC cobalt volatility. |
| Multi-Regional UN 38.3 Testing Infrastructure | Dual certification in Japan and Germany sustains aviation channel qualification continuity for medical shipments. |
| Printed Battery Manufacturing Scale-Up | Roll-to-roll electrode convergence enables disposable environmental monitor penetration for alpine rescue beacon designers. |
| REACH SVHC Pre-Validation Investment | Swiss and Japanese electrolyte disclosure packages accelerate German cardiac pacemaker OEM qualification cycles. |
| US Defense Procurement Localization | Arizona and Texas assembly footprints capture IRA-weighted military tender flow-downs from prime contractors. |
Methodological Framework
Desk research of customs trade data, SEC filings from battery manufacturers, EU Battery Regulation implementation documents, and FAA certification records preceded structured interviews with biomedical engineers at German medical OEMs, procurement managers at US defense contractors, cathode production directors at Japanese suppliers, and hospital GPO contracts managers. Primary fieldwork with these stakeholders combined with secondary validation from ECHA enforcement notices and METI industrial statistics. Bottom-up cell shipment modeling and top-down market sizing triangulated volume estimates across chemistry types and form factors.
Variance decomposition across the projection horizon isolates chemistry type, application end-use, form factor miniaturization trajectory, and regional regulatory cluster as primary segmentation dimensions. CAGRs derive from segment-level shipment growth rates applied to average selling price evolution by qualification tier. Industry-specific forecast inputs include lithium-thionyl chloride shelf-life degradation curves and REACH SVHC candidate list expansion timelines affecting electrolyte substitution patterns.
The analysis sits within stated boundaries; outcomes outside sustained EU Battery Regulation enforcement or UN 38.3 harmonization across aviation jurisdictions would require recalibration. Forecasts reflect assumptions about cathode precursor supply continuity and medical device OEM procurement consolidation trajectories. Revision becomes warranted when East Asian cathode concentration crosses critical dependency thresholds or when printed battery manufacturing yields inflect beyond current pilot-scale constraints.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Battery Simulator Market
Batteries
West Africa Battery Market
Batteries
East Africa Battery Market
Batteries
Battery-Powered Riveter Market
Batteries
Thin Film and Printed Battery Market
Batteries
Advanced Batteries Market
Batteries
Latin America Automotive Lead-Acid Battery Market
Batteries
Forklift Battery Charger Market
Batteries
South America Consumer Battery Market
Batteries
Carbon Foam Battery Market
Batteries
Secondary Battery Market
Batteries
Military Battery Market
Batteries
GCC Rechargeable Battery Market
Batteries
Disposable Batteries Market
Batteries
Alkaline Battery Market
Batteries
North Europe Battery Market