
 Chaga Mushroom Extract Market | 2026-2036
Chaga Mushroom Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Chaga Mushroom Extract Market Analytics
Premium-grade dual-extract specifications is reorganizing competitive dynamics in chaga processing. Baikal Herbs Ltd. leverages wild-harvested Siberian sourcing to anchor its position in high-potency raw material supply. Fungi Perfecti LLC sustains mycological credibility through Paul Stamets' research legacy and educational content. Four Sigmatic dominates ready-to-drink functional beverage placement in North American specialty retail channels.
Chaga mushroom extract comprises bioactive compounds including betulinic acid, polysaccharides, and melanin concentrated from Inonotus obliquus fruiting bodies through hot water and alcohol extraction protocols, primarily serving immune modulation and antioxidant applications in nutraceutical formulations. Powder formats lead production volume due to blending flexibility in supplement manufacturing, while liquid extracts capture premium positioning in direct-to-consumer wellness positioning. Pharmaceutical applications represent the fastest-growing demand cluster as researchers investigate chaga's adjuvant therapeutic potential.
FDA Current Good Manufacturing Practice regulations for dietary supplements enforce identity testing and contamination controls that shape extraction facility investments. USDA Organic certification and EFSA novel food assessments create divergent compliance pathways for European versus North American market entry. Stakeholders must monitor evolving adaptogen classification debates in major jurisdictions to anticipate ingredient list permissibility shifts.
Market Dynamics
Dual-extraction processing protocols are splitting the chaga supply base into premium wild-harvested Siberian suppliers and lower-cost cultivated alternatives, forcing buyers to choose between potency credentials and margin protection.
Growth Catalysts
- Immune-support ingredient demand:Post-pandemic consumer behavior prioritizes adaptogenic supplements, pulling chaga into mainstream dietary supplement formulations.
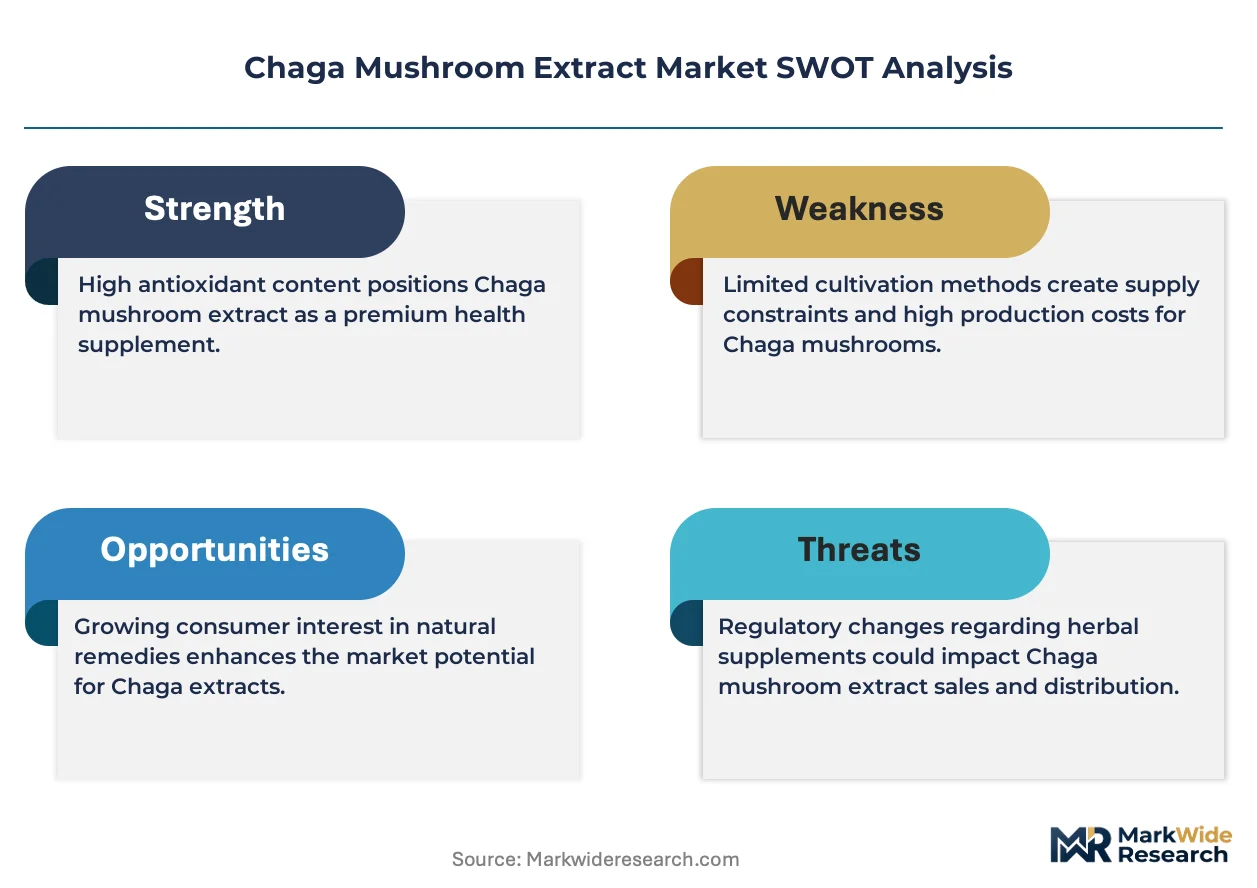
- FDA dietary supplement regulations:Current Good Manufacturing Practice enforcement creates compliance moats that favor established extraction facilities with identity testing capabilities.
- Hot water and alcohol extraction protocols:Standardized dual-extract specifications enable pharmaceutical-grade material qualification, opening adjuvant therapeutic research pipelines.
Market Restraints
- Wild harvest concentration in Siberia:Russian Far East supply zones face geopolitical friction and climate variability that destabilize raw material flows.
- Betulinic acid content variability:Natural fruiting body chemistry fluctuates by harvest location and season, complicating standardized dosing claims.
- Cultivated chaga substitution:Lab-grown Inonotus obliquus mycelium on grain substrates delivers inferior bioactive profiles but captures price-sensitive supplement tiers.
Strategic Opportunities
- Pharmaceutical adjuvant applications:Oncology and immunology researchers are investigating chaga polysaccharides for combination therapy protocols.
- USDA Organic certification pathways:Wild-harvested organic positioning commands 40-60% wholesale premiums over conventional material in North American wellness retail.
- Direct-to-consumer liquid extract channels:Subscription wellness platforms bypass traditional supplement distribution markups, capturing full retail margin.
Industry Challenges
- Mycological identification expertise:Extraction facilities struggle to hire qualified taxonomists capable of verifying Inonotus obliquus authenticity against adulterants.
- EFSA novel food assessment timelines:European market entry requires 18-36 month safety evaluation periods that freeze capital deployment.
- Extraction equipment capex requirements:GMP-compliant dual-extract lines demand seven-figure investments that exclude smaller wild-harvest cooperatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chaga Mushroom Extract Market |
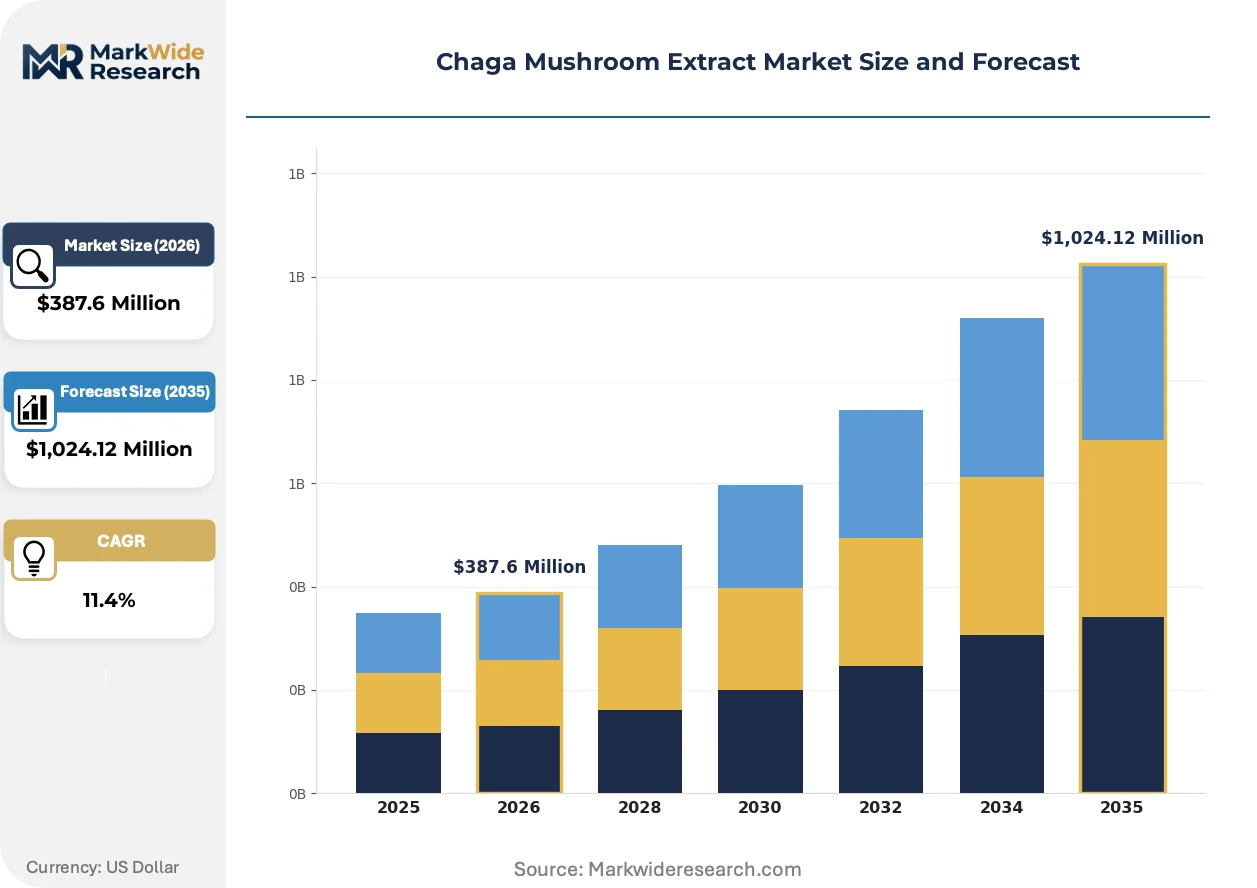
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid Extract, Capsules, Tea Application: Food & Beverage, Dietary Supplements, Cosmetic Products, Pharmaceuticals Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Health Food Stores End User: Individual Consumers, Health Enthusiasts, Food Manufacturers, Cosmetic Brands |
| Companies Covered | Baikal Herbs Ltd., Fungi Perfecti LLC, Annanda Chaga Mushrooms, Sayan Health Inc., Aloha Medicinals, Four Sigmatic, Nutra Green Biotechnology Co. Ltd., Nammex, Malama Mushrooms, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chaga Mushroom Extract Market Evolving Landscape
Processing technology and regulatory classification are diverging the chaga market into pharmaceutical-grade and wellness-grade supply tiers, with extraction methodology becoming the primary quality signal.
Subcritical water extraction technology is bifurcating the processing landscape. This method uses pressurized hot water below critical points to isolate polysaccharides without organic solvents. Pharmaceutical contract manufacturers are adopting it for cleaner-label adjuvant material. The technology is compressing traditional ethanol extraction's share in high-specification applications while enabling novel food dossier submissions in Europe.
EFSA novel food assessments are reshaping European market architecture. The regulatory pathway requires comprehensive toxicology data for non-traditional food ingredients. Supplement brands targeting EU distribution are reformulating around established botanicals or absorbing 24-month compliance timelines. This friction is diverting innovation investment toward North American and Asian markets with clearer ingredient permissibility frameworks.
Wellness subscription platforms are disintermediating conventional supplement retail. Consumers now discover chaga through personalized health apps rather than brick-and-mortar natural products stores. Direct-to-consumer brands capture recurring revenue through auto-ship liquid extract programs. This channel shift concentrates in urban coastal markets where digital health adoption runs highest.
Chaga Mushroom Extract Market Segmentation
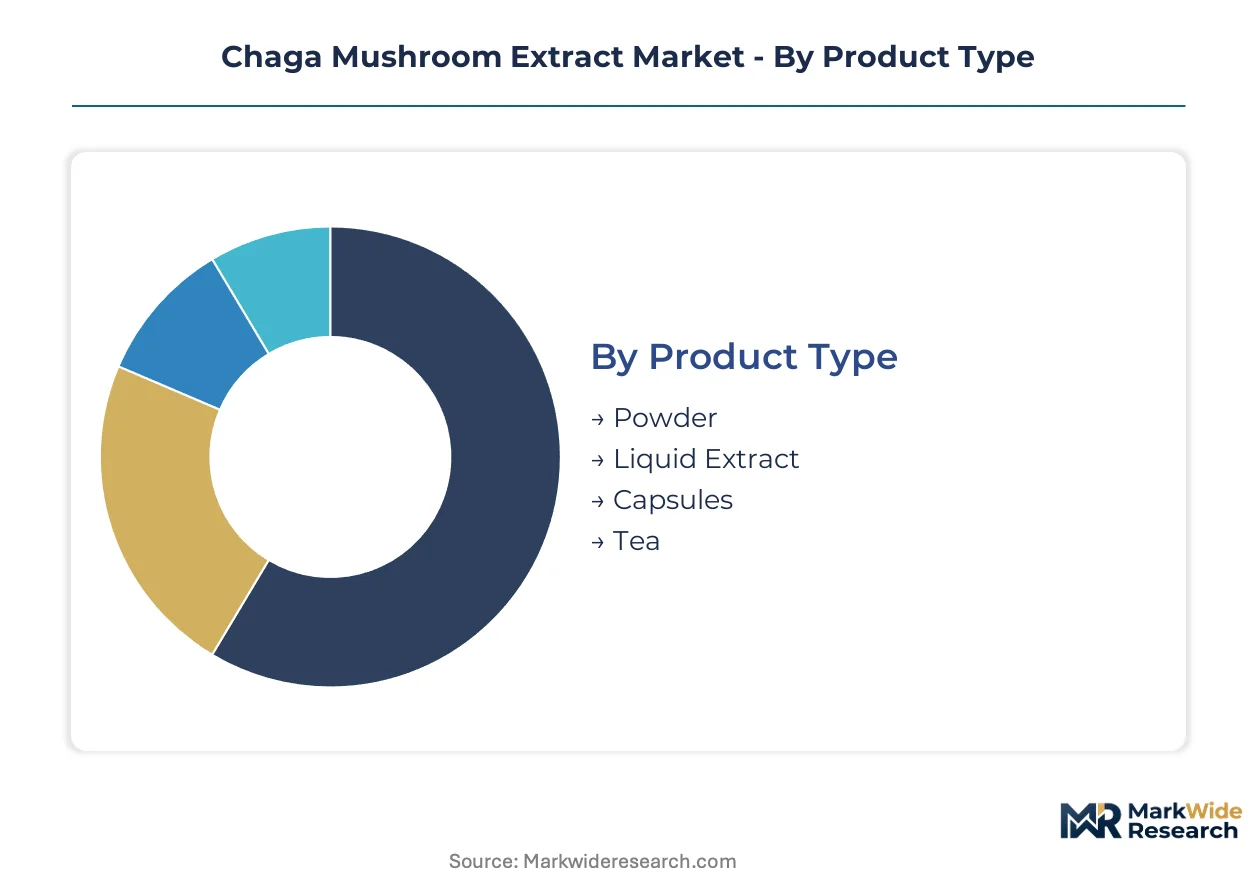
Segmentation in chaga mushroom extract markets reveals how extraction methodology and formulation format determine pricing power and channel access. Powder and liquid extract specifications command divergent margin structures based on bioactive concentration and end-use qualification requirements.
Product Type:
Premium margin pools concentrate in dual-extract liquid formats where pharmaceutical and direct-to-consumer wellness channels pay for standardized betulinic acid and polysaccharide content.
- Powder:Spray-dried extract from hot water processing delivers bulk manufacturing flexibility for supplement blenders. Demand concentrates in North American contract manufacturing facilities where USDA Organic certification enables wholesale premiums over conventional material.
- Liquid Extract:Alcohol and glycerin suspensions preserve volatile compounds for sublingual and beverage applications. Wellness subscription platforms in US coastal cities drive fastest volume expansion for dropper-format SKUs with third-party potency verification.
- Capsules:Encapsulated powder serves convenience-oriented health enthusiasts through retail pharmacy channels.
- Tea:Whole or chunked fruiting body infusions occupy traditional medicine positioning in Asian and Eastern European markets.
Powder holds installed capacity. Liquid extract is rotating up the share rankings.
Application:
Volume concentration sits with dietary supplement formulations, though pharmaceutical qualification protocols are opening the steepest expansion trajectory for GMP-certified extract suppliers.
- Food & Beverage:Functional beverage brands incorporate chaga into ready-to-drink adaptogen lines. Four Sigmatic and similar players drive North American specialty retail placement where mushroom-infused coffee alternatives capture premium shelf positioning.
- Dietary Supplements:Capsule and tablet formulations dominate current production volume. Immune-support positioning pulls chaga into post-pandemic supplement regimens across US and Canadian wellness retail channels.
- Cosmetic Products:Melanin and antioxidant compounds support anti-aging serum formulations in South Korean and Japanese beauty markets.
- Pharmaceuticals:Adjuvant therapeutic research investigates polysaccharide fractions for oncology protocols. EMA and FDA IND pathways require extract standardization that only dual-extract facilities can satisfy.
Dietary supplements anchor current revenue. Pharmaceuticals is climbing the fastest.
Distribution Channel:
Customer acquisition economics favor direct channels where brands capture full retail margin and subscription recurrence, while specialty retail maintains credibility signaling for premium positioning.
- Online Retail:Direct-to-consumer platforms and Amazon marketplace presence enable challenger brands to bypass traditional distribution markups. Auto-ship programs in US and Canadian urban markets concentrate recurring revenue for liquid extract suppliers.
- Specialty Stores:Independent natural products retailers and co-ops provide educational touchpoints for adaptogen-naive consumers. Staff recommendation drives trial conversion in Pacific Northwest and Northeast US markets.
- Supermarkets:Mass-market placement remains limited to powder formats in natural products aisles of Whole Foods and regional chains.
- Health Food Stores:GNC and Vitamin Shoppe shelf space requires slotting fees that favor established supplement brands with marketing co-op budgets.
Online retail is expanding most quickly. Specialty stores defend margin through service differentiation.
End User:
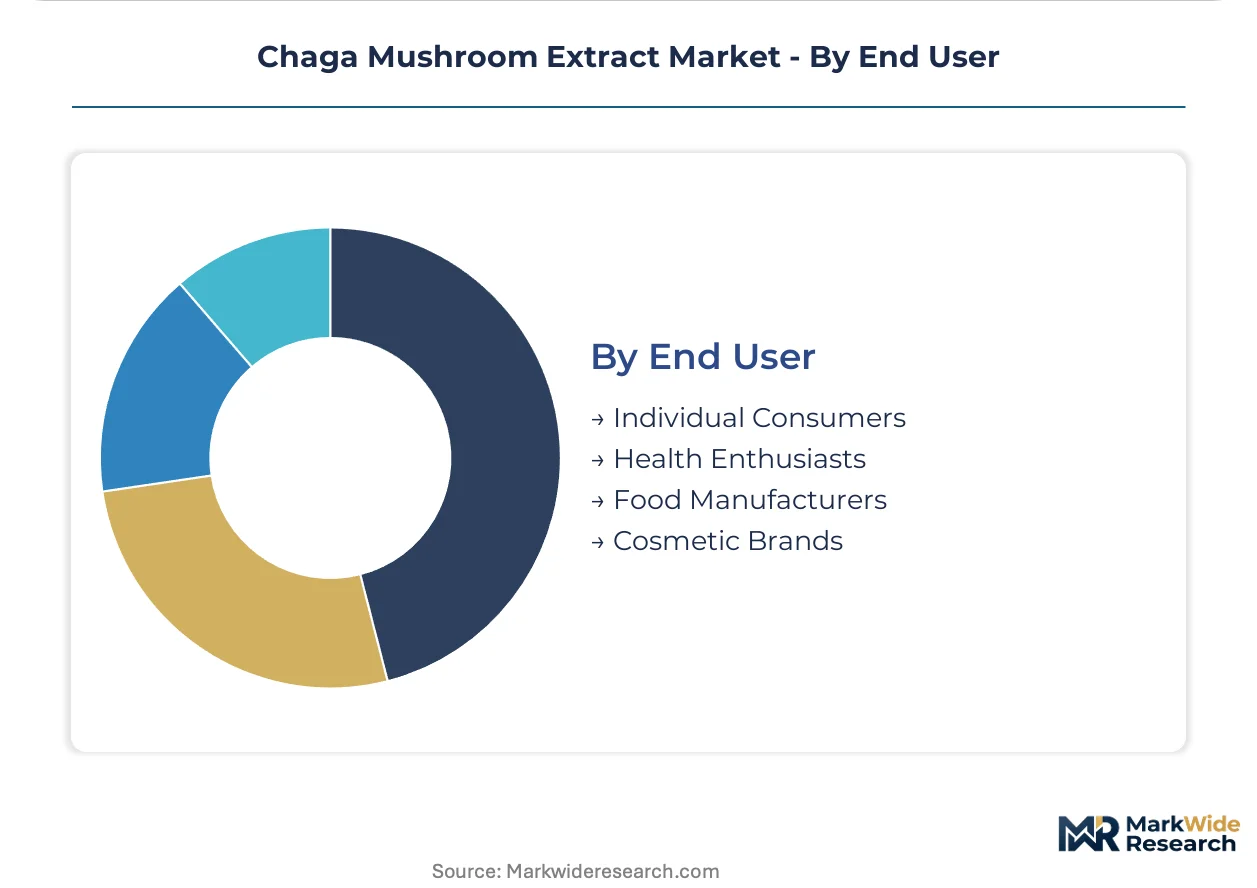
Procurement sophistication separates institutional buyers seeking certificate of analysis documentation from individual consumers responding to influencer and content marketing.
- Individual Consumers:Direct purchasers prioritize convenience and taste masking in functional beverage formats. Discovery occurs through Instagram and TikTok wellness content rather than traditional advertising.
- Health Enthusiasts:Biohacker and longevity communities demand third-party lab testing and wild-harvested provenance. They pay premiums for Siberian-sourced material with specified betulinic acid percentages.
- Food Manufacturers:Ingredient buyers require consistent polysaccharide content for functional food formulations. They source through distributors with lot traceability and organic certification documentation.
- Cosmetic Brands:Korean and Japanese beauty formulators seek melanin-rich extracts for UV-protective and antioxidant claims in premium skincare lines.
Health enthusiasts drive premium tier expansion. Food manufacturers provide volume stability through contract supply agreements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across demand centers. United States buyers absorb premiums for wild-harvested Siberian material while Southeast Asian markets gravitate toward cost-optimized cultivated alternatives. European procurement stalls on regulatory uncertainty.
United States
FDA Current Good Manufacturing Practice enforcement drives facility consolidation among dual-extract processors. The agency's identity testing requirements for dietary supplements filter out smaller wild-harvest cooperatives. Pacific Northwest extraction clusters in Oregon and Washington concentrate pharmaceutical-grade capacity serving oncology research pipelines.
Russia
Baikal Herbs Ltd. anchors wild-harvested supply from Siberian taiga zones. The Russian Far East faces climate variability and geopolitical friction that destabilize raw material flows. Lake Baikal processing infrastructure concentrates high-potency betulinic acid extraction for export to North American wellness brands.
Canada
Health Canada Natural Health Product Regulations enforce site licensing for chaga extract manufacturing. British Columbia and Ontario host GMP-certified facilities serving cross-border supplement brands. Vancouver-area importers manage Siberian raw material logistics for North American distribution.
China
NMPA novel food assessments create compliance friction for chaga ingredient imports. Domestic cultivation of Inonotus obliquus mycelium on grain substrates supplies price-sensitive powder manufacturers. Zhejiang and Shandong provinces concentrate spray-dried extract capacity for functional beverage formulations.
Finland
EFSA novel food pathways freeze European market entry for non-traditional chaga ingredients. Finnish suppliers pivot toward Asian and North American export markets with clearer permissibility frameworks. Helsinki-region R&D clusters investigate subcritical water extraction for cleaner-label pharmaceutical applications.
Chaga Mushroom Extract Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, fragmenting competitive dynamics across premium and mass-market tiers. Wild-harvested Siberian specialists command potency credentials while Asian cultivators capture volume through price-sensitive powder supply. Three archetypes dominate: dual-extract pharmaceutical-grade processors, direct-to-consumer wellness brands, and bulk raw material traders. Capacity expansion and USDA Organic certification represent the dominant competitive moves, with players building GMP-compliant lines or securing wild-harvest organic positioning to defend margin.
Within the wild-harvested premium tier, Baikal Herbs Ltd. and Sayan Health Inc. exemplify Siberian-sourced supply chain control. Fungi Perfecti LLC occupies a position bridging mycological research credibility with consumer education. Among cultivated-material processors, Nutra Green Biotechnology Co. Ltd. and Nammex represent scale-driven manufacturing archetypes serving contract supplement brands. Four Sigmatic anchors direct-to-consumer functional beverage placement in North American specialty retail.
| Leading Market Players |
|---|
| Baikal Herbs Ltd. |
| Fungi Perfecti LLC |
| Annanda Chaga Mushrooms |
| Sayan Health Inc. |
| Aloha Medicinals |
| Four Sigmatic |
| Nutra Green Biotechnology Co. Ltd. |
| Nammex |
| Malama Mushrooms |
| Others |
Value Network & Pricing Analysis
GMP-certified extraction capacity utilization above 80% in Oregon and Washington clusters concentrates supply-side pricing power among dual-extract processors, while smaller wild-harvest cooperatives face margin compression from identity testing compliance costs. This scale asymmetry stratifies the chaga market into premium wild-harvested Siberian supply and cost-optimized cultivated alternatives with divergent price floors.
Pricing Analysis
FDA Current Good Manufacturing Practice enforcement dictates the pricing tier structure across the chaga extract market. Three-tier pricing separates wild-harvested organic material from conventional powder and cultivated mycelium substitutes, with USDA Organic certification commanding wholesale premiums and brand positioning in wellness retail. Pricing pressure stems from cultivated chaga substitution in price-sensitive supplement tiers, eroding margins for mid-grade processors. Food manufacturers exhibit highest price sensitivity through contract manufacturing agreements, while health enthusiasts absorb premiums for specified betulinic acid content.
Supply Chain Analysis
Inventory lead times for Siberian raw material stretch 90-180 days depending on Lake Baikal processing queue depth and Russian Far East climate windows. Supply concentrates in Russia's taiga zones, China's Zhejiang and Shandong provinces, and Pacific Northwest extraction clusters. Raw material flows draw from wild-harvested Inonotus obliquus fruiting bodies, grain-substrate cultivated mycelium, and alcohol extraction solvents. Single-source vulnerability runs through Siberian wild-harvest zones facing geopolitical friction. Distribution runs through direct-to-consumer subscription platforms, specialty retail channels, and contract manufacturing facilities serving supplement brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical adjuvant research pipelines are disrupting traditional nutraceutical positioning, creating bifurcation between GMP-certified processors and wellness-grade suppliers. FDA IND pathway standardization represents the critical regulatory inflection separating investable scale from commodity exposure.
For Market Incumbents: Shield premium positioning by deepening backward integration into Siberian wild-harvest zones through exclusive sourcing agreements with Baikal-region cooperatives. Add GMP-certified capacity in British Columbia to capture cross-border Health Canada site licensing advantages. Cultivated chaga substitution from Chinese mycelium processors threatens mid-tier margin pools.
For New Entrants and Emerging Players: Direct-to-consumer subscription service gaps in European markets present white-space entry points where EFSA novel food assessments have frozen incumbent investment. Target Finnish and Nordic wellness consumers through subcritical water extraction positioning with cleaner-label pharmaceutical credibility. Launch through personalized health apps with auto-ship liquid extract programs rather than brick-and-mortar distribution.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer wellness brands with subscription auto-ship infrastructure. Long-term viability over the next decade rests on pharmaceutical-grade extraction capabilities serving oncology research pipelines. Target acquisition archetypes include dual-extract processors with FDA establishment registration and Siberian sourcing control. Monitor EMA and FDA IND filing volumes as inflection indicators for pharmaceutical demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Extract Capacity Expansion | GMP-certified lines enable pharmaceutical-grade material qualification serving FDA IND pathways. |
| Siberian Sourcing Integration | Exclusive wild-harvest agreements secure betulinic acid potency credentials for premium positioning. |
| USDA Organic Certification | Organic wild-harvested material commands wholesale premiums in North American wellness retail channels. |
| Direct-to-Consumer Platform Launch | Subscription auto-ship models capture full retail margin bypassing traditional supplement distribution. |
| Subcritical Water Extraction Adoption | Cleaner-label processing technology opens European novel food dossier submissions and pharmaceutical contracts. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with extraction facility operators, dietary supplement brand formulators, and regulatory affairs specialists; and secondary validation through FDA establishment registration databases, Health Canada Natural Health Product licensing records, USDA Organic certification listings, and EFSA novel food assessment dockets. Bottom-up volume modeling from extraction capacity and raw material flow data triangulated against top-down demand segmentation from channel shipment patterns and wellness retail audit data.
Across the projection horizon, the analytical framework modeled volume and value outputs through extraction methodology segmentation, formulation format tiers, application qualification requirements, and geographic regulatory clusters. CAGRs were derived from trend extrapolation of pharmaceutical research pipeline expansion, subscription platform adoption curves, and organic certification penetration rates. Industry-specific forecast inputs included EMA and FDA IND filing trajectories, Siberian climate harvest yield variability, and cultivated mycelium substitution elasticities.
Forecasts assume regulatory continuity in FDA dietary supplement enforcement and EFSA novel food assessment protocols; material policy shifts would require re-modeling. Outputs reflect assumptions regarding pharmaceutical adjuvant research advancement and wild-harvest supply stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Mediterranean Citrus Nutricosmetic Complex Market
Nutritional Supplements
L Carnitine Market
Nutritional Supplements
Milk Thistle Market
Nutritional Supplements
Fucoidan Market
Nutritional Supplements
Insoluble Dietary Fibers Market
Nutritional Supplements
Personalized Nutrition Market
Nutritional Supplements
Zinc Gluconate Market
Nutritional Supplements
US Nutraceuticals Market
Nutritional Supplements
Bone Supplements Market
Nutritional Supplements
Medium Chain Triglyceride (MCT) Food Market
Nutritional Supplements
Fish Collagen Peptides Market
Nutritional Supplements
Global Nutraceutical Market
Nutritional Supplements
Green Tea Supplements Market
Nutritional Supplements
Europe Amino Acid in Dietary Supplements Market
Nutritional Supplements
Lactoferrin Market
Nutritional Supplements
Europe Vegan Supplements Market