
 Vegan Tuna Market | 2026-2036
Vegan Tuna Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Tuna Market Analytics
Marine Stewardship Council chain-of-custody certification is unwinding competitive access for newer entrants unable to verify sustainable supply chains. Good Catch leverages proprietary legume-protein extrusion technology to replicate flaky tuna texture without ocean-derived inputs. Sophie's Kitchen anchors its position through retail placement across North American natural grocery networks. Thai Union extends its conventional seafood dominance into plant-based lines through dedicated alternative-protein R&D facilities in Thailand.
Vegan tuna comprises formulated plant-protein or microbial biomass products engineered to replicate the sensory properties—flavor, texture, mouthfeel—of cooked skipjack or yellowfin tuna, typically achieving protein content between 15 and 20 grams per serving through extrusion or shear-cell processing. Its primary commercial purpose is to substitute conventional tuna in sandwiches, salads, poke bowls, and sushi applications without mercury exposure or bycatch concerns. Packaged products currently lead volume as refrigerated deli-style formats gain shelf space, while frozen options represent the fastest-expanding segment driven by foodservice portion-control demand. Pea protein formulations command margin premiums over soy-based alternatives due to cleaner allergen profiles and non-GMO positioning in European and North American retail.
FDA GRAS self-affirmation pathways and USDA FSIS labeling oversight shape product claims and market entry timelines for US manufacturers, while EFSA novel food authorization under EU Regulation 2015/2283 governs European commercialization of fermented and cell-cultured tuna alternatives. REACH compliance for processing aids and EU Green Deal carbon-accounting requirements add compliance layers that favor scaled producers with dedicated regulatory affairs capacity. Stakeholders must monitor evolving nomenclature rules—whether "tuna" labeling survives challenge under dairy-style naming restrictions—as this determination will reshape packaging, marketing, and retail placement strategies.
Market Dynamics
Fermentation-derived biomass and precision extrusion technologies are compressing production costs while EU Green Deal protein-transition mandates accelerate procurement timelines for foodservice operators.
Growth Catalysts
- EU Green Deal sustainable protein targets:Binding carbon-accounting requirements for institutional catering contracts are redirecting procurement budgets toward plant-based seafood alternatives in German and French public-sector foodservice.
- Shear-cell processing maturation:This extrusion refinement is achieving flaky muscle-fiber alignment without traditional fish-derived inputs, opening formulation pathways for allergen-free product lines.
- West Coast flexitarian density:Metropolitan clusters in California, Oregon, and Washington state concentrate early-adopter households with disposable income thresholds supporting premium plant-protein trial.
Market Restraints
- Pea protein input cost volatility:Concentrated sourcing from Canadian and Ukrainian agricultural regions exposes margins to climate-driven harvest variability and geopolitical supply interruptions.
- EFSA novel food authorization timelines:Fermentation-derived and cell-cultured tuna alternatives face 18-24 month safety assessment protocols that freeze commercialization for European entrants lacking scaled regulatory affairs capacity.
- Conventional canned tuna price anchoring:Commodity skipjack pricing at retail sets a ceiling that plant-based alternatives struggle to undercut without sacrificing margin or ingredient quality.
Strategic Opportunities
- Japanese foodservice integration:Traditional sushi and teishoku restaurant chains face mounting pressure from METI sustainability guidelines, creating white space for texture-matched alternatives in high-visibility culinary applications.
- Refrigerated deli-format expansion:Grab-and-go sandwich and poke bowl counters in US urban convenience retail represent an underexploited channel with higher margin capture than frozen distribution.
- Fermentation-biomass hybrid formulations:Combining mycelium protein with legume extrudates is converging two technology streams to achieve amino acid completeness and umami depth without single-source dependency.
Industry Challenges
- Flavor chemist talent scarcity:The intersection of marine biochemistry and plant-protein formulation requires specialized expertise that outpaces current food science graduate program output.
- Marine Stewardship Council chain-of-custody certification:Verification protocols designed for wild-catch fisheries create documentation friction for biomass-derived alternatives seeking credibility signaling in European retail.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Tuna Market |
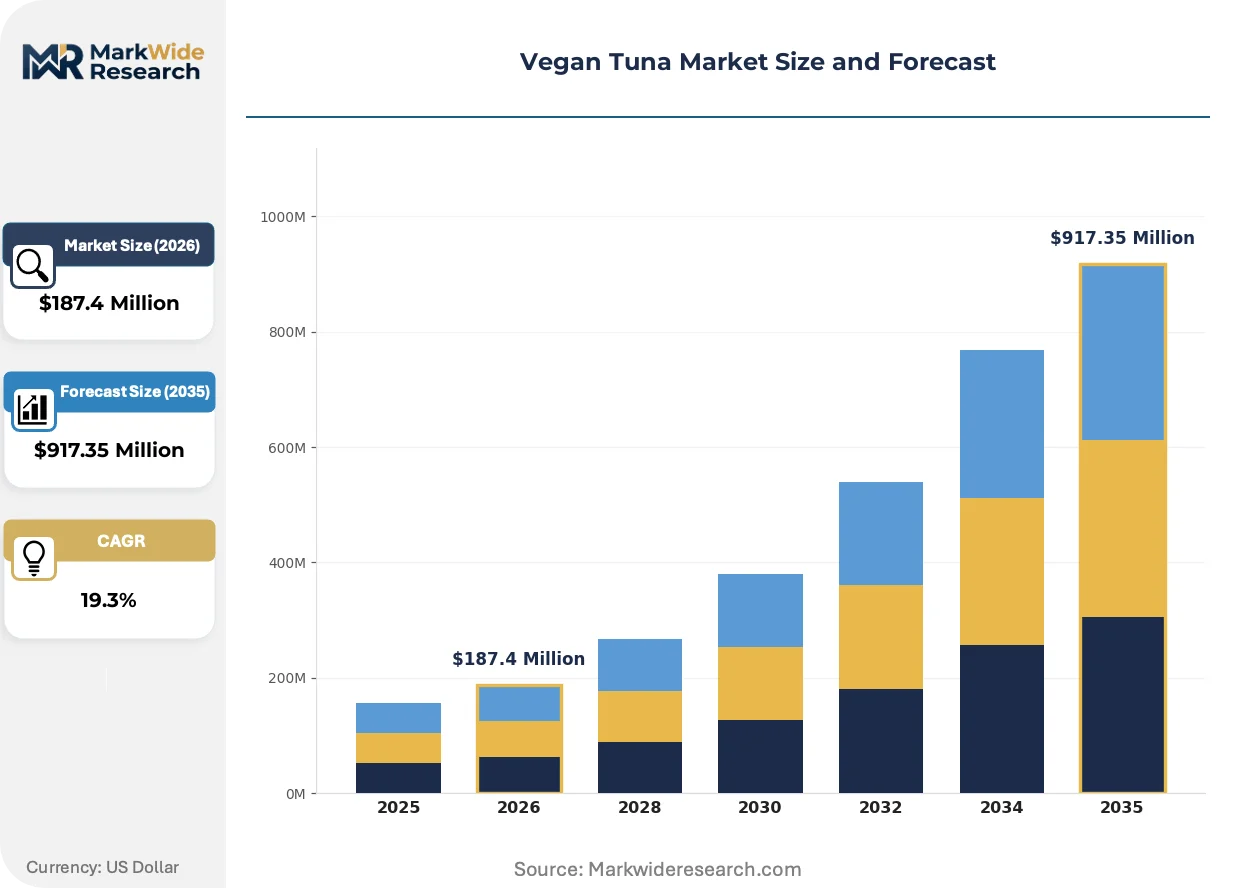
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $917.35 Million |
| CAGR (2026 – 2036) | 19.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Foods, Packaged Products, Canned Varieties, Frozen Options Ingredient Source: Pea Protein, Soy Protein, Seaweed Extract, Chickpeas Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Shops Customer Type: Vegetarians, Vegans, Flexitarians, Health-Conscious Consumers |
| Companies Covered | Good Catch, Sophie's Kitchen, Ocean Hugger Foods, Thai Union, Loma Linda, Garden Gourmet, Atlantic Natural Foods, Prime Roots, Endori, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Tuna Market Evolving Landscape
Bioprocessing advances and regulatory nomenclature battles are simultaneously expanding technical possibility and compressing marketing latitude for plant-based seafood positioning.
Precision fermentation of marine-derived proteins is displacing reliance on agricultural commodity inputs for umami depth and nutritional completeness. Foodservice distributors in the United States and Netherlands are accelerating qualification programs for these biomass-derived alternatives. The technology is displacing first-generation pea-soy formulations in premium positioning tiers where sensory fidelity commands price premiums.
EFSA novel food authorization under EU Regulation 2015/2283 is reshaping European commercialization pathways for fermented and cell-cultured alternatives. Manufacturers must construct dedicated toxicology and allergenicity dossiers that extend time-to-market by 18-36 months relative to conventional plant-protein launches. Fermentation-derived products face the most stringent scrutiny, favoring entrants with pre-existing regulatory infrastructure over venture-stage competitors.
Flexitarian household purchasing is rotating toward refrigerated deli-case formats over frozen alternatives in metropolitan US markets. Convenience-oriented retail channels including urban grocery and prepared-food counters are capturing volume that traditional frozen distribution cannot access. California and New York metropolitan statistical areas exhibit the most pronounced channel shift, with refrigerated SKUs achieving placement velocity multiples of frozen equivalents.
Vegan Tuna Market Segmentation
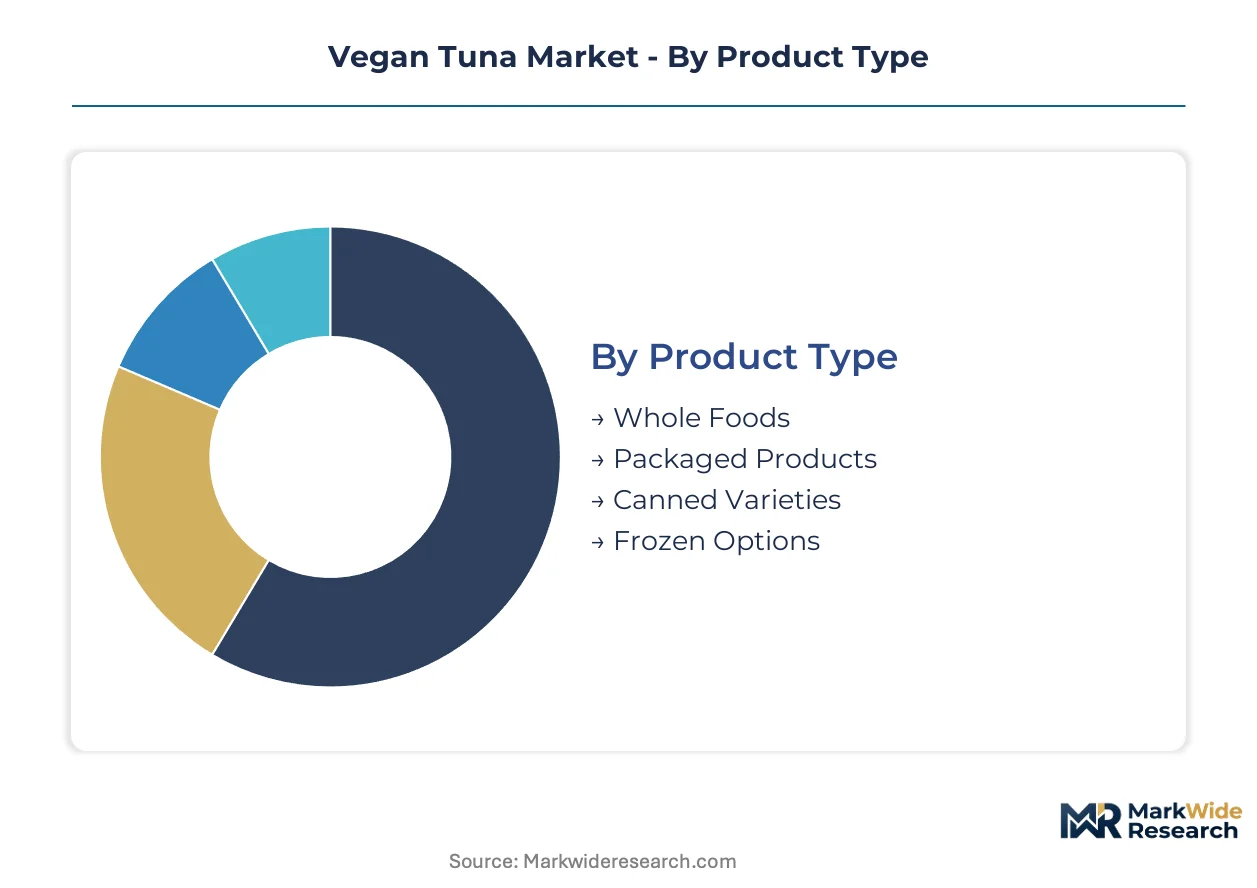
Vegan tuna segmentation reveals how formulation choices and channel strategies map to distinct regulatory exposures and margin profiles. Each dimension carries specific compliance burdens and growth velocity characteristics that reshape competitive positioning.
Product Type:
FDA GRAS self-affirmation and USDA FSIS labeling oversight create divergent entry timelines across formats, with refrigerated products facing stricter pathogen controls than shelf-stable alternatives.
- Packaged Products:Refrigerated deli-style formats dominate current shelf space in US metropolitan grocery. California and New York urban convenience retail channels capture velocity multiples above frozen equivalents, driven by grab-and-go prepared food demand.
- Frozen Options:Shear-cell processed extrudates achieve flaky muscle-fiber alignment for foodservice portion-control applications. German and French institutional catering contracts under EU Green Deal carbon-accounting mandates are redirecting procurement budgets toward this format.
- Whole Foods:Unprocessed legume or seaweed preparations for home formulation occupy niche natural grocery placement.
- Canned Varieties:Thermally stabilized formats compete directly with commodity skipjack pricing anchors in mass retail.
Packaged products handle the majority of throughput; frozen options are climbing the fastest on share.
Ingredient Source:
Input cost structures and allergen liability profiles stratify margin resilience, with concentrated agricultural sourcing exposing certain categories to climate and geopolitical volatility.
- Pea Protein:Non-GMO positioning and cleaner allergen profiles command retail premiums in European and North American markets. Canadian and Ukrainian harvest variability directly compresses margins for formulations dependent on this input.
- Soy Protein:Established extrusion infrastructure and amino acid completeness support economy-tier positioning. FDA GRAS status accelerates US commercialization relative to novel fermentation alternatives.
- Seaweed Extract:Marine-derived umami compounds reduce reliance on artificial flavor systems.
- Chickpeas:Mediterranean culinary familiarity aids sensory acceptance in Southern European markets.
Pea protein carries the volume concentration; seaweed extract is gaining share fastest.
Distribution Channel:
Channel selection determines which regulatory jurisdictions dominate compliance burden, with direct-to-consumer platforms facing FTC advertising scrutiny while brick-and-mortar encounters state-level food safety inspections.
- Supermarkets:Mainstream grocery placement in US West Coast metropolitan clusters concentrates flexitarian household trial. Oregon and Washington state retailers exhibit higher SKU velocity than national averages for refrigerated formats.
- Online Retail:Subscription and direct-to-consumer models bypass traditional slotting fee structures. EFSA novel food authorization timelines for fermented alternatives create 18-24 month commercialization freezes that disproportionately impact European e-commerce entrants.
- Health Food Stores:Natural grocery networks anchor premium positioning for early-stage brands.
- Specialty Shops:Asian grocery and sushi supply channels target texture-matched applications for foodservice integration.
Supermarkets manage the bulk of volume movement; online retail is expanding most quickly.
Customer Type:
Purchasing motivation and price elasticity vary sharply across dietary commitment levels, with health-driven trial converting to repeat purchase at divergent rates.
- Flexitarians:California, Oregon, and Washington metropolitan households with disposable income thresholds drive premium plant-protein trial. West Coast urban convenience retail placement captures this segment through prepared-food counter integration.
- Health-Conscious Consumers:Mercury avoidance and bycatch elimination motivate purchase independent of dietary restriction. REACH compliance for processing aids and EU Green Deal carbon-accounting requirements favor scaled producers with dedicated regulatory affairs capacity in European markets.
- Vegans:Ethical consistency demands drive highest willingness-to-pay for marine-input-free formulations.
- Vegetarians:Lacto-ovo dietary frameworks accept broader formulation flexibility than strict vegan positioning.
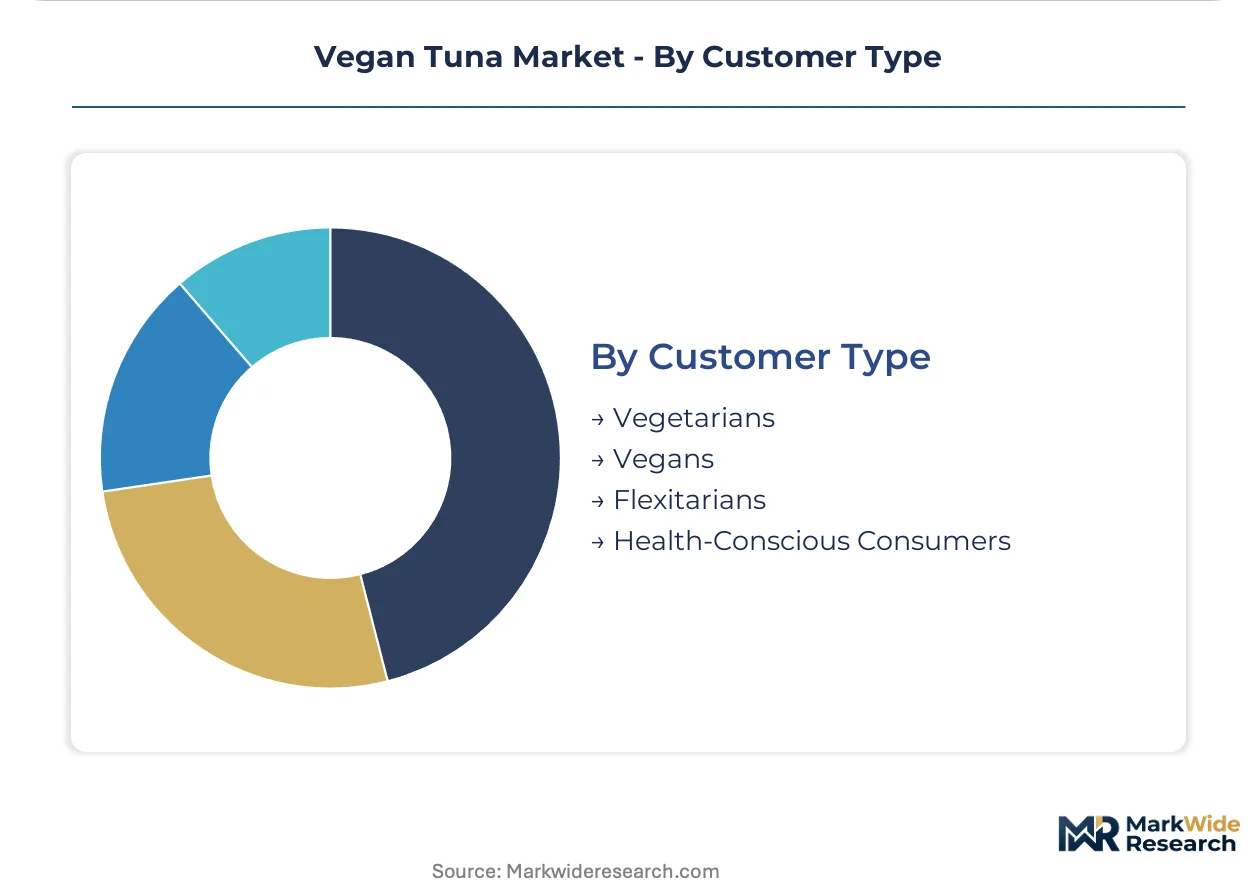
Flexitarians represent the largest addressable base; health-conscious consumers are accelerating fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Flexitarian households with premium disposable income concentrate in coastal metropolitan clusters across four distinct national markets. Each geography presents unique regulatory scaffolding and channel-access conditions that stratify competitive entry costs.
United States
California, Oregon, and Washington metropolitan statistical areas drive refrigerated format velocity through urban convenience retail placement. FDA GRAS self-affirmation pathways accelerate commercialization timelines relative to European counterparts. Los Angeles and San Francisco Bay Area prepared-food counters capture trial purchase from health-motivated flexitarians seeking mercury-free alternatives.
Germany
Binding EU Green Deal carbon-accounting mandates redirect institutional catering procurement budgets toward plant-based seafood alternatives. EFSA novel food authorization protocols under Regulation 2015/2283 impose 18-24 month safety assessment timelines that freeze market entry for fermentation-derived entrants. Berlin and Hamburg foodservice distributors qualify biomass alternatives for premium positioning tiers.
Thailand
Conventional seafood processing infrastructure enables backward integration into alternative-protein R&D facilities. METI sustainability guidelines in export destination markets create compliance pressure that domestic manufacturers leverage for technology transfer. Bangkok-based research clusters develop shear-cell processing capabilities for texture-matched export formulations.
Netherlands
REACH compliance requirements for processing aids favor scaled producers with dedicated regulatory affairs capacity in European distribution hubs. Dutch foodservice distributors accelerate qualification programs for precision-fermentation alternatives displacing first-generation formulations. Rotterdam logistics networks channel biomass-derived products into German and French retail channels.
Japan
Traditional sushi and teishoku restaurant chains face mounting pressure from METI sustainability guidelines creating white space for texture-matched alternatives. Tokyo and Osaka metropolitan foodservice markets exhibit concentrated demand for sensory-fidelity products in high-visibility culinary applications. Japanese consumers demonstrate willingness-to-pay premiums for marine-input-free formulations meeting traditional preparation standards.
Vegan Tuna Market Competitive Landscape
Player mix skews toward venture-stage technology developers and incumbent seafood conglomerates diversifying into alternative proteins. Market structure exhibits moderate consolidation with tiered positioning across premium sensory-fidelity and economy nutrition-complete segments. Strategic archetypes include proprietary extrusion technology specialists, conventional seafood backward integrators, and fermentation-biomass hybrid formulators. Dominant competitive moves encompass dedicated R&D facility construction and shear-cell processing technology licensing arrangements.
Within the technology-specialist tier, Good Catch and Sophie's Kitchen exemplify divergent channel strategies for plant-protein market penetration. Good Catch occupies a position anchored in proprietary legume-protein extrusion capabilities, while Sophie's Kitchen represents retail-placement concentration across North American natural grocery networks. Thai Union sits within the incumbent-diversifier archetype, leveraging conventional seafood infrastructure for alternative-protein R&D scale.
| Leading Market Players |
|---|
| Good Catch |
| Sophie's Kitchen |
| Ocean Hugger Foods |
| Thai Union |
| Loma Linda |
| Garden Gourmet |
| Atlantic Natural Foods |
| Prime Roots |
| Endori |
| Others |
Value Network & Pricing Analysis
Inventory cycles spanning 45-60 days for pea protein isolate bind pricing volatility to Canadian Prairie harvest conditions, compressing margin buffers for mid-tier extrusion processors while amplifying procurement leverage for scaled buyers with forward-contract coverage.
Pricing Analysis
Cost-plus contracts indexed to agricultural commodity exchanges dominate pea protein sourcing, with Canadian and Ukrainian harvest benchmarks resetting quarterly pricing bands. Three-tier pricing structure across premium, standard, and economy levels separates MSC chain-of-custody certified formulations from conventional extrudates and private-label economy tiers. Pricing pressure stems from conventional canned tuna commodity anchors that constrain retail ceiling prices. Foodservice distributors exhibit lowest price sensitivity due to EU Green Deal procurement mandates, while mass retail channels force margin compression through volume commitments.
Supply Chain Analysis
Black Sea grain corridor disruptions expose Ukrainian pea protein concentrate flows to geopolitical chokepoint risk, forcing European formulators toward Canadian and Australian alternative sourcing. Raw material dependencies center on yellow pea isolate, soy protein concentrate, and fermentation-derived mycelium biomass. Single-source vulnerability concentrates in Prairie Province processing infrastructure for premium non-GMO inputs. Distribution runs through refrigerated cold-chain networks for deli-format products, with frozen alternatives leveraging conventional seafood logistics infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges from flexitarian demand bifurcation, as refrigerated convenience formats and frozen foodservice applications diverge sufficiently to sustain distinct competitive ecosystems without consolidation pressure.
For Market Incumbents: Fortify shear-cell processing capabilities through captive R&D facilities in Thailand and Netherlands distribution hubs, defending against precision-fermentation entrants by accelerating FDA GRAS dossier accumulation. Backward integration into Canadian pea protein processing secures input cost stability against harvest volatility. For New Entrants and Emerging Players: Anchor in Japanese foodservice white space where METI sustainability guidelines create procurement receptivity for texture-matched alternatives. Target metropolitan California prepared-food counters through refrigerated deli-format placement, leveraging direct-store-delivery bypass of slotting fee structures. For Investors and Strategic Acquirers: Carve-out targets emerge from conventional seafood conglomerates with stranded alternative-protein R&D assets. Long-term viability hinges on fermentation-biomass hybrid technology maturation within a decade horizon. Signal to monitor: EFSA novel food authorization throughput rates for biomass-derived entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Shear-Cell Processing Scale-Up | Proprietary extrusion technology replicates flaky muscle-fiber alignment without fish-derived inputs. |
| EFSA Novel Food Dossier Investment | Regulatory infrastructure accelerates European commercialization timelines for fermentation alternatives. |
| Canadian Pea Protein Backward Integration | Upstream control over Prairie Province processing insulates margins from harvest volatility. |
| Japanese Foodservice Partnership | Tokyo and Osaka teishoku chains create high-visibility trial platforms for texture-matched products. |
| Refrigerated Deli-Format Expansion | Urban convenience retail placement captures velocity multiples above frozen distribution equivalents. |
Research Methodology
The analysis maps plant-protein extrusion, precision fermentation, and shear-cell processing sub-sectors, each validated through foodservice procurement directors, regulatory affairs leads at alternative-protein manufacturers, retail category buyers, and R&D directors at seafood conglomerates. Primary interview insights triangulate against FDA GRAS filings, EFSA novel food submissions, EU Green Deal procurement databases, and refrigerated distribution channel audits. Bottom-up SKU velocity data from California and New York metropolitan markets reconciles with top-down carbon-accounting mandate flow-through estimates.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. Segmentation dimensions modeled include product format, ingredient source, distribution channel, and customer dietary commitment level. CAGRs derive from elasticity-adjusted demand curves incorporating flexitarian household penetration rates and foodservice contract conversion timelines. Forecast inputs incorporate EU institutional catering procurement trajectories and West Coast retail placement velocity differentials.
Material uncertainties — EFSA authorization timeline extensions, pea protein harvest variability, and nomenclature restriction rulings — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory pathway efficiency and agricultural input stability. Revision becomes warranted when fermentation-derived product approval backlogs exceed 36-month thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Sugar Alternative Market
Alternative Food Sources
Mycoprotein Products Market
Alternative Food Sources
Europe Algae Protein Market
Alternative Food Sources
Products from Food Waste Market
Alternative Food Sources
Meat Analogue Market
Alternative Food Sources
Corn-Based Protein Market
Alternative Food Sources
Egg Substitutes Market
Alternative Food Sources
Spirulina Market
Alternative Food Sources
Asia-Pacific Algae Protein Market
Alternative Food Sources
Vegan Ham Market
Alternative Food Sources
Spirulina Beverages Market
Alternative Food Sources
Mealworms Market
Alternative Food Sources
Asia-Pacific Meat Substitutes Market
Alternative Food Sources
Insect Protein Market
Alternative Food Sources
Global Meal Replacement Shakes Market
Alternative Food Sources
Gluten Replacer Market