
 Recycled Ocean Plastics Market | 2026-2036
Recycled Ocean Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Recycled Ocean Plastics Market Intelligence
The EU Single-Use Plastics Directive is restructuring procurement standards across European packaging supply chains. Bureo leverages its NetPlus supply network to dominate certified fishing gear recovery along South American coastlines. Envision Plastics sustains mechanical recycling scale through proprietary decontamination protocols for post-consumer ocean polyethylene. 4Ocean anchors consumer-facing brand equity by integrating collection operations with finished goods manufacturing.
Recycled ocean plastics comprise post-consumer polymer waste recovered from marine environments, coastal waterways, and ocean-bound collection zones, typically requiring salt removal, UV degradation remediation, and sorting to achieve melt-flow indices suitable for re-extrusion or depolymerization. The primary commercial purpose centers on displacing virgin petrochemical feedstocks in durable and semi-durable goods where brand sustainability credentials command procurement preference. Polyethylene Terephthalate leads volume throughput due to established bottle-to-fiber infrastructure, while chemical recycling of nylon from fishing nets captures premium pricing in automotive and sporting goods applications where performance specifications resist mechanical degradation. Mechanical recycling occupies the cost-efficient baseline for packaging and construction segments, though pyrolysis capacity expansion is accelerating for mixed-polymer feedstocks that mechanical sorting cannot economically resolve.
The EPA's ocean debris program and California's SB 54 packaging EPR framework shape North American compliance obligations, while REACH registration requirements and the EU Green Deal's circular plastics targets govern European material certification and market access. BIS standards in India and China's GB recycling specifications are progressively incorporating ocean plastic traceability into national circular economy mandates. Stakeholders must monitor chemical recycling yield improvements and regulatory harmonization across these jurisdictions to secure feedstock agreements before collection infrastructure bottlenecks tighten.
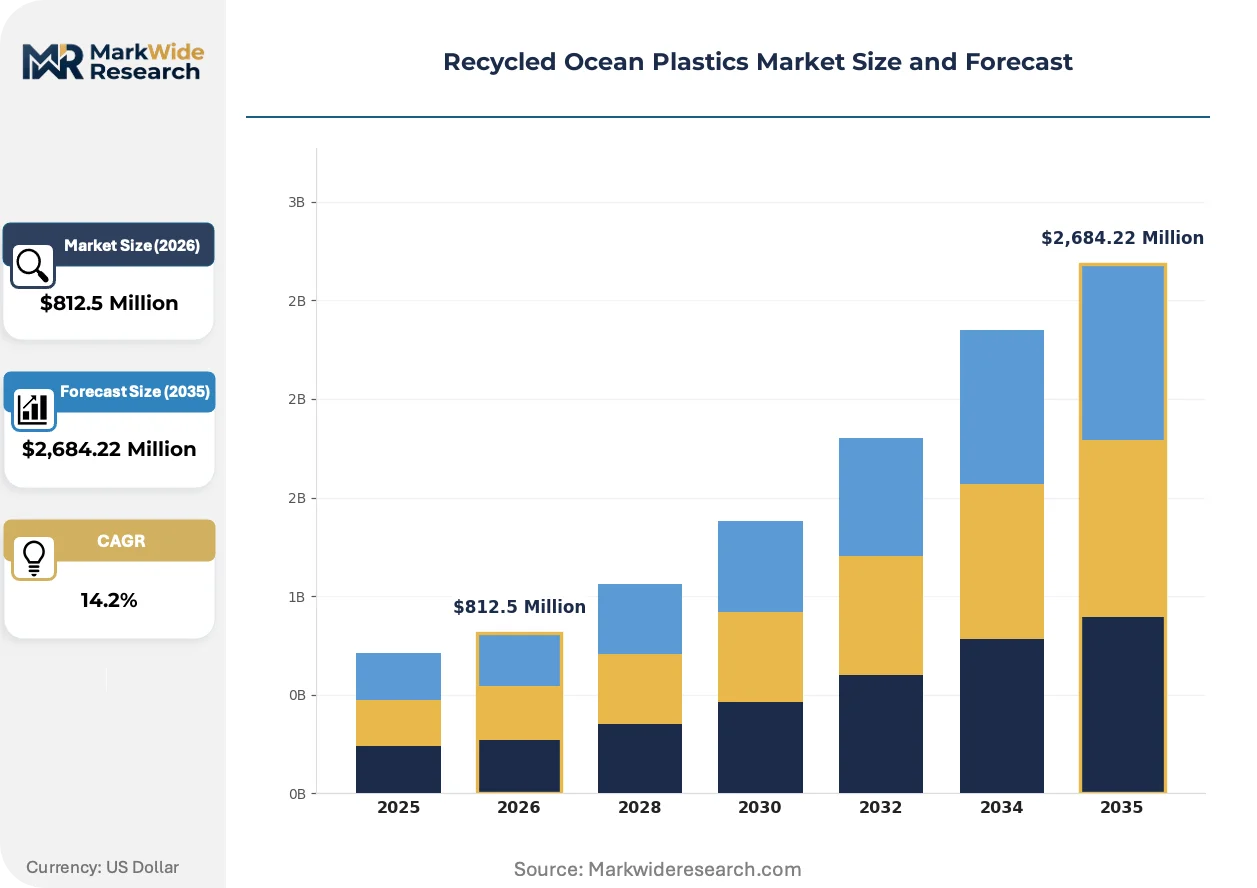
Market Dynamics
The EU Single-Use Plastics Directive is forcing packaging converters to source certified ocean-bound resins ahead of mechanical recycling capacity expansion, compressing procurement timelines while chemical recycling partnerships scramble to secure traceable feedstock agreements.
Growth Catalysts
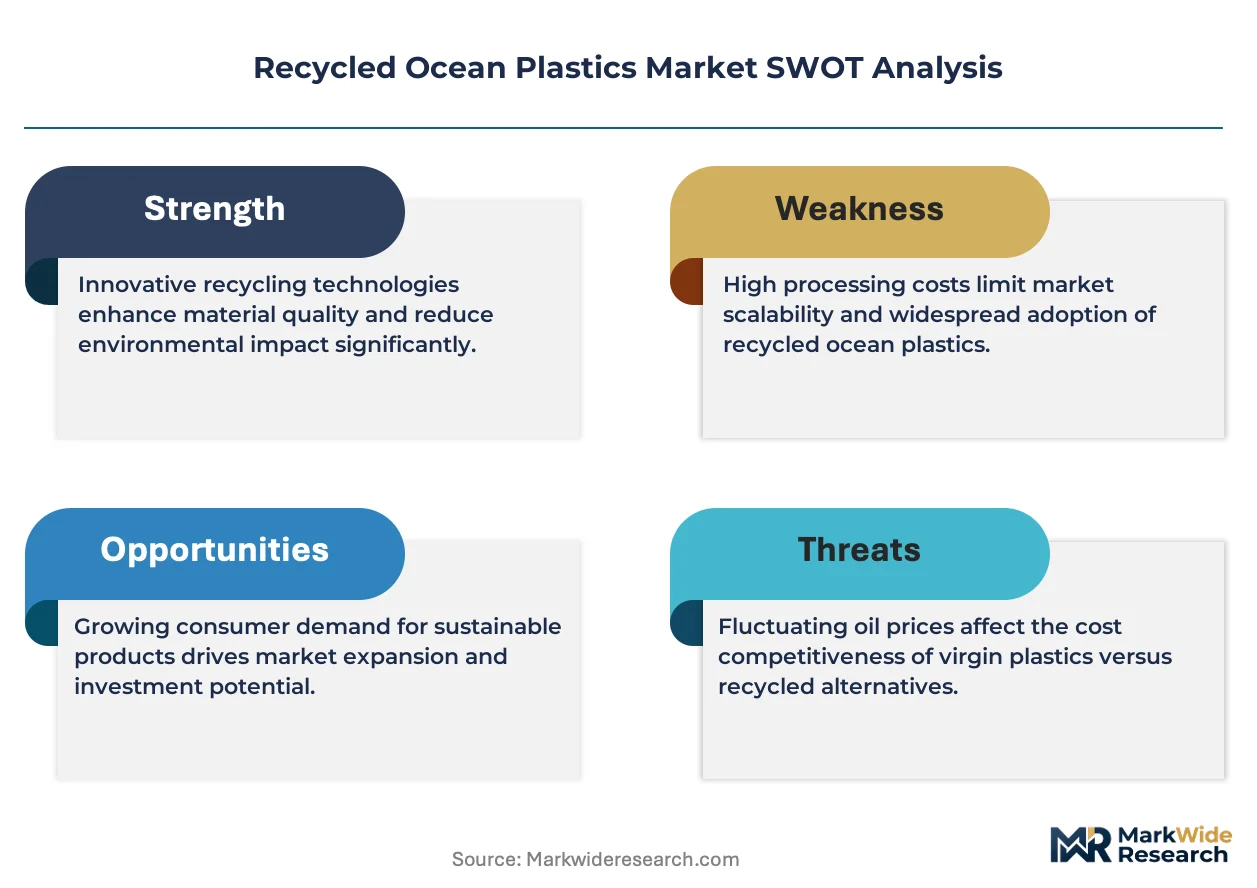
- REACH Registration Requirements:European material certification mandates are locking in premium pricing for traceable ocean plastic, pulling automotive OEMs toward recycled ocean nylon specifications for interior components.
- Mechanical Recycling Infrastructure:Established bottle-to-fiber processing lines for polyethylene terephthalate are absorbing coastal collection volumes at scale, lowering unit economics for packaging converters.
- California SB 54 Packaging EPR:Extended producer responsibility frameworks are redirecting brand sustainability budgets toward ocean plastic procurement, creating guaranteed offtake for certified resins.
Market Restraints
- Feedstock Volatility:Seasonal variation in coastal debris density and fishing fleet activity concentrates supply risk in Southeast Asian collection zones during monsoon periods.
- Decontamination Cost Structure:Salt removal and UV degradation remediation for post-consumer ocean polyethylene requires energy-intensive washing protocols that mechanical recyclers struggle to amortize.
- Pyrolysis Yield Limitations:Mixed-polymer feedstocks resist chemical recycling efficiency thresholds, trapping value in lower-grade applications despite premium pricing for pure nylon streams.
Strategic Opportunities
- Automotive Interior Specifications:German OEM sustainability scorecards are creating captive demand for performance-grade recycled ocean nylon in seat fabrics and trim components.
- GB Standards Integration:China's national circular economy mandates are progressively incorporating ocean plastic traceability, opening procurement channels for certified exporters.
- Sporting Goods Premium Positioning:Performance specifications in athletic footwear and equipment are resisting mechanical degradation, enabling pricing power for chemically recycled fishing net polymers.
Industry Challenges
- Certification Timeline Compression:Third-party ocean plastic verification protocols require 6-12 month audit cycles that lag behind brand procurement deadlines, creating supply gaps.
- Collection Infrastructure Bottlenecks:Port logistics and coastal sorting capacity in Indonesia and the Philippines constrain feedstock aggregation before monsoon season disruptions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recycled Ocean Plastics Market |
| Market Size in 2026 | $812.5 Million |
| Market Size in 2035 | $2,684.22 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyethylene, Polypropylene, Polyethylene Terephthalate, Nylon Application: Packaging, Textiles, Construction, Consumer Goods Process Type: Mechanical Recycling, Chemical Recycling, Pyrolysis, Upcycling End Use Industry: Consumer Electronics, Automotive Components, Furniture, Sporting Goods |
| Companies Covered | Bureo, Envision Plastics, 4Ocean, Plastic Bank, Tide Ocean SA, The Ocean Cleanup, Ocean Plastic Technologies, Veolia, Oceanworks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recycled Ocean Plastics Market Strategic Shifts & Innovations
Pyrolysis-based chemical recycling is overtaking mechanical sorting as the dominant processing pathway for mixed-polymer ocean debris, restructuring competitive positioning around yield optimization rather than scale economies alone.
Depolymerization reactors with integrated catalytic cracking are overtaking conventional mechanical washing lines for fishing net recovery, enabling nylon 6 regeneration at automotive-grade purity. Tier-1 suppliers in Germany and Japan are adopting these systems under 36-month payback assumptions. The technology is overtaking legacy mechanical recycling in premium applications where melt-flow consistency commands procurement preference.
REACH registration requirements for recycled content traceability are tightening documentation standards across European supply chains, forcing converters to maintain chain-of-custody records from collection point to finished goods. The regulation compresses supplier qualification timelines while expanding audit costs. Packaging segments serving EU markets are responding by consolidating procurement around pre-certified resin networks rather than spot-market sourcing.
Brand sustainability scorecards are displacing price-only procurement criteria in consumer-facing durable goods, compressing supplier selection cycles around verified ocean plastic content percentages. Sporting goods and apparel manufacturers are integrating collection operations with finished goods manufacturing to secure certification credibility. This pattern concentrates most visibly in California and Germany where EPR frameworks and OEM specifications overlap.
Recycled Ocean Plastics Market Segmentation
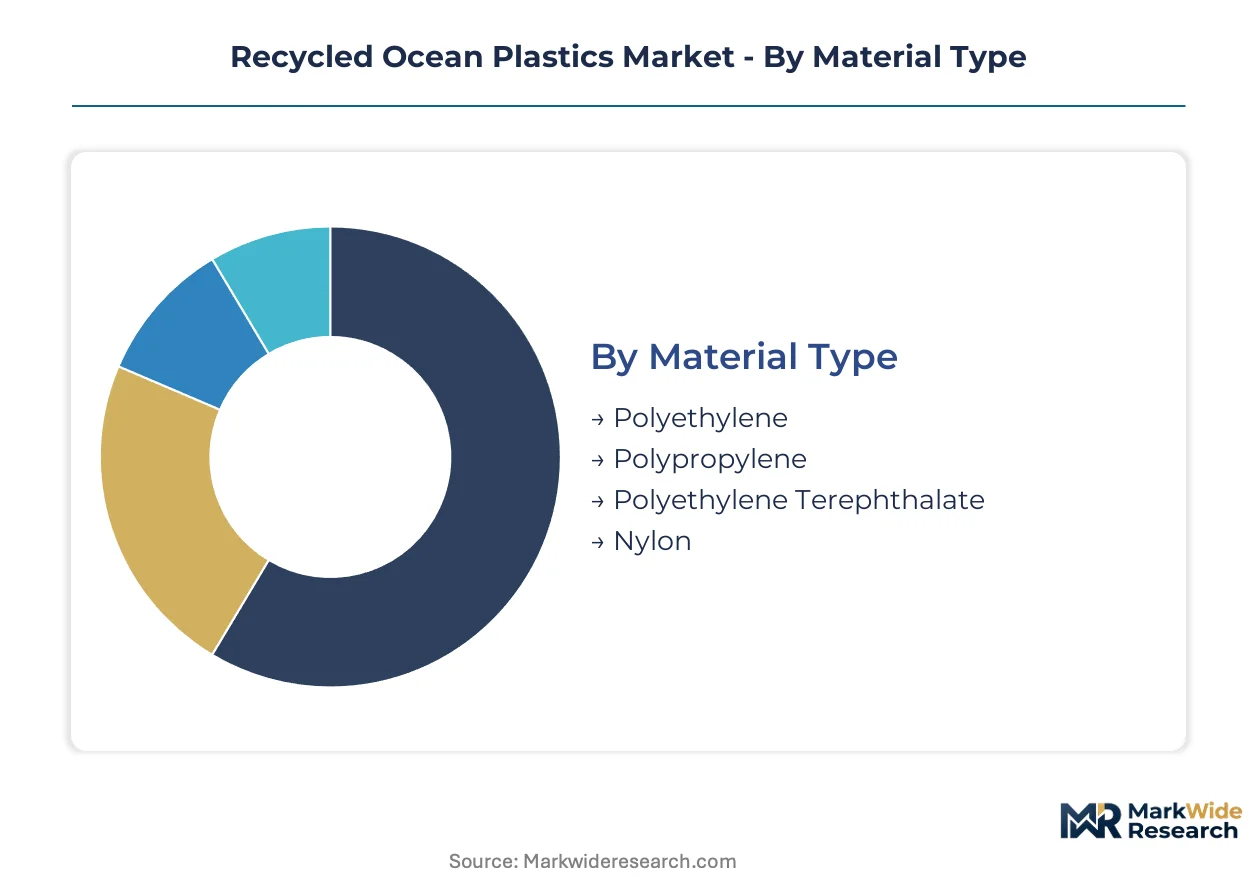
Material specifications and processing pathways determine procurement economics for ocean plastic feedstocks. Automotive OEMs and packaging converters source from distinct supply tiers based on performance requirements and certification standards.
Material Type:
Polymer chemistry dictates decontamination intensity and end-use suitability across coastal collection networks.
- Polyethylene:Post-consumer ocean polyethylene requires salt removal and UV degradation remediation through energy-intensive washing protocols. Packaging converters in Germany absorb coastal collection volumes at scale for bottle-to-fiber processing lines.
- Polyethylene Terephthalate:Established mechanical recycling infrastructure enables melt-flow consistency suitable for textile fiber regeneration. California's SB 54 EPR framework redirects brand sustainability budgets toward certified PET procurement from ocean-bound collection zones.
- Polypropylene:Mixed-polymer feedstocks resist pyrolysis yield thresholds despite expanding chemical recycling capacity.
- Nylon:Fishing net recovery through depolymerization reactors enables automotive-grade purity for German OEM interior specifications.
Polyethylene Terephthalate leads on scale; Nylon leads on momentum.
Application:
End-use durability requirements separate commodity packaging from performance-grade durable goods procurement.
- Packaging:Mechanical recycling occupies the cost-efficient baseline for rigid containers and flexible films where brand sustainability credentials command procurement preference. REACH registration requirements lock in premium pricing for traceable ocean-bound resins across European supply chains.
- Textiles:Bottle-to-fiber processing lines for PET absorb coastal collection volumes at scale, lowering unit economics for apparel manufacturers integrating collection operations with finished goods manufacturing.
- Construction:Lower-grade applications trap value from mixed-polymer feedstocks that resist chemical recycling efficiency thresholds.
- Consumer Goods:Sporting goods manufacturers specify chemically recycled fishing net polymers where performance specifications resist mechanical degradation.
Packaging dominates volume throughput; Textiles expands most quickly.
Process Type:
Technology selection hinges on feedstock purity and target melt-flow specifications for downstream converters.
- Mechanical Recycling:Proprietary decontamination protocols for post-consumer ocean polyethylene sustain scale advantages in packaging segments. Energy-intensive washing protocols strain amortization for smaller processors.
- Chemical Recycling:Depolymerization reactors with integrated catalytic cracking enable nylon 6 regeneration at automotive-grade purity. Tier-1 suppliers in Germany and Japan adopt these systems under 36-month payback assumptions.
- Pyrolysis:Mixed-polymer ocean debris processing overtakes mechanical sorting as the dominant pathway, restructuring competitive positioning around yield optimization.
- Upcycling:Premium positioning in consumer-facing durable goods compresses supplier selection cycles around verified ocean plastic content percentages.
Mechanical Recycling anchors current capacity; Chemical Recycling gains share fastest.
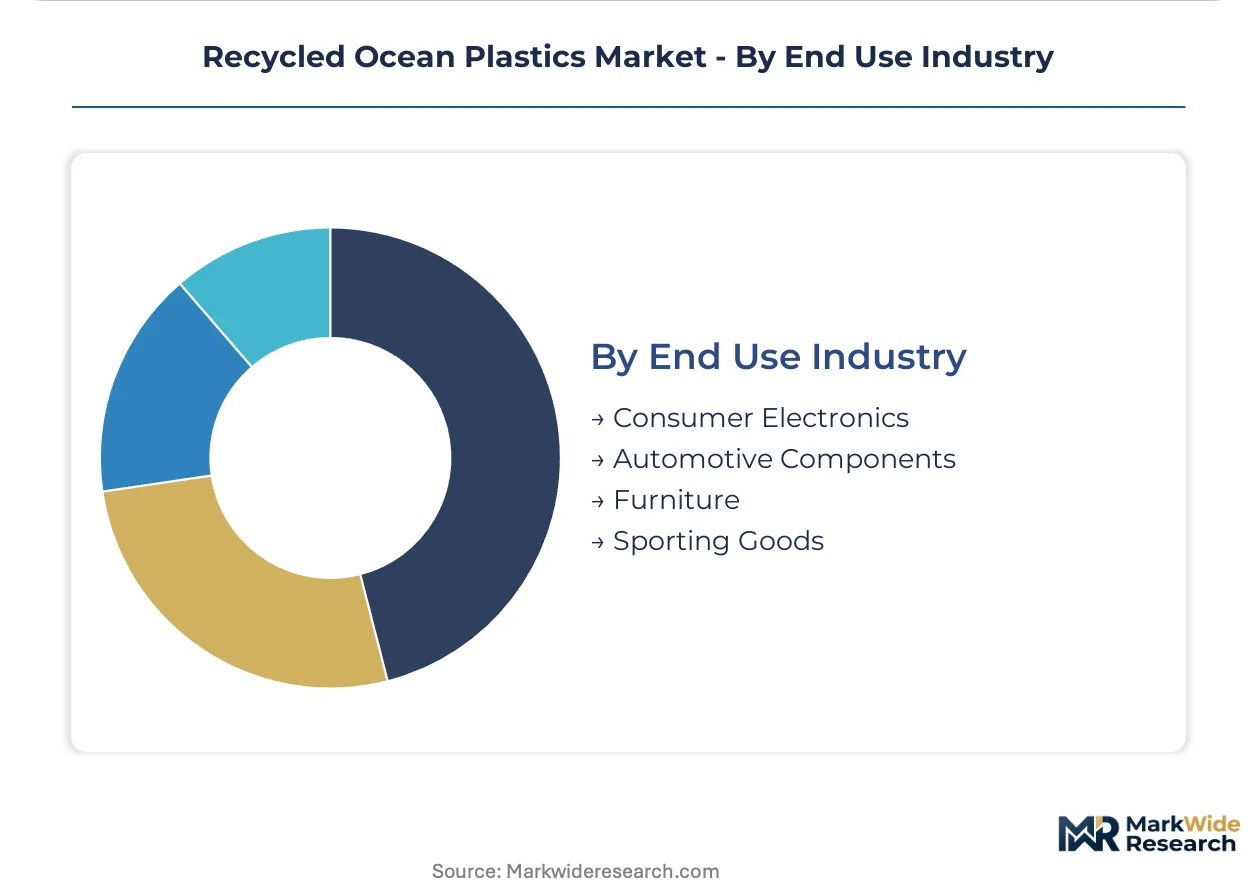
End Use Industry:
Sustainability scorecards and regulatory mandates reshape procurement criteria across durable goods manufacturing.
- Automotive Components:German OEM sustainability scorecards create captive demand for performance-grade recycled ocean nylon in seat fabrics and trim components. REACH registration requirements tighten documentation standards across European supply chains.
- Sporting Goods:Athletic footwear and equipment specifications resist mechanical degradation, enabling pricing power for chemically recycled fishing net polymers. Brand sustainability scorecards displace price-only procurement criteria.
- Consumer Electronics:EPR frameworks in California redirect manufacturer sustainability budgets toward certified resin networks rather than spot-market sourcing.
- Furniture:Construction segments absorb lower-grade pyrolysis outputs where performance specifications tolerate mixed-polymer feedstocks.
Automotive Components leads on premium pricing; Sporting Goods shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The recycled ocean plastics industry traces its commercial roots to coastal collection networks established in South America and Southeast Asia during the early 2010s, where fishing gear recovery and beach cleanup operations first achieved industrial scale.
Germany
Automotive OEM sustainability scorecards drive specification of recycled ocean nylon for seat fabrics and interior trim components. REACH registration requirements tighten documentation standards across European supply chains, mandating chain-of-custody verification from collection point to finished goods. The Stuttgart and Munich industrial corridors concentrate Tier-1 supplier adoption of depolymerization reactors for automotive-grade polymer regeneration.
United States
California's SB 54 packaging EPR framework redirects brand sustainability budgets toward certified ocean-bound resin procurement. The EPA's ocean debris program shapes federal compliance obligations for coastal collection operations. Los Angeles and San Diego anchor West Coast aggregation infrastructure, while New Jersey's port logistics support Atlantic seabed material intake.
China
GB standards integration progressively incorporates ocean plastic traceability into national circular economy mandates. The country's dual carbon goals accelerate chemical recycling capacity expansion for mixed-polymer feedstocks. Yangtze River Delta manufacturing clusters absorb certified resin imports for textile fiber regeneration, while Pearl River Delta converters develop proprietary decontamination protocols.
Indonesia
Monsoon-season collection volatility concentrates supply risk in Southeast Asian aggregation zones, compressing feedstock procurement timelines. Port logistics and coastal sorting capacity constraints tighten ahead of seasonal disruptions. Java and Sumatra fishing fleet operations generate nylon waste streams for depolymerization processing, though infrastructure bottlenecks limit year-round throughput consistency.
Brazil
Certified fishing gear recovery networks along South American coastlines supply traceable feedstock for automotive and sporting goods applications. National circular economy programs incorporate ocean plastic verification into export certification requirements. São Paulo's industrial corridor hosts mechanical recycling operations for post-consumer polyethylene, while coastal collection zones in Rio de Janeiro state aggregate material for international resin markets.
Recycled Ocean Plastics Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification credibility and feedstock traceability dimensions. The vendor base stratifies between collection-integrated operators and standalone processors, with mechanical recyclers occupying scale-driven positions while chemical recycling specialists capture performance-grade premiums. Three archetypes dominate: vertically integrated coastal collectors, proprietary technology licensors, and brand-aligned finished goods manufacturers. Competitive moves concentrate on strategic partnerships for feedstock security and capacity expansion in pyrolysis-based chemical recycling.
Within the collection-integrated tier, Bureo exemplifies geographic specialization through South American fishing gear recovery networks. Envision Plastics occupies a position among North American mechanical recyclers with proprietary decontamination capabilities. 4Ocean anchors brand-facing integration by combining collection operations with consumer goods manufacturing. These three represent distinct strategic postures: feedstock origination control, processing technology differentiation, and end-market brand equity capture.
| Leading Market Players |
|---|
| Bureo |
| Envision Plastics |
| 4Ocean |
| Plastic Bank |
| Tide Ocean SA |
| The Ocean Cleanup |
| Ocean Plastic Technologies |
| Veolia |
| Oceanworks |
| Others |
Cost & Logistics Intelligence
Certification-grade bifurcation between REACH-registered ocean-bound resins and uncertified coastal collections splits procurement economics across European automotive supply chains. German OEMs pay substantial premiums for traceable nylon 6 from fishing net depolymerization, while packaging converters in Southeast Asia source unverified polyethylene at commodity rates, compressing margins for mechanical recyclers lacking decontamination scale.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs ocean plastic procurement, with automotive-grade certified nylon commanding top rates, bottle-to-fiber PET occupying mid-tier contract positions, and mixed-polymer pyrolysis feedstocks trading at residual values. Price differentiation rests on chain-of-custody documentation depth and melt-flow consistency guarantees. Cost compression in mechanical recycling tiers is intensifying because energy-intensive salt removal and UV remediation erode processor margins. Packaging converters show highest price sensitivity, while German automotive Tier-1 suppliers absorb premiums for specification compliance.
Supply Chain Analysis
EU domestic-content mandates under the Single-Use Plastics Directive and California's SB 54 EPR framework are reshaping sourcing patterns toward certified collection networks. Feedstock aggregation concentrates in Indonesia, the Philippines, and Brazil, where coastal fishing fleets and monsoon-season debris generate volume. Raw material dependencies center on post-consumer fishing gear, coastal polyethylene recovery, and ocean-bound PET collection zones. Single-source vulnerability runs through Southeast Asian port logistics during monsoon disruptions. Distribution runs through pre-certified resin networks rather than spot-market sourcing for EU and California compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The recycled ocean plastics market compounds steadily as regulatory mandates harden procurement specifications across automotive and packaging sectors. Brand sustainability scorecards and EPR frameworks create durable demand tailwinds for certified feedstock providers.
For Market Incumbents: Cement feedstock security through long-term collection partnerships in Indonesian and Philippine coastal zones before monsoon infrastructure bottlenecks tighten. Expand depolymerization capacity in German industrial corridors to capture automotive nylon premiums. Chemical recycling yield improvements represent the critical defensive lever against mechanical recyclers achieving decontamination scale. For New Entrants and Emerging Players: Sporting goods distributors offer the most penetrable channel for chemically recycled fishing net polymers, as athletic footwear brands seek verified ocean plastic content for sustainability marketing. Target construction segment absorption of lower-grade pyrolysis outputs where performance tolerances permit mixed-polymer feedstocks. White-space exists in India's emerging BIS certification pathways before standards fully incorporate ocean plastic traceability. For Investors and Strategic Acquirers: Consolidation pressure builds where collection-integrated operators lack chemical recycling technology to capture automotive-grade premiums. Five-to-ten year viability favors processors with backward integration into coastal aggregation networks and proprietary depolymerization capabilities. Acquisition target archetype: South American fishing gear recovery specialists with untapped capacity expansion potential. Signal to watch: REACH audit timeline compression creating supply gaps for uncertified converters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Collection Networks | Secures traceable feedstock for REACH certification ahead of audit bottlenecks. |
| Depolymerization Capacity Expansion | Captures automotive nylon premiums from German OEM sustainability scorecards. |
| Long-term Supply Agreement | Locks in offtake from California SB 54 compliance-driven packaging converters. |
| Joint Venture | Combines Southeast Asian coastal logistics with European certification expertise. |
| Green Certification Program | Accelerates BIS and GB standards alignment for India and China market access. |
Research Approach
Multiple input streams — executive interviews, technical documentation, and trade data — were reconciled to construct this analysis. Primary fieldwork engaged collection network operators, mechanical recycling plant managers, automotive Tier-1 procurement leads, chemical recycling technology licensors, and brand sustainability officers at sporting goods manufacturers. Secondary validation drew from EPA ocean debris program filings, EU ECHA REACH registration databases, California SB 54 implementation guidance, Indonesian customs export records, and SEC disclosures from listed packaging converters. Bottom-up capacity modeling and top-down demand estimation were triangulated against verified installation data.
Data-stream reconciliation enabled segmentation across material type, process technology, end-use application, and geographic regulatory cluster. The analytical framework projected volume and value trajectories across the modeling period by linking collection infrastructure buildout timelines to downstream offtake commitments. CAGRs were derived from installed capacity ramp rates and brand procurement target disclosures. Industry-specific forecast inputs included monsoon-season collection volatility coefficients and depolymerization reactor yield curves from German and Japanese Tier-1 supplier adoption patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to pyrolysis yield breakthroughs, REACH audit timeline shifts, and monsoon pattern disruption from climate variability. Forecasts reflect documented assumptions regarding chemical recycling cost curves and EPR framework implementation pace. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Construction Waste Management Market
Waste Management & Pollution Control
GCC Pneumatic Waste Management System Market
Waste Management & Pollution Control
APAC Bio-Medical Waste Management Market
Waste Management & Pollution Control
Global Waste Disposal Equipment Market
Waste Management & Pollution Control
Medical Waste Management System Market
Waste Management & Pollution Control
Waste Recycling Services Market
Waste Management & Pollution Control
Industrial Solid Waste Management Market
Waste Management & Pollution Control
Asia-Pacific Industrial Waste Management Market
Waste Management & Pollution Control
Compostable Straws Market
Waste Management & Pollution Control
India Commercial Food Waste Decomposer Market
Waste Management & Pollution Control
India Waste Management Market
Waste Management & Pollution Control
Compostable and Biodegradable Refuse Bags Market
Waste Management & Pollution Control
Asia-Pacific Hazardous Waste Handling Automation Market
Waste Management & Pollution Control
Landfill Gas Market
Waste Management & Pollution Control
China Waste Management Market
Waste Management & Pollution Control
Saudi Arabia Medical Waste Management Market