
 Global Automated Marine Debris Collection Equipment Market | 2026-2036
Global Automated Marine Debris Collection Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automated Marine Debris Collection Equipment Market Analysis
Subscription-based fleet monitoring and predictive maintenance software is repositioning how automated marine debris collection equipment generates recurring revenue. The Ocean Cleanup leverages its river interception technology leadership to anchor long-term service contracts in major waterway systems. Water Witch sustains competitive positioning through specialized harbor-cleaning vessel manufacturing scaled across European ports. EFINOR Sea Cleaner differentiates via integrated oil-and-debris dual recovery systems that command premium service tiers.
Automated marine debris collection equipment encompasses self-propelled or moored systems engineered to extract floating and submerged waste from marine environments, typically incorporating conveyor mechanisms, filtration arrays, and debris compaction chambers rated for plastics, organic matter, and hydrocarbon contamination. Surface Collectors currently occupy the dominant product position due to lower capital thresholds and proven harbor deployment records, though Autonomous Vessels represent the fastest-expanding category as AI-enabled navigation reduces crew dependency. GPS Navigation technology leads installed bases across government fleet procurements, while Lidar Systems command higher-margin configurations in research institution deployments requiring precision bathymetry mapping.
The EU Marine Strategy Framework Directive and EPA Clean Water Act collectively shape equipment certification requirements, with CE marking and EPA vessel discharge standards determining market access for manufacturers serving transatlantic contracts. Japan's METI ocean innovation programs and South Korea's MFDS marine equipment safety protocols further segment procurement specifications across Northeast Asian tenders. Stakeholders must weigh regulatory divergence against platform standardization strategies when configuring multi-jurisdictional fleet deployments.
Market Dynamics
Autonomous navigation systems are compressing crew requirements and reshaping fleet economics across harbor authorities and coastal protection agencies worldwide. This technology shift is forcing incumbent manufacturers to reconfigure platform architectures around AI-enabled collision avoidance and remote monitoring capabilities.
Growth Catalysts
- EU Marine Strategy Framework Directive:Member state mandates for good environmental status in marine waters are accelerating procurement timelines for automated collection systems in Mediterranean and North Sea ports.
- Riverine plastic interception:Southeast Asian archipelagos experiencing severe harbor infrastructure strain from upstream waste influx are prioritizing autonomous interception deployments at major estuary systems.
- Lidar bathymetry integration:Research institutions are specifying precision mapping capabilities for submerged debris detection, expanding addressable applications beyond surface collection.
Market Restraints
- Specialized hull fabrication:Marine-grade aluminum and composite material costs fluctuate with energy-intensive smelting operations, constraining margin flexibility for vessel manufacturers.
- Sensor supply concentration:High-precision Lidar and multispectral imaging components concentrate among Japanese and German component suppliers, creating procurement vulnerability.
- EPA vessel discharge standards:Cross-jurisdictional certification friction between EPA requirements and CE marking protocols extends deployment timelines for transatlantic fleet operators.
Strategic Opportunities
- Indonesian coastal protection expansion:Procurement budgets at harbor authorities across Java and Sumatra remain underpenetrated by autonomous system providers relative to manual collection fleets.
- Subscription telemetry services:Predictive maintenance software and fleet monitoring platforms are creating recurring revenue streams that decouple manufacturer economics from unit sales cycles.
- Oil-and-debris dual recovery:Integrated hydrocarbon contamination handling capabilities command premium positioning in industrial port environments with combined pollution liabilities.
Industry Challenges
- Autonomous systems integration:Harbor authorities face operational complexity unifying AI-enabled collection platforms with legacy vessel management and berth scheduling systems.
- Marine robotics certification:Divergent safety protocols between Japan's METI ocean innovation programs and South Korea's MFDS marine equipment standards fragment R&D investment requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automated Marine Debris Collection Equipment Market |
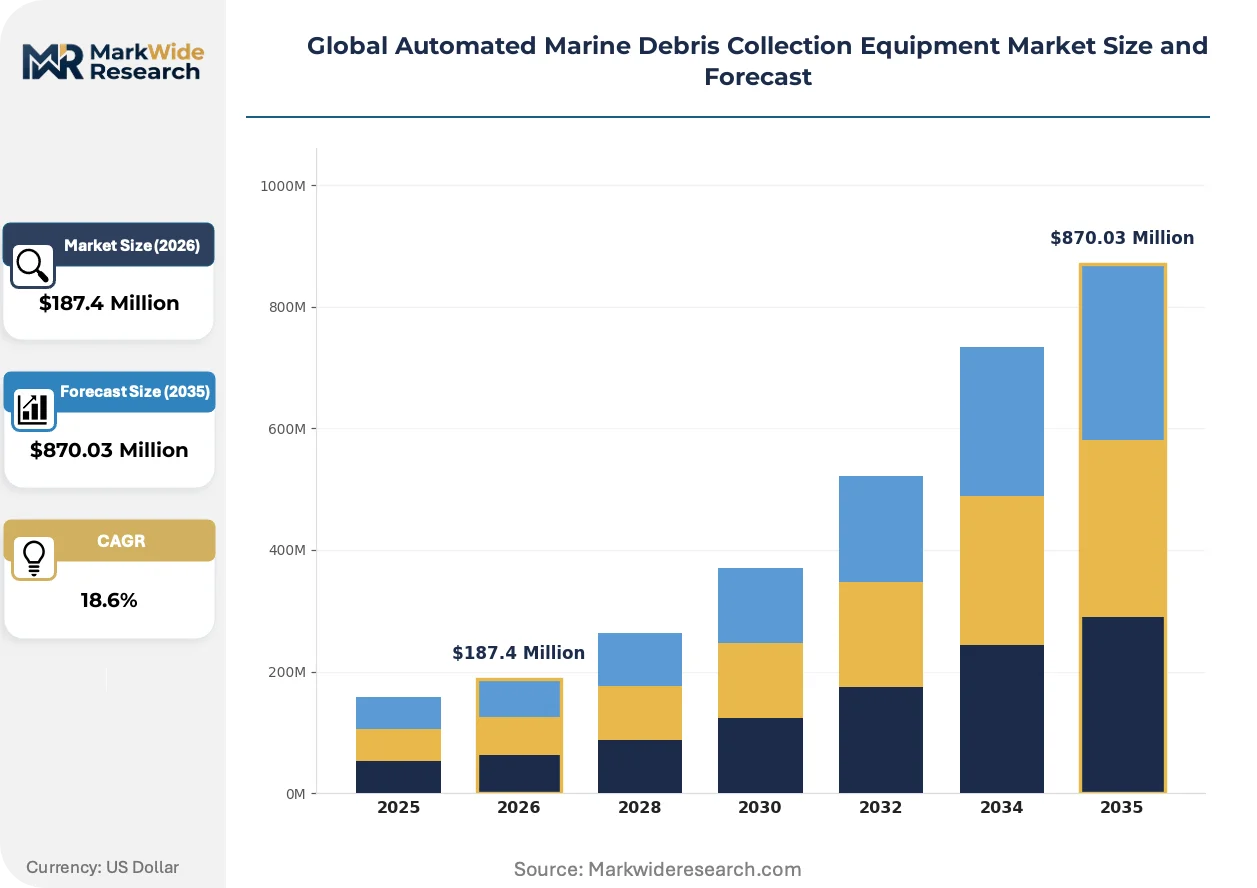
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surface Collectors, Underwater Robots, Floating Barriers, Autonomous Vessels Technology: AI-Enabled, GPS Navigation, Lidar Systems, Remote Monitoring End User: Government Agencies, Environmental NGOs, Coastal Protection, Research Institutions Deployment: Inshore, Offshore, Nearshore, Harbors |
| Companies Covered | Water Witch, Seabin Project, Mavi Deniz, Elastec, DESMI, The Ocean Cleanup, WasteShark, EFINOR Sea Cleaner, IADYS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automated Marine Debris Collection Equipment Market Emerging Trajectories
Convergence of autonomous navigation with real-time debris classification algorithms is compressing response times and expanding operational windows for collection fleets. Equipment manufacturers are repositioning around software-defined service architectures that extend platform lifecycles through over-the-air capability upgrades.
Machine vision-based waste classification is expanding into operational workflows across automated marine debris collection platforms. Harbor authorities in Rotterdam and Singapore are specifying real-time polymer identification capabilities to optimize downstream recycling segregation. This technology convergence is compressing manual sorting requirements and enabling continuous-operation deployments without shore-side intervention.
REACH chemical registration requirements and RoHS substance restrictions are tightening material specifications for hull coatings and hydraulic fluids in European deployments. Manufacturers serving EU member states are reformulating corrosion protection systems to eliminate restricted heavy metal compounds. The F-Gas Regulation phase-down is simultaneously accelerating adoption of electric propulsion architectures in harbor-cleaning vessel fleets.
Long-term service contracting is displacing traditional equipment purchase models among municipal harbor authorities and coastal protection agencies. Rotterdam and Jakarta port operators are structuring ten-year availability agreements that bundle platform provision with crew training and maintenance execution. This procurement evolution is most visible in Southeast Asian markets where capital budget constraints favor operational expenditure structures.
Global Automated Marine Debris Collection Equipment Market Segmentation
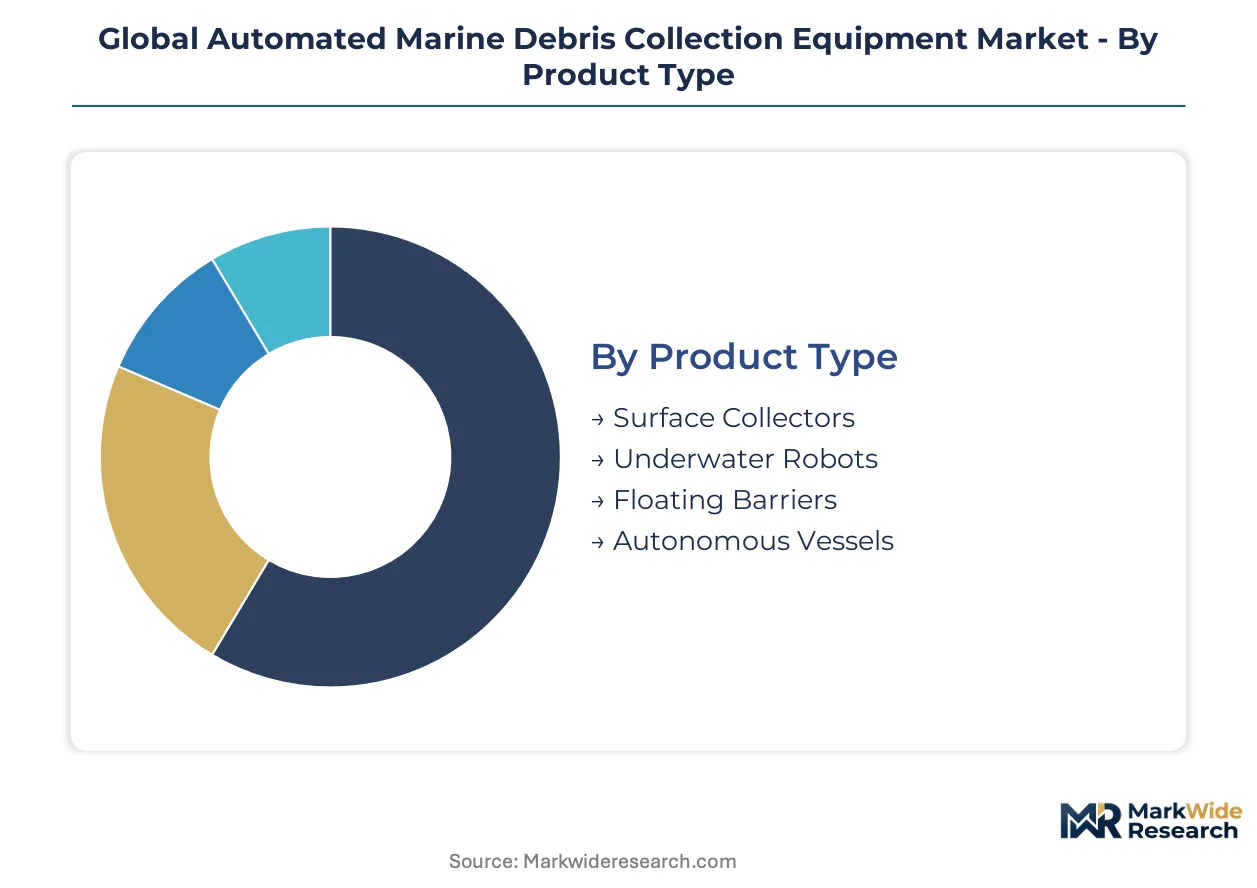
Equipment segmentation in the automated marine debris collection market determines procurement specifications, maintenance protocols, and fleet replacement cycles. Harbor authorities and coastal agencies configure multi-platform deployments around specific debris profiles, water depth requirements, and operational autonomy levels.
Product Type:
Replacement cycles vary dramatically across product categories, with surface-deployed systems requiring more frequent hull refurbishment than fully submerged platforms.
- Surface Collectors:Conveyor-based systems with filtration arrays and compaction chambers engineered for plastics and organic matter extraction. Demand concentrates in Mediterranean harbors and Southeast Asian estuaries where EU Marine Strategy Framework Directive compliance deadlines and riverine plastic influx create overlapping procurement pressures. Lower capital thresholds accelerate fleet refresh cycles compared to autonomous alternatives.
- Autonomous Vessels:Self-propelled platforms integrating AI-enabled collision avoidance with remote monitoring capabilities. Research institutions in Japan and South Korea specify these systems for precision bathymetry mapping applications, while Indonesian coastal protection agencies prioritize them for reducing crew dependency in high-volume collection zones.
- Underwater Robots:Tethered or untethered systems designed for submerged debris detection and extraction in restricted visibility conditions.
- Floating Barriers:Passive or semi-active moored systems intercepting surface debris through current-driven concentration mechanisms.
Surface Collectors sits at the top of the volume ranking, with Autonomous Vessels climbing the fastest.
Technology:
Technology selection directly shapes operational expenditure profiles, with premium sensing configurations commanding extended service contracts and telemetry subscriptions.
- GPS Navigation:Satellite-based positioning systems forming the installed base across government fleet procurements worldwide. CE marking and EPA vessel discharge standards have standardized integration protocols, reducing deployment friction for transatlantic operators.
- Lidar Systems:Precision bathymetry mapping technology specified by research institutions requiring submerged debris detection capabilities. Japanese and German component suppliers concentrate supply, creating procurement vulnerability that extends lead times for high-margin configurations.
- AI-Enabled:Real-time debris classification algorithms compressing response times and enabling continuous-operation deployments without shore-side intervention.
- Remote Monitoring:Telemetry infrastructure supporting predictive maintenance software and fleet optimization platforms.
GPS Navigation dominates current procurement volumes, though Lidar Systems is expanding most quickly in research-oriented deployments.
End User:
Customer type segmentation reveals divergent purchasing authority structures, with government agencies favoring capital expenditure models while environmental NGOs negotiate operational expenditure arrangements.
- Government Agencies:Municipal harbor authorities and national coastal protection bodies with multi-year procurement budgets. Rotterdam and Jakarta port operators structure long-term availability agreements bundling platform provision with crew training.
- Environmental NGOs:Mission-driven organizations prioritizing river interception deployments at major estuary systems. These stakeholders favor subscription-based fleet monitoring and software-defined service architectures that reduce upfront capital requirements.
- Coastal Protection:Specialized agencies in Indonesia and the Philippines expanding autonomous collection system procurement.
- Research Institutions:Academic and governmental laboratories specifying precision sensing capabilities for environmental monitoring applications.
Government Agencies account for the largest procurement volumes, with Environmental NGOs gaining share fastest through alternative financing structures.
Deployment:
Deployment environment dictates hull specification, sensor payload, and regulatory certification requirements, with inshore operations facing the most complex multi-jurisdictional compliance burdens.
- Harbors:Confined water deployments requiring specialized maneuvering capabilities and berth scheduling integration. Water Witch and EFINOR Sea Cleaner have scaled manufacturing across European ports, with Rotterdam specifying real-time polymer identification for downstream recycling segregation.
- Nearshore:Coastal zone operations balancing wave exposure with proximity to shore-based maintenance facilities. The Ocean Cleanup anchors long-term service contracts in major waterway systems through this deployment mode.
- Inshore:Protected water deployments including estuaries, bays, and river mouths with concentrated debris accumulation.
- Offshore:Open ocean operations requiring enhanced seakeeping and extended autonomous endurance.
Harbors leads deployment volumes, with Nearshore showing the steepest expansion trajectory as riverine interception priorities intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between the EU Marine Strategy Framework Directive and EPA vessel discharge standards is creating compliance-cost arbitrage, pushing manufacturers to optimize production footprints across jurisdictions with favorable certification reciprocity.
Indonesia
Coastal protection agencies across Java and Sumatra are accelerating procurement of autonomous collection systems as riverine plastic influx overwhelms manual fleet capacity. The country's national maritime regulator enforces equipment safety protocols aligned with IMO conventions. Jakarta port operators structure long-term availability agreements bundling platform provision with crew training and predictive maintenance subscriptions.
Netherlands
Rotterdam harbor authorities specify real-time polymer identification capabilities to optimize downstream recycling segregation, compressing manual sorting requirements. REACH chemical registration requirements and RoHS substance restrictions tighten material specifications for hull coatings and hydraulic fluids. The Randstad industrial cluster hosts specialized vessel fabricators scaling manufacturing across European ports with CE marking compliance.
United States
EPA Clean Water Act vessel discharge standards shape equipment certification requirements for manufacturers serving transatlantic contracts, extending deployment timelines where CE marking protocols diverge. Municipal harbor authorities favor capital expenditure procurement models with multi-year fleet refresh cycles. The Pacific Northwest and Gulf Coast concentrate demand for oil-and-debris dual recovery capabilities in industrial port environments.
Japan
METI ocean innovation programs fund precision sensing capabilities for submerged debris detection applications at research institutions. National safety protocols fragment R&D investment requirements relative to South Korean and European standards. The Kanto region around Tokyo anchors government fleet procurements specifying GPS navigation systems with standardized integration protocols.
South Korea
MFDS marine equipment safety protocols segment procurement specifications for autonomous navigation platforms in Northeast Asian tenders. Research institutions specify Lidar bathymetry integration for precision mapping applications beyond surface collection. The Busan-Ulsan industrial corridor concentrates vessel fabrication capacity serving domestic coastal protection agency deployments.
Global Automated Marine Debris Collection Equipment Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated system providers commanding premium positioning in harbor deployments while component fabricators serve retrofit markets. The vendor base concentrates among European and East Asian engineering houses with established maritime certification track records. Two strategic archetypes dominate: autonomous navigation specialists repositioning around AI-enabled service architectures, and legacy vessel manufacturers retrofitting conventional hulls with debris extraction mechanisms. Competitive moves center on long-term service contracting to displace equipment purchase models, and sensor technology licensing to secure component supply positions.
Among autonomous system specialists, The Ocean Cleanup exemplifies the river interception technology leader anchoring long-term service contracts in major waterway systems. Water Witch occupies a position within the specialized harbor-cleaning vessel tier, with manufacturing scaled across European ports. EFINOR Sea Cleaner represents the integrated dual-recovery archetype, commanding premium service tiers through combined oil-and-debris handling capabilities.
| Leading Market Players |
|---|
| Water Witch |
| Seabin Project |
| Mavi Deniz |
| Elastec |
| DESMI |
| The Ocean Cleanup |
| WasteShark |
| EFINOR Sea Cleaner |
| IADYS |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between CE-marked harbor systems and uncertified coastal units splits procurement budgets and supplier sourcing strategies across European and Southeast Asian deployments. Premium-tier manufacturers command sustained margins through integrated telemetry subscriptions, while commodity fabricators compete on hull-delivery speed for municipal fleets with constrained capital cycles.
Pricing Analysis
Distributor margins of 12-18% layer atop manufacturer pricing for government fleet procurements routed through maritime equipment dealers in Rotterdam and Singapore. Three-tier pricing structure across premium, standard, and economy levels tracks autonomy sophistication, with AI-enabled platforms capturing 40-60% uplifts over conveyor-based alternatives. Cost compression in standard-tier hull fabrication intensifies as Chinese aluminum suppliers expand European port delivery. Environmental NGOs exhibit highest price sensitivity, favoring operational-expenditure service contracts over capital-intensive platform purchases.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and German Lidar component suppliers, where precision bathymetry modules concentrate among three engineering houses. Marine-grade aluminum draws from Norwegian smelters and Chinese rolling mills, while composite hull fabrics hinge on South Korean carbon-fiber producers. Tariff exposure runs through EU-China trade friction on processed aluminum shapes. Distribution runs through specialized maritime equipment distributors serving harbor authorities, with direct OEM relationships dominating research institution procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory arbitrage between EPA vessel discharge standards and CE marking protocols creates compliance-cost differentials that favor European production footprints for transatlantic fleet operators. Manufacturers can exploit this divergence by anchoring final assembly in jurisdictions with favorable certification reciprocity.
For Market Incumbents: Extend predictive maintenance software capabilities to capture recurring revenue streams that decouple economics from unit sales cycles. Deepen backward integration into marine-grade aluminum supply through long-term offtake agreements with Norwegian smelters, defending margin position against Chinese import volatility. Fortify certification moats by accelerating METI and MFDS dual-compliance investments ahead of Northeast Asian tender specifications. For New Entrants and Emerging Players: Indonesian coastal protection agencies represent an underserved buyer archetype with procurement budgets scaling faster than autonomous system penetration. Municipal harbor authorities across Java and Sumatra offer white-space entry through ten-year availability agreements that bundle crew training with platform provision. Nearshore river interception deployments at major Southeast Asian estuaries provide the most penetrable application segment. Lead with subscription-telemetry pricing to bypass capital-budget constraints that stall equipment purchase decisions. For Investors and Strategic Acquirers: Consolidation pressure builds where sensor supply concentration fragments R&D investment requirements across Japanese, German, and Korean certification standards. Long-term viability centers on platform-agnostic software architectures that extend lifecycle value through over-the-air capability upgrades. Acquisition targets should display integrated oil-and-debris dual recovery capabilities or established CE-EPA dual certification track records. Watch for inflection where Indonesian procurement shifts from manual fleets to autonomous systems at harbor authorities with documented crew-shortage pain points.| Strategic Initiative | Industry Significance |
|---|---|
| Long-Term Service Contracting | Rotterdam and Jakarta port operators now structure ten-year availability agreements bundling maintenance with platform provision. |
| Sensor Technology Licensing | Japanese Lidar suppliers secure component supply positions through exclusive research institution partnerships requiring precision bathymetry. |
| Dual-Certification Investment | CE marking and EPA vessel discharge standard compliance unlocks transatlantic fleet procurement for integrated system providers. |
| Backward Integration into Aluminum Supply | Norwegian smelter offtake agreements insulate hull fabricators from energy-intensive production cost volatility. |
| AI-Enabled Navigation Platform Launch | Autonomous collision avoidance capabilities reduce crew dependency for Indonesian coastal protection agencies facing labor constraints. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with harbor authorities in Rotterdam, Jakarta, and Busan with secondary validation across IMO convention databases and EU Marine Strategy Framework Directive implementation reports. Harbor procurement directors, coastal protection agency engineers, maritime equipment distributors, vessel fabricator operations heads, and environmental NGO program managers contributed structured intelligence. Customs trade data on marine-grade aluminum shipments, SEC filings from listed industrial equipment manufacturers, and national tender databases from Indonesia and the Philippines anchored supply-side calibration. Bottom-up platform deployment counts triangulated against top-down market value estimates.
Comparable-period anchoring linked projection assumptions to historical fleet procurement cycles observed across Mediterranean and Southeast Asian harbor authorities. Segmentation dimensions modeled encompassed product type, navigation technology tier, end-user purchasing authority structure, and deployment environment classification. CAGRs derived from logistic diffusion curves fitted to autonomous system adoption patterns in government fleets, with cross-validation against aluminum price elasticity and sensor component lead time trajectories. Industry-specific inputs included REACH chemical registration compliance cost curves and F-Gas Regulation phase-down timelines affecting electric propulsion adoption.
Underlying measurement precision varies by segment; government agency procurement volumes carry tighter precision than environmental NGO subscription forecasts given tender transparency differentials. Forecasts reflect documented assumptions on regulatory enforcement intensity and sensor supply chain normalization. Commodity aluminum volatility, divergent safety protocol fragmentation between METI and MFDS standards, and Indonesian fiscal capacity constraints represent specific revision risks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Waste Recycling Services Market
Waste Management & Pollution Control
Automated Waste Collection System (AWCS) Market
Waste Management & Pollution Control
UAE Industrial Waste Management Market
Waste Management & Pollution Control
Incinerator Market
Waste Management & Pollution Control
Metal Recycling Equipment Market
Waste Management & Pollution Control
North America Solid Waste Management Market
Waste Management & Pollution Control
Compostable Straws Market
Waste Management & Pollution Control
Scrap Metal Recycling Market
Waste Management & Pollution Control
India Recycling Market
Waste Management & Pollution Control
Reusable Sediment Control Wattles Market
Waste Management & Pollution Control
Global Pharmaceutical Waste Management Market
Waste Management & Pollution Control
Waste Sorting Equipment Market
Waste Management & Pollution Control
UAE Biomedical Waste Management Market
Waste Management & Pollution Control
Landfill Gas Market
Waste Management & Pollution Control
APAC Bio-Medical Waste Management Market
Waste Management & Pollution Control
Waste Compactor Bins Market