
 GCC Industrial Waste Management Market | 2026-2036
GCC Industrial Waste Management Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Industrial Waste Management Market Insights
Zero-landfill certification is unwinding competitive dynamics across the GCC industrial waste management landscape. SUEZ Middle East Recycling LLC leverages its integrated collection-to-recycling infrastructure across Saudi Arabia and the UAE. EnviroServe anchors hazardous waste treatment capacity in the region's oil and gas corridors. Bee'ah sustains its dominance through exclusive municipal and industrial contracts in Sharjah and expanding emirate-level partnerships.
GCC industrial waste management encompasses the systematic handling, treatment, and disposal of manufacturing byproducts, petroleum residues, chemical sludges, and electronic discards generated across the Arabian Peninsula's industrial zones, typically requiring segregation protocols for heavy metal content above 5 ppm and thermal treatment thresholds for halogenated compounds. The service generates commercial value through resource recovery, regulatory compliance, and liability mitigation for petrochemical, pharmaceutical, and construction operators. Hazardous waste commands premium pricing due to specialized incineration and secure landfill requirements, while recycling services represent the fastest-expanding margin pool as circular economy mandates intensify. Treatment technologies remain structurally constrained by limited domestic bioremediation capacity, creating import dependence for advanced microbial degradation systems.
Saudi Arabia's Presidency of State Security enforces hazardous materials transport protocols alongside the Saudi Standards, Metrology and Quality Organization's industrial effluent discharge limits. The UAE's Ministry of Climate Change and Environment implements Extended Producer Responsibility frameworks that mandate manufacturer accountability for end-of-life product recovery. Stakeholders must monitor how Bahrain's National Oil and Gas Authority and Oman's Ministry of Environment and Climate Affairs coordinate cross-border waste movement regulations as Gulf economic integration deepens.
Market Dynamics
Zero-landfill mandates from the UAE's Ministry of Climate Change and Environment are compressing disposal options across the GCC's petrochemical corridors. Operators must now secure thermal treatment capacity or face operational shutdowns, fundamentally restructuring competitive positioning around incineration infrastructure ownership.
Growth Catalysts
- Extended Producer Responsibility frameworks:The UAE's MOCCAE mandates manufacturer accountability for end-of-life recovery, forcing industrial clusters to contract integrated waste services rather than rely on fragmented disposal.
- Jubail Industrial City concentration:Saudi Arabia's largest manufacturing cluster generates sufficient hazardous waste volumes to justify dedicated treatment zones, attracting specialized service providers with economies of scale.
- Waste-to-energy partnerships:Saudi Aramco's petrochemical complexes are embedding circular energy recovery into operational planning, creating captive demand for high-calorific industrial residue processing.
Market Restraints
- Bioremediation import dependence:Limited domestic microbial degradation capacity forces GCC operators to source advanced biological treatment systems from European suppliers, inflating project timelines.
- Halogenated compound thresholds:Thermal treatment requirements for chlorinated and fluorinated waste streams exceed local incineration capabilities, necessitating costly cross-border movement to specialized facilities.
- Secure landfill scarcity:Heavy metal content above 5 ppm requires engineered cell construction that few domestic sites can accommodate, concentrating hazardous disposal options in Bahrain and Oman.
Strategic Opportunities
- Kuwait's underpenetrated manufacturing base:The country's emerging pharmaceutical and food processing sectors lack established hazardous waste partnerships, creating first-mover advantages for integrated service providers.
- Electronic waste recovery:Precious metal reclamation from industrial e-waste remains undeveloped across the GCC, with current practices focusing on bulk shredding rather than component-level separation.
- Cross-border regulatory coordination:Bahrain's National Oil and Gas Authority and Oman's Ministry of Environment are harmonizing waste movement protocols, simplifying multi-country service contracts for regional operators.
Industry Challenges
- Segregation protocol enforcement:Industrial facilities struggle to maintain source separation for heavy metal streams, contaminating recyclable fractions and triggering Saudi Standards, Metrology and Quality Organization penalties.
- Specialized technician scarcity:Hazardous materials handling certification programs remain underdeveloped across GCC technical institutes, constraining operational expansion for treatment facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Industrial Waste Management Market |
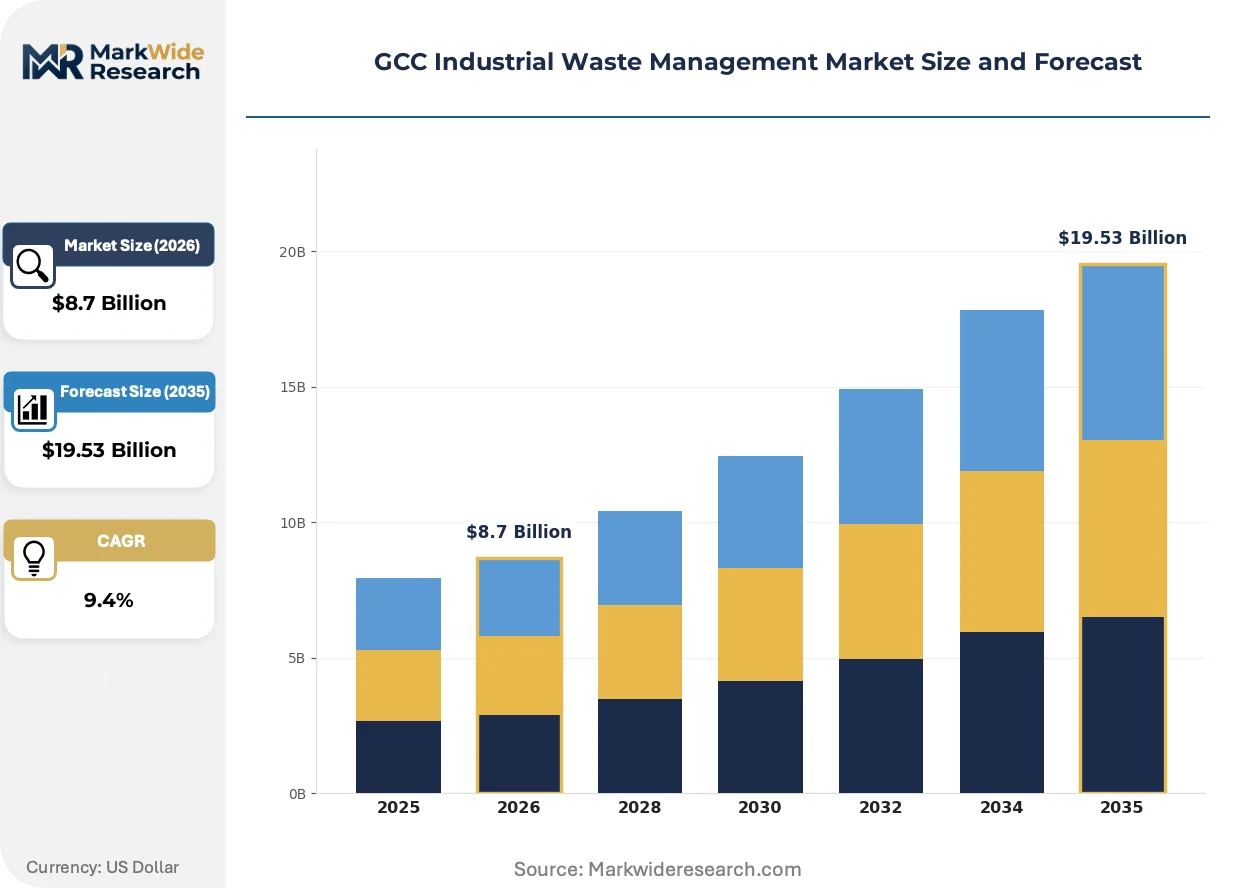
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Waste Type: Hazardous Waste, Non-Hazardous Waste, Biohazardous Waste, E-Waste Service Type: Collection, Treatment, Disposal, Recycling Industry Sector: Manufacturing, Construction, Oil & Gas, Pharmaceuticals Technology: Incineration, Landfilling, Bioremediation, Composting |
| Companies Covered | SUEZ Middle East Recycling LLC, EnviroServe, Averda, Saudi Investment Recycling Company, Green Mountains, Bee'ah, Veolia, Dulsco, Tadweer, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Industrial Waste Management Market Trends and Innovations
Advanced thermal treatment technologies are compressing residue volumes while extracting energy value, fundamentally altering the economics of hazardous waste acceptance. These developments intersect with tightening landfill diversion targets and evolving buyer procurement criteria.
Plasma gasification is fragmenting the competitive landscape for high-calorific industrial waste streams. This technology converts petroleum residues and chemical sludges into synthetic gas at temperatures exceeding 3,000°C, eliminating residual ash. Saudi Aramco's expanding petrochemical complexes are piloting integrated plasma units for process waste, bypassing traditional incineration providers. The technology is fragmenting service contracts by enabling on-site treatment rather than centralized facility dependence.
REACH-equivalent chemical registration requirements are propagating through GCC regulatory harmonization initiatives. The UAE's MOCCAE and Saudi Arabia's SFDA are aligning industrial effluent standards with European hazard classification frameworks, forcing manufacturers to requalify waste streams. Petrochemical operators in Jubail and Ruwais face the steepest compliance burdens, accelerating investment in real-time effluent monitoring systems.
Long-term service contracts are displacing spot-market waste disposal across the GCC's industrial zones. Petrochemical and pharmaceutical operators are consolidating vendor relationships to secure guaranteed thermal treatment capacity amid tightening landfill restrictions. Procurement teams now prioritize incineration availability over per-tonne pricing, with Saudi Arabia's manufacturing clusters leading this contractual shift. The behavior is most pronounced in integrated industrial cities where operational continuity depends on uninterrupted waste acceptance.
GCC Industrial Waste Management Market Segmentation
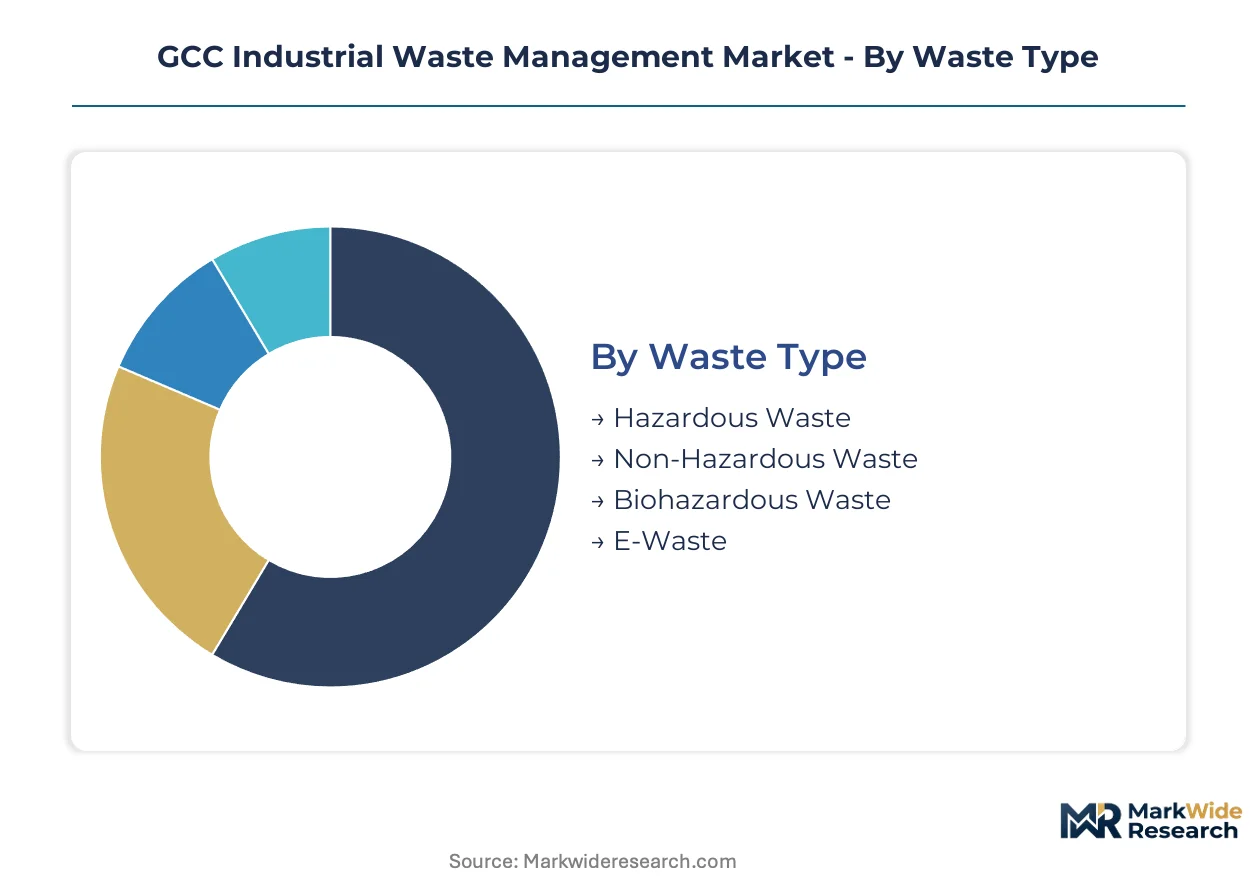
Waste stream composition and treatment complexity vary dramatically across GCC industrial zones, with hazardous fractions commanding specialized handling protocols. Regulatory thresholds for heavy metal content and halogenated compounds create sharp pricing differentials between segments.
Waste Type:
MOCCAE's landfill diversion mandates and Saudi Standards' effluent discharge limits apply differential stringency based on hazard classification, segmenting procurement behavior across industrial clusters.
- Hazardous Waste:Petroleum residues, chemical sludges, and heavy metal-laden streams exceeding 5 ppm concentration require thermal treatment or secure engineered landfilling. Jubail Industrial City's petrochemical operators generate sufficient volumes to justify dedicated incineration infrastructure, though halogenated compound thresholds often necessitate cross-border movement to Bahrain or Oman.
- Non-Hazardous Waste:Manufacturing byproducts and construction debris with contaminant levels below regulatory thresholds. The UAE's zero-landfill certification programs are compressing disposal options, forcing operators toward recycling partnerships rather than conventional landfill contracts.
- Biohazardous Waste:Pharmaceutical production residues and medical-industrial streams requiring sterilization protocols. Saudi Arabia's SFDA enforces containment standards that exceed general industrial effluent regulations.
- E-Waste:Electronic discards from industrial control systems and manufacturing equipment. Precious metal reclamation remains underdeveloped across the GCC, with current practices emphasizing bulk shredding over component-level separation.
Hazardous Waste handles the majority of throughput; E-Waste is the fastest mover on share.
Service Type:
Customer procurement patterns are shifting from spot-market transactions toward integrated long-term contracts as landfill scarcity tightens.
- Collection:Segregation protocol enforcement at source determines downstream treatment economics. SUEZ Middle East Recycling LLC leverages integrated collection infrastructure across Saudi Arabia and the UAE to capture recurring revenue streams.
- Treatment:Thermal processing, chemical neutralization, and biological degradation of hazardous streams. Plasma gasification pilots at Saudi Aramco complexes are fragmenting traditional incineration demand by enabling on-site processing.
- Disposal:Secure landfill placement for non-recoverable residues. Engineered cell scarcity concentrates viable options in Bahrain and Oman, creating cross-border logistics dependencies.
- Recycling:Resource recovery from metallic, plastic, and organic fractions. Circular economy mandates from MOCCAE are accelerating margin expansion in this segment faster than thermal treatment.
Collection anchors contract duration; Recycling climbs the fastest on share.
Industry Sector:
Volume concentration and waste complexity diverge sharply across end-use verticals, with petrochemical corridors driving infrastructure investment.
- Oil & Gas:Drilling muds, production chemicals, and refinery residues dominate hazardous waste generation. Saudi Aramco's waste-to-energy partnerships are embedding circular recovery into operational planning across the Eastern Province.
- Manufacturing:Metalworking fluids, coating wastes, and packaging discards from Jubail and Ruwais industrial cities. Extended Producer Responsibility frameworks are forcing integrated service procurement rather than fragmented disposal.
- Construction:Demolition debris, concrete washout, and treated wood waste. Non-hazardous classification allows simpler handling protocols, though aggregate recovery rates remain below European benchmarks.
- Pharmaceuticals:Active pharmaceutical ingredient residues and solvent streams requiring specialized incineration. Kuwait's emerging pharmaceutical base lacks established hazardous waste partnerships, creating first-mover opportunities.
Oil & Gas handles the majority of throughput; Pharmaceuticals gains share fastest.
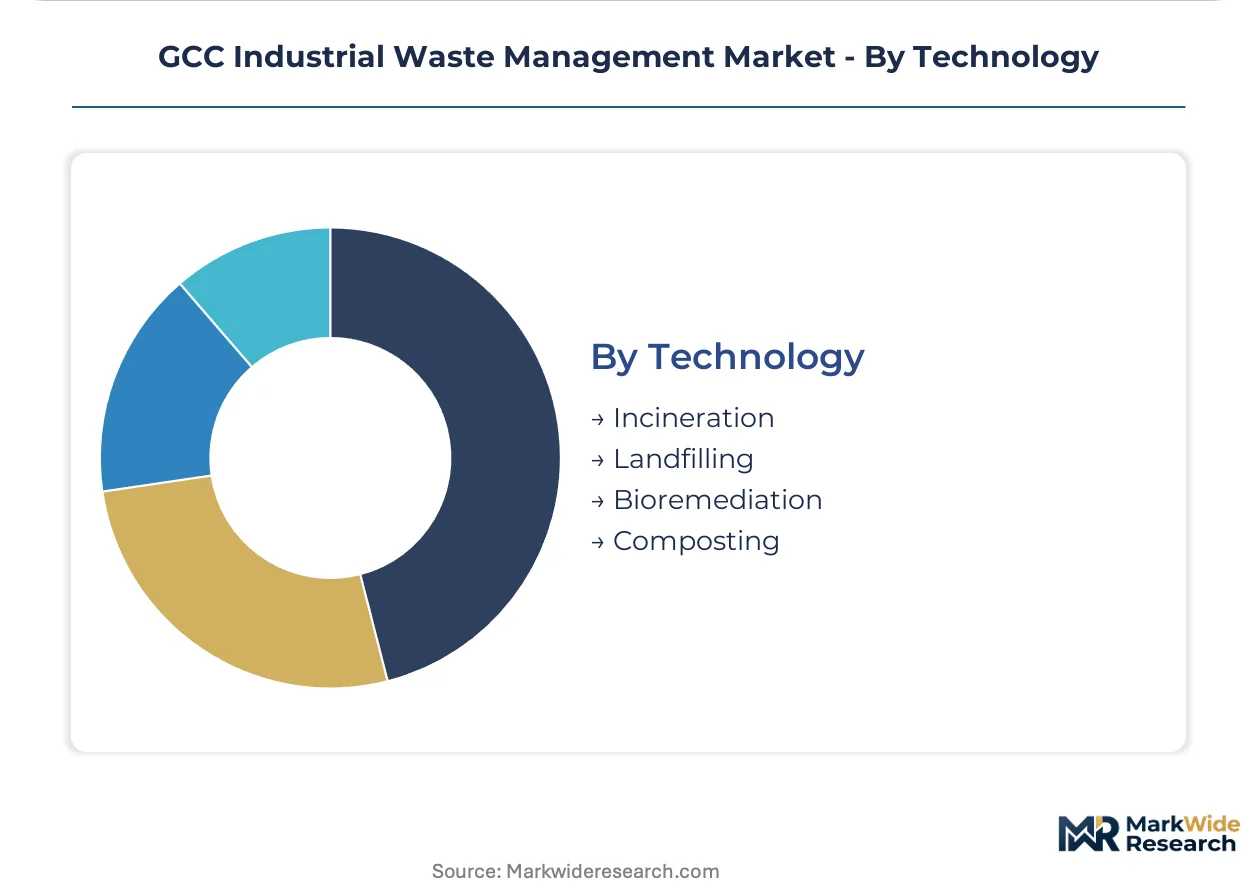
Technology:
Domestic capability gaps in biological treatment systems create import dependence that inflates project timelines and capital costs.
- Incineration:High-temperature thermal destruction of hazardous organic compounds. Local capacity constraints for halogenated waste streams force costly movement to specialized regional facilities.
- Landfilling:Engineered cell construction for heavy metal containment above 5 ppm. Secure site scarcity concentrates viable options, with Bahrain and Oman hosting the GCC's limited compliant capacity.
- Bioremediation:Microbial degradation of petroleum hydrocarbons and organic contaminants. Limited domestic expertise forces GCC operators to source advanced systems from European suppliers.
- Composting:Aerobic decomposition of non-hazardous organic industrial residues. Lower regulatory barriers and simpler infrastructure requirements support faster deployment across manufacturing zones.
Incineration handles the majority of throughput; Bioremediation expands most quickly on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Secure landfill capacity concentrates in Bahrain and Oman while thermal treatment infrastructure clusters around Saudi Arabia's Eastern Province and the UAE's industrial corridors. This geographic asymmetry shapes cross-border logistics dependencies and regulatory coordination imperatives across the Arabian Peninsula.
Saudi Arabia
Saudi Aramco's petrochemical complexes in the Eastern Province generate high-calorific residues that justify dedicated waste-to-energy partnerships. The Saudi Standards, Metrology and Quality Organization enforces industrial effluent discharge limits that exceed general municipal standards. Jubail Industrial City anchors the kingdom's largest manufacturing cluster, where integrated waste management zones attract specialized service providers through economies of scale.
United Arab Emirates
The UAE's Ministry of Climate Change and Environment mandates zero-landfill certification for industrial facilities, compressing disposal options toward thermal treatment. Extended Producer Responsibility frameworks hold manufacturers accountable for end-of-life product recovery, forcing integrated service procurement. Ruwais Industrial City in Abu Dhabi and Jebel Ali in Dubai concentrate petrochemical and manufacturing waste generation, driving demand for guaranteed incineration capacity.
Bahrain
The National Oil and Gas Authority coordinates hazardous waste movement protocols with neighboring Gulf states, simplifying multi-country service contracts. Bahrain hosts engineered secure landfill cells that accommodate heavy metal content above regulatory thresholds, attracting cross-border disposal from Saudi Arabia and Kuwait. The Sitra industrial zone processes petroleum residues that exceed local thermal treatment capabilities, necessitating regional facility partnerships.
Oman
Oman's Ministry of Environment and Climate Affairs harmonizes waste transport regulations with Bahrain and the UAE under Gulf economic integration initiatives. The Sultanate's limited domestic manufacturing base generates insufficient volumes to justify dedicated hazardous treatment infrastructure. Sohar Industrial Port and Duqm Special Economic Zone depend on imported bioremediation systems and cross-border thermal treatment partnerships for complex waste streams.
Kuwait
Kuwait's emerging pharmaceutical and food processing sectors lack established hazardous waste partnerships, creating first-mover advantages for integrated service providers. The country's national environmental regulator maintains containment standards for biohazardous streams that exceed general industrial effluent regulations. Shuaiba Industrial Area generates growing volumes of solvent residues and active pharmaceutical ingredient waste that currently move to Bahraini or Saudi treatment facilities.
GCC Industrial Waste Management Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the GCC industrial waste management landscape. Integrated multinational operators command thermal treatment infrastructure and secure landfill access, while regional specialists compete on collection network density and regulatory navigation. Three archetypes dominate: petrochemical-anchored service providers with captive energy recovery partnerships, municipal-contract operators leveraging exclusive emirate-level relationships, and cross-border logistics specialists managing halogenated compound movement to Bahraini and Omani facilities. Competitive dynamics center on long-term contract consolidation and incineration capacity expansion rather than per-tonne pricing competition.
Within the multinational tier, SUEZ Middle East Recycling LLC and Veolia occupy positions anchored by integrated collection-to-recycling infrastructure across Saudi Arabia and the UAE. EnviroServe represents the specialized hazardous treatment archetype, with positioning concentrated in oil and gas corridors. Bee'ah exemplifies the municipal-contract model through exclusive industrial and waste management relationships in Sharjah and expanding emirate-level partnerships. These three anchors illustrate how competitive positioning fragments across infrastructure ownership, regulatory relationships, and geographic concentration rather than consolidating around scale alone.
| Leading Market Players |
|---|
| SUEZ Middle East Recycling LLC |
| EnviroServe |
| Averda |
| Saudi Investment Recycling Company |
| Green Mountains |
| Bee'ah |
| Veolia |
| Dulsco |
| Tadweer |
| Others |
Pricing and Supply Chain Analysis
MOCCAE's zero-landfill certification gates both supplier qualification and price differentiation simultaneously, compressing disposal options while fragmenting service tiers based on thermal treatment ownership. Incineration capacity scarcity concentrates pricing power among infrastructure owners, forcing buyers toward long-term contracts that embed capacity premiums.
Pricing Analysis
The UAE's Extended Producer Responsibility framework dictates the pricing tier structure across GCC industrial waste services, stratifying contracts by guaranteed capacity access rather than per-tonne rates alone. Pricing separates zero-landfill-certified providers from conventional disposal operators, with hazardous waste streams commanding substantial premiums due to cross-border movement requirements. Cost compression in non-hazardous recycling is intensifying because circular economy mandates are flooding the segment with new entrants. Petrochemical clusters in Jubail and Ruwais exhibit the lowest price sensitivity, prioritizing operational continuity over unit economics.
Supply Chain Analysis
Inventory lead times for advanced bioremediation systems stretch project timelines, as European suppliers dominate microbial degradation technology. Supply concentrates in Germany, France, and the Netherlands for biological treatment equipment, while thermal incineration infrastructure clusters in Saudi Arabia and the UAE. Raw material dependencies include specialized refractory linings, emission control catalysts, and secure landfill engineered cell membranes. Single-source vulnerability runs through European bioremediation system suppliers. Distribution feeds from centralized treatment hubs toward industrial zone collection networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery anchored to petrochemical capacity expansion across Saudi Arabia's Eastern Province, where waste-to-energy partnerships are embedding circular recovery into operational planning.
For Market Incumbents: Secure long-term incineration capacity commitments from Jubail and Ruwais petrochemical operators before plasma gasification pilots fragment traditional thermal treatment demand. Defend margin position by acquiring exclusive municipal contracts in underpenetrated emirates, leveraging regulatory relationships to block new entrant certification pathways.
For New Entrants and Emerging Players: Kuwait's SFDA biohazardous certification fast-track offers entry into pharmaceutical waste services before established players consolidate partnerships. Target Kuwait's Shuaiba Industrial Area and Oman's Duqm Special Economic Zone, where solvent residue volumes exceed local treatment capacity. Lead with cross-border logistics expertise as the primary go-to-market angle, bundling Bahraini secure landfill access with collection services.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across plasma gasification technology deployment, favoring asset-light logistics specialists over heavy infrastructure plays. Five-to-ten-year viability hinges on regulatory coordination between Bahrain's National Oil and Gas Authority and Oman's Ministry of Environment. Acquisition targets should display integrated collection networks with emirate-level exclusivity. Watch for halogenated compound threshold harmonization as the inflection signal that unlocks regional consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Incineration Capacity Expansion | Saudi Aramco's petrochemical complexes require guaranteed thermal treatment access to maintain operational continuity. |
| Cross-Border Logistics Partnership | Bahrain's engineered secure landfill cells attract heavy metal waste streams from Kuwait and Saudi Arabia. |
| Plasma Gasification Pilot | On-site synthetic gas production at Jubail facilities fragments traditional centralized incineration demand. |
| Bioremediation Technology Licensing | European microbial degradation systems address domestic capacity gaps across Oman's Sohar Industrial Port. |
| Zero-Landfill Certification Program | MOCCAE mandates compress disposal options toward integrated service providers with thermal infrastructure. |
Research Methodology
Cross-validation between regulatory filing analysis and facility operator interviews anchors the qualitative findings, combining primary discussions with plant managers, procurement leads at downstream petrochemical OEMs, hazardous materials transport coordinators, and technical R&D directors with secondary validation from customs and trade data, Saudi Standards and Metrology and Quality Organization discharge records, MOCCAE certification registries, and SEC filings from listed waste service providers. Bottom-up volume estimates from individual industrial zone operators triangulate against top-down market sizing from national environmental agency statistics.
Sensitivity analysis around regulatory enforcement timelines and petrochemical capacity expansion schedules shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include waste hazard classification, service type tier, end-use industry vertical, and technology deployment mode. CAGRs derive from volume trajectory analysis anchored to named industrial cluster expansions, with forecast inputs incorporating plasma gasification adoption curves and bioremediation import dependency resolution timelines.
Underlying assumptions cover landfill diversion mandate enforcement consistency and cross-border waste movement protocol harmonization, with deviation risk concentrated in regulatory delay or thermal treatment capacity construction bottlenecks. Forecasts reflect these documented assumptions. Revision becomes warranted when plasma gasification cost curves fall below centralized incineration breakeven thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Sharp Waste Disposal Market
Waste Management & Pollution Control
North America Municipal Solid Waste Management Market
Waste Management & Pollution Control
Vacuum Waste Systems Market
Waste Management & Pollution Control
Europe Municipal Solid Waste Management Market
Waste Management & Pollution Control
Alkaline Solid Waste Market
Waste Management & Pollution Control
Medical Waste Management System Market
Waste Management & Pollution Control
Asia-Pacific Municipal Solid Waste Management Market
Waste Management & Pollution Control
Waste Paper Management Market
Waste Management & Pollution Control
Recycled Ocean Plastics Market
Waste Management & Pollution Control
India Commercial Food Waste Decomposer Market
Waste Management & Pollution Control
Animal Waste Incinerator Market
Waste Management & Pollution Control
Asia-Pacific Industrial Waste Management Market
Waste Management & Pollution Control
Singapore Waste Management Market
Waste Management & Pollution Control
India Bio-Medical Waste Management Market
Waste Management & Pollution Control
Saudi Arabia Medical Waste Management Market
Waste Management & Pollution Control
Trash Rakes Market