
 Asia Pacific Medical Waste Management Market | 2026-2036
Asia Pacific Medical Waste Management Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Medical Waste Management Market Insights
Asset-light service leasing is narrowing the competitive field in Asia Pacific medical waste management. Stericycle leverages its regional treatment infrastructure to secure multi-hospital contracts across Australia and Southeast Asia. Veolia Environnement anchors its position through integrated collection-to-disposal networks that reduce client compliance burden. Clean Harbors competes by specializing in high-complexity pharmaceutical and laboratory waste streams that require certified handling protocols.
Medical waste management encompasses the regulated handling, treatment, and final disposition of materials generated during patient diagnosis, treatment, or immunization, including sharps, pathological specimens, and contaminated supplies that require sterilization or destruction prior to landfill or recycling. The primary purpose is to prevent disease transmission, protect healthcare workers, and ensure environmental containment of biohazardous materials through verified chain-of-custody documentation. Treatment technology segments reveal incineration retaining dominance for pathological and pharmaceutical residues where complete destruction is mandated, while autoclaving gains share for infectious waste as energy costs and emissions scrutiny intensify across the region. End-user segmentation shows hospitals generating the largest volume base, though research facilities and laboratories command premium pricing due to specialized chemical and radioactive waste handling requirements.
China's MEE enforces dual carbon targets that restrict new incinerator permits and push facilities toward plasma and advanced thermal treatment. India's CPCB administers Bio-Medical Waste Management Rules that mandate bar-coded tracking and centralized common treatment facilities for clinics and small generators. Australia's EPA frameworks at state level impose landfill bans on untreated clinical waste that drive outsourcing to licensed operators. Stakeholders must monitor regulatory divergence across national boundaries when designing scalable service platforms.
Market Dynamics
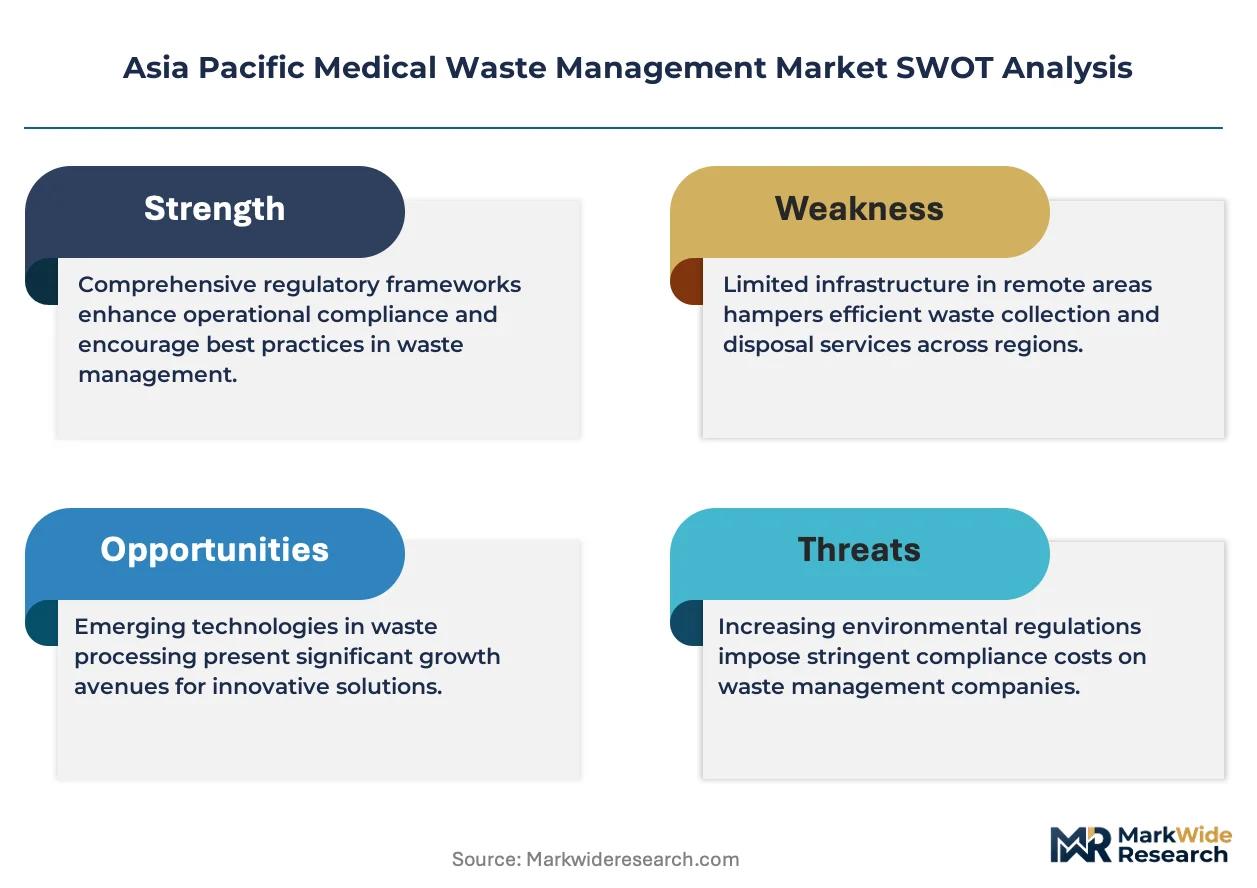
Asia Pacific medical waste management is undergoing structural compression as MEE dual carbon targets in China restrict incinerator permits while India's CPCB mandates bar-coded tracking systems that force consolidation among small-scale operators. This regulatory tightening is eliminating sub-scale competitors and accelerating capital deployment into centralized treatment infrastructure.
Growth Catalysts
- India's Bio-Medical Waste Management Rules:CPCB mandates for common treatment facilities push independent clinics toward outsourced handling, expanding addressable volume for licensed operators.
- Hospital network consolidation:Southeast Asian healthcare chains are standardizing waste contracts across multi-site portfolios, favoring vendors with regional logistics coverage.
- Plasma gasification:Advanced thermal treatment is displacing conventional incineration in Australian metropolitan markets where landfill bans on untreated clinical waste apply.
Market Restraints
- MEE permit scarcity:China's dual carbon framework restricts new incinerator approvals, capping treatment capacity expansion in high-demand provinces.
- Energy input volatility:Autoclave operators face margin pressure from electricity price fluctuations that autoclaving's thermal intensity amplifies relative to chemical treatment.
- Specialized vehicle shortage:Refrigerated transport fleet constraints in Indonesia and Philippines limit collection radius expansion for remote healthcare facilities.
Strategic Opportunities
- Vietnam's hospital privatization wave:Foreign-invested medical facilities in Ho Chi Minh City and Hanoi lack legacy disposal relationships, creating first-mover positioning for integrated service entrants.
- Pharmaceutical reverse logistics:Expired drug take-back mandates in South Korea and Japan require temperature-controlled chain-of-custody systems that command premium pricing.
- Digital tracking convergence:Integration of RFID waste tagging with blockchain verification is opening compliance-as-a-service revenue streams for technology-enabled operators.
Industry Challenges
- Certified technician scarcity:Biohazard handling licensure programs in India and Indonesia produce insufficient graduates to staff expanding treatment facility networks.
- Capex intensity for plasma systems:Advanced thermal equipment requires 3-5 year payback periods that strain balance sheets of mid-scale regional competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Medical Waste Management Market |
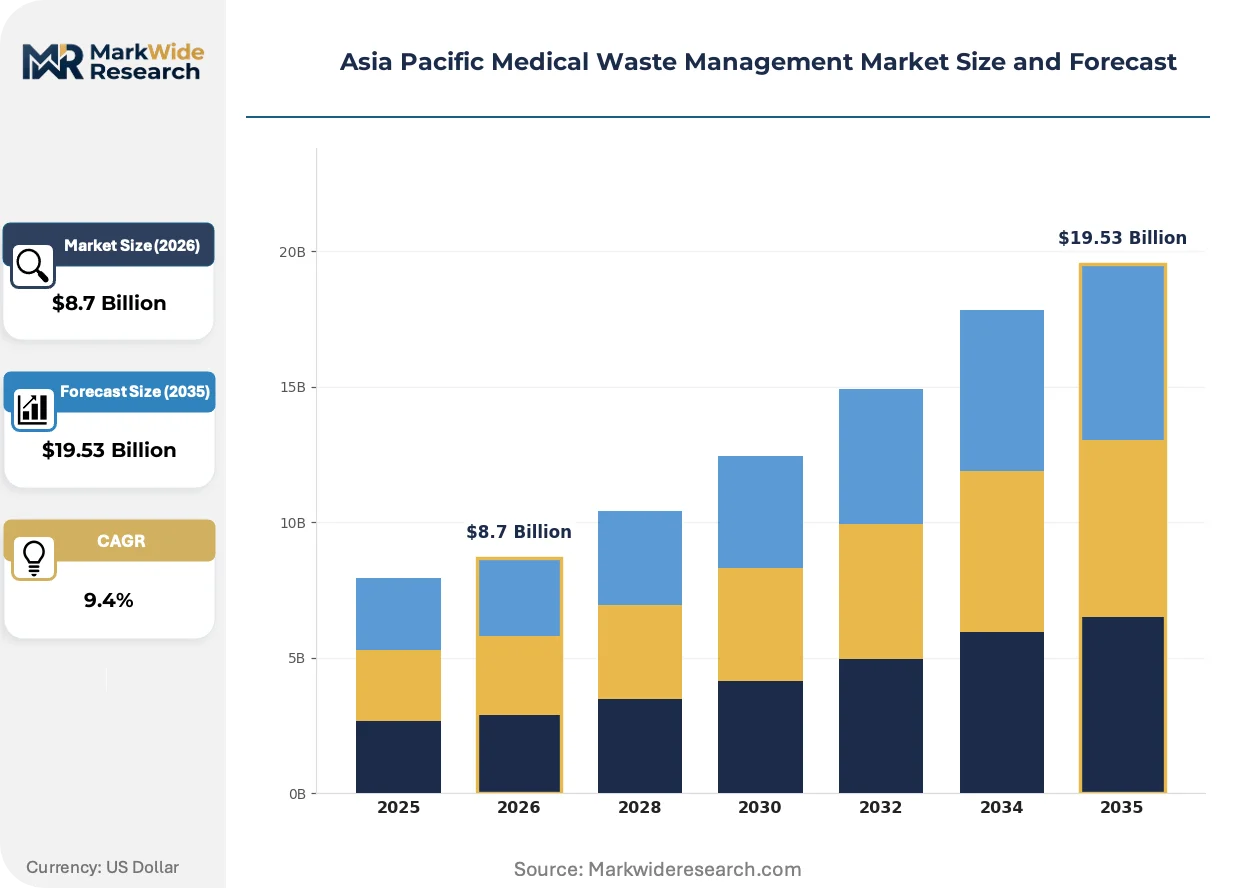
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Collection, Treatment, Disposal, Recycling Waste Type: Hazardous, Non-Hazardous, Infectious, Pathological End User: Hospitals, Clinics, Research Facilities, Laboratories Technology: Incineration, Autoclaving, Chemical Treatment, Plasma Treatment |
| Companies Covered | Suez, Stericycle, Veolia Environnement, Waste Management, Clean Harbors, Remondis, Daniels Sharpsmart, Biomedical Waste Solutions, Triumvirate Environmental, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Medical Waste Management Market Trends and Innovations
Digital infrastructure is virtualizing operational workflows across Asia Pacific medical waste management, compressing compliance documentation cycles and enabling real-time chain-of-custody verification that regulatory frameworks now mandate.
Autoclave monitoring systems are virtualizing quality assurance protocols through continuous temperature and pressure telemetry. Hospital procurement departments in Australia and Japan are specifying IoT-enabled treatment equipment that automates sterilization logs. This connectivity is virtualizing audit preparation, reducing manual documentation labor while tightening regulatory defensibility against EPA and state-level inspection regimes.
India's CPCB Bio-Medical Waste Management Rules now mandate bar-coded segregation at generation points for all healthcare facilities above 10 beds. The framework is forcing investment in centralized common treatment facilities as standalone clinic incinerators face closure deadlines. Small private hospitals in Maharashtra and Karnataka are consolidating into shared service contracts that transfer compliance liability to licensed third-party operators.
Research laboratories are unbundling waste handling from general facility management contracts and awarding standalone agreements to certified specialists. Academic medical centers in Singapore and South Korea now separate infectious, chemical, and radioactive streams across distinct vendor relationships. This fragmentation is most pronounced in Seoul and Singapore's Biopolis cluster, where precision handling requirements exceed generalist contractor capabilities.
Asia Pacific Medical Waste Management Market Segmentation
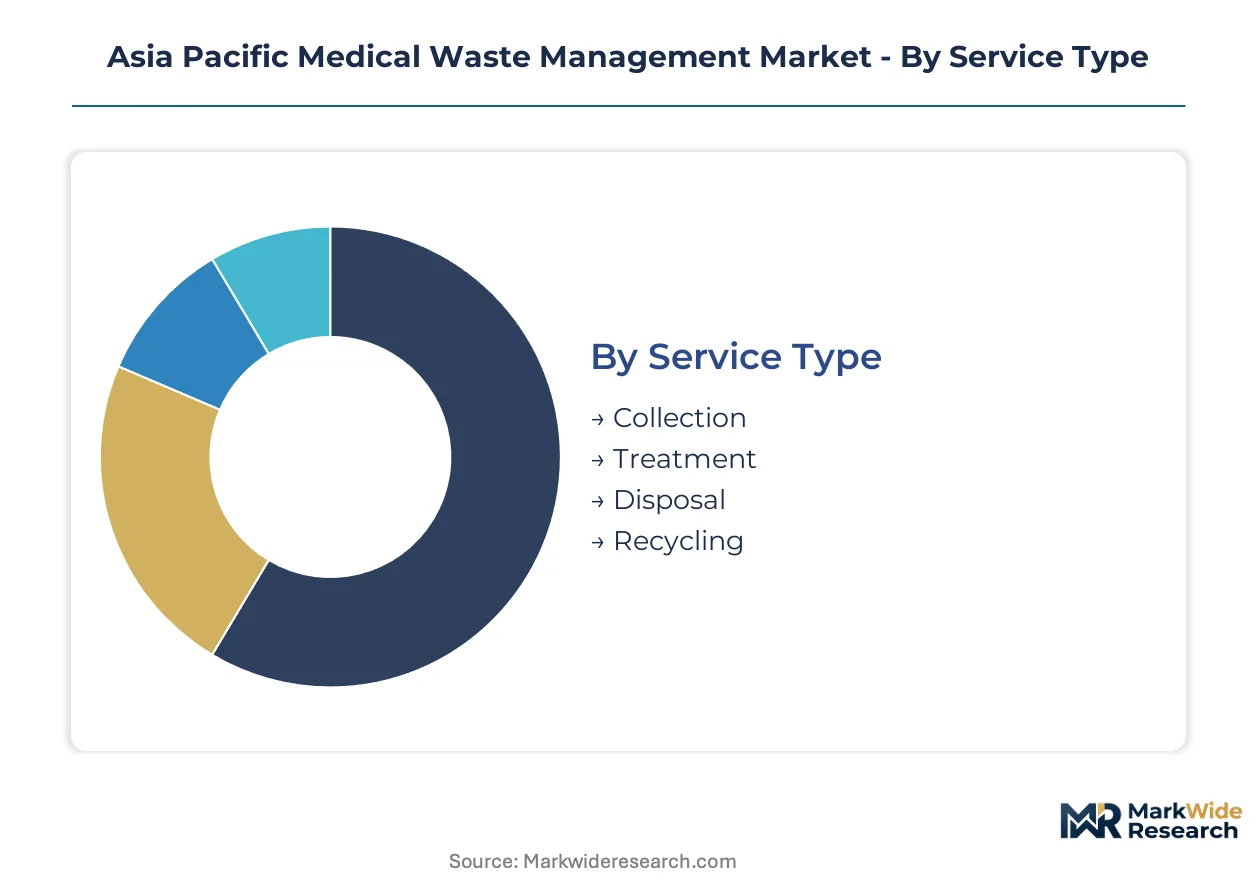
Medical waste management in Asia Pacific exhibits distinct demand patterns across service modalities, waste classifications, and treatment technologies. Segmentation reveals how regulatory pressure and infrastructure maturity reshape vendor positioning across India, China, and Southeast Asian markets.
Service Type:
Service models span the full operational spectrum from point-of-generation collection through final disposition, with cost structures and margin profiles varying sharply by activity intensity and capital deployment requirements.
- Collection:Refrigerated transport fleets with GPS-tracked routing dominate urban hospital contracts in Australia and Japan, where India's CPCB mandates bar-coded manifests that force consolidation among small-scale operators lacking digital infrastructure.
- Treatment:Centralized sterilization and destruction facilities command premium pricing in China's coastal provinces where MEE dual carbon restrictions cap new incinerator permits, creating scarcity value for licensed thermal processing capacity.
- Disposal:Landfill diversion services face tightening constraints across Australian state EPA frameworks that ban untreated clinical waste deposition, pushing generators toward certified third-party handlers with verified chain-of-custody documentation.
- Recycling:Plastics recovery from non-hazardous streams gains traction in South Korean and Japanese hospital networks seeking scope-three emissions reductions through circular material flows.
Established volume favors Treatment; emerging adoption favors Recycling.
Waste Type:
Classification systems determine handling protocols, licensing requirements, and liability exposure across national regulatory frameworks.
- Hazardous:Chemical and pharmaceutical residues requiring certified destruction protocols concentrate demand in Singapore's Biopolis cluster and Seoul's academic medical centers, where precision handling exceeds generalist contractor capabilities.
- Infectious:Contaminated materials from patient care settings generate the largest addressable volume base across India's expanding hospital network, with autoclaving displacing incineration as energy costs and emissions scrutiny intensify.
- Non-Hazardous:General medical packaging and uncontaminated supplies offer lower-margin commoditized handling, though segregation efficiency at generation points determines downstream processing economics for contracted operators.
- Pathological:Human tissue and anatomical specimens mandate complete thermal destruction under India's Bio-Medical Waste Management Rules, preserving incineration's role despite carbon-target pressures affecting other waste streams.
Volume concentration rests with Infectious; premium expansion centers on Hazardous.
End User:
Customer scale and complexity stratify procurement approaches, contract structures, and vendor qualification requirements.
- Hospitals:Multi-site healthcare networks across Southeast Asia are standardizing waste contracts across portfolios, favoring vendors with regional logistics coverage and centralized billing platforms that reduce procurement overhead.
- Clinics:Small private facilities in Maharashtra and Karnataka consolidate into shared service arrangements as standalone incinerators face closure deadlines, transferring compliance liability to licensed third-party operators.
- Research Facilities:Academic and commercial laboratories unbundle waste handling from general facility management, awarding standalone agreements to certified specialists capable of managing chemical and radioactive stream segregation.
- Laboratories:Diagnostic and testing facilities command premium pricing due to specialized handling requirements for biological specimens and reagent-contaminated materials that demand verified destruction protocols.
Procurement scale favors Hospitals; specialization premiums attach to Laboratories.
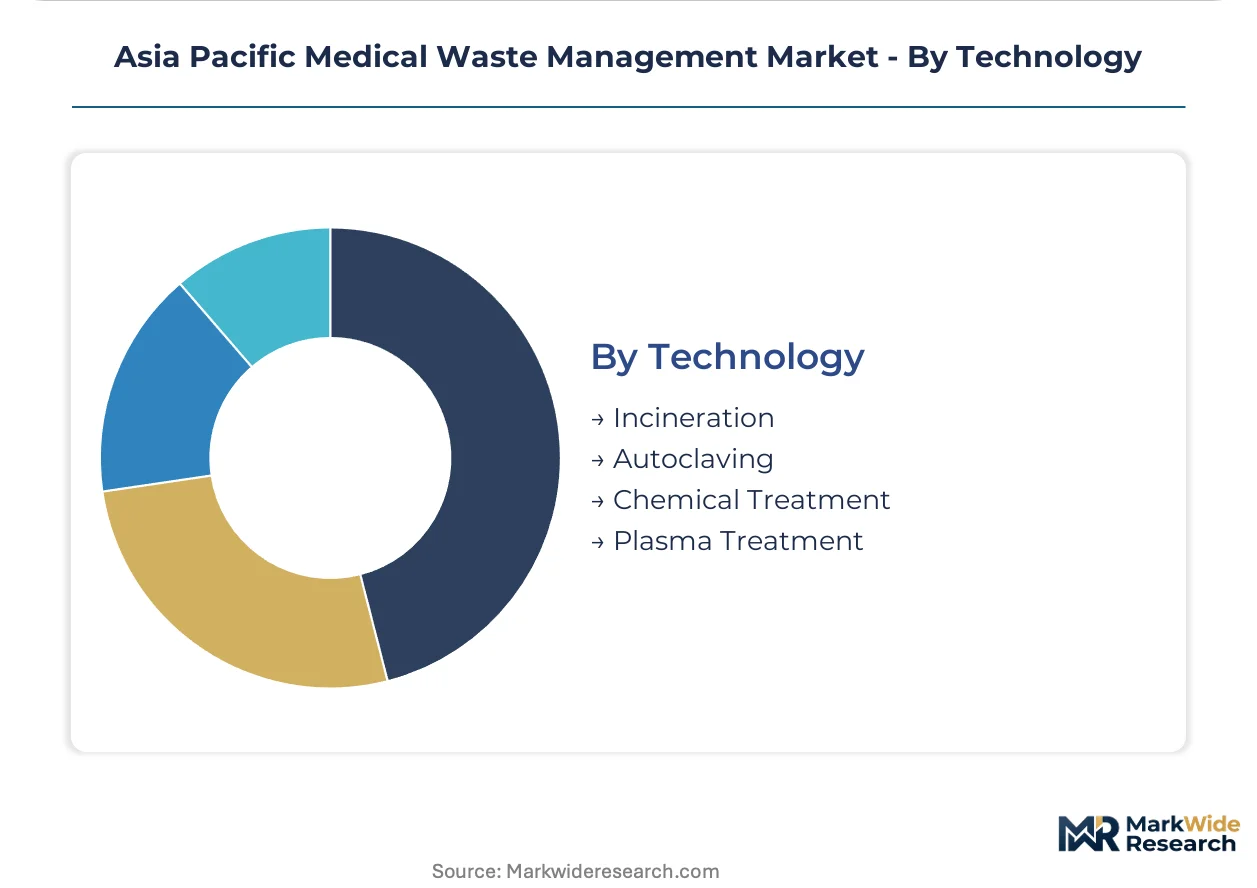
Technology:
Treatment modality selection reflects regulatory constraints, energy economics, and waste stream composition across metropolitan and provincial markets.
- Incineration:High-temperature combustion retains dominance for pathological and pharmaceutical residues where complete destruction is mandated, though China's MEE restricts new permits under dual carbon targets.
- Autoclaving:Steam sterilization gains share for infectious waste as electricity price volatility affects operating economics, with IoT-enabled monitoring systems automating compliance documentation for Australian and Japanese hospital procurement departments.
- Chemical Treatment:Disinfection protocols for liquid waste streams and select sharps categories offer lower capital intensity suitable for mid-scale regional competitors lacking balance sheet capacity for thermal equipment deployment.
- Plasma Treatment:Advanced thermal processing displaces conventional incineration in Australian metropolitan markets where landfill bans apply, though 3-5 year payback periods strain mid-scale operator balance sheets.
Incineration retains regulatory-mandated share; Plasma Treatment climbs fastest where carbon constraints tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Australian metropolitan markets exceeds Indonesian provincial benchmarks by a factor reflecting treatment scarcity and regulatory stringency. This asymmetry shapes capital deployment patterns across the region.
China
Provincial hospital networks in Jiangsu and Guangdong are consolidating waste contracts under pressure from MEE dual carbon targets that restrict new incinerator permits. The ministry's emission caps force generators toward plasma and advanced thermal alternatives in coastal manufacturing zones. Shanghai's Pudong medical cluster exemplifies this shift, with foreign-invested hospitals mandating blockchain-verified chain-of-custody documentation.
India
Maharashtra's private hospital chains are outsourcing waste handling as CPCB bar-code tracking mandates render standalone clinic incinerators non-compliant. The Bio-Medical Waste Management Rules impose centralized common treatment facility requirements that eliminate sub-scale competitors. Bengaluru's Health City corridor demonstrates this consolidation, with multi-site specialty hospitals standardizing contracts across cardiology and oncology centers.
Australia
State EPA landfill bans on untreated clinical waste are accelerating plasma gasification adoption in Sydney and Melbourne metropolitan markets. Victoria's Environment Protection Authority enforces the strictest deposition prohibitions, pushing generators toward licensed operators with verified destruction protocols. The Parkville biomedical precinct illustrates premium-tier demand, where research laboratories unbundle waste streams across infectious, chemical, and radioactive categories.
Japan
Expired pharmaceutical take-back mandates from the Ministry of Health, Labour and Welfare are creating temperature-controlled reverse logistics demand in Tokyo and Osaka medical corridors. METI circular economy guidelines pressure hospital networks toward plastics recovery from non-hazardous streams. The Kobe biomedical cluster showcases specialized handling requirements, where regenerative medicine facilities generate novel cell-culture waste categories lacking established treatment protocols.
Vietnam
Foreign-invested hospital privatization in Ho Chi Minh City and Hanoi is bypassing legacy disposal relationships that constrained public facility procurement. The Ministry of Health's 2023 technical regulations on medical waste management impose segregation standards that exceed domestic contractor capabilities. Thu Duc City's emerging medical zone attracts integrated service entrants seeking first-mover positioning before regulatory enforcement tightens.
Asia Pacific Medical Waste Management Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in collection equipment and treatment technology supply. The Asia Pacific medical waste management market exhibits tiered consolidation around multinational environmental service conglomerates with integrated collection-to-disposal networks. Three strategic archetypes dominate: asset-heavy treatment infrastructure operators, technology-enabled compliance service providers, and specialized hazardous waste handlers. Competitive dynamics center on multi-hospital contract consolidation and geographic expansion through strategic partnerships with regional logistics providers.
Among integrated service platforms, Stericycle and Veolia Environnement exemplify the asset-heavy archetype with established regional treatment footprints. Clean Harbors occupies a specialist position in high-complexity pharmaceutical and laboratory waste streams requiring certified handling protocols. These three entities represent contrasting strategic postures—Stericycle and Veolia leverage scale economies across standardized infectious waste categories, while Clean Harbors commands premium positioning through technical specialization that generalist contractors cannot replicate.
| Leading Market Players |
|---|
| Suez |
| Stericycle |
| Veolia Environnement |
| Waste Management |
| Clean Harbors |
| Remondis |
| Daniels Sharpsmart |
| Biomedical Waste Solutions |
| Triumvirate Environmental |
| Others |
Pricing and Supply Chain Analysis
China's plasma gasification equipment manufacturers concentrate upstream supply of advanced thermal treatment systems, anchoring margin pools in Australian and Japanese metropolitan markets where landfill bans on untreated clinical waste create scarcity pricing for certified destruction capacity.
Pricing Analysis
Configured-to-order pricing for plasma treatment systems commands substantial premiums over standardized autoclave service contracts. Three-tier pricing structure across premium, standard, and economy levels separates blockchain-verified chain-of-custody documentation from basic manifest tracking from unbundled collection-only arrangements. Price differentiation hinges on certification grade under India's CPCB Bio-Medical Waste Management Rules and geographic delivery cost for refrigerated transport fleets. Cost compression in Indonesian and Philippine provincial markets is intensifying because specialized vehicle shortages limit collection radius expansion. Small private clinics in Maharashtra and Karnataka exhibit the highest price sensitivity, while research laboratories in Singapore's Biopolis cluster demonstrate minimal elasticity due to precision handling requirements.
Supply Chain Analysis
Tariff exposure between China and Australia dominates supply chain risk planning for advanced thermal treatment equipment procurement. Manufacturing concentration for plasma gasification systems rests on China, Germany, and Japan, while specialized refrigerated transport fleets draw from South Korean and Thai assembly plants. Raw material dependencies include high-grade stainless steel for autoclave chambers, RFID tagging components for bar-coded tracking mandates, and medical-grade plastics for sharps containers. Single-source vulnerability persists for IoT-enabled monitoring systems that automate sterilization logs. Distribution runs through regional environmental service conglomerates with integrated collection-to-disposal networks that reduce client compliance burden.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific medical waste management represents an early-cycle expansion story as India's CPCB mandates for common treatment facilities force consolidation among sub-scale operators and transfer compliance liability to licensed third-party handlers.
For Market Incumbents: Harden defensive positioning through backward integration into plasma gasification equipment supply chains and capacity addition in Vietnam's Thu Duc City medical zone before regulatory enforcement tightens. Stericycle and Veolia Environnement face emerging competition from technology-enabled compliance service providers integrating RFID waste tagging with blockchain verification. For New Entrants and Emerging Players: Build out white-space positioning in Vietnam's foreign-invested hospital privatization wave and pharmaceutical reverse logistics for expired drug take-back mandates in South Korea and Japan. The most penetrable segment is Ho Chi Minh City and Hanoi's emerging medical zones lacking legacy disposal relationships. A direct go-to-market angle centers on compliance-as-a-service revenue streams bundling digital tracking infrastructure with treatment capacity. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale regional operators with licensed thermal processing capacity in Chinese coastal provinces where MEE dual carbon restrictions cap new incinerator permits. Long-term viability across the next decade hinges on regulatory divergence management capabilities and scalable service platform architecture. The critical signal to watch is bar-coded tracking mandate enforcement intensity across Indian state-level implementation.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Gasification Capacity Buildout | MEE dual carbon restrictions in China create scarcity value for licensed thermal processing infrastructure. |
| Blockchain-Verified Chain-of-Custody Integration | Shanghai's Pudong medical cluster mandates documentation standards that exceed generalist contractor capabilities. |
| Refrigerated Transport Fleet Expansion | Indonesian and Philippine collection radius constraints limit remote healthcare facility access for licensed operators. |
| Certified Technician Training Programs | India's CPCB facility expansion outpaces biohazard handling licensure program graduate supply. |
| Pharmaceutical Reverse Logistics Partnership | South Korean and Japanese expired drug take-back mandates require temperature-controlled custody systems. |
Research Methodology
A standing panel of hospital procurement managers, biomedical engineers, GPO contracts managers, and environmental compliance officers provided ongoing calibration against operating reality throughout the study. Primary interviews with treatment facility operators and logistics coordinators combined with secondary validation against CPCB enforcement notices, Australian state EPA framework updates, MEE emission cap disclosures, and hospital procurement database records. Bottom-up volume modeling across service type, waste classification, and treatment technology segments triangulated with top-down regulatory mandate impact assessment.
Scenario bracketing around MEE permit scarcity intensity and CPCB bar-code tracking enforcement pace shaped the analytical framework across the projection horizon. Segmentation dimensions modeled encompass service modality, waste stream hazard classification, end-user scale tier, and treatment technology maturity. CAGRs were derived from installed capacity expansion trajectories and contract standardization velocity across multi-site hospital networks. Industry-specific forecast inputs include plasma gasification adoption curves in Australian metropolitan markets and pharmaceutical reverse logistics mandate rollout timing.
Stress conditions across energy input volatility, certified technician supply constraints, and refrigerated transport fleet availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding regulatory enforcement consistency and capital deployment continuity for advanced thermal treatment infrastructure. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Trash Pump Market
Waste Management & Pollution Control
GCC Industrial Waste Management Market
Waste Management & Pollution Control
North America Trash Bags Market
Waste Management & Pollution Control
GCC Pneumatic Waste Management System Market
Waste Management & Pollution Control
Wheeled Bins Market
Waste Management & Pollution Control
US Municipal Solid Waste Management Market
Waste Management & Pollution Control
UAE Biomedical Waste Management Market
Waste Management & Pollution Control
Radioactive Waste Management System Market
Waste Management & Pollution Control
Asia-Pacific Waste Management Market
Waste Management & Pollution Control
Asia-Pacific Municipal Solid Waste Management Market
Waste Management & Pollution Control
Europe Municipal Solid Waste Management Market
Waste Management & Pollution Control
Wood Recycling Market
Waste Management & Pollution Control
North America Waste Management Market
Waste Management & Pollution Control
Landfill Compactor Market
Waste Management & Pollution Control
South American Waste Management Market
Waste Management & Pollution Control
Municipal Solid Waste Management Market