
 Global Alpha-Lactalbumin Market | 2026-2036
Global Alpha-Lactalbumin Market Size, Share, and Industry Trends Forecast 2026-2036
Global Alpha-Lactalbumin Market Analysis
Infant formula demand is hardening as the dominant end-use vertical for alpha-lactalbumin, displacing traditional sports nutrition applications. Arla Foods Ingredients leverages its Danish dairy cooperative structure to secure raw whey streams directly from farmer-owners. FrieslandCampina anchors its competitive position through specialized fractionation assets in the Netherlands that isolate proteins at pharmaceutical-grade purity. Glanbia competes by extending its ingredient portfolio across both adult nutrition and early-life nutrition channels.
Alpha-lactalbumin constitutes a globular whey protein fraction comprising approximately 123 amino acid residues with a molecular mass near 14.2 kDa, characterized by high tryptophan content and metal-binding capacity that supports neurodevelopmental applications. Powder formats dominate current manufacturing output due to superior shelf stability and ease of incorporation into dry-blend infant formulas. The isolate sub-category commands premium positioning as brands differentiate on protein concentration thresholds exceeding 90 percent purity. Liquid concentrates sustain volume traction in dairy applications where functional properties such as gelation and water-binding determine formulation economics.
FDA exercises oversight through GRAS notifications and infant formula nutrient specifications that dictate minimum protein quality benchmarks for US-market products. EFSA and EMA frameworks in Europe impose dual requirements on alpha-lactalbumin destined for food versus pharmaceutical applications, with the latter triggering novel food or drug-substance pathways. China's NMPA and national food safety standards (GB) create additional compliance layers for imported dairy protein ingredients. Stakeholders must monitor evolving metal-binding claims regulation and trace mineral fortification limits as clinical research advances.
Market Dynamics
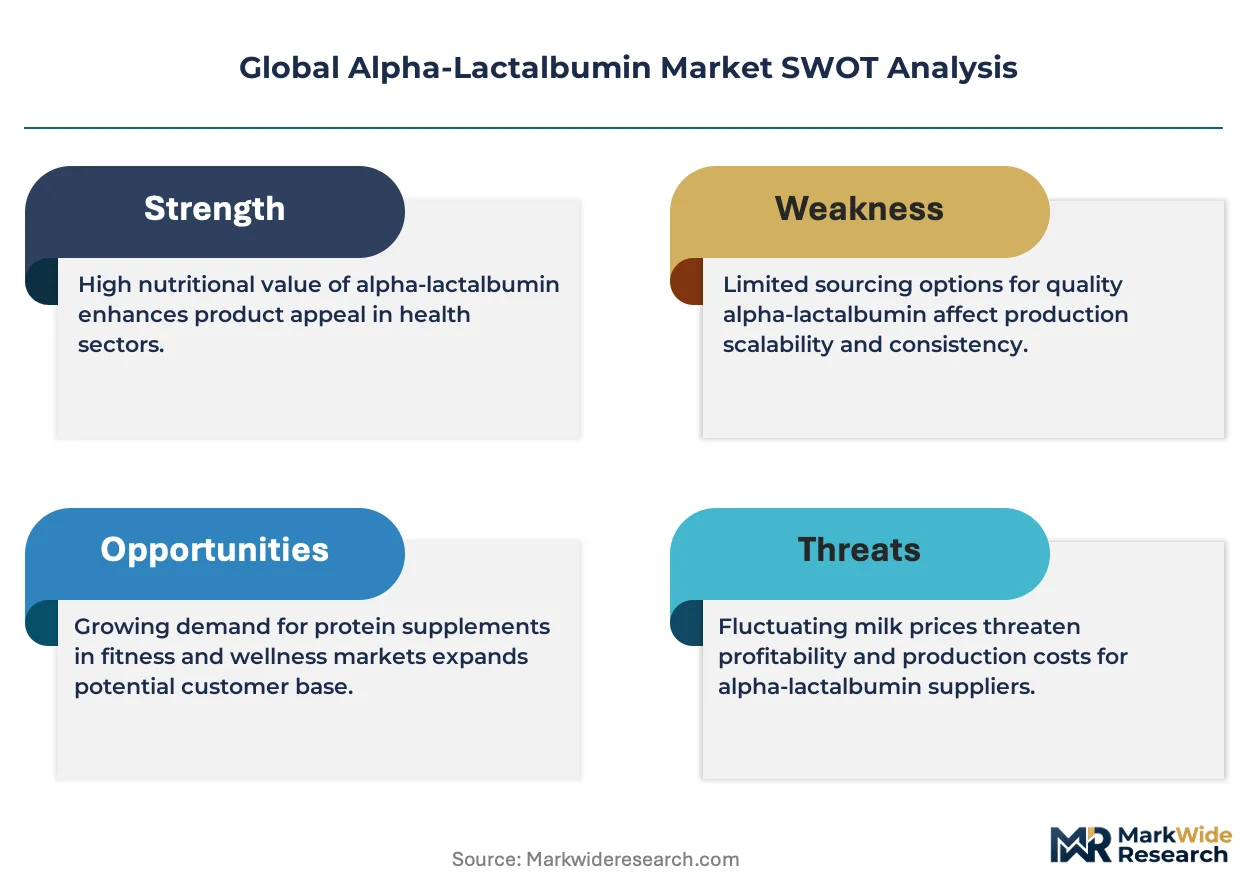
Infant formula manufacturers are consolidating procurement around alpha-lactalbumin suppliers with pharmaceutical-grade fractionation capabilities, compressing the supplier base toward integrated dairy cooperatives with captive whey streams and in-house isolation technology.
Growth Catalysts
- REACH solvent recovery mandates:The EU F-Gas Regulation and REACH frameworks are tightening emission standards for whey fractionation facilities, accelerating capital deployment into closed-loop membrane filtration systems that improve yield economics.
- Neurodevelopmental positioning:Alpha-lactalbumin's high tryptophan content and metal-binding capacity are driving reformulation in premium infant nutrition segments targeting sleep quality and cognitive development claims.
- Denmark-Netherlands cluster concentration:Specialized fractionation infrastructure in these markets is attracting downstream formulation R&D, creating geographic lock-in for high-purity isolate supply.
Market Restraints
- Whey input cost volatility:Cheese production cycles and milk powder commodity swings transmit directly to alpha-lactalbumin feedstock economics, compressing margin predictability for non-integrated processors.
- Fractionation technology concentration:Pharmaceutical-grade isolation capacity remains concentrated among a limited set of European dairy ingredient specialists, creating supply bottleneck risk during demand surges.
- Regulatory pathway friction:EMA novel food assessments and FDA GRAS notification timelines extend commercialization cycles for new metal-binding or neurodevelopmental claim formulations.
Strategic Opportunities
- China NMPA pathway optimization:Imported dairy protein registration under China's GB food safety standards and NMPA frameworks remains underpenetrated by European specialists with existing EFSA dossiers.
- Medical nutrition expansion:Clinical enteral nutrition and sarcopenia management applications represent adjacent demand pools beyond infant formula, leveraging existing pharmaceutical-grade purity certifications.
- Membrane-electrodialysis convergence:Integration of ceramic microfiltration with electrodialysis is enabling selective mineral binding for functional positioning in mineral-fortified formulations.
Industry Challenges
- Pharmaceutical-grade certification timelines:EMA drug-substance pathway documentation and FDA infant formula nutrient specification compliance require 18-36 month validation cycles that strain working capital.
- Specialized protein chemist scarcity:Whey fractionation process engineering and metal-binding characterization expertise concentrates among retiring cohorts in European dairy research institutes.
- Legacy ERP integration with batch tracking:Pharmaceutical-grade lot traceability requirements are forcing replacement of dairy-industry MRP systems not designed for serialized ingredient genealogy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Alpha-Lactalbumin Market |
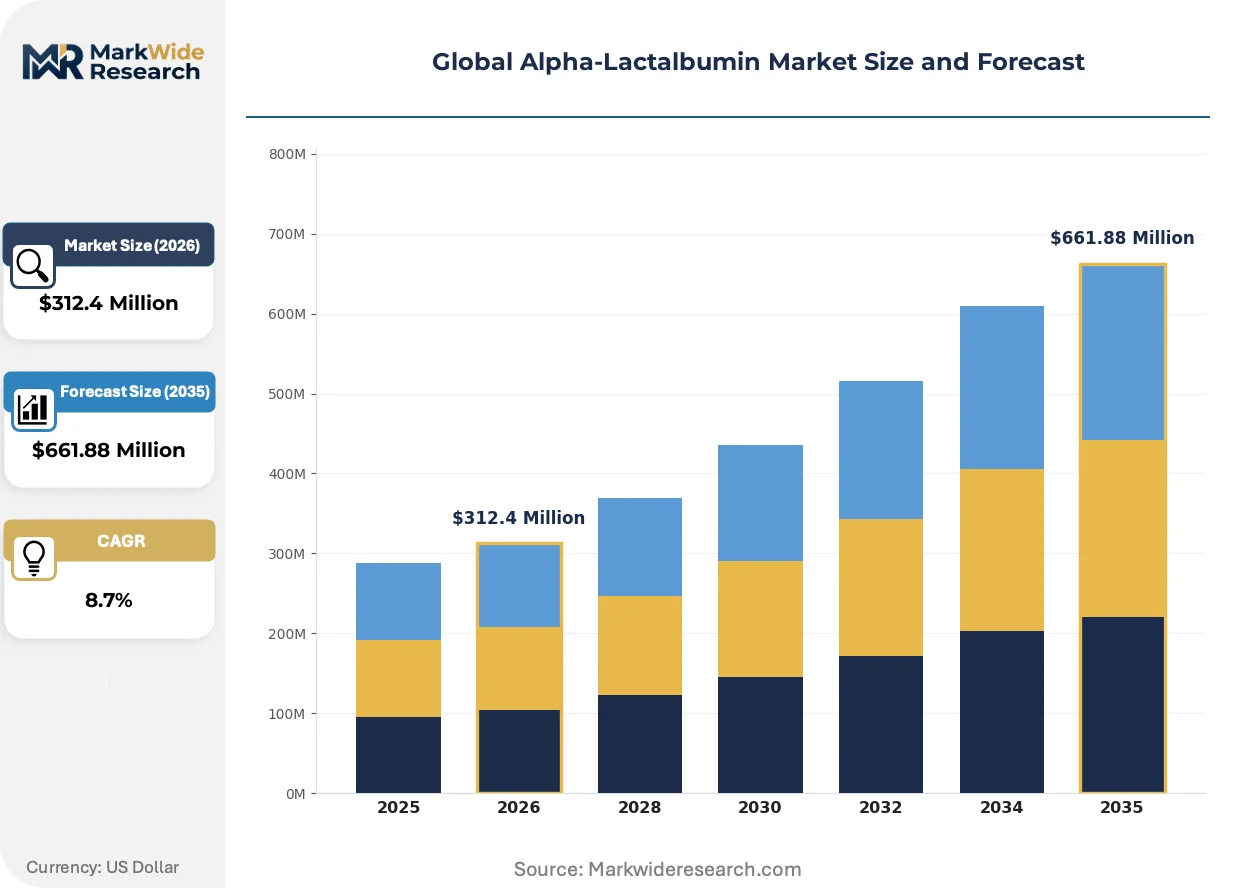
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Concentrate, Isolate End User: Food & Beverage, Pharmaceuticals, Nutrition Supplements, Infant Formula Application: Functional Foods, Dairy Products, Dietary Supplements, Sports Nutrition Distribution Channel: Online, Supermarkets, Health Stores, Direct Sales |
| Companies Covered | Arla Foods Ingredients, Hilmar Ingredients, Milk Specialties Global, Agropur, FrieslandCampina, Nestlé, Fonterra Co-operative Group, Glanbia, Morinaga Milk Industry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Alpha-Lactalbumin Market Emerging Trajectories
Fractionation technology, regulatory claim frameworks, and procurement consolidation are converging to reshape competitive positioning in alpha-lactalbumin supply. These shifts favor integrated operators with captive raw material access and in-house clinical validation capabilities.
Membrane filtration technology is integrating electrodialysis and ceramic microfiltration into continuous processing lines that recover alpha-lactalbumin at purity thresholds exceeding 95 percent. Infant formula manufacturers in Western Europe are adopting these systems at pilot scale, with commercial deployment accelerating through 2026. This integration is compressing the cost gap between isolate and concentrate grades, forcing commodity-positioned suppliers toward specialty claim differentiation.
China's NMPA and GB standards are tightening import documentation for dairy protein ingredients, requiring dual-language stability data and manufacturing site inspections that European suppliers previously avoided. This regulatory shift is raising compliance costs for mid-tier traders while benefiting integrated manufacturers with existing China dossier teams. The infant formula segment is responding by consolidating supplier panels toward dual-registered European dairy cooperatives.
Direct procurement contracts between infant formula brands and fractionation specialists are displacing traditional ingredient distributor intermediaries in premium nutrition segments. Arla Foods Ingredients and FrieslandCampina are capturing volume through multi-year offtake agreements with specified purity tiers and dedicated batch allocation. This channel compression is most visible in the Netherlands and Denmark, where formulation R&D co-location with fractionation assets enables just-in-time ingredient customization.
Global Alpha-Lactalbumin Market Segmentation
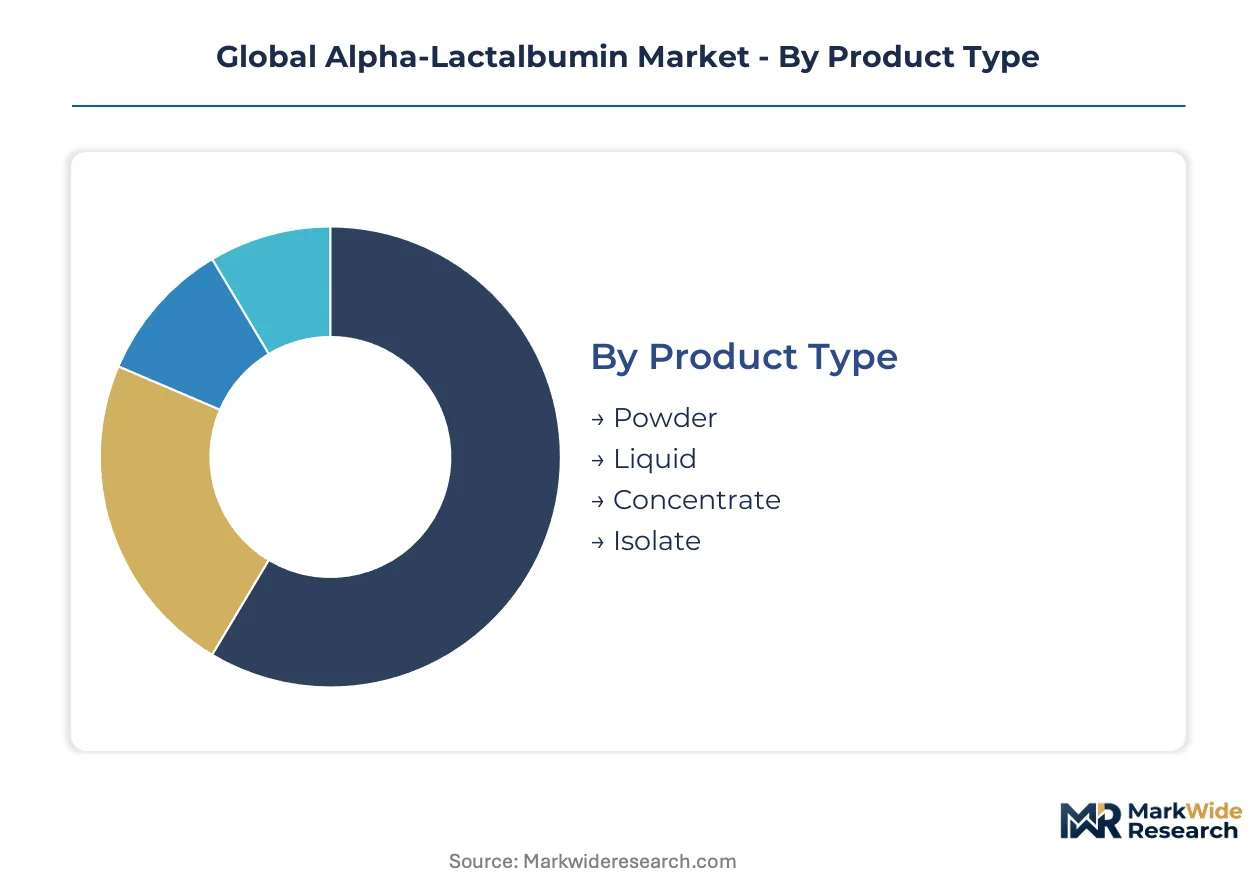
Alpha-lactalbumin procurement decisions pivot on purity thresholds, format compatibility with downstream processing, and regulatory certification tiers. Manufacturers segment supply to match infant formula nutrient specifications against pharmaceutical-grade drug-substance pathways.
Product Type:
Upgrade cycles from concentrate to isolate grades are accelerating as infant formula brands reformulate for neurodevelopmental positioning and metal-binding claims.
- Powder:Spray-dried formats deliver shelf stability exceeding 24 months under controlled humidity, supporting dry-blend infant formula manufacturing in Denmark and the Netherlands where fractionation clusters enable just-in-time powder supply. Demand concentrates among multinational formula brands seeking logistics flexibility across distributed production networks.
- Isolate:Protein concentrations exceeding 90 percent purity command premium positioning for pharmaceutical and medical nutrition applications. EMA drug-substance pathway documentation and FDA GRAS notifications for isolate grades extend validation timelines, compressing supplier pools toward integrated dairy cooperatives with captive whey streams and in-house clinical validation capabilities.
- Liquid:Retained water content limits transport economics to regional dairy applications where gelation and water-binding properties determine formulation value.
- Concentrate:Intermediate purity grades sustain volume traction in sports nutrition and functional dairy where cost thresholds outweigh certification requirements.
Volume placements concentrate in Powder; the faster expansion belongs to Isolate.
End User:
Customer procurement maturity separates pharmaceutical-grade buyers with 18-36 month validation cycles from commodity food manufacturers prioritizing spot pricing.
- Infant Formula:Premium segment reformulation targets alpha-lactalbumin's tryptophan-to-tyrosine ratio and metal-binding capacity for sleep quality and cognitive development claims. NMPA registration requirements in China and EFSA novel food assessments in Europe are consolidating supplier panels toward dual-registered European dairy cooperatives with existing dossier teams.
- Pharmaceuticals:Enteral nutrition and sarcopenia management applications leverage existing pharmaceutical-grade purity certifications, extending addressable demand beyond early-life nutrition. EMA drug-substance pathway compliance and FDA infant formula nutrient specifications create overlapping technical requirements that favor suppliers with integrated fractionation and clinical validation infrastructure.
- Nutrition Supplements:Sports nutrition demand is plateauing as procurement shifts toward infant formula verticals, though medical nutrition adjacencies sustain moderate volume.
- Food & Beverage:Functional dairy applications in processed cheese and yogurt rely on concentrate grades where gelation properties outweigh purity premiums.
Procurement concentration is hardening around Infant Formula; Pharmaceuticals are climbing the fastest as medical nutrition applications expand.
Application:
Formulation economics separate applications where functional properties determine value from those where clinical claims drive premium pricing.
- Dietary Supplements:Capsule and tablet formats prioritize powder flowability and compressibility, with demand fragmenting across adult wellness segments without the procurement consolidation seen in infant formula.
- Functional Foods:Mineral-fortified dairy beverages exploit alpha-lactalbumin's metal-binding capacity for positioning against competitive protein sources, though EFSA health claim substantiation requirements limit approved claim language.
- Sports Nutrition:Ready-to-drink protein beverages and bars sustain concentrate-grade consumption where rapid amino acid absorption claims compete with established whey isolate alternatives.
- Dairy Products:Processed cheese and yogurt manufacturing values water-binding and emulsification properties in liquid and concentrate formats, with regional dairy processors sourcing from proximate fractionation facilities.
Volume concentrates in Dairy Products; Dietary Supplements are gaining share fastest on medical nutrition expansion.
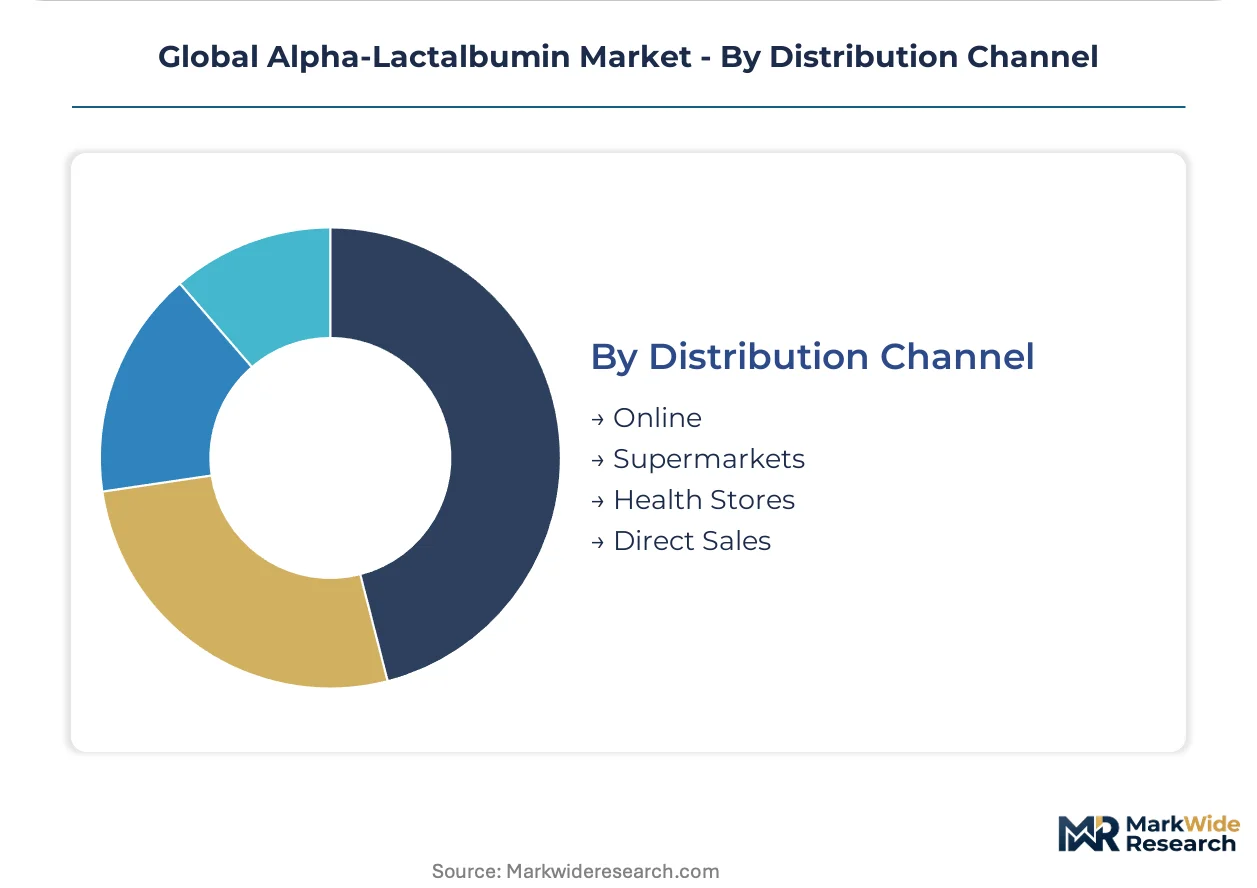
Distribution Channel:
Channel selection reflects buyer scale and certification requirements, with direct procurement displacing intermediaries in premium segments.
- Direct Sales:Multi-year offtake agreements with specified purity tiers and dedicated batch allocation dominate infant formula procurement, compressing distributor margins and enabling just-in-time customization through R&D co-location with fractionation assets in the Netherlands and Denmark.
- Online:E-commerce platforms sustain small-volume supplement manufacturers and regional dairy processors without the scale to justify direct supplier contracts, though NMPA and EFSA documentation requirements limit cross-border trade in pharmaceutical-grade material.
- Health Stores:Retail channel presence concentrates in finished supplement brands rather than bulk ingredient sales, with limited alpha-lactalbumin volume moving through this pathway.
- Supermarkets:Consumer-facing packaged foods with alpha-lactalbumin fortification reach shelves through branded food manufacturer supply chains rather than direct ingredient distribution.
Volume concentrates in Direct Sales; Online channels are expanding most quickly for mid-tier supplement manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Denmark's Agri-Food Innovation Zone tax incentives have concentrated pharmaceutical-grade fractionation infrastructure around Aarhus and Viby, drawing downstream infant formula R&D co-location from multinational brands seeking just-in-time customization.
Denmark
Arla Foods Ingredients leverages its cooperative structure to secure captive whey streams from farmer-owners across Jutland. EFSA novel food assessments and REACH solvent recovery mandates shape facility investments in membrane filtration systems. The Aarhus-Viby corridor hosts specialized electrodialysis pilot plants serving premium infant nutrition brands.
Netherlands
FrieslandCampina anchors fractionation capacity in the northern dairy belt where cheese production cycles supply consistent whey inputs. EU F-Gas Regulation compliance drives capital deployment into closed-loop recovery systems at pharmaceutical-grade isolation sites. Wageningen University partnerships accelerate ceramic microfiltration commercialization for 95-percent purity thresholds.
United States
FDA GRAS notifications and infant formula nutrient specifications dictate minimum protein quality benchmarks for domestic brands. EPA emission standards for dairy processing facilities influence solvent recovery investments at whey fractionation plants. Wisconsin and California dairy clusters sustain concentrate-grade output for sports nutrition applications.
China
NMPA registration requirements and GB food safety standards create compliance layers for imported dairy protein ingredients. Dual carbon goals and MEE environmental inspections pressure domestic fractionation capacity expansion. Shanghai and Tianjin formulation R&D centers drive demand for dual-registered European suppliers with existing dossier teams.
Japan
PMDA pharmaceutical pathways and METI industrial policy support medical nutrition applications beyond infant formula. JIS standards for functional food ingredients shape purity specifications for metal-binding claim formulations. Tokyo-Osaka formulation corridors sustain niche demand for isolate grades in sarcopenia management products.
Global Alpha-Lactalbumin Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated dairy cooperatives commanding premium-tier supply through captive raw material access. The supplier base compresses toward operators with in-house fractionation technology and pharmaceutical-grade certification infrastructure. Three archetypes dominate: cooperative-integrated fractionation specialists, independent whey processors with tolling arrangements, and multinational nutrition conglomerates with backward integration into dairy proteins. Competitive moves center on multi-year offtake agreements with dedicated batch allocation and membrane technology licensing partnerships.
Within the cooperative-integrated tier, Arla Foods Ingredients and FrieslandCampina occupy positions that exemplify captive supply chain control from farm through pharmaceutical-grade isolation. Among independent processors, Hilmar Ingredients and Milk Specialties Global represent archetypes of scale-driven tolling capacity serving brands without integrated fractionation assets. Glanbia sits within the diversified nutrition conglomerate category, extending ingredient portfolio breadth across adult and early-life nutrition channels without cooperative structural advantages.
| Leading Market Players |
|---|
| Arla Foods Ingredients |
| Hilmar Ingredients |
| Milk Specialties Global |
| Agropur |
| FrieslandCampina |
| Nestlé |
| Fonterra Co-operative Group |
| Glanbia |
| Morinaga Milk Industry |
| Others |
Supply Flow & Price Mechanics
Captive whey sourcing through cooperative-integrated fractionation anchors supply positions and pricing power for pharmaceutical-grade isolate tiers, compressing margin structures for non-integrated processors dependent on spot whey markets and tolling arrangements.
Pricing Analysis
Short lead-time premiums reward suppliers with membrane filtration capacity in Denmark and the Netherlands capable of just-in-time isolate delivery to infant formula R&D co-locations. Contract-based long-term offtake agreements dominate premium tiers, with price differentiation resting on EMA drug-substance certification and FDA GRAS notification status. Pricing pressure stems from whey input cost volatility transmitting through cheese production cycles, with sports nutrition concentrate buyers exhibiting highest price sensitivity versus pharmaceutical-grade infant formula procurement.
Supply Chain Analysis
Regional distribution centers in Aarhus and Viby feed hub-and-spoke patterns serving Western European infant formulation clusters. Supply concentrates in Denmark, the Netherlands, and Wisconsin, with raw material dependencies on cheese whey streams, ceramic membrane modules, and electrodialysis equipment. Single-source vulnerability concentrates in pharmaceutical-grade fractionation technology licensing held by retiring cohorts at European dairy research institutes. Distribution runs through direct procurement channels displacing traditional ingredient intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around integrated dairy cooperatives with captive whey streams, as REACH solvent recovery mandates and EMA certification timelines force non-integrated processors toward exit or acquisition.
For Market Incumbents: Hedge against whey input volatility through backward integration into cheese production or multi-year farmer-owner supply contracts. Fortify positions by accelerating ceramic microfiltration deployment ahead of EU F-Gas Regulation enforcement, while locking in NMPA registration capacity before China's GB standards tighten further. For New Entrants and Emerging Players: Capture white space in medical nutrition enteral formulations and sarcopenia management applications leveraging existing pharmaceutical-grade purity frameworks. China's underpenetrated NMPA pathway offers the most penetrable geography for European specialists with existing EFSA dossiers. Prioritize membrane-electrodialysis tolling partnerships over greenfield fractionation investment. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of independent whey processors with tolling arrangements by cooperative-integrated specialists seeking geographic expansion. Long-term viability favors operators with captive raw material access and in-house clinical validation infrastructure. Watch for inflection in China NMPA registration timelines as signal for import demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Whey Sourcing | Arla Foods Ingredients' cooperative structure secures captive raw streams from Jutland farmer-owners. |
| Membrane-Electrodialysis Capacity Expansion | FrieslandCampina's Wageningen partnerships accelerate 95-percent purity threshold commercialization. |
| Dual NMPA-EFSA Registration Investment | European specialists with existing dossier teams capture China import compliance premiums. |
| Medical Nutrition Portfolio Extension | Glanbia leverages pharmaceutical-grade certifications across sarcopenia and enteral nutrition channels. |
| Closed-Loop Solvent Recovery Deployment | EU F-Gas Regulation compliance drives capital into membrane filtration yield improvements. |
Methodological Framework
Document review covered FDA GRAS notifications, EMA drug-substance pathway filings, and China NMPA registration databases, complemented by interviews with whey fractionation plant managers, infant formula procurement directors, dairy cooperative technical leads, and membrane filtration equipment specialists. Secondary sources included EFSA novel food assessments, REACH compliance disclosures, SEC 10-K filings by listed dairy ingredient processors, and customs trade data for whey protein concentrate and isolate flows. Bottom-up volume triangulation against top-down value estimates validated segment splits across product types and end-use verticals.
Cross-referencing historical capacity expansion patterns against expert panel input on membrane technology adoption curves shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include purity grade tier, end-use application, regulatory certification pathway, and geographic production cluster. CAGRs derived from elasticity-adjusted demand projections incorporating infant formula birth-rate demographics and medical nutrition penetration assumptions.
The model holds under stable whey supply economics and continued EMA-FDA regulatory convergence; deviation in China import policy or membrane technology licensing access would shift volume trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Karaya Gum Market
Ingredients
Chlorella Ingredients Market
Ingredients
United Kingdom Gelatin Market
Ingredients
Food Grade Linseed Oil Market
Ingredients
Brazil Starch Derivatives Market
Ingredients
Global Dry Yeast Market
Ingredients
Edible Fiber Market
Ingredients
Canada Whey Protein Ingredients Market
Ingredients
Dill Seed Oil Market
Ingredients
Beetroot Powder Market
Ingredients
US Choline Bitartrate Market
Ingredients
Glucose (Dextrose) Market
Ingredients
Fruit Powder Market
Ingredients
North America Corn Starch Market
Ingredients
Omega Ingredients Market
Ingredients
Virginiamycin Market