
 Whipped Topping Concentrate Market | 2026-2036
Whipped Topping Concentrate Market Size, Share, and Industry Trends Forecast 2026-2036
Whipped Topping Concentrate Market Analytics
Plant-based fat systems is rebalancing cost structures across whipped topping concentrate formulations as coconut and palm kernel oils displace traditional dairy fat bases. RICH Products Corporation leverages its frozen dessert ingredient network to sustain North American supply relationships. Palsgaard A/S anchors its position through emulsifier and stabilizer expertise tailored to aerated food systems. BASF SE competes via specialty lipid and oleochemical portfolios that support high-overrun whipped applications.
Whipped topping concentrate denotes a concentrated base—typically comprising hydrogenated vegetable oils, emulsifiers, sweeteners, and stabilizing hydrocolloids—designed for dilution and aeration into finished whipped toppings with overrun levels between 80% and 200%. The product serves industrial bakeries, foodservice distributors, and retail channels seeking consistent foam stability and extended shelf life in finished desserts. Non-dairy concentrates now lead volume as plant-based bakery and frozen dessert formulations expand, while powder formats retain margin advantages through reduced cold-chain dependency and longer ambient storage windows. Liquid concentrates grow fastest in foodservice channels where reconstitution speed and batch consistency outweigh logistics costs.
The FDA governs whipped topping labeling and fat-content standards under 21 CFR 135.110, while the USDA monitors dairy-derived concentrates through its dairy grading and inspection programs. The EPA oversees effluent guidelines for wet-processing facilities that generate lipid-laden wastewater during concentrate manufacturing. Stakeholders must monitor evolving plant-based identity standards and emerging state-level packaging regulations that could reshape formulation and distribution requirements.
Market Dynamics
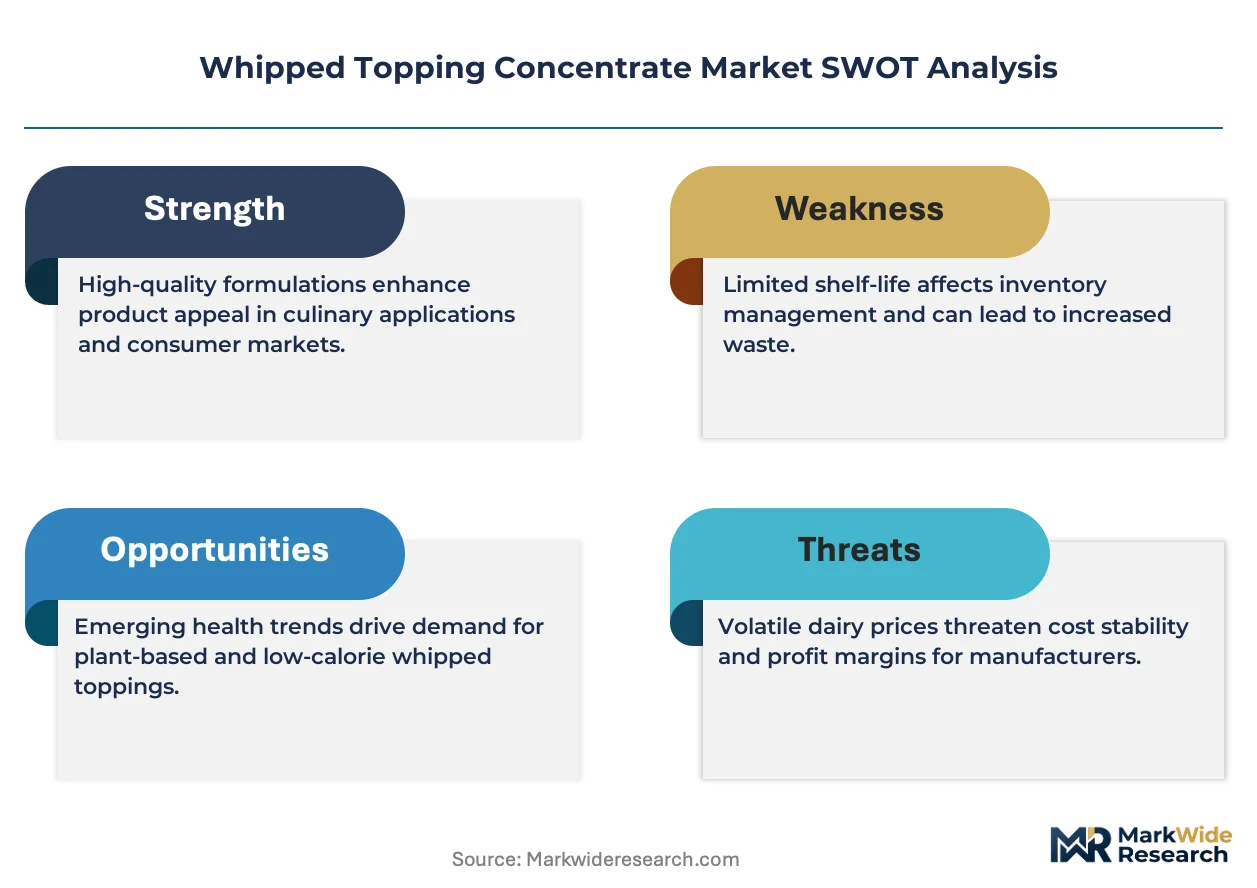
Plant-based fat substitution is compressing traditional dairy concentrate margins while forcing reformulation investments across industrial bakeries and frozen dessert manufacturers. Coconut and palm kernel oil supply chains now determine cost volatility for non-dairy emulsion systems.
Growth Catalysts
- EU Green Deal implementation:Clean-label mandates under the EU Green Deal are accelerating plant-based concentrate adoption as industrial bakeries reformulate to meet sustainability procurement standards.
- Quick-service restaurant expansion:Chain kitchens are adopting concentrated topping bases to standardize dessert preparation across franchise locations and reduce per-unit labor inputs.
- Hydrogenated vegetable oil processing advances:Improved fractionation technologies are enhancing foam stability in high-overrun applications, enabling broader foodservice penetration.
Market Restraints
- Palm kernel oil price volatility:Tropical supply disruptions and sustainability certification costs are squeezing margins for non-dairy concentrate manufacturers dependent on Southeast Asian feedstocks.
- Cold-chain infrastructure gaps:Liquid concentrate distribution remains constrained by refrigerated logistics limitations in secondary foodservice markets, favoring powder formats despite slower reconstitution.
- FDA fat-content thresholds:21 CFR 135.110 labeling standards create formulation rigidities that complicate clean-label transitions for products seeking whipped topping identity.
Strategic Opportunities
- Indian foodservice penetration:Underdeveloped dessert topping infrastructure in quick-service and bakery channels offers first-mover positioning for ambient-stable powder concentrates.
- Carbon labeling alignment:EU CSRD disclosure requirements are creating procurement preference for concentrates with verified lifecycle emissions data, rewarding early certifiers.
- Direct-to-industrial distribution:Bypassing traditional foodservice distributors through bulk tanker delivery to large bakery chains is compressing channel costs and improving margin capture.
Industry Challenges
- Emulsion stability expertise scarcity:Formulation chemists capable of optimizing aerated non-dairy systems command premium compensation, constraining R&D throughput at mid-tier manufacturers.
- Dual certification complexity:Simultaneous organic and kosher compliance timelines extend product development cycles by six to nine months, delaying market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Whipped Topping Concentrate Market |
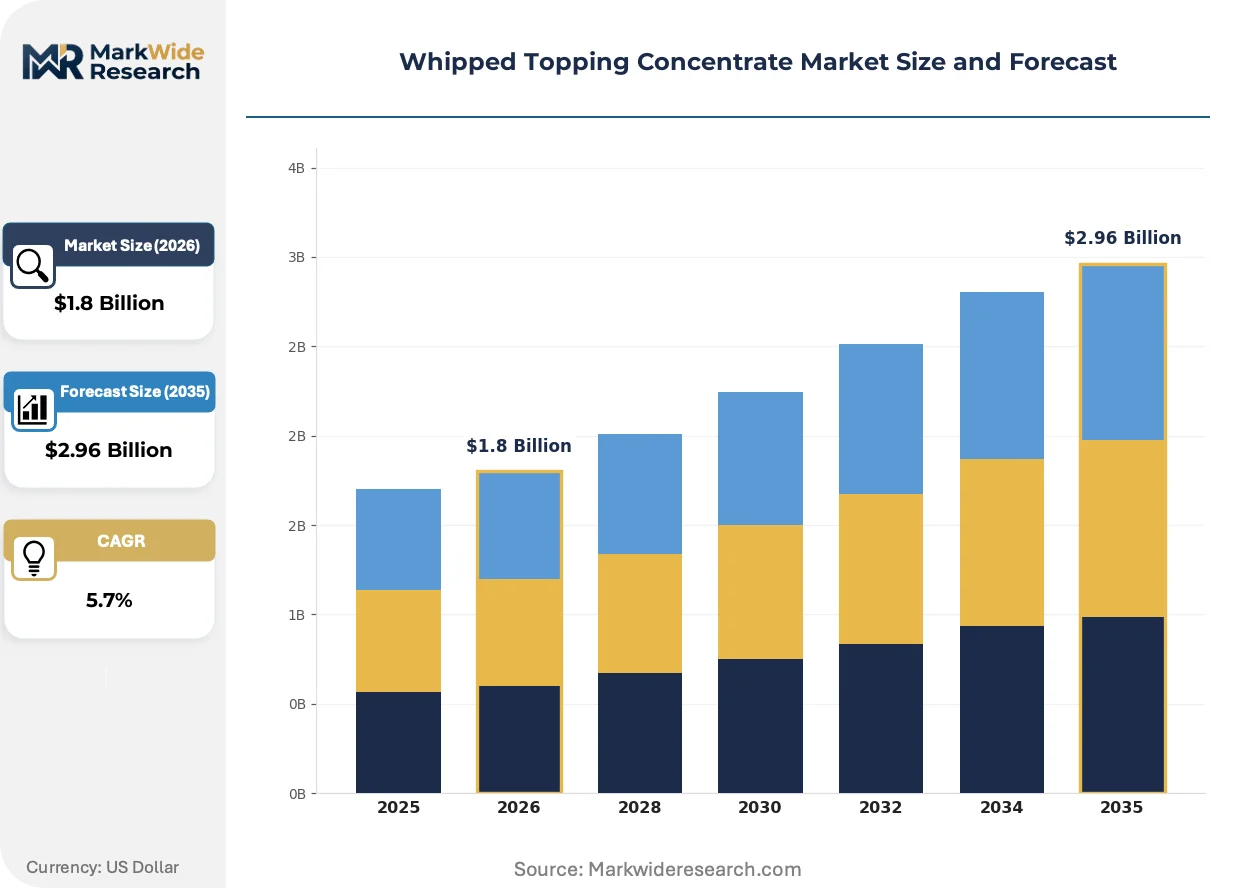
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-Dairy, Dairy, Organic, Flavored Form: Powder, Liquid, Aerosol, Ready-to-Use End User: Food Service, Retail, Bakery, Catering Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Oppenheimer Companies, RE Rich Family Holding, SKM Egg Products, Lasenor, Peak Food LLC, RICH Products Corporation, BASF SE, Palsgaard A/S, Fine Organics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Whipped Topping Concentrate Market Evolving Landscape
Continuous processing technology is displacing batch manufacturing in concentrate production, enabling real-time viscosity adjustment and reducing aeration variability. This shift is compressing quality control labor while expanding output consistency for high-volume bakery contracts.
Automated in-line aeration monitoring is automating overrun control in liquid concentrate manufacturing. Industrial bakeries in Germany and the United States are adopting these systems fastest, driven by penalty clauses for foam density deviations in chain supply agreements. The technology is automating quality assurance staffing reductions while tightening specification compliance.
REACH chemical registration requirements are tightening emulsifier approval pathways for European manufacturers. ECHA substance evaluation is extending lead times for novel stabilizer introductions, compressing formulation innovation cycles. German and French concentrate producers are responding by accelerating pre-registration dossier investments and shifting toward existing approved hydrocolloid portfolios.
Foodservice distributors are consolidating purchasing decisions into centralized procurement functions with technical specification authority. Large bakery chains and frozen dessert processors are displacing fragmented regional buying with national contract structures that demand batch-to-batch consistency guarantees. This concentration is most visible in Germany, where industrial bakery cooperatives negotiate multi-year concentrate supply agreements with embedded quality auditing rights.
Whipped Topping Concentrate Market Segmentation
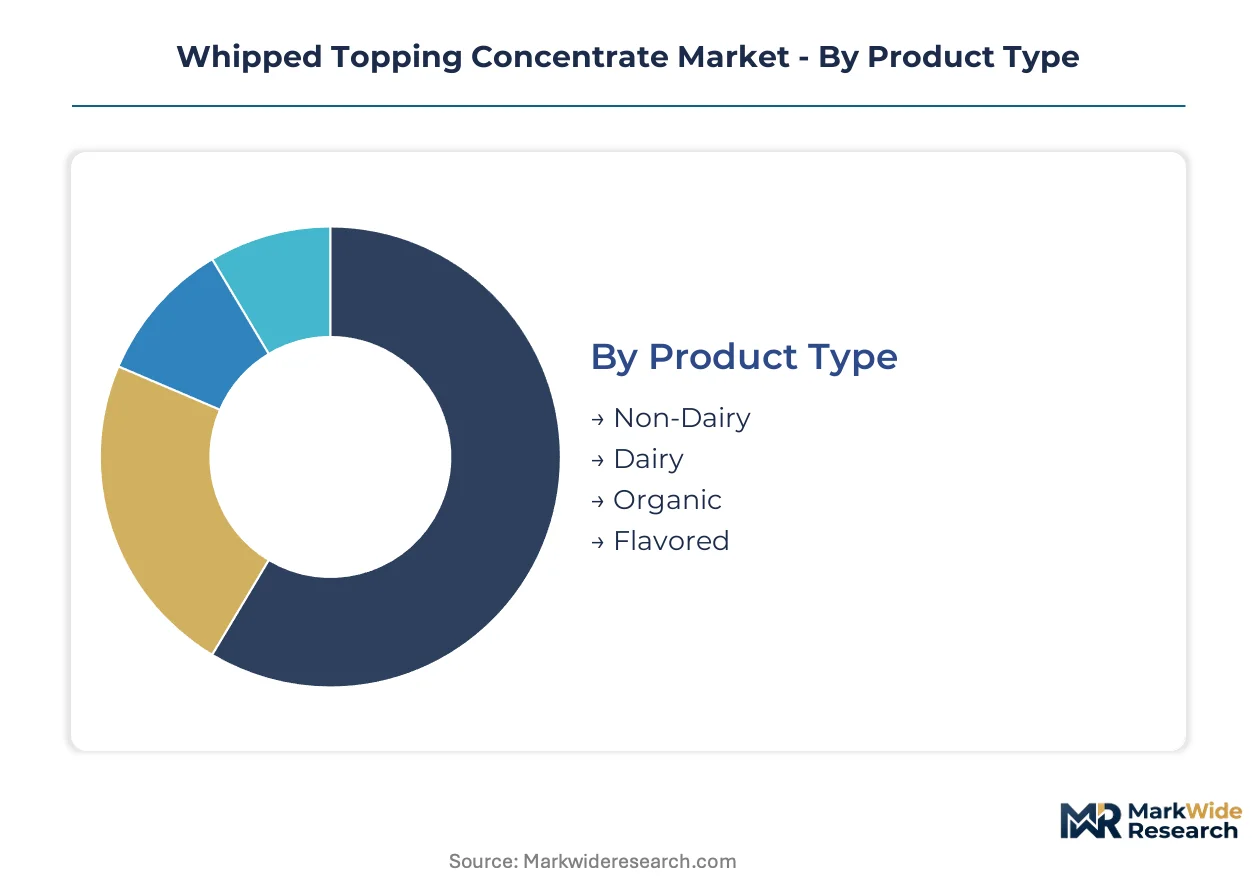
Whipped topping concentrate manufacturers navigate divergent formulation requirements across dairy and plant-based platforms, while powder-versus-liquid trade-offs reshape cold-chain investments. Segmentation clarity determines procurement channel selection and margin capture for industrial buyers.
Product Type:
The customization-standardization spectrum spans from commodity dairy bases to certified organic systems with traceable supply chains.
- Non-Dairy:Hydrogenated coconut and palm kernel oil emulsions now dominate volume as bakery chains reformulate for plant-forward menus. Industrial frozen dessert processors in Germany and quick-service restaurant networks across North America drive procurement concentration.
- Dairy:Traditional milk-fat concentrates retain footholds in premium bakery segments where clean-label dairy identity commands price premiums. FDA 21 CFR 135.110 fat-content thresholds constrain formulation flexibility for products seeking whipped topping designation.
- Organic:Certified organic bases carry dual compliance burdens—USDA National Organic Program and EU Organic Regulation—extending development timelines.
- Flavored:Vanilla, chocolate, and seasonal variants target retail dessert assembly kits with differentiated positioning.
Most installed capacity flows through Non-Dairy. Expansion is steepest in Organic.
Form:
Cost tier stratification separates ambient-stable powders from refrigerated liquid systems with diverging logistics overhead.
- Powder:Dehydrated concentrates eliminate cold-chain dependency and extend ambient shelf life to 18-24 months. Indian foodservice distributors favor powder for infrastructure-constrained secondary markets.
- Liquid:High-solids emulsions enable rapid reconstitution in high-volume bakery operations. Automated in-line aeration monitoring systems in German industrial bakeries optimize overrun consistency for liquid inputs.
- Aerosol:Propellant-dispensed formats serve instant-decoration needs in catering and small-format retail.
- Ready-to-Use:Pre-whipped concentrates target convenience-oriented retail channels with minimal labor requirements.
Powder commands the broadest geographic reach. Liquid is climbing the fastest in foodservice penetration.
End User:
Customer type fragmentation splits between specification-heavy industrial buyers and price-sensitive retail channels.
- Food Service:Chain kitchens demand batch-to-batch consistency guarantees with embedded quality auditing rights. Quick-service restaurant expansion across franchise networks standardizes on concentrated bases to reduce per-unit labor.
- Retail:Consumer-packaged concentrates compete on convenience positioning in supermarket dairy and frozen aisles.
- Bakery:Industrial bakeries in Germany represent the largest procurement volumes, negotiating multi-year supply agreements with tanker delivery terms.
- Catering:Event-service operators prioritize portion-control formats and rapid deployment for dessert finishing.
Food Service absorbs the majority of liquid concentrate output. Bakery is gaining share fastest on direct-to-industrial distribution models.
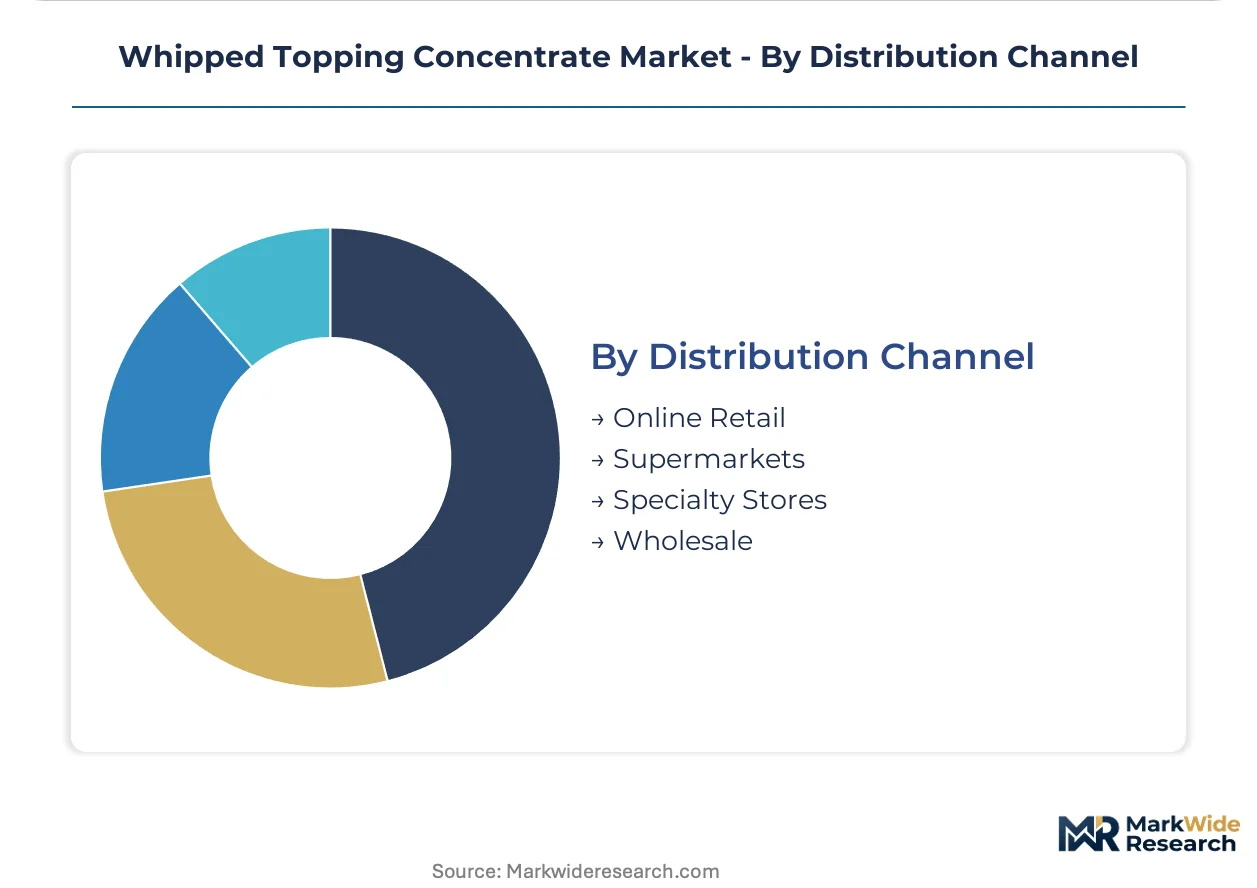
Distribution Channel:
Supply concentration varies from consolidated wholesale distributors to fragmented specialty retail networks.
- Online Retail:E-commerce platforms serve small-format buyers and specialty ingredient seekers with ambient shipping economics.
- Supermarkets:Mass retail chains stock ready-to-use and aerosol formats in dairy and frozen dessert sections.
- Specialty Stores:Gourmet and bakery supply retailers cater to artisan producers with premium and organic concentrates.
- Wholesale:Foodservice distributors consolidate purchasing decisions into centralized procurement functions with technical specification authority.
Wholesale channels move the highest tonnage. Online Retail is expanding most quickly in underpenetrated geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial bakeries and frozen dessert processors anchor procurement volumes across the whipped topping concentrate landscape. Bakery chains in quick-service networks are expanding concentrated topping base adoption to streamline kitchen operations. Clean-label reformulations and plant-forward ingredient standards are pushing manufacturers toward non-dairy emulsion systems.
Germany
Industrial bakery cooperatives negotiate multi-year concentrate supply agreements with embedded quality auditing rights. REACH chemical registration requirements under ECHA oversight tighten emulsifier approval pathways for European manufacturers. The Baden-Württemberg and Bavaria regions host the densest clusters of frozen dessert processors adopting automated in-line aeration monitoring systems.
United States
Quick-service restaurant chains standardize dessert preparation across franchise locations using concentrated bases to reduce per-unit labor inputs. FDA governs whipped topping labeling and fat-content standards under 21 CFR 135.110, constraining formulation flexibility for clean-label transitions. The Midwest industrial corridor spanning Illinois and Ohio concentrates frozen dessert manufacturing capacity with direct-to-industrial tanker delivery models.
India
Foodservice distributors in secondary markets favor ambient-stable powder concentrates due to infrastructure constraints. FSSAI regulates food additive standards and labeling requirements for whipped topping formulations entering the domestic market. Maharashtra and Gujarat host expanding quick-service networks where underdeveloped dessert topping infrastructure creates first-mover positioning opportunities for concentrate suppliers.
France
EU Green Deal implementation accelerates plant-based concentrate adoption as industrial bakeries reformulate to meet sustainability procurement standards. ANSM oversees food contact material safety for packaging systems used in concentrate distribution. The Île-de-France region concentrates foodservice procurement decision-making into centralized technical specification functions with national contract structures.
China
Bakery chain expansion in tier-two cities drives demand for consistent foam stability in finished dessert applications. SAMR monitors food additive usage and labeling compliance under national food safety standards. The Yangtze River Delta manufacturing belt concentrates hydrogenated vegetable oil processing capacity supporting high-overrun whipped applications.
Whipped Topping Concentrate Market Competitive Landscape
Global majors compete with regional champions across emulsifier technology and frozen dessert ingredient networks. The market structure shows moderate consolidation around specialty lipid portfolios and aerated food system expertise. Three archetypes dominate: diversified chemical conglomerates with oleochemical divisions, dedicated emulsifier and stabilizer specialists, and integrated frozen dessert ingredient suppliers. Competitive moves center on pre-registration dossier investments for REACH compliance and direct-to-industrial distribution bypassing traditional foodservice channels.
Within the integrated frozen dessert ingredient tier, RICH Products Corporation exemplifies scale-driven supply relationship management across North American bakery and foodservice networks. Palsgaard A/S anchors the emulsifier-specialist archetype through Danish technical expertise in aerated food systems. BASF SE represents the diversified chemical conglomerate model with German-based specialty lipid portfolios supporting high-overrun applications. These three occupy distinct competitive positions without direct product overlap, reducing price-driven confrontation while segmenting procurement decisions by technical specification complexity.
| Leading Market Players |
|---|
| Oppenheimer Companies |
| RE Rich Family Holding |
| SKM Egg Products |
| Lasenor |
| Peak Food LLC |
| RICH Products Corporation |
| BASF SE |
| Palsgaard A/S |
| Fine Organics |
| Others |
Value Network & Pricing Analysis
Industrial bakery cooperatives in Germany negotiate multi-year concentrate supply agreements with embedded quality auditing rights, locking in contract-based long-term offtake pricing that insulates large buyers from spot volatility in tropical oil feedstocks. This procurement concentration compresses margin capture for mid-tier manufacturers while rewarding scale players with volume-tier discounts and tanker delivery terms.
Pricing Analysis
Input-cost pass-through from coconut and palm kernel oil markets dominates pricing dynamics, with hydrogenated vegetable oil fractionation costs flowing directly into concentrate base pricing. Three-tier pricing structure across premium organic, standard industrial, and economy powder grades reflects certification level and cold-chain dependency. Pricing pressure stems from sustainability certification costs in EU markets, squeezing non-dairy concentrate margins. Foodservice distributors show highest price sensitivity due to fragmented regional buying, while industrial bakeries accept premium positioning for batch-to-batch consistency guarantees.
Supply Chain Analysis
Direct-to-industrial tanker delivery models serve large bakery chains in Germany and the United States, bypassing traditional foodservice distributors to compress channel costs. Manufacturing concentration clusters in Germany, the United States, and China, with hydrogenated vegetable oil processing capacity anchoring supply in the Yangtze River Delta and Midwest industrial corridor. Raw material dependencies center on Southeast Asian palm kernel oil, Indian coconut oil, and European emulsifier inputs. Single-source vulnerability in tropical oil supply chains exposes manufacturers to climate-driven harvest disruptions. Distribution runs through consolidated wholesale channels with technical specification authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in whipped topping concentrates hinges on plant-based fat system cost-down curves and premium organic tier penetration, as clean-label procurement standards reshape buyer willingness-to-pay.
For Market Incumbents: Anchor market position through captive supply of hydrogenated vegetable oil fractions and backward integration into emulsifier manufacturing. Invest in REACH pre-registration dossiers to secure novel stabilizer approval timelines. Defend against mid-tier competitors by locking industrial bakery cooperatives into multi-year tanker delivery contracts with embedded quality auditing rights. For New Entrants and Emerging Players: Launch via ambient-stable powder concentrate distribution to underdeveloped quick-service networks in Indian secondary markets where cold-chain infrastructure gaps favor dehydrated formats. Target foodservice distributors in Maharashtra and Gujarat with rapid-reconstitution formulations. Pursue FSSAI compliance early to accelerate domestic market entry ahead of multinational competitors. For Investors and Strategic Acquirers: Integrated frozen dessert ingredient suppliers are the most active acquirer in this space, seeking emulsifier technology and direct-to-industrial distribution capabilities. Long-term viability favors specialists with aerated food system expertise and established bakery chain relationships. Monitor EU CSRD carbon labeling alignment as inflection indicator for procurement preference shifts toward verified lifecycle emissions data.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oleochemical Feedstocks | Captive palm kernel and coconut oil supply secures margin stability against tropical price volatility. |
| REACH Pre-Registration Investment | ECHA compliance dossiers accelerate novel emulsifier market entry ahead of formulation competitors. |
| Direct-to-Industrial Tanker Delivery | Bulk supply agreements with German bakery cooperatives compress distributor margins and improve pricing power. |
| Organic Certification Dual Compliance | USDA National Organic Program and EU Organic Regulation alignment unlocks premium tier pricing in clean-label segments. |
| Automated In-Line Aeration Monitoring | German industrial bakery adoption of overrun control systems tightens specification compliance and reduces quality labor. |
Research Methodology
Direct dialogue with plant operations managers at industrial bakeries, procurement leads at frozen dessert processors, emulsifier R&D directors, foodservice distributor category buyers, and regulatory affairs specialists at concentrate manufacturers grounded the qualitative foundation. Secondary validation drew from FDA 21 CFR 135.110 filings, ECHA REACH substance registrations, FSSAI additive standards, EU Green Deal implementation documents, and customs trade data for hydrogenated vegetable oil imports. Bottom-up volume modeling across product type, form, and end-user segments triangulated against top-down market sizing from industrial bakery capacity data.
Segment-level projections across non-dairy, dairy, organic, and flavored product types; powder, liquid, aerosol, and ready-to-use forms; and foodservice, retail, bakery, and catering end-users fed into the analytical framework over the projection horizon. CAGRs were derived from elasticity-adjusted demand curves incorporating quick-service restaurant expansion rates and clean-label reformulation timelines. Forecast inputs included palm kernel oil price volatility indices and EU CSRD disclosure adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained tropical supply disruptions or accelerated FDA plant-based identity standard revisions. Periodic stress-testing of base assumptions is recommended, particularly regarding hydrogenated vegetable oil regulatory thresholds and REACH emulsifier approval timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Jasmine Extract Market
Ingredients
Textured Wheat Protein Market
Ingredients
Dried Distillers' Grains with Soluble Market
Ingredients
North America Collagen Ingredients Market
Ingredients
Low-Odor Fish Protein Hydrolysates from Med Species Market
Ingredients
Asia-Pacific Agar Market
Ingredients
Pig Protein Concentrate Market
Ingredients
Macleaya Cordata Extract Market
Ingredients
Italy Soy Protein Market
Ingredients
Torula Yeast Market
Ingredients
Omega 6 Market
Ingredients
Ground-Nut Oil Market
Ingredients
Murumuru Butter Market
Ingredients
South America Spirulina Extract Market
Ingredients
Global Personal Care Active Ingredients Market
Ingredients
Soy Lecithin Market