
 Vitamin K Market | 2026-2036
Vitamin K Market Size, Share, and Industry Trends Forecast 2026-2036
Vitamin K Market Analysis
China is narrowing its dependence on imported vitamin K intermediates through domestic fermentation capacity expansion. DSM-Firmenich leverages its integrated nutraceutical platform to sustain long-term supply agreements with pharmaceutical formulators. BASF SE anchors European phytomenadione production through advanced chemical synthesis capabilities. Kappa Bioscience specializes in menaquinone-7 derived from natto fermentation, competing on bioavailability claims against synthetic alternatives.
Vitamin K denotes a family of fat-soluble compounds—phylloquinone (K1) from plant sources and menaquinones (K2) from bacterial fermentation—essential for gamma-carboxylation of clotting factors and osteocalcin activation. Industrial production employs chemical synthesis for K1 and controlled fermentation for K2 homologs, with purity specifications typically exceeding 98% for pharmaceutical grades. Nutritional Supplements command the largest revenue pool among applications, though Functional Foods exhibit faster growth as fortification expands beyond dairy into plant-based alternatives. Menaquinone-7 leads product type expansion due to its longer half-life and bone health positioning, while Menadione remains restricted primarily to animal feed applications.
FDA oversight of dietary supplement cGMP compliance shapes manufacturing standards for US-bound vitamin K products, while EFSA novel food evaluations govern menaquinone-7 market access across EU member states. China's NMPA registration requirements for imported nutritional ingredients create additional compliance layers for foreign suppliers. Stakeholders must monitor evolving pharmacovigilance data linking vitamin K2 to cardiovascular outcomes, as regulatory reclassifications could redirect demand across application segments.
Market Dynamics
EFSA novel food authorization requirements are compressing menaquinone-7 market entry timelines, forcing suppliers to front-load toxicology and bioavailability studies before commercial launch.
Growth Catalysts
- Aging demographics:Osteoporosis prevalence among adults over 65 drives sustained phylloquinone and menaquinone demand in United States dietary supplements.
- Sports nutrition expansion:Athletes and fitness consumers seek bone density and cardiovascular support, expanding K2 adoption beyond traditional geriatric positioning.
- EFSA novel food framework:Regulatory clarity on menaquinone-7 safety profiles enables compliant suppliers to secure first-mover advantage across EU member states.
Market Restraints
- Fermentation input volatility:Soy protein and carbohydrate feedstock costs for natto-derived K2 fluctuate with agricultural commodity cycles.
- Supplier concentration:European phytomenadione synthesis capacity clusters around German and Swiss chemical manufacturers.
- Synthetic K1 price competition:Chemically produced phylloquinone maintains cost advantage over fermented K2 alternatives in commodity applications.
Strategic Opportunities
- Plant-based dairy fortification:Oat, almond, and soy milk alternatives represent underpenetrated vectors for K2 MK-7 integration.
- China domestic substitution:NMPA registration pathways for imported ingredients create opening for local fermentation capacity to displace foreign suppliers.
- Personalized nutrition platforms:Direct-to-consumer vitamin subscriptions enable precise dosing and combination formulations with vitamin D and calcium.
Industry Challenges
- Fermentation scale-up expertise:Qualified bioprocess engineers capable of optimizing Bacillus subtilis yields for MK-7 remain scarce.
- Cross-jurisdiction dossier preparation:Divergent FDA cGMP, EFSA novel food, and NMPA registration requirements multiply compliance documentation burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vitamin K Market |
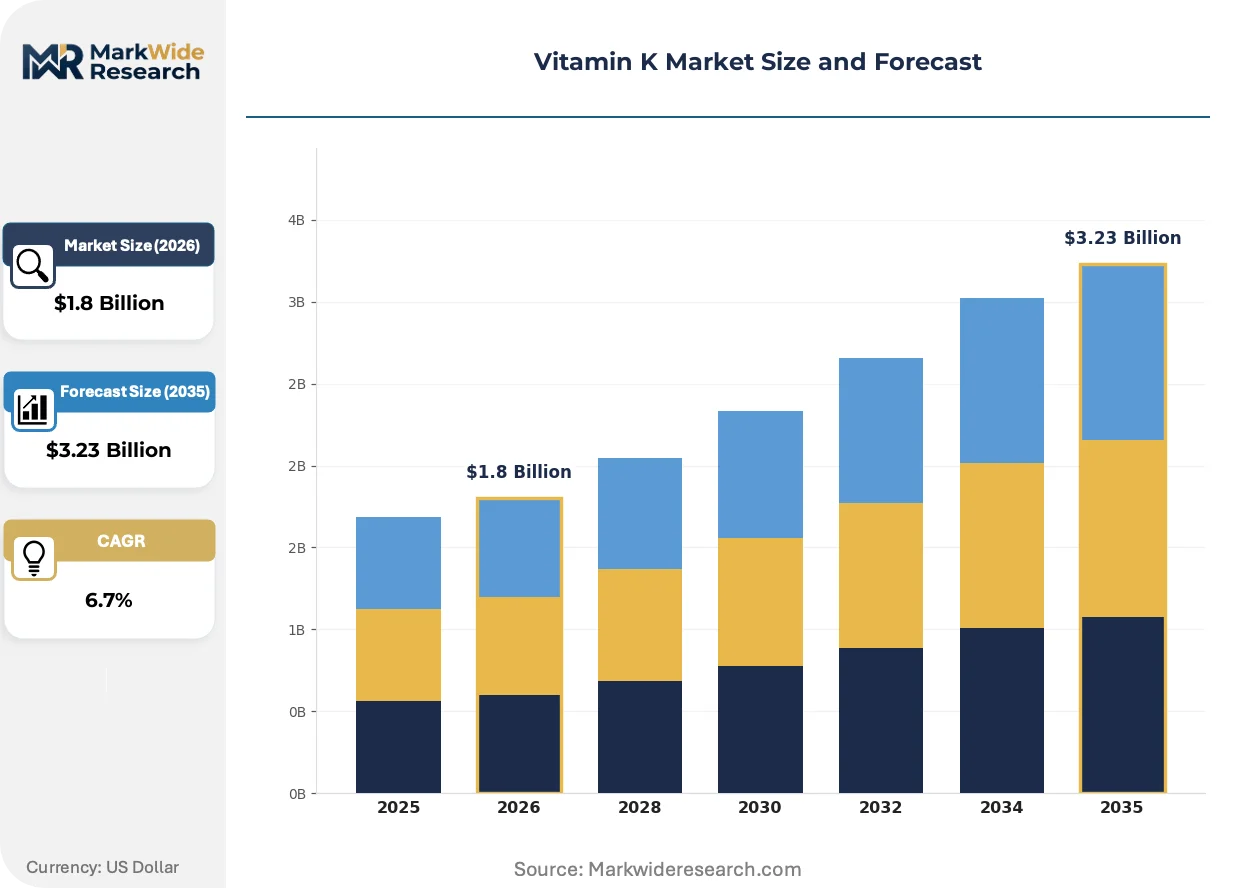
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phytomenadione, Menaquinone-4, Menaquinone-7, Menadione Application: Nutritional Supplements, Pharmaceuticals, Functional Foods, Fortified Beverages End User: Healthcare Providers, Athletes, Elderly, General Consumers Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Pharmacies |
| Companies Covered | Lonza, NOW Foods, DSM-Firmenich, Amphastar Pharmaceuticals, Pharmavite, BASF SE, Glanbia, Pfizer, Kappa Bioscience, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vitamin K Market Emerging Trajectories
Production methodologies and distribution architectures are diverging between synthetic chemistry and biotechnology pathways, with regulatory science increasingly determining competitive viability.
Controlled fermentation for menaquinone-7 is migrating from batch processing toward continuous bioreactor systems. Supplement manufacturers in North America and Western Europe are adopting these outputs for enhanced batch-to-batch consistency. The technology is migrating from pharmaceutical-grade specifications toward nutritional supplement price points, compressing synthetic K2 margins.
EFSA's 2023 updated guidance on vitamin K2 novel food applications tightens requirements for menaquinone-7 stability data and bioequivalence demonstration. European suppliers must now submit extended shelf-life studies and comparative pharmacokinetic profiles. The functional foods segment faces the steepest compliance burden, with several pending applications delayed for additional bone biomarker evidence.
Ingredient buyers are consolidating supplier relationships around vertically integrated fermentation houses with captive analytical capabilities. Traditional distributors and ingredient brokers lose share to direct manufacturer partnerships with certified quality documentation. This concentration is most visible in United States sports nutrition contract manufacturing, where brands demand single-source accountability for K2 purity and MK-7 isomer ratio verification.
Vitamin K Market Segmentation
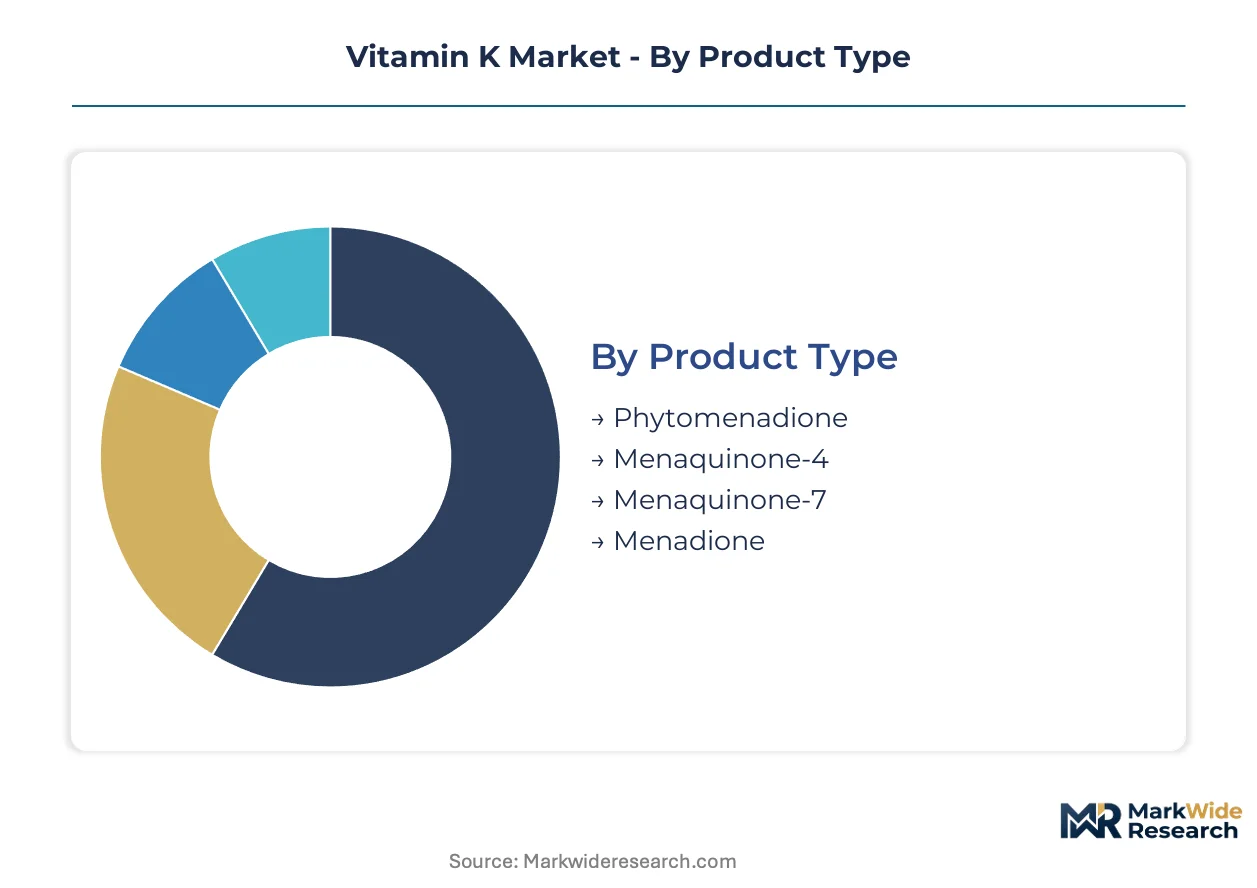
Vitamin K procurement patterns diverge sharply across product chemistries and end-use specifications, with pharmaceutical-grade phylloquinone commanding distinct supply chain protocols versus fermented menaquinones. Customer technical support requirements scale with application complexity, driving supplier investment in formulation assistance and stability documentation.
Product Type:
After-sales intensity varies dramatically across vitamin K chemistries, with pharmaceutical phytomenadione requiring batch-specific certificates of analysis and stability data that fermented K2 variants rarely match.
- Menaquinone-7:Longest half-life among vitamin K homologs enables once-daily dosing in bone health formulations. Demand concentrates in United States dietary supplement brands targeting osteoporosis prevention, though EFSA novel food dossier requirements delay EU market penetration for new entrants.
- Phytomenadione:Synthetic K1 dominates anticoagulant reversal protocols and neonatal prophylaxis. Hospital procurement in Germany and Switzerland anchors volume, with FDA cGMP compliance mandatory for US pharmaceutical supply contracts.
- Menaquinone-4:Shorter-chain menaquinone used primarily in Japanese osteoporosis pharmaceuticals and select Asian nutraceuticals.
- Menadione:Synthetic provitamin restricted to animal feed applications due to human toxicity concerns at elevated doses.
By volume, phytomenadione leads. By growth pace, menaquinone-7 is ahead.
Application:
Cost tier stratification separates commodity feed additives from premium pharmaceutical and nutraceutical grades, with analytical certification burden determining margin structure.
- Nutritional Supplements:Largest revenue pool combining bone health, cardiovascular, and sports nutrition positioning. Direct-to-consumer brands in the United States drive menaquinone-7 adoption, while private label manufacturers compete on MK-7 isomer ratio verification and third-party testing documentation.
- Functional Foods:Fastest-expanding vector as oat milk and almond yogurt fortification extends beyond traditional dairy. European plant-based dairy startups face EFSA stability data requirements that slow formulation timelines.
- Pharmaceuticals:Anticoagulant reversal and neonatal deficiency treatment command highest purity specifications, typically exceeding 98% with full impurity profiling.
- Fortified Beverages:Emerging application constrained by vitamin K lipophilicity and emulsion stability challenges in aqueous matrices.
Supplements capture current volume leadership. Functional foods are expanding most quickly.
End User:
Customer sophistication determines specification stringency, with healthcare institutions demanding pharmaceutical-grade documentation that general consumers rarely require.
- Elderly:Primary target for osteoporosis and cardiovascular positioning, driving sustained menaquinone-7 uptake in pharmacy and online channels.
- Athletes:Bone density and recovery positioning expands K2 adoption beyond geriatric demographics into sports nutrition.
- Healthcare Providers:Hospitals and clinics prescribe pharmaceutical phytomenadione for anticoagulant reversal, with procurement governed by national formularies.
- General Consumers:Mass-market multivitamin inclusion represents lowest-margin, highest-volume tier with minimal technical support requirements.
Elderly consumers anchor current demand. Athletes represent the steepest expansion trajectory.
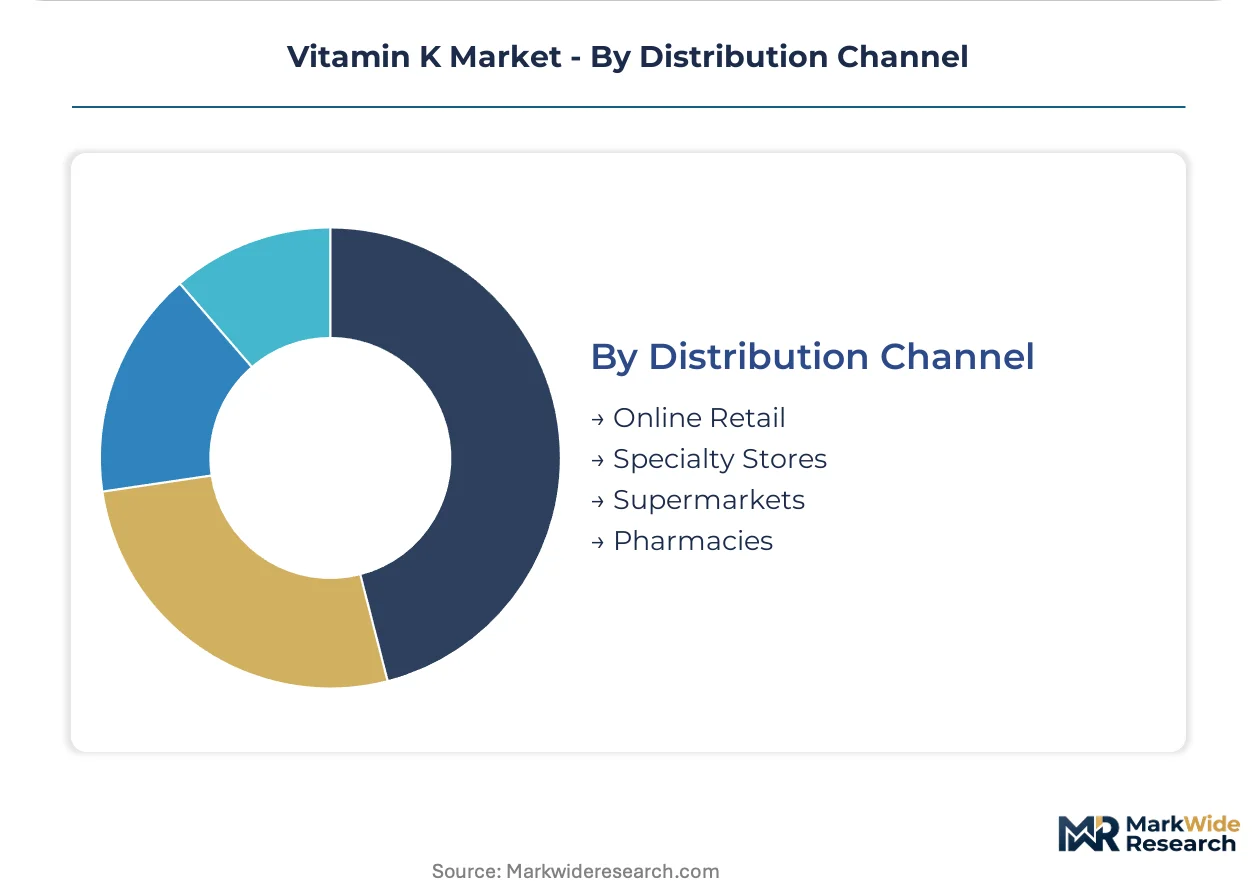
Distribution Channel:
Channel concentration reflects customer education needs, with complex menaquinone-7 formulations migrating toward direct-to-consumer platforms that enable detailed bioavailability messaging.
- Online Retail:Subscription vitamin services enable precise dosing customization and combination with vitamin D and calcium. United States direct-to-consumer brands dominate menaquinone-7 volume.
- Pharmacies:Professional recommendation drives phytomenadione sales and premium K2 positioning, particularly in German and Swiss markets.
- Specialty Stores:Sports nutrition retailers and health food cooperatives cater to athlete and wellness-focused segments with curated K2 assortments.
- Supermarkets:Mass-market multivitamin placement captures general consumer volume at compressed margins.
Pharmacies lead by current revenue. Online retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fermentation capacity for menaquinone-7 clusters in Switzerland and Germany, while phytomenadione synthesis dominates German chemical corridors. Chinese domestic production is displacing imported intermediates. United States dietary supplement brands drive finished product demand.
United States
Aging demographics and sports nutrition trends sustain menaquinone-7 procurement by direct-to-consumer brands. FDA cGMP compliance shapes manufacturing standards for all vitamin K products bound for dietary supplement channels. The Greater Boston and New Jersey pharmaceutical corridors host formulation laboratories serving both nutraceutical and pharmaceutical applications.
Germany
Hospital procurement of phytomenadione for anticoagulant reversal anchors pharmaceutical-grade demand. EFSA novel food evaluations for menaquinone-7 create compliance bottlenecks for EU market entrants. The Rhine-Ruhr chemical manufacturing belt maintains advanced synthesis capabilities for K1 production.
Switzerland
Precision fermentation expertise concentrates around Basel and Zurich for high-purity menaquinone-7 output. Swissmedic oversight of pharmaceutical ingredients ensures documentation standards that transfer to nutraceutical supply contracts. The Lake Geneva biotech corridor houses analytical laboratories certifying MK-7 isomer ratios for export markets.
China
Domestic Bacillus subtilis fermentation capacity is narrowing dependence on imported vitamin K intermediates. NMPA registration requirements for imported nutritional ingredients create procedural advantages for local suppliers. The Yangtze River Delta fermentation cluster is scaling continuous bioreactor systems for menaquinone-7 production.
Japan
Traditional natto-derived menaquinone-7 consumption underpins steady demand for fermented K2 variants. PMDA oversight of pharmaceutical applications maintains strict purity specifications for clinical-grade products. The Kansai region around Osaka retains specialized fermentation houses supplying both domestic nutraceuticals and export markets.
Vitamin K Market Vendor Landscape
Integrated chemical conglomerates and specialized fermentation houses split the market along synthesis-versus-biotechnology lines. German and Swiss manufacturers anchor phytomenadione supply through controlled chemical processes, while Nordic and Asian specialists compete on menaquinone-7 bioavailability positioning. Two strategic archetypes dominate: vertically integrated nutraceutical platforms with captive analytical capabilities, and pure-play fermentation specialists selling into branded supplement channels. Capacity expansion in continuous bioreactor systems and backward integration into fermentation feedstocks represent the dominant competitive moves.
Among the integrated chemical manufacturers, BASF SE exemplifies the European synthesis archetype with Rhine-Ruhr production assets. DSM-Firmenich occupies a position bridging pharmaceutical-grade phytomenadione and nutritional menaquinone-7 through its integrated platform. Kappa Bioscience represents the pure-play fermentation specialist model, with Norwegian origins and natto-derived K2 positioning.
| Leading Market Players |
|---|
| Lonza |
| NOW Foods |
| DSM-Firmenich |
| Amphastar Pharmaceuticals |
| Pharmavite |
| BASF SE |
| Glanbia |
| Pfizer |
| Kappa Bioscience |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Delta fermentation cluster anchors global menaquinone-7 capacity expansion, translating concentrated bioreactor expertise into downstream pricing leverage for domestic Chinese suppliers. This geographic consolidation compresses margins for imported K2 alternatives while elevating procurement power among vertically integrated nutraceutical platforms.
Pricing Analysis
EFSA novel food authorization requirements dictate the pricing tier structure across European vitamin K markets, separating pharmaceutical-grade phytomenadione from fermented K2 variants. Three-tier pricing structure across premium, standard, and economy levels reflects certification burden, with FDA cGMP compliance commanding the highest premiums for US-bound pharmaceutical contracts. Cost compression in commodity menadione runs through synthetic chemistry scale advantages. General consumer multivitamin buyers exhibit greatest price sensitivity; hospital procurement committees demonstrate least.
Supply Chain Analysis
Dual-use fermentation technology controls under export restriction regimes limit continuous bioreactor system transfers to Chinese facilities, constraining Western capacity expansion. Supply concentrates in Switzerland, Germany, and China's Yangtze Delta for menaquinone-7, with phytomenadione synthesis anchored in German chemical corridors. Raw material flows draw from soy protein isolates, carbohydrate feedstocks, and specialized Bacillus subtilis strain libraries. Single-source vulnerability concentrates around Swiss analytical laboratories certifying MK-7 isomer ratios. Distribution runs through direct manufacturer partnerships supplanting traditional ingredient brokers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vitamin K procurement is shifting toward platform-based supplier relationships where captive analytical capabilities and regulatory dossier libraries create interoperability advantages. This ecosystem consolidation rewards integrated fermentation houses with novel food approval track records.
For Market Incumbents: Insulate market position through backward integration into fermentation feedstock supply and captive Bacillus subtilis strain development. DSM-Firmenich's integrated platform demonstrates how pharmaceutical-grade documentation capabilities transfer to nutraceutical pricing power. Synthetic K1 manufacturers face substitution pressure from biofermented K2 alternatives with superior bioavailability claims. For New Entrants and Emerging Players: European plant-based dairy fortification represents the most penetrable white-space vector, with oat and almond milk categories lacking stable K2 emulsion formulations. Direct-to-consumer subscription models enable precise dosing customization without pharmacy channel barriers. Target sports nutrition contract manufacturers seeking single-source accountability for MK-7 purity verification. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-scarcity play because EFSA novel food authorization timelines and FDA cGMP compliance burdens create durable moats around approved suppliers. Acquisition targets should display vertical integration from fermentation through analytical certification. The signal to watch is pharmacovigilance data linking K2 to cardiovascular outcomes, which could trigger demand reclassification across application segments.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Bioreactor Scale-Up | Swiss and German fermentation houses migrate from batch processing toward continuous systems for MK-7 consistency. |
| Novel Food Dossier Investment | EFSA authorization requirements force front-loaded toxicology spending before EU commercial launch. |
| Backward Integration into Feedstocks | Natto-derived K2 specialists secure soy protein and carbohydrate supply against agricultural commodity cycles. |
| Direct-to-Consumer Platform Launch | Subscription vitamin services enable precise K2 dosing with vitamin D and calcium combination formulations. |
| Plant-Based Dairy Fortification Partnership | Oat and almond milk alternatives represent underpenetrated vectors for menaquinone-7 integration beyond traditional dairy. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA cGMP guidance documents, EFSA novel food opinions, NMPA registration filings, and customs trade data for vitamin K intermediates. Conversations with fermentation plant managers, nutraceutical procurement leads, regulatory affairs directors, and sports nutrition contract manufacturers inform supply-side dynamics. Secondary validation draws from pharmaceutical company 10-K disclosures, EFSA scientific opinions, and hospital procurement database extracts. Bottom-up volume modeling triangulates against top-down market sizing across product chemistry and application segments.
Forecast inputs incorporate fermentation yield improvements, regulatory approval timelines, and substitution elasticities between synthetic K1 and fermented K2 variants. Segmentation dimensions span product chemistry, application tier, end-user sophistication, and distribution channel structure. CAGRs derive from iterative reconciliation of volume trajectory assumptions with value-based pricing dynamics. Industry-specific inputs include EFSA novel food pipeline status and NMPA domestic substitution policy implementation.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-supported fermentation clusters would shift outcomes. Material shifts in EFSA pharmacovigilance classifications or FDA dietary supplement enforcement posture would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Middle East and Africa Food Fortifying Agents Market
Vitamin Fortified
Global Mineral Fortification Market
Vitamin Fortified
North America Vitamin a Market
Vitamin Fortified
Retinyl Linoleate Market
Vitamin Fortified
Europe Food Fortifying Agents Market
Vitamin Fortified
Global Adult Vitamin Gummies Market
Vitamin Fortified
Vitamin D Market
Vitamin Fortified
Calcium-Fortified Food Market
Vitamin Fortified
Global Quercetin Market
Vitamin Fortified
Vitamin Yeast Market
Vitamin Fortified
Middle East Feed Vitamins Market
Vitamin Fortified
Vitamin a in Feed Additives Market
Vitamin Fortified
Vitamin C Market
Vitamin Fortified
Vitamins Drink Market
Vitamin Fortified
Synthetic Vitamin E Market
Vitamin Fortified
North America Food Fortifying Agents Market