
 Global Multivitamin Capsules and Tablets Market | 2026-2036
Global Multivitamin Capsules and Tablets Market Size, Share, and Industry Trends Forecast 2026-2036
Global Multivitamin Capsules and Tablets Market Foresight
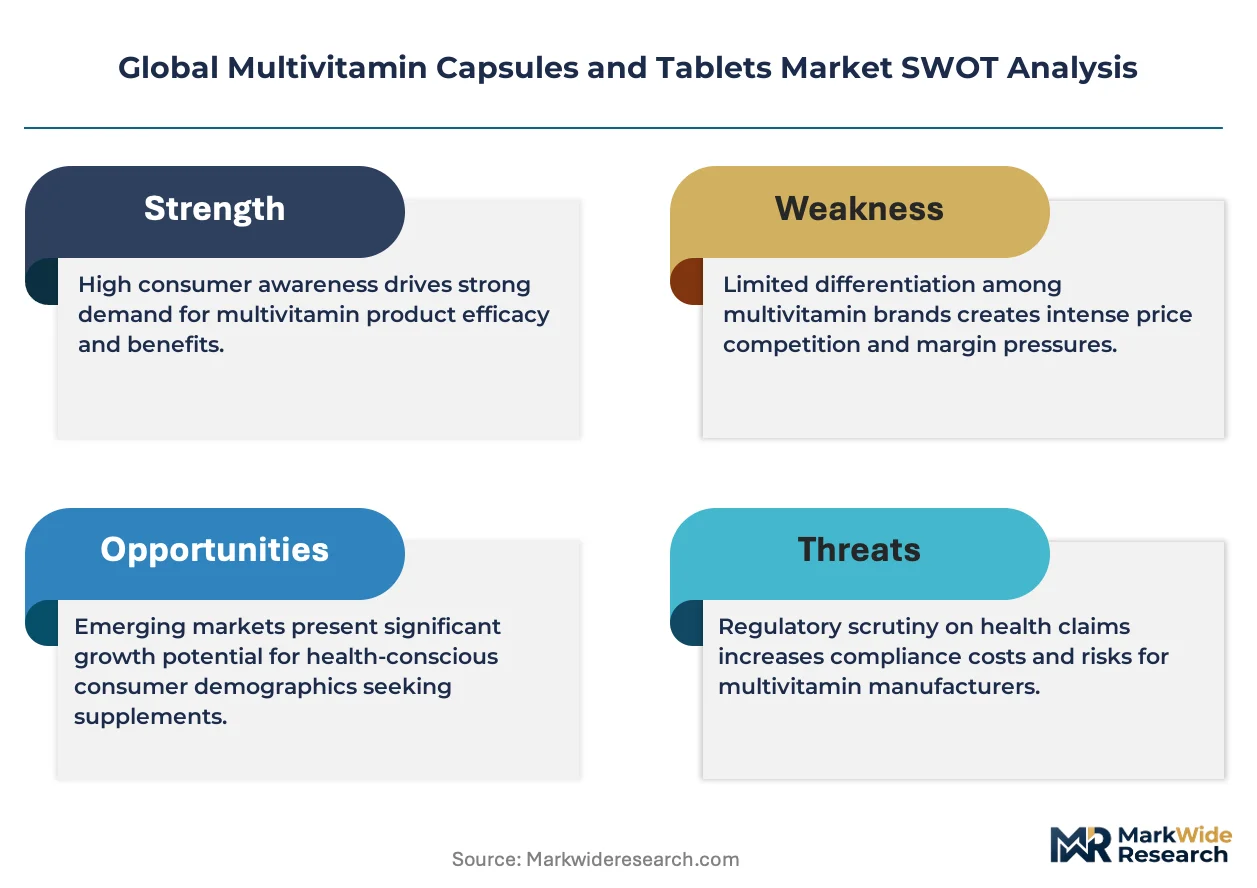
The EU Green Deal's nutrition-labelling requirements is realigning how multivitamin producers formulate and market across European retail channels. Bayer AG leverages its pharmaceutical heritage to sustain credibility with pharmacy buyers in regulated markets. Nature's Bounty Co. anchors its position through broad retail distribution and private-label partnerships. Amway Corporation differentiates via direct-sales networks that bypass traditional wholesale markups.
Multivitamin capsules and tablets are solid oral dosage forms containing two or more essential vitamins, often combined with minerals, manufactured through direct compression or wet granulation to achieve specified dissolution profiles and bioavailability targets. These products serve preventive health maintenance, addressing micronutrient gaps in populations with dietary deficiencies, restricted intake patterns, or elevated physiological demands. The capsules category leads in premium positioning due to faster absorption claims and gelatin-free alternatives, while gummies are capturing younger adult segments despite higher sugar content and manufacturing complexity. Distribution through online stores is expanding fastest as subscription models and telehealth referrals reshape replenishment behavior, though pharmacies retain margin strength in markets with reimbursement linkages or pharmacist counseling requirements.
The US FDA oversees dietary supplement Good Manufacturing Practices, while the EMA coordinates member-state assessments of health claims under the Nutrition and Health Claims Regulation, and India's FSSAI enforces standards for micronutrient fortification levels in domestically manufactured tablets. These frameworks elevate compliance costs for new entrants but protect established producers with in-house analytical laboratories and regulatory affairs teams. Stakeholders must monitor evolving maximum permitted levels for fat-soluble vitamins as toxicology data prompts downward revisions in major jurisdictions.
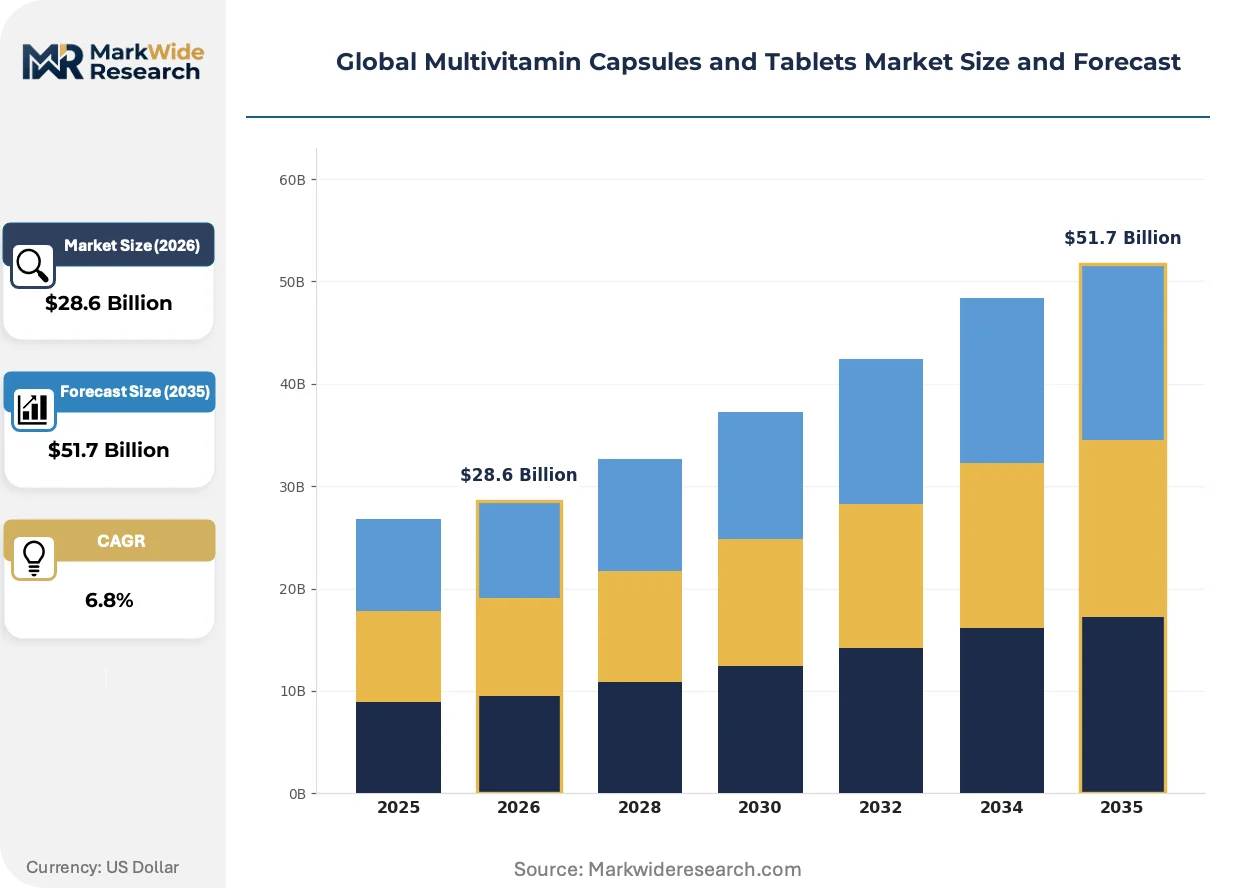
Market Dynamics
The EU Green Deal's nutrition-labelling requirements are forcing multivitamin producers to reformulate products and restructure marketing claims across European retail channels, compressing margins for non-compliant portfolios while rewarding early regulatory adapters.
Growth Catalysts
- FSSAI fortification mandates:India's enforcement of micronutrient standards in domestically manufactured tablets is expanding addressable market for compliant producers in tier-one cities.
- Senior bone-health demand:Japan's aging population is expanding consumption of calcium-vitamin D combinations through pharmacy and direct-sales channels.
- Telehealth referral networks:Online subscription models linked to physician consultations are reshaping replenishment behavior in US and German markets.
Market Restraints
- Gelatin supply concentration:Bovine and porcine gelatin sourcing from Brazil and Argentina creates input cost volatility for capsule manufacturers.
- Fat-soluble vitamin caps:EFSA and FDA toxicology revisions are downward-revising maximum permitted levels for vitamins A, D, E, and K, forcing reformulation.
- EU novel food barriers:The Nutrition and Health Claims Regulation creates multi-year approval timelines for new ingredient combinations.
Strategic Opportunities
- India tier-two expansion:Pharmacy chains in Pune, Ahmedabad, and Jaipur are building dedicated supplement aisles beyond saturated Mumbai-Delhi corridors.
- Gelatin-free alternatives:HPMC and pullulan capsules are capturing premium positioning among vegetarian and halal-certified consumer segments.
- PLI scheme leverage:India's production-linked incentive scheme for pharmaceuticals offers cost advantages for domestic tablet manufacturing.
Industry Challenges
- Regulatory affairs talent scarcity:Cross-jurisdictional compliance with FDA, EMA, and FSSAI frameworks requires specialized analytical laboratory capabilities.
- Legacy ERP integration:Direct-to-consumer subscription platforms demand real-time inventory synchronization with existing wholesale pharmacy systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Multivitamin Capsules and Tablets Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Tablets, Softgels, Chewable Tablets, Gummies Application: General Health, Immune Support, Bone Strength, Energy Boost, Skin Care Customer Type: Adults, Kids, Seniors, Athletes, Pregnant Women Distribution Channel: Pharmacies, Online Stores, Health Food Stores, Supermarkets, Direct Sales |
| Companies Covered | Abbott Laboratories, Bayer AG, Herbalife Nutrition, Pfizer Inc, Nestlé Health Science, Amway Corporation, GNC Holdings Inc, Nature's Bounty Co., Nature's Way Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Multivitamin Capsules and Tablets Market Shifts & Advancements
Formulation science and distribution infrastructure are undergoing parallel transformation as bioavailability engineering meets channel-specific packaging requirements and regulatory disclosure standards tighten across major markets.
Personalized micronutrient dosing platforms are converging with at-home diagnostic testing to enable subscription-based replenishment calibrated to individual biomarker profiles. Younger adult segments in Germany and South Korea are adopting these services fastest. This convergence is compressing the traditional one-size-fits-all multivitamin model into niche positioning.
REACH and RoHS substance restrictions are extending into dietary supplement packaging materials, forcing migration from certain plasticizers and coatings in EU-bound products. Manufacturers with in-house analytical laboratories are absorbing compliance costs more efficiently than contract producers. Capsule and tablet exporters to the Netherlands and Sweden are reformulating shell compositions ahead of 2027 implementation timelines.
Pharmacist counseling requirements in France and Japan are preserving pharmacy channel margins against e-commerce encroachment. Subscription models bypassing wholesale markups are displacing traditional retail replenishment in US and UK markets where telehealth referrals carry prescription-like authority. Germany's Apotheken mandate maintains professional gatekeeping that online pure-plays cannot replicate.
Global Multivitamin Capsules and Tablets Market Segmentation
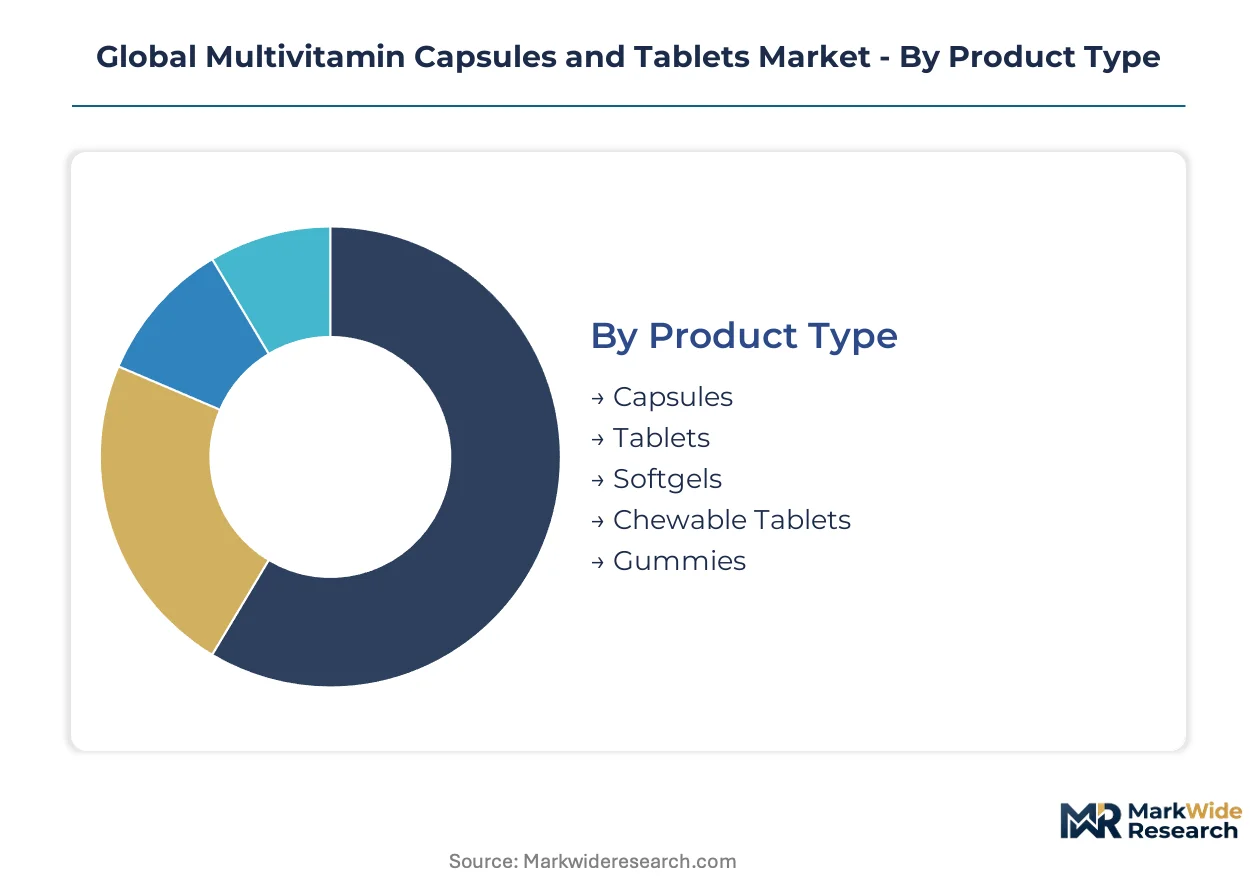
Multivitamin segmentation reflects divergent bioavailability engineering, regulatory compliance burdens, and channel-specific packaging requirements across preventive health applications. Formulation choices directly determine dissolution profiles, shelf stability, and permissible marketing claims in regulated jurisdictions.
Product Type:
Buyers differentiate primarily by absorption speed claims and dietary restriction compatibility, with gelatin content and shell composition driving premium positioning decisions.
- Capsules:Two-piece gelatin or HPMC shells encasing powder or beadlet formulations enable faster gastric emptying and higher bioavailability for fat-soluble vitamins. Demand concentrates in Germany and South Korea where vegetarian-certified alternatives command pharmacy shelf placement. Japan's PMDA labeling requirements favor capsule formats for senior-targeted bone-health combinations.
- Tablets:Direct-compressed or wet-granulated solid dosage forms offer superior mechanical stability and extended shelf life through moisture-barrier packaging. India's FSSAI fortification mandates favor tablet production for domestic manufacturing scale under PLI scheme incentives.
- Softgels:Gelatin-encapsulated liquid fills suit oil-soluble vitamin suspensions requiring precise unit dosing.
- Chewable Tablets:Compressible formulations with flavor masking target pediatric and geriatric populations with swallowing difficulties.
- Gummies:Pectin or gelatin-based confectionery matrices capture younger adult segments despite higher sugar content and complex moisture-control manufacturing.
Tablets lead volumes today; gummies are gaining share fastest.
Application:
Clinical positioning and reimbursement linkages separate preventive maintenance from condition-specific formulations in pharmacy channel negotiations.
- General Health:Broad-spectrum micronutrient combinations addressing dietary gap coverage without disease-specific claims. Formulations avoid EFSA-regulated health claim territories to maintain multi-market registration efficiency.
- Immune Support:Elevated vitamin C, D, and zinc combinations with documented T-cell function associations. US telehealth subscription models concentrate replenishment for this segment through physician referral networks.
- Bone Strength:Calcium-vitamin D-K2 matrices targeting osteoporosis prevention in post-menopausal populations. Japan's expanding senior demographic drives pharmacy and direct-sales volume.
- Energy Boost:B-complex and iron formulations addressing fatigue complaints in working-age adults.
- Skin Care:Biotin, vitamin E, and antioxidant combinations positioned at beauty retail crossover points.
General Health dominates current revenue; Immune Support shows steepest expansion trajectory.
Customer Type:
Physiological life-stage requirements dictate nutrient density, excipient safety profiles, and packaging child-resistance specifications.
- Adults:Standard-dose formulations covering RDA-level micronutrient replacement for employed populations with irregular dietary patterns. India's tier-one pharmacy chains allocate dedicated shelf space to adult maintenance portfolios.
- Seniors:Reduced iron content, enhanced B12 absorption aids, and bone-density focused mineral ratios. Japan's aging population expands pharmacy counseling-dependent purchases for this segment.
- Kids:Weight-appropriate dosing with palatability engineering and choking-hazard mitigation through gummy or chewable formats.
- Athletes:Electrolyte-inclusive formulations with NSF or Informed Sport certification for competitive use compliance.
- Pregnant Women:Folic acid and iron-optimized prenatal combinations with teratogenic risk screening for herbal excipients.
Adults generate largest absolute volume; Seniors demonstrate fastest share growth.
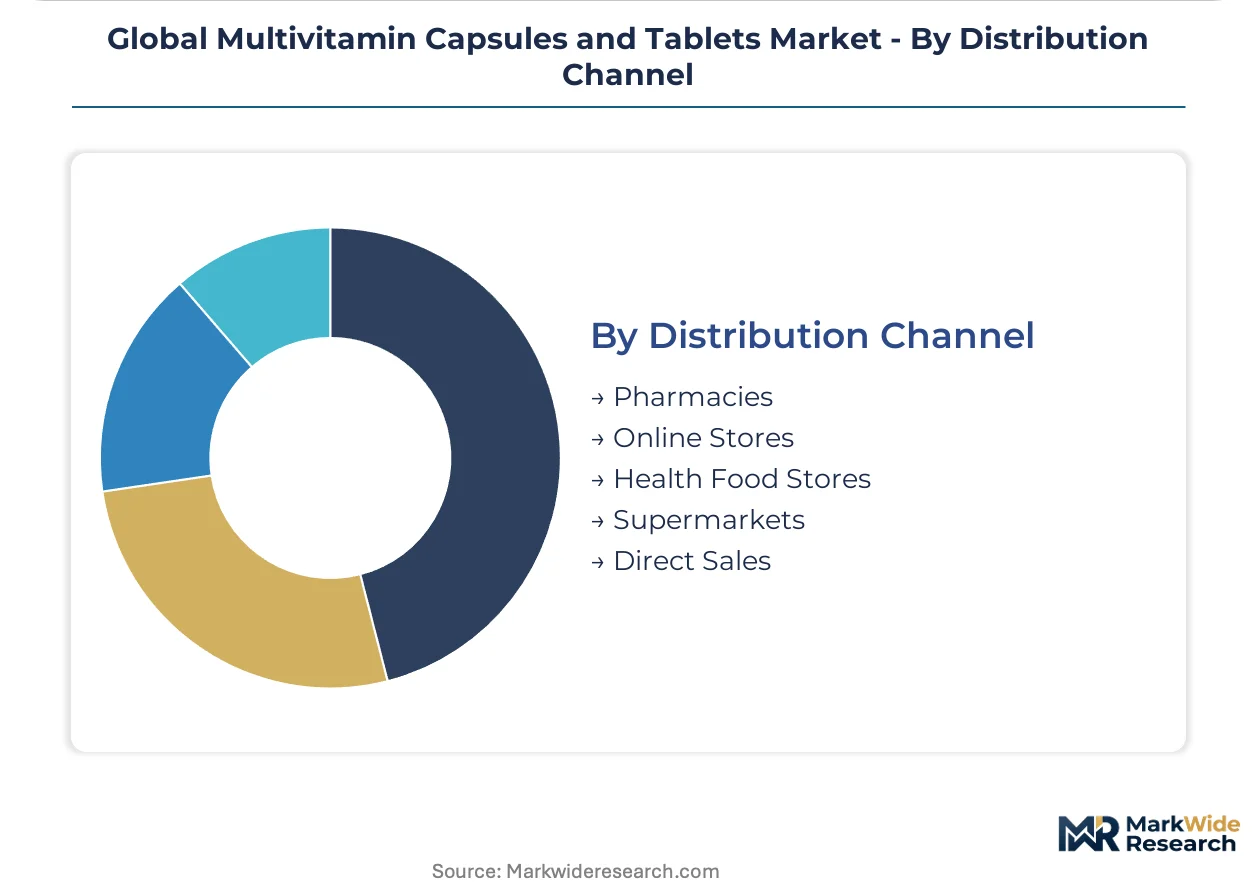
Distribution Channel:
Margin structure and professional gatekeeping intensity separate prescription-adjacent pharmacy channels from direct-to-consumer bypass models.
- Pharmacies:Professional counseling requirements in France and Japan preserve premium pricing and reimbursement linkages for condition-specific formulations. Germany's Apotheken mandate maintains regulatory compliance verification at point of sale.
- Online Stores:Subscription replenishment platforms with telehealth integration reshape US and UK purchasing patterns through algorithmic reorder timing. India's e-commerce platforms build dedicated supplement aisles in Mumbai and Delhi corridors.
- Health Food Stores:Staff-trained environments emphasizing organic and non-GMO certification differentiation.
- Supermarkets:Mass-market accessibility with price-promotional mechanics driving impulse purchase conversion.
- Direct Sales:Amway-style network marketing bypassing wholesale markups through personalized distributor relationships in East Asian markets.
Pharmacies retain volume leadership; Online Stores climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Multivitamin manufacturing originated in post-war pharmaceutical hubs where vitamin synthesis scaled for mass preventive health. The industry now distributes formulation expertise across three continents with distinct regulatory architectures shaping local competitive dynamics.
United States
Telehealth-integrated subscription models and pharmacy benefit manager negotiations drive volume concentration. FDA dietary supplement GMP enforcement elevates compliance costs for new entrants. Manufacturing clusters in New Jersey and California supply domestic tablet and capsule demand through direct-to-consumer platforms.
Germany
Apotheken-mandated professional counseling preserves pharmacy channel premiums against e-commerce displacement. EFSA health claim restrictions under EU Green Deal nutrition-labelling requirements compress marketing flexibility. Bavarian and North Rhine-Westphalia production facilities export tablet formulations across EU member states.
Japan
Expanding senior populations consume calcium-vitamin D combinations through pharmacy and direct-sales networks. PMDA labeling requirements favor capsule formats for bone-health positioning. Tokyo-Osaka industrial corridors host gelatin-free HPMC capsule manufacturing for halal-certified export markets.
India
FSSAI fortification mandates and PLI scheme incentives expand domestic tablet manufacturing scale. Tier-one pharmacy chains in Mumbai and Delhi build dedicated supplement aisles while e-commerce platforms penetrate tier-two cities. Gujarat and Maharashtra host contract manufacturing clusters serving export markets.
United Kingdom
Online subscription models with algorithmic replenishment timing displace traditional retail pharmacy purchasing. MHRA alignment with EFSA nutrient profiling criteria restricts label claims for imported formulations. Southeast England distribution centers serve EU re-export demand post-Brexit customs restructuring.
Global Multivitamin Capsules and Tablets Market Competitive Landscape
Premium-margin players sit above commodity-margin players across regulatory compliance capability and pharmacy channel access. The vendor base stratifies into three tiers: pharmaceutical heritage conglomerates with in-house analytical laboratories, direct-sales network operators bypassing wholesale markups, and private-label contract manufacturers serving retail consolidation. Consolidation pressures concentrate among mid-scale producers lacking cross-jurisdictional regulatory affairs teams. Dominant competitive moves include M&A for laboratory capabilities and geographic expansion into India's PLI-subsidized manufacturing zones.
Within the pharmaceutical heritage tier, Bayer AG and Pfizer Inc exemplify regulatory-driven competitive positioning. Among direct-sales network operators, Amway Corporation occupies a position bypassing traditional wholesale markups through personalized distributor relationships. Nature's Bounty Co. represents broad retail distribution archetypes with private-label partnership exposure. These three anchors illustrate how compliance infrastructure, channel architecture, and manufacturing scale separate margin tiers across the analysis window.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Bayer AG |
| Herbalife Nutrition |
| Pfizer Inc |
| Nestlé Health Science |
| Amway Corporation |
| GNC Holdings Inc |
| Nature's Bounty Co. |
| Nature's Way Products |
| Others |
Supply & Pricing Matrix
Captive gelatin sourcing from Brazilian and Argentinian rendering facilities anchors both input security and margin stability for capsule-dominant portfolios, while outsourced tablet manufacturing under India's PLI scheme compresses unit economics for generic competitors. This integration divergence separates premium-positioned producers with bovine supply contracts from price-competitive players exposed to spot-market porcine gelatin volatility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates pharmacy-certified formulations from private-label retail and bulk generic tiers. Price differentiation hinges on EFSA/FDA compliance certification and vegetarian-certified HPMC shell alternatives. Cost compression in the economy tier is intensifying because Indian contract manufacturers are scaling FSSAI-compliant tablet output. Pharmacy buyers in Germany and Japan demonstrate lowest price sensitivity due to professional counseling requirements, while supermarket channels in the US and UK face highest substitution elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Brazilian bovine gelatin processors supplying European capsule manufacturers. Active pharmaceutical ingredient production draws from India, China, and Switzerland for vitamin precursors and mineral chelates. Supply chain risk centers on REACH and RoHS substance restrictions extending into EU-bound packaging materials. Distribution runs through pharmacy wholesale networks in France and Germany, direct-sales networks in Japan, and algorithmic subscription platforms in the US and UK.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where senior-targeted bone-health formulations and personalized micronutrient platforms are shifting demand toward premium specifications with embedded regulatory compliance.
For Market Incumbents: Lock in analytical laboratory capabilities and cross-jurisdictional regulatory affairs teams to defend against emerging contract manufacturers with PLI-subsidized cost bases. Deepen backward integration into HPMC and pullulan capsule shell production to capture vegetarian-certified premium positioning ahead of 2027 REACH implementation timelines. For New Entrants and Emerging Players: Personalized dosing platforms integrated with at-home diagnostic testing offer technology-first wedge into Germany and South Korea's younger adult segments. Target India's tier-two pharmacy chains in Pune, Ahmedabad, and Jaipur where dedicated supplement aisle construction outpaces established Mumbai-Delhi saturation. Deploy telehealth referral partnerships as the primary go-to-market angle to bypass wholesale pharmacy markups. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale producers lack in-house toxicology screening and multi-market registration infrastructure. Frame long-term viability around regulatory compliance moats widening across the FDA, EMA, and FSSAI enforcement windows. Acquisition target archetype: regional tablet manufacturers with PLI scheme eligibility and latent analytical laboratory capacity. Signal to watch: EFSA downward revisions to fat-soluble vitamin maximum permitted levels triggering forced reformulation cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Gelatin-Free Capsule Manufacturing Scale-Up | HPMC and pullulan alternatives capture vegetarian, halal, and kosher-certified pharmacy shelf placement in Germany. |
| Telehealth Subscription Platform Integration | Algorithmic replenishment timing with physician referral networks displaces traditional retail pharmacy purchasing in US markets. |
| India PLI Scheme Manufacturing Footprint | Domestic tablet production under FSSAI fortification mandates achieves cost advantages for export to Middle East and Africa. |
| Cross-Jurisdictional Regulatory Affairs Buildout | In-house EMA, FDA, and FSSAI compliance teams protect margin tiers against enforcement escalation and toxicology revision cycles. |
| Tier-Two Pharmacy Channel Expansion | Dedicated supplement aisle partnerships in Pune, Ahmedabad, and Jaipur access underpenetrated demand beyond saturated tier-one corridors. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining executive interviews with regulatory affairs directors, pharmacy chain procurement managers, contract manufacturing plant heads, and direct-sales network operators. Secondary validation draws from FDA dietary supplement GMP filings, EFSA health claim register updates, FSSAI fortification mandate notifications, and customs trade data for gelatin and vitamin precursor imports. Bottom-up demand modeling and top-down macroeconomic alignment ensure triangulation across data sources.
Granularity-level framing applies product type, application, customer life-stage, and distribution channel dimensions at country-level resolution across the projection horizon. CAGRs derive from segment-specific volume trajectories weighted by pricing tier evolution. Forecast inputs include EMA toxicology revision schedules, PLI scheme capacity addition timelines, and telehealth platform penetration curves in subscription-eligible demographics.
The model holds under stable regulatory enforcement intensity and intact supply chain logistics; deviation in gelatin supply disruptions, REACH implementation acceleration, or FSSAI mandate expansion would shift volume and value trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Latin America Herbal Supplements Market
Nutritional Supplements
Japan Dietary Supplements Market
Nutritional Supplements
Europe Omega-3 Products Market
Nutritional Supplements
Bone Broth Protein Powder Market
Nutritional Supplements
North America Saffron Supplements Market
Nutritional Supplements
Vegan Collagen Protein Market
Nutritional Supplements
Global Egg Protein Market
Nutritional Supplements
Maternity Vitamins and Supplements Market
Nutritional Supplements
CBD Nutraceuticals Market
Nutritional Supplements
Flax Protein Powder Market
Nutritional Supplements
Choline Bitartrate Market
Nutritional Supplements
Europe Meal Replacement Products Market
Nutritional Supplements
L-Leucine Market
Nutritional Supplements
Asia-Pacific Arachidonic Acid Market
Nutritional Supplements
Hydrolyzed Whey Protein Market
Nutritional Supplements
Nutraceutical Gummies Market