
 Poland Car Rental Market | 2026-2036
Poland Car Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Poland Car Rental Market Analytics
Electric drivetrain components are displacing conventional combustion engine parts in rental fleet procurement, and this shift is realigning total cost of ownership calculations for Polish operators. Europcar International leverages its centralized fleet management platform to sustain operational efficiency across major Polish cities. Sixt anchors its competitive stance through premium vehicle positioning and digital-first booking infrastructure. Panek SA dominates the domestic landscape with extensive local branch coverage and integrated mobility services.
Car rental constitutes a short-term vehicle access service where operators maintain titled automobile fleets available for temporary use against periodic fees, typically governed by mileage allowances, insurance bundling, and fuel policies. The service enables commercial and individual mobility without capital-intensive vehicle ownership, with fleet composition calibrated to seasonal demand fluctuations and residual value optimization. Short-term rental captures the largest transaction volume among service types, while corporate rental commands superior margin pools through negotiated annual contracts and guaranteed utilization rates. SUV configurations lead vehicle type demand during winter months and leisure travel peaks, whereas sedan categories serve steady business traveler segments.
Poland's General Inspectorate of Road Transport enforces operator licensing and vehicle safety compliance, while EU-wide emissions standards under the European Green Deal shape fleet renewal timelines toward lower-carbon models. The Polish Financial Supervision Authority monitors consumer credit arrangements tied to long-term rental and leasing products, influencing contract structuring and risk assessment protocols. Stakeholders must evaluate charging infrastructure density and EU battery passport requirements when projecting fleet electrification trajectories and capital deployment schedules.
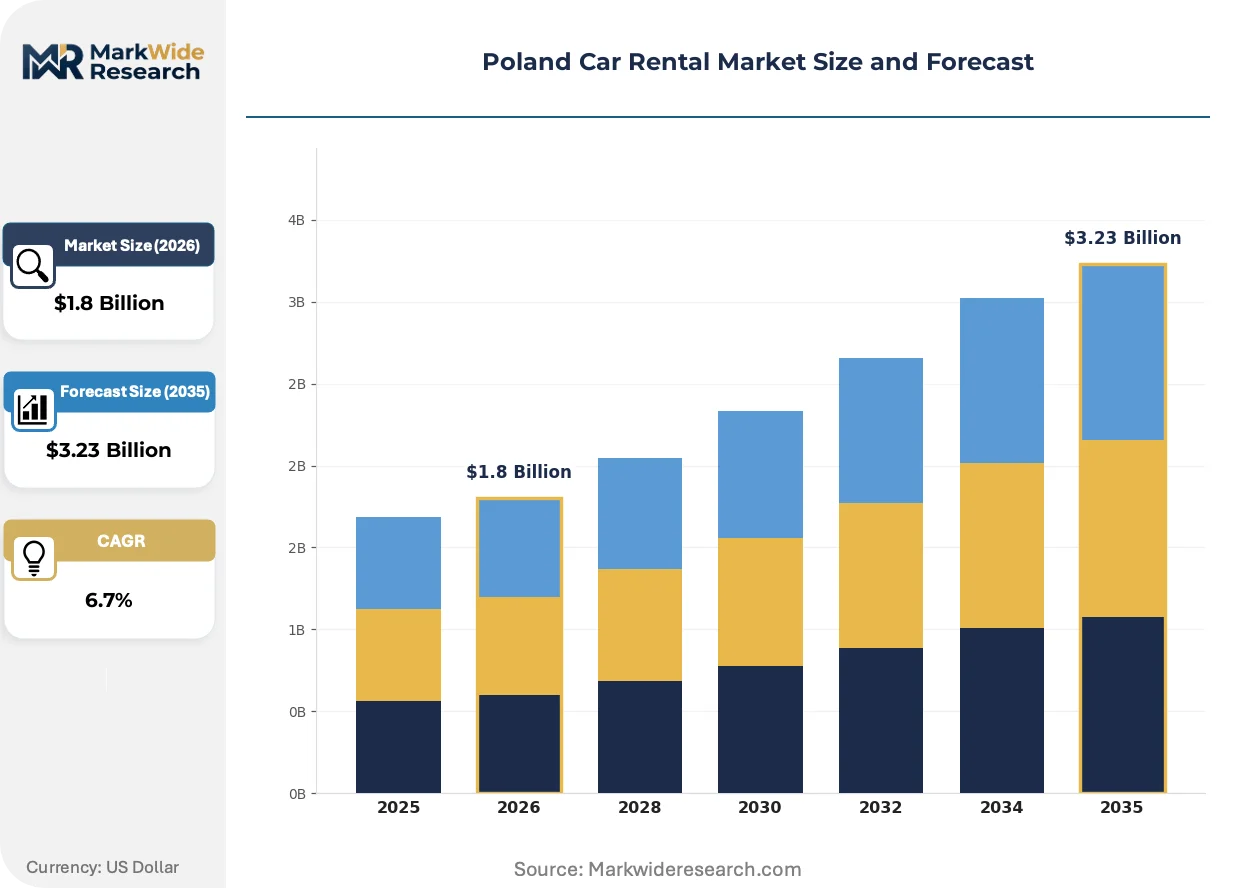
Market Dynamics
Fleet electrification timelines are compressing as Poland's General Inspectorate of Road Transport enforces EU Green Deal emissions standards, forcing operators to accelerate capital deployment toward battery-electric vehicles while managing residual value uncertainty in secondary markets.
Growth Catalysts
- EU Green Deal fleet mandates:Binding emissions reduction targets under the European Green Deal are accelerating Polish rental operator procurement of battery-electric vehicles, creating procurement volume concentration through 2035.
- Corporate outsourcing:Polish manufacturing and logistics firms are transferring fleet ownership risk to rental operators, generating contracted revenue pools with guaranteed utilization floors.
- Tri-City corridor demand density:Gdańsk-Gdynia-Sopot metropolitan concentration is producing localized fleet utilization premiums that justify dedicated branch infrastructure.
Market Restraints
- Charging infrastructure gaps:Poland's uneven fast-charging station distribution across secondary cities is constraining electric fleet operational radius and forcing hybrid transition strategies.
- Battery residual value opacity:Absence of standardized battery health certification frameworks is inflating depreciation risk assumptions and compressing financing availability for electric fleet acquisition.
- EU battery passport compliance:Traceability and recycling accountability requirements under pending EU regulations are layering administrative cost burdens onto fleet management operations.
Strategic Opportunities
- Intermodal mobility integration:Rail-station adjacent rental hubs in Warsaw and Kraków are enabling seamless last-mile connectivity bundles with public transit operators.
- Corporate subscription models:Flexible monthly vehicle access contracts are displacing traditional annual leasing arrangements among Polish SME professional services segments.
- EU Just Transition Fund:Regional development financing for sustainable transport infrastructure is opening subsidy pathways for charging depot construction in Silesian industrial zones.
Industry Challenges
- Telematics integration complexity:Legacy fleet management platforms require substantial reconfiguration to accommodate real-time battery state-of-charge monitoring and predictive maintenance algorithms.
- Certified technician scarcity:High-voltage systems repair capability gaps across Polish vocational training pipelines are extending vehicle downtime intervals and inflating third-party service dependency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poland Car Rental Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Short-Term Rental, Long-Term Rental, Luxury Rental, Corporate Rental Vehicle Type: SUV, Sedan, Hatchback, Van Customer Type: Business Travelers, Tourists, Local Residents, Event Attendees Distribution Channel: Online Booking, Rental Agency, Travel Agency, Direct Walk-In |
| Companies Covered | Budget Rent a Car System Inc., TOPCARS, Europcar International, Sixt, Panek SA, Enterprise Holding Inc., The Hertz Corporation, Carwiz, Avis Budget Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poland Car Rental Market Evolving Landscape
Digital-native booking platforms are compressing customer acquisition costs while artificial intelligence applications are reshaping fleet utilization forecasting and dynamic pricing architectures across Polish urban markets.
Telematics-enabled predictive maintenance systems are automating service interval optimization for rental operators. Polish fleet managers at Warsaw-based branches are deploying these platforms to reduce unplanned downtime by 15-20 percent. The technology is automating workshop scheduling and parts procurement workflows that previously required manual intervention.
Poland's Ministry of Infrastructure is enforcing periodic technical inspection tightening aligned with EU vehicle safety harmonization directives. Rental operators must now document enhanced brake system and emissions testing compliance before fleet renewal authorization. Short-term rental segments face compressed vehicle turnover cycles as inspection stringency escalates.
Subscription-based vehicle access is displacing traditional daily-rate structures among Polish corporate accounts. Procurement departments at Kraków technology firms are negotiating all-inclusive monthly fees covering insurance, maintenance, and mileage pools. This model concentrates most visibly in professional services verticals where vehicle needs fluctuate with project staffing cycles.
Poland Car Rental Market Segmentation
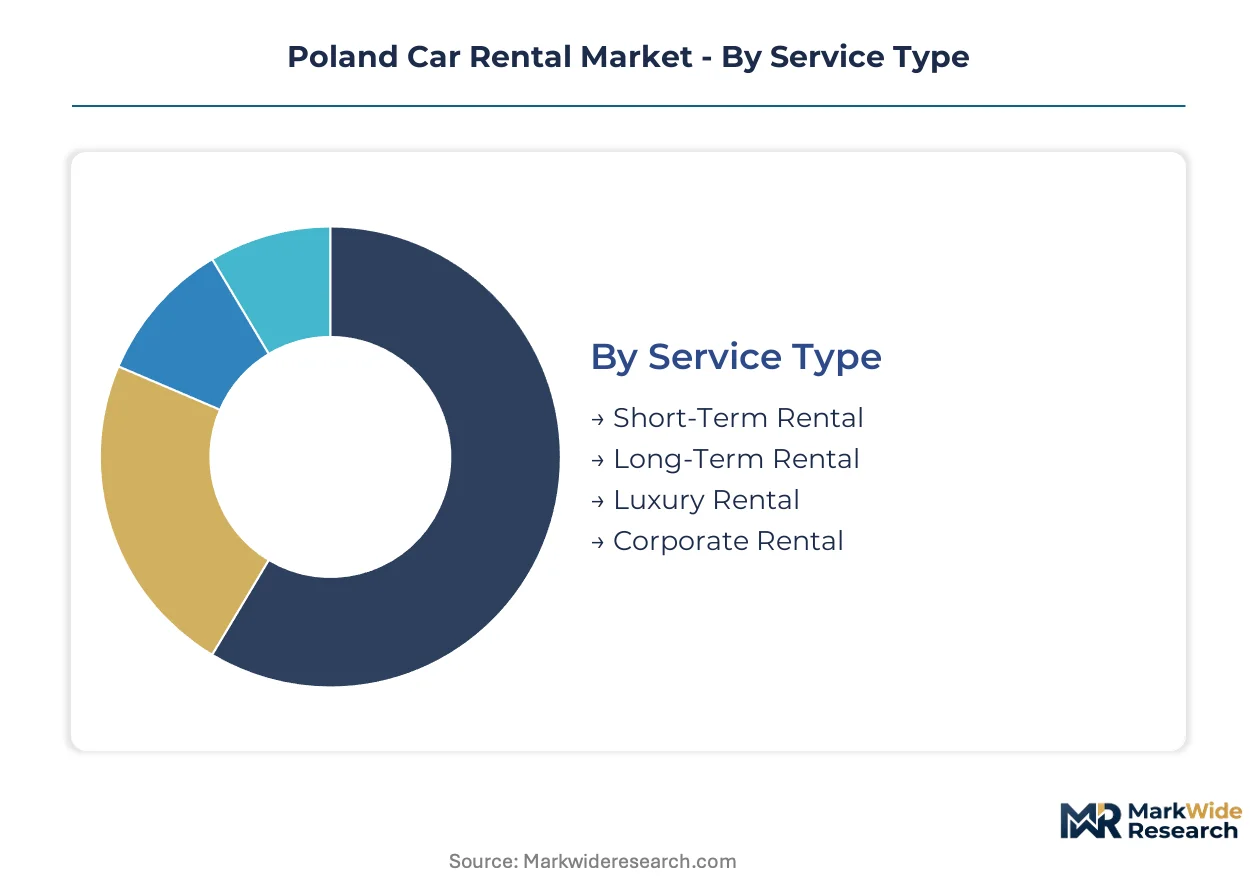
Segmentation patterns in the Poland Car Rental Market reveal distinct operational economics across service durations and customer profiles. Warsaw and Kraków operators calibrate fleet composition and pricing architectures to match utilization density and margin requirements within each category.
Service Type:
Short-term rental captures the highest transaction velocity while corporate rental delivers superior margin pools through contracted utilization guarantees.
- Short-Term Rental:Daily or weekly vehicle access structured around mileage allowances and fuel-return policies. Demand concentrates among tourists at Kraków's historic district and business travelers at Warsaw Chopin Airport, driven by seasonal leisure peaks and conference calendars.
- Long-Term Rental:Monthly to multi-year vehicle access without ownership transfer, bundling maintenance and insurance into fixed periodic fees. Polish SME professional services in the Tri-City corridor are adopting these arrangements to eliminate residual value risk from their balance sheets.
- Luxury Rental:Premium vehicle categories with concierge delivery and enhanced insurance coverage. Warsaw's corporate hospitality sector generates concentrated demand for executive transport during investor roadshows.
- Corporate Rental:Negotiated annual contracts with guaranteed utilization floors and centralized billing. Manufacturing and logistics firms across Silesian industrial zones are outsourcing fleet ownership to rental operators under these structures.
Mature deployment sits with short-term rental. Newer deployment is concentrated in corporate rental.
Vehicle Type:
Fleet composition tracks seasonal demand fluctuations and residual value optimization cycles across Polish urban markets.
- SUV:All-wheel-drive configurations with elevated ground clearance and expanded cargo capacity. Winter leisure travel to Zakopane and mountain resorts drives peak demand, with Warsaw operators maintaining higher SUV allocation ratios from November through March.
- Sedan:Three-box passenger configurations optimized for highway fuel efficiency and professional presentation. Business traveler segments at Kraków technology parks sustain steady year-round utilization for client meetings and airport transfers.
- Hatchback:Compact two-box designs maximizing urban maneuverability and parking efficiency. Local residents in Gdańsk's dense historic core favor these vehicles for short-duration neighborhood errands.
- Van:Commercial-grade cargo and passenger configurations with expanded payload capacity. Event logistics coordinators across Poland's trade fair circuit generate episodic demand for equipment and staff transport.
Volume leadership belongs to sedan configurations. Margin expansion is climbing fastest in SUV categories.
Customer Type:
Customer acquisition economics vary sharply between transient visitors and recurring local accounts with established credit relationships.
- Business Travelers:Corporate-account mobility with expense-report integration and loyalty program enrollment. Warsaw's financial services district generates the densest concentration of weekday rental initiations.
- Tourists:International and domestic leisure visitors seeking flexible exploration access. Kraków's UNESCO heritage status sustains inbound rental demand across extended summer travel windows.
- Local Residents:Polish households supplementing owned-vehicle access for specific occasions or during repair intervals. Tri-City metropolitan households utilize short-term rental for weekend coastal excursions.
- Event Attendees:Conference, wedding, and sporting event participants requiring temporary transport coordination. Poznań's international fair grounds generate periodic demand spikes synchronized with exhibition calendars.
Established revenue concentration sits with business travelers. Customer acquisition investment is expanding most aggressively toward local residents.
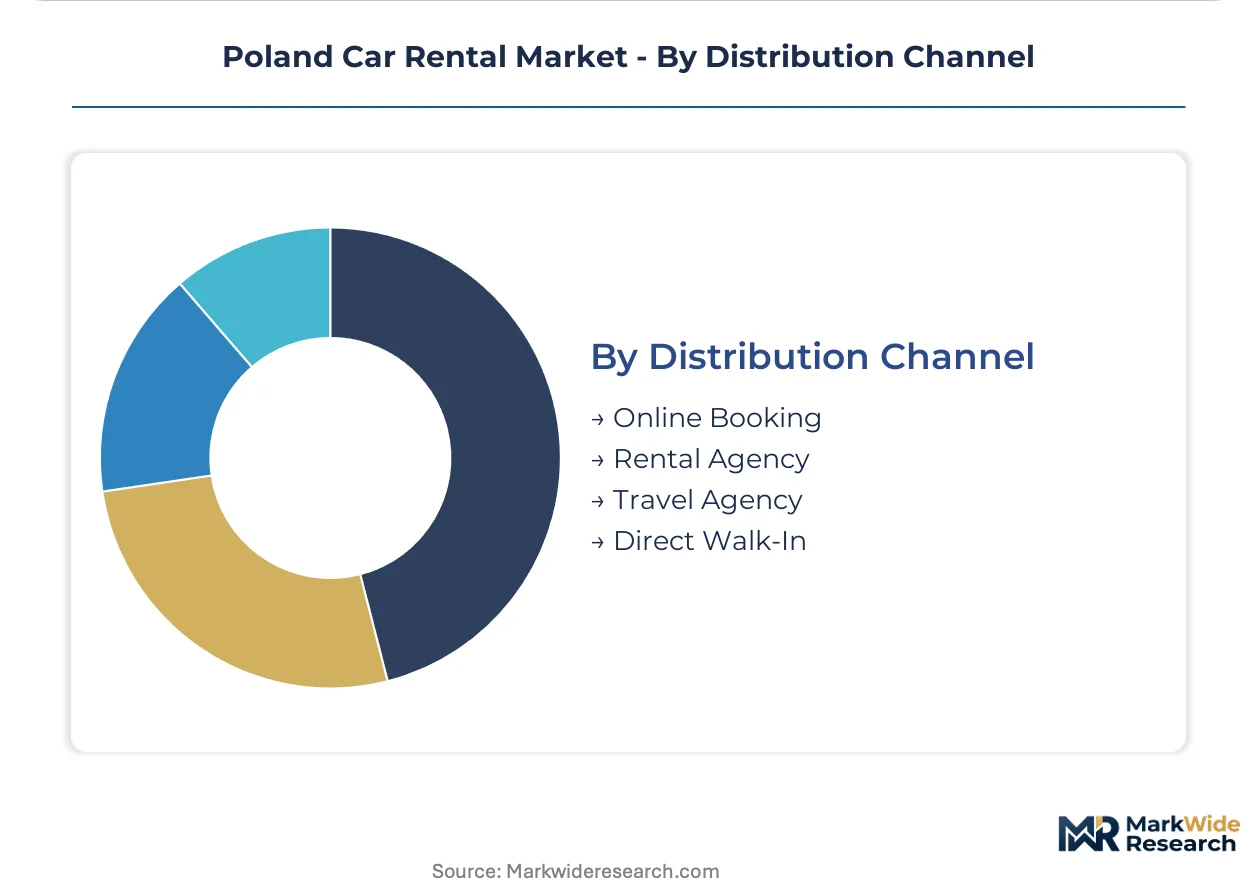
Distribution Channel:
Booking infrastructure investments are reallocating capital from physical branch networks toward digital platform development and API connectivity.
- Online Booking:Direct-to-consumer reservation platforms with real-time fleet availability and dynamic pricing engines. Warsaw-based Panek SA and international operators are deploying mobile-first interfaces to compress customer acquisition costs.
- Rental Agency:Company-operated physical locations with staffed counters and vehicle handover protocols. Major Polish cities maintain these facilities at airport terminals and central rail stations for walk-up demand capture.
- Travel Agency:Intermediary-arranged bookings bundled with accommodation and itinerary services. Kraków's tourism infrastructure includes these channels for inbound European tour operators.
- Direct Walk-In:Unplanned rental initiation at physical locations without advance reservation. Secondary city branches in Łódź and Wrocław process these transactions with higher per-unit staffing overhead.
Legacy infrastructure investment sits with rental agency locations. Platform development capital is concentrating in online booking.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Poland's car rental demand clusters around Warsaw, Kraków, and the Tri-City metropolitan corridor, with secondary cities generating episodic utilization spikes tied to industrial and tourism calendars.
Warsaw Metropolitan Area
Corporate fleet outsourcing and financial services mobility anchor Warsaw's rental volume, with the Ministry of Infrastructure enforcing periodic technical inspection standards that compress vehicle turnover cycles. Chopin Airport and central rail stations concentrate branch infrastructure for business traveler capture.
Kraków and Lesser Poland
UNESCO heritage tourism and technology park business travel sustain dual demand peaks, with EU Green Deal emissions standards accelerating electric fleet procurement among local operators. The historic district and Balice Airport generate concentrated short-term rental initiations across extended summer windows.
Tri-City Corridor
Gdańsk-Gdynia-Sopot metropolitan density produces localized utilization premiums that justify dedicated depot infrastructure, with manufacturing and logistics firms outsourcing fleet ownership under annual contracts. Coastal leisure travel drives seasonal SUV allocation spikes from June through August.
Silesian Industrial Zone
Manufacturing and heavy industry clusters in Katowice and surrounding municipalities generate corporate rental demand with guaranteed utilization floors, with EU Just Transition Fund subsidies opening pathways for charging depot construction. Industrial outsourcing trends concentrate fleet management contracts among regional operators.
Łódź and Central Poland
Logistics hub positioning and textile industry heritage create mixed business-leisure demand profiles, with secondary city branch networks capturing direct walk-in transactions at higher per-unit staffing overhead. Intermodal connectivity with Warsaw generates corridor rental flows for extended-stay business assignments.
Poland Car Rental Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with international platforms and domestic operators dividing the Polish market through distinct capability positioning. Market structure exhibits tiered concentration where global brands anchor airport and premium segments while local specialists capture corporate outsourcing volume through relationship density. Three archetypes dominate: international network platforms with centralized fleet management, domestic integrated mobility providers with branch saturation, and premium-positioned specialists with digital-first infrastructure. Competitive moves concentrate on fleet electrification acceleration and intermodal hub placement.
Among international network operators, Europcar International and Sixt occupy positions exemplifying platform-scale efficiency and premium digital infrastructure respectively. Panek SA anchors the domestic specialist tier as a Warsaw-based S.A. representing integrated mobility services with extensive local branch coverage. These three players illustrate the competitive segmentation between global reach, premium positioning, and domestic density that structures Polish rental market rivalry.
| Leading Market Players |
|---|
| Budget Rent a Car System Inc. |
| TOPCARS |
| Europcar International |
| Sixt |
| Panek SA |
| Enterprise Holding Inc. |
| The Hertz Corporation |
| Carwiz |
| Avis Budget Inc. |
| Others |
Value Network & Pricing Analysis
Corporate fleet outsourcing contracts with guaranteed utilization floors are forcing Polish rental operators to restructure procurement toward longer asset holding periods and bundled maintenance pricing. This demand compression feeds back into supply chain negotiations with OEMs and service providers.
Pricing Analysis
Volume leadership sits with short-term daily rentals while margin expansion concentrates in corporate subscription contracts. Three-tier pricing structure across premium, standard, and economy levels differentiates fleet segments, with SUV winter premiums and electric vehicle residual uncertainty as key price drivers. Cost compression in the economy tier is intensifying because of telematics-enabled fleet optimization lowering per-unit operational overhead. Local residents in secondary cities exhibit highest price sensitivity; Warsaw corporate accounts demonstrate lowest sensitivity due to centralized procurement and expense integration.
Supply Chain Analysis
Vehicle procurement rests on German OEM supply networks for combustion platforms and South Korean battery cell producers for electric fleet transitions. Key inputs include lithium-ion battery packs, semiconductor components for telematics systems, and high-voltage charging hardware. Single-source vulnerability runs through South Korean cathode material suppliers exposed to export licensing shifts. Distribution runs through manufacturer-direct fleet sales agreements and specialized remarketing channels for residual value realization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
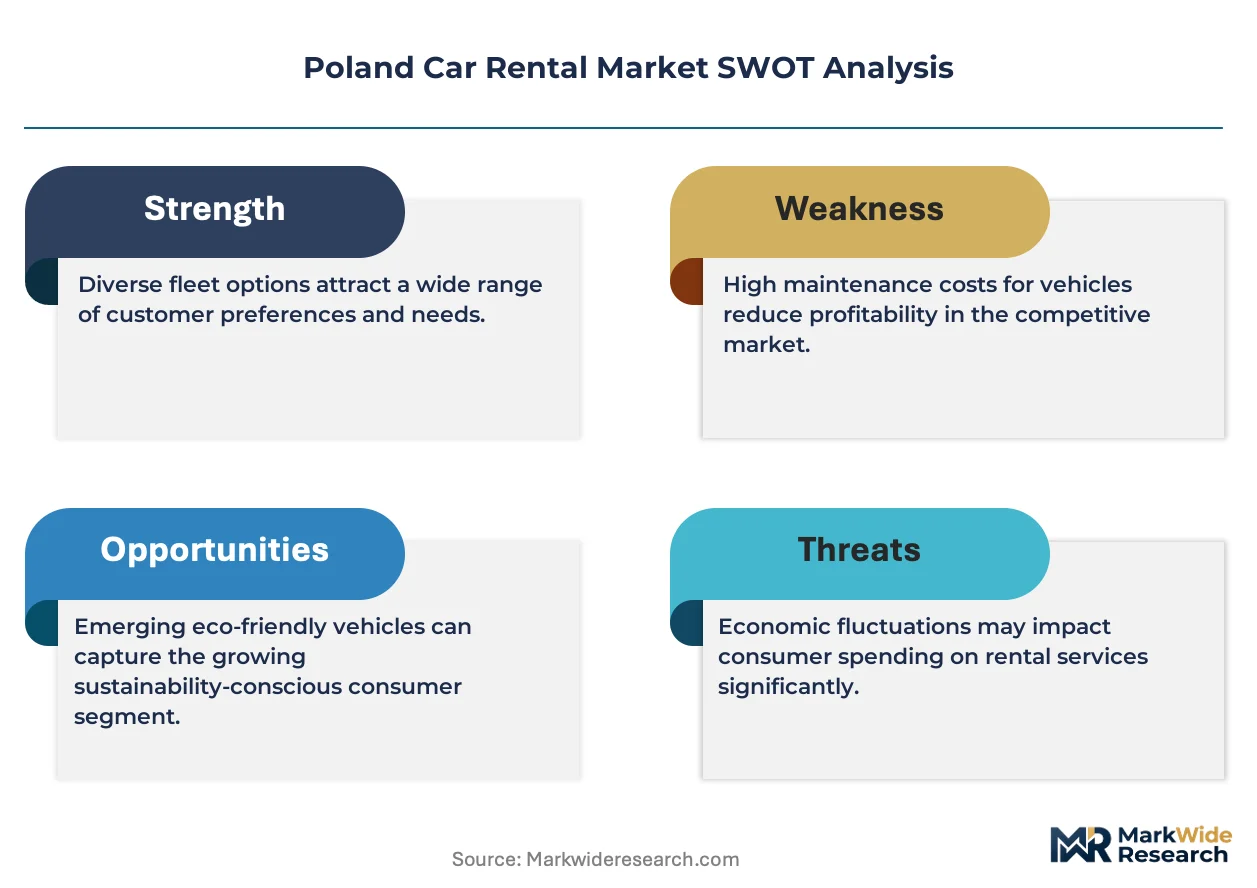
Poland's car rental market operates as a cost-of-compliance story where EU Green Deal emissions mandates create regulatory moats favoring operators with capital depth for electric fleet transitions and certified technician training programs.
For Market Incumbents: Anticipate battery residual value opacity and charging infrastructure gaps as structural margin threats. Consolidate defensive positioning through backward integration into in-house high-voltage service capabilities and captive charging depot construction in Silesian industrial zones. Prioritize certification investment under Poland's General Inspectorate of Road Transport technical inspection tightening to compress competitor fleet renewal cycles.
For New Entrants and Emerging Players: The mid-tier price-point gap between premium-positioned international platforms and economy-focused domestic operators offers white-space entry. Target corporate subscription models among Kraków technology SMEs with flexible monthly contracts displacing annual leases. Pursue intermodal mobility integration at Warsaw Centralna and Kraków Główny rail hubs as differentiated go-to-market positioning.
For Investors and Strategic Acquirers: The window for entry favors domestic operators with dense branch networks and integrated mobility service capabilities over asset-light platform plays. Acquisition target archetype: regional specialists with established corporate outsourcing relationships in Tri-City or Silesian manufacturing corridors. Monitor EU Just Transition Fund subsidy disbursement velocity as inflection indicator for charging infrastructure deployment economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Electric Fleet Transition Acceleration | EU Green Deal compliance timelines force capital deployment toward battery-electric vehicle procurement ahead of residual value certainty. |
| Charging Depot Construction Partnership | EU Just Transition Fund subsidies in Silesian industrial zones reduce infrastructure capex burden for fleet electrification. |
| Intermodal Hub Placement | Rail-station adjacent rental locations at Warsaw Centralna enable last-mile connectivity bundles with public transit operators. |
| Corporate Subscription Model Launch | Flexible monthly vehicle access contracts displace traditional annual leasing among Polish SME professional services segments. |
| Telematics Platform Integration | Predictive maintenance systems reduce unplanned downtime by automating workshop scheduling and parts procurement workflows. |
Research Methodology
Vehicle registration databases, EU emissions compliance filings, and corporate fleet outsourcing contract disclosures formed the secondary backbone of this study. Primary fieldwork encompassed interviews with fleet operations directors at Warsaw and Kraków rental branches, procurement managers at Polish manufacturing firms, charging infrastructure developers, and vocational training program administrators. Bottom-up fleet size and utilization estimates triangulated against top-down market value projections derived from regulatory filing analysis.
Historical trendline analysis across vehicle type transitions and service model evolution informed projection architecture. Segmentation modeling encompassed service duration tiers, vehicle propulsion architectures, customer account types, and regional demand density clusters. CAGRs were derived through regression analysis of fleet procurement patterns and contracted revenue pool expansion. Industry-specific forecast inputs included EU battery passport compliance timelines and Poland's General Inspectorate of Road Transport inspection protocol tightening schedules.
Inputs from corporate sustainability disclosures and EU funding program announcements were available through the study window; gaps in real-time battery health certification framework development introduce uncertainty bands around electric fleet residual value assumptions. Forecasts reflect documented assumptions regarding charging infrastructure buildout velocity and technician training pipeline expansion. EU Green Deal mandate enforcement intensity and battery passport implementation timing constitute the trigger set warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Bike Rental Market
Transportation Services
Water Truck Rental Market
Transportation Services
ASEAN Taxi Market
Transportation Services
Middle East Car Rental Market
Transportation Services
Online Bus Ticketing Service Market
Transportation Services
Europe Vehicle Rental Market
Transportation Services
Car Rental Market
Transportation Services
Global Moto Taxi Service Market
Transportation Services
Malaysia Car Rental Market
Transportation Services
Philippines Car Rental Market
Transportation Services
Vacuum Truck Rentals Market
Transportation Services
North America Vehicle Rental Market
Transportation Services
United States White Glove Delivery Service Market
Transportation Services
MUV Rental Market
Transportation Services
Car Rental Service Market
Transportation Services
Australia Taxi Market