
 Multiparameter Patient Monitoring System Market | 2026-2036
Multiparameter Patient Monitoring System Market Size, Share, and Industry Trends Forecast 2026-2036
Multiparameter Patient Monitoring System Market Analytics
The EU Medical Device Regulation (MDR) is broadening compliance obligations for patient monitoring equipment sold across European member states. GE Healthcare leverages its installed base of anesthesia workstations to cross-sell multiparameter modules into surgical suites. Shenzhen Mindray Bio-Medical Electronics Co., Ltd. anchors its competitive position through manufacturing scale in Southern China and aggressive pricing for emerging market tenders. Koninklijke Philips N.V. differentiates via proprietary predictive algorithms embedded in its IntelliVue platform.
A multiparameter patient monitoring system is an integrated electronic device that simultaneously acquires, processes, and displays multiple physiological signals—typically electrocardiography, pulse oximetry, non-invasive blood pressure, respiratory rate, and temperature—through digital sensors and signal-conditioning circuitry, enabling continuous surveillance of patient status in acute and sub-acute care settings. Portable monitors command premium pricing in emergency services and inter-hospital transfer applications where mobility determines clinical utility. Wireless communication and cloud integration represent the fastest-expanding technology layers, as health systems seek to reduce alarm fatigue while extending monitoring continuity from critical care wards into step-down units and homecare environments.
The FDA enforces 510(k) clearance pathways with escalating scrutiny of cybersecurity controls and software-as-a-medical-device functionality, while the EU MDR mandates notified body involvement for even incremental hardware revisions. Health Canada and the Therapeutic Goods Administration (TGA) in Australia have aligned post-market surveillance requirements with FDA Sentinel and European vigilance databases, creating transnational compliance reciprocity that favors vendors with established quality management systems. Stakeholders must weigh capital expenditure against subscription-based remote monitoring models as reimbursement frameworks evolve toward episode-of-care and value-based contracting structures.
Market Dynamics
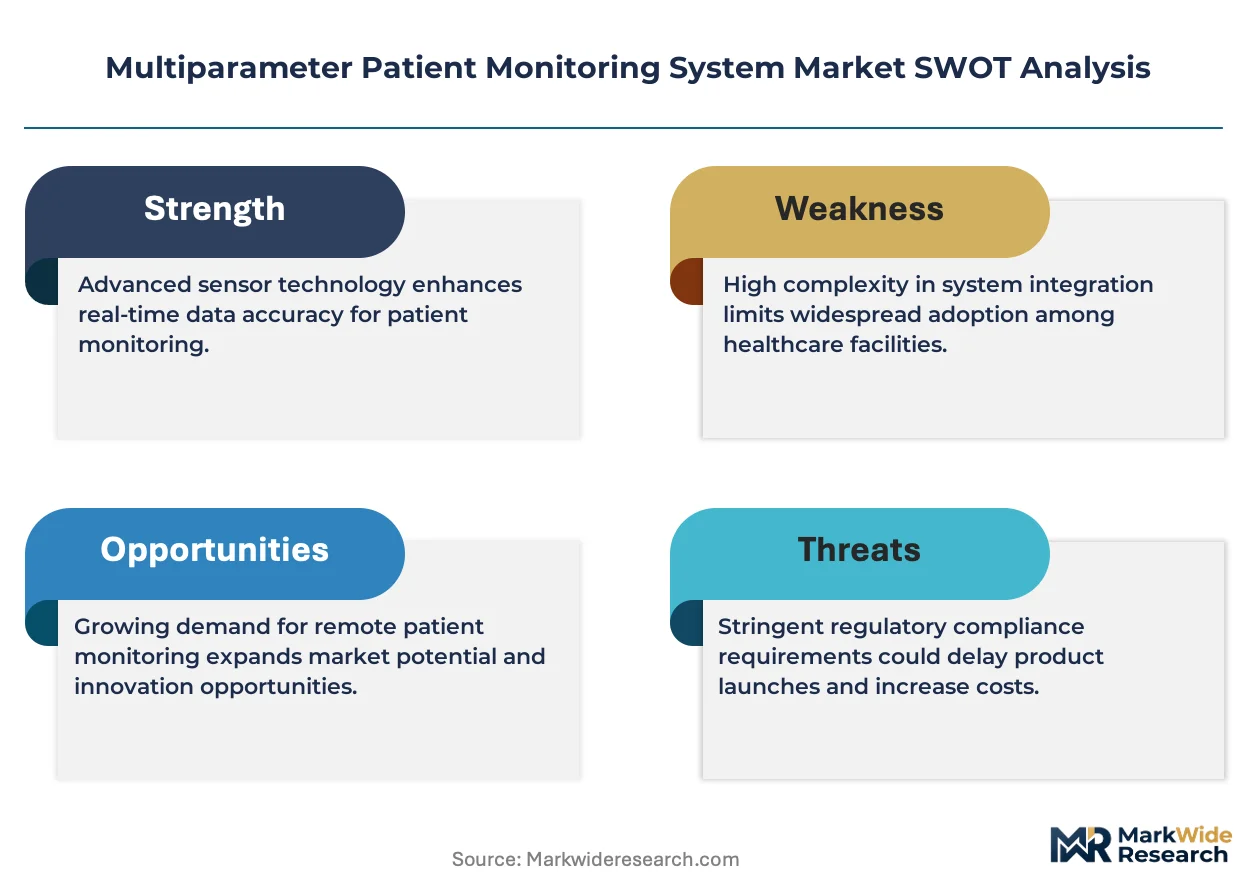
Wireless telemetry infrastructure is displacing hardwired bedside configurations across acute care wards, forcing manufacturers to reengineer hardware-software stacks for continuous cloud connectivity rather than episodic data capture.
Growth Catalysts
- EU MDR compliance mandates:Stricter notified body oversight for patient monitoring devices accelerates replacement cycles in German and French university hospitals seeking certified platforms.
- Alarm fatigue reduction protocols:Clinical engineering departments in US health systems prioritize predictive alerting algorithms that filter non-actionable notifications.
- Inter-hospital transfer mobility requirements:Emergency medical services in India and Brazil specify lightweight portable monitors for ambulance-based critical care.
Market Restraints
- Semiconductor supply concentration:Analog front-end chips and medical-grade sensors rely heavily on Taiwanese and South Korean foundry capacity, exposing lead time volatility.
- FDA 510(k) cybersecurity validation:Escalating software documentation requirements extend clearance timelines for wireless-enabled submissions.
- Disposable electrode cost structures:Single-use SpO2 probes and ECG leads create recurring material expenses that constrain total cost of ownership in price-sensitive tenders.
Strategic Opportunities
- Home-based step-down monitoring:Post-acute care providers in the United States pilot subscription models extending ICU-grade surveillance into residential settings.
- AI-embedded predictive analytics:Machine learning models trained on multi-parameter trends enable early deterioration detection in general wards.
- Rural hospital retrofit programs:India's Ayushman Bharat infrastructure investments fund telemetry upgrades in district-level facilities lacking critical care capacity.
Industry Challenges
- Biomedical engineering talent scarcity:Health systems struggle to hire specialists capable of integrating cloud-native platforms with legacy HL7 interfaces.
- Interoperability certification complexity:IEEE 11073 and FHIR compliance testing demands extended validation cycles before enterprise deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multiparameter Patient Monitoring System Market |
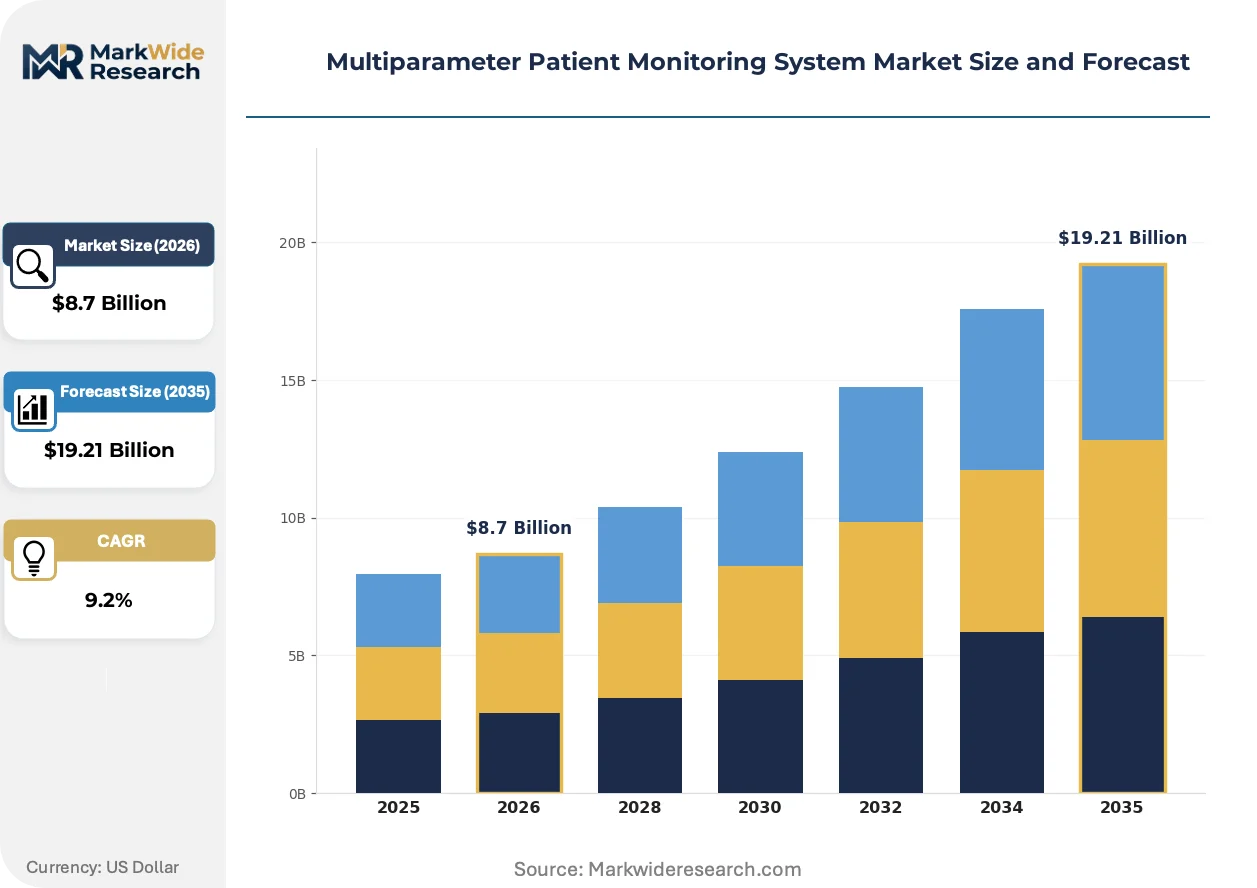
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.21 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bedside Monitors, Portable Monitors, Wearable Monitors, Remote Monitoring Systems End User: Hospitals, Homecare, Diagnostic Centers, Emergency Services Technology: Digital Sensors, Wireless Communication, Cloud Integration, Telemetry Systems Application: Cardiac Monitoring, Respiratory Monitoring, Multi-parameter Monitoring, Critical Care |
| Companies Covered | GE Healthcare, Koninklijke Philips N.V., Medtronic, Shenzhen Mindray Bio-Medical Electronics Co., Ltd., Drägerwerk AG & Co. KGaA, Nihon Kohden Corporation, Masimo Corporation, Schiller AG, Spacelabs Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multiparameter Patient Monitoring System Market Evolving Landscape
Patient monitoring architecture is pivoting from device-centric hardware sales toward continuous data service layers, embedding analytics engines directly at the edge of clinical workflows.
Edge computing is converging with low-power wide-area networking to enable real-time physiological signal processing without continuous hospital Wi-Fi dependency. Surgical suites and step-down units in Nordic health systems deploy these hybrid architectures to maintain monitoring continuity during patient transport. This convergence is compressing the traditional boundary between critical care devices and consumer-grade wearables.
EU MDR Article 10 post-market surveillance obligations now mandate systematic vigilance reporting for software updates to Class IIa monitoring devices. Manufacturers must maintain technical documentation for incremental algorithm revisions that previously escaped notified body scrutiny. German and Dutch hospital procurement offices now weight MDR compliance certificates above legacy CE-mark acceptance in tender evaluations.
Health system purchasing departments unbundle hardware acquisition from remote monitoring subscriptions, separating capital equipment from recurring clinical decision support fees. Integrated delivery networks in the United States negotiate per-patient-per-day pricing for cloud analytics rather than per-device licensing. This restructuring is most visible in California and Texas health systems consolidating vendor relationships under single-source monitoring contracts.
Multiparameter Patient Monitoring System Market Segmentation
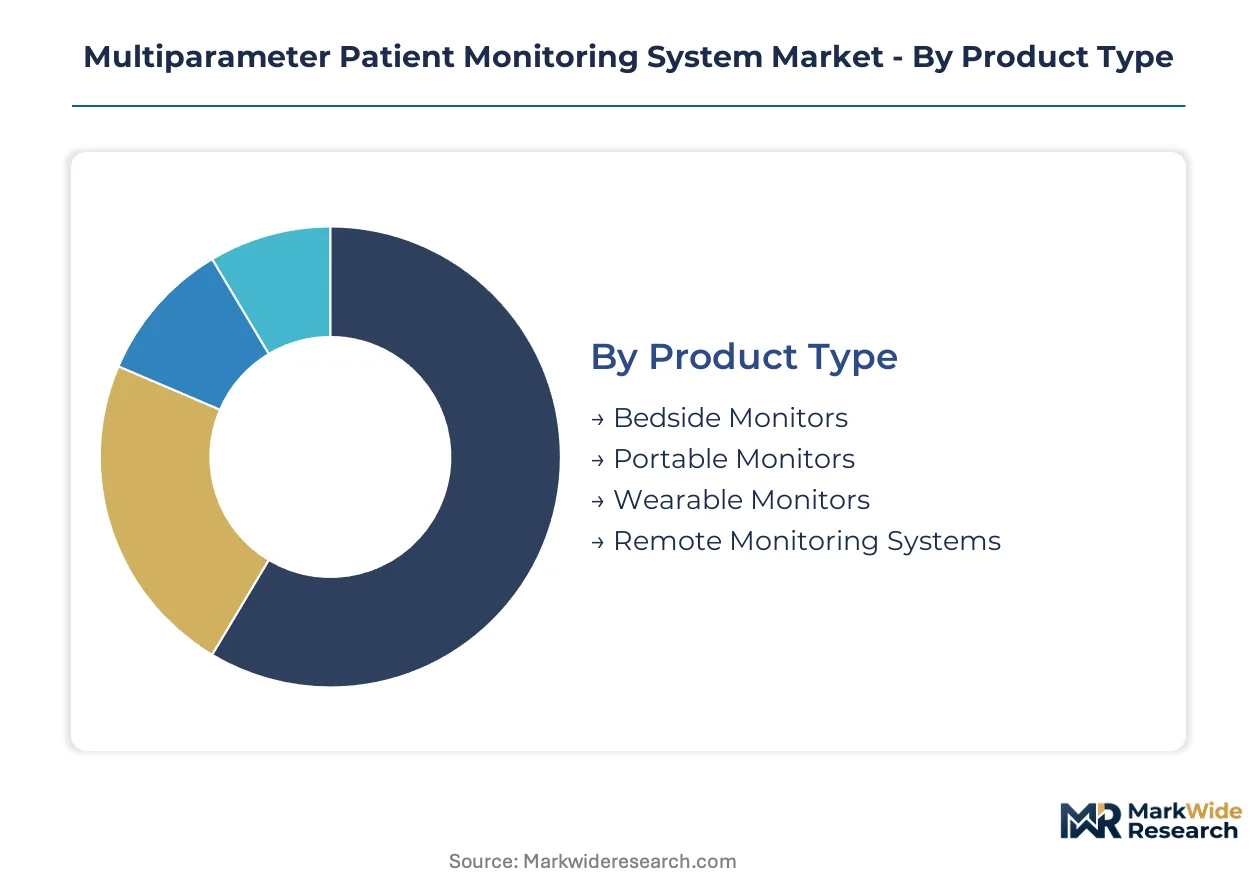
Segmentation in the Multiparameter Patient Monitoring System Market reveals divergent hardware-software configurations optimized for care setting mobility requirements. Procurement patterns differ sharply between capital-intensive hospital infrastructure and subscription-based remote surveillance models.
Product Type:
Customization intensity varies from fully configurable modular platforms to sealed disposable units, with pricing power concentrated at the high-mobility end of the spectrum.
- Bedside Monitors:Stationary units integrate electrocardiography, pulse oximetry, non-invasive blood pressure, and respiratory rate through centralized nursing station displays. German university hospitals prioritize these for ICU retrofit programs driven by EU MDR compliance deadlines.
- Portable Monitors:Battery-powered devices weighing under 2.5 kilograms enable continuous surveillance during inter-hospital transfers. Emergency medical services in India specify lightweight configurations for ambulance-based critical care under Ayushman Bharat infrastructure investments.
- Wearable Monitors:Patch-based sensors transmit physiological data through low-power wide-area networks. Homecare providers in the United States pilot subscription models extending ICU-grade surveillance into residential settings.
- Remote Monitoring Systems:Cloud-native architectures aggregate multi-parameter streams from dispersed patient locations. Health systems in Texas negotiate per-patient-per-day pricing for analytics rather than per-device licensing.
Most installed capacity flows through Bedside Monitors. Expansion is steepest in Remote Monitoring Systems.
End User:
Customer archetypes span from capital-constrained public health systems to premium-paying integrated delivery networks with value-based contracting maturity.
- Hospitals:Acute care facilities deploy centralized telemetry infrastructure across critical care wards and step-down units. Hospital ICUs in the United States are expanding deployments of wireless-enabled monitoring platforms to reduce alarm fatigue.
- Homecare:Post-acute providers manage chronic conditions through cloud-connected wearable sensors. California health systems consolidate vendor relationships under single-source monitoring contracts spanning hospital-to-home continuity.
- Diagnostic Centers:Outpatient facilities require compact multi-parameter units for pre-operative assessment and stress testing. Brazilian emergency services specify portable monitors for pre-hospital triage.
- Emergency Services:Ambulance operators demand ruggedized devices with extended battery autonomy. Inter-hospital transfer mobility requirements concentrate procurement specifications in India and Brazil.
Revenue concentration sits with Hospitals. Homecare demonstrates the steepest expansion trajectory as reimbursement frameworks evolve toward episode-of-care structures.
Technology:
Technology layering determines cybersecurity validation burden and FDA 510(k) clearance complexity, with wireless stacks facing escalating scrutiny.
- Digital Sensors:Analog front-end chips convert physiological signals into conditioned digital outputs. Semiconductor supply concentration in Taiwanese and South Korean foundries exposes lead time volatility for medical-grade sensor procurement.
- Wireless Communication:Bluetooth Low Energy and proprietary radio protocols enable bedside-to-cloud data transmission. FDA premarket notification requirements for Class II medical devices are tightening software validation protocols for wireless-enabled submissions.
- Cloud Integration:HIPAA-compliant data lakes aggregate longitudinal patient records across care transitions. Health Canada and Australia's TGA have aligned post-market surveillance requirements with FDA Sentinel databases.
- Telemetry Systems:Hardwired and hybrid architectures maintain monitoring continuity during patient transport. Nordic health systems deploy these configurations to bridge critical care wards and surgical suites.
Digital Sensors anchor installed base economics. Cloud Integration is gaining share fastest as health systems unbundle hardware from analytics subscriptions.
Application:
Application specialization ranges from single-parameter depth to integrated multi-signal platforms, with clinical utility determining price realization.
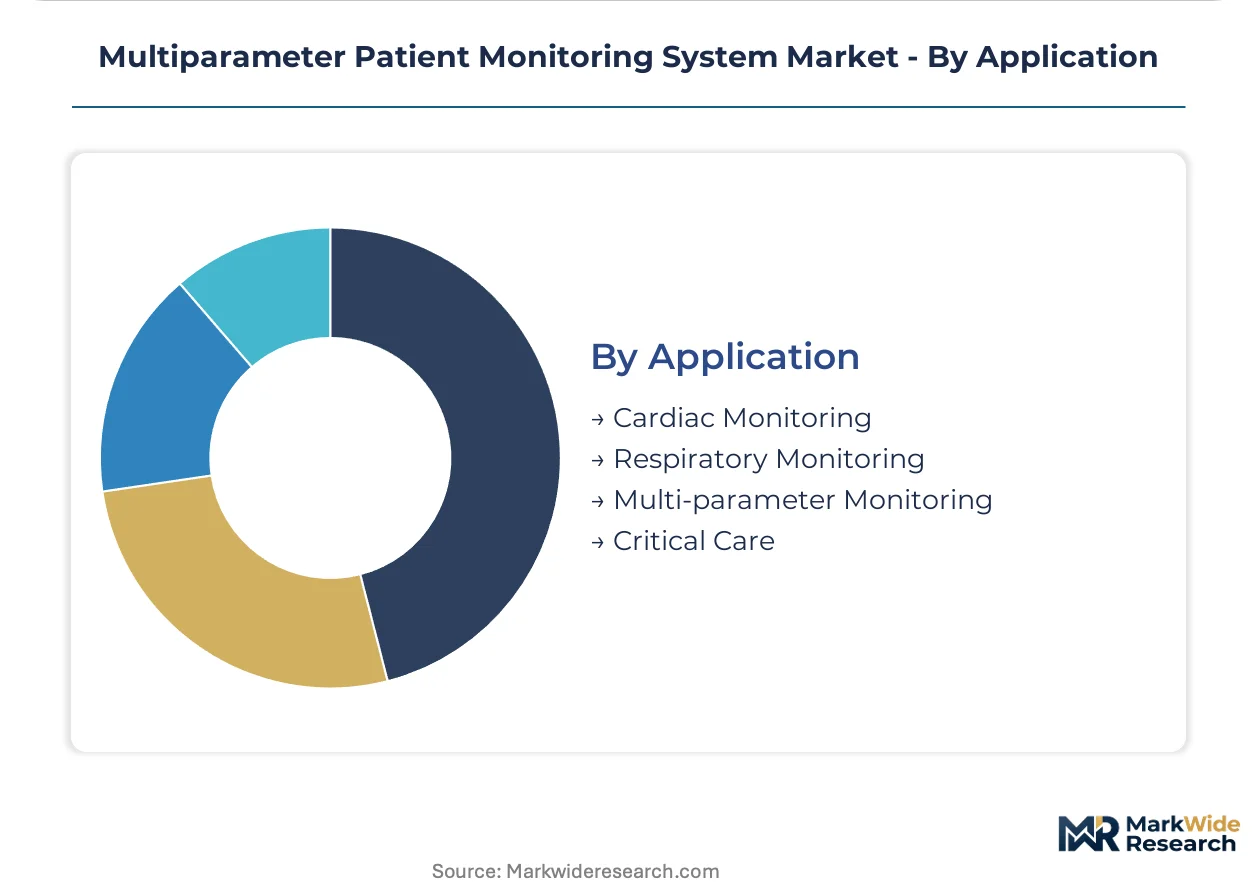
- Cardiac Monitoring:Twelve-lead ECG acquisition with arrhythmia detection algorithms dominates critical care deployment. Predictive alerting algorithms filter non-actionable notifications in US health systems prioritizing alarm fatigue reduction.
- Respiratory Monitoring:Capnography and impedance pneumography track ventilation status in surgical suites. GE Healthcare leverages anesthesia workstation installed bases to cross-sell multi-parameter modules into these environments.
- Multi-parameter Monitoring:Integrated platforms simultaneously display ECG, SpO2, NIBP, and temperature through unified interfaces. Koninklijke Philips N.V. differentiates via proprietary predictive algorithms embedded in IntelliVue configurations.
- Critical Care:High-acuity settings demand FDA-cleared platforms with Class IIa MDR certificates. German and Dutch hospital procurement offices now weight MDR compliance certificates above legacy CE-mark acceptance in tender evaluations.
Multi-parameter Monitoring commands the largest installed footprint. Critical Care applications are climbing the fastest as general wards adopt ICU-grade surveillance protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The multiparameter patient monitoring system industry traces its commercial origins to post-war American hospital electrification, with subsequent scaling across German precision engineering clusters and Japanese semiconductor integration. Distribution now spans three continents with distinct regulatory maturity levels.
United States
FDA 510(k) cybersecurity validation timelines extend clearance cycles for wireless-enabled submissions. Hospital ICUs expand deployments of wireless-enabled monitoring platforms to reduce alarm fatigue. California health systems consolidate vendor relationships under single-source monitoring contracts spanning hospital-to-home continuity.
Germany
University hospitals retrofit aging telemetry infrastructure with cloud-integrated systems driven by EU MDR compliance deadlines. The EU Medical Device Regulation mandates notified body involvement for incremental hardware revisions. Bavarian medical technology clusters anchor production of anesthesia-integrated monitoring modules for surgical suites.
India
Ayushman Bharat infrastructure investments fund telemetry upgrades in district-level facilities lacking critical care capacity. CDSCO medical device registration requirements tighten quality management system documentation for imported monitoring equipment. Emergency medical services in Maharashtra specify lightweight portable monitors for ambulance-based critical care.
China
NMPA Class II medical device approval pathways accelerate for domestic manufacturers with established quality management systems. Southern China manufacturing clusters anchor cost-competitive production of multi-parameter modules for emerging market tenders. Shenzhen-based producers leverage scale economies to capture price-sensitive procurement specifications across Southeast Asia.
Brazil
ANVISA medical device registration harmonizes with FDA Sentinel surveillance databases for post-market vigilance alignment. Emergency services specify ruggedized portable monitors with extended battery autonomy for pre-hospital triage. São Paulo metropolitan health systems pilot subscription-based remote monitoring models for post-acute care transitions.
Multiparameter Patient Monitoring System Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent technology stacks. The market structure consolidates around integrated medical technology conglomerates with anesthesia workstation installed bases, while specialized monitoring pure-plays occupy premium algorithmic niches. Three archetypes dominate: diversified healthcare conglomerates leveraging cross-selling synergies, focused monitoring specialists embedding predictive analytics, and scale-driven Asian manufacturers capturing emerging market tenders. Dominant competitive moves include portfolio diversification into cloud-native service layers and strategic partnerships with health systems for episode-of-care contracting.
Among diversified healthcare conglomerates, GE Healthcare and Koninklijke Philips N.V. exemplify archetypes leveraging installed base penetration into surgical suites and critical care wards. Shenzhen Mindray Bio-Medical Electronics Co., Ltd. anchors the scale-driven manufacturing tier, representing Southern China production concentration for price-competitive tender participation across emerging markets.
| Leading Market Players |
|---|
| GE Healthcare |
| Koninklijke Philips N.V. |
| Medtronic |
| Shenzhen Mindray Bio-Medical Electronics Co., Ltd. |
| Drägerwerk AG & Co. KGaA |
| Nihon Kohden Corporation |
| Masimo Corporation |
| Schiller AG |
| Spacelabs Healthcare |
| Others |
Value Network & Pricing Analysis
Cloud-native telemetry architectures are compressing hardware margins while concentrating procurement power among integrated delivery networks with episode-of-care contracting maturity. This technological pivot simultaneously elevates recurring software revenue streams and exposes manufacturers to semiconductor supply volatility concentrated in East Asian foundries.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by FDA clearance tier and algorithmic sophistication. Premium configurations with Class IIa MDR certificates and predictive analytics command substantial markups from German university hospitals, while price-sensitive tenders in India and Brazil gravitate toward economy-tier units with basic parameter sets. Cost compression in the standard tier is intensifying because Shenzhen-based manufacturers leverage Southern China production scale to undercut mid-market incumbents. Emergency medical services in emerging markets exhibit the highest price sensitivity, whereas US integrated delivery networks prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
ISO 13485 and FDA QSR certification requirements gate access to hospital procurement channels, filtering component suppliers to a qualified tier with established quality management systems. Analog front-end chip fabrication concentrates in Taiwan and South Korea, while medical-grade sensor assembly clusters in Southern China and Malaysia. The supply chain draws from specialized inputs including MEMS pressure sensors, pulse oximetry LEDs, and biocompatible electrode substrates. Single-source vulnerability in Taiwanese foundry capacity for analog signal-conditioning ICs represents the dominant structural risk. Distribution runs through regional medical device distributors with GPO contracting relationships and direct hospital sales forces for enterprise accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU MDR compliance costs in Germany and France create pricing umbrellas that Chinese manufacturers exploit through cost-optimized production for price-sensitive emerging markets.
For Market Incumbents: Deploy algorithmic differentiation to protect margin structure against Shenzhen-based price competition. GE Healthcare and Koninklijke Philips N.V. should deepen predictive analytics R&D while consolidating anesthesia workstation cross-selling relationships. Certification investment in EU MDR Class IIa pathways maintains tender eligibility in German and Dutch procurement offices. Channel control through exclusive GPO contracts with US integrated delivery networks limits displacement risk from emerging Asian entrants. For New Entrants and Emerging Players: Launch via subscription-based remote monitoring models targeting US homecare step-down transitions. The most penetrable white space sits in rural Indian district hospitals funded by Ayushman Bharat infrastructure investments, where lightweight portable monitors with basic parameter sets satisfy unmet critical care capacity gaps. A direct-to-hospital sales approach bypassing established distributor networks enables price undercutting in Brazilian emergency services procurement. For Investors and Strategic Acquirers: Valuations sit cheapest among monitoring pure-plays with FDA-cleared platforms but limited cloud analytics penetration. Long-term viability over the projection horizon favors targets with established quality management systems capable of EU MDR transition. The signal to monitor is reimbursement framework evolution toward per-patient-per-day pricing models in US health systems, which would accelerate hardware-software unbundling and elevate recurring revenue multiples.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Cybersecurity Submission | Accelerates clearance timelines for wireless-enabled platforms competing in US hospital ICUs. |
| EU MDR Class IIa Certification Pathway | Maintains tender eligibility in German and Dutch university hospital procurement evaluations. |
| Hospital System Partnership | California and Texas integrated delivery networks consolidate vendor relationships under single-source contracts. |
| Software Companion Development | Predictive algorithms embedded at the edge reduce alarm fatigue in US critical care wards. |
| Reimbursement Strategy | Per-patient-per-day pricing models align with episode-of-care contracting in US post-acute transitions. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down manufacturing capacity tracking forms the analytical core of this study. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists at notified bodies were combined with secondary validation from FDA 510(k) databases, EU MDR certificates of conformity, hospital procurement databases, and CMS Medicare reimbursement filings. Top-down triangulation against Southern China production capacity estimates and Taiwanese foundry output data ensures supply-side consistency.
Historical trendline analysis of installed base replacement cycles and telemetry infrastructure upgrade patterns informed the projection framework. The model segments across product mobility tier, end-user facility type, wireless technology stack, and critical care application depth. CAGRs were derived from regression analysis of capital expenditure patterns and subscription service adoption curves. Industry-specific forecast inputs include EU MDR compliance deadline clustering and Ayushman Bharat infrastructure investment disbursement trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under semiconductor supply disruption scenarios or FDA cybersecurity guidance revisions. The analysis reflects assumptions regarding reimbursement framework stability and MDR notified body capacity expansion. A model refresh is warranted upon material change in US hospital value-based contracting penetration rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
United Kingdom Patient Monitoring Market
Patient Monitoring
Continuous Cardiac Monitoring Devices Market
Patient Monitoring
Heart Monitoring Devices Market
Patient Monitoring
Patient Monitoring Pods Market
Patient Monitoring
Artificial Intelligence (AI) in Remote Patient Monitoring Market
Patient Monitoring
Gas Exchange Monitor Market
Patient Monitoring
Cardiopulmonary Exercise Testing Market
Patient Monitoring
Respiratory Gas Monitors Market
Patient Monitoring
Europe Patient Monitoring Devices Market
Patient Monitoring
Europe Respiratory Monitoring Market
Patient Monitoring
Respiratory Monitoring Devices Market
Patient Monitoring
Ambulatory Heart Monitor Market
Patient Monitoring
IoT in Healthcare Market
Patient Monitoring
Global Bed Monitoring System and Baby Monitoring System Market
Patient Monitoring
Body Fat Measurement Market
Patient Monitoring
Portable Multi-Parameter Monitors Market