
 Europe Patient Monitoring Devices Market | 2026-2036
Europe Patient Monitoring Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Patient Monitoring Devices Market Insights
Silicon-based sensors are displacing traditional electrode materials in multi-parameter monitors and is realigning unit economics for European manufacturers. Philips leverages integrated diagnostic platforms to sustain its installed base across Dutch and Belgian hospital networks. Drägerwerk AG & Co. KGaA anchors perioperative monitoring through German-engineered anesthesia workstations. Masimo differentiates via proprietary pulse oximetry algorithms that command premium positioning in critical care procurement.
Patient monitoring devices encompass electronic systems that acquire, process, display, and transmit physiological data such as electrocardiography waveforms, blood oxygen saturation, respiratory rate, and invasive pressure readings with sampling frequencies typically exceeding 250 Hz for cardiac applications. These systems serve to enable early detection of clinical deterioration, reduce response times to adverse events, and support decentralized care delivery across acute and ambulatory environments. Wearables and remote patient monitoring are capturing disproportionate investment as health systems in Italy and Spain prioritize hospital-at-home reimbursement frameworks. Vital sign monitors retain the largest revenue pool but face margin compression from commoditized bedside units. Continuous glucose monitors represent the fastest-expanding application within ambulatory settings.
The EU Medical Device Regulation and CE marking requirements administered by notified bodies in Germany and France are extending compliance timelines and elevating documentation burdens for software-as-a-medical-device submissions. EMA coordination with national health technology assessment bodies in England and the Netherlands is reshaping evidence standards for connected monitoring platforms seeking reimbursement eligibility. Stakeholders must weigh regulatory capital requirements against the pace of wireless technology refresh cycles when allocating R&D budgets.
Market Dynamics
The EU Medical Device Regulation (MDR) is compressing product lifecycles as manufacturers redirect R&D capital toward clinical evidence generation for legacy device recertification. Wireless telemetry refresh cycles now outpace regulatory approval timelines, forcing portfolio rationalization across German and French hospital networks.
Growth Catalysts
- Hospital-at-home reimbursement frameworks:Italy and Spain are expanding DRG codes for remote monitoring, channeling acute care telemetry into ambulatory settings.
- Silicon photonics integration:Semiconductor foundries in the Netherlands are fabricating optical sensors that reduce power consumption in wearable monitors by half.
- Elderly care infrastructure mandates:National aging strategies across Scandinavia require continuous vital sign surveillance in nursing facilities.
Market Restraints
- Notified body capacity constraints:German and French certification bodies face 18-month backlogs for MDR conformity assessments, freezing new product introductions.
- Specialized sensor supply concentration:Single-source dependence on Taiwanese MEMS foundries exposes European OEMs to geopolitical shipping disruptions.
- Software-as-medical-device liability:Unclear jurisprudence on AI-enabled alarm algorithms elevates product liability premiums for algorithm developers.
Strategic Opportunities
- Perioperative depth-of-anesthesia monitoring:Belgian and Dutch surgical centers are retrofitting legacy workstations with proprietary brain function sensors.
- EU AI Act compliance services:Conformity assessment consultancies are capturing value from manufacturers lacking in-house risk management documentation capabilities.
- Cross-border telemedicine corridors:The European Health Data Space initiative enables remote monitoring data portability between Austrian and Czech hospital systems.
Industry Challenges
- Embedded systems firmware expertise:European engineering labor pools lack sufficient real-time operating system programmers for Class III device development.
- Legacy bedside monitor integration:Proprietary data protocols from 1990s-era installations block seamless interoperability with cloud analytics platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Patient Monitoring Devices Market |
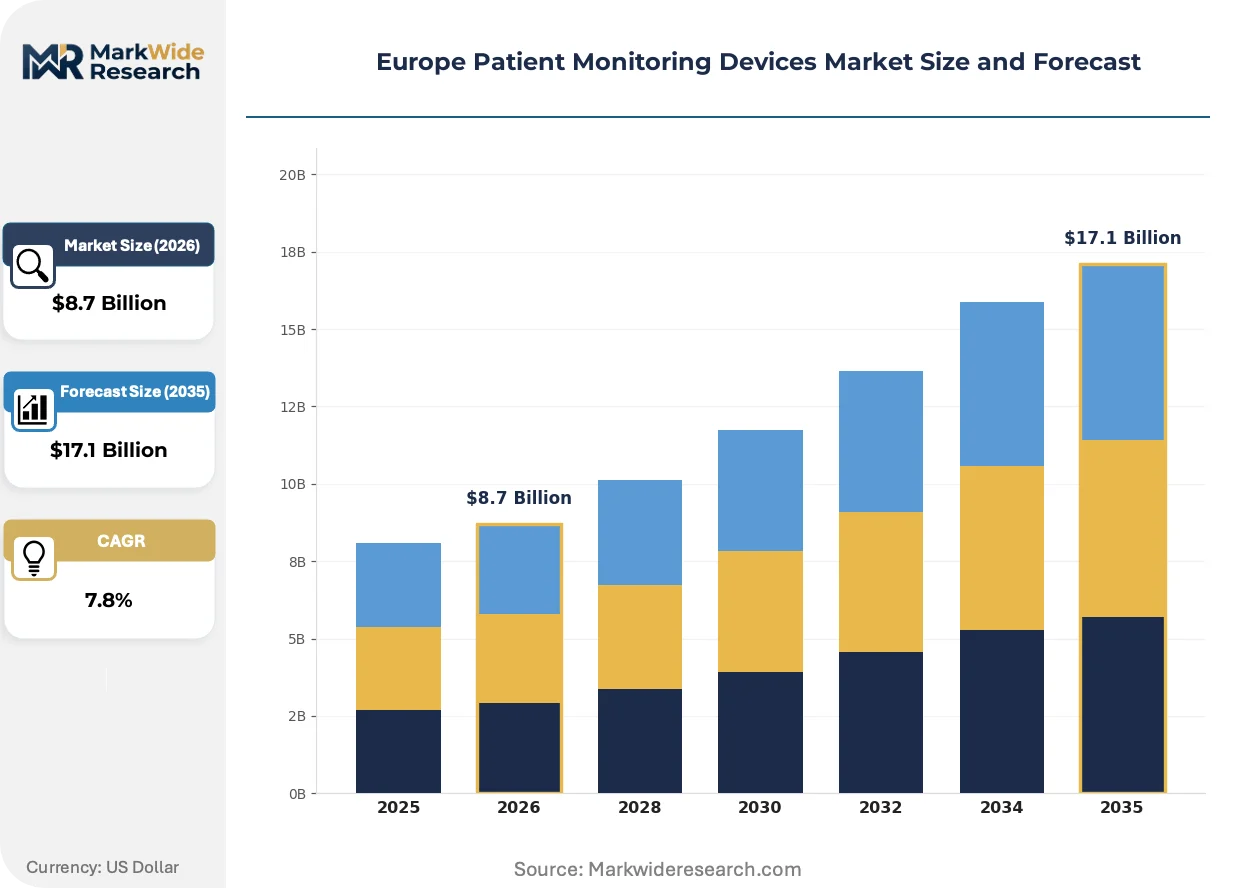
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearables, Vital Sign Monitors, Remote Patient Monitoring, Continuous Glucose Monitors Technology: Wireless, Cloud-Based, Bluetooth, Telehealth Systems End User: Hospitals, Home Care Settings, Clinics, Rehabilitation Centers Application: Chronic Disease Management, Postoperative Care, Cardiac Monitoring, Elderly Care |
| Companies Covered | GE Healthcare, Philips, Drägerwerk AG & Co. KGaA, Abbott, Medtronic, Boston Scientific Corporation, Johnson & Johnson, Masimo, Nihon Kohden Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Patient Monitoring Devices Market Trends and Innovations
Wireless connectivity standards and edge computing architectures are collapsing the latency gap between sensor acquisition and clinical decision support. European manufacturers are racing to embed AI inference engines directly into telemetry hardware.
Photoplethysmography sensors with multi-wavelength LED arrays are absorbing hemoglobin concentration measurement functions previously requiring invasive blood draws. Cardiology wards in German university hospitals are deploying these modules for continuous anemia screening. The technology is absorbing laboratory testing revenue streams while compressing nursing workload for specimen collection.
MDR Article 120 transition deadlines are forcing manufacturers to sunset non-compliant legacy telemetry systems by 2027. Notified bodies in Germany are prioritizing technical documentation reviews for devices with established clinical benefit profiles. Anesthesia workstation manufacturers are accelerating software updates to satisfy post-market surveillance requirements for algorithm transparency.
Acute care networks in France and Belgium are consolidating vendor contracts around integrated diagnostic platforms that bundle monitoring hardware with predictive analytics subscriptions. Purchasing committees now weight total cost of ownership over capital expenditure minimization. This behavioral shift favors suppliers with captive cloud infrastructure over standalone device vendors.
Europe Patient Monitoring Devices Market Segmentation
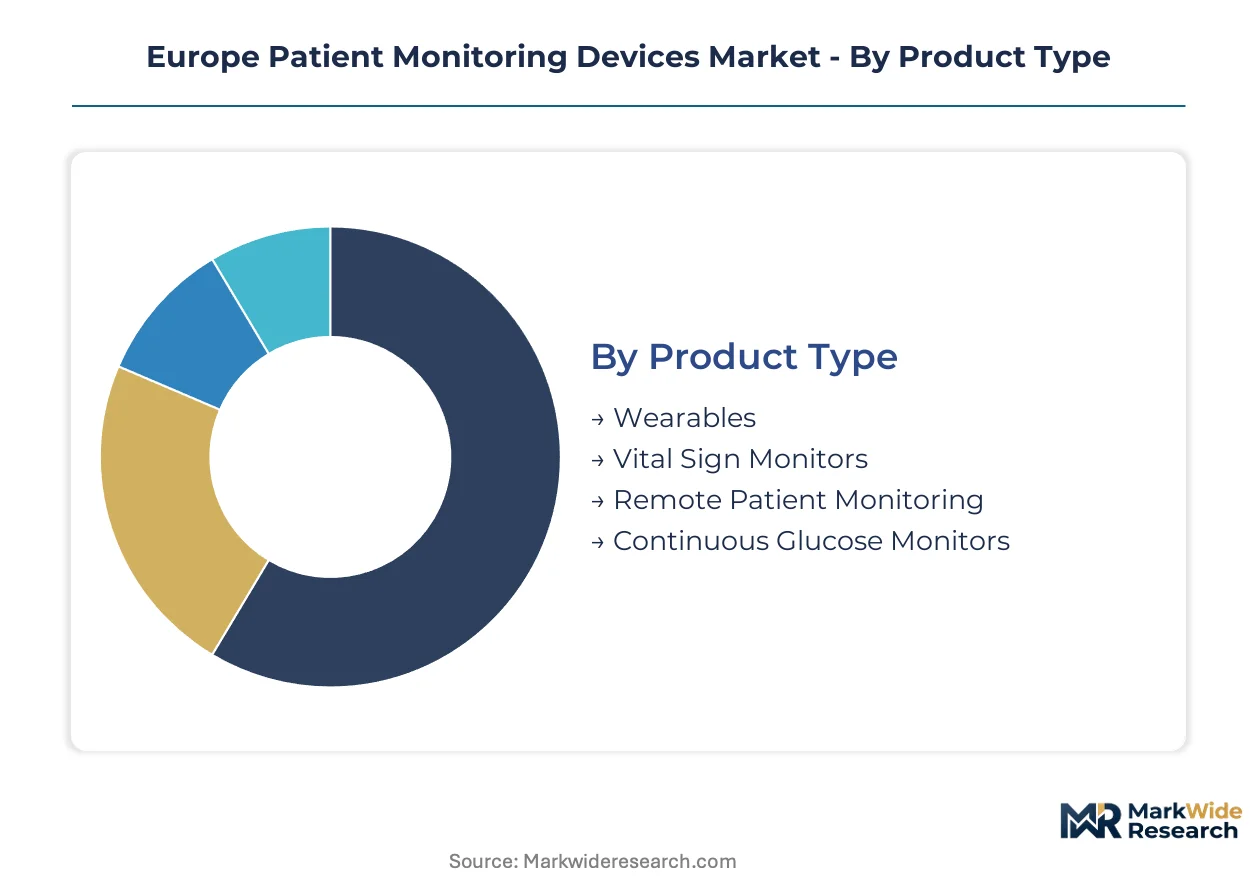
Product refresh cycles and regulatory recertification timelines are fragmenting procurement patterns across European health systems. Segmentation reveals where replacement demand concentrates versus where net-new installations are expanding.
Product Type:
Wireless telemetry upgrades are driving replacement decisions as hospitals phase out wired bedside installations.
- Wearables:Battery-powered wrist and patch form factors incorporating photoplethysmography and accelerometry for ambulatory vital sign capture. Demand clusters in Italian and Spanish hospital-at-home programs where DRG reimbursement now covers remote physiological surveillance.
- Vital Sign Monitors:Multi-parameter bedside units measuring ECG, SpO2, NIBP, and temperature through silicon-based sensor arrays. German and French acute care networks are consolidating procurement around integrated platforms that bundle hardware with predictive analytics subscriptions.
- Remote Patient Monitoring:Cloud-connected hub devices relaying patient data to centralized clinical dashboards.
- Continuous Glucose Monitors:Factory-calibrated interstitial glucose sensors with smartphone connectivity.
Volume placements concentrate in Vital Sign Monitors; the faster expansion belongs to Continuous Glucose Monitors.
Technology:
Connectivity infrastructure investments are reshaping technology adoption curves based on IT modernization budgets.
- Wireless:Proprietary radio frequency and Wi-Fi telemetry protocols enabling untethered patient mobility within hospital wards. Belgian and Dutch surgical centers are retrofitting anesthesia workstations with wireless modules to eliminate cable clutter in operating theaters.
- Cloud-Based:Scalable data architectures hosting patient records and algorithmic analytics on European-located servers. Scandinavian nursing facilities are mandating cloud connectivity for continuous surveillance of elderly residents under national aging strategies.
- Bluetooth:Low-energy pairing protocols for consumer-grade wearables and smartphone gateways.
- Telehealth Systems:Integrated video consultation platforms with embedded physiological data feeds.
Wireless deployments dominate current installations; cloud-based architectures are climbing the fastest as cybersecurity frameworks mature.
End User:
Care delivery site determines device specification requirements and reimbursement pathways.
- Hospitals:Acute care networks with 24/7 monitoring infrastructure and centralized alarm management. German university hospitals are deploying photoplethysmography modules with multi-wavelength LED arrays for continuous anemia screening in cardiology wards.
- Home Care Settings:Patient residences equipped with cellular-connected monitoring kits and nurse hotline support. Italian regional health authorities are expanding DRG codes to reimburse remote monitoring for post-acute recovery.
- Clinics:Outpatient facilities requiring portable vital sign acquisition for episodic visits.
- Rehabilitation Centers:Long-term recovery facilities tracking functional improvement metrics.
Hospitals retain the largest installed base; home care settings are gaining share fastest as reimbursement frameworks shift.
Application:
Clinical use case specificity determines sensor configuration and alarm threshold customization.
- Chronic Disease Management:Longitudinal surveillance protocols for diabetes, hypertension, and heart failure patients. French regional health agencies are bundling continuous glucose monitors with telehealth subscriptions for Type 1 diabetes populations.
- Postoperative Care:Early warning score algorithms detecting hemorrhage, infection, or respiratory compromise. Austrian and Czech hospital systems are piloting cross-border data portability for remote postoperative monitoring under the European Health Data Space initiative.
- Cardiac Monitoring:Arrhythmia detection through extended Holter-style or patch-based ECG recording.
- Elderly Care:Fall detection and nocturnal vital sign surveillance in nursing facilities.
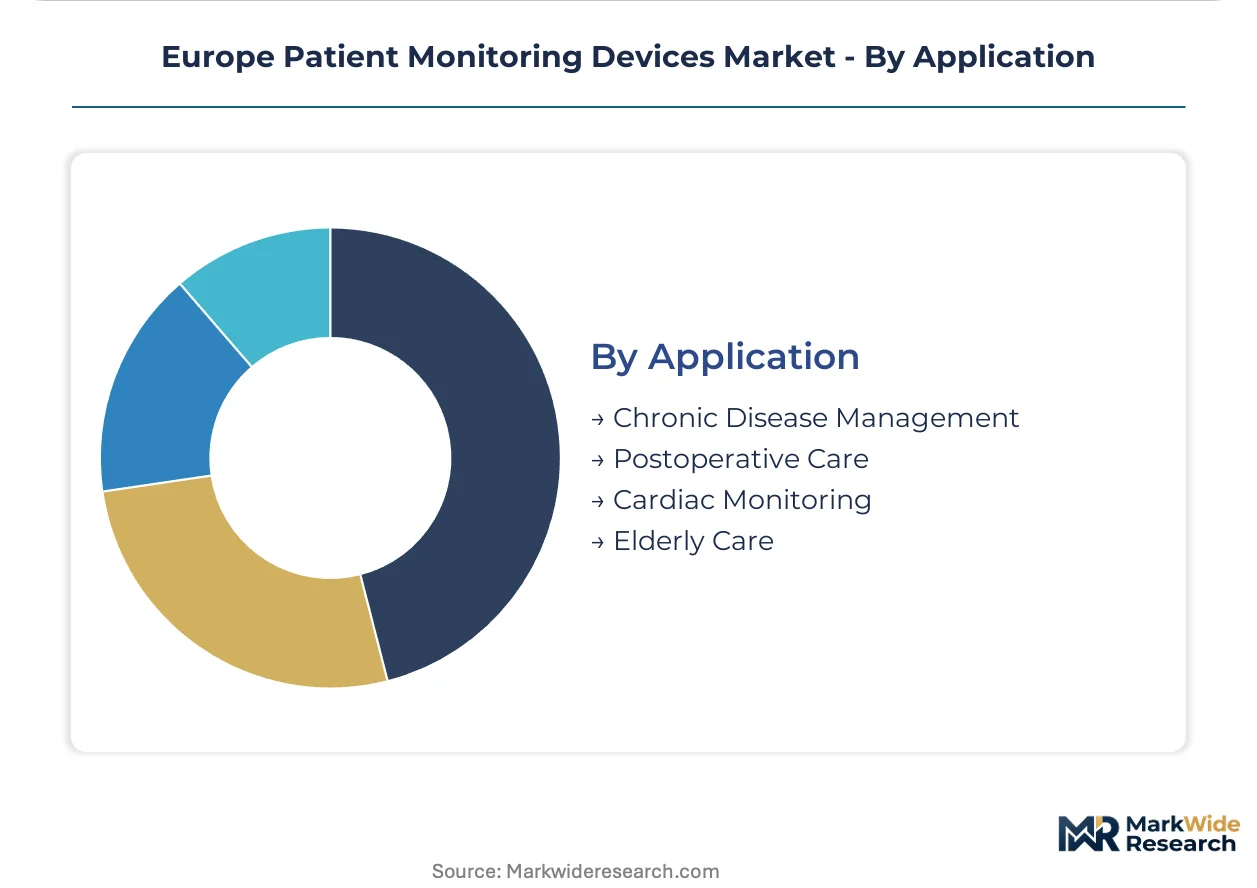
Chronic disease management accounts for the highest procedure volume; postoperative care applications are expanding most quickly as surgical volumes rebound.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Western European acute care networks account for the majority of procurement value, with hospital-at-home reimbursement frameworks accelerating adoption in Southern Europe. Nordic aging strategies and Central European cross-border data initiatives are reshaping deployment patterns.
Germany
University hospitals in Berlin and Munich are deploying multi-wavelength photoplethysmography modules for continuous anemia screening in cardiology wards. The EU MDR notified body in Berlin faces 18-month backlogs for conformity assessments, freezing new product introductions from domestic manufacturers. Baden-Württemberg's medical device cluster around Stuttgart anchors anesthesia workstation production for perioperative monitoring.
France
Regional health agencies in Paris and Lyon are bundling continuous glucose monitors with telehealth subscriptions for Type 1 diabetes populations. ANSM coordinates with HAS on health technology assessment standards for connected monitoring platforms seeking reimbursement eligibility. The Île-de-France surgical network is consolidating vendor contracts around integrated diagnostic platforms with predictive analytics.
Netherlands
Philips leverages integrated diagnostic platforms to sustain its installed base across Dutch hospital networks in Amsterdam and Rotterdam. EMA coordination with ZIN on evidence standards is reshaping reimbursement pathways for cloud-connected devices. Eindhoven's semiconductor foundries fabricate optical sensors that reduce power consumption in wearable monitors by half.
Italy
Regional health authorities in Lombardy and Emilia-Romagna are expanding DRG codes to reimburse remote monitoring for post-acute recovery. The Italian Ministry of Health is aligning national procurement frameworks with EU AI Act risk classification for algorithm-enabled devices. Milan's hospital-at-home programs are scaling battery-powered patch monitors for ambulatory vital sign capture.
Belgium
Surgical centers in Brussels and Leuven are retrofitting legacy anesthesia workstations with wireless modules to eliminate cable clutter in operating theaters. The Belgian Federal Agency for Medicines and Health Products enforces CE marking documentation for software-as-medical-device submissions. The Dutch-Belgian acute care corridor is piloting cross-border telemetry data portability under the European Health Data Space initiative.
Europe Patient Monitoring Devices Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated platform vendors capturing hospital procurement consolidation while component suppliers serve wearable OEMs. The vendor base concentrates around three strategic archetypes: diversified health technology conglomerates with captive cloud infrastructure, mid-cap anesthesia and critical care specialists with German engineering positioning, and algorithm-centric sensor developers commanding premium pricing in pulse oximetry. Competitive moves center on portfolio rationalization to satisfy MDR recertification timelines and strategic partnerships with semiconductor foundries for silicon photonics integration.
Among diversified health technology conglomerates, GE Healthcare and Philips exemplify the integrated platform archetype that bundles monitoring hardware with predictive analytics subscriptions. Drägerwerk AG & Co. KGaA anchors the mid-cap specialist tier with German-engineered anesthesia workstations. Masimo occupies a premium positioning in critical care procurement through proprietary pulse oximetry algorithm differentiation.
| Leading Market Players |
|---|
| GE Healthcare |
| Philips |
| Drägerwerk AG & Co. KGaA |
| Abbott |
| Medtronic |
| Boston Scientific Corporation |
| Johnson & Johnson |
| Masimo |
| Nihon Kohden Corporation |
| Others |
Pricing and Supply Chain Analysis
German and French hospital network consolidation around integrated diagnostic platforms is forcing component suppliers to bundle predictive analytics subscriptions with hardware, compressing margins on standalone bedside monitors while elevating pricing power for captive cloud infrastructure vendors.
Pricing Analysis
Volume placements concentrate in commoditized vital sign monitors where three-tier pricing structure across premium, standard, and economy levels has collapsed toward the lower band; price differentiation hinges on CE marking tier under MDR Article 120 and after-sales service bundling. Philips and Drägerwerk command premium positioning through German-engineered anesthesia workstations with proprietary algorithm transparency. Cost compression in standard-tier bedside units stems from Taiwanese MEMS foundry supply exposure. Home care settings show highest price sensitivity as Italian regional health authorities negotiate DRG reimbursement rates.
Supply Chain Analysis
Regional distribution centers in the Netherlands and Germany anchor hub-and-spoke patterns for semiconductor component flows into Eindhoven foundries and Stuttgart medical device clusters. Supply draws from Taiwan for MEMS sensors, the Netherlands for silicon photonics, and Germany for precision mechanical assemblies. Single-source dependence on Taiwanese foundries exposes European OEMs to geopolitical shipping disruptions. Distribution runs through specialized medical device logistics providers with temperature-controlled handling for optical sensor modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into semiconductor fabrication and captive cloud infrastructure development constitutes the defining competitive race, as manufacturers seek to escape foundry pricing volatility and capture recurring revenue from algorithm-enabled monitoring platforms.
For Market Incumbents: Anchor perioperative monitoring share through accelerated MDR recertification of legacy anesthesia workstations before 2027 sunset deadlines. Deepen in-house production of silicon photonics sensors at Eindhoven-adjacent facilities to offset Taiwanese MEMS supply risk. Defend against algorithm-centric entrants by embedding AI inference engines directly into telemetry hardware rather than cloud-only deployment. For New Entrants and Emerging Players: EU AI Act compliance services in Germany and France opens a window for consultancies capturing value from manufacturers lacking risk management documentation capabilities. Target Italian and Spanish hospital-at-home programs where DRG reimbursement expansion creates net-new installation demand outside entrenched acute care networks. Lead with battery-powered patch monitors for ambulatory vital sign capture rather than bedside unit displacement. For Investors and Strategic Acquirers: The window for entry favors mid-cap anesthesia specialists with German engineering positioning and established CE marking pathways. Long-term viability rests on portfolio breadth spanning hardware, software, and reimbursement strategy capabilities. Watch notified body backlog resolution in Berlin as the inflection indicator for new product introduction velocity.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR Article 120 recertification secures market access for legacy telemetry systems in German hospitals. |
| Hospital System Partnership | Consolidated vendor contracts with French surgical networks bundle hardware with predictive analytics subscriptions. |
| Software Companion Development | AI-enabled alarm algorithms satisfy EU AI Act risk classification requirements for algorithm transparency. |
| Backward Integration | Eindhoven semiconductor foundries reduce power consumption and external foundry dependence for wearable monitors. |
| Reimbursement Strategy | Italian regional DRG code expansion channels acute care telemetry into ambulatory hospital-at-home settings. |
Research Methodology
Independent corroboration across hospital procurement databases, GPO contracts, and EMA coordination records underwrites the qualitative findings. Primary interviews with hospital purchasing committees, biomedical engineers, and GPO contracts managers were cross-referenced against secondary validation from CE marking documentation, notified body assessment reports, and CMS Medicare data. Bottom-up unit economics modeling and top-down health system expenditure triangulation anchored market sizing.
Comparable-period anchoring to historical telemetry installation rates and reimbursement framework adoption curves structured the projection horizon. Segmentation dimensions spanned product type, connectivity technology, end user site, and clinical application with regional regulatory cluster overlays. CAGRs were derived from replacement cycle analysis against wireless refresh timelines and MDR compliance deadlines. Forecast inputs incorporated silicon photonics yield rates and notified body capacity utilization assumptions.
The model assumes a particular technology adoption path; alternative pathways for edge-computing AI inference would alter the outlook. Forecasts reflect documented assumptions around reimbursement expansion velocity and foundry supply continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Contact-Free Sleep Monitoring Systems Market
Patient Monitoring
South America Remote Patient Monitoring Systems Market
Patient Monitoring
Global Patient Monitoring Market
Patient Monitoring
Brain Tissue Oxygen Monitoring Systems Market
Patient Monitoring
Cardiopulmonary Exercise Testing Market
Patient Monitoring
B-Ketone Monitoring System Market
Patient Monitoring
Asia-Pacific Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
South Africa Patient Monitoring Market
Patient Monitoring
North America Patient Monitoring Market
Patient Monitoring
Wearable Patient Monitor Market
Patient Monitoring
Urine Monitoring Systems Market
Patient Monitoring
Cardiac Patch Monitor Market
Patient Monitoring
Saudi Arabia Patient Monitoring Market
Patient Monitoring
Global Blood Pressure Monitoring Devices Market
Patient Monitoring
South America Body Temperature Monitoring Market
Patient Monitoring
Pre-Mature Baby Monitoring Equipment Market