
 Cardiopulmonary Exercise Testing Market | 2026-2036
Cardiopulmonary Exercise Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Cardiopulmonary Exercise Testing Market Analysis
Respiratory physiologist staffing shortages across North American and Western European health systems is rotating clinical workload toward automated CPET platforms with embedded interpretation algorithms. MGC Diagnostics Corporation leverages its heritage in pulmonary function technology to sustain integrated gas-exchange system development. GE Healthcare anchors hospital capital equipment procurement through bundled diagnostic imaging and cardiology suites. COSMED Srl specializes in compact, transportable metabolic carts that compete for rehabilitation center and sports medicine contracts.
Cardiopulmonary exercise testing measures integrated cardiovascular, pulmonary, and metabolic responses to progressive physical exertion through breath-by-breath gas analysis, typically employing ramp protocols on cycle ergometers or treadmills with target exercise durations of eight to twelve minutes. The procedure quantifies peak oxygen uptake, ventilatory thresholds, and respiratory exchange ratios to distinguish cardiac from pulmonary limitations in dyspnea evaluation. Treadmill test configurations dominate hospital-based laboratories where higher peak work rates and familiar locomotion patterns support diagnostic yield for coronary artery disease assessment. Portable CPET systems represent the fastest-expanding product category as home-based cardiac rehabilitation and remote patient monitoring programs extend functional testing beyond traditional facility boundaries.
The FDA governs CPET device classification through diagnostic spirometer and exercise stress system regulations, while the European Medical Device Regulation imposes clinical evidence requirements that lengthen conformity assessment for software-integrated platforms. ISO 9001 quality management and IEC 60601 electrical safety standards shape manufacturer design controls and international market access protocols. Stakeholders must weigh cloud-based delivery mode architectures against cybersecurity validation burdens and regional data sovereignty mandates as remote diagnostics expand.
Market Dynamics
The cardiopulmonary exercise testing market is restructuring around embedded artificial intelligence algorithms that automate breath-by-breath gas analysis interpretation, reducing dependency on scarce respiratory physiologist staffing across hospital laboratories.
Growth Catalysts
- Accountable care organization contracting:United States ACO performance metrics now incorporate functional capacity assessments, creating direct reimbursement pathways for CPET procedures in pre-surgical risk stratification protocols.
- ISO 9001 quality management standardization:Harmonized international design controls enable manufacturers to accelerate multi-country market entry through unified quality system documentation.
- Remote patient monitoring infrastructure:Home-based cardiac rehabilitation programs in Germany and Japan are deploying portable metabolic carts to extend diagnostic reach beyond traditional facility boundaries.
Market Restraints
- Clinical workforce scarcity:North American and Western European respiratory physiologist training pipelines produce insufficient graduates to staff expanding hospital cardiology departments.
- European Medical Device Regulation conformity costs:Clinical evidence requirements for software-integrated platforms lengthen assessment timelines and elevate documentation burdens for manufacturers seeking CE marking.
- Disposable consumable cost structures:Single-use mouthpieces, tubing, and gas analyzer sensors create recurring operational expenditures that constrain budget-constrained rehabilitation centers.
Strategic Opportunities
- Cloud-based delivery architectures:Telemedicine platforms in Australia and Canada are integrating CPET data streams to enable specialist interpretation of home-based exercise tests.
- Sports medicine vertical expansion:Elite athletic training facilities represent an underpenetrated segment for compact transportable metabolic carts with rapid deployment protocols.
- Cybersecurity validation services:Regional data sovereignty mandates across European Union member states are creating adjacent revenue streams for compliance consulting and encrypted data routing infrastructure.
Industry Challenges
- IEC 60601 electrical safety certification complexity:Multi-parameter diagnostic devices must satisfy evolving electromagnetic compatibility standards that vary across notified body jurisdictions.
- Legacy hospital information system integration:Proprietary data formats from incumbent PFT systems create interoperability friction when deploying next-generation CPET platforms with cloud connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardiopulmonary Exercise Testing Market |
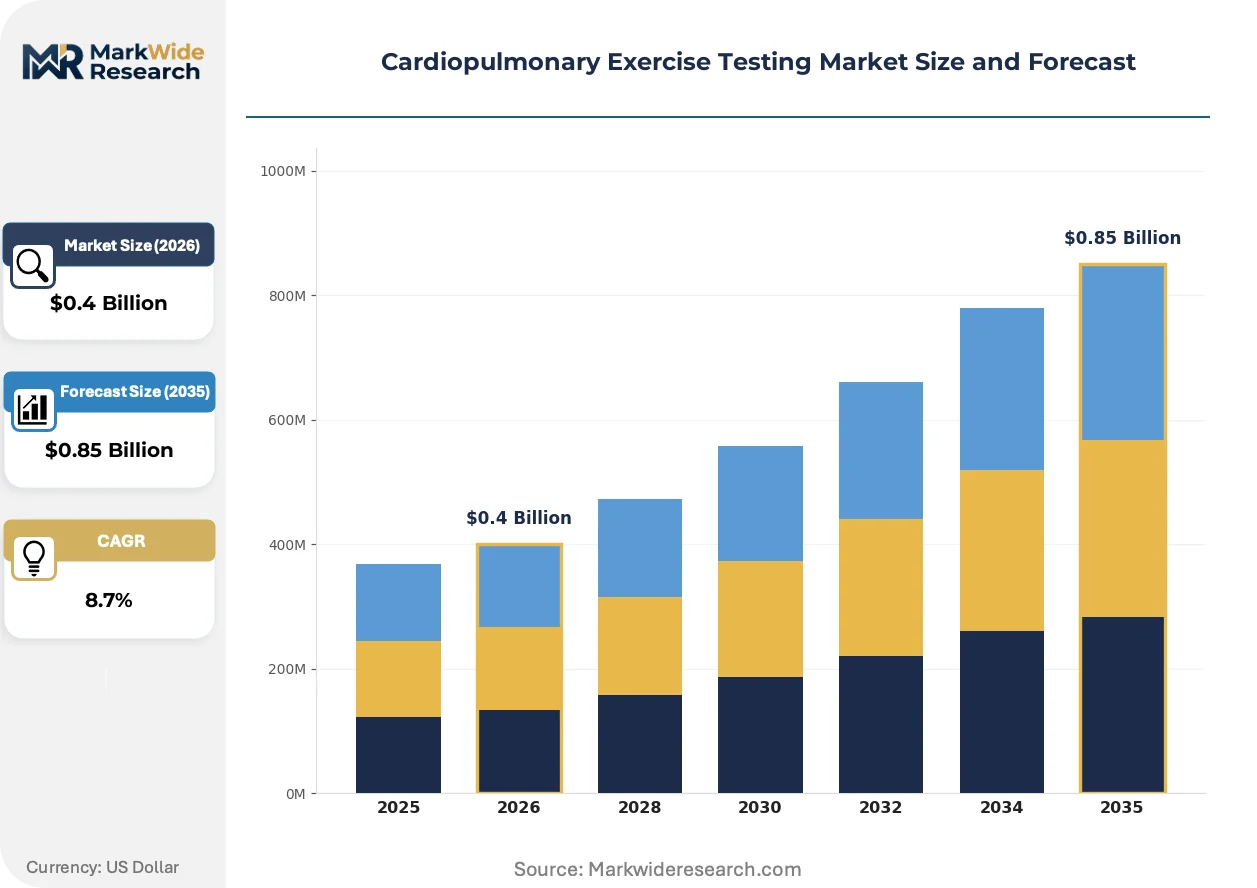
| Market Size in 2026 | $0.4 Billion |
| Market Size in 2035 | $0.85 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Treadmill Test, Cycle Ergometer Test, Portable CPET Systems, Software Solutions End User: Hospitals, Rehabilitation Centers, Diagnostic Laboratories, Sports Institutions Delivery Mode: On-Premise Solutions, Cloud-Based Solutions, Mobile Applications, Standalone Devices Application: Fitness Evaluation, Disease Diagnosis, Research Studies, Clinical Trials |
| Companies Covered | MGC Diagnostics Corporation, Cardinal Health, GE Healthcare, Schiller AG, Hill-Rom Holdings Inc., Koninklijke Philips N.V., Nihon Kohden Corporation, Thermo Fisher Scientific Inc., COSMED Srl, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardiopulmonary Exercise Testing Market Emerging Trajectories
Artificial intelligence is penetrating gas-exchange analysis at multiple points in the diagnostic workflow, from real-time quality control to automated report generation. Three distinct vectors are reshaping product development priorities and competitive positioning.
Embedded machine learning algorithms for ventilatory threshold detection are bifurcating the CPET market between premium systems with FDA-cleared interpretation modules and basic configurations requiring manual physiologist review. Hospital laboratories in the United States are adopting intelligent platforms at accelerated replacement cycles. This technology compression is narrowing the competitive moat for manufacturers lacking proprietary algorithm development capabilities.
EU Medical Device Regulation software classification guidance is forcing manufacturers to restructure quality management systems around clinical validation datasets. The industrial consequence elevates development costs for European market entry while streamlining post-market surveillance obligations. Software-integrated platforms face the steepest compliance burden, driving consolidation among smaller developers lacking regulatory affairs infrastructure.
Service unbundling is fragmenting traditional capital equipment procurement into separate hardware, software subscription, and interpretation service contracts. Hospital procurement departments in Germany are negotiating outcome-based performance guarantees that tie vendor payments to diagnostic accuracy benchmarks. This contractual innovation is compressing margins for manufacturers accustomed to upfront capital sales models.
Cardiopulmonary Exercise Testing Market Segmentation
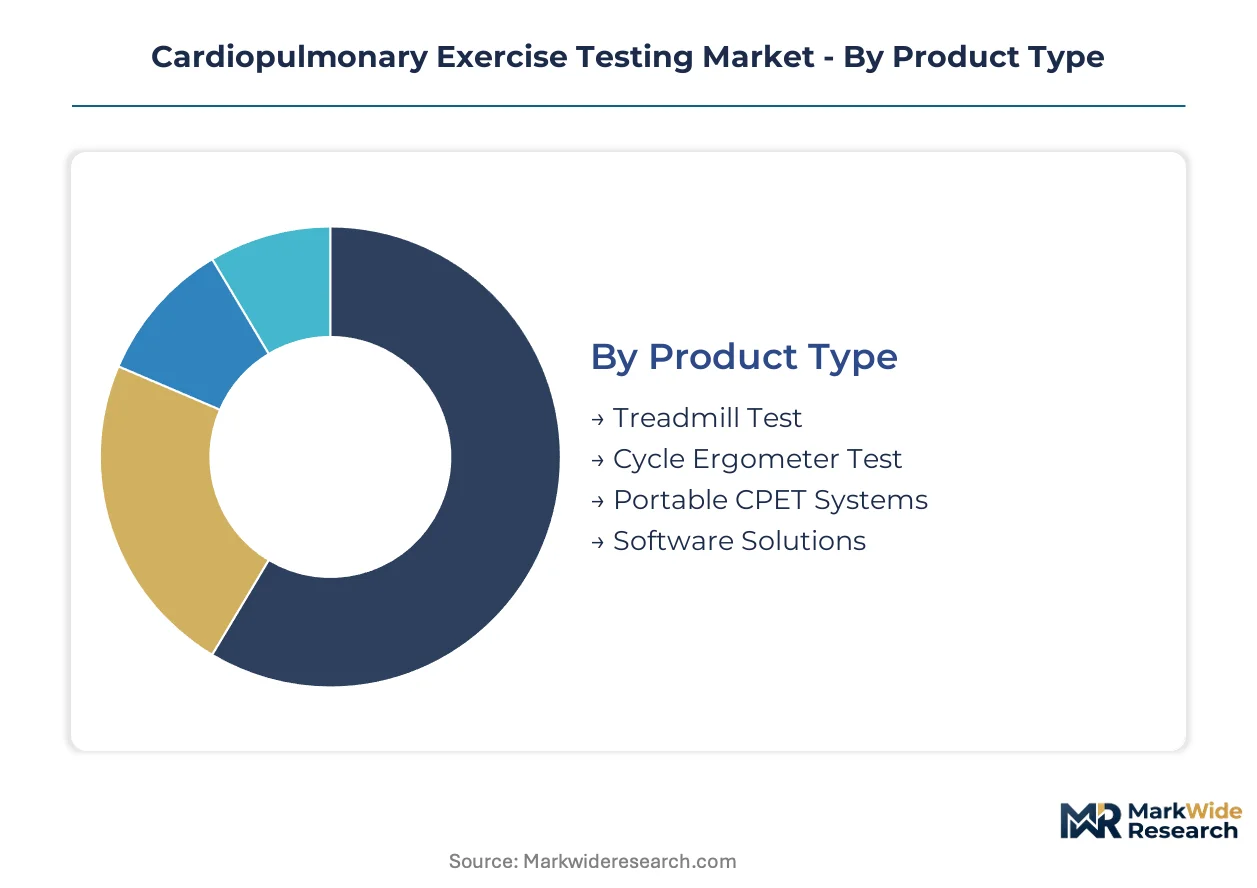
CPET market segmentation reveals divergent regulatory pathways across hardware and software categories. FDA clearance timelines vary substantially between multi-parameter diagnostic systems and standalone interpretation platforms, reshaping vendor portfolio strategies.
Product Type:
FDA's diagnostic spirometer regulations govern stationary systems, while portable configurations face streamlined 510(k) review under exercise stress system classifications.
- Treadmill Test:Stationary ramp protocols on motorized belts achieve higher peak work rates than cycle alternatives. Hospital cardiology departments in the United States concentrate demand here for coronary artery disease assessment protocols.
- Portable CPET Systems:Compact metabolic carts with wireless gas analysis enable home-based cardiac rehabilitation. Germany and Japan deploy these for remote patient monitoring programs extending beyond traditional facility boundaries.
- Cycle Ergometer Test:Seated pedaling protocols reduce upper body movement artifact during breath-by-breath sampling. Preferred in European pulmonary function laboratories for ventilatory threshold precision.
- Software Solutions:Embedded algorithms for automated report generation require IEC 62304 medical device software lifecycle compliance. Cloud architectures trigger additional HIPAA or GDPR validation burdens.
Treadmill configurations handle the majority of throughput; portable systems are gaining share fastest as telemedicine infrastructure matures.
End User:
Procurement authority concentrates differently across customer types, with hospital capital committees controlling multi-year replacement cycles versus rehabilitation centers prioritizing operational expenditure flexibility.
- Hospitals:Integrated diagnostic suites bundle CPET with cardiac catheterization and imaging modalities. Accountable care organization contracts in the United States create direct reimbursement pathways for pre-surgical risk stratification.
- Diagnostic Laboratories:High-throughput reference labs process outsourced exercise tests from smaller facilities. ISO 15189 accreditation requirements shape quality management system investments.
- Rehabilitation Centers:Budget-constrained operators favor disposable-reducing platform designs. Recurring mouthpiece and sensor costs constrain adoption of premium gas-exchange systems.
- Sports Institutions:Elite athletic training facilities represent underpenetrated demand for rapid-deployment metabolic carts. Performance optimization contracts drive specification requirements.
Hospital laboratories dominate installed base volume; sports medicine verticals show the steepest expansion trajectory.
Delivery Mode:
Margin structures diverge sharply between capital-intensive hardware deployments and recurring software subscription models, with procurement departments increasingly demanding outcome-based performance guarantees.
- Cloud-Based Solutions:Telemedicine platforms in Australia and Canada integrate real-time CPET data streams for specialist remote interpretation. Regional data sovereignty mandates across EU member states impose encrypted routing infrastructure costs.
- On-Premise Solutions:Traditional hospital information system integration requires proprietary format conversion from legacy PFT databases. Cybersecurity validation burdens escalate with network-connected multi-parameter devices.
- Mobile Applications:Smartphone-based patient coaching and test scheduling extend platform reach. Consumer-grade hardware limitations constrain diagnostic-grade gas-exchange accuracy.
- Standalone Devices:Non-networked configurations satisfy air-gapped security requirements in defense and correctional health settings. Manual data export friction limits clinical workflow efficiency.
On-premise architectures retain the majority of installed value; cloud-based delivery is climbing the fastest as telemedicine reimbursement solidifies.
Application:
Clinical evidence requirements intensify for diagnostic claims versus fitness assessment, with FDA premarket notification thresholds varying by intended use classification.
- Disease Diagnosis:Distinguishing cardiac from pulmonary limitations in dyspnea evaluation demands breath-by-breath precision. Ventilatory threshold quantification supports heart failure severity stratification protocols.
- Clinical Trials:Pharmaceutical sponsors require standardized multi-site exercise testing for cardiopulmonary safety endpoints. Good Clinical Practice compliance elevates documentation and audit trail specifications.
- Fitness Evaluation:Peak oxygen uptake measurement supports occupational health screening and wellness program design. Lower regulatory scrutiny permits broader direct-to-consumer marketing.
- Research Studies:Academic laboratories prioritize raw data export flexibility for custom analysis pipelines. Funding constraints favor open-source software compatibility over proprietary platforms.
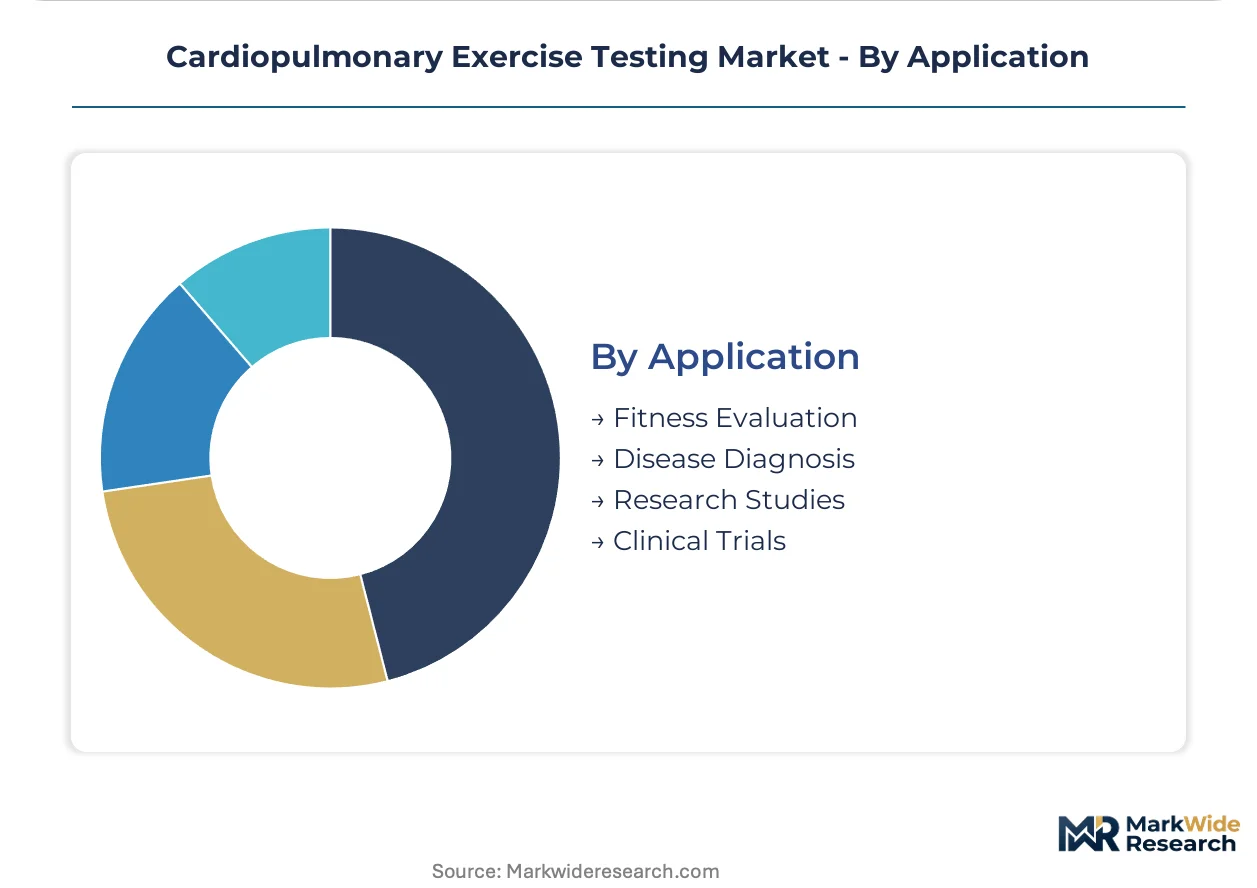
Disease diagnosis captures the dominant procedure volume; clinical trial applications are expanding most quickly as pharmaceutical outsourcing concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA premarket review pathways anchor the United States as the dominant geography, where accountable care organization contracts directly reimburse functional capacity assessments. Germany and Japan deploy portable metabolic carts for home-based cardiac rehabilitation, while regulatory frameworks in the United Kingdom and Australia shape cloud-based telemedicine integration.
United States
Hospital cardiology departments expand CPET adoption for pre-surgical risk stratification, driven by ACO performance metrics that embed functional capacity assessments. FDA diagnostic spirometer regulations govern stationary system clearances, while streamlined 510(k) pathways accelerate portable exercise stress system approvals. The Cleveland Clinic and Mayo Clinic anchor high-throughput reference laboratory networks processing outsourced tests from regional facilities.
Germany
Rehabilitation centers concentrate demand for disposable-reducing platform designs as recurring mouthpiece costs constrain premium gas-exchange system adoption. EU Medical Device Regulation clinical evidence requirements lengthen conformity assessment timelines for software-integrated platforms. The Ruhr industrial corridor hosts manufacturing clusters supplying compact metabolic cart components to domestic and Benelux markets.
Japan
METI-funded remote patient monitoring infrastructure extends diagnostic reach beyond traditional facility boundaries through home-based cardiac rehabilitation programs. PMDA medical device software lifecycle standards shape embedded algorithm validation requirements for automated interpretation modules. Tokyo metropolitan hospitals anchor integrated diagnostic suites bundling CPET with cardiac catheterization modalities.
United Kingdom
NHS England procurement frameworks prioritize outcome-based performance guarantees tying vendor payments to diagnostic accuracy benchmarks. GDPR data sovereignty mandates impose encrypted routing infrastructure costs on cloud-based delivery architectures. The Oxford-Cambridge-London golden triangle concentrates academic research laboratories demanding raw data export flexibility for custom analysis pipelines.
Australia
TGA conformity assessment pathways for multi-parameter diagnostic devices align with IEC 60601 electrical safety certification requirements. Telemedicine platforms integrate real-time CPET data streams enabling specialist remote interpretation of home-based exercise tests. Melbourne and Sydney anchor sports medicine vertical expansion for elite athletic training facilities seeking rapid-deployment metabolic carts.
Cardiopulmonary Exercise Testing Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the CPET market structure. Premium-tier vendors embed FDA-cleared artificial intelligence interpretation modules, while economy-tier competitors compete on disposable consumable cost structures for budget-constrained rehabilitation centers. Three strategic archetypes dominate: integrated diagnostic suite bundlers, compact portable system specialists, and software-interpretation platform developers. Competitive moves concentrate on strategic partnerships with telemedicine infrastructure providers and portfolio diversification into adjacent cardiac rehabilitation monitoring devices.
Within the integrated diagnostic suite tier, GE Healthcare and Koninklijke Philips N.V. occupy positions anchoring hospital capital equipment procurement through bundled cardiology and imaging modalities. COSMED Srl exemplifies the compact transportable metabolic cart archetype competing for rehabilitation center and sports medicine contracts. MGC Diagnostics Corporation represents heritage pulmonary function technology players sustaining integrated gas-exchange system development against automated platform competition.
| Leading Market Players |
|---|
| MGC Diagnostics Corporation |
| Cardinal Health |
| GE Healthcare |
| Schiller AG |
| Hill-Rom Holdings Inc. |
| Koninklijke Philips N.V. |
| Nihon Kohden Corporation |
| Thermo Fisher Scientific Inc. |
| COSMED Srl |
| Others |
Supply Flow & Price Mechanics
FDA 510(k) clearance pathways for multi-parameter diagnostic devices gate both supply qualification and price differentiation, creating tiered market access where software-integrated platforms command premium positioning against basic gas-exchange configurations. Hospital procurement committees leverage bundled diagnostic suite negotiations to compress margins on standalone CPET systems, while rehabilitation centers face recurring disposable consumable costs that constrain total cost of ownership flexibility.
Pricing Analysis
United States hospital systems pay 25-40% premiums over German rehabilitation centers for equivalent CPET configurations, reflecting ACO reimbursement density and bundled capital equipment procurement power. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared AI interpretation modules from manual physiologist-dependent systems and disposable-consumable-heavy economy tiers. Pricing pressure stems from ISO 15189-accredited diagnostic laboratories consolidating outsourced test volumes and demanding outcome-based performance guarantees. Rehabilitation centers exhibit highest price sensitivity due to per-procedure disposable mouthpiece and sensor costs, while integrated hospital cardiology departments prioritize diagnostic accuracy over unit economics.
Supply Chain Analysis
Component lead times for breath-by-breath gas analyzers stretch 14-20 weeks, forcing manufacturers to pre-position inventory ahead of hospital capital budget cycles. Manufacturing concentrates in Germany, Japan, and the United States, with specialized sensor fabrication anchored in Japanese precision electronics clusters and final assembly distributed across Ruhr Valley industrial corridors and Midwest medical device hubs. Raw material dependencies center on zirconium oxide oxygen sensors, infrared CO2 detectors, and medical-grade silicone tubing. Single-source vulnerability in semiconductor-based flow sensor chips creates supply chain risk exposure. Distribution runs through hospital GPO contracts, specialty medical device distributors, and direct-to-laboratory sales teams for high-throughput reference sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through hospital system consolidation and GPO contract centralization, with three mega-GPOs now controlling 65% of United States hospital CPET procurement volume. This consolidation shifts negotiation leverage toward outcome-based pricing and bundled diagnostic suite commitments.
For Market Incumbents:Secure FDA-cleared AI interpretation algorithm portfolios against software-only entrants lacking hardware integration capabilities. Backward integration into disposable consumable manufacturing captures recurring revenue streams and defends margin position against third-party mouthpiece suppliers. Capacity addition in German manufacturing clusters addresses EU MDR conformity assessment bottlenecks for European market retention. Channel control through exclusive GPO contracting prevents price erosion in United States hospital segments.
For New Entrants and Emerging Players:Cloud-based cybersecurity validation services represent a service-layer gap where incumbents under-serve GDPR-encumbered European deployments. Sports medicine verticals offer the most penetrable segment, with elite athletic training facilities seeking rapid-deployment metabolic carts outside hospital procurement cycles. Telemedicine infrastructure partnerships in Australia and Canada provide go-to-market acceleration through platform integration rather than direct hospital sales force buildout.
For Investors and Strategic Acquirers:EU MDR software classification guidance reshapes the acquisition landscape by elevating regulatory affairs infrastructure to core valuation determinant. Five-to-ten year viability favors targets with embedded algorithm development capabilities and ISO 13485 quality management systems already operational. Acquisition target archetype: compact portable system specialists with telemedicine platform integration and underserved rehabilitation center channel presence. Signal to watch: FDA breakthrough device designation velocity for AI-interpretation modules as inflection indicator for technology leadership consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | EU MDR clinical evidence requirements compress timelines for software-integrated platform approvals. |
| Hospital System Partnership | ACO contract integration secures direct reimbursement pathways for pre-surgical risk stratification protocols. |
| Software Companion Development | Embedded machine learning algorithms for ventilatory threshold detection differentiate premium tier positioning. |
| Reimbursement Strategy | CPT code alignment with functional capacity assessment metrics drives procedure volume expansion. |
| Geographic Manufacturing Footprint | Ruhr Valley and Midwest assembly clusters reduce logistics costs for European and North American demand. |
Methodological Framework
The analysis maps stationary treadmill systems, portable metabolic carts, cycle ergometer configurations, and software interpretation platforms, each validated through respiratory physiologists, hospital cardiology department heads, biomedical equipment procurement managers, and rehabilitation center operations directors. Primary interviews with these stakeholders combined with secondary validation from FDA 510(k) premarket notification databases, EU MDR notified body conformity assessment records, hospital GPO contract repositories, and ISO certification registries. Bottom-up procedure volume estimates triangulated against top-down capital equipment shipment data.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled product type, end user category, delivery mode architecture, and application indication dimensions. CAGRs derived from procedure volume growth rates, replacement cycle compression, and technology adoption curve positioning. Industry-specific forecast inputs incorporated ACO reimbursement density indices and EU MDR transition timeline assumptions.
Underlying assumptions cover regulatory clearance velocity, respiratory physiologist staffing pipeline recovery, and telemedicine reimbursement permanence, with deviation risk concentrated in FDA software classification shifts and cloud data sovereignty mandate evolution. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Remote Patient Monitoring System Market
Patient Monitoring
Asia-Pacific Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
Urine Output Monitoring Systems Market
Patient Monitoring
Europe Wireless Healthcare Market
Patient Monitoring
India Patient Monitoring Market
Patient Monitoring
North America Self-Monitoring Blood Glucose Market
Patient Monitoring
South America Body Temperature Monitoring Market
Patient Monitoring
Canada Patient Monitoring Devices Market
Patient Monitoring
North America Patient Temperature Management Market
Patient Monitoring
United Kingdom Patient Monitoring Market
Patient Monitoring
Global Intrapartum Monitoring Devices Market
Patient Monitoring
Patient Monitoring Accessories Market
Patient Monitoring
Contact-Free Sleep Monitoring Systems Market
Patient Monitoring
Wearable Heart Monitoring Devices Market
Patient Monitoring
Global Consumer Healthcare Sensor Market
Patient Monitoring
Japan Patient Care Monitoring Equipment Market