
 Central Patient Monitoring System Market | 2026-2036
Central Patient Monitoring System Market Size, Share, and Industry Trends Forecast 2026-2036
Central Patient Monitoring System Market Outlook
Aftermarket service revenue is tilting toward predictive analytics subscriptions and remote technical support contracts. Philips Healthcare leverages its installed base across North American health systems to sustain recurring software revenue streams. GE Healthcare anchors its position through deep integration with enterprise imaging and electronic health record architectures. Nihon Kohden competes in Asian markets with specialized cardiac monitoring configurations and localized regulatory compliance expertise.
A central patient monitoring system comprises networked bedside devices, centralized display workstations, and alarm management software that aggregate real-time physiologic data from multiple patients for simultaneous surveillance by clinical staff. These systems typically process electrocardiography, pulse oximetry, blood pressure, and respiratory rate signals through dedicated local area networks with sub-second latency requirements, enabling early detection of patient deterioration in acute care settings. Hardware devices dominate current procurement budgets, though cloud platforms represent the fastest-expanding segment as hospitals seek elastic compute capacity for AI analytics workloads. Software solutions command premium pricing when bundled with clinical decision support algorithms for cardiac monitoring and neurological event detection.
FDA 510(k) clearance pathways shape product development timelines and software update protocols for manufacturers serving the United States market. The EU Medical Device Regulation enforces stricter clinical evidence requirements and post-market surveillance obligations for systems distributed in Europe. Stakeholders must weigh regulatory compliance investments against the pace of AI algorithm iteration as competitive differentiation increasingly depends on real-time predictive capabilities rather than hardware specifications alone.
Market Dynamics
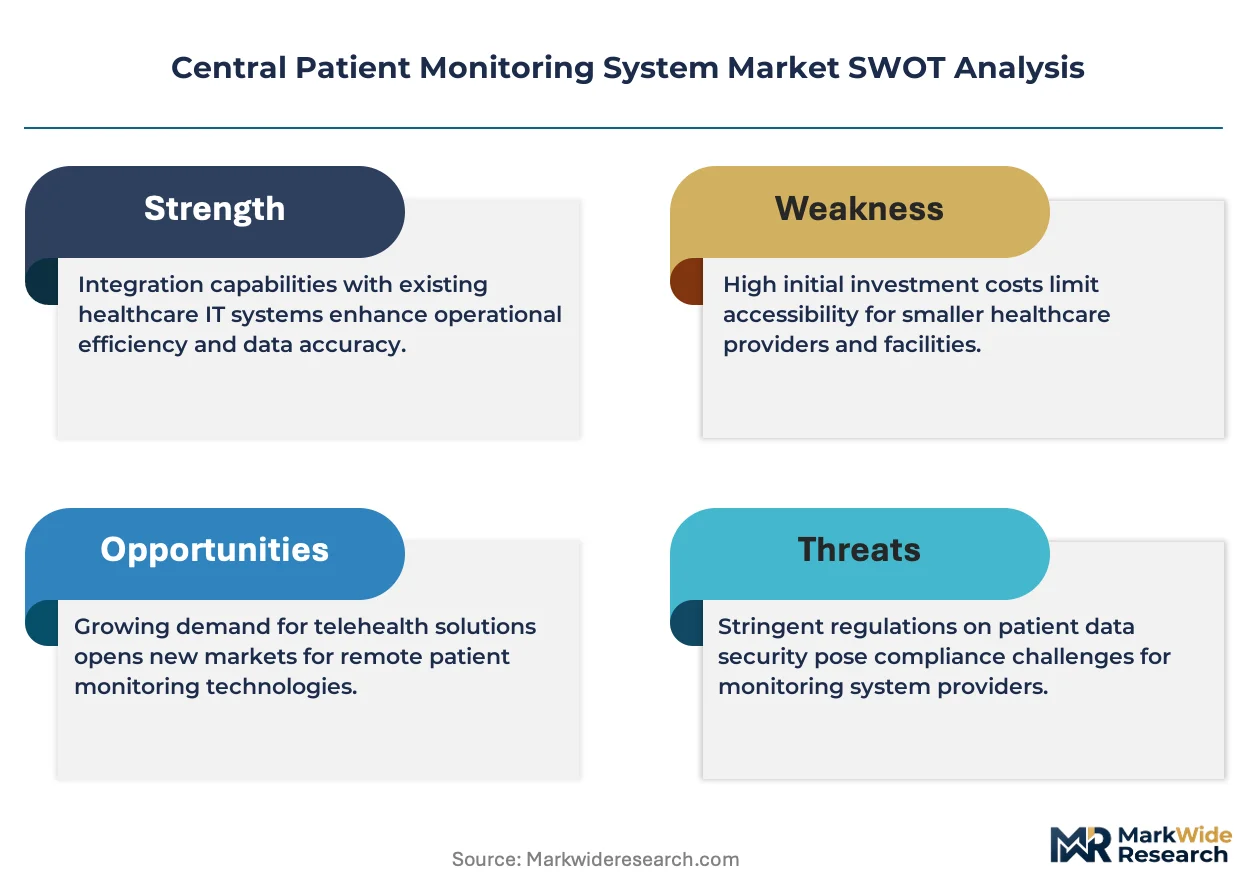
Hospital ICUs are consolidating disparate bedside devices into unified monitoring architectures, forcing vendors to prioritize interoperability certifications over standalone hardware performance metrics. This integration imperative is compressing procurement cycles and elevating software validation requirements as the primary competitive gate.
Growth Catalysts
- MDR clinical evidence mandates:European hospitals are replacing legacy systems ahead of EU Medical Device Regulation enforcement deadlines, creating replacement demand for compliant centralized platforms.
- AI-enabled early warning algorithms:Machine learning models processing multi-parameter physiologic streams are reducing false alarm rates in cardiac and neurological monitoring, accelerating ICU adoption.
- China's hospital tier-upgrading program:Secondary and tertiary facilities in Sichuan and Guangdong provinces are deploying integrated monitoring infrastructure as part of national acute care modernization initiatives.
Market Restraints
- Semiconductor supply concentration:Taiwan and South Korea fabrication constraints are extending lead times for specialized signal processing chips used in bedside telemetry modules.
- FDA 510(k) software validation costs:Premarket notification requirements for Class II medical devices are extending development timelines and freezing iterative algorithm updates.
- Wireless coexistence interference:Unlicensed spectrum congestion in 2.4 GHz and 5 GHz bands is degrading transmission reliability in dense clinical environments.
Strategic Opportunities
- India's Ayushman Bharat expansion:Government-funded critical care infrastructure in tier-2 cities is creating first-time demand for affordable centralized monitoring configurations.
- Cloud-native predictive analytics:Elastic compute architectures are enabling real-time deterioration scoring without on-premise server investments, opening mid-size hospital segments.
- Remote technical support subscriptions:Predictive maintenance models using device telemetry are shifting revenue from episodic service calls to recurring software contracts.
Industry Challenges
- Cybersecurity validation complexity:FDA and EU MDR requirements for networked medical device security are extending pre-market testing phases and complicating post-market patch management.
- Biomedical engineering talent scarcity:Health systems lack sufficient staff to configure alarm management protocols and optimize clinical decision support rule sets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Central Patient Monitoring System Market |
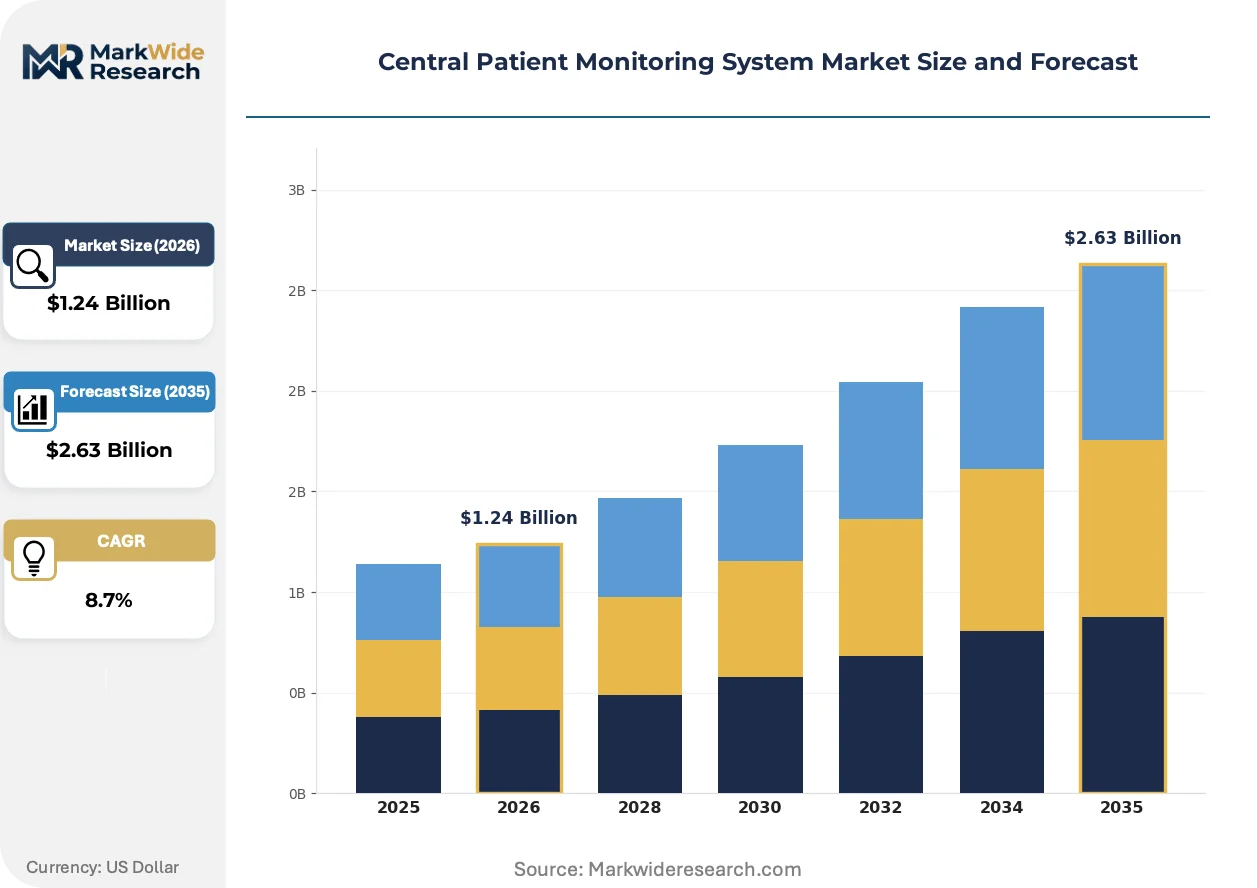
| Market Size in 2026 | $1.24 Billion |
| Market Size in 2035 | $2.63 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Solutions, Hardware Devices, Integration Services, Cloud Platforms End User: Hospitals, Homecare Providers, Long-term Care Facilities, Telehealth Services Technology: Wearable Devices, IoT Solutions, AI Analytics, Mobile Applications Application: Cardiac Monitoring, Respiratory Monitoring, Neurological Monitoring, Vital Signs Tracking |
| Companies Covered | Philips Healthcare, GE Healthcare, Nihon Kohden, Mindray, Drager, Spacelabs Healthcare, Schiller, Infinium Medical, Comen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Central Patient Monitoring System Market Strategic Shifts
Edge computing architectures are relocating analytics workloads from centralized servers to bedside devices, reducing latency for deterioration detection while complicating software update orchestration. This shift is redefining hardware-software value allocation across the vendor ecosystem.
Continuous glucose monitoring integration is collapsing the boundary between metabolic and physiologic surveillance, enabling diabetic patients in post-surgical ICUs to receive unified glycemic and hemodynamic oversight from single-platform displays. Academic medical centers in Germany and Massachusetts are piloting these converged workflows. The technology is collapsing procurement silos that historically separated endocrine monitoring from critical care capital budgets.
EU AI Act risk classification requirements are mandating conformity assessments for machine learning components in patient monitoring software, compelling vendors to document training data provenance and algorithmic explainability. Systems deployed in France and the Netherlands face heightened documentation burdens for cardiac arrhythmia detection modules. Manufacturers are responding by segregating European product variants with enhanced audit trails.
Subscription-based software licensing is displacing perpetual purchase models as hospital capital expenditure constraints intensify. Chief financial officers in United States health systems are favoring operational expenditure structures that bundle algorithm updates and cybersecurity patches. This preference is most pronounced among mid-size community hospitals in Texas and Florida seeking to preserve liquidity for staffing investments.
Central Patient Monitoring System Market Segmentation
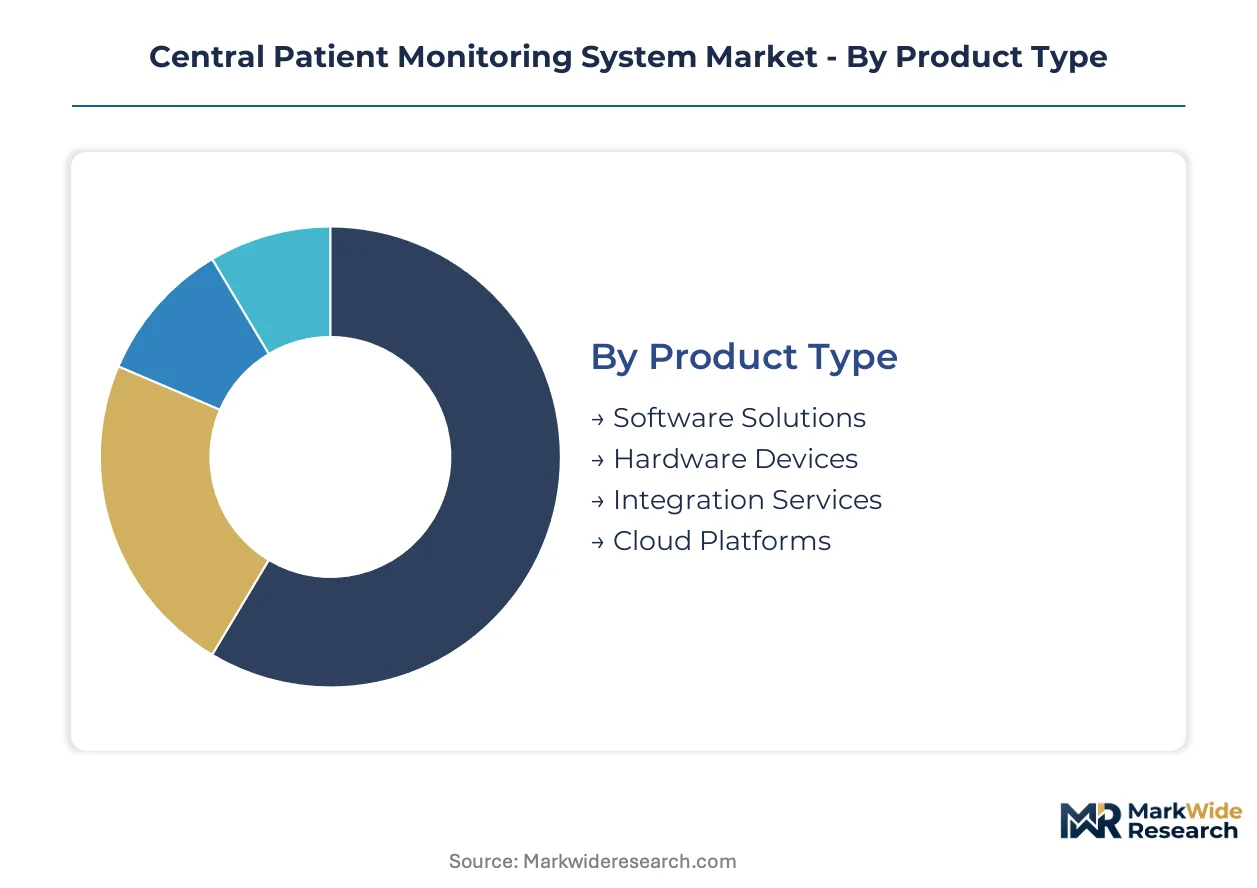
Segmentation in the central patient monitoring system market reveals divergent procurement priorities across acute care infrastructure, home-based delivery models, and algorithmic intelligence layers. Understanding these divisions exposes where capital expenditure concentrates versus where operational spending migrates toward recurring software contracts.
Product Type:
Mature hardware installations dominate installed base metrics while cloud-native architectures represent the emerging expansion frontier for elastic AI workloads.
- Hardware Devices:Bedside telemetry modules, centralized display workstations, and dedicated local area network infrastructure process electrocardiography, pulse oximetry, and respiratory rate signals with sub-second latency requirements. Demand concentrates in United States hospital ICUs modernizing aging telemetry footprints ahead of FDA cybersecurity guidance enforcement.
- Software Solutions:Alarm management platforms, clinical decision support algorithms, and predictive deterioration scoring engines command premium pricing when bundled with cardiac arrhythmia detection or neurological event identification capabilities. German academic medical centers are prioritizing these solutions to comply with EU AI Act documentation mandates for machine learning components.
- Cloud Platforms:Elastic compute architectures enable real-time analytics without on-premise server investments.
- Integration Services:Interoperability certification and legacy system migration support compress procurement cycles.
Hardware Devices retain volume leadership; Cloud Platforms hold the steepest expansion curve.
End User:
Cost tier stratification separates capital-intensive acute care deployments from operational-expenditure-focused outpatient and remote monitoring arrangements.
- Hospitals:Tertiary and secondary facilities in Sichuan and Guangdong provinces deploy integrated monitoring infrastructure through China's hospital tier-upgrading program. ICU consolidation of disparate bedside devices into unified architectures elevates interoperability certifications over standalone performance metrics.
- Telehealth Services:Remote patient surveillance platforms aggregate multi-parameter physiologic data for distributed clinical oversight, shifting revenue from episodic encounters to subscription-based monitoring contracts. United States health systems in Texas and Florida favor operational expenditure structures that preserve liquidity for staffing investments.
- Homecare Providers:Post-acute monitoring configurations extend surveillance beyond institutional boundaries.
- Long-term Care Facilities:Skilled nursing installations prioritize simplified alarm protocols and reduced biomedical engineering dependencies.
Hospitals command the largest absolute procurement volumes; Telehealth Services are climbing the fastest as reimbursement models shift toward remote care.
Technology:
Application-driven adoption patterns favor technologies that collapse latency between physiologic signal generation and clinical intervention.
- AI Analytics:Machine learning models processing multi-parameter physiologic streams reduce false alarm rates in cardiac and neurological monitoring. EU Medical Device Regulation clinical evidence mandates and EU AI Act conformity assessments are compelling vendors to document training data provenance and algorithmic explainability for European deployments.
- Wearable Devices:Continuous glucose monitoring integration collapses boundaries between metabolic and physiologic surveillance, enabling unified glycemic and hemodynamic oversight from single-platform displays in post-surgical ICUs.
- IoT Solutions:Networked sensor ecosystems enable device telemetry for predictive maintenance models.
- Mobile Applications:Clinician-facing interfaces for alarm acknowledgment and deterioration alerts extend surveillance beyond fixed workstations.
AI Analytics captures the steepest investment trajectory; Wearable Devices are gaining share fastest through metabolic-physiologic convergence.
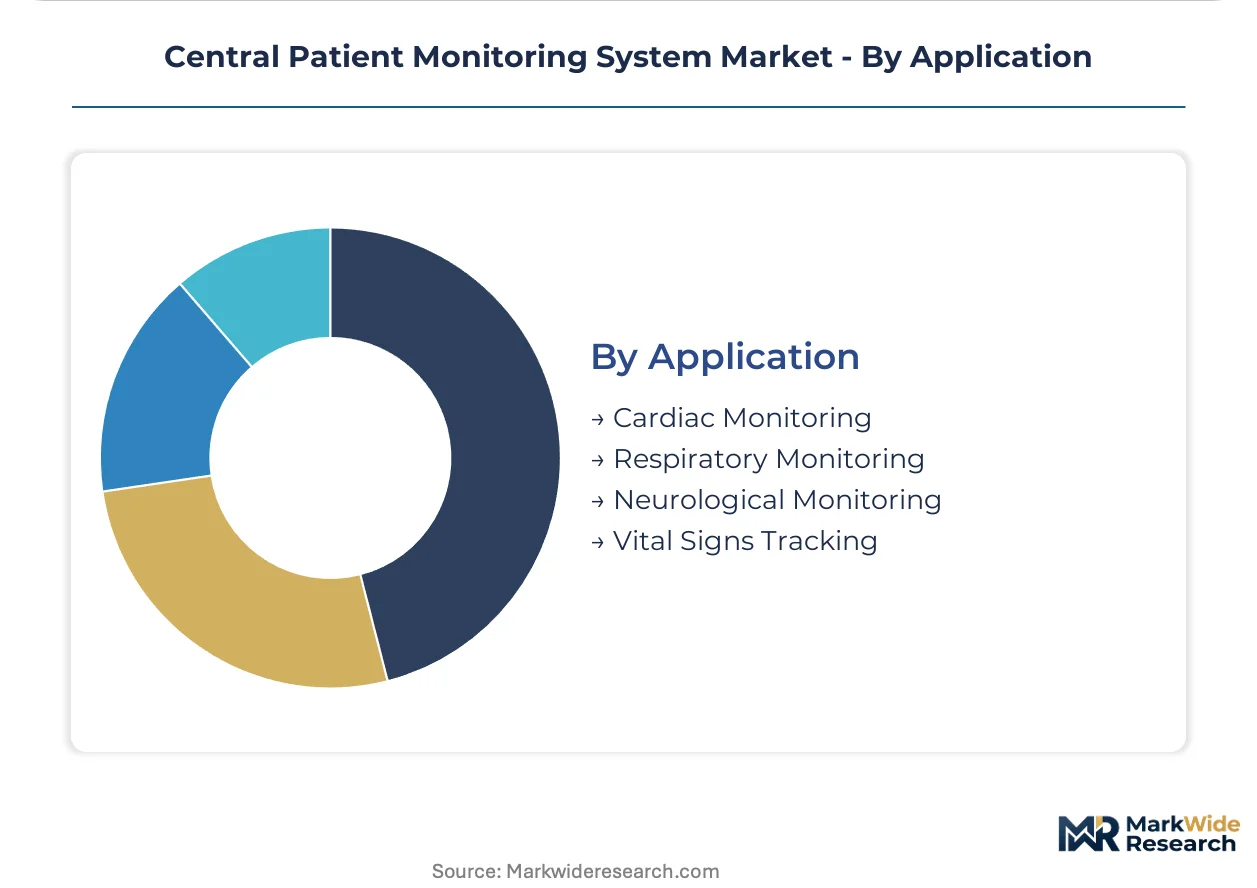
Application:
Customer type differentiation separates high-acuity specialized monitoring from generalized surveillance suitable for lower-intensity settings.
- Cardiac Monitoring:Arrhythmia detection modules with integrated early warning algorithms dominate ICU procurement budgets. FDA 510(k) software validation requirements extend development timelines for iterative algorithm updates, freezing competitive differentiation around real-time predictive capabilities.
- Neurological Monitoring:Seizure detection and intracranial pressure surveillance command specialized hardware-software bundles with enhanced signal processing fidelity. Academic medical centers in Massachusetts pilot converged workflows integrating continuous metabolic data.
- Respiratory Monitoring:Capnography and respiratory rate trending support ventilator weaning protocols.
- Vital Signs Tracking:Generalized multi-parameter surveillance serves lower-acuity wards and step-down units.
Cardiac Monitoring retains revenue concentration; Neurological Monitoring holds the premium pricing position through specialized configuration requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States health systems prioritize AI-enabled early warning algorithms and subscription software models, while German hospitals emphasize EU MDR compliance and clinical evidence documentation. Chinese facilities focus on tier-upgrading infrastructure programs at scale.
United States
Hospital ICUs in Texas and Florida are consolidating bedside telemetry into unified architectures that reduce false alarm rates through machine learning models. FDA 510(k) clearance pathways for Class II medical devices are extending software validation timelines and freezing iterative algorithm updates. Academic medical centers in Massachusetts pilot converged workflows integrating continuous metabolic and hemodynamic surveillance.
Germany
Tertiary facilities prioritize predictive analytics subscriptions and clinical decision support algorithms to comply with EU AI Act conformity assessments for machine learning components. The EU Medical Device Regulation enforces stricter post-market surveillance obligations and clinical evidence requirements for cardiac monitoring systems. Medical technology clusters in Baden-Württemberg and Bavaria anchor development of explainable AI documentation for arrhythmia detection modules.
China
Secondary and tertiary hospitals in Sichuan and Guangdong provinces deploy integrated monitoring infrastructure through national hospital tier-upgrading initiatives. NMPA medical device registration requirements are tightening software validation protocols for networked patient surveillance platforms. Manufacturing concentration in the Yangtze River Delta supports cost-competitive bedside telemetry production for domestic and export markets.
India
Government-funded critical care infrastructure in tier-2 cities through Ayushman Bharat expansion creates first-time demand for affordable centralized monitoring configurations. CDSCO medical device regulations are evolving to address software-as-a-medical-device classifications for cloud-native predictive analytics. Hospital procurement in Maharashtra and Karnataka favors operational expenditure structures that bundle remote technical support with hardware deployment.
Japan
Aging acute care infrastructure drives replacement demand for integrated monitoring platforms with enhanced interoperability certifications. PMDA pharmaceutical and medical device agency requirements shape software update protocols for AI-enabled deterioration scoring engines. Medical device manufacturers in the Kanto region focus on edge computing architectures that relocate analytics workloads to bedside devices for reduced latency.
Central Patient Monitoring System Market Competitive Environment
Capability concentration sits with specialized cardiac monitoring developers; scale advantage sits with diversified health technology conglomerates. The vendor ecosystem organizes around three archetypes: integrated platform providers with enterprise imaging and electronic health record architectures; regional specialists with localized regulatory compliance expertise; and emerging entrants with cloud-native elastic compute offerings. Dominant competitive moves include interoperability certification investments that compress procurement cycles, and predictive maintenance subscriptions that shift revenue from episodic service calls to recurring software contracts.
Among diversified health technology conglomerates, Philips Healthcare and GE Healthcare exemplify scale-driven platform strategies, while Nihon Kohden occupies a position as a regional specialist with concentrated presence in Asian markets. Philips leverages installed base relationships across North American health systems to sustain recurring software revenue streams. GE anchors positioning through deep integration with enterprise infrastructure. Nihon Kohden competes through specialized cardiac monitoring configurations and localized regulatory knowledge.
| Leading Market Players |
|---|
| Philips Healthcare |
| GE Healthcare |
| Nihon Kohden |
| Mindray |
| Drager |
| Spacelabs Healthcare |
| Schiller |
| Infinium Medical |
| Comen |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Taiwan and South Korea semiconductor fabrication is extending lead times for specialized signal processing chips and forcing bedside telemetry manufacturers to pre-commit capacity through multi-year contracts, compressing margin flexibility across hardware tiers while elevating subscription software pricing power.
Pricing Analysis
Long-term offtake agreements dominate procurement for hardware devices, while cloud-native predictive analytics platforms operate on tiered SaaS subscriptions calibrated to ICU bed count and algorithm complexity. Price differentiation hinges on FDA 510(k) clearance tier and bundled clinical decision support capabilities, with premium configurations commanding substantial markups for neurological event detection modules. Cost compression in mid-tier hardware intensifies as Chinese manufacturers from the Yangtze River Delta expand export capacity. Community hospitals in Texas and Florida exhibit acute price sensitivity, favoring operational expenditure structures that preserve liquidity for staffing investments.
Supply Chain Analysis
Export-control regimes restricting advanced semiconductor flows to Chinese medical device manufacturers are fragmenting sourcing strategies and accelerating regionalization of component supply. Taiwan, South Korea, and Japan anchor global production of specialized signal processing chips, analog front-ends, and high-fidelity sensor arrays. The supply chain draws from rare earth elements for magnetic components in telemetry modules, medical-grade plastics for housing assemblies, and precision-machined metals for patient-contact electrodes. Single-source vulnerability concentrates in advanced node semiconductors for AI-enabled bedside devices. Distribution runs through hospital GPO contracts in the United States, direct government procurement in China, and regional medical device distributors in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive positioning as interoperability certifications become the primary procurement gate, with unified monitoring architectures displacing standalone device purchasing across United States and German health systems.
For Market Incumbents: Harden installed base retention through predictive maintenance subscriptions that convert episodic service revenue into recurring software contracts, while accelerating backward integration into edge computing chip design to reduce dependency on Taiwan and South Korea fabrication. Deepen FDA 510(k) software validation capabilities to defend against cloud-native entrants with faster algorithm iteration cycles. For New Entrants and Emerging Players: Build out cloud-native predictive analytics offerings targeting mid-size community hospitals in India and Southeast Asia seeking elastic compute capacity without on-premise server investments. India's Ayushman Bharat tier-2 city expansion represents the most penetrable geography, with government-funded critical care infrastructure creating first-time demand for affordable centralized monitoring configurations. Partner with regional telehealth platforms to embed deterioration scoring engines into remote patient surveillance workflows. For Investors and Strategic Acquirers: Capital is best deployed toward specialized cardiac monitoring developers with EU MDR compliance documentation and explainable AI audit trails for European market access. Long-term viability favors vendors with demonstrated interoperability certification velocity and recurring software revenue exceeding fifty percent of total sales. Watch FDA cybersecurity guidance enforcement timelines as the signal indicating when hardware refresh cycles will accelerate across United States hospital systems.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Clearance timelines determine competitive algorithm refresh velocity against cloud-native rivals. |
| CE Marking Pathway | EU MDR clinical evidence mandates create replacement demand across German tertiary facilities. |
| Hospital System Partnership | Integrated EHR architectures at Massachusetts academic centers lock in multi-year platform contracts. |
| Software Companion Development | AI-enabled early warning algorithms for cardiac monitoring reduce false alarm rates and elevate pricing power. |
| Reimbursement Strategy | Remote patient monitoring CPT codes in United States telehealth services shift revenue to subscription models. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR conformity assessment databases, hospital procurement records, and GPO contract disclosures. Primary interviews engaged biomedical engineers, ICU clinical directors, health system purchasing committee members, and regulatory affairs specialists at device manufacturers. Secondary validation drew from CMS Medicare reimbursement data, NMPA registration filings, and customs trade records for medical device components. Bottom-up demand modeling across ICU bed counts, telemetry device replacement cycles, and software subscription attach rates was triangulated against top-down market sizing.
Forecast inputs incorporate hardware procurement volumes, SaaS subscription growth curves, and AI algorithm licensing penetration across the projection horizon. Segmentation dimensions modeled include product type, end user category, technology layer, and application acuity level. CAGRs were derived from regression analysis of historical replacement cycles and forward projection of regulatory-driven refresh demand. Industry-specific inputs include semiconductor lead time fluctuations and EU AI Act conformity assessment timelines.
Stress conditions across Taiwan fabrication capacity, FDA software validation backlog duration, and EU MDR enforcement rigor were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding hospital capital expenditure constraints and telehealth reimbursement stability. Material shifts in export control regimes for medical-grade semiconductors or NMPA software-as-a-medical-device classification rulings would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
North America Respiratory Monitoring Market
Patient Monitoring
Europe Hemodynamic Monitoring Market
Patient Monitoring
IoT in Healthcare Market
Patient Monitoring
Germany Blood Glucose Monitoring Market
Patient Monitoring
Sleep Tracking Devices Market
Patient Monitoring
US Remote Patient Monitoring and Care Market
Patient Monitoring
Respiratory Monitoring Market
Patient Monitoring
Remote Home Monitoring Systems Market
Patient Monitoring
RFID Blood Monitoring System Market
Patient Monitoring
Healthcare Biosensors IoT Market
Patient Monitoring
Europe Remote Patient Monitoring Systems Market
Patient Monitoring
Wearable Health Sensors Market
Patient Monitoring
Telemonitoring Systems Market
Patient Monitoring
Global Consumer Healthcare Sensor Market
Patient Monitoring
Health Sensors Market
Patient Monitoring
Asia-Pacific Patient Monitoring Market