
 United Kingdom Patient Monitoring Market | 2026-2036
United Kingdom Patient Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Patient Monitoring Market Analytics
The United Kingdom is reshaping patient monitoring supply dynamics through domestic manufacturing investments in medtech corridors near Cambridge and Oxford. GE Healthcare leverages its Hatfield imaging campus to sustain engineering pipelines for connected monitoring ecosystems. Medtronic anchors its European patient monitoring R&D in Watford, competing on algorithm-intensive cardiac platforms. Philips dominates UK hospital procurement through long-term service contracts spanning diagnostic and monitoring modalities.
Patient monitoring encompasses continuous or intermittent physiological measurement through sensors, signal processors, and data interfaces that track parameters including electrocardiography, pulse oximetry, respiratory rate, and blood glucose with sampling frequencies from seconds to hours. These systems serve clinical decision-making by enabling early deterioration detection, chronic condition surveillance, and post-acute care transitions outside traditional facilities. Wearable devices and remote monitoring systems capture the fastest expansion as NHS integrated care boards reallocate budgets toward community-based surveillance, while implantable monitors command premium margins in cardiac arrhythmia management despite constrained eligibility pools. Bluetooth and Wi-Fi connectivity standards define the technology architecture, though Zigbee retains niche traction in long-term care facility deployments where mesh network resilience matters.
The Medicines and Healthcare products Regulatory Agency enforces UKCA marking requirements for active implantable and non-implantable monitoring devices, while NHS England's Digital Technology Assessment Criteria govern procurement eligibility for software-enabled systems. Care Quality Commission inspections pressure providers to demonstrate audit trails from monitoring data through clinical action, tightening vendor accountability for integration reliability. Stakeholders must track how the Health Research Authority evolves real-world evidence frameworks for algorithm updates that alter device indications without full re-registration.
Market Dynamics
NHS England's hospital-at-home mandates are compressing deployment cycles for remote patient monitoring infrastructure. Integrated care systems now channel capital toward interoperable platforms that bridge acute and community settings, forcing vendors to reconfigure service architectures around real-time data continuity rather than episodic device sales.
Growth Catalysts
- Integrated Care System Procurement Mandates:NHS England's 2022 structural reforms consolidate purchasing authority within 42 integrated care boards, creating concentrated demand pools for vendors with proven interoperability credentials.
- Remote Monitoring Reimbursement Codes:New NHS tariff structures compensate providers for virtual ward admissions, directly monetizing continuous physiological surveillance outside hospital walls.
- Bluetooth Low Energy 5.3:Extended range and reduced power consumption enable patch-based cardiac monitors to stream data reliably from patient homes to clinical dashboards.
Market Restraints
- UKCA Marking Transition Costs:The Medicines and Healthcare products Regulatory Agency's post-Brexit conformity assessment requirements impose retesting burdens on manufacturers previously certified under EU MDR frameworks.
- Semiconductor Supply Concentration:Analog front-end chips for biosignal acquisition remain concentrated among Taiwanese foundries, exposing UK device assemblers to lead-time volatility.
- Interoperability Standard Fragmentation:Competing data exchange protocols between NHS Digital's FHIR implementations and proprietary vendor formats create integration friction for multi-supplier deployments.
Strategic Opportunities
- Scotland's National Digital Platform:NHS Scotland's unified health record infrastructure offers a testbed for AI-augmented early warning algorithms that could scale to England's fragmented system.
- Social Care Technology Fund:Department of Health and Social Care grants targeting domiciliary care providers create a channel for consumer-grade monitoring devices with clinical-grade backend integration.
- MHRA Software-as-a-Medical-Device Pathway:Streamlined registration for algorithm-updatable monitors enables vendors to commercialize predictive deterioration models without full hardware re-certification.
Industry Challenges
- Clinical Informatics Workforce Gap:NHS trusts report persistent shortages of data engineers capable of configuring device-to-EHR integration pipelines, delaying go-live dates for monitoring deployments.
- Cybersecurity Certification Burden:DCMS Code of Practice for consumer IoT security and NHS Digital's Data Security and Protection Toolkit impose overlapping compliance requirements on connected device vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Patient Monitoring Market |
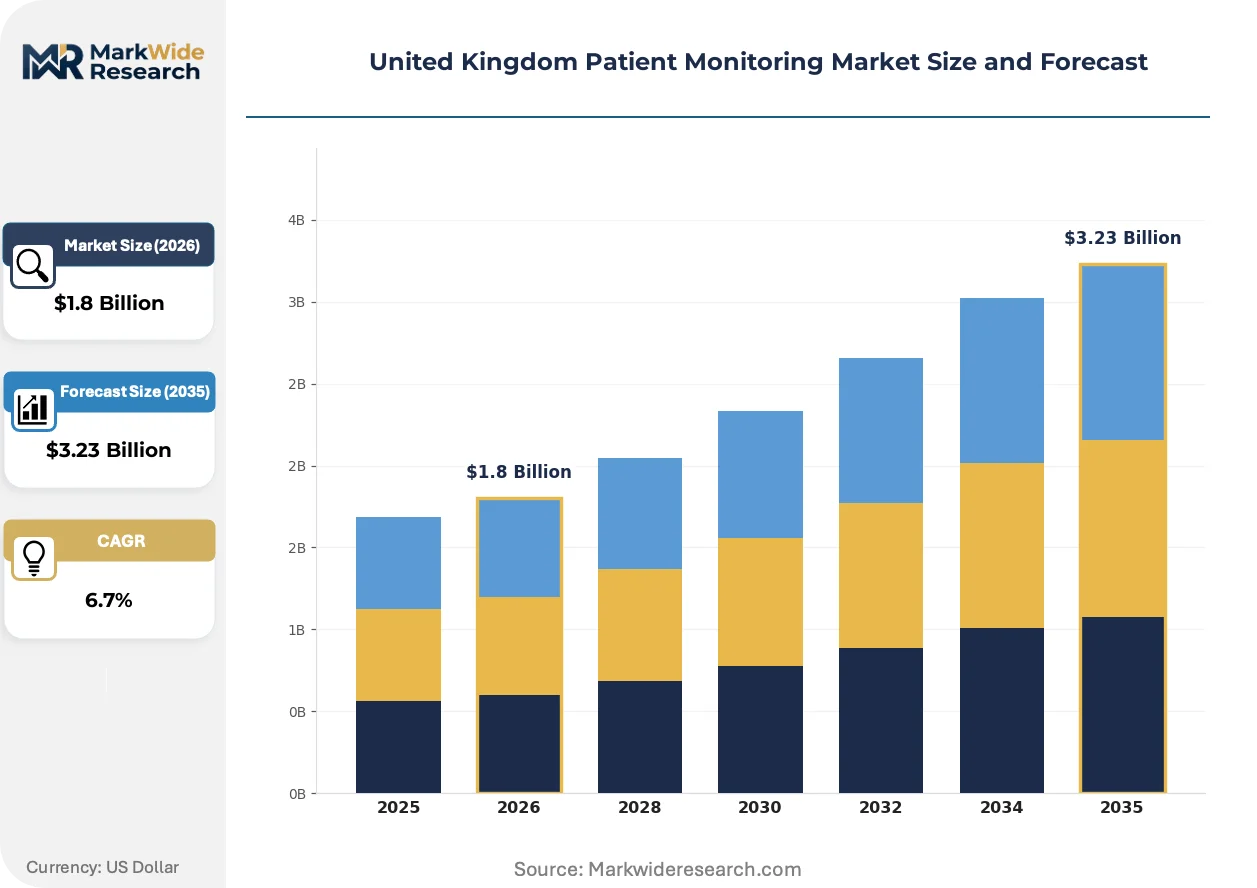
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Implantable Monitors, Remote Monitoring Systems, Pulse Oximeters Technology: Bluetooth, Wi-Fi, Zigbee, NFC End User: Hospitals, Home Care, Rehabilitation Centers, Long-Term Care Facilities Application: Cardiac Monitoring, Respiratory Monitoring, Diabetes Management, Chronic Disease Management |
| Companies Covered | Abbott Laboratories, GE Healthcare, Becton, Dickinson and Company, Boston Scientific Corporation, Koninklijke Philips N.V., Medtronic Plc, Dragerwerk AG, Johnson & Johnson, Masimo Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Patient Monitoring Market Evolving Landscape
Algorithmic patient risk stratification is displacing threshold-based alarm systems across NHS acute trusts. Vendors are re-engineering monitoring platforms around machine learning inference at the edge, compressing response times for deterioration events while reducing false alarm fatigue among nursing staff.
Pulse oximetry and respiratory rate sensing is migrating from fingertip clip devices to ring-form-factor wearables. Early adopters in post-COVID virtual ward programs favor continuous nocturnal oxygen saturation trending over spot-check workflows. This shift is compressing average selling prices for legacy clip-on sensors while opening subscription revenue streams for cloud analytics layers.
The Medicines and Healthcare products Regulatory Agency's 2024 guidance on predetermined change control plans permits manufacturers to deploy algorithm updates without fresh UKCA assessments. Cardiac monitoring vendors are restructuring R&D roadmaps around iterative arrhythmia detection model improvements rather than hardware refresh cycles. Implantable loop recorder segments show fastest uptake of this regulatory flexibility.
Integrated care boards are unbundling device procurement from multi-year service contracts that previously locked hospitals into single-vendor ecosystems. Greater Manchester and West Midlands systems now separate hardware acquisition, software licensing, and clinical support into distinct tender lots. This fragmentation favors specialized monitor manufacturers previously excluded from bundled diagnostic-imaging contracts.
United Kingdom Patient Monitoring Market Segmentation
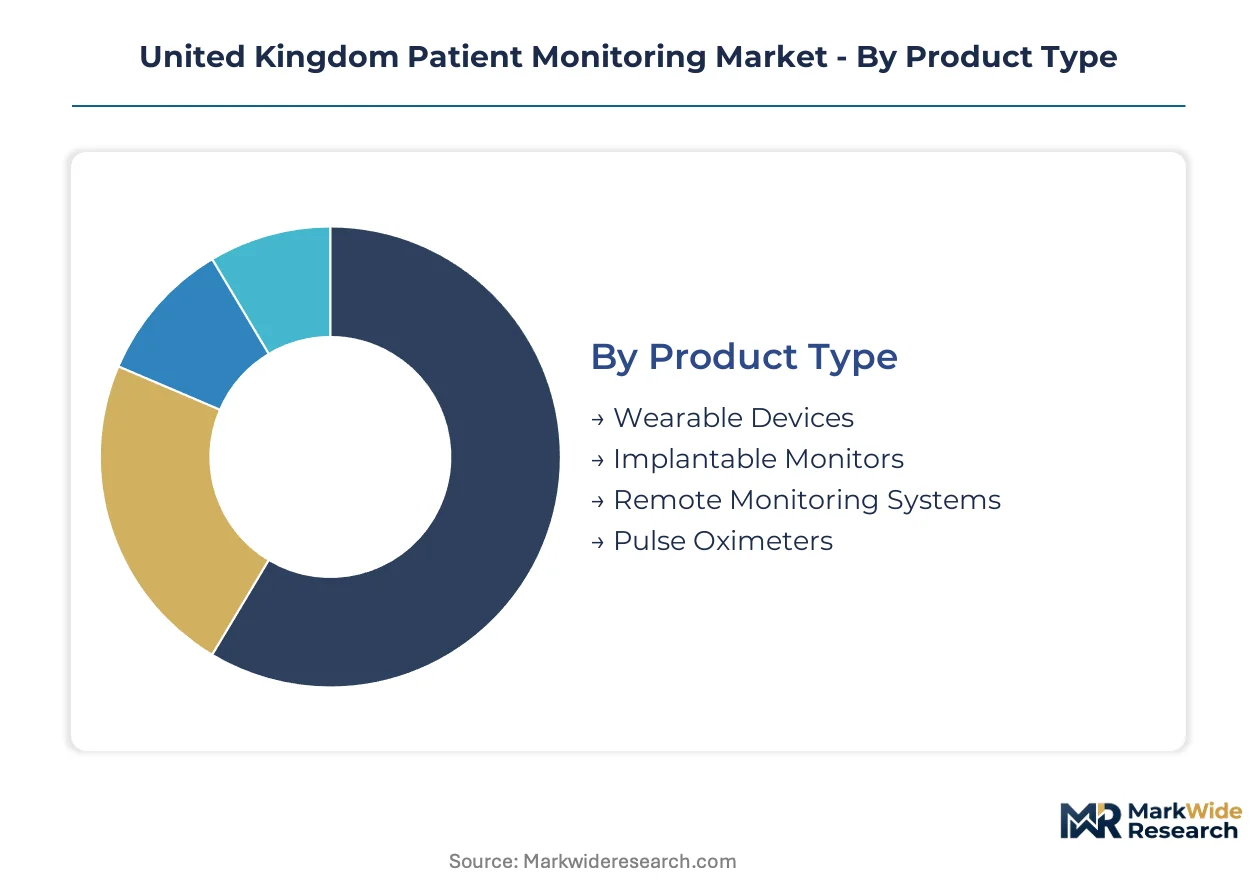
Patient monitoring segmentation in the United Kingdom tracks how physiological surveillance fragments across device formats, wireless protocols, care settings, and clinical indications. NHS procurement reforms and hospital-at-home expansion reshape which segments capture capital allocation versus operational budgets.
Product Type:
Use-case spectrum spans acute bedside telemetry through domiciliary patch monitors to subcutaneous implantable sensors.
- Wearable Devices:Patch-form electrocardiography monitors and ring-based pulse oximeters stream continuous data via Bluetooth Low Energy to clinical dashboards. Demand concentrates in Greater London integrated care systems deploying virtual ward programs for post-acute cardiac patients, with NHS tariff reforms directly reimbursing remote physiological surveillance.
- Remote Monitoring Systems:Hub-and-sensor architectures aggregate multiple vital signs through cellular or broadband backhaul to cloud analytics platforms. Procurement is accelerating across South East England where integrated care boards reallocate budgets from hospital infrastructure toward community-based deterioration detection.
- Implantable Monitors:Subcutaneous loop recorders and leadless pacemakers with diagnostic capabilities command premium pricing in cardiac arrhythmia management despite constrained eligibility pools requiring electrophysiologist referral.
- Pulse Oximeters:Fingertip clip devices face price compression as nocturnal oxygen saturation trending migrates to ring-form-factor wearables in post-COVID respiratory surveillance programs.
The dominant share belongs to Wearable Devices, while Remote Monitoring Systems are closing the gap fastest.
Technology:
Connectivity standards determine network resilience, power consumption, and integration friction with NHS Digital infrastructure.
- Bluetooth:Bluetooth Low Energy 5.3 dominates patch-based cardiac and pulse oximetry applications, with extended range enabling reliable home-to-cloud streaming without patient smartphone dependency.
- Wi-Fi:Higher bandwidth supports multi-parameter bedside monitors and video-enabled virtual ward consultations, though power constraints limit ambulatory deployment.
- Zigbee:Mesh network architecture retains niche traction in long-term care facility deployments where infrastructure resilience across multiple relay nodes matters more than consumer interoperability.
- NFC:Near-field pairing simplifies device onboarding and clinician authentication workflows, particularly for diabetes management devices requiring frequent patient-initiated data uploads.
Bluetooth holds the installed base advantage, yet Wi-Fi is expanding most quickly as hospital-at-home programs demand richer media channels.
End User:
Capital intensity and procurement authority vary sharply across institutional purchasers versus dispersed domiciliary care providers.
- Hospitals:Acute trusts deploy multi-parameter bedside monitors and centralized telemetry stations, with Care Quality Commission inspection pressures tightening requirements for audit trail documentation from device data through clinical action.
- Home Care:Domiciliary providers access Department of Health and Social Care Social Care Technology Fund grants for consumer-grade devices with clinical-grade backend integration, though workforce gaps in data engineering delay deployment timelines.
- Long-Term Care Facilities:Nursing homes prioritize fall detection and nocturnal vital sign trending for dementia cohorts, with mesh network reliability outweighing interoperability concerns.
- Rehabilitation Centers:Post-acute stroke and orthopedic recovery programs leverage wearable accelerometry and remote physiologic monitoring to shorten length of stay while tracking community reintegration.
Hospitals retain the largest revenue concentration, though Home Care is gaining share fastest as integrated care boards shift surveillance budgets upstream.
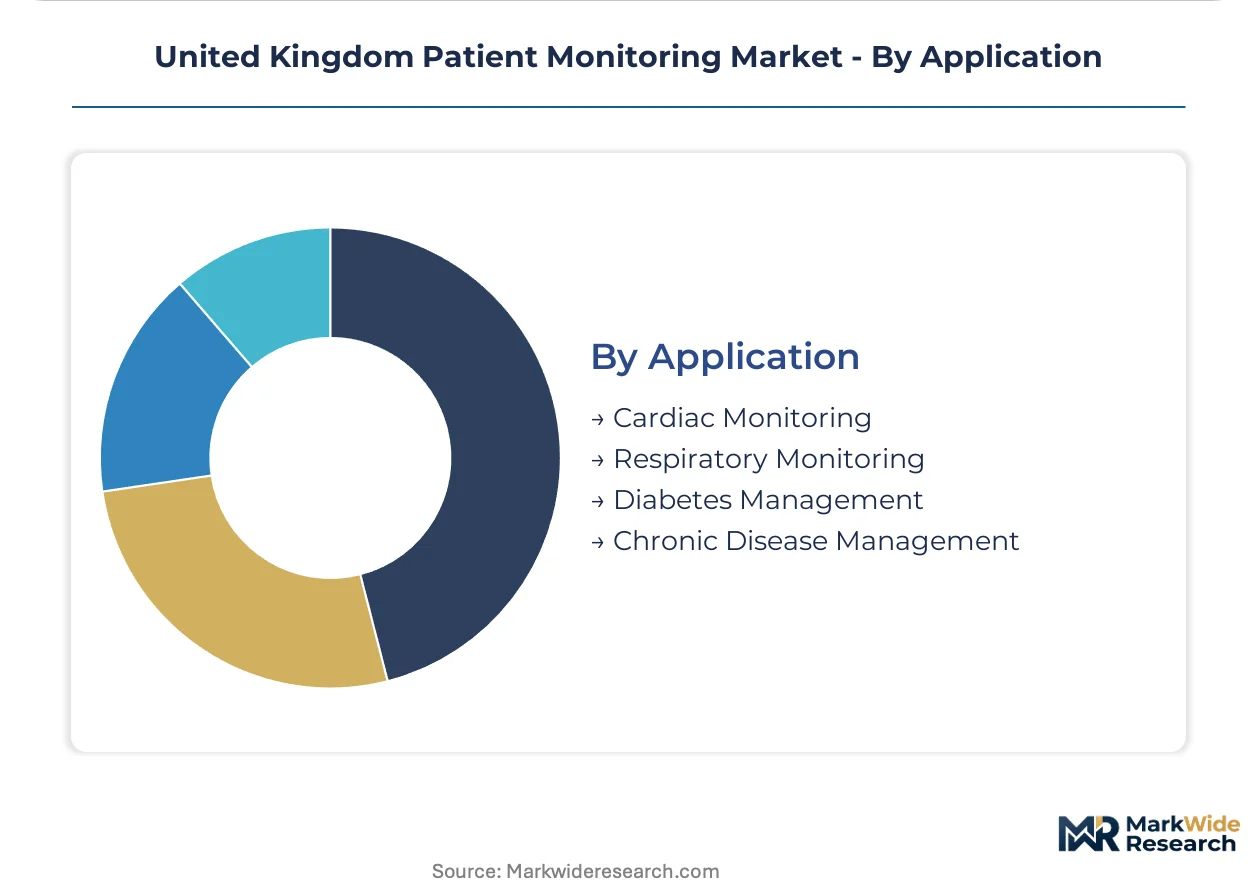
Application:
Clinical indication determines algorithm complexity, regulatory pathway, and reimbursement eligibility under NHS tariff structures.
- Cardiac Monitoring:Arrhythmia detection and heart failure surveillance drive the most sophisticated algorithm development, with Medicines and Healthcare products Regulatory Agency predetermined change control plans enabling iterative model updates without full UKCA re-certification.
- Chronic Disease Management:Multi-condition platforms track hypertension, chronic kidney disease, and frailty syndromes through integrated vital sign streams, aligning with integrated care board population health management objectives.
- Respiratory Monitoring:Post-COVID virtual wards and COPD exacerbation prevention programs favor continuous nocturnal oxygen saturation and respiratory rate trending over traditional spot-check workflows.
- Diabetes Management:Continuous glucose monitors with predictive hypoglycemia alerts face slower NHS adoption due to eligibility restrictions and specialized endocrinology workforce constraints compared to cardiac applications.
Cardiac Monitoring commands the deepest revenue pool, while Chronic Disease Management is climbing the fastest as risk stratification algorithms mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across the United Kingdom diverge sharply between acute hospital concentration in Greater London and the South East versus community-based surveillance expansion in the North and Midlands, where integrated care boards reallocate capital toward domiciliary monitoring infrastructure.
Greater London and the South East
Virtual ward admissions for post-acute cardiac patients drive demand for Bluetooth-enabled patch monitors, with NHS tariff reforms directly reimbursing remote physiological surveillance. The Medicines and Healthcare products Regulatory Agency's 2024 software-as-a-medical-device guidance accelerates compliance timelines for vendors serving this procurement hub. GE Healthcare leverages its Hatfield imaging campus to sustain engineering pipelines for connected monitoring ecosystems serving London's integrated care systems.
Midlands
West Midlands integrated care boards unbundle device procurement from multi-year service contracts, fragmenting hardware acquisition into distinct tender lots. NHS England's hospital-at-home mandates compress deployment cycles for remote patient monitoring infrastructure across Birmingham and Coventry catchments. Medtronic anchors its European patient monitoring R&D in Watford, competing on algorithm-intensive cardiac platforms for this restructured procurement environment.
North England
Greater Manchester's integrated care system separates hardware acquisition, software licensing, and clinical support into distinct procurement lots, favoring specialized monitor manufacturers. Care Quality Commission inspection pressures tighten requirements for audit trail documentation from device data through clinical action. The region's industrial corridors near Manchester and Leeds host emerging domestic manufacturing investments in medtech assembly.
Scotland
NHS Scotland's National Digital Platform offers a unified health record infrastructure for AI-augmented early warning algorithm testing. The country's centralized procurement authority channels demand toward interoperable platforms bridging acute and community settings. Edinburgh and Glasgow clusters concentrate algorithm development for predictive deterioration models targeting remote patient cohorts.
United Kingdom Patient Monitoring Market Competitive Landscape
Capability concentration sits with algorithm-intensive cardiac specialists; scale advantage sits with diversified diagnostic-imaging conglomerates with long-term NHS service contracts. The vendor base stratifies across three tiers: premium-tier manufacturers with predetermined change control plan approvals, mid-tier specialists in single-parameter monitoring, and emerging entrants from consumer electronics seeking clinical-grade backend integration. Dominant competitive moves include portfolio diversification into software-as-a-medical-device offerings and strategic partnerships with integrated care boards for virtual ward infrastructure.
Among US-based diversified medtech conglomerates, Abbott Laboratories and Boston Scientific Corporation exemplify the premium-tier cardiac monitoring archetype, while Medtronic Plc anchors algorithm-intensive platform development from its Watford R&D base. Koninklijke Philips N.V. occupies a position representing scale-driven service contract dominance across UK hospital procurement, competing against GE Healthcare's imaging-integrated monitoring ecosystems.
| Leading Market Players |
|---|
| Abbott Laboratories |
| GE Healthcare |
| Becton, Dickinson and Company |
| Boston Scientific Corporation |
| Koninklijke Philips N.V. |
| Medtronic Plc |
| Dragerwerk AG |
| Johnson & Johnson |
| Masimo Corporation |
| Others |
Value Network & Pricing Analysis
Cambridge and Oxford's medtech manufacturing corridors concentrate UK assembly capacity for connected monitoring devices, translating regional engineering density into pricing leverage for vendors serving NHS integrated care systems. This geographic clustering of biomedical R&D and production infrastructure directly shapes procurement negotiations, as proximity to Hatfield and Watford engineering hubs reduces service response times and supports premium positioning for algorithm-intensive cardiac platforms.
Pricing Analysis
Greater London commands 15-20% price premiums over Midlands and North England procurement for identical Bluetooth-enabled patch monitors, reflecting integrated care system budget concentration and faster virtual ward deployment timelines. Three-tier pricing structure across premium algorithm-intensive, standard multi-parameter, and economy spot-check tiers dominates the market, with differentiation driven by UKCA certification tier and after-sales clinical support bundling. Cost compression in the economy tier is intensifying because unbundled procurement contracts separate hardware from service obligations. Home care providers exhibit highest price sensitivity due to Social Care Technology Fund grant dependency, while acute trusts prioritize interoperability over unit cost.
Supply Chain Analysis
Analog front-end chips for biosignal acquisition draw from Taiwanese foundries, with UK device assemblers sourcing MEMS sensors from Germany and display modules from South Korea. Raw material dependencies center on semiconductor wafers, lithium-ion cells for wearable power, and medical-grade polymers for biocompatible housings. Single-source vulnerability in Taiwanese analog chip supply exposes UK manufacturers to lead-time volatility exceeding six months. Distribution runs through NHS Supply Chain central procurement for acute trusts, while domiciliary providers purchase via specialized medtech distributors with clinical integration support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom patient monitoring market sits in a cyclical recovery phase, with NHS England's hospital-at-home mandates driving capital reallocation toward remote infrastructure after pandemic-era emergency purchasing exhaustion.
For Market Incumbents: Pre-empt algorithm commoditization by securing predetermined change control plan approvals from the Medicines and Healthcare products Regulatory Agency, locking in regulatory pathways for iterative cardiac detection model updates without hardware re-certification. Deepen backward integration into edge-computing chip design to reduce Taiwanese foundry dependency, while expanding Watford and Hatfield engineering pipelines to capture unbundled procurement contracts across West Midlands and Greater Manchester integrated care systems. For New Entrants and Emerging Players: Scotland's National Digital Platform represents the most penetrable entry point for AI-augmented early warning algorithms, offering unified health record infrastructure absent England's fragmentation. Social Care Technology Fund grant channels for domiciliary care providers create a second white-space target, enabling consumer-grade device sales with clinical-grade backend integration. A direct-to-integrated-care-board sales model bypasses NHS Supply Chain central procurement barriers. For Investors and Strategic Acquirers: Long-term, this sits as a software-as-a-medical-device consolidation play because algorithm-updatable monitors with MHRA change control approvals command durable margin premiums over hardware-refresh competitors. Target acquisition profiles should emphasize vendors with live NHS Digital FHIR implementations and proven virtual ward deployment records. Monitor MHRA guidance evolution on real-world evidence frameworks as the signal for accelerated M&A activity.| Strategic Initiative | Industry Significance |
|---|---|
| MHRA Predetermined Change Control Plan Filing | Enables algorithm updates without UKCA re-certification, accelerating cardiac platform R&D cycles. |
| NHS Digital FHIR Integration Certification | Unlocks procurement eligibility across 42 integrated care boards with interoperability mandates. |
| Virtual Ward Infrastructure Partnership | Captures recurring revenue from NHS tariff structures reimbursing remote physiological surveillance. |
| Edge Computing Chip Design Acquisition | Reduces Taiwanese foundry dependency for analog front-end biosignal acquisition components. |
| Scotland National Digital Platform Pilot | Positions AI-augmented algorithms for scaling to England's fragmented integrated care system. |
Research Methodology
A standing panel of NHS integrated care board procurement directors, biomedical engineering leads at acute trusts, MHRA regulatory affairs specialists, and domiciliary care technology coordinators provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation against NHS Digital procurement databases, Care Quality Commission inspection reports, MHRA device registration filings, and integrated care board annual technology plans. Bottom-up unit demand modeling triangulated against top-down NHS capital expenditure forecasts.
Scenario-bracketing framed demand projections across the analysis window, with segmentation dimensions spanning device format, wireless protocol standard, care setting, and clinical indication. CAGRs derived from fitted growth curves applied to NHS tariff reimbursement trajectories and hospital-at-home admission targets, cross-referenced against semiconductor supply lead-time assumptions and UKCA certification pipeline capacity.
Macroeconomic conditions sit as an overlay; deviation in NHS capital allocation cycles or Taiwanese semiconductor export restrictions would shift the trajectory materially. Forecasts reflect documented assumptions about integrated care system consolidation pace and MHRA regulatory pathway evolution. Cross-checking against NHS England virtual ward admission actuals versus targets is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Wireless Patient Monitoring Market
Patient Monitoring
Multi-Parameter Patient Monitoring Market
Patient Monitoring
Respiratory Gas Monitors Market
Patient Monitoring
Global Home Blood Pressure Monitoring Devices Market
Patient Monitoring
ECG Monitoring System Market
Patient Monitoring
Global Anaesthesia Monitoring Devices Market
Patient Monitoring
Brain Monitoring Systems Market
Patient Monitoring
Middle East and Africa Body Temperature Monitoring Market
Patient Monitoring
Global Bed Monitoring System and Baby Monitoring System Market
Patient Monitoring
MRI Compatible Patient Monitoring Systems Market
Patient Monitoring
Monitoring Wristband Market
Patient Monitoring
Brain Tissue Oxygen Monitoring Systems Market
Patient Monitoring
Wearable Cardiac Monitors Market
Patient Monitoring
Healthcare Biosensors IoT Market
Patient Monitoring
Asia-Pacific Remote Patient Monitoring Systems Market
Patient Monitoring
Middle East and Africa Fetal and Neonatal Monitoring Market