

Copper Cabling Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Copper Cabling Systems Market Insights
Cat8 specification-tier certification is unwinding legacy Cat5e and Cat6 commitments across enterprise and colocation environments. CommScope leverages its structured cabling portfolio to anchor North American data center buildouts. Panduit sustains manufacturing scale across industrial automation channels where shielded twisted pair dominates. Belden competes through specialized coaxial and twinax assemblies serving broadcast and military interconnect applications.
Copper cabling systems encompass insulated conductor assemblies engineered to transmit electrical signals or power across twisted pair, coaxial, or flat conductor geometries, typically specified by impedance tolerance, attenuation per hundred meters, and flame-smoke ratings for plenum or riser deployment. These systems serve as the physical layer backbone for Ethernet networking, RF distribution, and control signaling in commercial and industrial facilities. Shielded twisted pair commands premium positioning in electromagnetic interference-heavy environments such as factory floors and medical imaging suites, while Cat6a maintains volume leadership in standard enterprise retrofits where cost-per-port governs procurement. Unshielded twisted pair retains margin compression in commodity residential and small-office installations where brand differentiation weakens.
The U.S. National Electrical Code, TIA-568 cabling standards, and EU CPR fire performance classifications collectively shape product certification requirements and market access conditions for copper cabling manufacturers. China's GB standards and MIIT telecommunications regulations impose additional electromagnetic compatibility and environmental testing protocols on imported cable assemblies. Stakeholders must monitor evolving PoE++ power delivery specifications and their thermal loading implications on conductor gauge selection and installation practices.
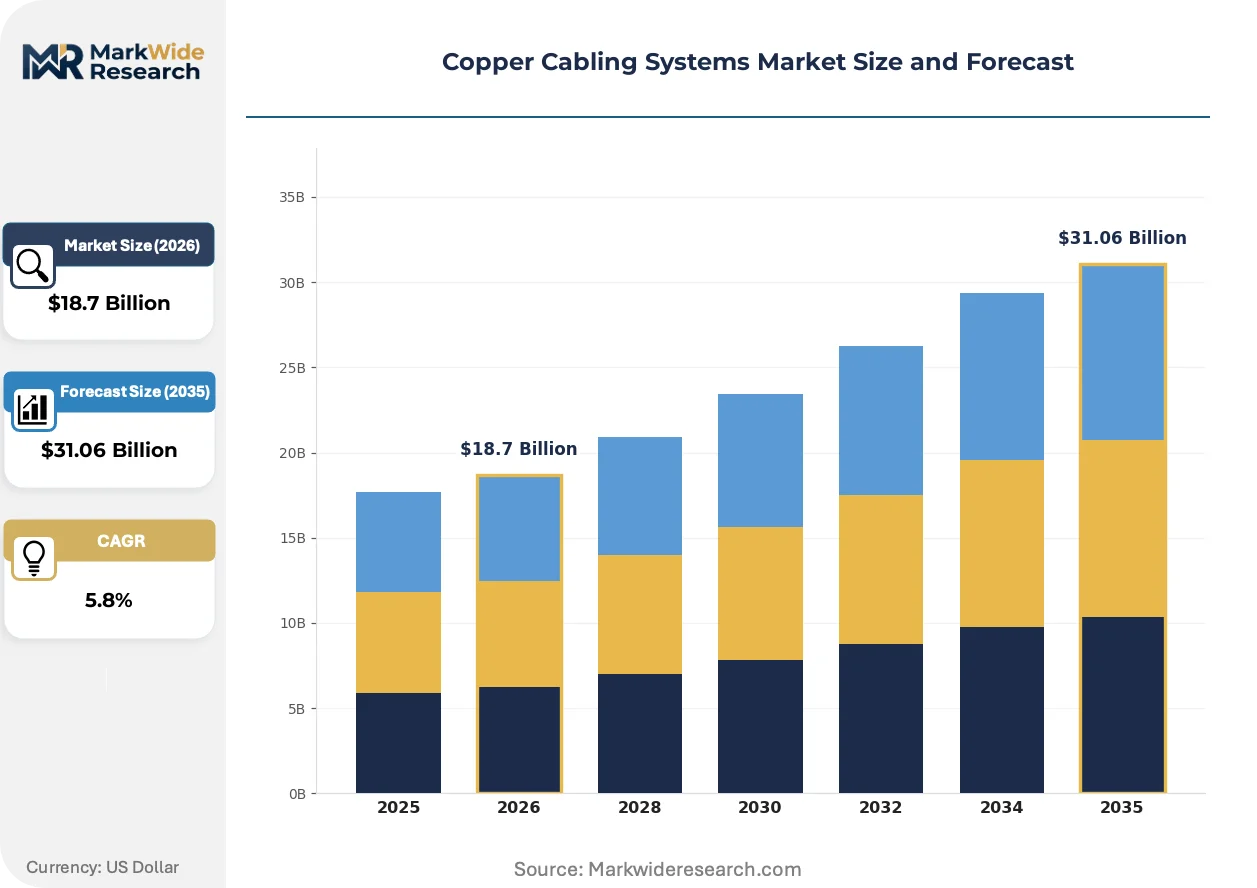
Market Dynamics
The transition from Cat6a to Cat8 certification tiers is compressing replacement cycles across enterprise data centers, as AI-driven rack densities force infrastructure managers to re-cable before standard depreciation schedules expire.
Growth Catalysts
- Hyperscale facility construction:China's MIIT telecommunications regulations are accelerating premium copper deployments in new cloud computing campuses across Beijing and Shanghai clusters.
- PoE++ thermal loading standards:The U.S. National Electrical Code's updated ampacity tables are mandating heavier conductor gauges for power-over-Ethernet installations in smart building retrofits.
- Industrial digitization mandates:Factory automation channels in Germany and Japan are pulling shielded twisted pair volumes for machine-to-machine interconnects.
Market Restraints
- Copper price volatility:LME copper futures fluctuations are compressing margin predictability for cable assemblers dependent on spot metal purchases.
- Fiber optic substitution:Single-mode fiber is capturing bandwidth-intensive runs above 10 Gbps in greenfield data center builds.
- REACH compliance costs:ECHA substance restrictions on halogenated flame retardants are forcing reformulation of plenum-rated jacket compounds.
Strategic Opportunities
- India's PLI scheme for electronics:Domestic manufacturing incentives are creating localized supply capacity for copper interconnects serving South Asian data center growth.
- Medical imaging suite upgrades:Electromagnetic compatibility requirements in diagnostic equipment are opening premium shielded cable volumes.
- EU Green Deal procurement rules:Public sector cabling tenders are embedding recycled copper content thresholds that favor circular-economy-certified suppliers.
Industry Challenges
- Certified installer scarcity:TIA-568 Cat8 field testing competence is concentrating among a limited pool of trained contractors, extending deployment timelines.
- Legacy infrastructure integration:Brownfield facilities face termination compatibility issues when patching 25-year-old Cat5e plant against new switch generations.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Copper Cabling Systems Market Trends and Innovations
Active optical cable encroachment and intelligent cable management systems are forcing copper manufacturers to defend physical-layer relevance through performance tiering and embedded diagnostics rather than commodity volume.
Cat8 twisted pair cabling is miniaturizing connector footprints while maintaining 2 GHz bandwidth tolerance. Hyperscale operators in Northern Virginia and Frankfurt are specifying these assemblies for top-of-rack switching at 25 Gbps and 40 Gbps speeds. The technology is miniaturizing data center aisle widths by reducing cable bulk density per rack unit.
EU CPR fire performance classifications are tightening smoke toxicity thresholds for copper cables deployed in enclosed transit and high-occupancy structures. Manufacturers serving the Netherlands and Denmark must now submit extended test data on halogen acid gas evolution. Medical and transportation verticals are absorbing the steepest certification cost increments.
Specification-driven procurement is consolidating vendor relationships around certified performance tiers rather than unit cost. Enterprise IT managers in Singapore and Sydney are pre-qualifying cable plants through third-party test house verification. This pattern is most pronounced in financial services and defense contracting channels where liability exposure governs sourcing decisions.
Copper Cabling Systems Market Segmentation
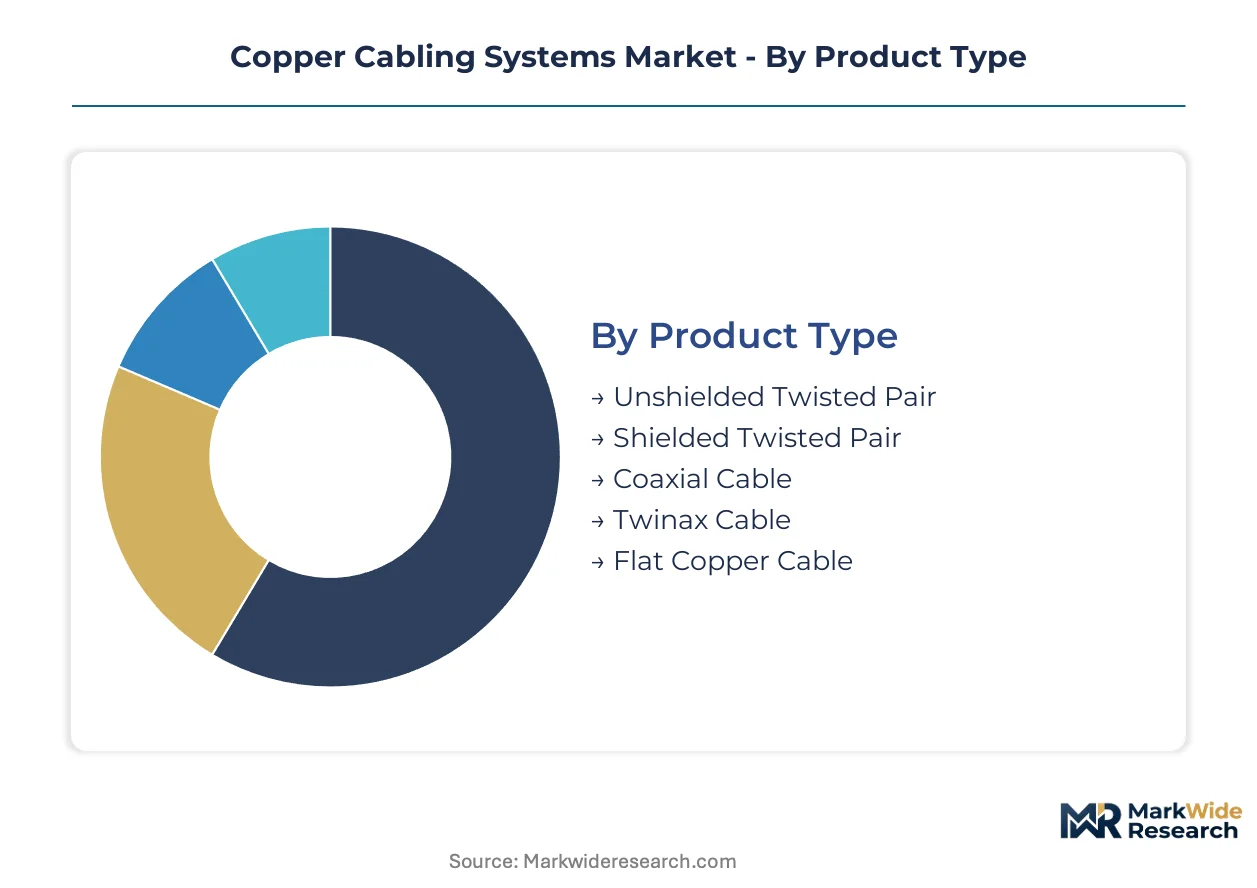
Copper cabling manufacturers must navigate divergent margin structures across product architectures, certification tiers, and deployment environments. Specification complexity and installation labor intensity create distinct profit pools that reward targeted portfolio positioning over undifferentiated volume plays.
Product Type:
Margin pools concentrate in electromagnetic interference-resistant architectures where certification barriers limit supplier entry.
- Shielded Twisted Pair:Foil or braided shielding surrounds conductor pairs to attenuate external noise. Factory automation floors in Germany and medical imaging suites in the United States absorb premium pricing for guaranteed signal integrity under IEC 61156-5 performance envelopes.
- Unshielded Twisted Pair:Balanced twisted conductor geometry without metallic shielding. Enterprise retrofits across Singapore and Sydney procurement offices favor this architecture where cost-per-port governs large-scale switch-to-desk deployments.
- Coaxial Cable:Central conductor with dielectric spacer and cylindrical shield serves RF distribution and legacy video backbones.
- Twinax Cable:Two insulated conductors within a single shield enable balanced differential signaling for high-speed interconnects.
- Flat Copper Cable:Parallel conductors laminated in planar geometry suit confined-space ribbon applications and under-carpet installations.
Shielded twisted pair holds installed capacity. Unshielded twisted pair is rotating up the share rankings.
Technology:
Certification tier selection directly determines replacement cycle timing and depreciation recovery rates for infrastructure managers.
- Cat8:Four-pair shielded construction supporting 2 GHz bandwidth and 25-40 Gbps speeds over 30-meter channels. Hyperscale operators in Northern Virginia and Frankfurt clusters specify these assemblies for top-of-rack switching where rack density compression justifies premium expenditure.
- Cat6a:Augmented Category 6 delivers 10 Gbps to 100 meters with stricter alien crosstalk limits. Standard enterprise refresh programs across commercial office towers in London and Toronto treat this as the default upgrade path from legacy Cat5e plant.
- Cat5:Legacy 100 MHz bandwidth specification persists in residential and cost-constrained small-office environments.
- Cat6:250 MHz bandwidth tier captures mid-market installations where 10 Gbps is not yet required.
- Cat7:Fully shielded S/FTP construction with individual pair shielding serves specialized industrial and broadcast applications.
Cat6a holds installed capacity. Cat8 is rotating up the share rankings.
Application:
Demand concentration varies sharply by vertical capital expenditure cycles and regulatory compliance intensity.
- Data Centers:Structured cabling backbones interconnecting compute, storage, and network elements. AI-driven rack density expansion in Beijing and Shanghai cloud campuses is pulling premium copper volumes ahead of standard depreciation schedules.
- Industrial Automation:Machine-to-machine interconnects on factory floors. Shielded twisted pair dominates where variable frequency drives and welding equipment generate electromagnetic noise requiring TIA-1005-A compliance.
- Telecommunications:Central office and outside plant copper infrastructure for voice and DSL services.
- Security Systems:Power-over-Ethernet delivery to IP cameras and access control endpoints.
- Building Automation:HVAC, lighting, and sensor networks in smart building retrofits.
Telecommunications holds installed capacity. Data centers are rotating up the share rankings.
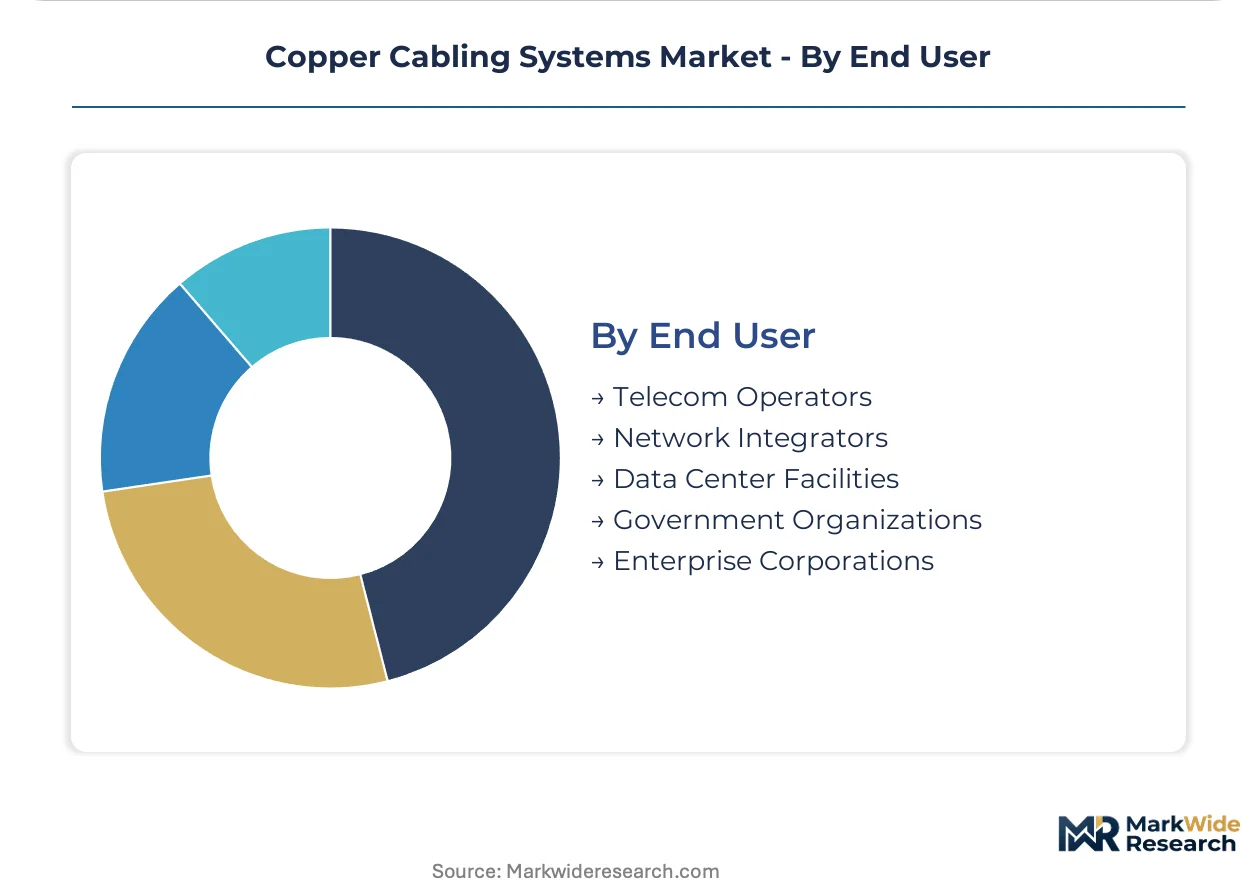
End User:
Procurement sophistication and liability exposure create divergent vendor qualification requirements across buyer categories.
- Data Center Facilities:Hyperscale and colocation operators with internal engineering teams. Third-party test house verification of cable plants is standard practice before volume commitment in Singapore and Sydney financial services corridors.
- Enterprise Corporations:IT infrastructure managers in commercial and industrial organizations. Specification-driven procurement is consolidating vendor relationships around certified performance tiers rather than unit cost in defense contracting channels.
- Telecom Operators:Incumbent carriers and competitive local exchange carriers maintaining copper access networks.
- Network Integrators:Systems contractors and value-added resellers serving mid-market installations.
- Government Organizations:Public sector entities with embedded sustainability and domestic content requirements under EU Green Deal procurement rules.
Telecom operators hold installed capacity. Data center facilities are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale data center operators in China absorb premium copper cabling without price sensitivity, while European industrial buyers negotiate aggressively on shielded twisted pair volumes for factory automation retrofits.
United States
AI-driven rack density expansion in Northern Virginia data center clusters is pulling Cat8 certification volumes ahead of standard depreciation schedules. The National Electrical Code's updated ampacity tables for PoE++ installations now mandate heavier conductor gauges in smart building retrofits. Dallas-Fort Worth colocation facilities are consolidating vendor relationships around third-party test house verification protocols.
China
MIIT telecommunications regulations are accelerating premium copper deployments in Beijing and Shanghai cloud computing campuses. GB standards and electromagnetic compatibility testing protocols impose additional certification burdens on imported cable assemblies. Yangtze River Delta hyperscale construction is absorbing shielded twisted pair volumes for machine-to-machine interconnects at unprecedented scale.
Germany
Factory automation channels are pulling shielded twisted pair volumes for variable frequency drive environments requiring TIA-1005-A compliance. ECHA REACH substance restrictions on halogenated flame retardants are forcing reformulation of plenum-rated jacket compounds. Bavarian automotive manufacturing clusters are specifying electromagnetic interference-resistant architectures for welding equipment interconnects.
India
PLI scheme electronics manufacturing incentives are creating localized supply capacity for copper interconnects serving South Asian data center growth. BIS certification requirements and domestic content rules are reshaping procurement patterns for government and enterprise tenders. Maharashtra's Mumbai-Pune corridor is emerging as the primary concentration for structured cabling distribution to financial services corridors.
Japan
METI industrial digitization mandates are accelerating shielded twisted pair deployments for precision manufacturing environments. JIS standards for electromagnetic compatibility are tightening certification requirements for medical imaging suite upgrades. Osaka-Kansai manufacturing clusters are absorbing premium cable volumes for diagnostic equipment interconnects requiring guaranteed signal integrity.
Copper Cabling Systems Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the copper cabling systems market. The vendor base organizes into three strategic tiers: specification-certified premium suppliers serving hyperscale data centers, scale-driven manufacturers capturing enterprise retrofit volumes, and regional specialists defending niche electromagnetic interference applications. Consolidation pressures are intensifying as certification complexity concentrates procurement relationships around fewer qualified suppliers. Two dominant competitive moves are reshaping positioning: backward integration into copper conductor drawing operations to hedge LME price volatility, and strategic partnerships with third-party test houses to accelerate Cat8 field certification timelines.
Among North American infrastructure suppliers, CommScope and Belden occupy distinct archetype positions. CommScope exemplifies the specification-certified tier through its structured cabling portfolio anchoring data center buildouts. Belden represents specialized interconnect expertise serving broadcast and military applications where coaxial and twinax assemblies dominate. Panduit sits within the scale-driven manufacturing archetype, sustaining production volumes across industrial automation channels where shielded twisted pair commands premium positioning.
| Leading Market Players |
|---|
| CommScope |
| Panduit |
| Legrand |
| Belden |
| Corning |
| Rosenberger |
| Molex |
| FS.com |
| Furukawa Electric |
| Others |
Pricing and Supply Chain Analysis
Ninety-day copper conductor inventory positions at major cable assemblers now determine pricing power across certification tiers, with LME spot exposure compressing margins on unshielded twisted pair while Cat8 shielded assemblies retain premium resilience through specification lock-in.
Pricing Analysis
Extended field-certification service contracts now anchor lifetime value for hyperscale data center operators negotiating structured cabling deployments. Three-tier pricing structure across premium Cat8, standard Cat6a, and economy Cat5e levels stratifies procurement pools, with TIA-568 certification tier and third-party test house verification serving as the primary price differentiation drivers. Cost compression in commodity unshielded twisted pair is intensifying because residential and small-office buyers absorb spot copper volatility directly. Enterprise retrofit channels exhibit highest price sensitivity, while hyperscale facilities in Northern Virginia and Frankfurt clusters demonstrate minimal elasticity for guaranteed 25-40 Gbps performance.
Supply Chain Analysis
Strategic stockpiling of refined copper cathode dominates inventory strategy among tier-one manufacturers hedging against LME futures volatility, while just-in-time jacket compound sourcing persists for standardized assemblies. Manufacturing gravity centers on China, Germany, and the United States, with Yangtze River Delta clusters feeding Asian hyperscale demand and Bavarian automotive corridors absorbing shielded twisted pair volumes. Raw material dependencies rest on Chilean and Peruvian copper concentrate, South Korean fluoropolymer compounds for plenum-rated jackets, and domestic PVC resin supplies. Single-source vulnerability concentrates in halogenated flame retardant formulations facing ECHA REACH restrictions. Distribution runs through authorized distributor networks and direct OEM contracts to data center integrators and industrial automation channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified Cat8 field-testing competence now constrains deployment velocity, with TIA-568 qualified installer pools limiting expansion capacity for infrastructure managers across hyperscale and enterprise channels.
For Market Incumbents: Compound certification barriers by embedding diagnostic capabilities into cable assemblies and securing exclusive third-party test house partnerships that accelerate field verification timelines. Backward integration into copper conductor drawing operations hedges LME price volatility exposure. Capacity addition in India's PLI-subsidized manufacturing corridors captures South Asian data center growth before localized supply matures. For New Entrants and Emerging Players: Differentiate on electromagnetic interference-resistant architectures for medical imaging suite upgrades where JIS and IEC 61156-5 compliance requirements limit incumbent responsiveness. India's emerging structured cabling distribution infrastructure represents the most penetrable geography, with Mumbai-Pune corridor financial services demand outpacing certified supply. Pursue white-label manufacturing partnerships with established test houses to bypass field-certification capability gaps. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because certification complexity concentrates procurement relationships around fewer qualified suppliers while AI-driven rack density forces premature replacement cycles. Target mid-cap specialists with captive Cat8 testing infrastructure and established hyperscale operator relationships. Watch PoE++ thermal loading standards evolution as the signal for conductor gauge specification shifts that would trigger inventory obsolescence cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Drawing | Captive cathode supply insulates margin predictability against LME futures volatility for tier-one assemblers. |
| Cat8 Field Certification Partnership | Exclusive test house relationships compress deployment timelines for hyperscale operators in Northern Virginia clusters. |
| PLI Scheme Manufacturing Localization | Domestic Indian capacity captures South Asian data center growth under BIS certification and content rules. |
| Halogen-Free Jacket Reformulation | ECHA REACH compliance on flame retardants opens premium positioning for circular-economy-certified suppliers in EU tenders. |
| Embedded Diagnostic Cable Development | Intelligent management systems defend physical-layer relevance against active optical cable encroachment in top-of-rack switching. |
Research Methodology
Desk research of TIA-568 standards documentation, ECHA REACH substance restriction filings, and hyperscaler capex disclosure preceded structured interviews with data center infrastructure managers, certified cabling contractors, and procurement leads at colocation operators. Primary fieldwork with industrial automation engineers and medical imaging suite facilities directors validated secondary findings on electromagnetic interference requirements. Customs records for copper cathode and fluoropolymer compound trade flows, alongside SEC 10-K filings from structured cabling manufacturers, provided supply chain triangulation. Bottom-up unit economics across certification tiers reconciled with top-down market sizing from national electrical code adoption patterns.
Variance decomposition across product architecture, certification tier, and deployment environment shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include shielding architecture, bandwidth specification, end-use vertical, and regional regulatory cluster. CAGRs derived from replacement cycle compression analysis and hyperscale facility construction pipelines. Industry-specific forecast inputs incorporated PoE++ thermal loading ampacity table revisions and MIIT telecommunications regulation enforcement timelines.
The analysis sits within stated boundaries; outcomes outside sustained AI rack density expansion or ECHA substance restriction acceleration would require recalibration. Forecasts reflect assumptions on certified installer training pipeline capacity and copper price volatility bands. Revision becomes warranted when fiber optic substitution rates in greenfield data center builds cross thresholds that would strand copper infrastructure investments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.