
 Cable Racks Market | 2026-2036
Cable Racks Market Size, Share, and Industry Trends Forecast 2026-2036
Cable Racks Market Outlook
India is tilting toward expanded cable rack manufacturing as industrial infrastructure investments accelerate across Gujarat and Tamil Nadu. Atkore Inc. leverages vertical integration in steel conduit and cable management to sustain margin control across North American distribution channels. Legrand anchors European market presence through deep specialization in structured cabling enclosures and power distribution accessories. Eaton competes on industrial-grade rack systems designed for harsh-environment applications in energy and utility sectors.
Cable racks are structural support frameworks, typically fabricated from cold-rolled steel or extruded aluminum with powder-coated or galvanized finishes, engineered to organize, route, and protect electrical and data cables in commercial and industrial facilities. Their primary purpose is to prevent cable damage, enable thermal management, and facilitate maintenance access in complex installations. Steel racks dominate commercial construction due to load-bearing capacity and fire resistance, while aluminum variants are gaining share in weight-sensitive applications such as aerospace maintenance facilities and offshore platforms. Data center end users represent the fastest-expanding demand pool, driven by hyperscale facility construction and fiber density requirements that exceed legacy tray capacities.
OSHA workplace safety standards in the United States mandate load-rated cable support systems in industrial environments, while the EU's CE marking and RoHS frameworks restrict hazardous substances in metal coatings and plastics used for European-market products. India's BIS certification requirements for electrical installation components create compliance thresholds that filter import competition and elevate domestic manufacturing quality benchmarks. Stakeholders must monitor evolving fire-resistance testing protocols and material traceability mandates as procurement specifications tighten across regulated end-use sectors.
Market Dynamics
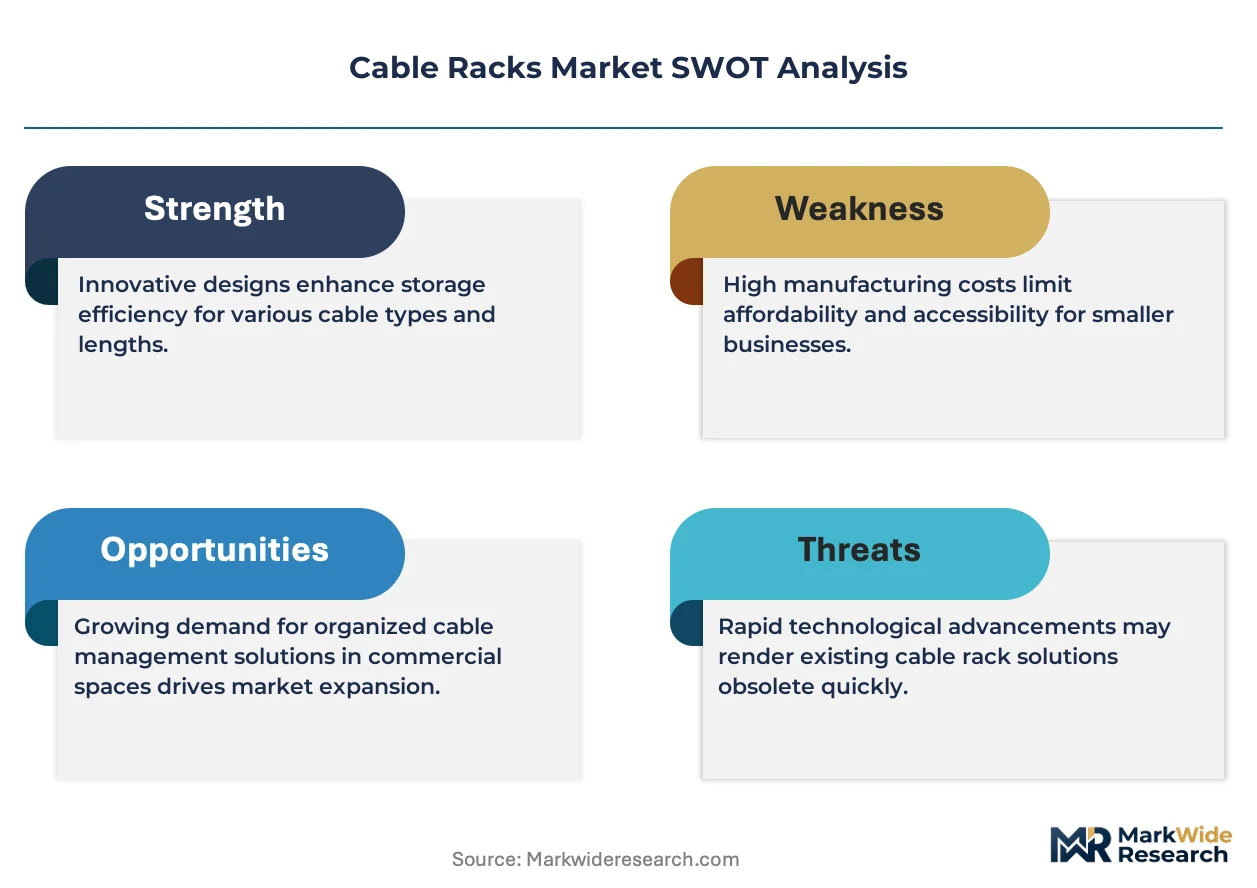
Data center densification is compressing cable rack specifications as hyperscale operators demand load-bearing capacity that exceeds legacy tray architectures while maintaining airflow optimization in confined rack elevations.
Growth Catalysts
- Hyperscale Data Center Construction:Fiber density requirements in cloud computing facilities are pulling heavy-duty ladder rack and channel cable tray specifications beyond traditional commercial-grade capacities.
- India's PLI Scheme for Electronics Manufacturing:Production-linked incentives for semiconductor and component assembly are accelerating industrial facility builds across Gujarat and Tamil Nadu, expanding cable management infrastructure procurement.
- EU RoHS Directive Compliance:Hazardous substance restrictions in metal coatings and plastics are filtering supplier bases toward certified manufacturers with material traceability systems.
Market Restraints
- Steel Price Volatility:Cold-rolled steel input costs fluctuate with energy-intensive smelting operations, compressing margin predictability for powder-coated rack fabricators.
- Supply Concentration in Chinese Extrusion:Aluminum profile sourcing clusters in Zhejiang and Guangdong provinces create geographic dependency risk for lightweight rack variants.
- Fire-Resistance Testing Protocol Gaps:Inconsistent UL 2196 and IEC 60331 certification reciprocity between jurisdictions extends product validation timelines.
Strategic Opportunities
- Modular Pre-Configured Rack Systems:Plug-and-play cable management assemblies reduce on-site installation labor for data center contractors facing skilled electrician shortages.
- Offshore Platform Weight Reduction Mandates:Aluminum alloy rack variants capture share in North Sea and Gulf of Mexico energy installations where deck load limits tighten.
- India BIS Certification Barriers:Domestic quality benchmarks for electrical installation components filter import competition and elevate local manufacturing scale advantages.
Industry Challenges
- Welding Technician Scarcity:Certified aluminum TIG welders for aerospace-grade rack fabrication command premium wages that inflate production costs.
- Legacy Tray Retrofit Complexity:Integrating high-capacity ladder racks into existing commercial buildings requires structural reinforcement that extends project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cable Racks Market |
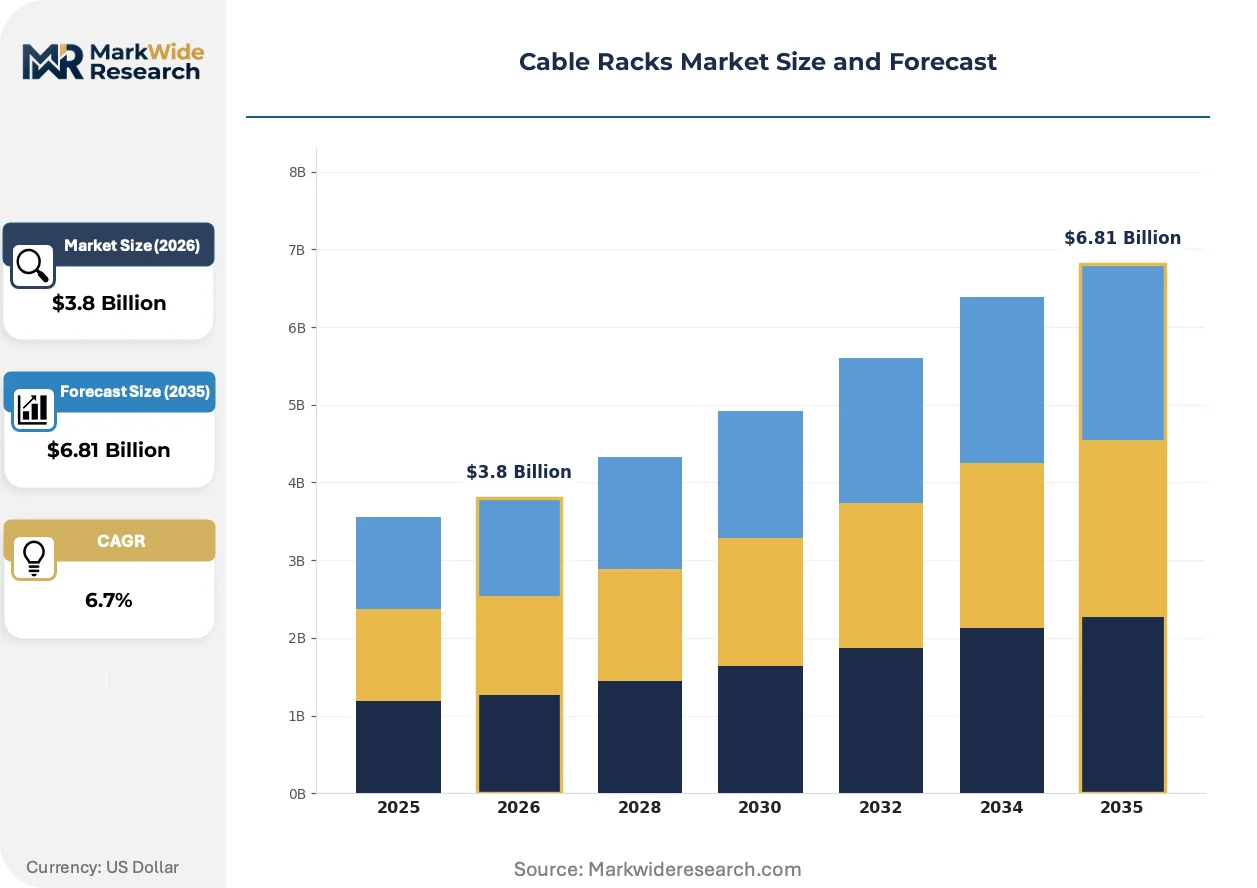
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Racks, Aluminum Racks, Plastic Racks, Wood Racks End User: Telecommunications, Data Centers, Industrial, Residential Installation Type: Floor-mounted, Wall-mounted, Ceiling-mounted, Rack-mounted Distribution Channel: Online Retail, Direct Sales, Wholesale, Specialty Stores |
| Companies Covered | Atkore Inc., Legrand, ABB Ltd., Eaton, Niedax Group, OBO Bettermann, Hubbell Inc., Basor Electric S.A., Chatsworth Products, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cable Racks Market Strategic Shifts
Material science advances and regulatory tightening are compressing traditional cable rack design cycles while elevating performance specifications across commercial and industrial end uses.
Composite-reinforced polymer cable trays are collapsing the weight differential between steel and legacy aluminum architectures. Offshore oil platform operators in the North Sea are specifying glass-fiber reinforced nylon channel systems to meet strict deck load limits without sacrificing corrosion resistance. This material shift is collapsing the historical premium pricing gap between marine-grade aluminum and commodity steel alternatives.
China's GB standards for electrical installation products are mandating enhanced fire-resistance ratings for cable support systems in high-rise commercial buildings. MIIT enforcement of these protocols is filtering non-compliant imports and elevating domestic manufacturer quality benchmarks. Data center construction in Shanghai and Shenzhen is accelerating specification upgrades to meet these tightened material performance thresholds.
Buyers are consolidating vendor relationships around full-suite cable management providers capable of delivering integrated ladder rack, conduit, and grounding systems under single-source contracts. Electrical contractors on large-scale industrial projects are shifting away from fragmented procurement of discrete components. This consolidation pattern is most visible in US commercial construction where general contractors face liability exposure from multi-vendor installation coordination failures.
Cable Racks Market Segmentation
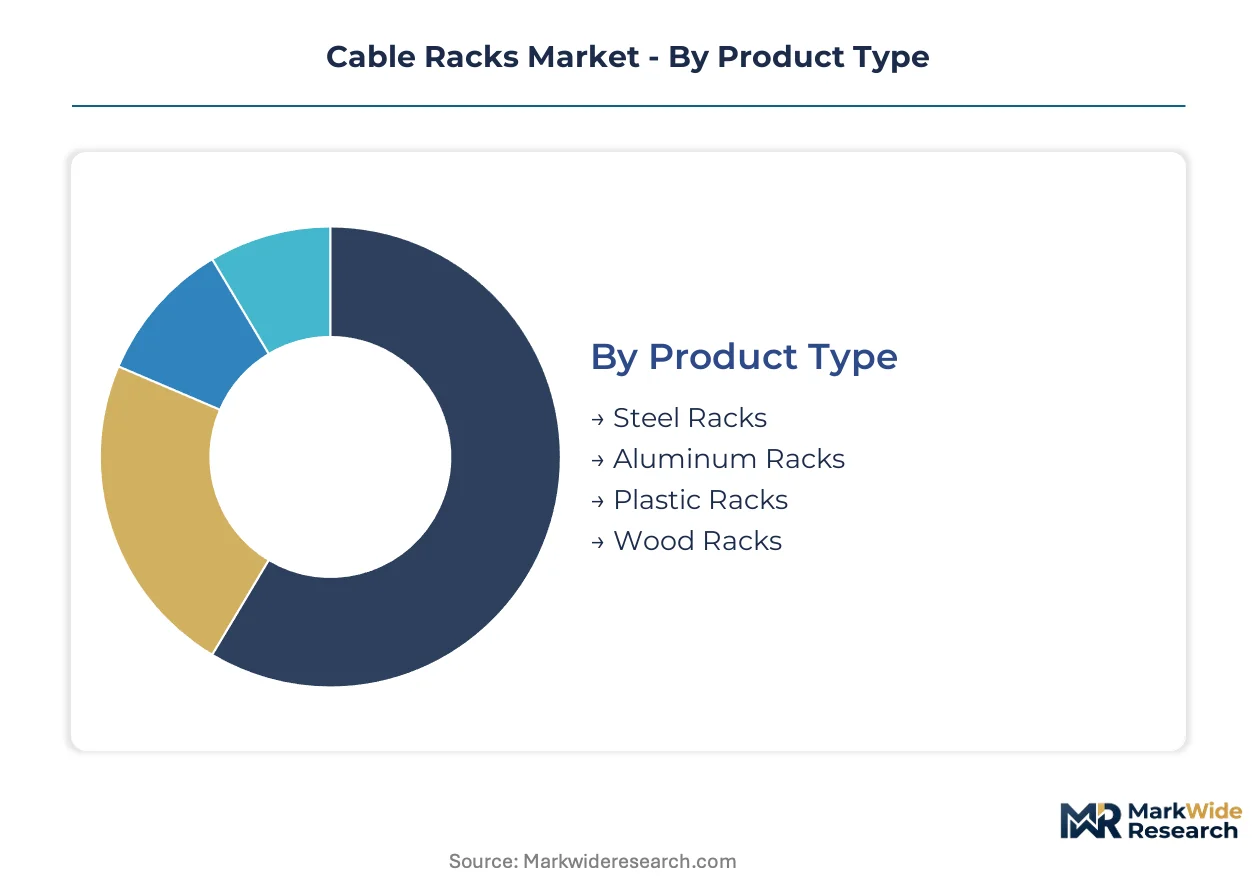
Cable rack specifications diverge sharply across deployment environments, from fire-rated steel assemblies in commercial high-rises to corrosion-resistant aluminum extrusions on offshore platforms. Understanding these segment boundaries enables procurement alignment with load-bearing requirements, thermal management protocols, and installation labor constraints.
Product Type:
Use-case spectrum spans heavy-load industrial infrastructure to weight-sensitive aerospace maintenance bays.
- Steel Racks:Cold-rolled steel with powder-coated or galvanized finishes delivers maximum load-bearing capacity and fire resistance. Demand concentrates in North American commercial construction and Indian industrial corridors where BIS certification mandates structural integrity documentation.
- Aluminum Racks:Extruded aluminum alloys reduce weight by 60-70% versus steel equivalents while maintaining corrosion resistance. Offshore platform operators in the North Sea and Gulf of Mexico specify these variants as deck load limits tighten and maintenance access requirements intensify.
- Plastic Racks:Glass-fiber reinforced polymer systems collapse the weight differential between steel and aluminum architectures. Marine-grade specifications in Norwegian and UK North Sea installations drive specification upgrades.
- Wood Racks:Treated hardwood assemblies serve temporary construction site applications and heritage building retrofits where metallic finishes conflict with aesthetic requirements. Scandinavian commercial restoration projects sustain niche procurement volumes.
Established volume favors steel racks; emerging adoption favors aluminum racks.
End User:
Customer concentration patterns reflect capital cycle timing across infrastructure verticals.
- Data Centers:Hyperscale operators demand ladder rack and channel tray specifications exceeding legacy commercial capacities as fiber density requirements multiply. Shanghai and Shenzhen construction pipelines accelerate specification upgrades to meet China's GB fire-resistance mandates.
- Telecommunications:5G backbone expansion and central office modernization sustain procurement of wall-mounted and rack-mounted assemblies. India's PLI scheme for electronics manufacturing accelerates facility builds across Gujarat and Tamil Nadu.
- Industrial:Manufacturing plants and energy utilities specify OSHA-compliant load-rated systems for heavy-cable environments. US Gulf Coast petrochemical complexes drive demand for corrosion-resistant finishes.
- Residential:Smart home infrastructure and distributed energy storage installations expand lightweight rack adoption in multi-unit construction. German and French residential electrification retrofits sustain moderate growth.
Data centers represent the steepest expansion trajectory; industrial maintains the largest installed base.
Installation Type:
Mounting configuration determines structural engineering requirements and labor skill thresholds.
- Floor-mounted:Freestanding ladder rack systems support heavy cable bundles in data center white spaces and industrial process areas. UAE and Saudi logistics hub construction sustains regional procurement concentration.
- Wall-mounted:Bracket-supported channel trays organize horizontal cable runs in commercial corridors and telecommunications closets. European commercial renovation projects favor these for space-constrained retrofits.
- Ceiling-mounted:Suspended assemblies maximize floor space utilization in cleanroom environments and retail facilities. Japanese pharmaceutical manufacturing expansion drives specification demand.
- Rack-mounted:Integrated cabinet systems consolidate server, power, and cable management in standardized elevations. South Korean cloud facility construction accelerates adoption of pre-configured modular assemblies.
Floor-mounted dominates capital-intensive greenfield projects; rack-mounted gains share in modular data center deployments.
Distribution Channel:
Channel selection reflects project scale, specification complexity, and contractor procurement autonomy.
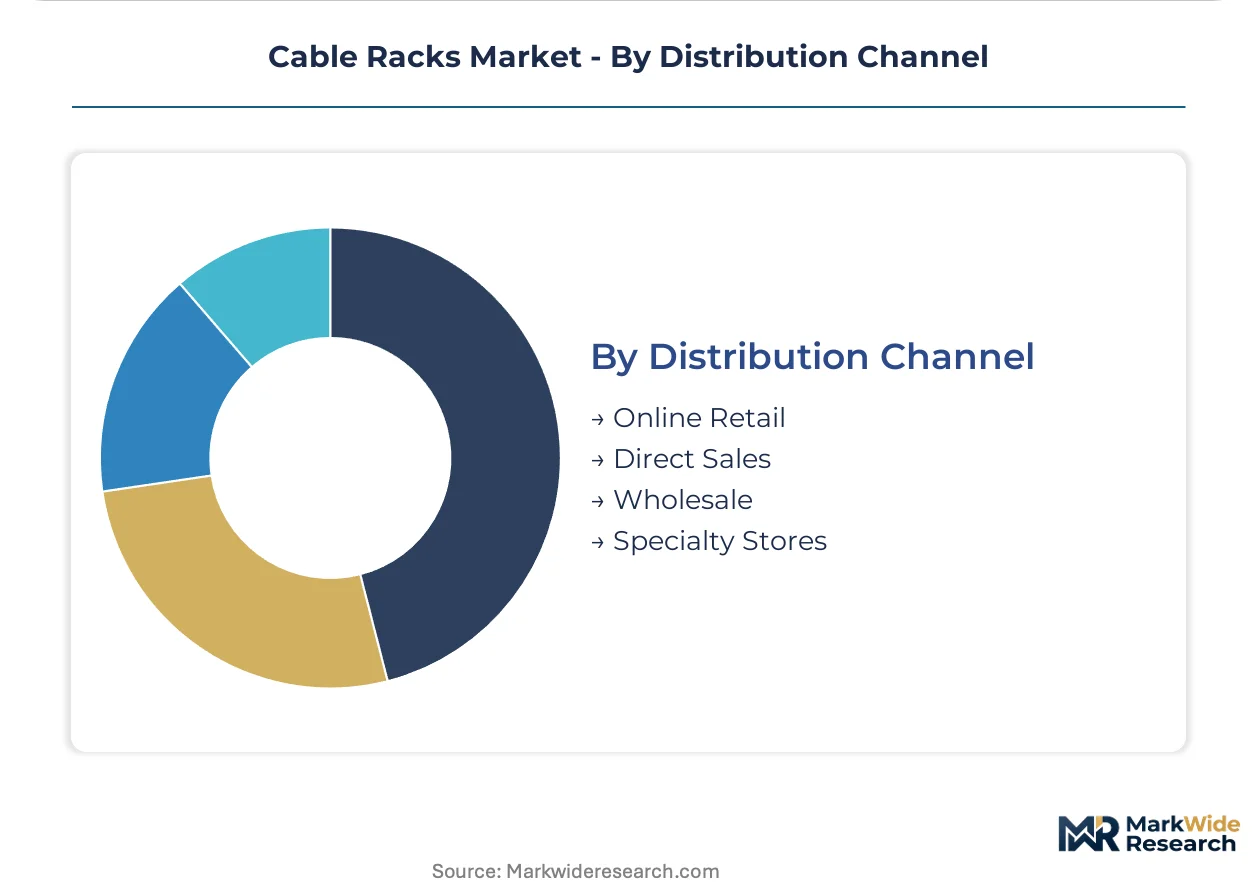
- Direct Sales:Manufacturer-direct relationships serve hyperscale data center operators and national electrical contractors requiring custom engineering support. US general contractors consolidate vendor relationships around integrated full-suite providers.
- Wholesale:Electrical distributors stock standard ladder rack and channel tray dimensions for commercial construction spot buying. Indian industrial corridor development sustains regional wholesale hub expansion.
- Online Retail:E-commerce platforms capture small-project and maintenance procurement for standardized dimensions. Australian and Canadian remote site operators leverage digital channels where distributor coverage thins.
- Specialty Stores:Local electrical supply houses provide same-day availability for emergency repairs and small commercial jobs. Italian and Spanish contractor networks sustain this channel's relevance.
Direct sales capture the largest project values; online retail expands fastest in fragmented maintenance markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA workplace safety standards anchor demand concentration in the United States, where load-rated cable support systems dominate industrial procurement. Regional markets diverge sharply based on regulatory stringency, material certification requirements, and infrastructure investment cycles.
United States
Hyperscale data center construction across Northern Virginia and Dallas-Fort Worth drives heavy-duty ladder rack specifications beyond legacy commercial capacities. OSHA mandates load-rated systems in petrochemical facilities along the Gulf Coast, where corrosion-resistant finishes command premium procurement. Houston and Bay Area industrial clusters sustain concentrated demand from energy sector infrastructure upgrades.
Germany
Industrial automation expansion in Baden-Württemberg and Bavaria pulls structured cabling infrastructure for smart manufacturing facilities. REACH and RoHS frameworks restrict hazardous substances in metal coatings, filtering supplier bases toward certified manufacturers. Stuttgart and Munich automotive engineering centers specify fire-rated assemblies for production facility electrification retrofits.
China
MIIT enforcement of GB fire-resistance standards accelerates specification upgrades in Shanghai and Shenzhen data center construction pipelines. Dual carbon goals compress energy intensity targets for cable management infrastructure in high-rise commercial buildings. Yangtze River Delta manufacturing clusters drive domestic production scale for aluminum extrusion and powder-coated steel assemblies.
India
PLI scheme incentives for electronics manufacturing accelerate industrial facility builds across Gujarat and Tamil Nadu, expanding cable rack procurement volumes. BIS certification requirements for electrical installation components filter import competition and elevate domestic manufacturing quality benchmarks. Ahmedabad and Chennai industrial corridors concentrate demand from semiconductor assembly and component fabrication plants.
United Arab Emirates
Logistics hub construction in Dubai and Abu Dhabi sustains floor-mounted ladder rack procurement for warehouse automation and data center white spaces. MOHAP building safety codes mandate fire-resistant cable support systems in high-rise commercial developments. Jebel Ali industrial zone clusters demand corrosion-resistant aluminum variants for coastal humidity exposure.
Cable Racks Market Competitive Environment
Vertically integrated steel processors and specialized cable management architects split the market into distinct capability tiers. The vendor base concentrates around full-suite providers capable of delivering integrated ladder rack, conduit, and grounding systems under single-source contracts. Three archetypes dominate: steel-centric conglomerates with captive raw material supply, aluminum specialists serving weight-sensitive applications, and modular system integrators targeting data center contractors. Competitive moves center on backward integration into steel conduit production and geographic expansion through distributor network consolidation.
Among North American fabricators, Atkore Inc. exemplifies the vertically integrated archetype through upstream control over steel conduit supply chains. Legrand occupies a position within the European specialist tier, anchoring structured cabling enclosure capabilities. Eaton represents the industrial-grade systems archetype, with positioning calibrated toward harsh-environment energy and utility applications. These three anchors illustrate how strategic differentiation around material control, regional specialization, and end-use focus shapes competitive boundaries.
| Leading Market Players |
|---|
| Atkore Inc. |
| Legrand |
| ABB Ltd. |
| Eaton |
| Niedax Group |
| OBO Bettermann |
| Hubbell Inc. |
| Basor Electric S.A. |
| Chatsworth Products, Inc. |
| Others |
Value Chain & Pricing Dynamics
Zhejiang and Guangdong aluminum extrusion clusters concentrate upstream capacity for lightweight rack variants, compressing margin buffers for fabricators lacking captive supply or long-term offtake agreements. Cold-rolled steel procurement from Yangtze River Delta mills anchors cost structures for powder-coated assemblies serving North American commercial construction, while energy-intensive smelting operations transmit volatility into input pricing.
Pricing Analysis
North American ladder rack quotations run 15-25% above Southeast Asian spot equivalents before freight and duty, reflecting OSHA load-rating certification premiums and domestic fabrication labor costs. Three-tier pricing structure across premium certified, standard commercial, and economy-grade levels separates UL 2196 fire-rated assemblies from uncertified imports. Pricing pressure stems from steel price volatility transmitted through energy-intensive smelting operations. Data center contractors show lowest price sensitivity due to specification lock-in, while small commercial renovators drive spot-market discounting.
Supply Chain Analysis
Export-control regimes on advanced aluminum alloys and specialty steel grades limit material flows to certain defense-adjacent applications, though standard construction-grade inputs remain unrestricted. Manufacturing concentrates in China, India, and the United States for finished assemblies, with cold-rolled steel and aluminum extrusion as primary inputs. Single-source vulnerability clusters in Zhejiang extrusion capacity for aerospace-grade alloys. Distribution runs through electrical wholesalers for commercial spot buying and direct manufacturer relationships for hyperscale data center projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cable rack infrastructure sits in early-cycle expansion as hyperscale data center construction accelerates specification upgrades beyond legacy commercial capacities, with India's PLI scheme adding incremental facility build demand.
For Market Incumbents: Pre-empt margin compression from steel price volatility by securing captive supply through backward integration into cold-rolled steel processing or long-term offtake agreements with Yangtze River Delta mills. Accelerate BIS certification investment to filter import competition in India's expanding industrial corridors. For New Entrants and Emerging Players: Establish a beachhead in glass-fiber reinforced polymer channel systems for North Sea offshore platforms, where deck load mandates displace legacy aluminum architectures. Target modular pre-configured rack assemblies for data center contractors facing skilled electrician shortages, leveraging plug-and-play installation labor savings as the primary go-to-market angle. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among full-suite cable management providers capable of delivering integrated ladder rack, conduit, and grounding systems under multi-year facility maintenance contracts. Long-term viability favors vertically integrated steel processors with upstream conduit control. Watch hyperscale data center capex announcements as the primary demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Conduit | Captive raw material supply insulates margin from Yangtze River Delta price volatility. |
| BIS Certification Investment | Quality benchmarks filter import competition in Gujarat and Tamil Nadu industrial corridors. |
| Modular Pre-Configured Systems Launch | Plug-and-play assemblies reduce on-site labor for contractors facing certified welder scarcity. |
| Aluminum Alloy R&D Partnership | Lightweight variants capture share in North Sea and Gulf of Mexico offshore installations. |
| Distributor Network Consolidation | Channel control secures preference from US general contractors consolidating vendor relationships. |
Study Parameters
Desk research of trade association publications, customs import records, and regulatory filings preceded structured interviews with data center construction managers, electrical contractor procurement leads, cable rack manufacturing executives, and BIS certification auditors. Primary fieldwork captured specification evolution, installation labor constraints, and channel purchasing patterns. Secondary validation drew from MIIT enforcement bulletins, OSHA technical standards, and EU RoHS compliance databases. Bottom-up facility build counts triangulated against top-down infrastructure investment forecasts.
Assumptions held fixed include continued enforcement of China's GB fire-resistance standards, sustained PLI scheme funding for Indian electronics manufacturing, and stable OSHA load-rating mandates across the analysis window. Segmentation modeling incorporated product type, end user vertical, installation configuration, and geographic regulatory cluster. CAGRs derived from facility build pipelines, content-per-rack estimates, and replacement cycle analysis. Hyperscale data center capex trajectories and aluminum alloy availability served as industry-specific demand and supply inputs.
Sensitivities concentrate around steel price volatility, BIS certification timeline extensions, and fire-resistance testing protocol reciprocity gaps between UL and IEC frameworks. Forecasts reflect documented assumptions on infrastructure investment continuity. Material shifts in China's dual carbon policy enforcement or India's PLI scheme scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Coaxial Cable Market
Cables
Cable Material Market
Cables
Latin America Wire and Cable Market
Cables
North America Wire and Cable Market
Cables
Global Cable Tie Market
Cables
Copper Cabling Systems Market
Cables
Power and Control Cable Market
Cables
Cable Clamp Market
Cables
Premise Cable Market
Cables
US Medium Voltage Cable Accessories Market
Cables
Europe HVAC Cables Market
Cables
SATA Power Cable Market
Cables
Aluminium Battery Cable Market
Cables
Submarine Communication Cables Market
Cables
India Wire and Cable Market
Cables
Asia Pacific MV and HV Underground Cables and Accessories Market