
 Multi-Cloud SDN Market | 2026-2036
Multi-Cloud SDN Market Size, Share, and Industry Trends Forecast 2026-2036
Multi-Cloud SDN Market Foresight
Hyperscaler infrastructure buildouts in Northern Virginia and Frankfurt is realigning capacity planning across the multi-cloud SDN supply base. Cisco Systems leverages its installed base of enterprise routers to extend policy orchestration into hybrid environments. Microsoft Corporation anchors cloud-native SDN development through deep integration with Azure networking stacks. Nutanix competes by specializing in software-defined networking for on-premise-to-cloud federation.
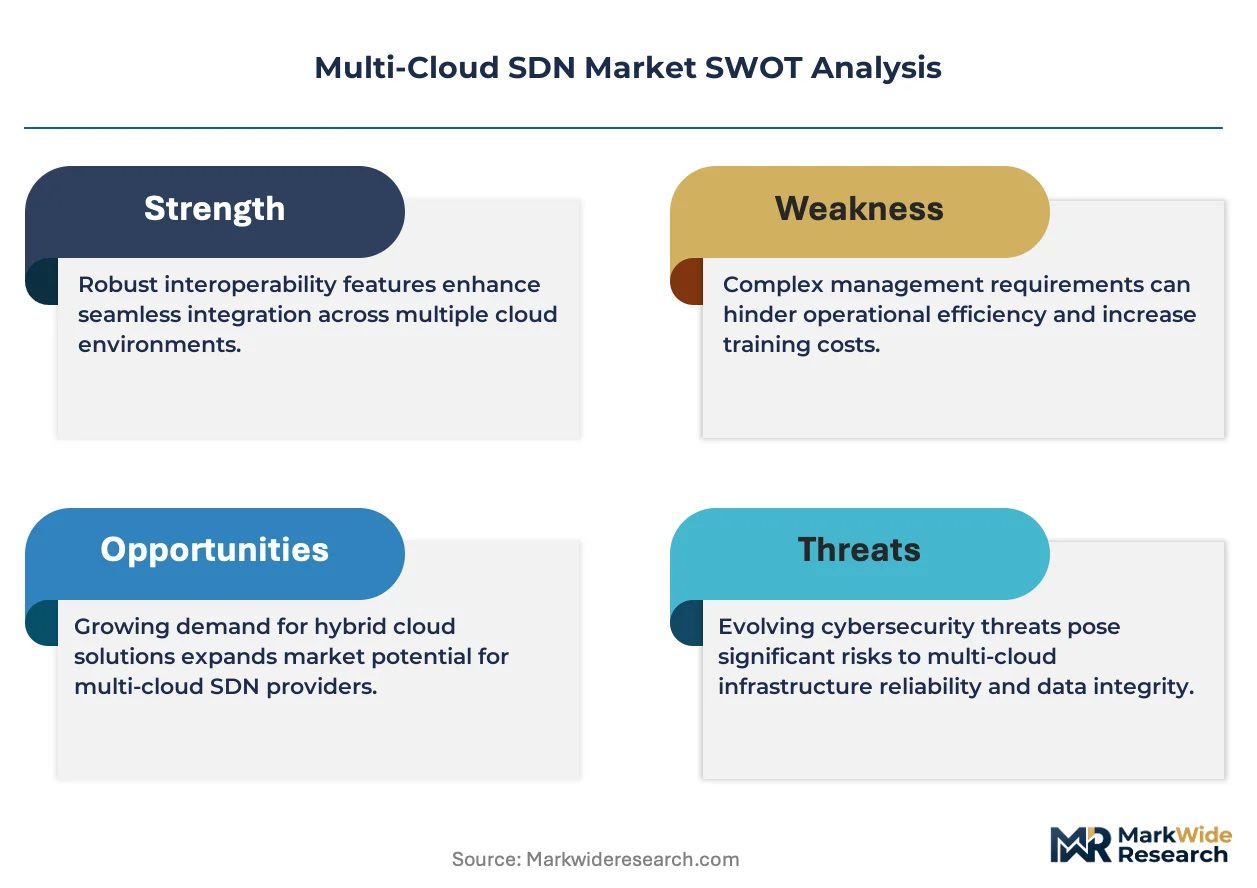
Multi-cloud SDN denotes software-defined networking architectures that abstract and programmatically control network resources across two or more cloud environments through centralized controllers and open APIs, typically operating at overlay layers with tunneling protocols such as VXLAN or Geneve to maintain tenant isolation. The technology enables enterprises to enforce consistent security policies, optimize traffic paths, and automate provisioning without hardware dependency at each cloud endpoint. Hybrid cloud deployment configurations currently occupy the largest addressable footprint, as enterprises retain sensitive workloads on-premise while bursting to public infrastructure. Security services within the service-type dimension command premium positioning due to zero-trust mandates and cross-cloud encryption requirements. OpenFlow-based technology approaches face displacement pressure from intent-based networking models that reduce manual policy scripting.
The Federal Communications Commission in the United States imposes baseline reliability standards on telecommunications infrastructure that indirectly shape SDN redundancy architectures, while the European Union Agency for Cybersecurity enforces cross-border certification schemes affecting vendor market access. ISO 27001 and IEC 62443 frameworks increasingly appear as procurement prerequisites for managed service providers selecting multi-cloud networking platforms. Stakeholders must monitor divergence between national cloud sovereignty laws and unified SDN control plane designs.
Market Dynamics
Intent-based networking is compressing the policy configuration cycle from weeks to minutes, forcing vendors to abandon OpenFlow-centric architectures in favor of declarative automation frameworks that abstract intent into executable network states.
Growth Catalysts
- EU AI Act compliance mandates:Cross-border data governance requirements are accelerating demand for unified control planes that enforce consistent encryption and access policies across distributed cloud footprints.
- Financial services federation:Capital markets firms require seamless workload mobility between on-premise data centers and public clouds for real-time risk analytics and regulatory reporting.
- Zero-trust architecture adoption:Microsegmentation policies spanning multiple cloud environments are driving investment in overlay networking solutions with granular identity-based access controls.
Market Restraints
- Controller interoperability gaps:Proprietary northbound APIs from dominant cloud providers fragment the orchestration layer and increase integration costs for multi-vendor deployments.
- Specialized engineering scarcity:Shortages of professionals skilled in both cloud-native networking and legacy enterprise infrastructure constrain deployment velocity for hybrid architectures.
- Cross-cloud latency penalties:East-west traffic between geographically dispersed cloud regions degrades application performance for latency-sensitive workloads.
Strategic Opportunities
- Edge-to-cloud orchestration:Manufacturing and industrial IoT deployments at remote sites create demand for lightweight SDN controllers that extend policy enforcement to distributed edge locations.
- Sovereign cloud requirements:Data localization laws in Germany, France, and India are compelling providers to architect region-specific control planes that maintain compliance without sacrificing unified management.
- Converged security-networking stacks:Integration of secure access service edge frameworks with SDN overlays is opening new service categories for managed security providers.
Industry Challenges
- Certification timeline compression:ISO 27001 and IEC 62443 compliance cycles for multi-cloud networking platforms now span 12-18 months, delaying revenue recognition for new market entrants.
- Technical debt reconciliation:Enterprises must maintain parallel operational models for legacy VLAN-based segmentation alongside modern overlay networks during multi-year migration windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multi-Cloud SDN Market |
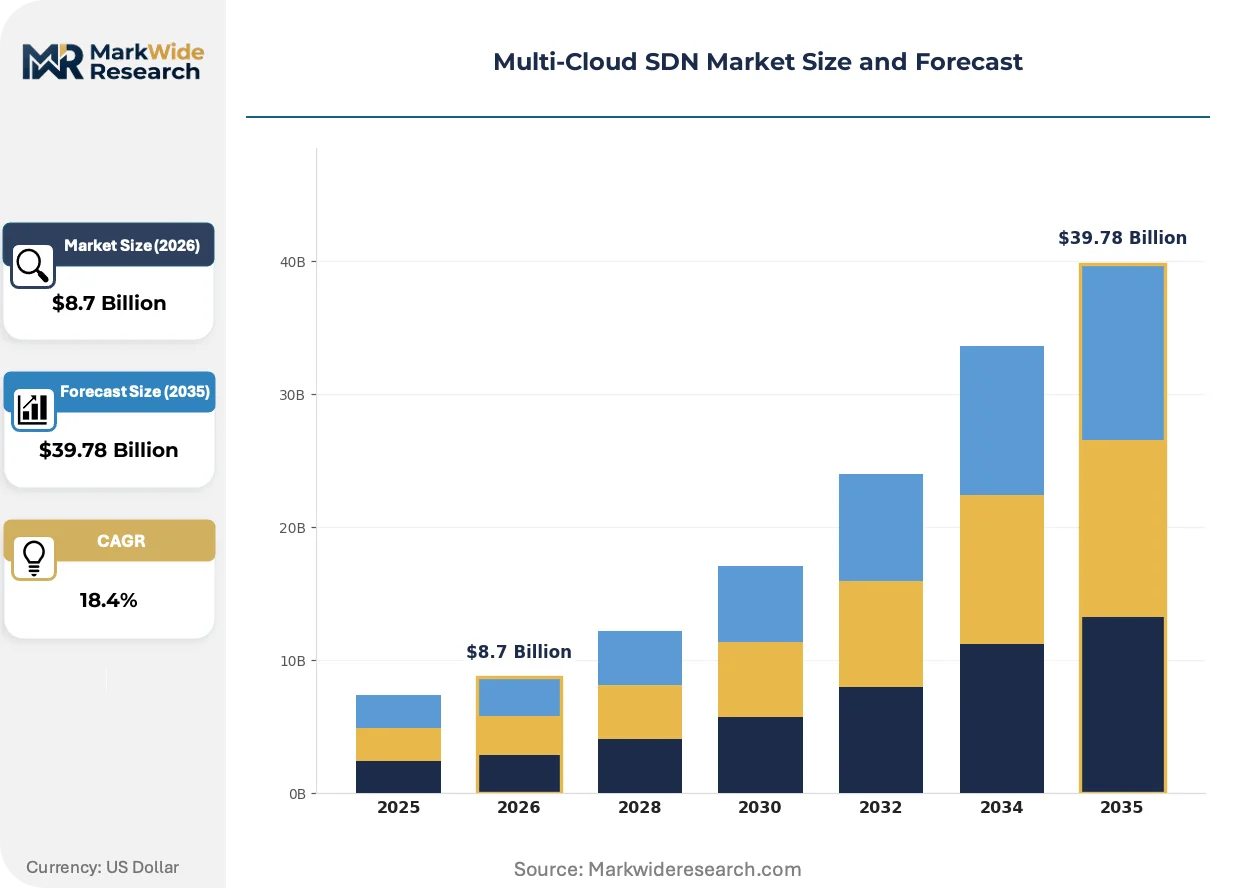
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Private Cloud, Public Cloud, Hybrid Cloud Service Type: Network Management, Connectivity Services, Security Services, Performance Monitoring End User: IT Enterprises, Telecommunication Providers, Managed Service Providers, Cloud Providers Technology: OpenFlow, Virtual Extensible LAN, Network Virtualization, Cloud Exchange |
| Companies Covered | Amazon Web Services, Inc., Microsoft Corporation, Cisco Systems, Inc., Hewlett Packard Enterprise, Dell Inc., IBM Corporation, Oracle Corporation, Nutanix, Inc., Broadcom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multi-Cloud SDN Market Shifts & Advancements
Automation is reshaping how network engineering teams design, deploy, and operate multi-cloud infrastructure, with three convergent developments altering competitive positioning across the vendor landscape.
Geneve tunneling is electrifying the overlay networking layer by unifying encapsulation across heterogeneous cloud environments. Large enterprises with Kubernetes-heavy workloads are standardizing on Geneve to replace fragmented VXLAN implementations. This consolidation is electrifying procurement decisions in favor of vendors offering native Geneve support across on-premise and public cloud footprints.
The FCC's reliability standards for telecommunications infrastructure are indirectly mandating redundant controller architectures in SDN deployments serving regulated industries. Financial services and healthcare providers must demonstrate failover capabilities that satisfy baseline uptime requirements. These mandates are accelerating adoption of active-active controller clusters in United States deployments.
Enterprise buyers are consolidating vendor relationships around integrated networking-security platforms rather than best-of-breed point solutions. Procurement teams now evaluate SDN offerings based on native integration with cloud access security brokers and zero-trust network access frameworks. This consolidation is most pronounced in United States federal contracting, where FedRAMP authorization requirements favor unified platform approaches over fragmented toolchains.
Multi-Cloud SDN Market Segmentation
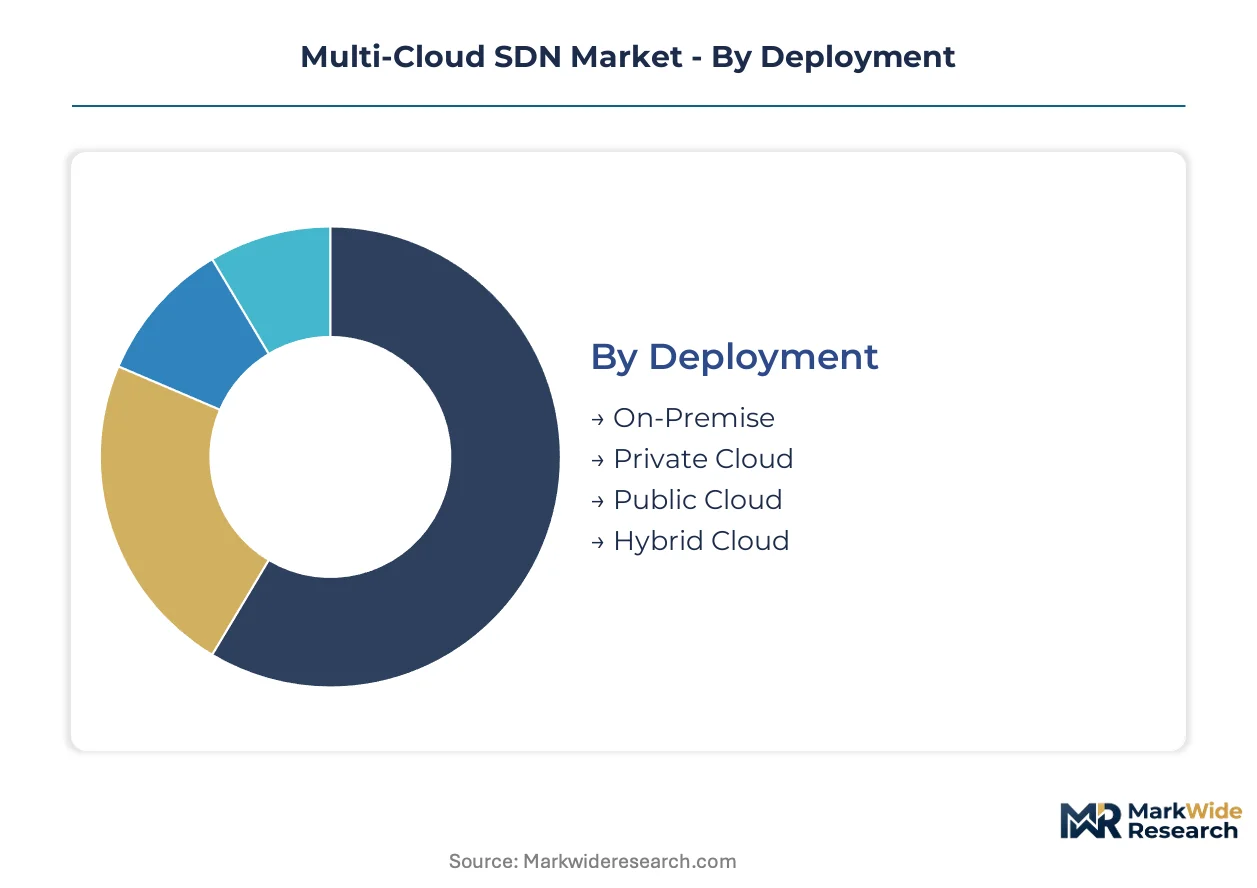
Multi-cloud SDN architectures fragment across deployment models, service layers, and underlying protocols, each carrying distinct capital requirements and integration complexity. Procurement teams weight these dimensions differently based on existing infrastructure commitments and regulatory exposure.
Deployment:
Capital intensity peaks with hybrid configurations demanding parallel investment in on-premise controllers and cloud-native orchestration layers.
- Hybrid Cloud:Combines on-premise infrastructure with public cloud bursting through unified control planes. Financial services firms in the United States favor this model for real-time risk analytics requiring low-latency local processing alongside elastic cloud compute.
- Public Cloud:Relies entirely on hyperscaler-managed networking stacks with customer-defined overlay policies. German manufacturers expanding into India deploy this model to avoid data center construction timelines while navigating India's data localization requirements through region-specific cloud regions.
- Private Cloud:Dedicated infrastructure within single-tenant environments with full stack control.
- On-Premise:Traditional data center deployments with SDN overlays retrofitting existing hardware.
Hybrid Cloud absorbs the bulk of installed capacity; Public Cloud is expanding most quickly.
Service Type:
Margin profiles diverge sharply between commoditized connectivity and premium security bundles requiring specialized engineering talent.
- Security Services:Encompasses microsegmentation, encryption management, and zero-trust policy enforcement across cloud boundaries. United States federal contractors prioritize these capabilities to satisfy FedRAMP authorization requirements for cross-boundary data protection.
- Connectivity Services:Delivers inter-cloud tunneling and bandwidth optimization through programmable WAN links. Frankfurt-based financial institutions leverage these services to maintain sub-millisecond latency between primary and disaster recovery sites spanning multiple cloud regions.
- Network Management:Centralized controller platforms for policy definition and traffic engineering.
- Performance Monitoring:Telemetry and analytics for cross-cloud visibility and troubleshooting.
Connectivity Services commands the largest revenue base; Security Services is gaining share fastest.
End User:
Technical sophistication and procurement authority vary dramatically across buyer categories, shaping vendor engagement models and contract structures.
- IT Enterprises:Direct consumers of multi-cloud networking for internal application portfolios. Large retailers in France deploy these solutions to unify e-commerce platforms across AWS, Azure, and on-premise legacy systems while maintaining GDPR-compliant audit trails.
- Telecommunication Providers:Carriers integrating SDN into managed service offerings for enterprise customers. Japanese operators under METI guidance are standardizing on cloud-native architectures to replace proprietary network management systems.
- Managed Service Providers:Third-party operators delivering networking-as-a-service to mid-market clients.
- Cloud Providers:Hyperscalers extending native networking capabilities through partner ecosystems.
IT Enterprises represent the deepest installed base; Managed Service Providers are climbing the fastest.
Technology:
Protocol selection locks buyers into specific vendor ecosystems and determines interoperability with existing infrastructure investments.
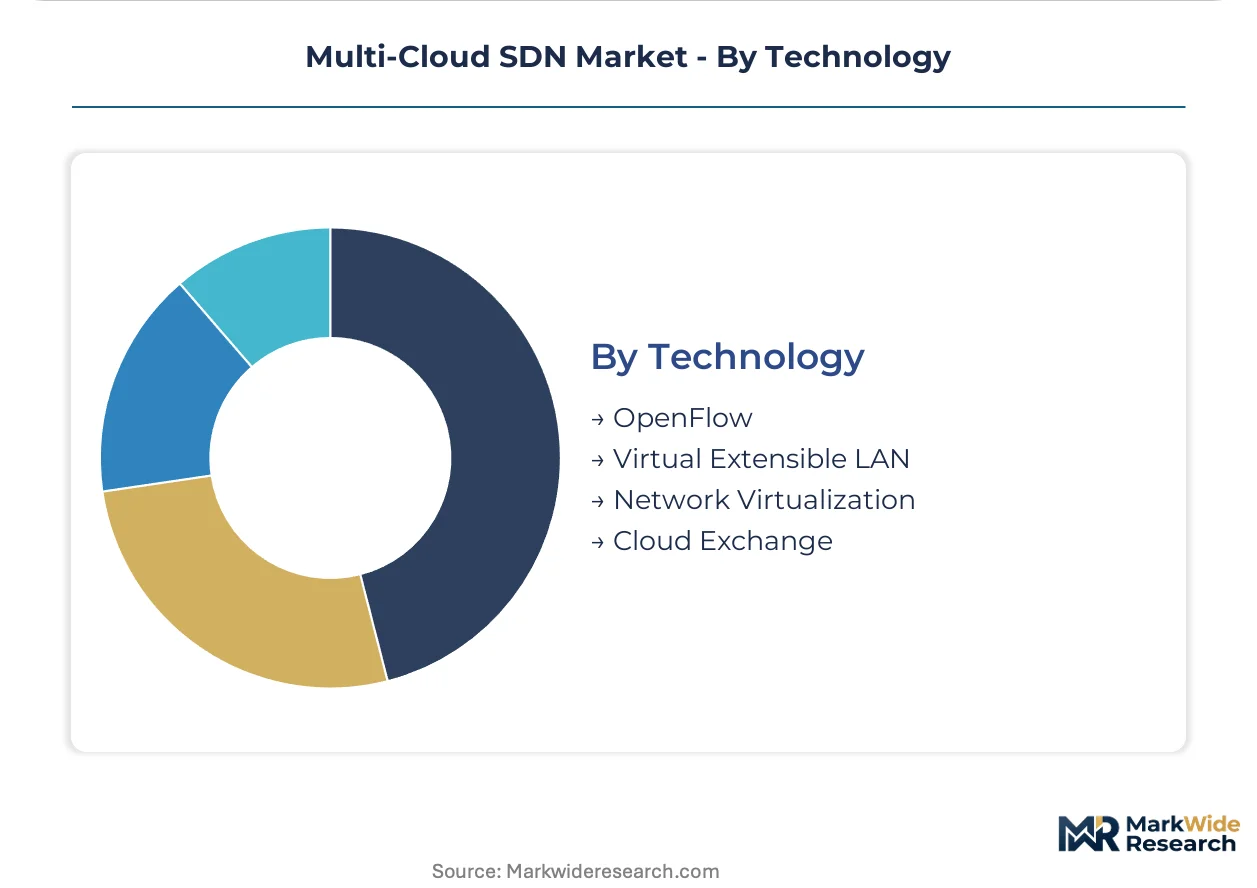
- Virtual Extensible LAN:Mature encapsulation protocol supported across enterprise hardware and major cloud platforms. Northern Virginia data centers standardize on VXLAN for seamless workload migration between on-premise VMware environments and AWS Outposts deployments.
- Network Virtualization:Abstracts physical network resources into software-defined segments independent of underlying hardware. Healthcare systems in Switzerland adopt this approach to isolate patient data flows across multiple cloud providers while satisfying Swissmedic requirements for data sovereignty.
- OpenFlow:Southbound protocol for direct switch programming, now facing displacement pressure.
- Cloud Exchange:Interconnection platforms enabling direct private connectivity between cloud environments.
Virtual Extensible LAN retains the broadest deployment footprint; Network Virtualization is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's hyperscaler density anchors North American capacity expansion. Frankfurt's data center cluster drives European interconnection demand. Singapore's submarine cable landing points shape Asia-Pacific traffic engineering.
United States
Financial services federation and zero-trust mandates propel enterprise SDN investment. The FCC imposes baseline reliability standards on telecommunications infrastructure that shape controller redundancy architectures. Northern Virginia data centers absorb the bulk of hybrid cloud deployments as AWS Outposts and Azure Stack extend hyperscaler networking into on-premise environments.
Germany
Automotive Industry 4.0 initiatives and sovereign cloud requirements accelerate edge-to-cloud orchestration demand. The EU AI Act and NIS2 Directive tighten cross-border data governance compliance for unified control planes. Frankfurt's financial district hosts sub-millisecond latency configurations between primary and disaster recovery sites spanning multiple cloud regions.
India
Data localization laws and mid-market cloud migration create demand for lightweight SDN controllers. The RBI and MeitY enforce sector-specific data residency requirements affecting multi-cloud architecture design. Mumbai and Bengaluru data center operators deploy region-specific control planes to satisfy compliance without sacrificing unified management visibility.
Japan
Telecommunications modernization under METI guidance replaces proprietary network management with cloud-native architectures. The country's national cybersecurity regulator mandates encryption standards for cross-border enterprise traffic. Tokyo and Osaka metropolitan areas concentrate managed service provider activity for industrial IoT deployments at remote manufacturing sites.
United Kingdom
Post-Brexit regulatory divergence and financial services competitiveness drive overlay networking investment. The Information Commissioner's Office enforces GDPR-aligned data protection requirements for cross-cloud audit trails. London's fintech cluster deploys microsegmentation policies spanning AWS, Azure, and on-premise legacy systems for real-time risk analytics.
Multi-Cloud SDN Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue edge-native specialization and API abstraction layers. The vendor base concentrates around three archetypes: legacy networking incumbents extending policy orchestration into hybrid environments, cloud-native specialists federating on-premise-to-cloud connectivity, and hyperscalers anchoring cloud-native SDN development through deep stack integration. Dominant competitive moves include strategic partnerships for controller interoperability and portfolio diversification into converged security-networking stacks.
Within the legacy networking tier, Cisco Systems and Hewlett Packard Enterprise occupy positions exemplifying installed-base leverage for hybrid cloud extension. Microsoft Corporation represents cloud-native anchoring through Azure networking stack integration. Among cloud-native specialists, Nutanix exemplifies the on-premise-to-cloud federation archetype.
| Leading Market Players |
|---|
| Amazon Web Services, Inc. |
| Microsoft Corporation |
| Cisco Systems, Inc. |
| Hewlett Packard Enterprise |
| Dell Inc. |
| IBM Corporation |
| Oracle Corporation |
| Nutanix, Inc. |
| Broadcom |
| Others |
Supply & Pricing Matrix
EU AI Act compliance mandates gate qualified supply and premium-tier pricing access for multi-cloud SDN vendors, as certification timelines stretch 12-18 months and ISO 27001 prerequisites filter out uncertified competitors from federal contracting pools. Buyers in financial services and healthcare segments now bundle encryption management and zero-trust policy enforcement as non-negotiable warranty inclusions, compressing margins for vendors unable to demonstrate FedRAMP authorization or cross-border data governance capabilities.
Pricing Analysis
Warranty and service bundling separates premium-tier SDN vendors from commodity connectivity providers, with encryption management and 24/7 controller redundancy now standard inclusions rather than upsells. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, where FedRAMP-authorized platforms command 40-60% premiums over uncertified alternatives. Price differentiation hinges on native integration with cloud access security brokers and zero-trust network access frameworks. Mid-market managed service providers exhibit highest price sensitivity, while United States federal contractors prioritize compliance over cost. Pricing pressure stems from hyperscaler-managed networking stacks commoditizing baseline connectivity services.
Supply Chain Analysis
Dual-sourcing requirements for SDN controllers now mandate multi-supplier qualification across United States, Germany, and India data center operators to mitigate single-source vulnerability from proprietary northbound API fragmentation. Supply concentration rests on Taiwan and South Korea for merchant silicon underpinning programmable switches, with China and Vietnam supplying enclosure and power components. Raw material dependencies include advanced semiconductors, optical transceivers, and specialized cooling systems. Tariff exposure on Chinese-manufactured hardware intensifies cost volatility. Distribution runs through direct enterprise sales for large deployments and managed service provider channels for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multi-cloud SDN markets traverse a technology-transition phase where intent-based networking architectures displace OpenFlow-centric legacy systems, compressing policy configuration cycles from weeks to minutes and rendering manual scripting competencies obsolete.
For Market Incumbents: Cement controller interoperability through strategic partnerships with hyperscaler networking teams to neutralize proprietary API fragmentation threats. Prioritize certification investment in ISO 27001 and IEC 62443 frameworks to defend federal contracting access against emerging cloud-native specialists. Build backward integration into merchant silicon supply through dedicated foundry relationships to secure programmable switch capacity.
For New Entrants and Emerging Players: Enter via lightweight edge-to-cloud orchestration controllers targeting manufacturing IoT deployments at remote industrial sites in Germany and Japan. Sovereign cloud requirements in India and France present the most penetrable geography-application intersection. Pursue managed service provider channel partnerships as the primary go-to-market angle, bypassing direct enterprise sales cycles dominated by incumbents.
For Investors and Strategic Acquirers: Geneve tunneling standardization across Kubernetes-heavy workloads is the leading indicator that overlay networking consolidation will accelerate vendor shakeout. Long-term viability favors cloud-native specialists with demonstrated on-premise-to-cloud federation capabilities and active-active controller cluster architectures. Target acquisition archetypes include edge-native SDN startups with API abstraction layers and established managed security provider relationships. Watch hyperscaler capex disclosures in Northern Virginia and Frankfurt as the inflection signal for capacity expansion timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native Azure networking stack integration anchors cloud-native SDN development for Microsoft Corporation. |
| Strategic Partnership | Cisco Systems extends policy orchestration into hybrid environments through installed-base enterprise router leverage. |
| Acquisition of Specialist Firm | Nutanix specializes in software-defined networking for on-premise-to-cloud federation through targeted capability builds. |
| Geographic Expansion | Frankfurt data center cluster drives European interconnection demand for sub-millisecond latency configurations. |
| Product Launch | Geneve tunneling support across on-premise and public cloud footprints electrifies procurement decisions for large enterprises. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with network engineering directors, cloud architects, managed service provider operations leads, and federal procurement officers. FCC reliability standards documentation, EU AI Act implementation guidance, and ISO 27001 certification databases provided regulatory boundary conditions. Hyperscaler capex disclosures and data center operator expansion announcements supplied infrastructure investment signals. Bottom-up triangulation across deployment model, service type, and technology segmentation converged with top-down macroeconomic validation.
Granularity-level modeling distinguished hybrid cloud, public cloud, private cloud, and on-premise configurations at the deployment dimension, with security services, connectivity services, network management, and performance monitoring tracked separately across the service-type layer. Technology segmentation captured Virtual Extensible LAN, Network Virtualization, OpenFlow, and Cloud Exchange protocol adoption patterns. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion across the analysis window. Intent-based networking displacement timelines and sovereign cloud regulatory implementation schedules served as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU AI Act enforcement or hyperscaler API standardization breakthroughs. Deviation in controller interoperability resolution timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Video Streaming Software Market
Software & Services
Contract Abstraction Software Market
Software & Services
Ground Handling Software Market
Software & Services
Application Server Market
Software & Services
Global Decision Support Software Market
Software & Services
Auto Software Market
Software & Services
Mobile Device Management (MDM) Market
Software & Services
Storyboarding Software Market
Software & Services
E-Clinical Solution Software Market
Software & Services
Sourcing Software Market
Software & Services
GCC Human Capital Management Software Market
Software & Services
Enterprise Mobility Software Market
Software & Services
Computer Backup Software Market
Software & Services
Commissioning Software Market
Software & Services
Global Java Web Frameworks Software Market
Software & Services
App Creation Software Market