
 Multi-Cloud Networking Market | 2026-2036
Multi-Cloud Networking Market Size, Share, and Industry Trends Forecast 2026-2036
Multi-Cloud Networking Market Outlook
Enterprise buyers with legacy data center investments is unwinding toward cloud-native startups and digital-first mid-market firms as the primary demand engine. Cisco Systems leverages its installed base of routing hardware to extend into software-defined multi-cloud fabrics. VMware Inc. anchors its position through deep integration with hyperscaler marketplaces. Cloudflare Inc. competes by collapsing security and networking into a single edge-delivered stack.
Multi-cloud networking encompasses the architectural layer that orchestrates connectivity, policy enforcement, and observability across two or more public or private cloud environments, typically implemented through software-defined controllers that abstract underlying physical infrastructure. Its primary commercial purpose is to eliminate network silos while maintaining consistent security posture and application performance across disparate cloud domains. The service type dimension shows network security and traffic engineering capturing the deepest margin pools as these functions resist commoditization. Deployment model dynamics reveal hybrid cloud configurations leading current enterprise adoption while multi-cloud-native architectures represent the fastest-growing configuration. SD-WAN technology dominates current implementation patterns, though artificial intelligence-driven autonomous networking is displacing manual policy management in advanced deployments.
FCC guidelines on critical infrastructure cybersecurity and the EU GDPR's data residency mandates shape product requirements for cross-border traffic management and encryption standards. ISO 27001 and the EU AI Act further constrain how automated networking systems handle sensitive enterprise data across jurisdictional boundaries. Stakeholders must decide whether to build proprietary control planes or embed third-party orchestration as hyperscaler networking APIs mature and regulatory fragmentation deepens.
Market Dynamics
The convergence of artificial intelligence-driven traffic management with software-defined networking controllers is reconfiguring how enterprises orchestrate connectivity across distributed cloud environments, compressing the operational window for manual policy administration.
Growth Catalysts
- EU AI Act compliance mandates:Automated network governance systems must now embed audit trails for AI-driven routing decisions, compelling enterprises to upgrade from legacy segmentation to unified policy frameworks.
- Financial services workload distribution:Banks and insurers are deploying multi-cloud fabrics to manage latency-sensitive trading applications alongside batch analytics across heterogeneous infrastructure.
- SD-WAN technology maturation:Controller software now abstracts physical transport layers, enabling consistent security posture enforcement without hardware dependency at each endpoint.
Market Restraints
- Hyperscaler API lock-in:Proprietary networking interfaces from dominant cloud providers create switching costs that resist third-party orchestration layer insertion.
- Cross-border data residency friction:GDPR localization requirements fragment traffic engineering architectures, forcing redundant infrastructure deployment in each jurisdiction.
- Specialized engineering talent scarcity:Shortage of professionals fluent in both cloud-native networking and legacy routing protocols constrains enterprise implementation velocity.
Strategic Opportunities
- Edge computing convergence:Collapsing security and networking into single-stack edge deployments opens new service categories for distributed application delivery.
- India's digital infrastructure expansion:TRAI policy frameworks and PLI scheme incentives are accelerating domestic cloud capacity, creating demand for inter-cloud connectivity solutions.
- Autonomous networking adoption:Machine learning-driven self-healing networks reduce operational headcount requirements while improving incident response times.
Industry Challenges
- ISO 27001 certification complexity:Multi-cloud architectures must demonstrate consistent control implementation across disparate provider environments, extending audit timelines.
- Interoperability standard fragmentation:Competing controller protocols from hardware incumbents and cloud-native vendors delay enterprise consolidation decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multi-Cloud Networking Market |
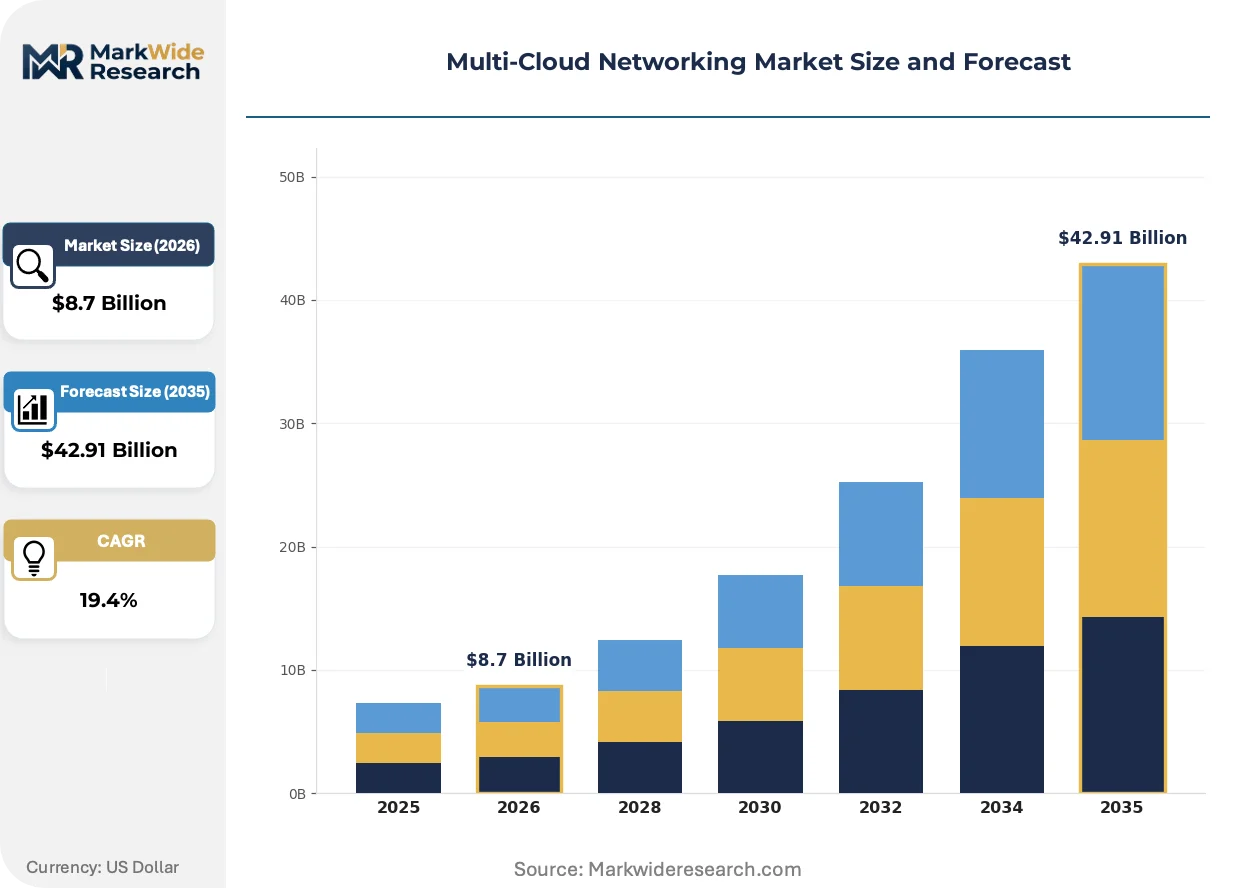
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $42.91 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Type: Network Security, Data Management, Connectivity Solutions, Traffic Engineering End User: BFSI, Healthcare, Retail, Telecommunications Technology: SD-WAN, VPN, Artificial Intelligence, Machine Learning |
| Companies Covered | Cisco Systems, Inc., VMware Inc., F5, Inc., Oracle, Juniper Networks Inc., Hewlett Packard Enterprise Development LP, Cloudflare Inc., Aviatrix, Inc., Microsoft Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multi-Cloud Networking Market Strategic Shifts
Artificial intelligence is penetrating network operations centers, displacing reactive troubleshooting with predictive traffic engineering that anticipates congestion before service degradation occurs.
Intent-based networking is decomposing traditional command-line configuration into declarative policy languages that translate business requirements into automated infrastructure provisioning. Large enterprises with complex hybrid footprints are piloting these systems most aggressively. The technology is decomposing the role of specialized network engineers into platform operators who manage abstraction layers rather than device-specific parameters.
FCC critical infrastructure cybersecurity guidelines are mandating encryption standards and access logging for cross-border traffic flows that transit national backbone networks. Financial services and energy sector deployments face the steepest compliance burdens. US-based enterprises are restructuring their multi-cloud backbones to segment traffic by data classification tier, adding architectural cost but reducing regulatory exposure.
Enterprise sourcing patterns are compressing vendor evaluation cycles as pre-integrated security-networking bundles displace best-of-breed component procurement. Mid-market firms with limited internal engineering capacity are driving this shift most visibly. Germany's manufacturing sector exemplifies the pattern, where Mittelstand companies favor single-vendor edge stacks over multi-supplier integration projects.
Multi-Cloud Networking Market Segmentation
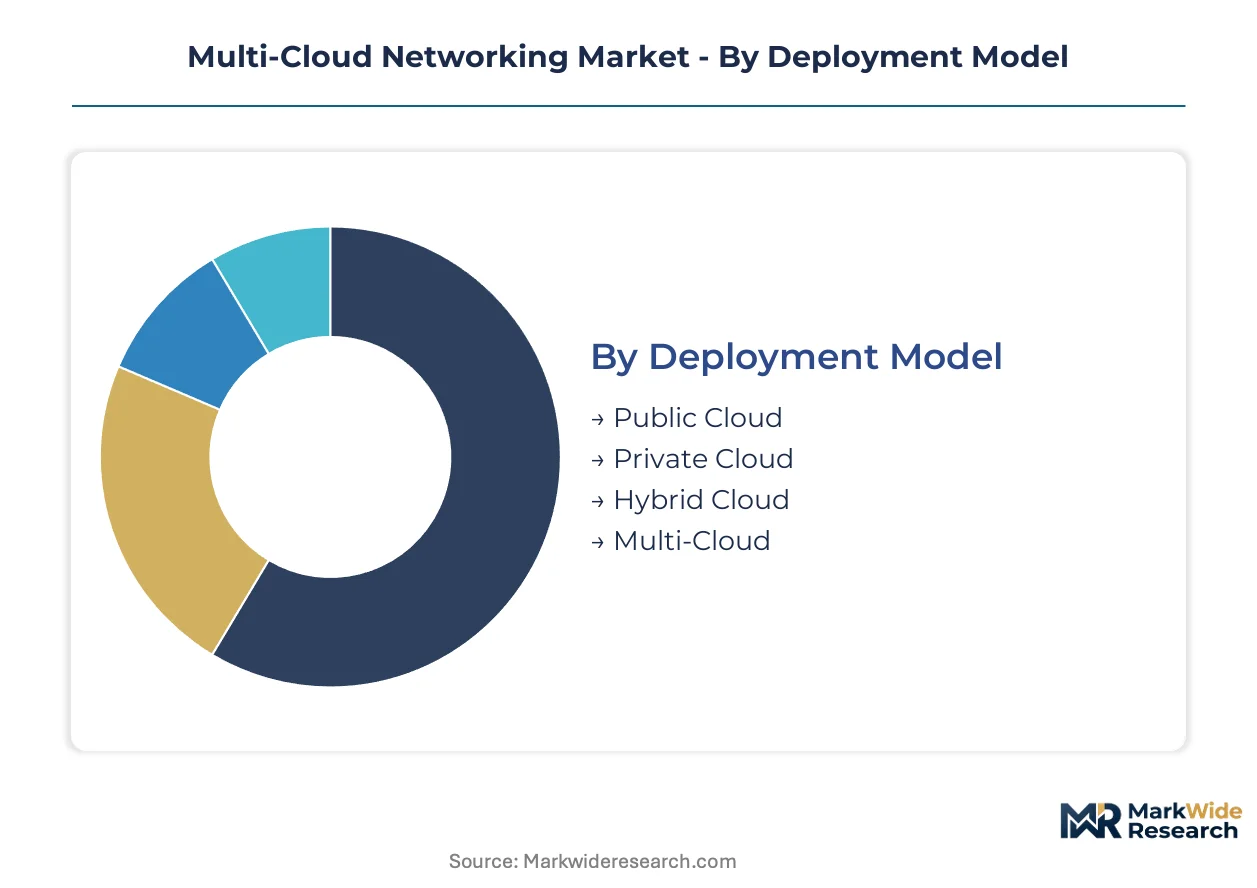
Architectural choices in multi-cloud networking determine where vendors extract value and where enterprises face switching costs. Deployment configurations, service layers, and underlying technologies each concentrate margin pools differently across the stack.
Deployment Model:
Hybrid configurations currently capture the deepest margin pools as enterprises pay premiums for unified control planes spanning legacy and cloud-native infrastructure.
- Public Cloud:Native networking services from hyperscalers abstract physical infrastructure through proprietary APIs. Financial services firms in the United States deploy these for burst workloads, though egress fees erode total cost advantages at scale.
- Private Cloud:Dedicated infrastructure with tenant-isolated networking stacks serves regulated industries requiring data sovereignty guarantees. German manufacturing enterprises favor this model to satisfy GDPR localization mandates without shared-tenant exposure.
- Hybrid Cloud:Orchestration layers synchronize policy enforcement across on-premises and cloud-hosted resources. Large enterprises with sunk data center investments drive demand here, accepting complexity premiums for workload portability.
- Multi-Cloud:Architectures spanning two or more hyperscalers without single-provider dependency represent the steepest expansion trajectory. Advanced adopters in India leverage this configuration to negotiate provider pricing and mitigate concentration risk.
Hybrid Cloud holds installed capacity. Multi-Cloud is rotating up the share rankings.
Service Type:
Security and traffic engineering resist commoditization most effectively, commanding pricing premiums that data management services cannot match.
- Network Security:Zero-trust segmentation and micro-perimeter enforcement protect lateral movement across cloud boundaries. BFSI buyers in the United States prioritize these capabilities to satisfy OCC cybersecurity guidance and state-level breach notification laws.
- Traffic Engineering:Intelligent path selection and congestion-aware routing optimize application performance across disparate cloud regions. Telecommunications providers deploy these services to guarantee SLA adherence for latency-sensitive enterprise customers.
- Data Management:Cross-cloud replication and consistency services address storage fragmentation without deep packet inspection. Retail enterprises adopt these for inventory synchronization across geographically distributed fulfillment systems.
- Connectivity Solutions:Backbone provisioning and last-mile abstraction complete the service stack. Healthcare organizations in Germany utilize these to link hospital networks with cloud-hosted diagnostic platforms under BSI IT-Grundschutz compliance.
Network Security dominates revenue contribution. Traffic Engineering is climbing the fastest.
End User:
Financial services and telecommunications verticals concentrate procurement budgets, though healthcare is accelerating procurement velocity.
- BFSI:Trading infrastructure and fraud analytics drive multi-cloud networking investment. US banks face dual pressure from SEC cybersecurity disclosure rules and FFIAC examination priorities.
- Telecommunications:5G core disaggregation and edge computing deployments require programmable interconnect fabrics. Indian carriers leverage TRAI-mandated infrastructure sharing to reduce capital intensity.
- Healthcare:Electronic health record portability and telemedicine scaling create networking complexity. HIPAA-covered entities prioritize encrypted transit and audit logging for cross-cloud patient data flows.
- Retail:Omnichannel fulfillment and real-time personalization engines distribute workloads across cloud environments. Seasonal demand spikes favor elastic connectivity provisioning over fixed infrastructure commitments.
BFSI anchors current spending. Healthcare is gaining share fastest.
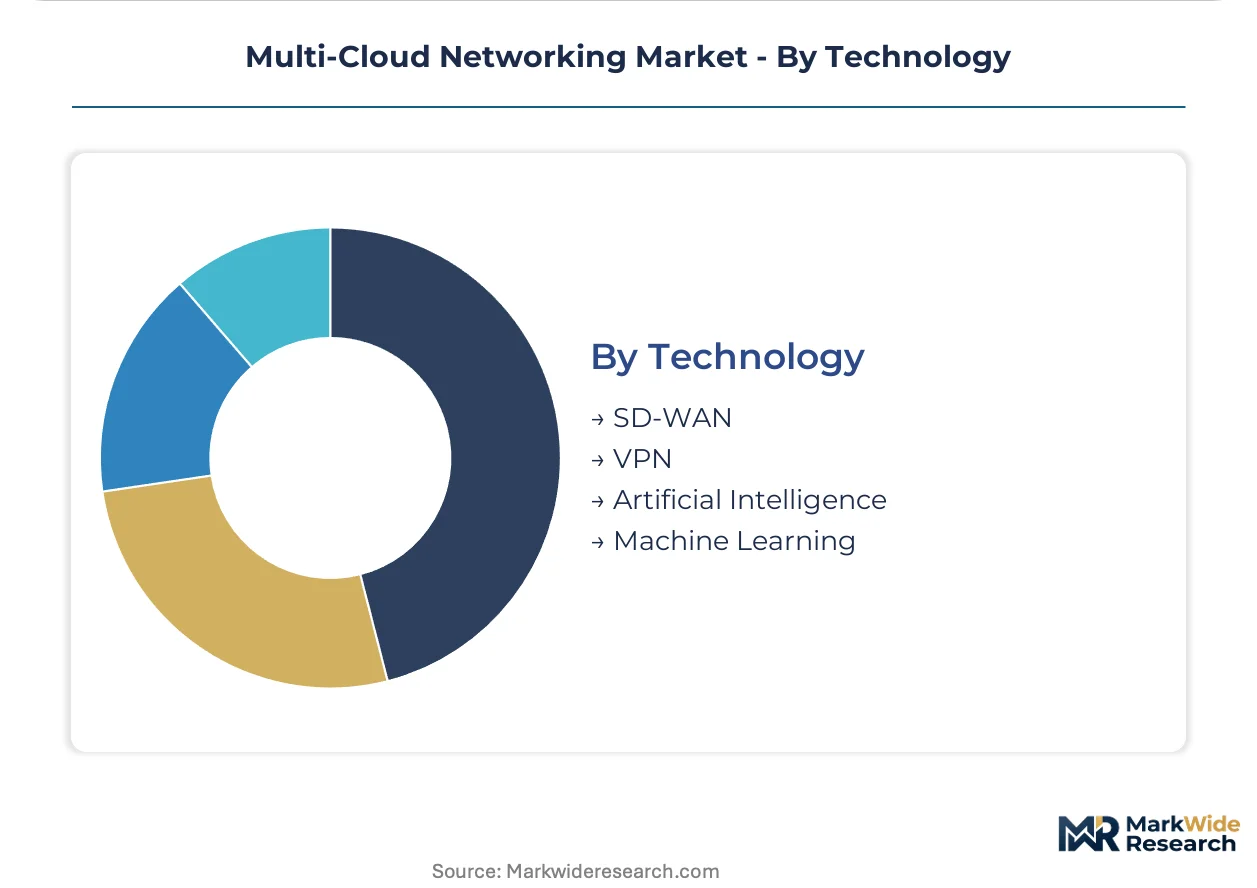
Technology:
SD-WAN maturity has compressed hardware margins while AI-driven autonomous networking opens new pricing tiers.
- SD-WAN:Controller-based abstraction of transport layers enables policy-driven path selection without proprietary CPE lock-in. Mid-market enterprises in the United States standardize on this technology to reduce MPLS dependency.
- Artificial Intelligence:Predictive traffic engineering and anomaly detection replace reactive network operations. Advanced deployments in India's financial sector automate incident response under RBI operational resilience guidelines.
- VPN:Encrypted tunneling persists for point-to-point connectivity and remote access scenarios. Regulatory mandates in Germany enforce IPsec standards for cross-border administrative traffic.
- Machine Learning:Pattern recognition models optimize routing decisions based on historical performance data. Telecommunications operators deploy these for self-healing backbone networks with minimal human intervention.
SD-WAN commands current deployment volume. Artificial Intelligence is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Submarine cable landings at Mumbai, Singapore, and Marseille anchor inter-cloud traffic flows across three continents. These fiber optic corridors determine latency economics for multi-cloud networking procurement decisions.
United States
Financial services firms distribute trading workloads across AWS, Azure, and Google Cloud regions to optimize execution latency. FCC cybersecurity guidelines mandate encryption standards for cross-border traffic transiting national backbone networks. New York and Chicago financial districts host the densest concentrations of multi-cloud interconnect facilities.
Germany
Industrial conglomerates require unified network governance across on-premises Siemens infrastructure and hyperscaler environments. GDPR data localization mandates force redundant infrastructure deployment in Frankfurt and Munich metro areas. Bavaria's automotive sector pilots edge-computing convergence for factory-floor connectivity.
India
Domestic cloud capacity expansion under TRAI policy frameworks accelerates demand for inter-cloud connectivity solutions. RBI operational resilience guidelines drive autonomous networking adoption in Mumbai's banking sector. Bangalore's technology corridor hosts the fastest-growing deployments of AI-driven traffic engineering.
United Kingdom
Telecommunications providers disaggregate 5G core networks across multi-cloud fabrics to reduce vendor lock-in. FCA operational resilience requirements impose recovery time objectives on cross-cloud service continuity. London's financial district concentrates procurement budgets for zero-trust segmentation solutions.
Japan
Manufacturing enterprises synchronize supply chain systems across domestic private clouds and offshore SaaS platforms. METI digital infrastructure incentives support SD-WAN maturation in Osaka industrial zones. Tokyo's financial institutions deploy intent-based networking for declarative policy management.
Multi-Cloud Networking Market Competitive Environment
Concentration sits with legacy networking hardware incumbents extending into software-defined fabrics. The vendor base spans three tiers: routing equipment manufacturers with installed base leverage, cloud-native orchestration specialists, and edge-delivered security-networking converged platforms. Strategic moves center on hyperscaler marketplace integration and AI-driven autonomous networking capability acquisition.
Within the legacy infrastructure tier, Cisco Systems and Juniper Networks occupy positions anchored by routing hardware footprints. VMware Inc. exemplifies the virtualization-to-cloud orchestration archetype through hyperscaler marketplace embedding. Cloudflare Inc. represents the edge-converged stack model, collapsing security and networking into single-platform delivery.
| Leading Market Players |
|---|
| Cisco Systems, Inc. |
| VMware Inc. |
| F5, Inc. |
| Oracle |
| Juniper Networks Inc. |
| Hewlett Packard Enterprise Development LP |
| Cloudflare Inc. |
| Aviatrix, Inc. |
| Microsoft Corporation |
| Others |
Value Chain & Pricing Dynamics
Software-defined controller platforms replacing legacy hardware appliances simultaneously shift supply geography toward cloud-native development clusters and compress pricing premiums for proprietary routing equipment. This substitution dynamic redistributes margin capture from hardware incumbents toward orchestration software vendors while fragmenting procurement decisions across hyperscaler marketplaces.
Pricing Analysis
Volume-discount tiering structures stratify across enterprise scale bands, with per-port subscription rates declining at committed-volume thresholds above ten thousand endpoints. Pricing differentiation rests on ISO 27001 certification tier and embedded AI-driven autonomous networking capability. Cost compression in mid-market segments is intensifying because hyperscaler-native networking services absorb baseline connectivity demand. Mid-market enterprises with limited engineering staff exhibit highest price sensitivity, while financial services institutions prioritize compliance-grade premiums over unit economics.
Supply Chain Analysis
The United States and India anchor software development and cloud infrastructure deployment respectively, with Taiwan supplying specialized silicon for programmable networking hardware. Controller software draws from open-source routing protocol stacks and proprietary AI training datasets, while physical layer components source from East Asian fabrication networks. Single-source vulnerability concentrates in specialized encryption chipsets subject to export control restrictions. Distribution runs through hyperscaler marketplace integrations and direct enterprise sales organizations with certified implementation partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
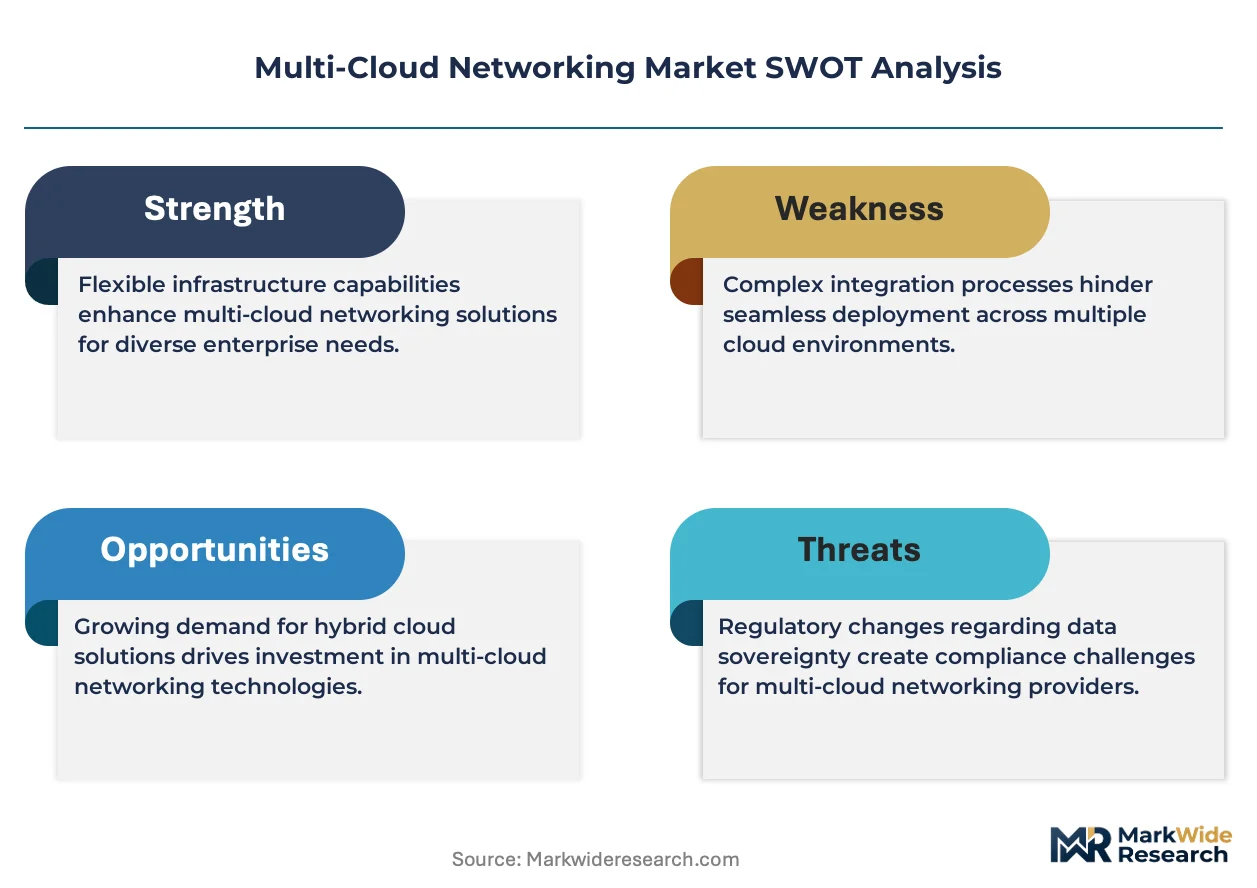
Fragmentation opportunity permeates this market as regulatory divergence between EU AI Act mandates and FCC cybersecurity guidelines creates specialized compliance niches. Demand-side shift toward sovereign cloud requirements in Germany and India fragments unified procurement patterns.
For Market Incumbents: Secure hyperscaler marketplace embedding positions before cloud-native orchestration specialists capture mid-market share. Defend installed base leverage through backward integration into AI-driven traffic analytics. Prioritize ISO 27001 certification maintenance as competitive moat against emerging cloud-native entrants. For New Entrants and Emerging Players: Lead with edge-delivered security-networking convergence targeting India's digital infrastructure expansion under TRAI policy frameworks. Capture Mittelstand manufacturing segment in Germany through single-stack simplicity competing against multi-vendor integration complexity. Pursue channel partnerships with regional systems integrators lacking autonomous networking capability. For Investors and Strategic Acquirers: Capital is best deployed toward cloud-native orchestration specialists with proven hyperscaler API integration and compliance automation IP. Long-term viability favors platforms bridging legacy routing protocols with intent-based declarative policy languages. Signal to monitor: acceleration of RBI operational resilience enforcement driving autonomous networking procurement velocity in Mumbai banking sector.| Strategic Initiative | Industry Significance |
|---|---|
| Hyperscaler Marketplace Integration | Embedding orchestration layers within AWS, Azure, and Google Cloud marketplaces captures procurement workflows at decision point. |
| AI-Driven Autonomous Networking Acquisition | Machine learning traffic engineering capability addresses talent scarcity constraining enterprise implementation velocity. |
| Edge Security-Networking Convergence | Single-stack delivery collapses vendor count for mid-market firms with limited integration capacity. |
| Compliance Automation Platform Development | Automated EU AI Act audit trail generation differentiates offerings for regulated financial services buyers. |
| Regional Cloud Infrastructure Partnership | Domestic capacity expansion in India under PLI scheme incentives creates inter-cloud connectivity demand. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of SEC filings, hyperscaler capex disclosures, and regulatory docket analysis. Network architects, cloud procurement officers, and compliance directors at financial services and telecommunications enterprises provided operational perspective. Secondary validation drew from FCC cybersecurity guideline documents, EU AI Act implementation guidance, and TRAI policy frameworks. Bottom-up deployment estimates triangulated against top-down infrastructure spending projections.
Segmentation dimensions modeled span deployment configuration, service type layer, end-user vertical, and underlying technology architecture across the analysis window. CAGRs derived from slope-intercept analysis of historical infrastructure investment patterns projected against regulatory mandate implementation timelines. Forecast inputs incorporated RBI operational resilience deadlines and GDPR data localization enforcement intensity variations.
The analysis sits within stated boundaries; outcomes outside sustained hyperscaler API stability and regulatory enforcement consistency would require recalibration. Forecasts reflect assumptions regarding SD-WAN technology maturation pace and AI-driven policy automation adoption curves. Recalibration cycles align with material shifts in EU AI Act enforcement interpretation and FCC critical infrastructure guideline revision schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Middle East and Africa Cloud Infrastructure Services Market
Cloud Computing
Public Cloud Application Infrastructure Services Market
Cloud Computing
Cloud Load Balancers Market
Cloud Computing
Saudi Arabia Cloud Services Market
Cloud Computing
Application Hosting Market
Cloud Computing
Cloud Data Quality Monitoring Market
Cloud Computing
Israel Cloud Computing Market
Cloud Computing
Global Cloud Dictation Solution Market
Cloud Computing
Cloud Backup Market
Cloud Computing
Cloud Management for the Openstack Market
Cloud Computing
Cloud Continuum Market
Cloud Computing
Cloud Management Market
Cloud Computing
Cloud Based-Batch Processing Market
Cloud Computing
Government Cloud Computing Market
Cloud Computing
United States Cloud Computing Market
Cloud Computing
Public Finance Cloud Market