
 Mobile Device Management (MDM) Market | 2026-2036
Mobile Device Management (MDM) Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Device Management (MDM) Market Intelligence
Cloud-native container orchestration is shifting how MDM platforms deliver scalability and reduce infrastructure overhead for distributed workforces. Microsoft Intune leverages Azure's global footprint to anchor enterprise subscriptions across multinational deployments. VMware Workspace ONE differentiates through unified endpoint management that converges mobile and desktop governance. SOTI MobiControl specializes in rugged device management for logistics and field-service verticals.
Mobile Device Management encompasses software platforms that provision, monitor, and secure endpoint devices through over-the-air configuration of policies, encryption protocols, and application containers. These systems enforce compliance through remote wipe capabilities, geofencing, and certificate-based authentication while integrating with identity providers for zero-trust access control. Cloud-based deployment leads solution adoption as organizations prioritize subscription flexibility and rapid scaling over capital-intensive on-premises infrastructure. Enterprise Solutions within the solution category capture concentrated margin pools due to bundled security modules and premium support tiers. Healthcare end users represent the fastest-growing demand segment as HIPAA-mandated safeguards drive procurement of MDM platforms with audit trails and patient-data isolation.
FDA guidelines on mobile medical applications intersect with HIPAA requirements to shape product standards for healthcare MDM deployments in the United States. The EU AI Act and GDPR collectively force vendors to embed algorithmic transparency and data-residency controls into European offerings. Stakeholders must monitor how NIST zero-trust architecture mandates and emerging state-level privacy statutes in California and Virginia reshape procurement specifications and vendor qualification criteria.
Market Dynamics
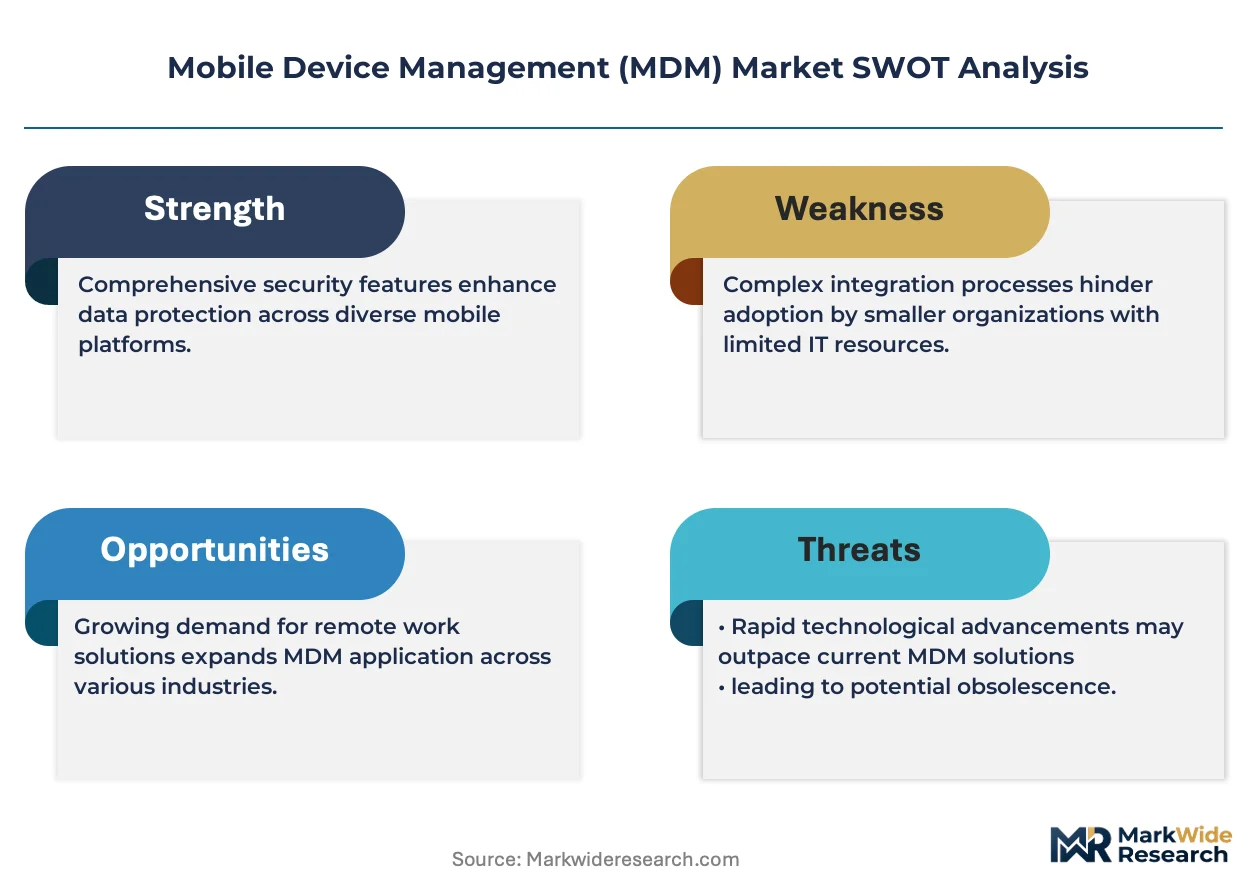
Zero-trust security architectures are compressing deployment cycles as enterprises replace perimeter-based VPNs with continuous device verification, forcing MDM vendors to embed conditional access engines directly into policy orchestration layers.
Growth Catalysts
- HIPAA audit mandates:US healthcare systems must demonstrate mobile patient-data containment, driving procurement of MDM platforms with containerized encryption and remote wipe capabilities.
- Industrial IoT convergence:German manufacturing clusters are deploying rugged device management for shop-floor tablets and handheld scanners, extending MDM beyond smartphones into operational technology environments.
- EU AI Act compliance:Algorithmic transparency requirements for automated endpoint decisions are compelling European enterprises to upgrade governance frameworks with auditable policy engines.
Market Restraints
- Certificate authority concentration:Dependence on a limited pool of root certificate providers creates single-point-of-failure risk for zero-trust authentication chains.
- On-premises infrastructure drag:Capital-intensive server deployments and dedicated IT staffing requirements deter mid-market adopters from hybrid architectures.
- Fragmented OS ecosystems:Divergent update cycles across Android OEM variants and iOS release cadences strain policy consistency for multi-platform fleets.
Strategic Opportunities
- India's PLI scheme:Local device manufacturing incentives are creating demand for domestically hosted MDM instances with data-residency guarantees.
- 5G private networks:Convergence of cellular slicing and edge computing enables real-time policy enforcement for latency-sensitive field applications.
- CSRD reporting mandates:EU corporate sustainability disclosures require IT asset lifecycle tracking, opening subscription modules for carbon-accounting integration.
Industry Challenges
- Identity architect scarcity:Shortage of engineers skilled in SCIM protocol implementation and SAML federation delays enterprise rollout timelines.
- Legacy EMM migration friction:Transitioning from on-premises MobileIron or BlackBerry deployments to cloud-native stacks requires parallel policy validation and user re-enrollment.
- Cross-border data routing complexity:Conflicting sovereignty requirements between GDPR, China's PIPL, and sector-specific banking regulations complicate multinational policy harmonization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Device Management (MDM) Market |
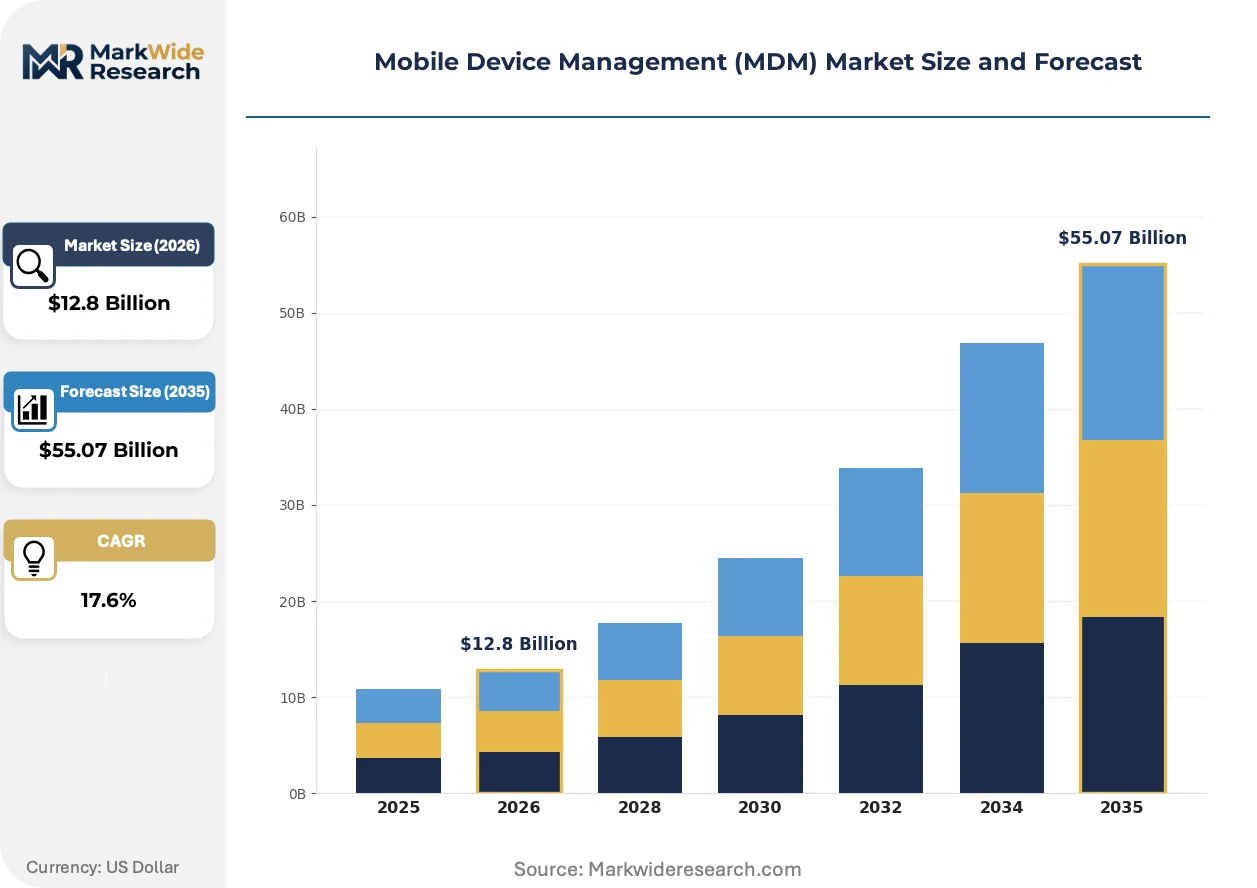
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $55.07 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
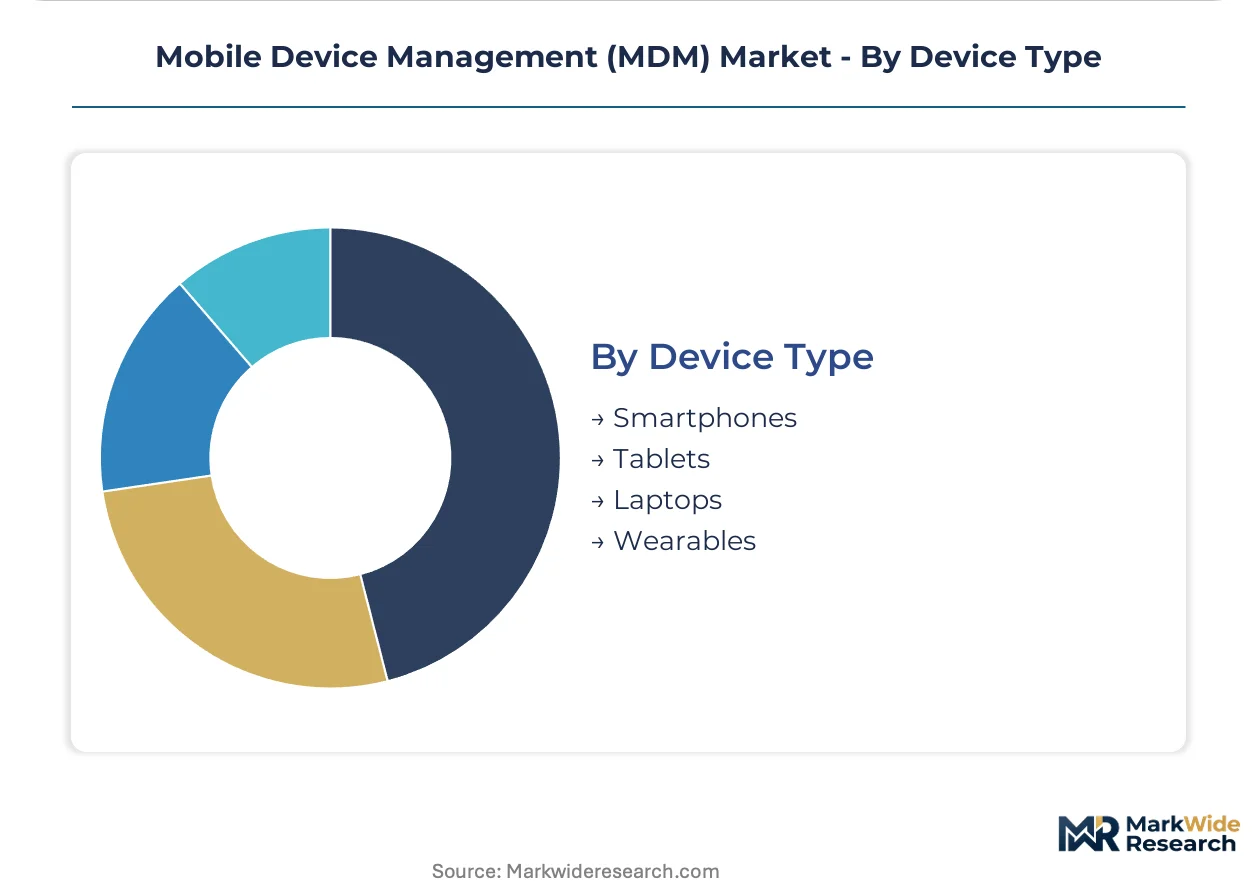
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services Solution: Enterprise Solutions, MDM Solutions, Unified Endpoint Management, Security Solutions End User: Healthcare, Education, BFSI, Retail Device Type: Smartphones, Tablets, Laptops, Wearables |
| Companies Covered | Jamf Pro, Scalefusion, Microsoft Intune, SOTI MobiControl, Hexnode, VMware Workspace ONE, ManageEngine Mobile Device Manager Plus, Miradore, IBM MaaS360, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Device Management (MDM) Market Strategic Shifts & Innovations
Artificial intelligence is embedding predictive capabilities directly into endpoint governance, shifting MDM from reactive policy enforcement to anticipatory threat containment and automated compliance remediation.
Agentic AI for autonomous endpoint remediation is overtaking rule-based automation in enterprise procurement evaluations. Financial services institutions in Singapore and London are piloting self-healing device configurations that isolate anomalies without human ticketing. This compression of mean-time-to-resolution is overtaking traditional tier-one support contracts as a vendor selection criterion.
The EU AI Act's risk-classification framework for automated decision systems is forcing MDM vendors to document algorithmic logic for policy enforcement engines. Industrial deployments in Bavaria and the Netherlands now require explainability dashboards for geofencing triggers and access denials. Healthcare providers are responding by demanding vendor attestations of conformity with MDR technical documentation standards.
Subscription unbundling is fragmenting how mid-market buyers procure endpoint security. Regional system integrators in Texas and Ontario are white-labeling modular MDM components rather than reselling full suites. This channel restructuring is most visible among K-12 districts and municipal governments with constrained capital budgets seeking à-la-carte device enrollment and application management without premium security bundles.
Mobile Device Management (MDM) Market Segmentation
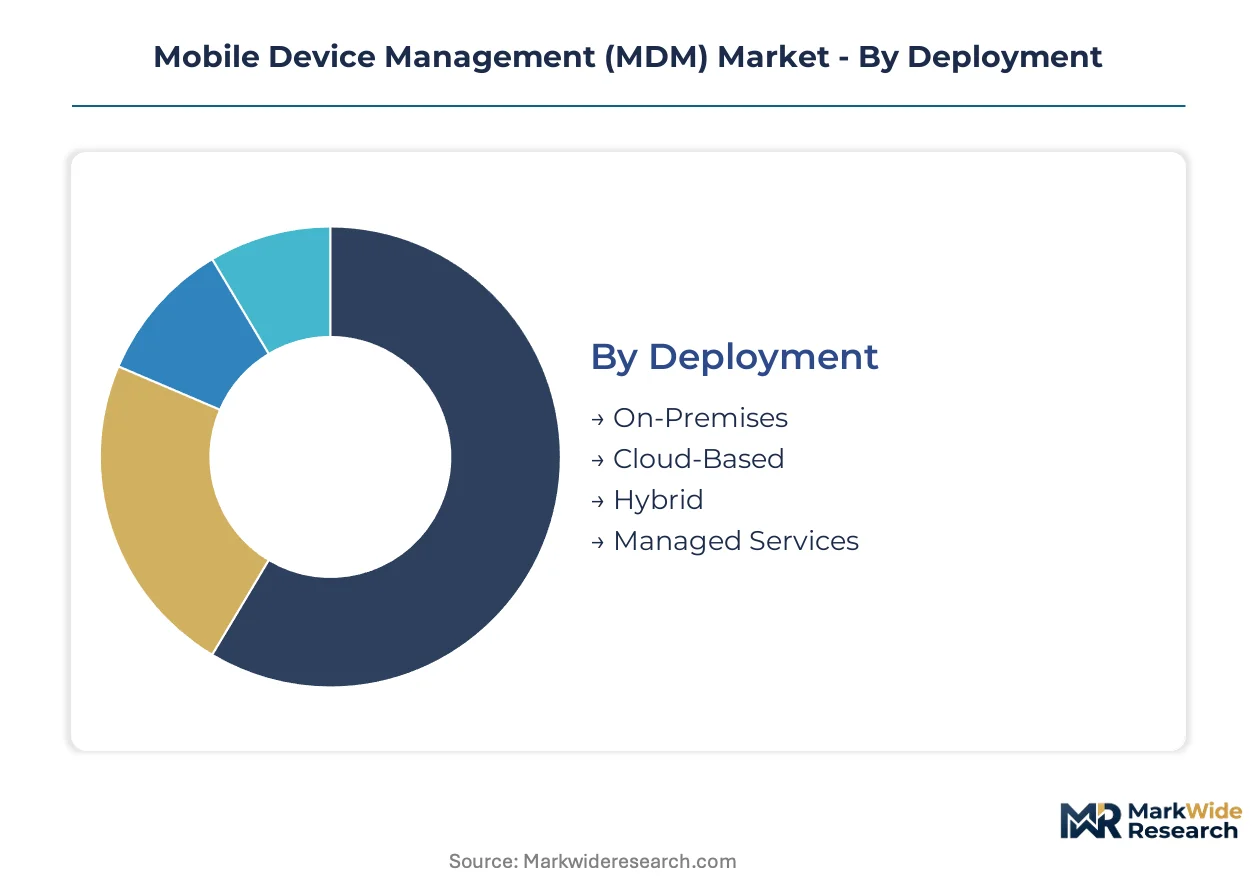
MDM procurement patterns diverge sharply across deployment architectures, solution bundles, and device ecosystems. Understanding these fault lines reveals where vendors capture margin premiums versus where commoditization pressures concentrate.
Deployment:
Technical architecture determines capital intensity, policy latency, and data sovereignty compliance scope.
- Cloud-Based:Multi-tenant SaaS architectures eliminate server provisioning overhead and compress enrollment timelines to hours rather than weeks. Healthcare systems in the United States favor this model for HIPAA-compliant audit trails without dedicated infrastructure teams, though recurring subscription costs accumulate over five-year TCO horizons.
- Hybrid:Policy orchestration splits between cloud-hosted consoles and on-premises policy enforcement nodes, accommodating German manufacturing requirements for shop-floor data residency alongside centralized IT visibility. This architecture demands dual skill sets in cloud-native and legacy Windows Server administration, limiting adoption to enterprises with mature identity teams.
- On-Premises:Single-tenant deployments on customer-managed hardware satisfy financial services regulators in Singapore and Swiss banking authorities demanding air-gapped certificate stores.
- Managed Services:Third-party operators assume full policy administration and tier-one support, appealing to K-12 districts and municipal governments lacking dedicated endpoint engineers.
Mature deployment sits with On-Premises. Newer deployment is concentrated in Cloud-Based.
Solution:
Bundle composition separates commodity device enrollment from premium security modules and unified governance platforms.
- Enterprise Solutions:Comprehensive suites integrate MDM, mobile application management, and identity federation with premium support SLAs. German automotive suppliers and Dutch logistics operators procure these bundles for converged smartphone and rugged handheld governance across continental fleets.
- Security Solutions:Specialized modules focus on containerized encryption, threat detection, and conditional access engines without full UEM overhead. Financial institutions in London and Singapore pilot these for zero-trust compliance without displacing incumbent EMM investments.
- MDM Solutions:Core device provisioning, inventory, and policy enforcement without bundled security or desktop management.
- Unified Endpoint Management:Converged mobile and desktop governance platforms extending policy scope to macOS, Windows, and ChromeOS endpoints.
Revenue concentration favors Enterprise Solutions. Procurement experimentation is expanding most quickly in Security Solutions.
End User:
Vertical-specific compliance mandates and device diversity requirements reshape solution specifications and sales cycles.
- Healthcare:HIPAA-mandated patient data isolation, FDA mobile medical application guidelines, and clinical workflow integration dominate procurement criteria. Containerized encryption with remote wipe capabilities and audit trail generation commands premium pricing in United States hospital systems.
- BFSI:Multi-jurisdictional data residency requirements, PCI-DSS tokenization, and biometric authentication integration drive demand for on-premises or hybrid architectures with certificate-based device attestation.
- Education:1:1 device programs and shared tablet carts in K-12 environments prioritize low-touch enrollment and application whitelisting over advanced security modules.
- Retail:Point-of-sale tablet fleets and associate handhelds for inventory management require rugged device support and geofencing for loss prevention.
Procurement velocity is fastest in Healthcare. Contract renewal concentration sits with BFSI.
Device Type:
Form factor diversity strains policy consistency and expands addressable endpoint populations beyond traditional smartphone management.
- Smartphones:iOS and Android fleet heterogeneity demands granular OEM-specific policy adaptation, with Samsung Knox and Apple Business Manager enrollment pathways diverging in certificate handling and remote command reliability.
- Wearables:Smartwatches and clinical body-worn sensors introduce battery-constrained policy enforcement and specialized health data flows requiring FDA and MDR documentation. Bavarian industrial pilots and Dutch healthcare networks are expanding procurement for field technician and patient monitoring use cases.
- Tablets:Larger screen real estate supports clinical documentation and field service workflows with distinct kiosk mode and peripheral pairing requirements.
- Laptops:macOS and Windows endpoint convergence with mobile policy frameworks extends MDM scope into traditional desktop management territory.
Policy maturity concentrates in Smartphones. Addressable expansion is climbing the fastest in Wearables.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for Mobile Device Management solutions concentrates in economies with stringent data sovereignty requirements and advanced industrial digitization programs. Healthcare systems, financial institutions, and manufacturing clusters drive procurement velocity across distinct regulatory environments. Geopolitical fragmentation in data governance is compelling multinational enterprises to deploy regionally segmented MDM architectures.
United States
HIPAA audit mandates and FDA mobile medical application guidelines propel healthcare procurement of containerized encryption platforms. Hospital systems in Texas and California prioritize remote wipe capabilities and audit trail generation for clinical workflows. The Southeast corridor hosts expanding data center footprints serving federal zero-trust compliance requirements.
Germany
Industrial IoT convergence in manufacturing clusters demands rugged device management for shop-floor tablets and handheld scanners. The EU AI Act and GDPR collectively force algorithmic transparency into policy enforcement engines. Bavarian automotive suppliers and Dutch logistics operators procure converged smartphone and rugged handheld governance across continental fleets.
India
The PLI scheme for local device manufacturing creates demand for domestically hosted MDM instances with data-residency guarantees. Karnataka and Maharashtra host expanding enterprise technology centers requiring sovereign cloud deployments. Domestic system integrators white-label modular MDM components for mid-market adopters with constrained capital budgets.
Singapore
Financial services institutions pilot self-healing device configurations that isolate anomalies without human ticketing. The Monetary Authority of Singapore's operational resilience guidelines compress mean-time-to-resolution as a vendor selection criterion. The city-state's position as a regional data hub attracts multinational headquarters seeking Asia-Pacific policy orchestration.
United Kingdom
NIST zero-trust architecture mandates influence procurement specifications for financial institutions in London and Edinburgh. The Financial Conduct Authority's operational resilience rules accelerate replacement of perimeter-based VPNs with continuous device verification. Scottish healthcare trusts expand mobile clinical deployments with NHS Digital compliance frameworks.
Mobile Device Management (MDM) Market Key Industry Players
Portfolio diversification dominates the current landscape as established vendors extend from mobile governance into converged endpoint platforms. The vendor base clusters around three strategic archetypes: cloud-native SaaS providers leveraging hyperscaler infrastructure, legacy enterprise software vendors integrating MDM into broader workplace suites, and specialized rugged device managers serving industrial verticals. M&A activity and strategic partnerships constitute the primary competitive moves, with acquisition targets selected for vertical-specific policy engines or regional data residency certifications.
Among cloud-native specialists, Scalefusion and Hexnode exemplify the modular subscription approach fragmenting mid-market procurement. VMware Workspace ONE occupies a position bridging enterprise virtualization heritage with unified endpoint convergence. Microsoft Intune anchors the hyperscaler-integrated tier, leveraging Azure's global footprint for multinational policy orchestration. SOTI MobiControl represents the rugged specialization archetype, with logistics and field-service verticals driving concentrated margin capture. Jamf Pro sits within the Apple-centric governance segment, reflecting device ecosystem fragmentation in enterprise fleets.
| Leading Market Players |
|---|
| Jamf Pro |
| Scalefusion |
| Microsoft Intune |
| SOTI MobiControl |
| Hexnode |
| VMware Workspace ONE |
| ManageEngine Mobile Device Manager Plus |
| Miradore |
| IBM MaaS360 |
| Others |
Cost & Logistics Intelligence
Cloud infrastructure costs cascade through MDM subscription tiers, with hyperscaler compute and storage fees anchoring SaaS pricing floors while certificate authority licensing and identity federation modules stratify premium bundles for healthcare and financial services buyers.
Pricing Analysis
Volume concentration in cloud-native SaaS tiers compresses per-seat margins, while enterprise solutions with bundled security modules and managed services capture premium pricing. Price differentiation hinges on compliance certification depth—HIPAA, GDPR, and EU AI Act attestation tiers—and vertical customization for rugged device management. Pricing pressure stems from modular unbundling by regional system integrators serving K-12 and municipal buyers. Mid-market education and small government segments exhibit highest price sensitivity; BFSI and healthcare systems show lowest sensitivity due to regulatory non-negotiability.
Supply Chain Analysis
Dual-sourcing requirements for certificate authorities and identity providers compel MDM vendors to qualify multiple root trust anchors, mitigating single-point-of-failure risks in zero-trust authentication chains. Supply concentration centers on the United States for hyperscaler infrastructure, Ireland and Germany for GDPR-compliant data residency nodes, and India for PLI-scheme device manufacturing. Component dependencies span cryptographic hardware security modules, SCEP/ACME protocol stacks, and OEM-specific device management APIs. Supply chain risk concentrates in cross-border data routing complexity under conflicting sovereignty regimes. Distribution runs through direct enterprise sales, hyperscaler marketplaces, and regional system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MDM vendors are racing to deepen control over identity federation and certificate lifecycle management, with backward integration into cryptographic infrastructure emerging as the decisive margin lever.
For Market Incumbents: Deploy acquisition of specialized certificate authority and rugged device management capabilities to counter modular unbundling by regional integrators. Consolidate channel control through exclusive hyperscaler marketplace positioning against emerging cloud-native challengers. Prioritize EU AI Act compliance documentation as a competitive moat for European healthcare and industrial accounts. For New Entrants and Emerging Players: India's PLI scheme opens a window for domestically hosted MDM instances with data-residency guarantees, bypassing entrenched multinational incumbents. Target K-12 districts and municipal governments in Texas and Ontario with white-labeled modular components—device enrollment and application management without premium security bundles—delivered through regional system integrator partnerships. For Investors and Strategic Acquirers: Consolidation of certificate authority providers is the leading indicator that identity infrastructure scarcity will reshape vendor valuations. Frame long-term viability around 5-10 year zero-trust architecture mandates across federal and healthcare sectors. Target acquisition archetypes: vertical-specific policy engine specialists with FDA or MDR documentation depth, and regional data residency certification holders in Germany, Singapore, or India.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Converging mobile and desktop governance through UEM architectures captures VMware Workspace ONE's enterprise virtualization heritage. |
| Acquisition of Specialist Firm | Certificate authority and rugged device management targets address zero-trust authentication and industrial IoT convergence gaps. |
| Strategic Partnership | Hyperscaler marketplace exclusivity with Microsoft Azure anchors multinational policy orchestration for Intune deployments. |
| Geographic Expansion | Domestic hosting in Karnataka and Maharashtra satisfies India's PLI scheme data-residency requirements for sovereign cloud demand. |
| Product Launch | Agentic AI self-healing configurations for Singapore financial services compress mean-time-to-resolution below traditional support contracts. |
Research Approach
SEC filings, hyperscaler capex disclosures, and GPO contracts for healthcare procurement formed the secondary backbone, cross-referenced with primary interviews involving CISOs, IT procurement officers, platform engineers, and channel partners specializing in endpoint governance. Bottom-up enrollment volume estimates and top-down SaaS revenue triangulation validated segment splits across deployment architectures and vertical end users.
Historical trendline analysis of subscription renewal rates and expansion revenue informed growth trajectory modeling across the projection horizon. Segmentation dimensions spanned deployment model, organization size, vertical compliance intensity, device ecosystem complexity, and regional regulatory cluster. CAGRs derived from fitted trend extrapolation incorporating HIPAA audit mandate timing, EU AI Act implementation phases, and 5G private network deployment curves.
The model assumes a particular technology adoption path; alternative pathways for agentic AI autonomous remediation would alter the outlook if self-healing capabilities displace traditional tier-one support contracts faster than anticipated. Deviation in certificate authority consolidation timelines or zero-trust federal procurement acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Referral Marketing Software Market
Software & Services
On-Demand Wellness Software Market
Software & Services
Global Decision Support Software Market
Software & Services
Global Club Management Software Market
Software & Services
Global Enterprise Architecture Tools Market
Software & Services
Global Plumbing Software Market
Software & Services
Curriculum Mapping Software Market
Software & Services
Global Product Information Management (PIM) Software Market
Software & Services
Ecommerce Inventory Management Software Market
Software & Services
Stock Control Software Market
Software & Services
Simulation Software Market
Software & Services
Sales Performance Management (SPM) Software Market
Software & Services
Geophysical Software Service Market
Software & Services
Generative Design Software Market
Software & Services
Poultry Farm Management Software Market
Software & Services
Global Employee Recognition Software Market