
 Application Server Market | 2026-2036
Application Server Market Size, Share, and Industry Trends Forecast 2026-2036
Application Server Market Analysis
Enterprise-grade container orchestration with certified Kubernetes conformance is rotating the Application Server market toward higher-reliability tiers. IBM Corporation anchors its position through deep mainframe integration and hybrid cloud middleware stacks. Oracle Corporation competes via in-house silicon-to-software verticality and database-optimized runtime engines. Red Hat, Inc. leverages its open-source distribution model to control the upstream container platform ecosystem.
An application server is a software framework that provides runtime services—connection pooling, transaction management, security enforcement, and messaging middleware—to deploy and execute server-side business logic, typically supporting Java EE, Jakarta EE, or .NET specifications. Its primary purpose is to host multi-tier enterprise applications that require session persistence, load balancing, and fault tolerance across distributed compute clusters. Cloud-based deployment models now capture the fastest expansion as organizations retire capital-intensive on-premises data centers, while managed services within the service-type dimension concentrate margin pools through recurring operational contracts. Web applications and enterprise applications remain the dominant application-type categories, though mobile backends are gaining share as API gateway functionality merges into server runtimes.
FCC guidelines on telecommunications infrastructure security, combined with HIPAA requirements for healthcare data isolation, shape product certification roadmaps for U.S.-deployed application servers. In Europe, ETSI cybersecurity standards and GDPR data residency rules mandate runtime encryption and geographic instance pinning that vendors must engineer into their distribution architectures. Stakeholders should monitor how sovereign cloud certifications proliferate across national regulators, as these will determine which runtime platforms qualify for government and critical-infrastructure procurement.
Market Dynamics
Containerized Kubernetes conformance is forcing enterprise IT departments to retire legacy on-premises middleware stacks and adopt certified, auditable runtime environments that satisfy sovereign cloud mandates.
Growth Catalysts
- EU AI Act compliance deadlines:European financial services firms are accelerating procurement of certified application servers with built-in runtime encryption and geographic instance pinning to meet algorithmic accountability requirements.
- Hyperscaler partnership ecosystems:India's sovereign cloud initiatives are creating dedicated procurement channels for government and critical-infrastructure runtime platforms through localized data center partnerships.
- API gateway consolidation:Mobile backend developers are merging gateway functionality directly into application server runtimes, collapsing previously separate infrastructure tiers.
Market Restraints
- Specialized talent scarcity:Container orchestration expertise concentrates in technology hubs, creating hiring bottlenecks for enterprise IT departments in secondary markets.
- Legacy integration friction:Mainframe-dependent financial institutions face extended migration timelines due to COBOL business logic embedded in decades-old middleware configurations.
- Silicon supply concentration:Database-optimized runtime engines depend on specialized processor architectures with limited qualified foundry capacity.
Strategic Opportunities
- Healthcare data isolation mandates:HIPAA requirements for patient information segregation are creating certified-runtime procurement pools in the United States that favor vendors with healthcare-specific compliance engineering.
- Edge computing convergence:5G network slicing and lightweight container runtimes are merging to enable low-latency application server deployment at telecommunications infrastructure edges.
- German sovereign cloud expansion:Gaia-X federation standards are opening procurement channels for runtime platforms that demonstrate data sovereignty through geographic instance pinning and cryptographic provenance.
Industry Challenges
- Jakarta EE certification timelines:Vendors face extended validation cycles for new runtime releases, compressing product roadmaps against customer upgrade windows.
- Multi-cloud orchestration complexity:Enterprise architects struggle to maintain consistent security policies across heterogeneous Kubernetes distributions from competing cloud providers.
- Technical debt remediation costs:Session persistence refactoring for stateless container architectures demands capital allocation that competes with innovation budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Application Server Market |
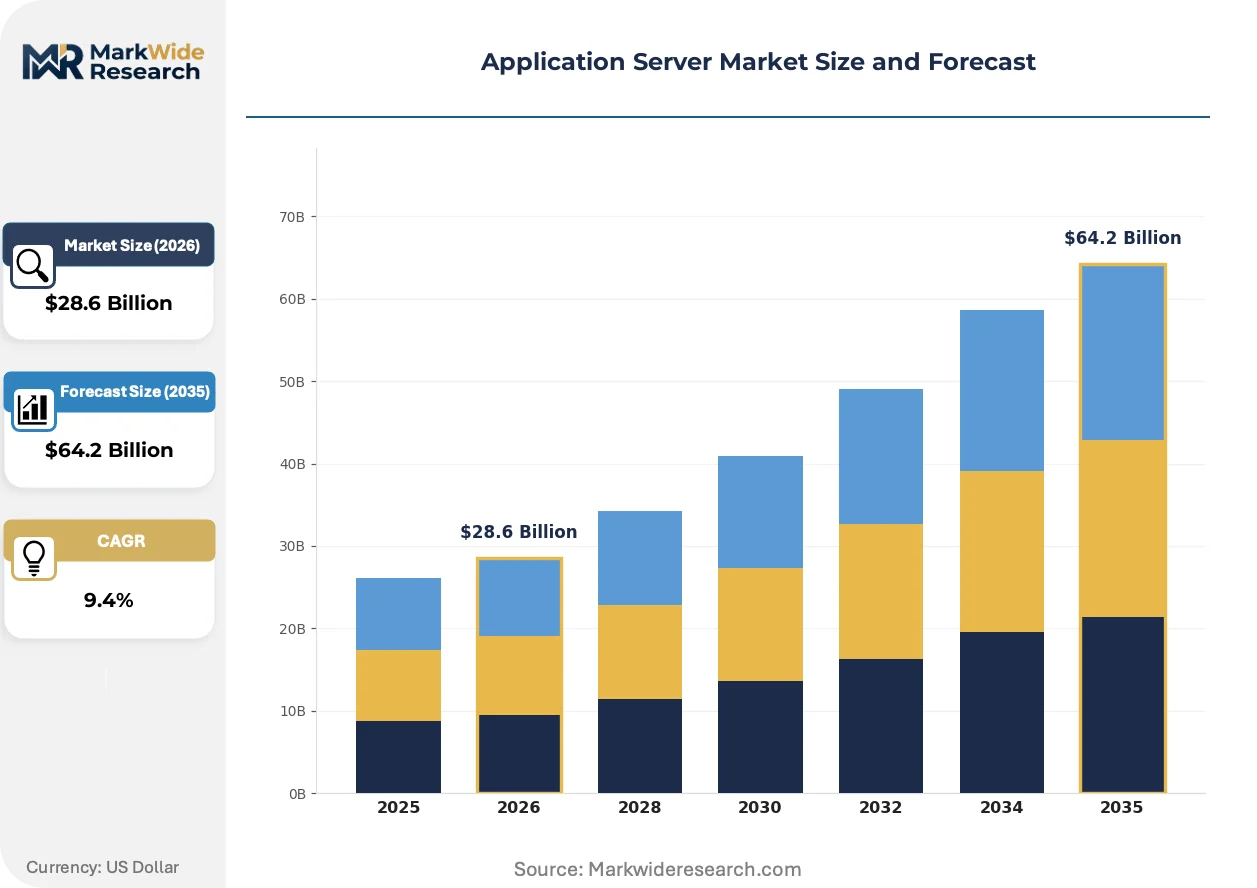
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $64.2 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premises, Cloud-Based, Hybrid, Virtualized End User: IT Enterprises, Small Businesses, Government, Educational Institutions Application Type: Web Applications, Mobile Applications, Enterprise Applications, E-Commerce Solutions Service Type: Managed Services, Professional Services, Support Services, Maintenance Services |
| Companies Covered | Microsoft Corporation, IBM Corporation, Oracle Corporation, Red Hat, Inc., SAP SE, Broadcom, Inc., TIBCO Software Inc., VMware LLC, The Apache Software Foundation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Application Server Market Emerging Trajectories
Runtime environments are fragmenting across specialized tiers as regulatory mandates and performance requirements diverge, creating distinct product categories that resist commoditization.
Quarkus and Micronaut native compilation is supplanting traditional JVM warm-up models in latency-sensitive microservices deployments. Capital markets trading platforms are adopting these frameworks at accelerated pace to eliminate garbage collection pauses. This shift is compressing the addressable market for conventional application servers in high-frequency transaction processing segments.
GDPR Article 32 technical measures and the EU AI Act risk management framework are mandating runtime encryption with hardware security module integration. European healthcare and financial services procurement specifications now require cryptographic attestation chains that trace execution environments to certified hardware roots. Vendors are responding by engineering geographic instance pinning and sovereign cloud certifications into distribution architectures.
Consumption-based billing models are displacing perpetual license structures in enterprise middleware procurement. Managed service providers and hyperscaler marketplaces are capturing margin pools through operational contracts that bundle runtime licensing with infrastructure operations. This pattern is most visible in United States enterprise IT departments accelerating cloud migration timelines to retire capital-intensive data center commitments.
Application Server Market Segmentation
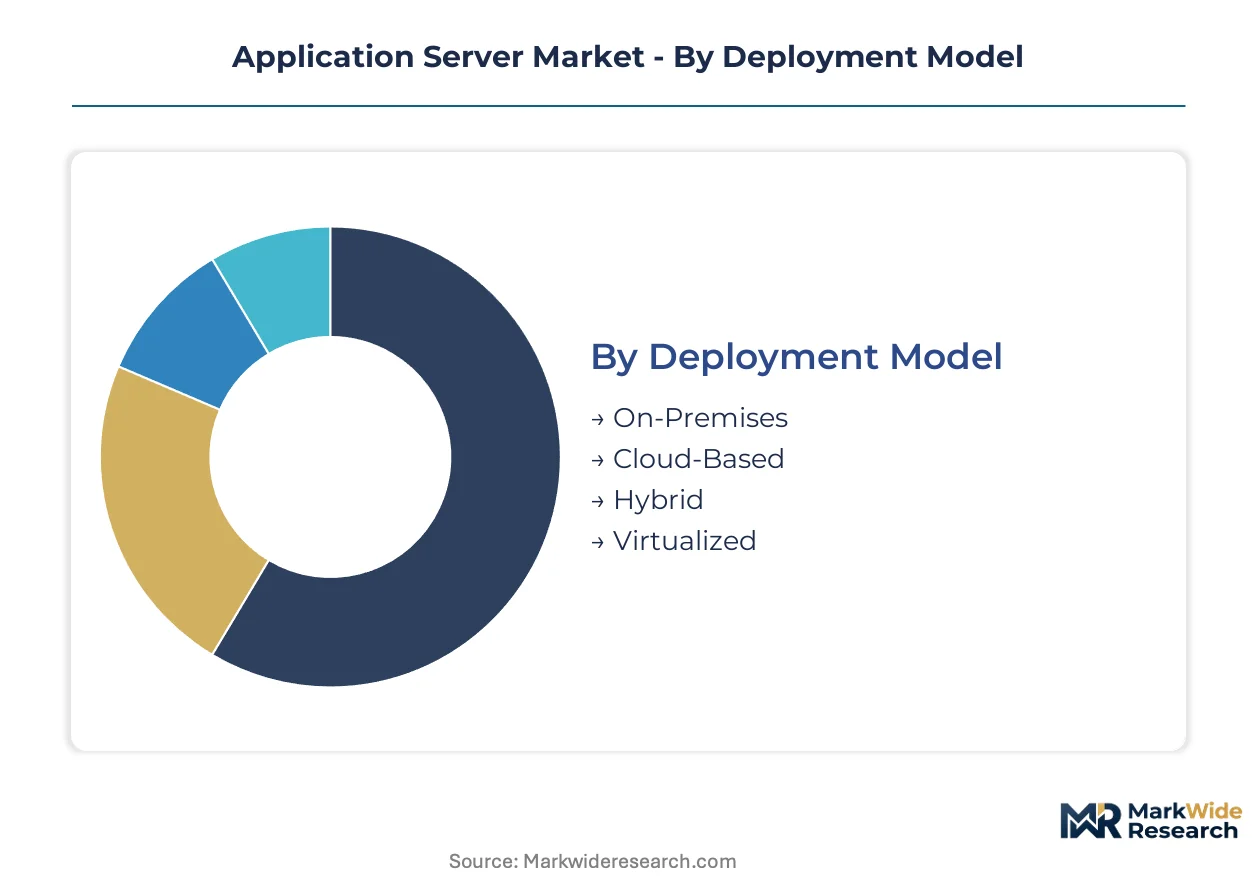
Application server procurement patterns fragment sharply across deployment models and service tiers as enterprises balance legacy middleware investments against containerized cloud migration timelines. Segmentation reveals where substitution pressure from Kubernetes-native platforms is collapsing traditional revenue pools and where certified runtime environments command pricing premiums.
Deployment Model:
Cloud-based and hybrid configurations face the most intense substitution threat from serverless computing and container-as-a-service platforms, while on-premises installations retain defensive moats in regulated sectors with data residency mandates.
- On-Premises:Traditional data center installations host mission-critical workloads requiring sub-millisecond latency and air-gapped security architectures. Financial services firms in Frankfurt and healthcare systems in Boston maintain these deployments to satisfy GDPR Article 32 and HIPAA technical safeguard requirements, though capital expenditure burdens are accelerating depreciation pressures.
- Cloud-Based:Hyperscaler-managed runtime environments eliminate infrastructure ownership while embedding automated scaling and geographic redundancy. Indian government cloud initiatives and German Gaia-X federation standards are channeling sovereign-certified procurement toward localized data center partnerships with cryptographic provenance guarantees.
- Hybrid:Split architectures synchronize on-premises transaction processing with cloud burst capacity for seasonal demand spikes. Manufacturing ERP systems in Stuttgart and insurance policy administration in Mumbai deploy this model to retain sensitive data locally while offloading analytics workloads.
- Virtualized:Hypervisor-abstracted application servers consolidate legacy middleware onto shared hardware infrastructure. Cost-conscious educational institutions and municipal government data centers in secondary US markets continue these deployments to extend equipment lifecycles.
On-Premises retains volume leadership; Cloud-Based holds the steepest expansion curve.
End User:
IT Enterprises absorb the majority of professional services and managed services contract value, while government procurement concentrates in certified runtime pools with sovereign cloud mandates.
- IT Enterprises:Large technology departments drive container orchestration adoption through certified Kubernetes conformance programs and multi-cloud governance frameworks. Capital markets trading platforms in London and Tokyo are replacing conventional JVM-based servers with Quarkus native compilation to eliminate garbage collection pauses.
- Small Businesses:Resource-constrained organizations leverage hyperscaler marketplace subscriptions and consumption-based billing to access enterprise-grade runtime capabilities without infrastructure operations overhead. SaaS-embedded application server functionality is displacing dedicated procurement in this tier.
- Government:National critical infrastructure programs require cryptographic attestation chains and geographic instance pinning. India's MeitY empanelment and Germany's BSI certification standards filter vendor participation in public sector runtime procurement.
- Educational Institutions:Research computing clusters and student-facing administrative systems operate on deferred maintenance budgets with extended upgrade cycles. Virtualized deployment models dominate this price-sensitive segment.
IT Enterprises dominate contract value; Government procurement is climbing fastest on sovereign cloud mandates.
Application Type:
Enterprise applications generate the deepest professional services attachment, while mobile backends are collapsing separate API gateway tiers into consolidated runtime stacks.
- Web Applications:Traditional three-tier architectures with session persistence and connection pooling remain the foundational workload for Jakarta EE-certified servers. E-commerce platforms in São Paulo and Dubai process high-volume transaction flows through these runtimes.
- Mobile Applications:Backend-as-a-service convergence is merging push notification management, authentication, and data synchronization directly into application server distributions. Latency-sensitive microservices in Seoul and Singapore financial technology clusters are driving this consolidation.
- Enterprise Applications:ERP and CRM integration middleware demands transaction integrity across distributed compute clusters. Manufacturing supply chain systems in Munich and pharmaceutical batch processing in Basel require these runtime guarantees.
- E-Commerce Solutions:Seasonal demand volatility necessitates elastic scaling with cart session replication across availability zones. Retail platforms in Sydney and Toronto deploy these configurations for peak traffic absorption.
Enterprise Applications anchor services revenue; Mobile Applications are gaining share fastest through gateway consolidation.
Service Type:
Managed services contracts capture recurring revenue streams as enterprises outsource runtime operations, while professional services face margin compression from standardized container deployment patterns.
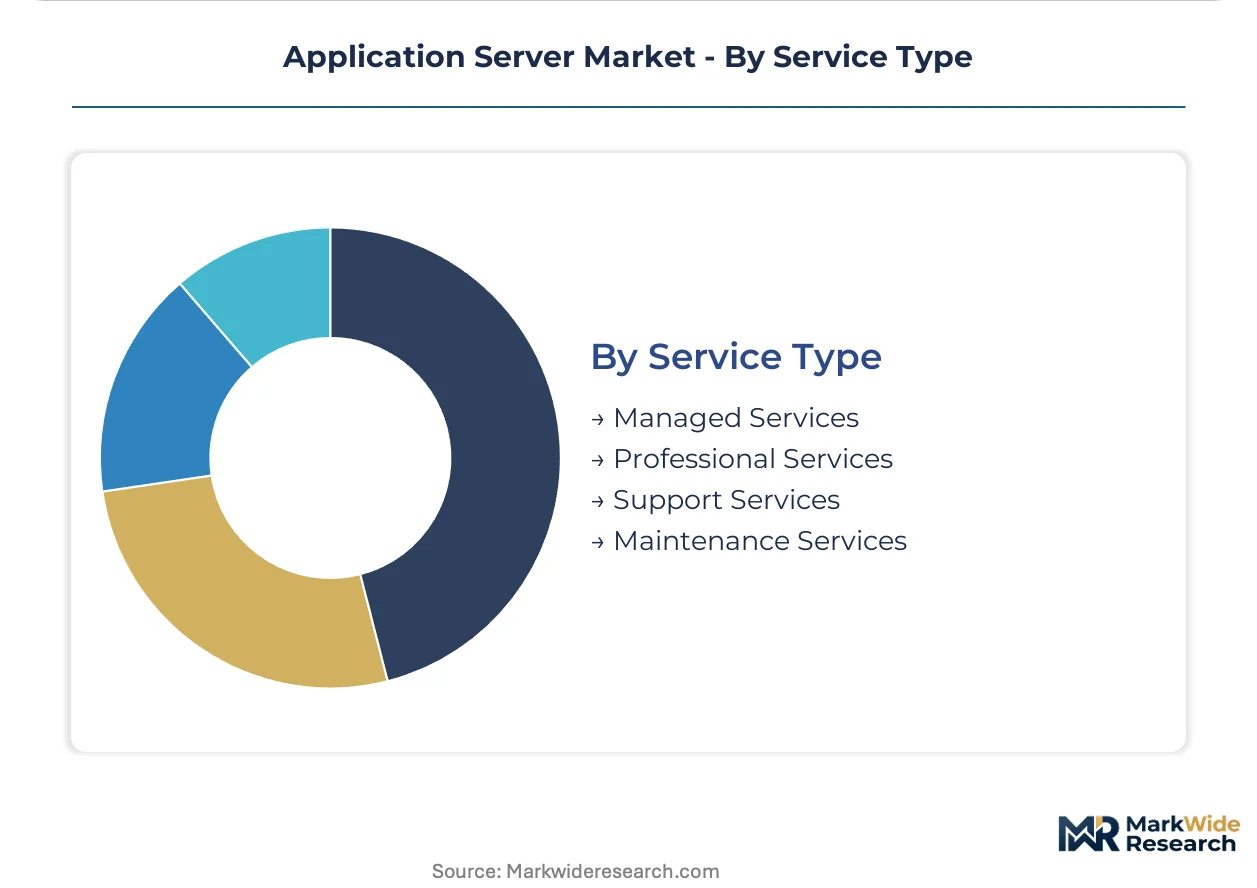
- Managed Services:Operational contracts bundle runtime licensing with infrastructure monitoring, patch management, and incident response. US healthcare systems migrating to HIPAA-compliant cloud environments are accelerating procurement of these comprehensive agreements.
- Professional Services:Custom integration and migration consulting addresses legacy middleware retirement and container refactoring. COBOL-dependent financial institutions in New York and London require extended engagement timelines for business logic extraction.
- Support Services:Technical assistance subscriptions provide vendor escalation paths and runtime troubleshooting. Mission-critical manufacturing execution systems in industrial clusters around Stuttgart and Detroit maintain these relationships.
- Maintenance Services:Version upgrade entitlements and extended security patch coverage protect long-term deployments. Government contracts with multi-year procurement cycles standardize these provisions.
Managed Services leads recurring revenue; Professional Services is expanding most quickly on legacy migration demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across procurement environments. United States healthcare systems absorb premium pricing for HIPAA-compliant managed services, while Indian educational institutions and municipal data centers prioritize cost-optimized virtualized deployments. German financial institutions occupy the middle ground, paying certification premiums but demanding cryptographic provenance guarantees.
United States
Enterprise IT departments in New York and Chicago drive container orchestration adoption through certified Kubernetes conformance programs. FCC telecommunications security guidelines and HIPAA technical safeguard requirements shape product certification roadmaps for runtime platforms. Capital markets trading platforms in Manhattan are replacing conventional JVM-based servers with native compilation frameworks to eliminate garbage collection pauses.
Germany
Manufacturing ERP systems in Stuttgart and pharmaceutical batch processing in Basel require transaction integrity across distributed compute clusters. ETSI cybersecurity standards and GDPR Article 32 data residency rules mandate runtime encryption with hardware security module integration. Gaia-X federation standards in Frankfurt are opening procurement channels for platforms demonstrating data sovereignty through geographic instance pinning.
India
Small businesses in Bangalore and Hyderabad leverage hyperscaler marketplace subscriptions to access enterprise-grade runtime capabilities without infrastructure operations overhead. MeitY empanelment standards and sovereign cloud initiatives create dedicated procurement channels for government runtime platforms through localized data center partnerships. Insurance policy administration in Mumbai deploys hybrid architectures to retain sensitive data locally while offloading analytics workloads.
Japan
Capital markets trading platforms in Tokyo are accelerating procurement of certified application servers with built-in runtime encryption to meet algorithmic accountability requirements. METI industrial policy frameworks and JIS standards shape product certification roadmaps for financial services runtime environments. Manufacturing execution systems in the Chubu industrial corridor around Nagoya maintain technical assistance subscriptions for mission-critical vendor escalation paths.
United Kingdom
COBOL-dependent financial institutions in the City of London face extended migration timelines due to business logic embedded in decades-old middleware configurations. FCA operational resilience requirements and GDPR compliance deadlines are accelerating procurement of certified runtime environments with cryptographic attestation chains. E-commerce platforms in London process high-volume transaction flows through Jakarta EE-certified servers with session persistence and connection pooling.
Application Server Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the Application Server market. The vendor base clusters around three strategic positions: mainframe-integrated hybrid cloud specialists, open-source distribution platforms controlling upstream container ecosystems, and database-optimized runtime engine providers with silicon-to-software verticality. Dominant competitive moves include hyperscaler partnership ecosystem expansion and sovereign cloud certification engineering for government procurement qualification.
Within the enterprise-integrated tier, IBM Corporation and Oracle Corporation exemplify divergent architectural philosophies. Red Hat, Inc. anchors the open-source distribution archetype with upstream container platform influence. Microsoft Corporation occupies a position spanning cloud-native managed services and legacy middleware migration tooling. These three archetypes—mainframe-hybrid, open-source upstream, and cloud-native integrated—represent the competitive structure governing procurement decisions across regulated industries.
| Leading Market Players |
|---|
| Microsoft Corporation |
| IBM Corporation |
| Oracle Corporation |
| Red Hat, Inc. |
| SAP SE |
| Broadcom, Inc. |
| TIBCO Software Inc. |
| VMware LLC |
| The Apache Software Foundation |
| Others |
Supply Flow & Price Mechanics
Ninety-day certification cycles for Jakarta EE conformance create inventory pressure on vendor release schedules, concentrating pricing power with distributors who pre-validate runtime stacks for regulated buyers. This lead-time compression rewards hyperscaler marketplaces with certified image repositories while squeezing independent software vendors on margin.
Pricing Analysis
Managed services contracts and multi-year operational agreements drive lifetime value in this market. Three-tier pricing structure across premium, standard, and economy levels separates sovereign-certified runtimes with hardware security module integration from basic container platforms. Cost compression in the standard tier is intensifying because hyperscaler marketplace aggregation collapses procurement friction. Small businesses in India's secondary cities exhibit highest price sensitivity, while United States healthcare systems absorb premium positioning for HIPAA-compliant managed services.
Supply Chain Analysis
Container image distribution costs spike during trans-Pacific bandwidth congestion, forcing runtime vendors toward localized registry replication in Frankfurt, Mumbai, and Singapore data centers. Software supply chains draw from United States-based hyperscaler infrastructure, Indian systems integration labor pools, and German cryptographic hardware manufacturing. Single-source vulnerability concentrates in qualified hardware security module foundries. Distribution runs through hyperscaler marketplaces and certified systems integrators with sovereign cloud credentials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Container-native runtime consolidation represents high-growth disruption as Kubernetes conformance mandates collapse legacy middleware procurement channels. The EU AI Act's algorithmic accountability requirements accelerate this inflection across European financial services.
For Market Incumbents: Secure sovereign cloud certification pipelines in Germany's Gaia-X federation and India's MeitY empanelment to defend against open-source distribution platforms. Anchor hybrid cloud middleware stacks through mainframe integration depth that container-native competitors cannot replicate. Certification investment in runtime encryption with hardware security module integration protects margin position against commodity container platforms.
For New Entrants and Emerging Players: Lead with healthcare data isolation mandates in United States hospital systems, where HIPAA technical safeguard requirements create certified-runtime procurement pools with limited incumbent saturation. Target municipal government data centers in secondary US markets with virtualized deployment models that extend equipment lifecycles. Go-to-market through hyperscaler marketplace listings with consumption-based billing eliminates infrastructure operations overhead for price-constrained buyers.
For Investors and Strategic Acquirers: Long-term, this sits as a compliance-arbitrage play because regulatory divergence across GDPR, EU AI Act, and sovereign cloud mandates fragments procurement specifications and resists commoditization. Acquisition targets cluster around open-source distribution platforms with upstream Kubernetes influence and healthcare-specific compliance engineering capabilities. Monitor Jakarta EE certification timeline compression as inflection indicator for vendor product roadmap stress.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | Gaia-X federation standards in Frankfurt open procurement channels for data-sovereign runtime platforms. |
| API Gateway Consolidation | Mobile backend developers in Seoul merge gateway functionality directly into application server distributions. |
| Native Compilation Migration | Capital markets trading platforms in Tokyo adopt Quarkus frameworks to eliminate garbage collection pauses. |
| Managed Services Bundling | US healthcare systems accelerate procurement of operational contracts with HIPAA-compliant runtime monitoring. |
| Hardware Security Module Integration | European financial services procurement specifications now require cryptographic attestation chains to certified hardware roots. |
Methodological Framework
Cross-validation between executive interviews and regulatory filing analysis anchors the qualitative findings in this study. Primary research incorporated conversations with enterprise IT architects, platform engineers at hyperscaler partnerships, healthcare compliance officers, and government procurement leads. Secondary validation drew from SEC 10-K infrastructure disclosures, ETSI cybersecurity standard drafts, MeitY empanelment guidelines, and hyperscaler capex announcements. Bottom-up deployment model sizing and top-down regulatory mandate impact assessment were triangulated for segment-level consistency.
Sensitivity analysis across deployment model adoption curves, sovereign cloud certification timelines, and container-native substitution rates shaped the analytical framework. Segmentation dimensions modeled include deployment architecture, end-user organization scale, application workload type, and regional regulatory cluster. CAGRs were derived through logistic diffusion curves for technology substitution and compliance-driven procurement acceleration. Industry-specific inputs encompassed Jakarta EE certification pipeline data and hyperscaler marketplace transaction velocity indicators.
Forecasts assume regulatory continuity in EU AI Act implementation, HIPAA technical safeguard enforcement, and Gaia-X federation standards; material policy shifts would require re-modeling. Technology risk factors include serverless computing substitution acceleration and legacy mainframe integration breakthroughs. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Digital Experience Management Software Market
Software & Services
Automotive Digital Retailing Software Market
Software & Services
Photo Editing Software Market
Software & Services
Germany HR Payroll Software Market
Software & Services
Global Java Web Frameworks Software Market
Software & Services
Automation Test Software Market
Software & Services
Software Publishers Market
Software & Services
SRM Software Market
Software & Services
Customer Self-Service Software Market
Software & Services
Global Remote Desktop Management Market
Software & Services
North America Saas-Based Expense Management Market
Software & Services
Africa Financial Services Software Market
Software & Services
Global Back Testing Software Market
Software & Services
EDA Tools Market
Software & Services
Global Retail Inventory Management Software Market
Software & Services
Global Budgeting Software Market